
 China Cold Chain Logistics Market | 2026-2036
China Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Cold Chain Logistics Market Analysis
Fresh produce distribution channels from farm to urban retail is tilting toward consolidated platform operators with temperature-controlled mandates. Sinotrans Limited leverages its state-backed port and rail infrastructure to dominate cross-provincial frozen goods corridors. JD Logistics anchors last-mile chilled delivery through proprietary warehouse robotics and same-day urban networks.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining precise thermal bands from negative eighteen degrees Celsius for frozen goods to two to eight degrees Celsius for pharmaceuticals—designed to prevent spoilage, ensure safety compliance, and extend shelf life of perishable products. Warehousing commands the largest capital allocation within service type segments due to land scarcity near tier-one consumption centers, while temperature-sensitive pharmaceuticals represents the fastest-expanding product type category driven by biologics distribution requirements. IoT Solutions within technology segments attracts disproportionate R&D investment as real-time thermal telemetry becomes mandatory for pharmaceutical regulatory compliance.
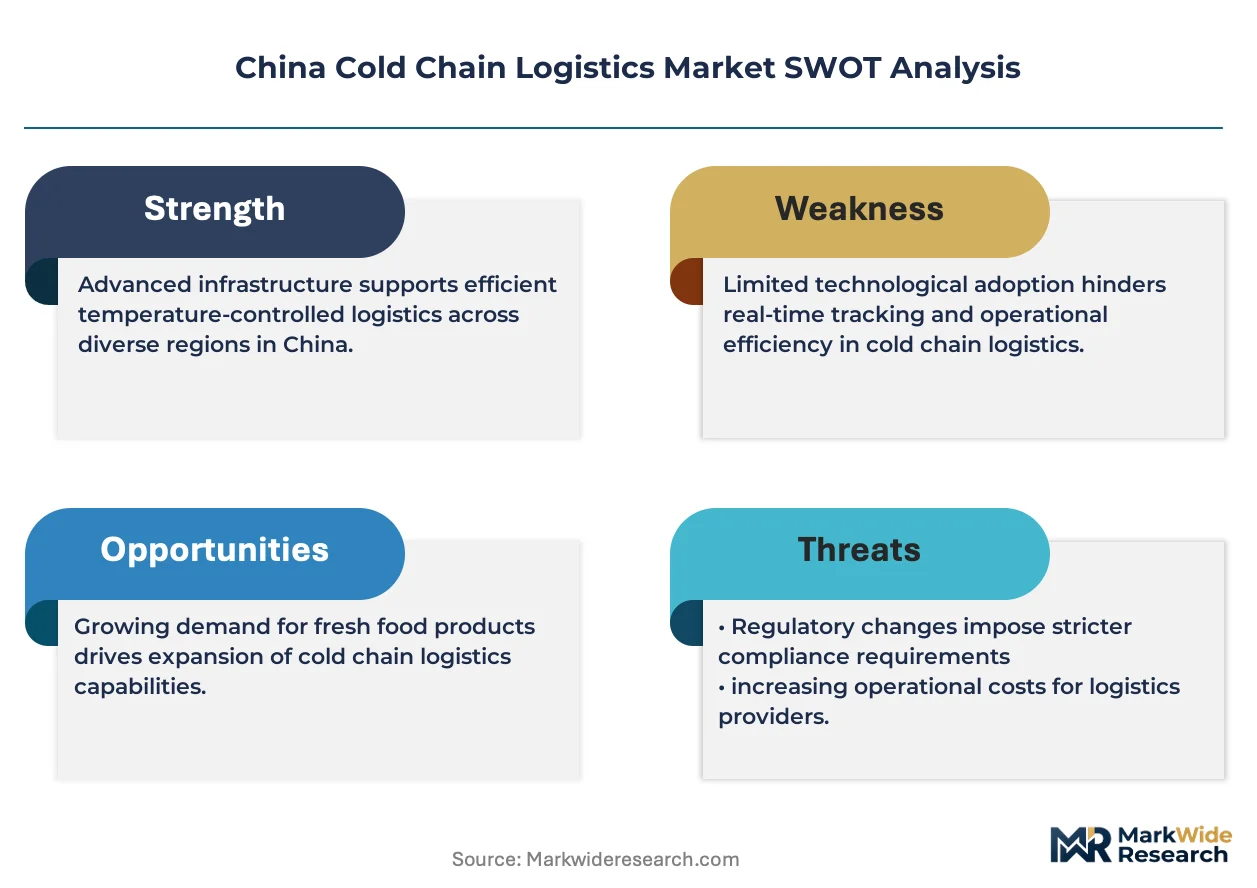
SAMR enforces national food safety standards that mandate full temperature traceability across cold chain operations, while MEE carbon reduction frameworks penalize diesel-refrigerated transport in major metropolitan zones. GB standards for refrigerated vehicle construction are tightening insulation performance thresholds, effectively raising equipment replacement cycles and OEM qualification barriers. Stakeholders must weigh electrification capex against diesel phase-out timelines when calibrating fleet renewal schedules.
Market Dynamics
China's dual carbon goals are forcing diesel-to-electric fleet conversion across refrigerated transport, compressing equipment replacement cycles while reshaping capital deployment patterns for logistics operators.
Growth Catalysts
- Biologics Distribution Expansion:Temperature-sensitive pharmaceuticals now require negative seventy degrees Celsius ultra-low storage for mRNA therapies, pulling investment into specialized cryogenic infrastructure.
- SAMR Traceability Mandates:National food safety standards now require full temperature logging across farm-to-retail chains, compelling warehouse automation and IoT sensor deployment.
- Yangtze River Delta Clustering:Consumption concentration around Shanghai, Hangzhou, and Nanjing generates route density that justifies dedicated cold chain corridors and multi-temperature consolidation centers.
Market Restraints
- Land Scarcity Near Tier-One Centers:Industrial zoned land within fifty kilometers of Shanghai commands premium rates that absorb thirty to forty percent of warehouse project returns.
- Electric Vehicle Range Constraints:Current battery technology limits refrigerated truck operational radius to under two hundred kilometers in sub-zero conditions, fragmenting inter-city networks.
- GB Standards Tightening:Revised insulation performance thresholds for refrigerated vehicle construction disqualify legacy equipment and extend OEM qualification timelines.
Strategic Opportunities
- Western Province Penetration:Sichuan and Shaanxi cold storage capacity per capita remains below one-third of eastern coastal levels, creating first-mover advantage for temperature-controlled fresh produce distribution.
- Carbon Credit Monetization:MEE frameworks in Beijing and Shenzhen metropolitan zones allow electric fleet operators to trade emission reduction certificates against diesel phase-out penalties.
- Pharmaceutical-Grade Robotics:Convergence of automated storage and retrieval systems with thermal validation protocols opens contract logistics services to international biologics manufacturers.
Industry Challenges
- Refrigeration Technician Shortage:Skilled labor capable of maintaining ammonia and CO2 cascade systems in ultra-low applications commands wage premiums that strain operating margins.
- Multi-Temperature Integration Complexity:Legacy warehouse management systems lack native support for simultaneous frozen, chilled, and ambient zone orchestration, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cold Chain Logistics Market |
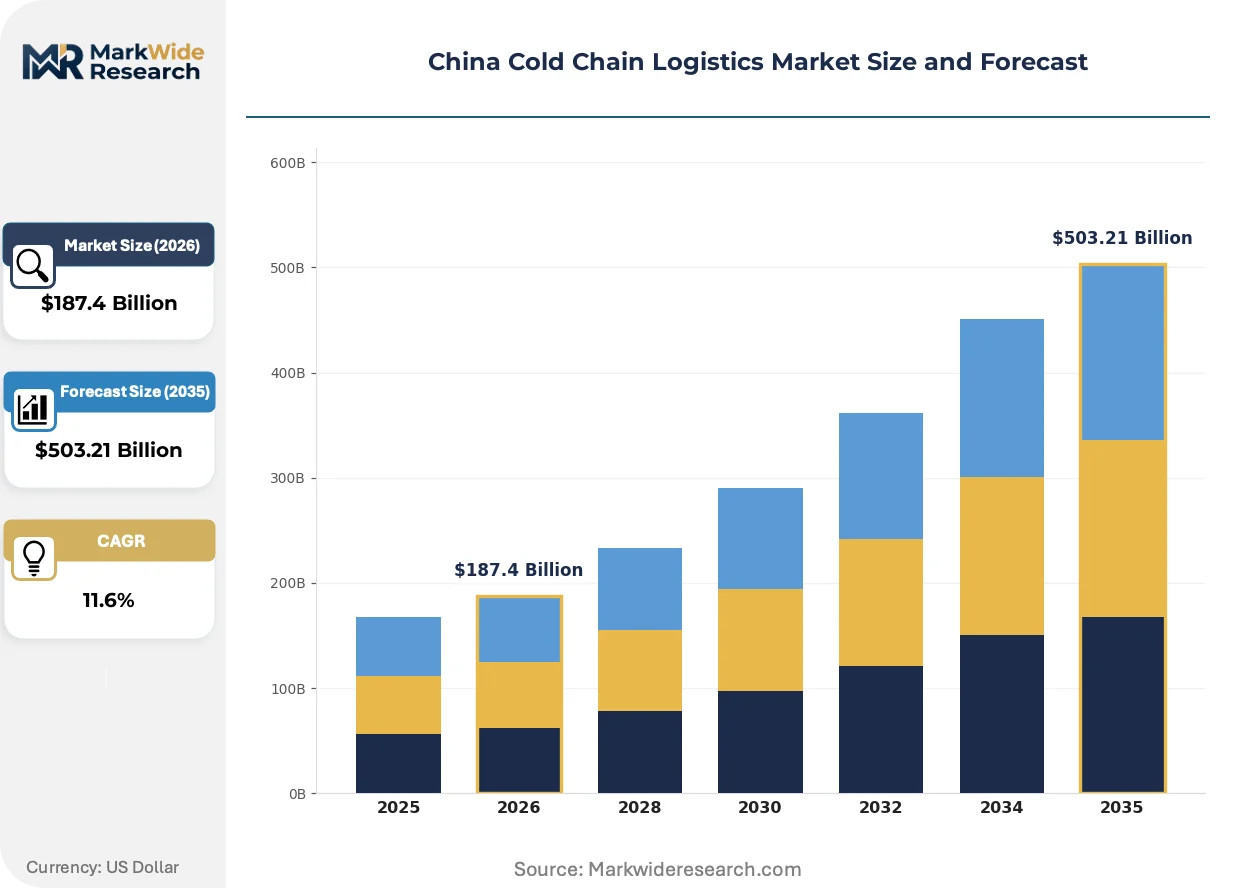
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution End User: Food & Beverage, Pharmaceuticals, Chemicals, Retail Technology: Refrigerated Vehicles, Temperature Monitoring, Tracking Systems, IoT Solutions Product Type: Frozen Goods, Chilled Goods, Perishable Foods, Temperature-Sensitive Pharmaceuticals |
| Companies Covered | Sinotrans Limited, SF Express, Beijing Ershang Group, JD Logistics, China Merchants Americold Logistics, Nichirei Logistics Group, Shanghai Jin Jiang International Industrial Investment, CJ Rokin Logistics & Supply Chain, HNA Cold Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cold Chain Logistics Market Emerging Trajectories
Real-time thermal telemetry is becoming mandatory infrastructure rather than competitive differentiator, compressing compliance timelines and reshaping vendor qualification criteria across pharmaceutical and fresh food segments.
IoT sensor networks embedded in refrigerated vehicles and warehouse racking are digitizing temperature compliance documentation for NMPA pharmaceutical distribution licenses. Third-party logistics operators now deploy these systems as table stakes for biologics contracts, with real-time alerts replacing end-of-trip paper logs. The technology is digitizing audit preparation and reducing customs clearance friction for temperature-sensitive imports.
MEE carbon reduction frameworks now penalize diesel-refrigerated transport in Beijing, Shanghai, and Shenzhen metropolitan zones, accelerating electric chassis and cryogenic cooling unit adoption. Logistics operators face compressed fleet renewal schedules as municipal authorities advance low-emission zone effective dates. Cold chain segments serving pharmaceutical distribution, where temperature integrity cannot degrade during power transitions, are responding with hybrid electric-thermal storage architectures.
Platform-based procurement of temperature-controlled transport capacity is consolidating fragmented owner-operator fleets under consolidated booking systems. Fresh produce distributors in the Yangtze River Delta now source lane capacity through digital freight marketplaces rather than contracted carrier relationships. This pattern concentrates volume with platform operators capable of guaranteeing temperature bands while compressing rates for standalone refrigerated truck owners.
China Cold Chain Logistics Market Segmentation
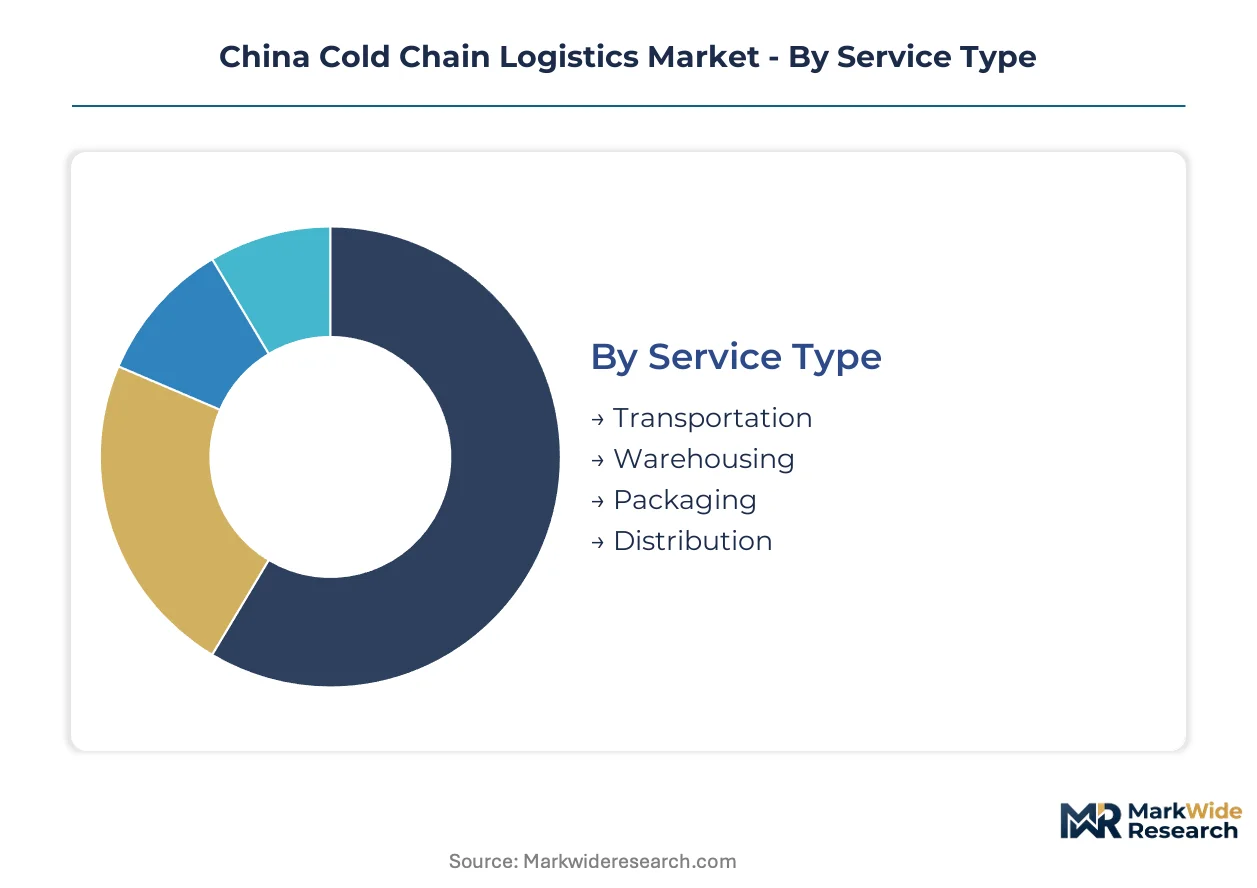
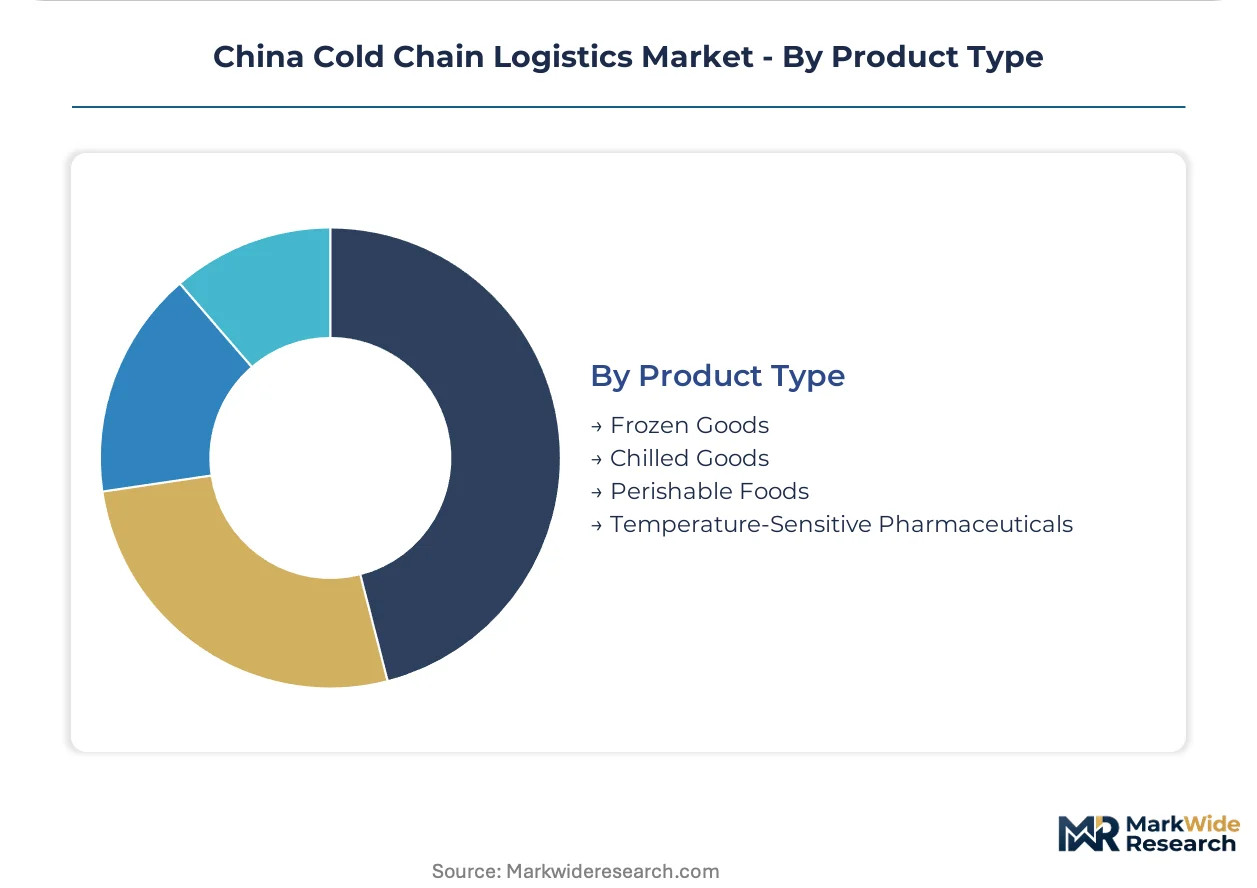
Cold chain logistics demands precise segmentation because temperature bands, regulatory requirements, and capital intensity vary dramatically across service modes and product categories. Operators configure entirely different asset bases for frozen pork distribution versus mRNA vaccine storage, making segment-level strategy essential for capital deployment.
Service Type:
Cost tier structures the competitive landscape, with capital-heavy segments demanding state-backed or platform-scale balance sheets.
- Transportation:Refrigerated trucking and rail movement of temperature-controlled cargo. Diesel-to-electric fleet conversion in Beijing, Shanghai, and Shenzhen metropolitan zones compresses replacement cycles while MEE carbon frameworks penalize legacy equipment.
- Warehousing:Climate-controlled storage facilities maintaining precise thermal bands from negative eighteen degrees Celsius to two to eight degrees Celsius. Land scarcity within fifty kilometers of Shanghai absorbs thirty to forty percent of project returns, favoring operators with state-backed land access.
- Packaging:Insulated containers and phase-change materials for last-mile thermal protection. E-commerce fresh produce volumes in the Yangtze River Delta drive demand for reusable cold boxes.
- Distribution:Consolidated platform operators coordinating multi-temperature consolidation and cross-docking. SAMR traceability mandates force middleware investment for legacy warehouse management systems.
Warehousing holds installed capacity. Distribution is rotating up the share rankings.
End User:
Application-specific compliance requirements create divergent vendor qualification barriers and contract tenures.
- Food & Beverage:Fresh produce, dairy, meat, and seafood requiring frozen or chilled corridors from farm to retail. Platform-based procurement through digital freight marketplaces concentrates volume with temperature-guaranteeing operators in the Yangtze River Delta.
- Pharmaceuticals:Biologics, vaccines, and temperature-sensitive therapies demanding ultra-low storage to negative seventy degrees Celsius for mRNA distribution. NMPA licensing requirements mandate real-time thermal telemetry and digitized compliance documentation.
- Chemicals:Industrial temperature-sensitive inputs and specialty reagents. Sichuan and Shaanxi capacity gaps create first-mover opportunities for hazardous-materials-certified cold storage.
- Retail:Omnichannel grocers and convenience chains operating multi-temperature fulfillment networks. JD Logistics anchors same-day chilled delivery through proprietary warehouse robotics.
Food and Beverage holds installed capacity. Pharmaceuticals is climbing the fastest.
Technology:
Supply concentration favors integrated platform operators over standalone equipment vendors.
- Refrigerated Vehicles:Electric chassis and cryogenic cooling units replacing diesel equipment under dual carbon goals. Current battery technology limits operational radius to under two hundred kilometers in sub-zero conditions.
- Temperature Monitoring:Real-time thermal telemetry systems digitizing compliance documentation for SAMR and NMPA audits. Third-party logistics operators deploy these as table stakes for biologics contracts.
- Tracking Systems:GPS and RFID-enabled cargo visibility across farm-to-retail chains. Fresh produce distributors source lane capacity through consolidated booking systems rather than contracted carrier relationships.
- IoT Solutions:Sensor networks embedded in vehicles and warehouse racking with automated alert protocols. This segment attracts disproportionate R&D investment as real-time telemetry becomes mandatory infrastructure.
Temperature Monitoring holds installed capacity. IoT Solutions is gaining share fastest.
Product Type:
Margin profiles diverge sharply between commodity frozen goods and pharmaceutical-grade cold chain services.
- Frozen Goods:Meat, seafood, and processed foods maintained at negative eighteen degrees Celsius. Sinotrans Limited leverages port and rail infrastructure to dominate cross-provincial frozen corridors.
- Chilled Goods:Dairy, fresh produce, and prepared foods requiring zero to four degrees Celsius. Yangtze River Delta urban clustering generates route density justifying dedicated multi-temperature consolidation centers.
- Perishable Foods:High-velocity fresh items with compressed shelf lives demanding rapid throughput. Platform operators with temperature-controlled mandates are consolidating farm-to-urban-retail channels.
- Temperature-Sensitive Pharmaceuticals:Biologics and vaccines with strict thermal validation requirements. Automated storage and retrieval systems with thermal validation protocols open contract logistics to international manufacturers.
Frozen Goods holds installed capacity. Temperature-Sensitive Pharmaceuticals is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold storage rates in Shanghai command triple the per-pallet premiums of Sichuan basin facilities, compressing returns for operators lacking state-backed land access while creating arbitrage incentives for western expansion.
Yangtze River Delta
Shanghai, Hangzhou, and Nanjing cluster consumes over one-third of national chilled produce volume, generating route density that justifies dedicated multi-temperature consolidation centers. SAMR traceability mandates force warehouse automation investment across Zhejiang and Jiangsu provinces. JD Logistics anchors same-day delivery networks through proprietary robotics in this corridor.
Pearl River Delta
Guangzhou and Shenzhen drive pharmaceutical-grade cold chain demand from biologics manufacturing clusters in Dongguan and Foshan. MEE carbon reduction frameworks penalize diesel-refrigerated transport in Shenzhen metropolitan zones, accelerating electric fleet trials. Port-centric frozen goods corridors connect to Hong Kong re-export channels.
Beijing-Tianjin-Hebei
Capital region consumption pulls frozen meat and dairy through Tianjin port infrastructure while local MEE low-emission zones advance diesel phase-out timelines. Sinotrans Limited leverages rail connectivity to dominate cross-provincial frozen corridors serving northern markets. Land scarcity within fifty kilometers of Beijing absorbs disproportionate capital allocation.
Sichuan-Chongqing
Chengdu and Chongqing cold storage capacity per capita remains below one-third of eastern coastal levels, creating first-mover advantage for temperature-controlled fresh produce distribution. Dual carbon goals accelerate electric vehicle deployment despite sub-zero range constraints in western mountain corridors. Local platform operators consolidate fragmented owner-operator fleets through digital booking systems.
Shandong Peninsula
Qingdao and Yantai port infrastructure supports seafood export cold chains while Jinan serves as inland consolidation hub for northern produce. GB standards tightening for refrigerated vehicle construction raises equipment replacement cycles across provincial fleets. Agricultural processing clusters generate concentrated frozen goods volumes for rail-connected distribution.
China Cold Chain Logistics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying insulated containers, phase-change materials, and telemetry hardware. The competitive structure concentrates around state-backed logistics conglomerates with captive port and rail access, mid-scale regional operators serving single provinces, and e-commerce platforms with proprietary last-mile chilled networks. Two strategic archetypes dominate: infrastructure-heavy incumbents leveraging land access and policy relationships, and technology-native challengers deploying warehouse robotics and IoT compliance systems. Capacity expansion and fleet electrification represent the dominant competitive moves, with operators calibrating capex against municipal diesel phase-out timelines.
Within the state-backed infrastructure tier, Sinotrans Limited and Beijing Ershang Group occupy positions anchored by port, rail, and policy access. JD Logistics exemplifies the technology-native archetype, representing platform-scale investment in warehouse robotics and same-day urban chilled networks. SF Express sits within the integrated express-cold chain segment, leveraging existing sortation infrastructure for temperature-controlled parcel flows. These three entities collectively illustrate the competitive tension between asset-heavy incumbency and digital-native operational models reshaping capital deployment patterns.
| Leading Market Players |
|---|
| Sinotrans Limited |
| SF Express |
| Beijing Ershang Group |
| JD Logistics |
| China Merchants Americold Logistics |
| Nichirei Logistics Group |
| Shanghai Jin Jiang International Industrial Investment |
| CJ Rokin Logistics & Supply Chain |
| HNA Cold Chain |
| Others |
Supply Flow & Price Mechanics
MEE carbon reduction frameworks in Beijing, Shanghai, and Shenzhen metropolitan zones determine both pricing tier spreads and supply chain shape by penalizing diesel-refrigerated transport and compressing fleet renewal timelines.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade cold chain services from commodity frozen goods. Three-tier pricing structure across premium, standard, and economy levels applies across warehousing and transport segments. Price differentiation hinges on SAMR traceability compliance and NMPA licensing tiers. Cost compression in standard frozen corridors is intensifying because platform-based procurement concentrates volume with temperature-guaranteeing operators. Small owner-operators in the Yangtze River Delta exhibit highest price sensitivity; international biologics manufacturers show lowest sensitivity due to thermal validation requirements.
Supply Chain Analysis
Tariff exposure between China and key equipment sourcing markets for electric chassis and cryogenic cooling units dominates supply chain risk assessment. Manufacturing concentration rests on China, Germany, and Japan for refrigeration equipment and battery systems. Raw material dependencies include lithium-ion cells, ammonia refrigerants, and phase-change materials. Single-source vulnerability persists for ultra-low temperature storage compressors. Distribution runs through state-backed port and rail infrastructure operators alongside e-commerce platform consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across western provincial cold storage creates entry niches as Sichuan and Shaanxi per-capita capacity gaps widen against eastern benchmarks.
For Market Incumbents: Insulate core Yangtze River Delta positions through backward integration into electric chassis procurement and captive land access near Shanghai. SAMR traceability mandate compliance costs threaten margin structures for operators lacking warehouse automation. Certification investment in NMPA pharmaceutical-grade facilities represents the priority defensive lever against technology-native challengers. For New Entrants and Emerging Players: Western province temperature-controlled fresh produce distribution in Sichuan-Chongqing corridors represents the most penetrable entry point given sub-one-third per-capita capacity versus coastal levels. Hybrid electric-thermal storage architectures for pharmaceutical distribution address unmet ultra-low temperature integrity requirements during power transitions. Go-to-market positioning as MEE carbon credit monetization specialists unlocks municipal low-emission zone access. For Investors and Strategic Acquirers: Dual carbon goal diesel phase-out timelines reshape the acquisition landscape by accelerating electric fleet valuations and stranding legacy refrigerated vehicle assets. Five-to-ten-year viability favors platform-scale operators with proprietary IoT compliance systems over standalone equipment-reliant fleets. Target acquisition archetype: regional cold storage operators with state-backed land access in tier-one proximity. The signal to watch is municipal low-emission zone effective date acceleration in Beijing-Tianjin-Hebei and Pearl River Delta clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | MEE carbon frameworks in Beijing, Shanghai, and Shenzhen penalize diesel equipment and compress replacement cycles. |
| Pharmaceutical-Grade Certification Investment | NMPA licensing requirements for real-time thermal telemetry open contract logistics to international biologics manufacturers. |
| Western Province Capacity Buildout | Sichuan and Shaanxi cold storage gaps below one-third of eastern levels create first-mover arbitrage opportunities. |
| IoT Compliance Platform Deployment | SAMR traceability mandates digitize temperature documentation and reshape vendor qualification criteria. |
| Multi-Temperature Consolidation Center Development | Yangtze River Delta urban clustering generates route density justifying dedicated frozen-chilled-ambient orchestration facilities. |
Methodological Framework
Desk research of refrigerated vehicle OEM technical specifications, SAMR regulatory filings, and MEE carbon framework documentation preceded structured interviews with cold chain logistics operators, pharmaceutical distribution executives, warehouse automation specialists, and electric fleet procurement managers. Primary fieldwork combined with secondary validation against customs trade data, provincial cold storage capacity registries, and NMPA pharmaceutical distribution license databases. Bottom-up segment sizing and top-down macro reconciliation provided cross-checks.
Assumptions held fixed include SAMR traceability mandate enforcement timelines and MEE metropolitan low-emission zone expansion patterns; variables tested included electric vehicle battery density improvement trajectories and biologics distribution volume growth across the analysis window. Segmentation dimensions modeled encompass service type, end-use vertical, technology tier, product temperature band, and regional consumption cluster. CAGRs derived from logistic curve fitting to historical capacity installation and fleet procurement patterns. Industry-specific inputs included pharmaceutical cold chain compliance cost curves and land scarcity premium absorption rates near tier-one centers.
Macroeconomic conditions sit as an overlay; deviation in construction material costs, electricity pricing, and credit availability for infrastructure projects would shift the trajectory. Forecasts reflect documented assumptions regarding dual carbon goal implementation pace and biologics pipeline commercialization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Europe Logistics Automation Market