
 Maritime Logistics and Services Market | 2026-2036
Maritime Logistics and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Logistics and Services Market Intelligence
Asian shipyard output is broadening the available fleet for intermodal operators. Maersk leverages its integrated logistics platform to control end-to-end cargo flows across major trade lanes. Mediterranean Shipping Company anchors its expansion through aggressive vessel deployment and terminal investments. CMA CGM differentiates with specialized reefer services and regional feeder networks.
Maritime logistics and services encompasses the coordination, movement, and management of cargo via sea transport, typically involving vessels with capacities exceeding 10,000 TEU for mainline routes and dedicated port infrastructure for container handling. The sector functions through freight forwarding intermediaries, customs clearance agents, and terminal operators who synchronize multimodal handoffs between ocean, rail, and road carriers. Freight forwarding commands the largest service-type revenue pool due to its role in consolidating fragmented shipper demand. Container shipping dominates application-level volume, though liquid shipping retains premium rate structures tied to specialized tanker requirements. Automation technology represents the fastest-expanding technology segment as terminals pursue crane productivity targets and reduced vessel turnaround times.
The International Maritime Organization enforces carbon intensity indicators that mandate documented efficiency improvements for vessels above 5,000 gross tonnage. The European Union extends emissions trading to maritime routes calling at EU ports, directly elevating fuel cost structures for operators serving Rotterdam, Hamburg, and Antwerp. Port state control regimes under Paris MoU and Tokyo MoU inspect vessel compliance with safety and environmental standards, creating divergent market access conditions. Stakeholders must weigh fleet renewal timelines against alternative fuel infrastructure availability at priority ports.
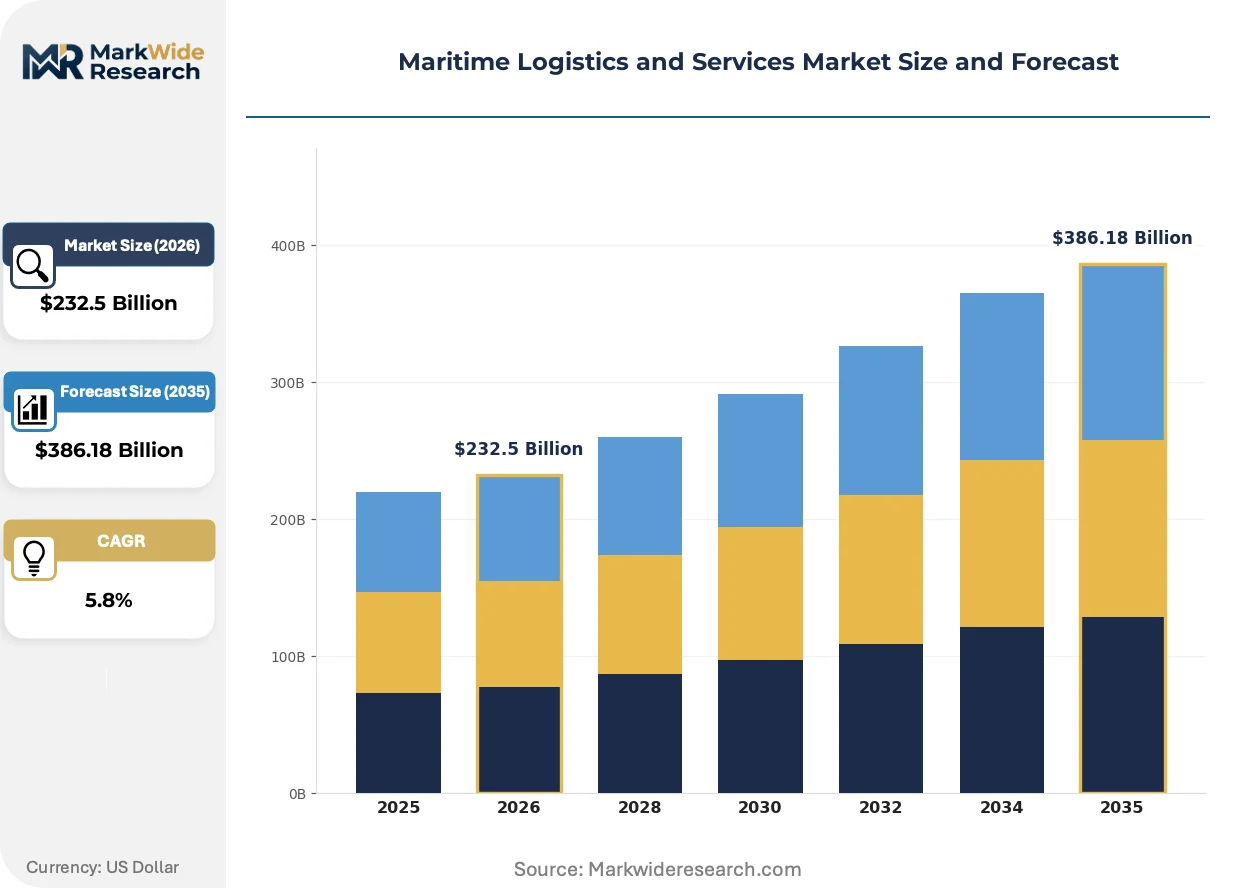
Market Dynamics
The International Maritime Organization's carbon intensity indicators are compressing fleet renewal timelines while simultaneously constraining available capital for vessel upgrades. This regulatory pressure intersects with port automation investments to reshape competitive positioning across container terminals and liner networks.
Growth Catalysts
- Cold Chain Pharmaceutical Demand:Temperature-sensitive biologics and vaccine distribution networks are expanding refrigerated container bookings across major trade lanes. Specialized reefer infrastructure investments follow pharmaceutical manufacturing concentration in Ireland and Singapore.
- EU Emissions Trading System Extension:Maritime routes calling at Rotterdam, Hamburg, and Antwerp now face direct carbon cost exposure. This policy mechanism accelerates scrubber retrofits and dual-fuel engine conversions on existing tonnage.
- Southeast Asian Transshipment Concentration:Singapore and Port Klang are capturing incremental hub volume as manufacturing supply chains diversify from single-origin dependence. Dedicated feeder networks and automated yard systems support this geographic shift.
Market Restraints
- Steel and Engine Cost Volatility:Newbuild vessel pricing fluctuates with specialty steel plate and two-stroke marine engine component availability. Korean and Chinese shipyards pass through material cost swings with limited contract flexibility.
- Alternative Fuel Infrastructure Gaps:Methanol and ammonia bunkering facilities remain concentrated at Rotterdam and Singapore. Vessel operators face stranded asset risk on routes lacking compatible refueling infrastructure.
- Paris MoU Inspection Regimes:Port state control detention rates for environmental compliance create unpredictable market access conditions. Substandard tonnage faces exclusion from Northern European cargo markets.
Strategic Opportunities
- Indian Subcontinent Port Modernization:Jawaharlal Nehru Port and Mundra are expanding automated terminal capacity to capture transshipment volume bypassing traditional hubs. Indian regulatory frameworks under Sagarmala support private terminal concessions.
- Digital Freight Platform Integration:API-connected booking systems are displacing traditional forwarder intermediation on Asia-Europe corridors. Real-time visibility tools compress documentation processing from days to hours.
- Green Methanol Supply Chain Development:Renewable methanol production facilities in Denmark and the Netherlands are creating compatible bunkering networks for dual-fuel newbuilds. Early-mover liner operators secure offtake agreements at fixed pricing.
Industry Challenges
- Maritime Cybersecurity Certification:IMO 2021 cybersecurity guidelines mandate documented risk management systems. Implementation timelines compress as flag states incorporate requirements into statutory audits.
- Legacy Terminal Operating System Migration:Decades-old mainframe architectures at established ports resist integration with cloud-based vessel scheduling platforms. Capital allocation debates delay modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Logistics and Services Market |
| Market Size in 2026 | $232.5 Billion |
| Market Size in 2035 | $386.18 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Customs Brokerage, Shipping Agency End User: Shipping Companies, Importers, Exporters, Freight Brokers Technology: Tracking Systems, Port Management Software, Cargo Handling Systems, Automation Technology Application: Container Shipping, Bulk Shipping, Liquid Shipping, Vehicle Transport |
| Companies Covered | COSCO Shipping Lines, Ocean Network Express (ONE), Mediterranean Shipping Company (MSC), Kuehne + Nagel, Evergreen Marine Corporation, Maersk, Hapag-Lloyd, DHL Supply Chain & Global Forwarding, CMA CGM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Logistics and Services Market Strategic Shifts & Innovations
Artificial intelligence applications are penetrating vessel routing optimization and predictive maintenance scheduling. These capabilities intersect with satellite connectivity improvements to enable real-time decision-making at sea.
Autonomous navigation systems are converging with shore-based remote monitoring centers to reduce crew requirements on deep-sea routes. Maersk and other integrated operators are piloting these capabilities on selected Asia-Europe sailings. Reduced manning levels compress operating cost structures while raising cybersecurity and liability coverage complexity.
The European Union's Fit for 55 regulatory package extends emissions trading to maritime transport with phased implementation through 2026. Liner operators serving EU ports must acquire carbon allowances or face operational penalties. This policy mechanism is accelerating scrubber retrofits and slow-steaming protocols on transatlantic and Asia-Europe services.
Shipper procurement patterns are compressing contract durations from annual to quarterly frameworks. Container lines face revenue volatility as spot market exposure increases. This behavioral shift is most pronounced among North American retailers and automotive manufacturers seeking supply chain flexibility.
Maritime Logistics and Services Market Segmentation
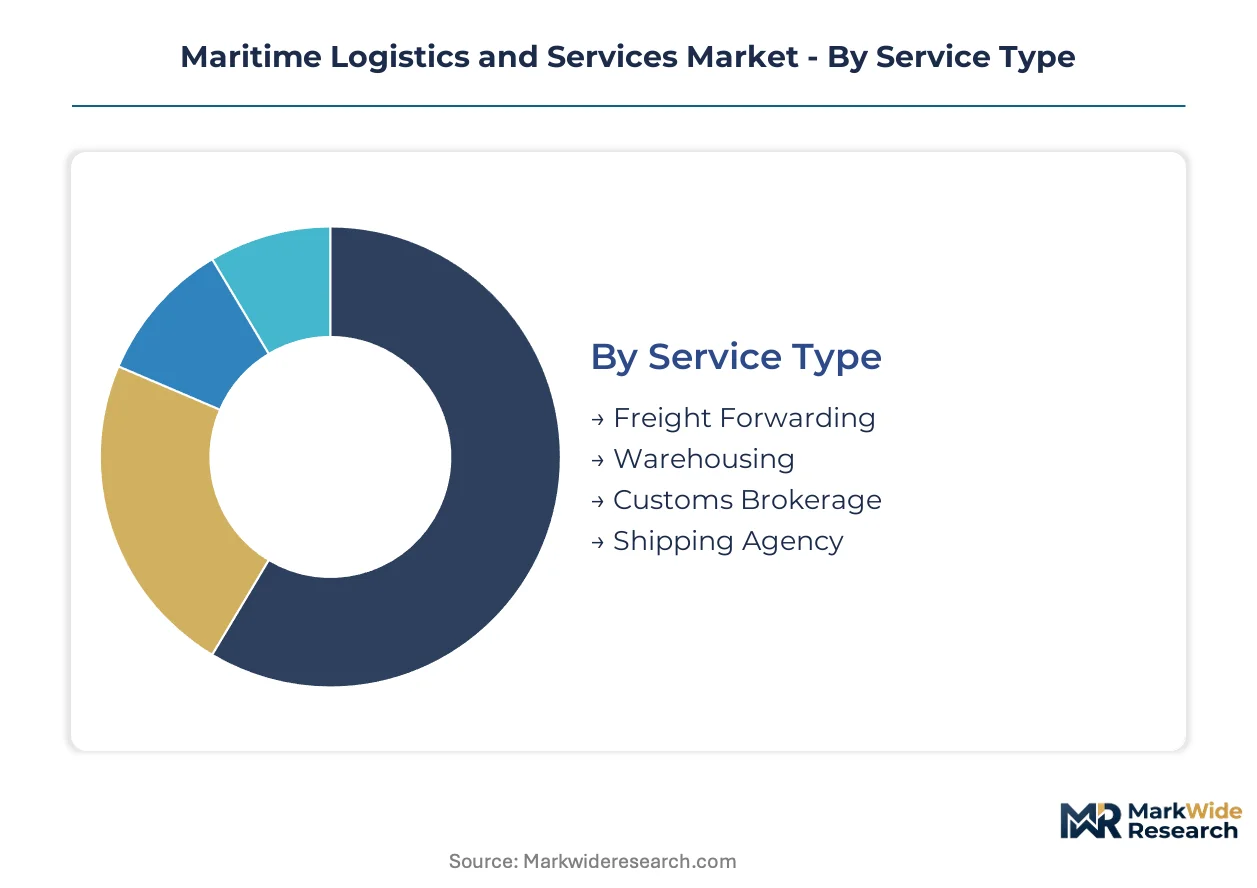
Segmentation reveals how maritime logistics value pools concentrate across service intermediaries, cargo handling technologies, and vessel applications. Understanding these splits exposes where capital deployment and regulatory exposure diverge most sharply across the value chain.
Service Type:
Shippers select service tiers based on documentation complexity, cargo value density, and multimodal coordination requirements rather than pure freight cost minimization.
- Freight Forwarding:Consolidates fragmented shipper demand into container volumes through NVOCC arrangements and carrier contract negotiations. Pharmaceutical and automotive manufacturers in Ireland and Singapore drive specialized forwarding demand for temperature-controlled and just-in-time cargo. Regulatory fragmentation across EU emissions trading and IMO carbon intensity rules elevates compliance documentation burdens.
- Warehousing:Provides bonded storage, value-added processing, and inventory positioning at port-centric logistics parks. Demand clusters at Rotterdam and Singapore where free trade zone status supports re-export processing. Cold chain pharmaceutical storage commands premium rates due to validated temperature mapping requirements.
- Customs Brokerage:Manages tariff classification, duty drawback claims, and origin certification for cross-border cargo. Complexity escalates with EU carbon border adjustment mechanisms and divergent ASEAN customs union protocols.
- Shipping Agency:Coordinates vessel husbandry, crew changes, and bunker supply at port calls. Agency margins compress at automated terminals with reduced stevedoring coordination needs.
Freight forwarding leads volumes today; automation technology integration is gaining share fastest across service tier differentiation.
End User:
Procurement scale and contract duration separate these buyer categories more than cargo type or trade lane selection.
- Shipping Companies:Integrated liner operators like Maersk and MSC source terminal services, agency networks, and feeder coordination through long-term framework agreements. Vessel deployment decisions at Asia-Europe and transatlantic frequencies determine service procurement volumes.
- Importers:Retailers and manufacturers purchasing FOB or CIF terms require destination customs clearance and inland distribution. North American retail procurement patterns are compressing contract durations toward quarterly frameworks.
- Exporters:Agricultural and industrial shippers in Brazil, Australia, and the US Gulf Coast book bulk and container capacity through forwarder intermediaries. Seasonal harvest windows create demand spikes for specialized reefer and open-top equipment.
- Freight Brokers:Digital platforms and traditional intermediaries match spot cargo with available vessel space. API-connected booking systems are displacing voice brokerage on major trade lanes.
Shipping companies anchor contract value today; freight brokers are expanding most quickly through platform disintermediation.
Technology:
Technology adoption separates terminals and carriers by crane productivity, vessel turnaround compression, and visibility service tier.
- Tracking Systems:Satellite-connected container devices provide location, temperature, and shock monitoring for high-value cargo. Pharmaceutical and electronics shippers mandate real-time visibility as a service baseline.
- Port Management Software:Optimizes berth allocation, yard planning, and gate appointment scheduling through algorithmic dispatch. TOS migration from legacy mainframes to cloud architectures remains capital-intensive at established ports.
- Cargo Handling Systems:Automated guided vehicles and rail-mounted gantry cranes stack containers in high-density yard configurations. Jawaharlal Nehru Port and Mundra are deploying these systems to capture transshipment volume.
- Automation Technology:Remote-operated ship-to-shore cranes and autonomous yard tractors reduce labor exposure and expand operating windows. This segment climbs the fastest as terminals pursue productivity targets and IMO cybersecurity guidelines mandate system hardening.
Tracking systems dominate installed base today; automation technology shows the steepest expansion trajectory through crane productivity mandates.
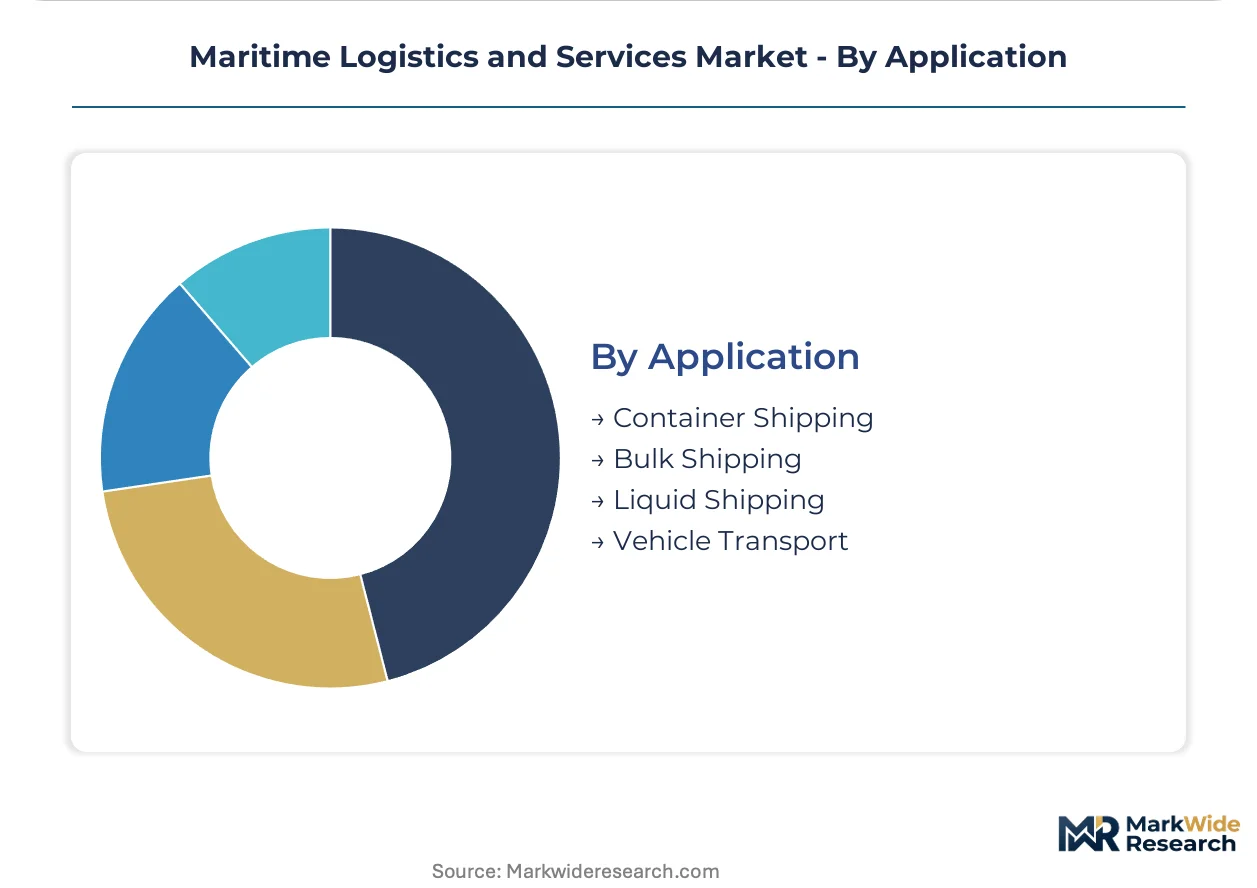
Application:
Vessel specialization and cargo stowage requirements create divergent rate structures and fleet investment cycles across shipping modes.
- Container Shipping:Deploys cellular vessels with capacities exceeding 10,000 TEU on mainline routes, supported by feeder networks at transshipment hubs. Southeast Asian hub concentration at Singapore and Port Klang is reshaping network design.
- Bulk Shipping:Transports iron ore, coal, and grain through dedicated Capesize and Panamax vessels. Steel and engine cost volatility at Korean and Chinese shipyards directly impacts newbuild availability.
- Liquid Shipping:Requires double-hull tanker construction and specialized cargo handling for crude, chemicals, and LNG. Premium rate structures persist due to specialized infrastructure and regulatory certification burdens.
- Vehicle Transport:Pure car and truck carriers accommodate finished vehicle roll-on/roll-off cargo with adjustable deck configurations. Automotive manufacturer supply chain diversification is expanding route requirements.
Container shipping leads volumes today; liquid shipping retains the strongest rate premiums through specialized tanker requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting maritime investment toward jurisdictions with faster port automation permitting and lower carbon compliance costs. Operators are relocating fleet management functions to capture these divergent cost structures.
China
Shanghai and Ningbo-Zhoushan handle the world's largest container throughput volumes, driven by manufacturing export concentration along the Yangtze River Delta. The Ministry of Transport enforces domestic emission control areas requiring low-sulfur fuel use at major coastal ports. COSCO Shipping Lines anchors fleet deployment decisions from Shanghai headquarters, coordinating vessel scheduling across Asia-Europe and transpacific strings.
Singapore
Transshipment hub status attracts pharmaceutical cold chain investments and LNG bunkering infrastructure development. The Maritime and Port Authority administers port dues incentives for vessels exceeding environmental certification thresholds. Tuas Port automation deployment is compressing vessel turnaround times to under 12 hours for mainline calls.
Germany
Hamburg and Bremerhaven serve as Northern European gateway terminals for automotive and machinery exports. The EU Emissions Trading System extension to maritime routes imposes direct carbon cost exposure on operators calling at German ports. German shipowners are accelerating scrubber retrofits to defend route profitability under the new allowance regime.
United States
Los Angeles-Long Beach and Savannah handle peak import volumes from Asian manufacturing origins. The Environmental Protection Agency enforces vessel emission standards under the Clean Air Act for operations within 200 nautical miles of the coast. East Coast port expansions at Charleston and New York-New Jersey are capturing volume diversion from West Coast congestion.
Netherlands
Rotterdam functions as Europe's primary alternative fuel bunkering hub with methanol and ammonia infrastructure investments. The Port of Rotterdam Authority coordinates with the EU Green Deal implementation timeline for maritime decarbonization. Maasvlakte terminal automation is setting productivity benchmarks for European container handling.
Maritime Logistics and Services Market Key Industry Players
European operators anchor the premium service tier; Asian specialists hold volume leadership through fleet scale advantages. Market structure consolidates around integrated liner networks controlling terminal assets and inland distribution. Three archetypes dominate: asset-heavy integrated carriers, digital-forward freight forwarders, and regional feeder specialists. Competitive moves concentrate on terminal concession acquisitions and alternative fuel offtake agreements.
Within the integrated carrier tier, Maersk and MSC exemplify end-to-end logistics platform strategies, while CMA CGM occupies a position emphasizing specialized reefer capabilities. Kuehne + Nagel represents the freight forwarding archetype with digital booking infrastructure. These anchors illustrate how capital deployment separates asset owners from service intermediaries in current market conditions.
| Leading Market Players |
|---|
| COSCO Shipping Lines |
| Ocean Network Express (ONE) |
| Mediterranean Shipping Company (MSC) |
| Kuehne + Nagel |
| Evergreen Marine Corporation |
| Maersk |
| Hapag-Lloyd |
| DHL Supply Chain & Global Forwarding |
| CMA CGM |
| Others |
Cost & Logistics Intelligence
Quarterly procurement compression from North American retailers and automotive manufacturers is forcing liner operators to absorb spot market volatility while maintaining service frequency on Asia-Europe and transpacific strings. This demand-side contracting shift elevates working capital requirements and compresses margin buffers across freight forwarding intermediaries and vessel operators alike.
Pricing Analysis
Freight forwarder margin layers absorb the primary pricing pressure as NVOCC arrangements consolidate fragmented shipper demand into container volumes. Three-tier pricing structure across premium reefer, standard dry container, and economy break-bulk levels stratifies by cargo value density and documentation complexity. Cost compression in standard dry container tiers is intensifying because steel and engine cost volatility at Korean and Chinese shipyards limits contract flexibility. Automotive manufacturers exhibit the highest price sensitivity due to just-in-time inventory requirements, while pharmaceutical shippers accept premium rates for validated cold chain infrastructure.
Supply Chain Analysis
Direct-to-carrier channels handle hyperscale demand from integrated liner operators like Maersk and MSC, while forwarder intermediation serves fragmented agricultural and industrial exporters. Manufacturing concentration draws from China, South Korea, and Vietnam for container production, specialty steel plate, and two-stroke marine engine components. Supply chain risk centers on single-source vulnerability for methanol and ammonia bunkering infrastructure concentrated at Rotterdam and Singapore. Distribution runs through automated transshipment hubs at Singapore, Port Klang, and Jawaharlal Nehru Port with feeder network extensions to secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Emissions Trading System carbon costs at Rotterdam and Hamburg diverge sharply from Southeast Asian hub economics, redirecting fleet deployment and terminal investment toward jurisdictions with lower compliance burdens.
For Market Incumbents: Acquire automated terminal concessions at Indian Subcontinent ports to preempt transshipment volume diversion from traditional Singapore and Port Klang hubs. Integrate backward into green methanol supply chains through offtake agreements with Danish and Dutch production facilities to defend route profitability against EU carbon allowance exposure. Digital freight platforms threatening forwarder intermediation demand API-connected booking system investments to retain Asia-Europe corridor share.
For New Entrants and Emerging Players: Mid-sized pharmaceutical manufacturers in Ireland and Singapore represent an underserved buyer archetype seeking specialized reefer forwarding without integrated liner minimum volume commitments. Cold chain pharmaceutical distribution networks offer the most penetrable segment given validated temperature mapping requirements that deter generalist competitors. A go-to-market angle anchored in satellite-connected container visibility devices can displace legacy tracking systems on high-value electronics and biologics lanes.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional feeder specialists controlling dedicated networks at Southeast Asian transshipment hubs. Long-term viability over the projection horizon favors operators with dual-fuel newbuild orderbooks and compatible bunkering infrastructure access. Watch for inflection signals in IMO cybersecurity guideline implementation timelines as flag states incorporate requirements into statutory audits and elevate compliance costs for substandard tonnage.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Deployment | Remote-operated ship-to-shore cranes at Tuas Port compress vessel turnaround below 12 hours. |
| Alternative Fuel Supply Agreement | Green methanol offtake contracts with Rotterdam and Singapore bunkering networks secure dual-fuel vessel utilization. |
| Digital Platform Integration | API-connected booking systems displace voice brokerage on Asia-Europe corridors through real-time visibility. |
| Cold Chain Infrastructure Expansion | Specialized reefer investments at Ireland and Singapore pharmaceutical clusters capture biologics distribution growth. |
| Feeder Network Acquisition | Regional specialists at Port Klang and Jawaharlal Nehru Port capture transshipment volume from manufacturing diversification. |
Research Approach
Multiple input streams — primary interviews with liner operator fleet managers, terminal operations directors, and freight forwarding procurement leads; secondary validation through IMO regulatory filings, EU Emissions Trading System documentation, and port authority throughput statistics — were reconciled through bottom-up and top-down triangulation. Customs and trade data from major transshipment hubs supplemented vessel deployment schedules and container equipment fleet databases. Stakeholder perspectives from pharmaceutical supply chain managers and automotive logistics directors provided demand-side validation for service tier segmentation.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented modeling of service type, technology adoption, and application mode. Segmentation dimensions included freight forwarding versus warehousing versus customs brokerage, automation technology penetration tiers, and container versus bulk versus liquid shipping applications. CAGRs were derived from vessel orderbook analysis, terminal capacity expansion timelines, and regulatory implementation schedules. Forecast inputs incorporated carbon intensity indicator compliance costs and alternative fuel infrastructure development curves.
Underlying measurement precision varies by segment; automation technology and cold chain pharmaceutical service tiers carry tighter precision than legacy break-bulk and general cargo categories due to equipment tracking granularity. Forecasts reflect base assumptions around IMO regulatory enforcement consistency and EU carbon allowance pricing trajectories that could shift with policy amendments or macroeconomic disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Iraq Air Freight Transport Market