
 UK Countertop Ice Makers Market | 2026-2036
UK Countertop Ice Makers Market Size, Share, and Industry Trends Forecast 2026-2036
UK Countertop Ice Makers Market Insights
East Asian manufacturing capacity is reconfiguring supply timelines for UK importers of compact refrigeration equipment. Tefcold leverages its European distribution network to sustain rapid replenishment cycles across British catering supply chains. Nisbets anchors its market presence through deep catalog penetration within the UK hospitality procurement channel. Polar Refrigeration differentiates via specialized warranty terms that reduce downtime risk for commercial end users.
Countertop ice makers are self-contained, electrically powered appliances designed to produce and store ice cubes or nuggets within a compact footprint typically under 50 centimetres in width, employing compressor-driven refrigeration cycles or thermoelectric cooling plates to freeze water in removable trays or auger systems. Their primary commercial purpose is to deliver on-demand ice production for food service operations and residential settings where permanent plumbing connections for built-in units are impractical or unavailable. Portable ice makers occupy the fastest-expanding product tier as urban renters and caravan owners prioritise mobility over capacity. Air-cooled compressor technology leads unit economics for mid-market models, while thermoelectric variants capture premium positioning through silent operation in open-plan kitchen environments.
The UK Office for Product Safety and Standards enforces electrical safety compliance through BS EN standards, while Ecodesign regulations mandate minimum energy efficiency thresholds that reshape compressor selection and insulation specifications for appliances sold in Great Britain. BSI certification requirements for electromagnetic compatibility add testing burdens that favour established suppliers with dedicated conformity assessment resources. Stakeholders must monitor potential divergence between retained EU law and forthcoming UK-specific efficiency benchmarks as the government reviews its appliance energy framework.
Market Dynamics
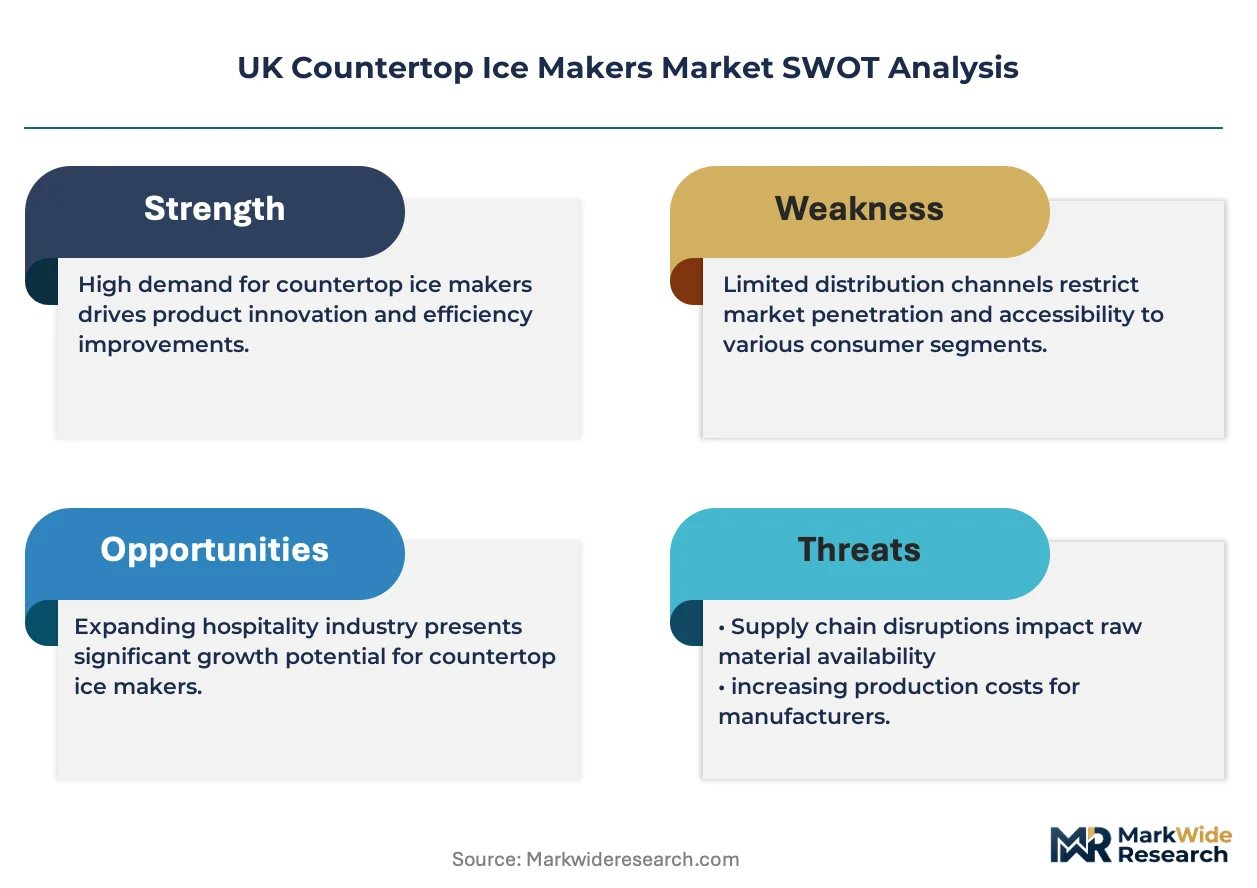
Ecodesign energy labelling mandates are compressing margins for compressor-dependent manufacturers while accelerating thermoelectric R&D investment cycles across British supply chains.
Growth Catalysts
- Apartment living density:Greater London's high-rise residential stock limits full-size freezer installations, funnelling demand toward sub-50cm countertop units. Boutique hospitality venues in Manchester and Birmingham replicate this procurement pattern.
- Ecodesign framework:Retained EU efficiency thresholds drive manufacturers toward lower-consumption compressor designs, creating product refresh cycles that stimulate replacement demand among commercial operators.
- Caravan and motorhome ownership:Portable thermoelectric variants capture demand from UK leisure vehicle owners prioritising off-grid ice production without permanent plumbing.
Market Restraints
- Copper and refrigerant input costs:Compressor manufacturing depends on copper winding and HFC refrigerant supplies exposed to commodity volatility and F-Gas Regulation phase-down schedules.
- East Asian supply concentration:Component sourcing clusters in Guangdong and Zhejiang provinces expose UK importers to shipping timeline compression and tariff uncertainty.
- Water reservoir capacity limits:Countertop units cap daily output at 12-15 kilograms, disqualifying them from high-volume food service operations requiring 50+ kilogram daily ice.
Strategic Opportunities
- Scotland and Northern England penetration:Edinburgh, Glasgow, and Leeds exhibit lower countertop ice maker saturation relative to London, presenting whitespace for regional distribution partnerships.
- Smart home integration:WiFi-enabled ice production scheduling and filter replacement alerts converge with broader UK connected kitchen adoption curves.
- Extended producer responsibility frameworks:Anticipated UK appliance recycling mandates create first-mover advantage for manufacturers designing modular, repairable compressor assemblies.
Industry Challenges
- BSI electromagnetic compatibility certification:Testing timelines for BS EN 55014 compliance extend 8-12 weeks, delaying product launches for entrants lacking established conformity assessment relationships.
- Thermoelectric cooling efficiency gaps:Peltier plate systems deliver slower freeze cycles than compressor alternatives, requiring engineering trade-offs between silence and throughput that limit commercial viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Countertop Ice Makers Market |
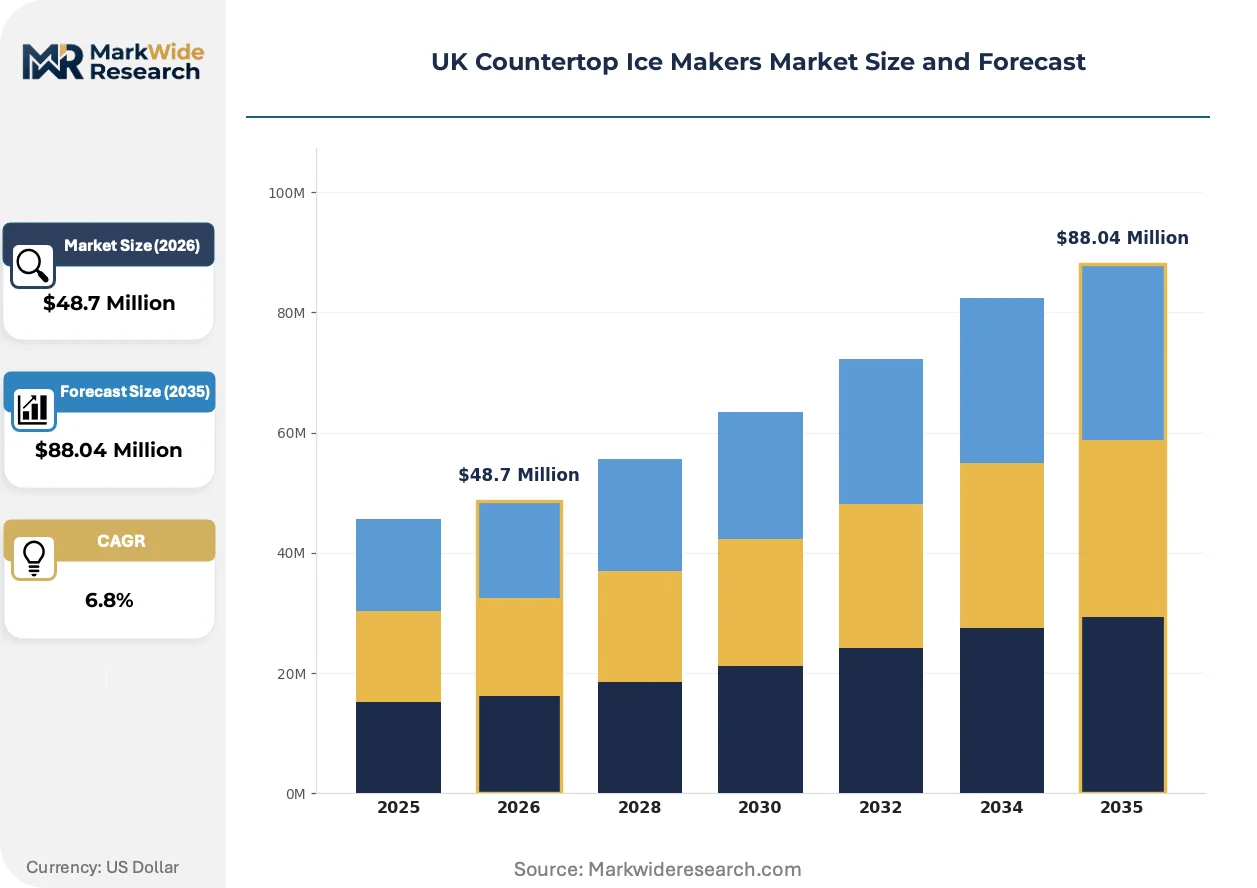
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ice Makers, Built-In Ice Makers, Modular Ice Makers, Under-Counter Ice Makers End User: Homes, Restaurants, Bars, Cafés Technology: Air-Cooled, Water-Cooled, Ice-Freezing, Thermoelectric Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | Tefcold, Nisbets, Cooks Professional, Geepas, Polar Refrigeration, Direct Catering Products Ltd, NewAir, Whynter LLC, Igloo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Countertop Ice Makers Market Trends and Innovations
Silent operation specifications are rewriting competitive differentiation as open-plan kitchen layouts proliferate across UK residential new-builds and boutique hotel fit-outs.
Compressor-driven refrigeration is migrating from standard reciprocating designs toward variable-speed inverter compressors. Premium residential developers in Surrey and Berkshire specify these units for luxury apartment installations. The technology is migrating from commercial refrigeration into countertop formats, compressing noise output below 42 decibels and enabling placement in living areas without acoustic isolation.
Retained EU Ecodesign regulations mandate minimum energy efficiency thresholds that reshape insulation specifications and compressor selection for Great Britain. The UK's Office for Product Safety and Standards enforces compliance through market surveillance programmes. Commercial catering procurement teams now filter supplier shortlists by verified energy label ratings, privileging A-grade units in tender evaluations.
Direct-to-operator e-commerce channels are displacing traditional catering equipment distributors for sub-£500 portable units. Amazon Business and Nisbets' digital platform capture growing share from regional dealer networks. This pattern concentrates in Greater London and the South East, where rapid delivery expectations and price transparency accelerate channel switching among independent cafés and mobile catering operators.
UK Countertop Ice Makers Market Segmentation
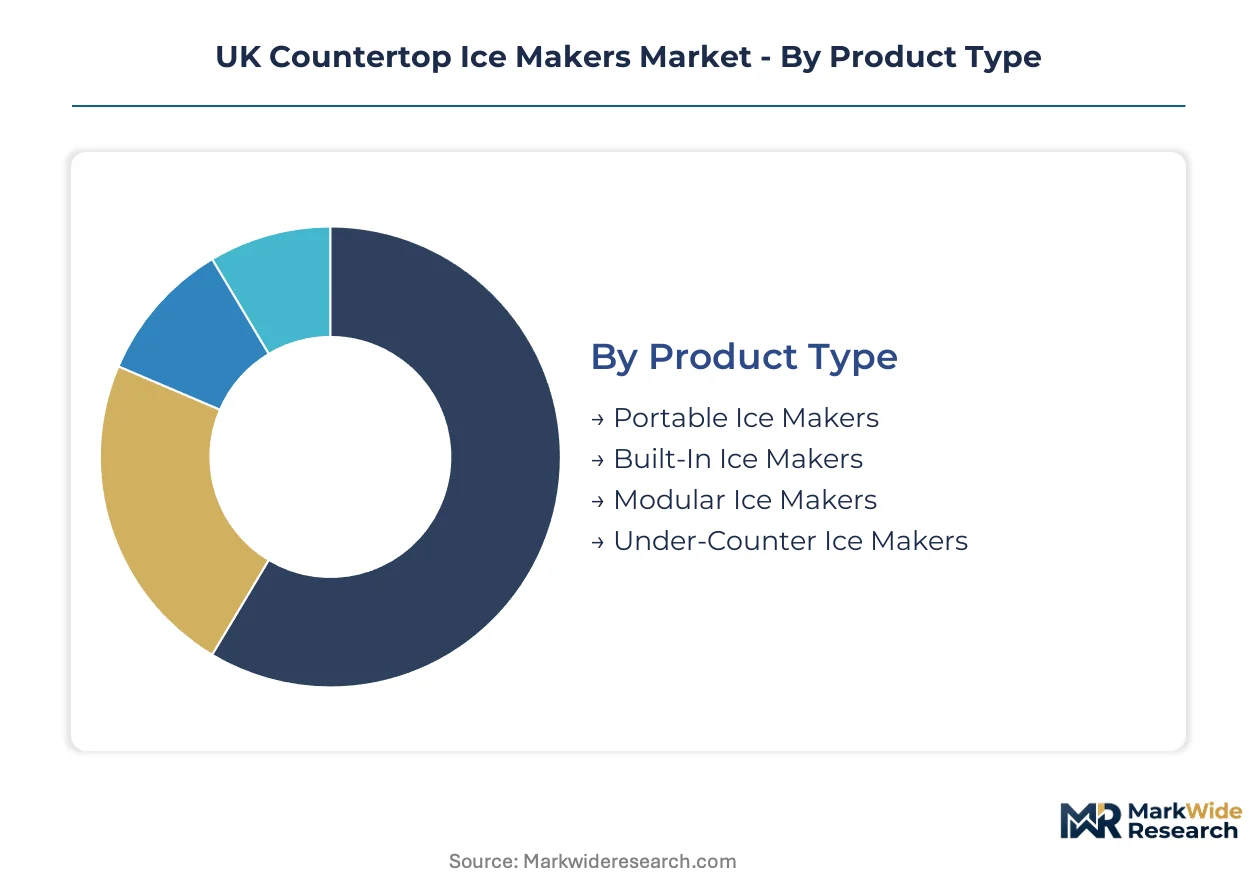
Countertop ice maker procurement patterns diverge sharply across installation constraints, operational intensity, and buyer sophistication. Segment-specific service requirements and replacement cycles reshape margin structures for British distributors and manufacturers serving this compact appliance category.
Product Type:
After-sales service intensity varies dramatically by installation permanence, with portable units demanding minimal technical support while built-in and modular systems require specialized technician networks across UK urban centres.
- Portable Ice Makers:Self-contained units with manual water reservoirs and gravity drainage dominate caravan parks and rental apartment segments. Demand concentrates in Greater London's high-rise residential stock where permanent plumbing modifications are prohibited by leasehold restrictions. These units generate the highest return rates due to scale formation and pump failures, driving aftermarket filter and descaling kit sales.
- Built-In Ice Makers:Front-venting designs integrate beneath countertops with dedicated water lines and drain connections. Premium kitchen renovations in Surrey and Berkshire specify these for seamless aesthetic alignment. Installation complexity requires certified plumber coordination, elevating total cost of ownership and locking in regional dealer relationships for warranty service.
- Modular Ice Makers:Stackable bin-and-head configurations suit boutique Manchester hotels needing 50-100 kilogram daily output without floor-standing footprints.
- Under-Counter Ice Makers:Enclosed cabinet designs with finished sides serve Birmingham café chains prioritizing front-of-house placement flexibility.
By volume, Portable Ice Makers leads. By growth pace, Built-In Ice Makers is ahead.
End User:
Cost tier stratification separates residential impulse purchases from commercial procurement governed by total cost of ownership calculations and energy label compliance verification.
- Homes:Urban renters and suburban homeowners seeking convenience without freezer compartment sacrifice. Edinburgh and Glasgow flat conversions drive Scottish demand where kitchen square footage averages 40% below London standards.
- Restaurants:Independent operators in Leeds and Newcastle require 15-25 kilogram daily output for beverage service without central ice plant investment. These buyers prioritize rapid delivery and 24-hour replacement guarantees over unit price.
- Bars:Cocktail-focused venues demand clear, slow-melting cube geometries that compressor-driven units deliver more reliably than thermoelectric alternatives.
- Cafés:Counter service models in Brighton and Bristol select compact footprints that preserve workspace for point-of-sale equipment and display cases.
Homes dominates unit shipments. Bars commands the steepest expansion trajectory as craft cocktail culture penetrates secondary UK cities.
Technology:
Application environment dictates cooling architecture selection, with noise sensitivity and ambient temperature tolerance driving divergence between residential and commercial specifications.
- Air-Cooled:Compressor-driven systems with forced convection dominate mid-market commercial installations. Manchester and Birmingham food service operations favor these for reliability and repair parts availability through Tefcold's distribution network.
- Water-Cooled:Heat exchange via incoming water supply suits high-temperature kitchen environments where ambient air exceeds 32°C. These units face regulatory pressure under Ecodesign water efficiency thresholds.
- Ice-Freezing:Batch production methods using refrigerated plates capture economy-tier residential demand through supermarket retail channels.
- Thermoelectric:Peltier plate cooling eliminates compressor noise for open-plan kitchen layouts in premium London residential new-builds. Slower freeze cycles limit commercial viability despite silent operation advantages.
Air-Cooled leads installed base. Thermoelectric is gaining share fastest among premium residential developers.
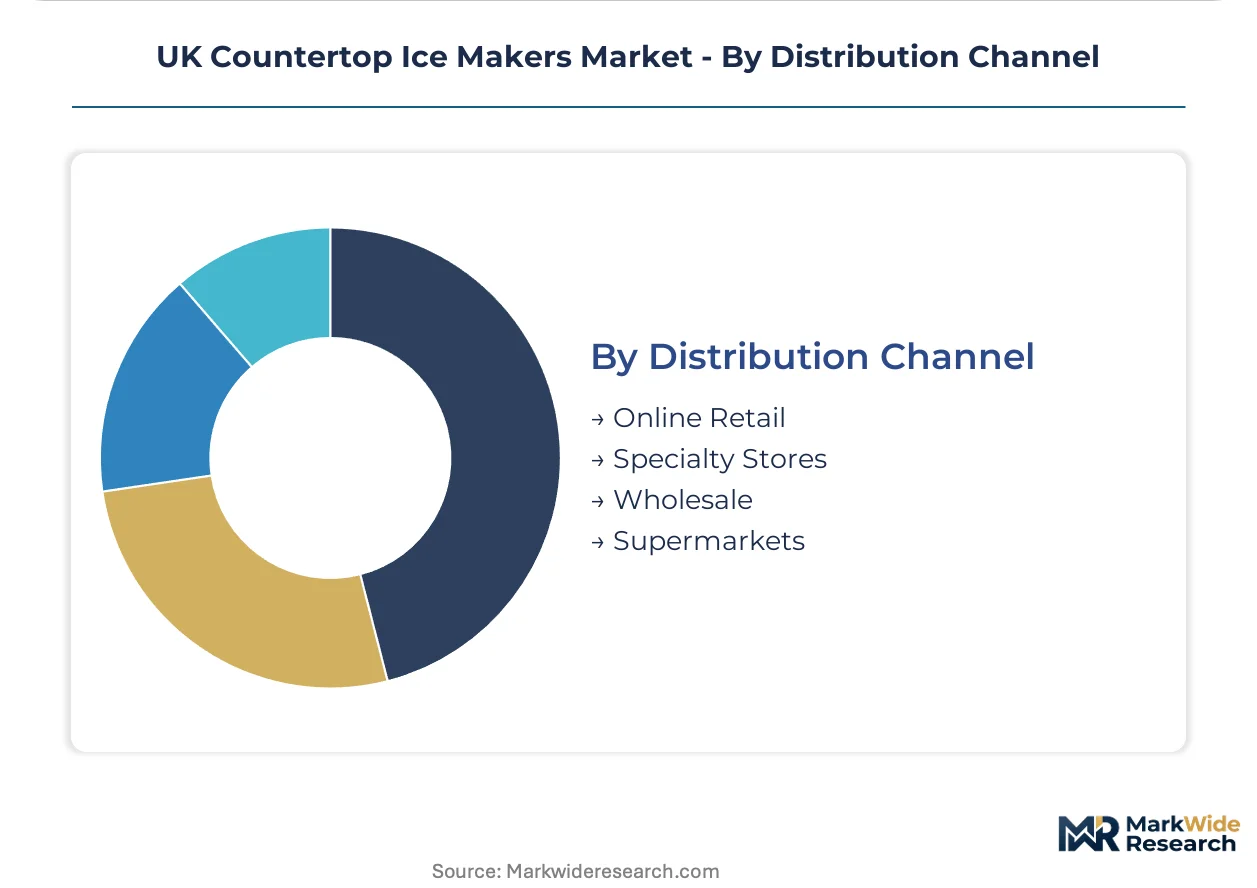
Distribution Channel:
Customer type and purchase urgency determine channel selection, with commercial operators maintaining hybrid procurement strategies across digital platforms and established dealer relationships.
- Online Retail:Amazon Business and Nisbets' digital platform capture sub-£500 portable unit sales from independent cafés and mobile catering operators. Greater London buyers expect next-day delivery as standard.
- Specialty Stores:Regional catering equipment dealers in Glasgow and Leeds provide specification guidance and installation coordination for built-in and modular systems.
- Wholesale:Cash-and-carry depots serve high-volume restaurant groups with consolidated procurement across refrigeration categories.
- Supermarkets:Currys and John Lewis stock impulse-purchase portable units for residential buyers prioritizing immediate availability over technical consultation.
Online Retail leads transaction volume. Specialty Stores retains margin superiority through service attachment and installation revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Office for Product Safety and Standards enforces Ecodesign compliance across Great Britain, anchoring regulatory gravity in the UK. Regional demand concentrates in high-density urban centres where apartment living and boutique hospitality limit full-size appliance installations.
Greater London and the South East
Leasehold restrictions in high-rise residential stock prohibit permanent plumbing modifications, funnelling demand toward portable countertop units. Ecodesign energy labelling mandates drive commercial procurement teams toward A-grade compressor models. Canary Wharf and Shoreditch boutique hotels specify silent thermoelectric variants for open-plan bar installations.
Midlands
Birmingham café chains and Manchester boutique hospitality venues replicate London procurement patterns for compact ice production. The retained EU efficiency thresholds under UK Ecodesign regulations accelerate replacement cycles among independent restaurant operators. Leeds exhibits lower saturation relative to southern markets, presenting whitespace for regional distribution partnerships.
Scotland
Edinburgh and Glasgow flat conversions drive Scottish demand where kitchen square footage averages below London standards. The Scottish Government's building standards for energy efficiency align with Ecodesign thresholds, reinforcing specification requirements. Edinburgh's Old Town hospitality cluster sources portable units for listed building renovations where structural modifications face planning constraints.
North England
Newcastle and Liverpool independent operators require 15-25 kilogram daily output for beverage service without central ice plant investment. Local authorities enforce electrical safety compliance through BS EN standards surveillance programmes. Manchester's Northern Quarter bar district prioritises rapid delivery and 24-hour replacement guarantees over unit price in procurement decisions.
Wales and Northern Ireland
Cardiff and Belfast leisure vehicle owners capture portable thermoelectric demand for off-grid ice production in caravan parks. The UK's F-Gas Regulation phase-down schedules expose these peripheral markets to refrigerant supply volatility. Coastal tourism clusters in Pembrokeshire and the Antrim Coast drive seasonal demand spikes for compact refrigeration equipment.
UK Countertop Ice Makers Market Competitive Landscape
Capability concentration sits with established catering equipment specialists; scale advantage sits with diversified refrigeration manufacturers. The vendor base separates into three functional tiers: European distribution networks, domestic procurement platforms, and East Asian original equipment suppliers. Two strategic archetypes dominate competitive positioning—warranty-term differentiation and rapid replenishment cycle management. M&A activity remains minimal; portfolio diversification into adjacent compact refrigeration categories and geographic expansion through regional dealer partnerships represent the dominant competitive moves.
Among UK-based catering supply specialists, Nisbets anchors the procurement platform archetype through deep catalog penetration within the hospitality channel. Tefcold represents the European distribution network model, leveraging continental logistics infrastructure to sustain rapid replenishment cycles. Polar Refrigeration occupies the warranty-specialist position, reducing downtime risk for commercial end users through service-term differentiation. These three companies exemplify how competitive positioning in this market derives from channel control and post-sale risk transfer rather than manufacturing scale or proprietary technology.
| Leading Market Players |
|---|
| Tefcold |
| Nisbets |
| Cooks Professional |
| Geepas |
| Polar Refrigeration |
| Direct Catering Products Ltd |
| NewAir |
| Whynter LLC |
| Igloo |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Immingham freight corridor's container cost dynamics compress margins for UK distributors while amplifying price spreads between premium thermoelectric units and economy-tier compressor models. Guangdong-to-Southampton shipping timelines tether inventory carrying costs to seasonal demand spikes, forcing importers to balance bulk procurement discounts against working capital constraints. This logistics-cost feedback loop rewards established players with bonded warehousing capacity and squeezes smaller entrants reliant on spot freight rates.
Pricing Analysis
Geographic price spreads between Greater London and Northern England reach 15-20 percent for identical portable units, reflecting last-mile delivery cost stratification and dealer network density gaps. Three-tier pricing structure across premium inverter-compressor, standard reciprocating, and economy thermoelectric levels segments buyers by noise tolerance and installation permanence. Cost compression in the economy tier is intensifying because East Asian OEMs are bypassing British intermediaries for direct Amazon Business listings. Independent cafés in Manchester and Birmingham exhibit highest price sensitivity, while Surrey luxury apartment developers accept 40 percent premiums for sub-42 decibel specifications.
Supply Chain Analysis
Copper winding feedstock from Chile and Zambia, HFC refrigerant precursors from Chinese chemical complexes, and ABS plastic resin from South Korean petrochemical plants anchor component cost volatility. Compressor assembly concentrates in Guangdong and Zhejiang provinces, with thermoelectric Peltier plates sourcing primarily from Taiwanese semiconductor foundries. Single-source vulnerability in HFC-134a supply chains exposes UK importers to F-Gas Regulation phase-down disruption. Distribution runs through Nisbets' centralized fulfillment hub in Wigan, Tefcold's continental European cross-docking network, and Amazon Business's parcel delivery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regional hospitality procurement channels and diverging Ecodesign compliance timelines create niche entry points for specialized service providers. The shift toward direct-to-operator e-commerce dissolves traditional dealer territorial monopolies.
For Market Incumbents: Entrench warranty-service differentiation by deploying certified technician networks in Edinburgh and Leeds before regional competitors replicate Polar Refrigeration's downtime-guarantee model. Capture backward integration into inverter-compressor module refurbishment to offset copper price volatility and extend asset life for commercial fleet operators. The threat of East Asian OEMs establishing direct UK fulfillment centers demands preemptive channel-locking through exclusive distribution agreements with independent café purchasing cooperatives. For New Entrants and Emerging Players: Northern England's lower countertop ice maker saturation relative to Greater London presents whitespace for regional distribution partnerships targeting Newcastle and Liverpool independent operators. The caravan and motorhome segment offers the most penetrable entry vector, with seasonal demand spikes underserved by incumbent catering-focused logistics. A go-to-market angle combining portable thermoelectric units with descaling subscription services addresses the highest return-rate pain point in the residential tier. For Investors and Strategic Acquirers: Specialist warranty-service providers with captive technician networks in underserved UK regions offer the most defensible acquisition profile for long-term positioning. These assets compound value through recurring service revenue attachment rather than transactional equipment margins. The signal to watch is consolidation among East Asian OEMs establishing direct UK e-commerce presence, which would compress distributor multiples and accelerate channel disintermediation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Distribution Partnership | Edinburgh and Glasgow flat conversions drive Scottish demand where kitchen square footage constrains full-size installations. |
| Inverter-Compressor Module Refurbishment | Ecodesign efficiency thresholds extend replacement cycles and create aftermarket service revenue pools. |
| Direct-to-Operator E-Commerce Platform | Amazon Business and Nisbets' digital platform capture sub-£500 portable unit sales from mobile catering operators. |
| Silent Operation Specification Development | Premium London residential new-builds specify sub-42 decibel thermoelectric units for open-plan kitchen layouts. |
| Extended Producer Responsibility Design | Anticipated UK appliance recycling mandates reward modular, repairable compressor assembly architectures. |
Research Methodology
A spread of perspectives from commercial catering procurement managers, regional equipment dealers, Ecodesign compliance consultants, and caravan park operators converged on the working assumptions shaping this analysis. Primary interviews with Manchester boutique hotel owners and Birmingham café chain technical directors validated demand-side segmentation hypotheses. Secondary sources included UK Office for Product Safety and Standards enforcement bulletins, F-Gas Regulation implementation guidance, and British Retail Consortium customs data. Bottom-up unit shipment estimates triangulated against top-down hospitality sector capital expenditure surveys.
Demand-supply-balance modeling across the projection horizon anchored volume forecasts in leasehold restriction penetration rates and Ecodesign replacement cycle acceleration. Segmentation dimensions spanned installation type, cooling technology, end-user operational intensity, and regional urban density gradients. CAGRs derived from fitted S-curve adoption patterns for smart home integration features and variable-speed compressor migration. Industry-specific inputs included BS EN 55014 certification timeline distributions and copper futures curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive direct-to-consumer moves by Guangdong-based OEMs or accelerated UK-specific efficiency benchmark divergence would shift outcomes beyond modeled ranges. Quarterly review of Amazon Business category share shifts and F-Gas Regulation refrigerant quota auction prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Restaurant Equipment Market