
 Sunflower Husk Pellets Market | 2026-2036
Sunflower Husk Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Sunflower Husk Pellets Market Analytics
Automated pelletizing and torrefaction technology is fragmenting the traditional sunflower husk processing stack, enabling smaller mills to achieve industrial-grade combustion performance without massive capital outlays. CM Biomass leverages vertical integration from Ukrainian sunflower crushing facilities to finished pellet output, sustaining cost advantages across the Black Sea logistics corridor. EcoPellets competes through specialized heating pellet formulations calibrated for Central European boiler specifications. Biosemira anchors its position in animal bedding pellets, dominating Scandinavian equine and poultry farm supply chains through premium dust-control processing.
Sunflower husk pellets are compressed cylindrical fuel or bedding products manufactured from the lignocellulosic outer shell of Helianthus annuus seeds, typically extruded at 6-8mm diameter with bulk densities of 600-700 kg/m³ and moisture content below 10% to ensure stable combustion and storage. Their primary commercial purpose spans thermal energy substitution in residential and industrial boilers, plus absorbent bedding applications in livestock operations. Biofuel Pellets occupy the largest margin pool as power generators seek renewable alternatives to natural gas and lignite, while Animal Bedding Pellets extend into premium agricultural segments with lower volume but higher per-ton profitability. Heating Pellets lead unit growth in Polish and Romanian district heating retrofits, where municipal operators prioritize locally sourced biomass over imported wood pellets.
EU Green Deal emission benchmarks and the F-Gas Regulation indirectly pressure fossil fuel heating systems, creating compliance-driven demand for certified biomass alternatives across member states. REACH and ECHA frameworks govern chemical emissions from combustion appliances, shaping pellet quality standards and ash content thresholds that manufacturers must meet for CE-marked product access. Stakeholders should monitor how the EU AI Act and evolving carbon border adjustment mechanisms reshape certification costs and cross-border pellet trade flows.
Market Dynamics
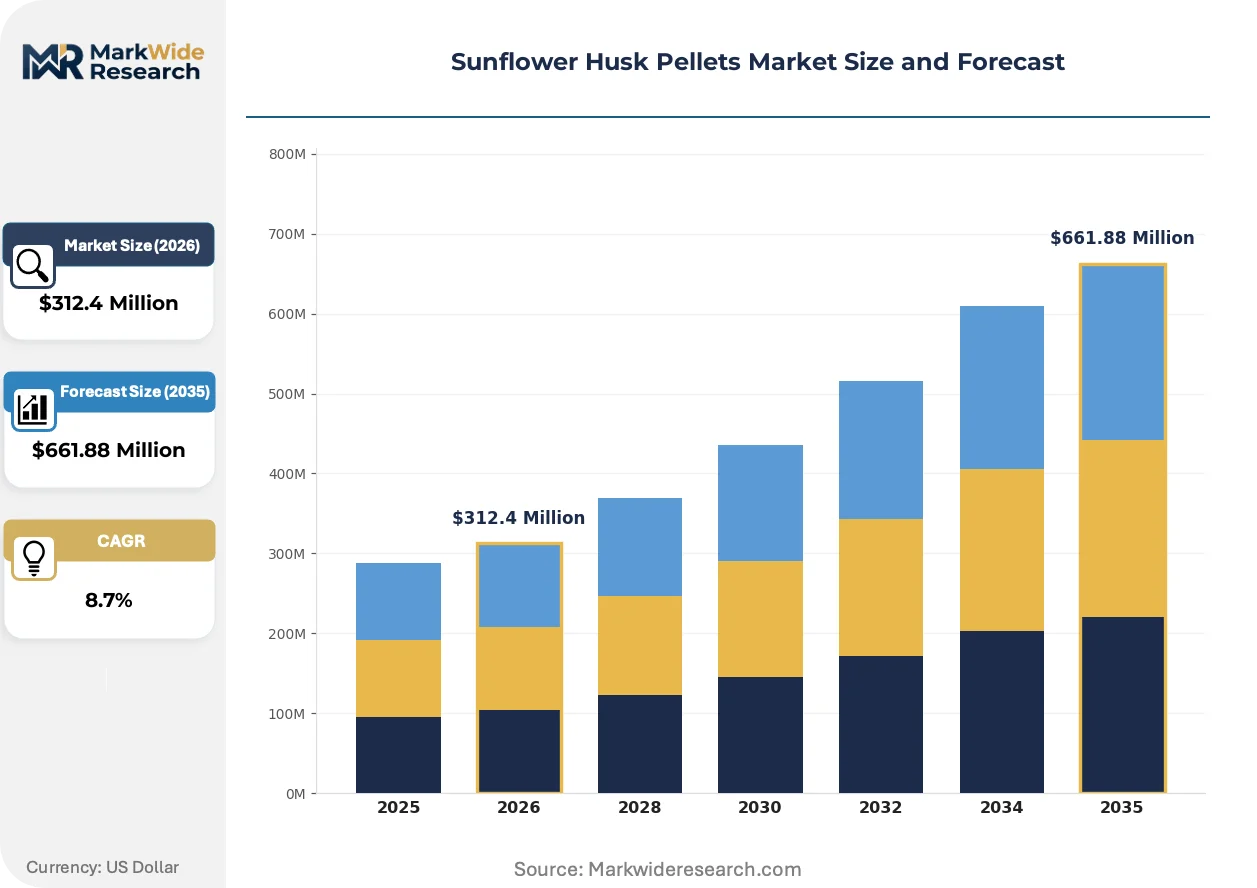
Automated torrefaction systems are compressing capital barriers for sunflower husk pellet producers, allowing regional mills in Bulgaria and Romania to achieve combustion specifications previously requiring industrial-scale infrastructure investments.
Growth Catalysts
- EU Green Deal emission benchmarks:Power generation utilities across Poland and Germany face binding coal-phaseout timelines, accelerating procurement of certified biomass substitutes for district heating feedstock.
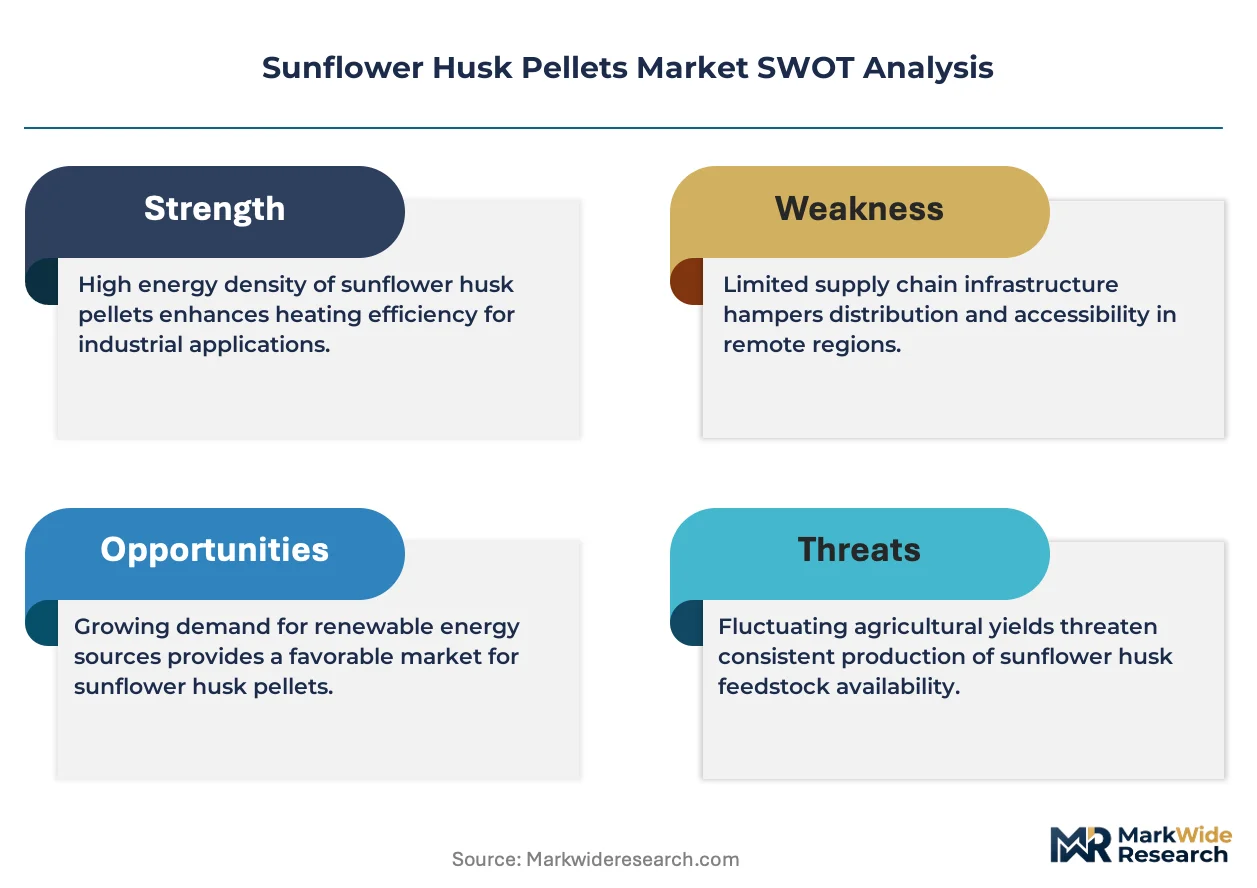
- Torrefaction technology maturation:Smaller pelletizing operations now achieve 18-20 MJ/kg calorific values without massive dryer investments, expanding viable producer bases beyond traditional crushing conglomerates.
- Ukrainian feedstock concentration:The Black Sea agricultural belt generates sufficient husk volume to supply multiple export-oriented pelletizing clusters with raw material cost advantages.
Market Restraints
- Input cost volatility:Sunflower oil market fluctuations directly compress husk availability and pricing, tying pellet economics to commodity cycles outside producer control.
- Supply concentration risk:Overreliance on Ukrainian crushing facilities for raw material exposes downstream processors to Black Sea logistics disruptions and geopolitical friction.
- Technical limitation:High chlorine and potassium content in sunflower husks accelerates boiler corrosion, limiting adoption in high-efficiency combined heat and power installations without flue gas treatment upgrades.
Strategic Opportunities
- Underpenetrated Scandinavian district heating:Swedish and Finnish municipal networks currently favor wood pellets, presenting conversion potential as sunflower husk achieves sustainability certification parity.
- Carbon border adjustment mechanisms:The EU's evolving CBAM framework disadvantages imported fossil fuel heating, creating tariff-driven preference for locally sourced biomass alternatives.
- Animal bedding premiumization:Dust-controlled pellet formulations command per-ton margins exceeding thermal grades, with equine and poultry operations in Denmark and Norway seeking absorbent substitutes for straw.
Industry Challenges
- Certification timeline compression:ENplus and sustainability scheme audits require 6-12 month validation cycles, delaying market access for new pelletizing entrants.
- Logistics reconfiguration friction:Transitioning from bulk agricultural husk transport to packaged pellet distribution demands cold-chain-adjacent moisture control investments unfamiliar to traditional crushing operators.
- Combustion engineering skill scarcity:Boiler operators lack training on high-ash sunflower husk firing protocols, creating adoption resistance at the facility level despite policy mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunflower Husk Pellets Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofuel Pellets, Biomass Pellets, Heating Pellets, Animal Bedding Pellets End Use Industry: Power Generation, Heating Solutions, Agricultural Industry, Feed Production Packaging Type: Bulk Bags, Standard Bags, Custom Bags, Loose Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | CM Biomass, Biosemira, EcoPellets, Green Energy Biofuel, Procarbon, JSC BIOGRA, Agripellets, BioPower Solutions, UKRAOIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunflower Husk Pellets Market Evolving Landscape
Processing technology convergence and regulatory compliance automation are restructuring competitive requirements across sunflower husk pellet manufacturing, favoring operators who integrate quality control systems with sustainability documentation.
Torrefaction-enhanced pellet production is rendering obsolete the traditional tradeoff between small-scale mill economics and industrial-grade combustion performance. Polish district heating cooperatives are adopting these upgraded fuels for base-load boiler operations previously reserved for wood pellets or natural gas. The technology is rendering obsolete capital-intensive dryer infrastructure as the primary barrier to market entry.
REACH and ECHA frameworks governing combustion appliance emissions are tightening ash content thresholds and heavy metal limits for CE-marked pellet products. Manufacturers must now integrate continuous emissions monitoring into production workflows to maintain certification validity. German and Austrian boiler OEMs are most affected, sourcing exclusively from suppliers with validated sustainability documentation.
Long-term offtake contracting is displacing spot-market purchasing among Central European power generators seeking supply security under renewable energy obligation schemes. Municipal district heating operators in Romania and Bulgaria are locking in three-to-five-year pellet supply agreements with fixed escalation clauses. This pattern is most visible in Poland, where state-owned utilities consolidate procurement through centralized biomass purchasing platforms.
Sunflower Husk Pellets Market Segmentation
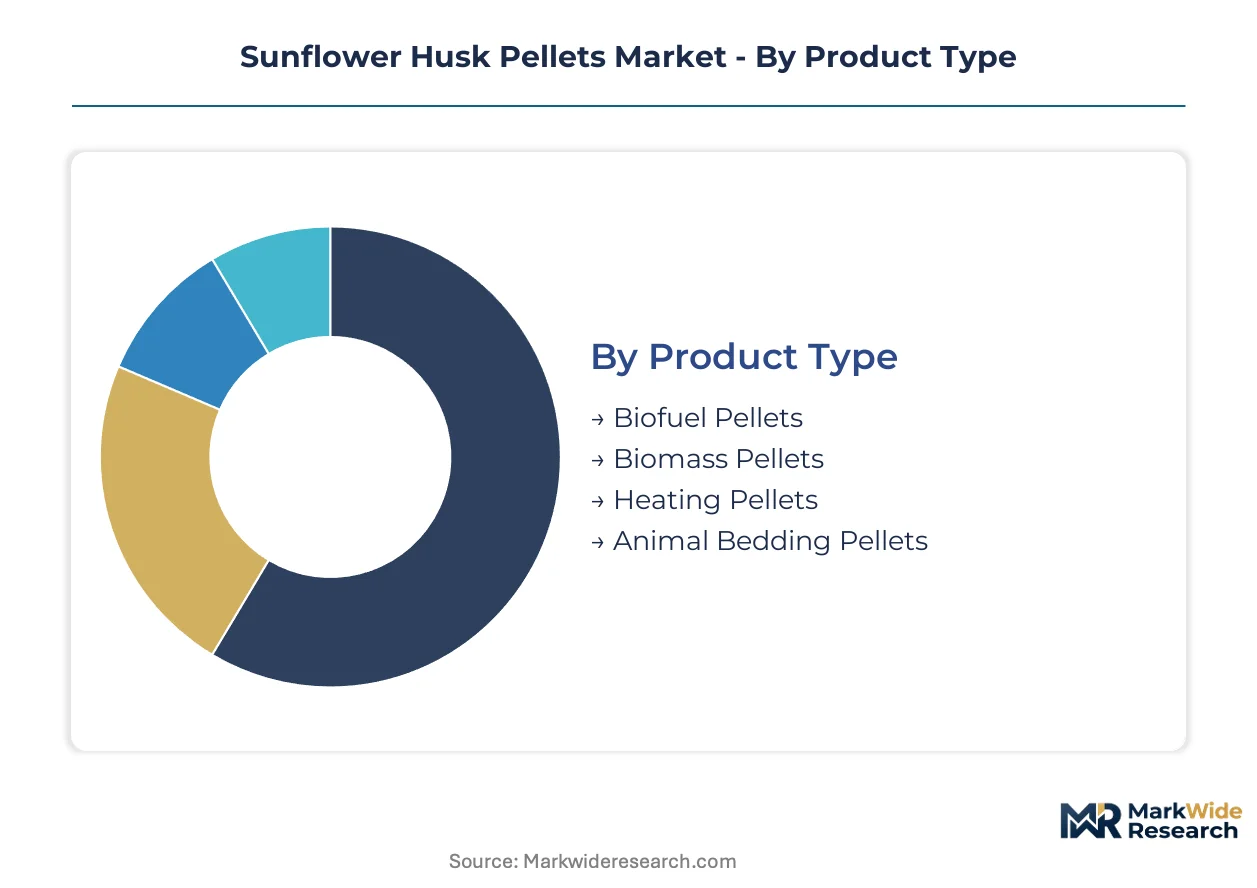
Product differentiation in sunflower husk pellets determines combustion performance specifications, logistics requirements, and margin structures across thermal energy and agricultural end-uses. Segmentation clarity enables procurement alignment with EU sustainability certification tiers and boiler OEM compatibility standards.
Product Type:
Application requirements split the product landscape across energy substitution versus absorbent bedding functions, with calorific value and dust-control specifications diverging sharply.
- Biofuel Pellets:Engineered for 18-20 MJ/kg calorific output through torrefaction enhancement, these pellets serve Polish and German district heating networks facing coal-phaseout mandates under EU Green Deal timelines. Power generators prioritize ENplus certification for renewable energy obligation compliance.
- Heating Pellets:Calibrated to Central European residential and commercial boiler specifications with controlled ash content below 3%, these formulations address corrosion concerns in high-efficiency installations. Romanian and Bulgarian municipal operators source locally to minimize transport moisture absorption.
- Biomass Pellets:General-purpose thermal grades for industrial co-firing applications without premium certification requirements.
- Animal Bedding Pellets:Dust-controlled formulations for Scandinavian equine and poultry operations, commanding per-ton premiums through absorbency and ammonia-binding properties.
Biofuel Pellets holds installed capacity. Heating Pellets is rotating up the share rankings.
End Use Industry:
Customer type determines volume scale, contract duration, and sustainability documentation intensity across energy and agricultural sectors.
- Power Generation:Central European utilities procure under long-term offtake agreements with fixed escalation clauses, consolidating purchases through state-owned biomass platforms. ENplus and sustainability scheme audits impose 6-12 month validation cycles that delay supplier qualification.
- Heating Solutions:Municipal district heating cooperatives in Poland and Romania adopt torrefaction-enhanced pellets for base-load operations previously reserved for wood pellets or natural gas. REACH and ECHA frameworks tighten ash content thresholds for CE-marked product access.
- Agricultural Industry:Livestock operations in Denmark and Norway seek absorbent substitutes for straw bedding with premium dust-control specifications.
- Feed Production:Limited husk pellet incorporation into ruminant fiber supplements, constrained by nutritional digestibility requirements.
Power Generation commands contract volume. Heating Solutions is climbing the fastest as municipal retrofits accelerate.
Packaging Type:
Volume scale and moisture control requirements shape packaging selection, with logistics reconfiguration demanding cold-chain-adjacent investments unfamiliar to traditional crushing operators.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate utility and municipal procurement, enabling mechanized handling at district heating depots. Polish and Romanian operators prioritize UV-stabilized woven polypropylene for outdoor storage durability.
- Standard Bags:15-20 kg polyethylene sacks serve residential heating customers through retail and distributor channels, requiring moisture barriers below 10% content preservation.
- Custom Bags:Branded and private-label configurations for agricultural bedding distributors targeting equine facility supply chains.
- Loose:Bulk pneumatic delivery to large-scale power generation facilities with on-site storage silos and automated feeding systems.
Bulk Bags holds throughput scale. Standard Bags is gaining share fastest through retail channel expansion.
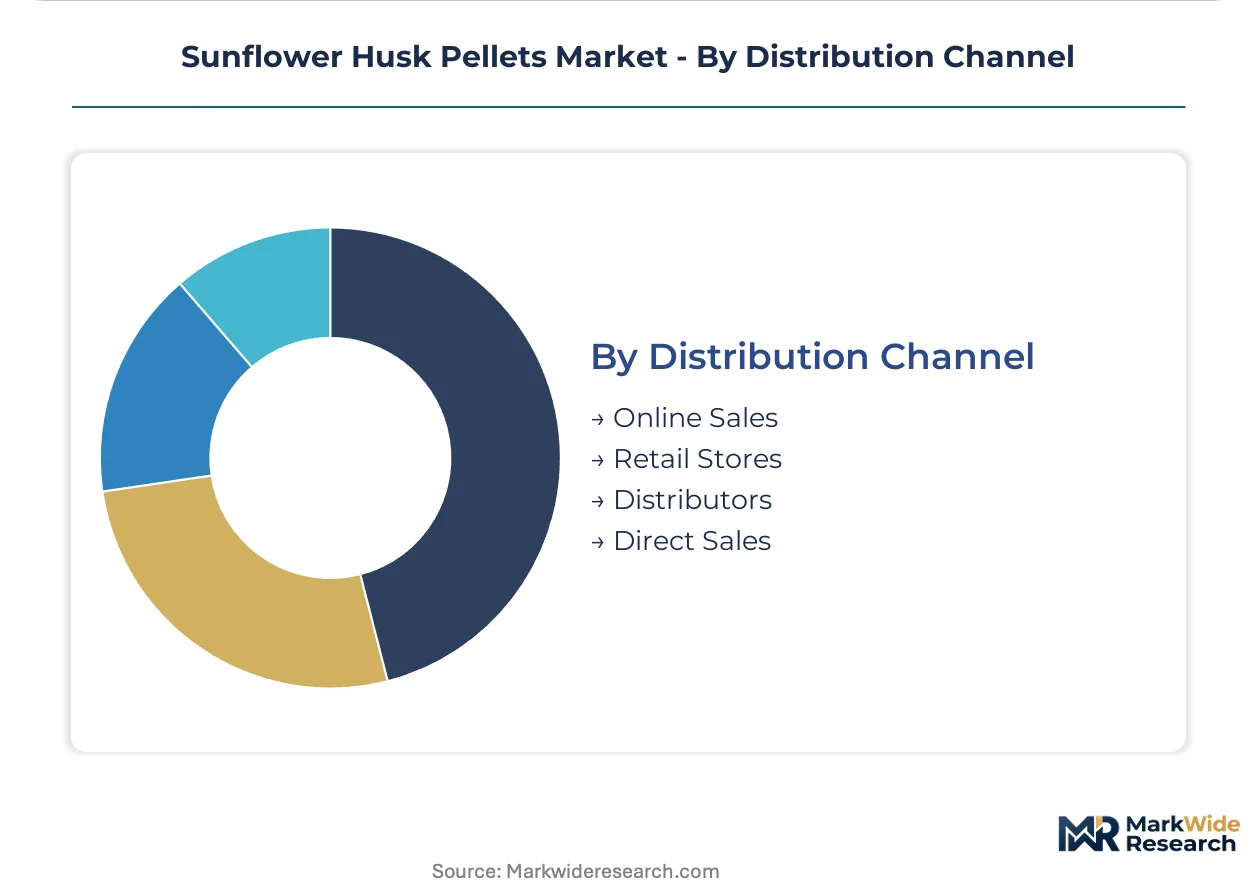
Distribution Channel:
Supply concentration and certification timeline pressures favor direct relationships with large-volume purchasers, while fragmented agricultural demand sustains intermediary layers.
- Distributors:Agricultural bedding pellets move through specialized biomass and farm supply networks dominating Scandinavian equine and poultry segments. Danish distributors consolidate dust-controlled formulations from multiple pelletizing sources.
- Direct Sales:Utilities and municipal heating operators bypass intermediaries for three-to-five-year supply agreements with Ukrainian and Bulgarian producers, locking in Black Sea logistics corridor access.
- Online Sales:Emerging channel for residential heating customers seeking certified pellet deliveries with sustainability documentation.
- Retail Stores:Seasonal residential demand through agricultural cooperatives and building material outlets in Poland and Romania.
Distributors holds agricultural segment penetration. Direct Sales is expanding most quickly as utility procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in sunflower husk pellets tilt heavily toward intra-European trade, with Black Sea producers supplying Central European heating networks under long-term supply contracts. Ukraine dominates feedstock origination while Bulgarian and Romanian mills capture value-add pelletizing margins.
Ukraine
Black Sea crushing facilities generate sufficient husk volume to supply multiple export-oriented pelletizing clusters with raw material cost advantages. The country's agricultural belt concentrates feedstock supply, exposing downstream processors to logistics disruptions and geopolitical friction. Odessa and Mykolaiv anchor Black Sea corridor operations serving German and Polish district heating procurement.
Bulgaria
Municipal district heating operators in Sofia and Plovdiv adopt torrefaction-enhanced pellets for base-load operations previously reserved for wood pellets or natural gas. REACH and ECHA frameworks tighten ash content thresholds for CE-marked product access. The Stara Zagora industrial zone scales pelletizing capacity to serve regional heating cooperatives.
Romania
State-owned utilities consolidate procurement through centralized biomass purchasing platforms, locking in three-to-five-year pellet supply agreements with fixed escalation clauses. EU Green Deal emission benchmarks accelerate certified biomass substitution for coal-phaseout timelines. The Dobrogea region concentrates crushing and pelletizing infrastructure along Black Sea logistics routes.
Poland
Power generation utilities face binding coal-phaseout mandates under EU Green Deal timelines, accelerating procurement of certified biomass substitutes for district heating feedstock. ENplus certification imposes six-to-twelve-month validation cycles that delay supplier qualification. The Silesian and Małopolska heating networks drive municipal retrofit demand for locally sourced pellets.
Germany
German and Austrian boiler OEMs source exclusively from suppliers with validated sustainability documentation under tightening REACH and ECHA frameworks. The EU's evolving carbon border adjustment mechanism disadvantages imported fossil fuel heating, creating tariff-driven preference for biomass alternatives. Bavarian and Baden-Württemberg district heating operators expand procurement of Eastern European pellet supply.
Sunflower Husk Pellets Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated crushing-to-pellet operators and specialized regional mills. Automated torrefaction systems compress capital barriers, allowing smaller Bulgarian and Romanian producers to achieve combustion specifications previously requiring industrial-scale infrastructure. Two strategic archetypes dominate: Black Sea-integrated feedstock controllers and Central European boiler-calibrated formulation specialists. Competitive moves center on long-term offtake contracting with municipal utilities and backward integration into Ukrainian crushing capacity.
Within the integrated supply tier, CM Biomass anchors Black Sea logistics corridor positioning through Ukrainian sunflower crushing facility linkages. EcoPellets exemplifies the formulation-specialist archetype, occupying a position calibrated for Central European boiler specifications. Biosemira represents the agricultural-application vector, sitting within premium dust-control processing for Scandinavian equine and poultry supply chains.
| Leading Market Players |
|---|
| CM Biomass |
| Biosemira |
| EcoPellets |
| Green Energy Biofuel |
| Procarbon |
| JSC BIOGRA |
| Agripellets |
| BioPower Solutions |
| UKRAOIL |
| Others |
Value Network & Pricing Analysis
Ukrainian crushing facility concentration in the Black Sea agricultural belt concentrates feedstock pricing power upstream, while downstream margin pools accrue to Bulgarian and Romanian pelletizing operations that capture torrefication-enhanced product premiums. This structural asymmetry rewards operators who control logistics corridor access rather than raw material origination alone.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing structures, with three-tier pricing stratification across ENplus-certified premium grades, standard heating pellets, and uncertified economy biomass. Price differentiation hinges on certification level and volume scale, with municipal utilities locking in fixed-escalation clauses while residential retail channels absorb higher per-unit delivery costs. Cost compression in economy tiers is intensifying because sunflower oil market volatility feeds directly into husk availability. Agricultural bedding buyers exhibit lowest price sensitivity, accepting per-ton premiums for dust-controlled formulations.
Supply Chain Analysis
EU dual-use export controls on torrefaction technology limit equipment flows to certain Black Sea jurisdictions, constraining capacity buildout speed for regional mills. Geographic supply concentration centers on Ukraine, Bulgaria, and Romania, with raw material dependencies on sunflower crushing byproduct streams, polypropylene packaging, and natural gas drying inputs. Single-source vulnerability runs through Odessa corridor logistics, where geopolitical friction exposes downstream processors to feedstock interruption. Distribution runs through direct sales relationships with municipal utilities and specialized agricultural distributors serving Scandinavian equine operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated municipal procurement platforms in Poland and Romania, where state-owned utilities centralize biomass purchasing through three-to-five-year supply agreements. This consolidation fragments negotiating leverage for smaller pelletizing entrants.
For Market Incumbents: Pre-empt torrefication technology diffusion by locking exclusive equipment supply partnerships before regional mills achieve combustion specification parity. CM Biomass-type integrated operators should defend corridor positioning through backward integration into additional Ukrainian crushing capacity, while formulation specialists like EcoPellets must accelerate ENplus certification investments to maintain OEM boiler access as REACH thresholds tighten. For New Entrants and Emerging Players: Scandinavian district heating networks present the most penetrable white-space target, where Swedish and Finnish municipal operators currently favor wood pellets but face sustainability certification pressure to diversify feedstock. Danish and Norwegian agricultural bedding channels offer secondary entry through premium dust-control formulations. A specialized go-to-market angle targeting equine facility supply chains through Danish distributor relationships bypasses utility procurement consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive Ukrainian feedstock and established Black Sea logistics relationships, as these archetypes capture margin pools at both origination and processing stages. Long-term viability across the analysis window rests on torrefication technology access and certification audit completion speed. The signal to watch is ENplus validation timeline compression, as accelerated audit cycles would favor well-capitalized incumbents over emerging regional mills.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing | Captures Ukrainian husk origination margins and secures Black Sea corridor feedstock access. |
| Torrefaction Technology Licensing | Enables Bulgarian and Romanian mills to achieve industrial-grade combustion specifications without massive dryer capital. |
| Long-term Supply Agreement | Locks in Polish and Romanian municipal utility procurement through state-owned biomass purchasing platforms. |
| ENplus Certification Program | Opens CE-marked product access under tightening REACH and ECHA ash content thresholds. |
| Geographic Expansion to Scandinavia | Targets underpenetrated Swedish and Finnish district heating networks seeking biomass feedstock diversification. |
Research Methodology
Cross-validation between primary interviews and secondary trade data anchors the qualitative findings across the sunflower husk pellet value chain. Stakeholder conversations encompassed pelletizing plant managers, municipal utility procurement officers, agricultural bedding distributors, boiler OEM technical directors, and Black Sea logistics operators. Secondary sources included EU customs and trade flow databases, ECHA emissions framework documentation, ENplus certification registry filings, and biomass purchasing platform disclosures. Bottom-up capacity assessments triangulated against top-down energy substitution demand projections.
Calibration against historical price formation patterns and certification timeline data shaped the analytical framework. Segmentation dimensions modeled include product type tier, end-use industry, packaging format, and regional production cluster. CAGRs were derived from supply-demand balance trajectories across the projection horizon, incorporating torrefication adoption curves and coal-phaseout mandate compliance schedules as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Ukrainian crushing conglomerates or rapid torrefication equipment localization would shift outcomes. Material shifts in Black Sea logistics access or EU carbon border adjustment mechanism implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Compressor Oil Market
Others
Dried Fruit Extracts Market
Others
Global Injectable Nanomedicine Market
Others
Powder Coating Equipment Market
Others
Propanil Market
Others
Bio-Imaging Technologies Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Paper Shredder Market
Others
Residential Electrical Conduit Market
Others
Super Computer Market
Others
One-Way Degassing Valve Market
Others
United States Air Furnaces Market
Others
Enterprise Video Market
Others
Infant Positioning Aids Market
Others
Metal Air Battery Market
Others
Retail Digital Signage Market