
 Automotive Coolant Additives Market | 2026-2036
Automotive Coolant Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coolant Additives Market Analysis
Multi-source procurement for ethylene glycol and corrosion inhibitor packages is decoupling from traditional single-source petrochemical dependencies. BASF SE leverages its integrated caprolactam-to-glycol value chain to sustain cost advantages in European supply. Shell plc anchors its position through backward integration into Middle Eastern feedstock operations. Valvoline Inc. differentiates via specialized distribution partnerships with North American fleet maintenance networks.
Automotive coolant additives comprise chemical formulations—typically blends of ethylene or propylene glycol, corrosion inhibitors, pH buffers, and antifoam agents—engineered to regulate engine operating temperatures while preventing cavitation erosion and galvanic corrosion in aluminum-steel cooling systems. Organic Acid Technology dominates product-type value pools due to extended service intervals and compatibility with modern aluminum radiators, while pre-mixed formulations are gaining share in aftermarket channels where technician labor costs discourage on-site dilution. Passenger vehicles consume the largest application volume, though heavy-duty vehicles generate superior per-unit margins because of larger cooling system capacities and more frequent drain intervals.
The EPA regulates coolant disposal under RCRA hazardous waste provisions, while REACH mandates disclosure of boron- and phosphate-based inhibitor chemistries across European supply chains. OEMs increasingly require additive packages certified to OEM-specific standards such as VW TL 774 or Ford WSS-M97B44, creating compliance barriers for unqualified suppliers. Stakeholders must monitor how evolving OEM thermal management architectures—particularly for battery electric vehicles—will redefine additive performance specifications and qualification protocols.
Market Dynamics
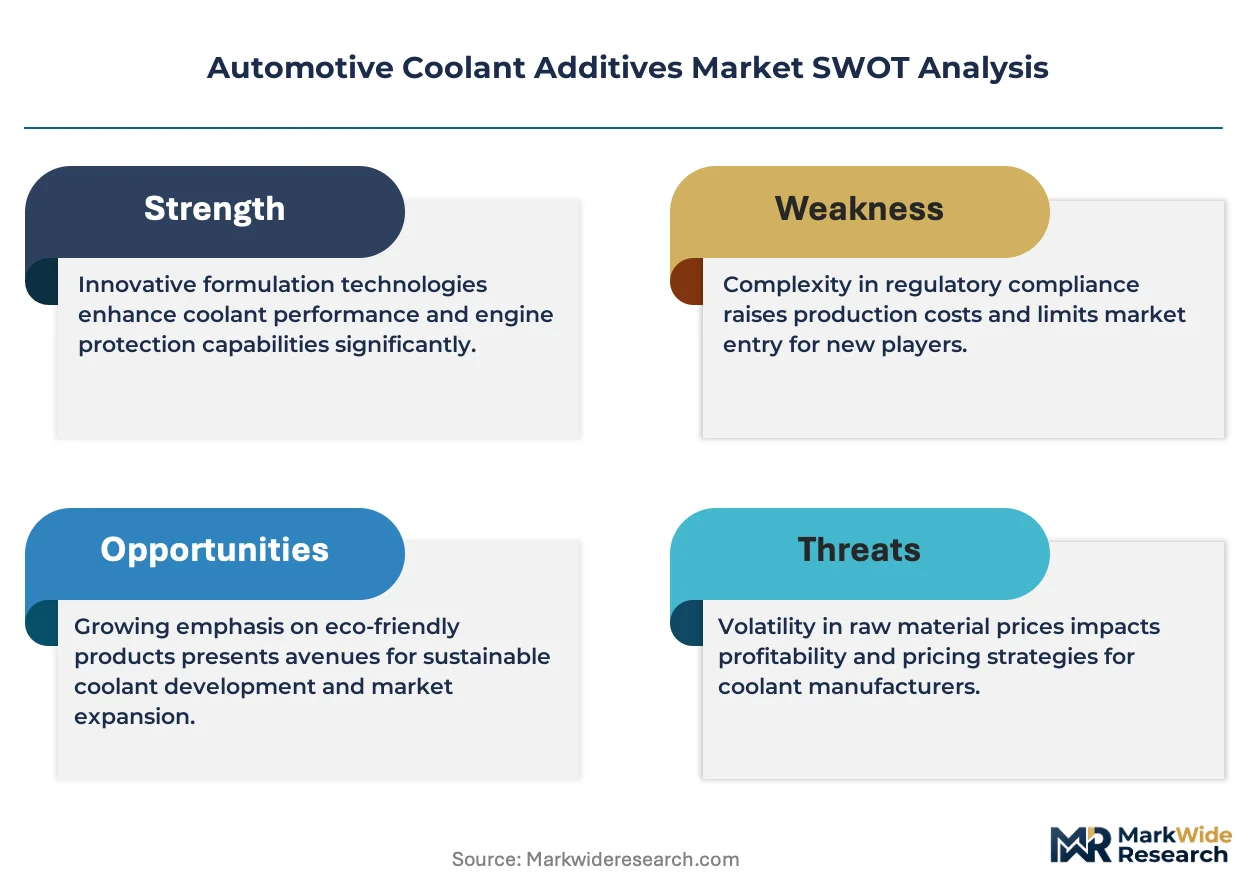
The EU Green Deal and F-Gas Regulation are forcing automotive fluid suppliers to reformulate corrosion inhibitor packages away from boron- and phosphate-based chemistries, compressing qualification timelines and fragmenting supplier tiers.
Growth Catalysts
- Electric Vehicle Thermal Architectures:Battery electric vehicles require specialized low-conductivity coolants for direct cell contact cooling, opening additive demand pools absent in internal combustion platforms.
- REACH Disclosure Mandates:The European Chemicals Agency's transparency requirements for inhibitor chemistries are accelerating substitution toward Organic Acid Technology formulations with cleaner regulatory profiles.
- German Manufacturing Concentration:Stuttgart and Wolfsburg anchor OEM coolant specification authority, creating pull-through effects for additive packages qualified to VW TL 774 and Mercedes-Benz MB 325.0 standards.
Market Restraints
- Ethylene Glycol Feedstock Volatility:Crude oil and natural gas price swings transmit directly into base fluid costs, compressing blender margins during upstream spikes.
- OEM Certification Barriers:Ford WSS-M97B44 and GM 6277M specifications require multi-year qualification protocols that freeze out unqualified additive suppliers from first-fill contracts.
- Propylene Glycol Substitution:Lower-toxicity propylene glycol formulations are displacing ethylene glycol in consumer-accessible aftermarket channels, threatening volume in the economy segment.
Strategic Opportunities
- India Fleet Modernization:The country's PLI scheme for automotive manufacturing is expanding domestic coolant demand as local OEMs adopt aluminum-intensive thermal systems requiring advanced inhibitor packages.
- Pre-Mixed Formulation Channels:Technician labor cost pressures in North American independent repair networks are shifting volume toward ready-to-use coolants that eliminate on-site dilution errors.
- Heavy-Duty Service Interval Compression:Mining and long-haul logistics operators in Australia are shortening drain intervals to protect aluminum-steel cooling systems in high-load applications.
Industry Challenges
- Electrochemist Talent Scarcity:Formulation of low-conductivity battery thermal fluids requires rare expertise in ionic contamination control and galvanic corrosion modeling.
- Legacy System Integration:Hybrid thermal architectures combining battery and engine cooling demand additive packages compatible with disparate metallurgy and operating temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coolant Additives Market |
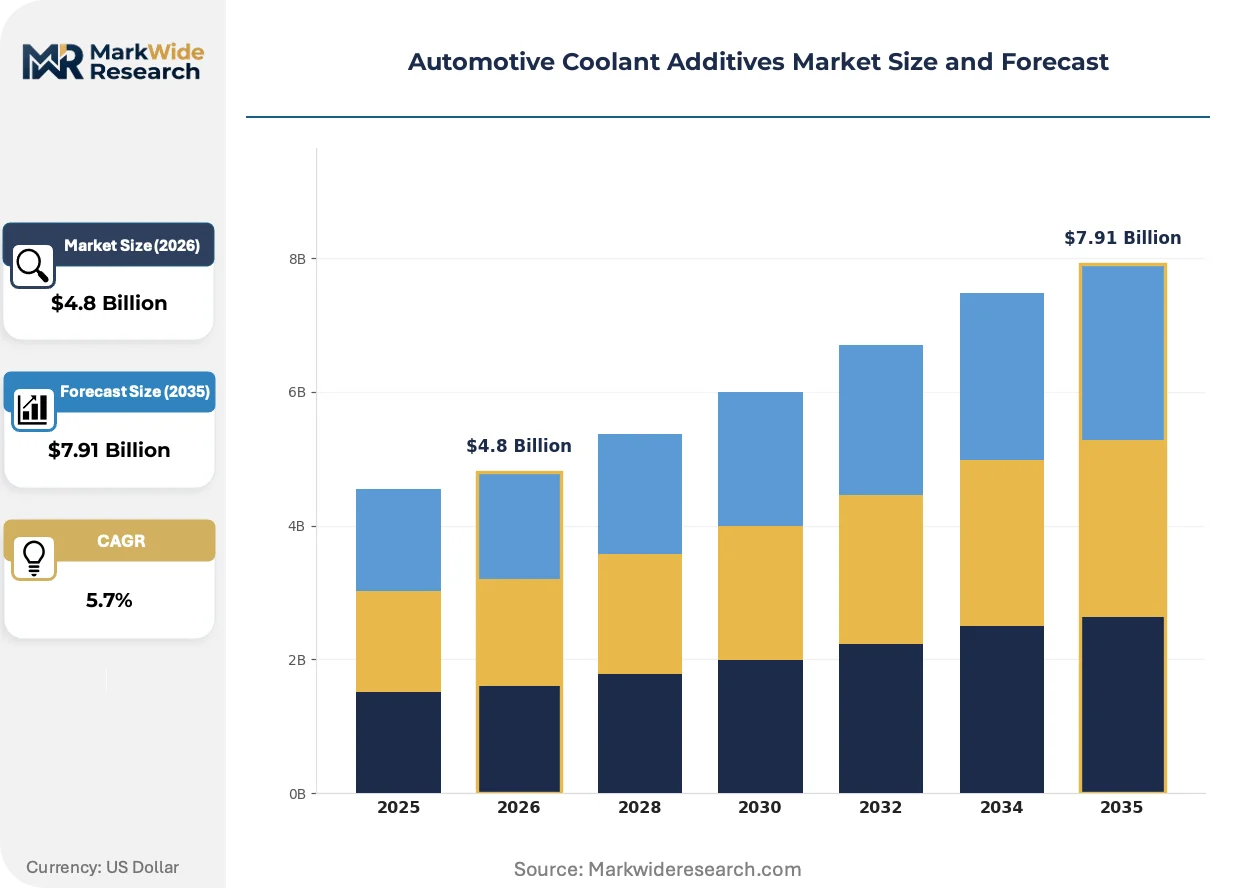
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Pre-mixed, Organic Acid Technology, Inorganic Additives End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Application: Passenger Vehicles, Commercial Vehicles, Heavy-duty Vehicles, Motorcycles Distribution Channel: Online Retail, Automotive Stores, Wholesalers, Direct Sales |
| Companies Covered | Prestone Products Corporation, Shell plc, ExxonMobil Corporation, Chevron Corporation, TotalEnergies SE, Valvoline Inc., BASF SE, Castrol, Sinopec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coolant Additives Market Emerging Trajectories
Additive formulation is modularizing around discrete functional blocks—corrosion inhibition, pH buffering, antifoam—enabling rapid reconfiguration for divergent OEM thermal architectures. Three forces are compressing development cycles and reshaping competitive positioning.
Organic Acid Technology is modularizing into substrate-specific variants targeting aluminum radiators, magnesium engine blocks, and copper-brazed heat exchangers respectively. Tier-1 suppliers are adopting these building-block approaches to compress qualification timelines for EV-specific thermal fluids. The structural consequence is collapsing the traditional monolithic additive package model into configurable component libraries.
REACH Annex XIV authorization requirements for boric acid derivatives are forcing European formulators to validate phosphate- and silicate-free inhibitor alternatives. Industrial consequence includes extended validation periods for new additive packages and accelerated obsolescence of legacy formulations. German OEMs are responding by tightening first-fill specification windows and demanding earlier regulatory roadmap disclosure from suppliers.
Fleet maintenance networks are consolidating procurement authority into centralized technical buyers who specify additive packages by performance metric rather than brand. Independent repair chains are displacing traditional jobber distribution with direct supplier relationships and private-label formulations. This concentration is most visible in North American Class 8 trucking, where national fleet managers now dictate coolant standards across thousands of service locations.
Automotive Coolant Additives Market Segmentation
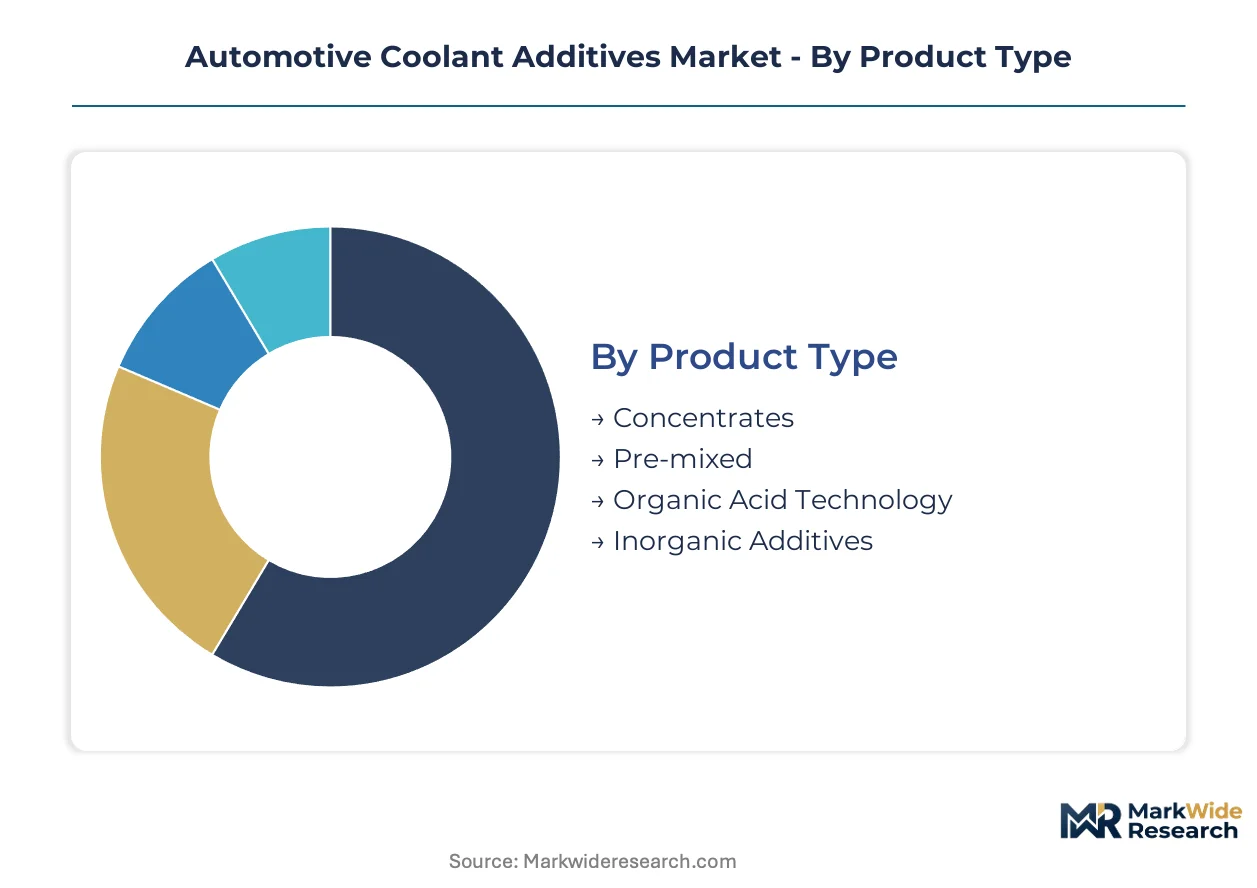
Automotive coolant additives fragment across four intersecting dimensions, each carrying distinct certification burdens and margin profiles. Product-type and application segments dominate value capture, while distribution channels and end-user categories determine qualification timelines and pricing power.
Product Type:
VW TL 774, Ford WSS-M97B44, and Mercedes-Benz MB 325.0 certifications stratify product-type segments by qualification difficulty and first-fill eligibility. OEM-specific approvals concentrate demand in certified formulations while locking out unqualified suppliers from factory-fill contracts.
- Organic Acid Technology:Extended-life formulations utilizing carboxylate-based inhibitors deliver 5-year/150,000-mile service intervals in aluminum-intensive cooling systems. Demand concentrates in German OEM first-fill programs where Mercedes-Benz and Volkswagen specification authority creates pull-through effects across European supply chains. REACH Annex XIV restrictions on boric acid derivatives are accelerating substitution toward these cleaner-regulatory-profile formulations.
- Pre-mixed:Ready-to-use coolants eliminate on-site dilution errors and technician labor costs in aftermarket channels. North American independent repair networks are shifting procurement toward these formulations as fleet maintenance networks consolidate buying authority into centralized technical buyers who specify by performance metric rather than brand identity.
- Concentrates:Full-strength glycol bases requiring field dilution retain cost advantages in high-volume industrial applications and emerging-market service operations where labor differentials favor manual mixing protocols.
- Inorganic Additives:Traditional silicate and phosphate inhibitor packages face accelerated obsolescence as EU Green Deal mandates force reformulation away from boron- and phosphate-based chemistries.
Leading the category by volume: Organic Acid Technology. Growing fastest: Pre-mixed.
End User:
Procurement authority consolidation is reshaping end-user segments, with national fleet managers and centralized technical buyers displacing traditional jobber distribution channels.
- OEMs:Factory-fill specifications require multi-year qualification protocols to Ford WSS-M97B44, GM 6277M, and VW TL 774 standards. Stuttgart and Wolfsburg manufacturing corridors anchor specification authority, creating compliance barriers that freeze out unqualified additive suppliers from first-fill contracts.
- Aftermarket Providers:Private-label formulations and direct supplier relationships are displacing traditional brand loyalty as independent repair chains consolidate procurement. North American Class 8 trucking fleets now dictate coolant standards across thousands of service locations through centralized technical buyers.
- Vehicle Assemblers:Contract manufacturing arrangements for niche and specialty vehicle producers require flexible additive packages compatible with mixed-metallurgy thermal systems.
- Repair Shops:Technician labor cost pressures favor pre-mixed formulations that eliminate dilution errors and reduce service time in high-throughput maintenance operations.
Highest margin concentration: OEMs. Expanding most quickly: Aftermarket Providers.
Application:
Cooling system capacity and drain interval frequency create divergent per-unit economics across vehicle applications, with heavy-duty platforms generating superior margins despite smaller volume shares.
- Heavy-duty Vehicles:Mining and long-haul logistics operators in Australia are compressing drain intervals to protect aluminum-steel cooling systems under sustained high-load conditions. Larger cooling system capacities and more frequent service cycles generate per-unit margins exceeding passenger vehicle applications by substantial multiples.
- Passenger Vehicles:Aluminum radiator adoption and extended service intervals drive Organic Acid Technology penetration in OEM first-fill and dealer service channels. India's PLI scheme for automotive manufacturing is expanding domestic coolant demand as local OEMs adopt aluminum-intensive thermal systems requiring advanced inhibitor packages.
- Commercial Vehicles:Fleet standardization programs and centralized procurement authority favor certified additive packages with documented performance metrics across mixed-duty cycles.
- Motorcycles:Compact cooling system volumes and price-sensitive aftermarket channels sustain demand for economy-tier ethylene glycol concentrates.
Largest volume base: Passenger Vehicles. Steepest expansion trajectory: Heavy-duty Vehicles.
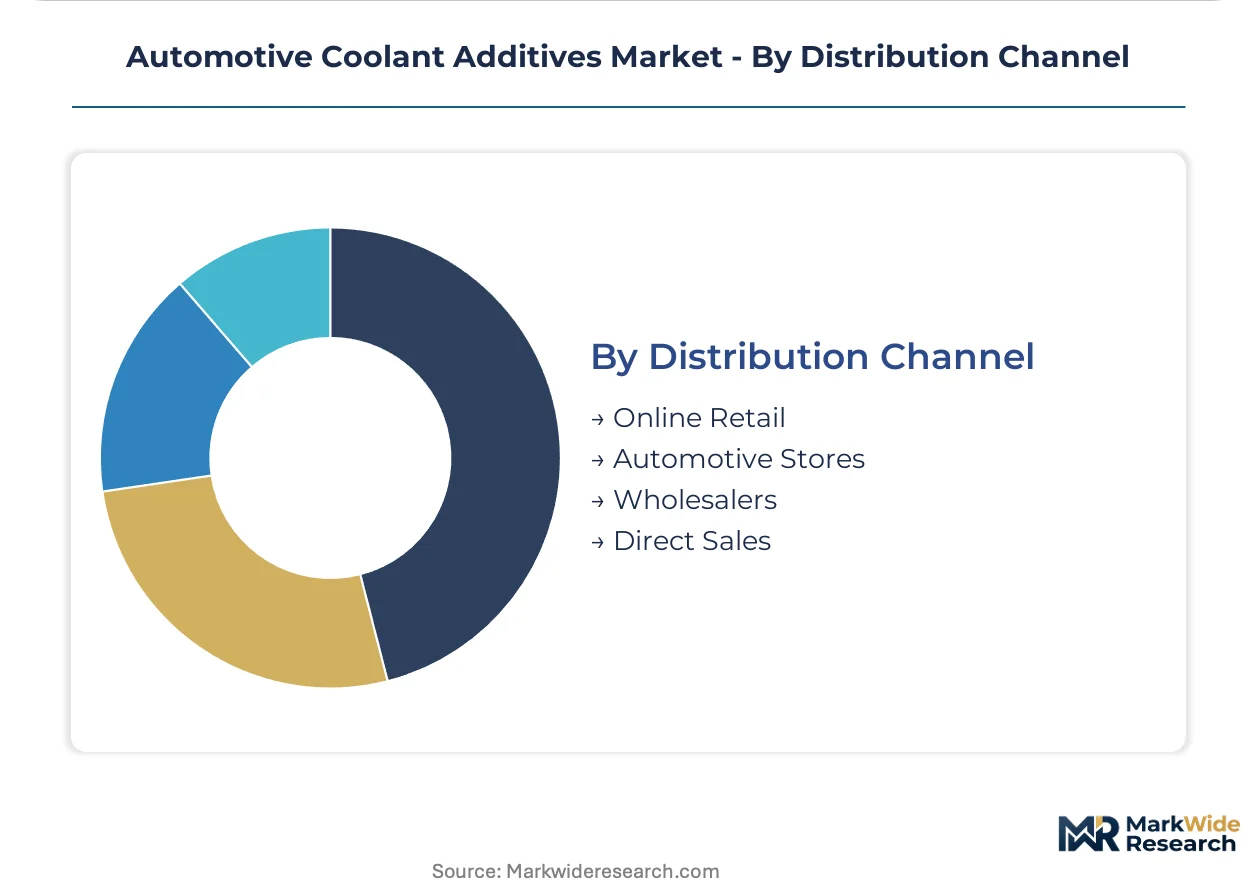
Distribution Channel:
Channel selection determines pricing transparency, technical support requirements, and brand loyalty retention in fragmented aftermarket supply chains.
- Automotive Stores:Traditional jobber networks retain volume in emergency replacement and consumer DIY segments where immediate availability outweighs price optimization.
- Direct Sales:National fleet managers and OEM technical buyers negotiate additive packages by performance specification, bypassing distribution markups through supplier relationships.
- Online Retail:E-commerce penetration concentrates in consumer-accessible pre-mixed formulations where shipping economics favor smaller package sizes.
- Wholesalers:Regional distribution hubs service independent repair chains with mixed-brand inventory requirements and consolidated delivery logistics.
Dominant volume channel: Automotive Stores. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene glycol production clusters in Texas and Louisiana anchor North American supply, while German chemical corridors around Ludwigshafen and Marl dominate European base fluid manufacturing. Feedstock proximity to automotive assembly districts dictates regional additive formulation economics.
United States
EPA RCRA hazardous waste provisions govern coolant disposal compliance across the aftermarket. The agency's multi-jurisdictional enforcement creates uniform baseline standards from California to Michigan. Houston's petrochemical corridor supplies concentrated glycol bases to Detroit-area blending operations serving Ford and GM first-fill programs.
Germany
REACH Annex XIV authorization requirements for boric acid derivatives force rapid inhibitor reformulation cycles. The EU Green Deal compounds pressure through F-Gas Regulation alignment with automotive fluid standards. Stuttgart and Wolfsburg manufacturing corridors anchor VW TL 774 and Mercedes-Benz MB 325.0 specification authority, pulling additive demand through European supply chains.
China
MIIT fuel efficiency mandates accelerate aluminum radiator adoption in domestic passenger vehicle production. GB standards for automotive fluids create technical barriers for imported additive packages. Yangtze River Delta chemical parks near Shanghai concentrate glycol production capacity serving BYD and Geely thermal system requirements.
India
PLI scheme incentives for automotive manufacturing expand domestic coolant demand as aluminum-intensive thermal systems proliferate. BIS certification requirements for automotive fluids create compliance gates for foreign additive suppliers. Tamil Nadu's Sriperumbudur automotive belt anchors Ford India and Hyundai Motor India coolant specification authority.
Japan
METI carbon neutrality roadmaps pressure thermal fluid suppliers toward lower-emission formulation pathways. JIS standards for automotive coolants maintain stringent compatibility requirements with hybrid powertrain architectures. Toyota City and Hiroshima production clusters drive first-fill additive specifications across Asia-Pacific affiliate operations.
Automotive Coolant Additives Market Vendor Landscape
Global majors compete with regional champions across feedstock integration and OEM certification dimensions. The vendor base stratifies into petrochemical-integrated multinationals, specialized additive formulators, and regional blending operations. Three archetypes dominate: backward-integrated oil majors with captive glycol supply, chemical conglomerates with corrosion inhibitor expertise, and aftermarket-focused distributors with fleet maintenance relationships. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Among petrochemical-integrated players, Shell plc and ExxonMobil Corporation exemplify feedstock-controlled positioning, while BASF SE anchors the chemical-specialist tier through its Ludwigshafen-based integrated value chains. Valvoline Inc. occupies the aftermarket-distributor archetype with North American fleet network penetration. These three represent distinct strategic postures rather than comparable operational scale.
| Leading Market Players |
|---|
| Prestone Products Corporation |
| Shell plc |
| ExxonMobil Corporation |
| Chevron Corporation |
| TotalEnergies SE |
| Valvoline Inc. |
| BASF SE |
| Castrol |
| Sinopec Corporation |
| Others |
Supply Flow & Price Mechanics
National fleet managers in North American Class 8 trucking now dictate additive specifications across thousands of service locations, compressing price discovery into centralized technical buyers who negotiate by performance metric rather than brand identity. This procurement concentration favors contract-based long-term offtake agreements over spot-market transactions, locking in volume commitments that buffer blenders against ethylene glycol feedstock volatility.
Pricing Analysis
Warranty and service-bundling arrangements separate OEM first-fill programs from unbundled aftermarket transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—VW TL 774 and Ford WSS-M97B44 approvals command substantial premiums over generic formulations. Price differentiation hinges on qualification difficulty and factory-fill eligibility. Cost compression in the economy tier is intensifying because propylene glycol substitution threatens ethylene glycol volumes. DIY consumers in automotive stores exhibit highest price sensitivity; OEM technical buyers show least sensitivity due to warranty compliance requirements.
Supply Chain Analysis
India's PLI scheme for automotive manufacturing and China's MIIT fuel efficiency mandates are reshaping sourcing patterns toward domestic-content compliance. Feedstock supply draws from Texas and Louisiana petrochemical corridors in North America, Ludwigshafen and Marl chemical clusters in Germany, and Yangtze River Delta parks near Shanghai. Raw material dependencies center on ethylene oxide, corrosion inhibitor packages, and pH buffer chemistries. Single-source vulnerability concentrates in boron-based inhibitor supply chains facing REACH Annex XIV restrictions. Distribution runs through regional wholesalers servicing independent repair chains with mixed-brand inventory requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemist talent scarcity for low-conductivity battery thermal fluid formulation props pricing across EV-specific additive segments, constraining capacity expansion and sustaining margin premiums for qualified suppliers.
For Market Incumbents: Anchor factory-fill relationships through accelerated certification investment in VW TL 774 and Mercedes-Benz MB 325.0 specification windows. Defend against private-label displacement by deepening captive supply of corrosion inhibitor building blocks. Prioritize backward integration into Middle Eastern feedstock operations to buffer margin compression during upstream ethylene glycol spikes. For New Entrants and Emerging Players: Fleet maintenance networks represent the most penetrable channel archetype for unqualified additive suppliers frozen out of OEM first-fill contracts. Target Australia's mining and long-haul logistics operators compressing drain intervals for aluminum-steel cooling system protection. Pursue direct supplier relationships with centralized technical buyers specifying by performance metric rather than incumbent brand loyalty. For Investors and Strategic Acquirers: The window for entry favors specialized additive formulators with modular corrosion inhibitor building-block capabilities and existing REACH-compliant regulatory profiles. Long-term viability hinges on qualification velocity for divergent OEM thermal architectures spanning battery electric and hybrid platforms. Monitor German OEM specification roadmap disclosures as the inflection indicator for additive package obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Operations | Shell plc's Middle Eastern captive supply anchors cost position against ethylene glycol volatility. |
| OEM Certification Investment | BASF SE's Ludwigshafen value chain sustains VW TL 774 and Mercedes-Benz MB 325.0 qualification advantages. |
| Modular Formulation Development | Building-block approaches compress qualification timelines for EV-specific low-conductivity thermal fluids. |
| Fleet Network Direct Relationships | Valvoline Inc.'s North American fleet maintenance partnerships displace traditional jobber distribution channels. |
| REACH-Compliant Inhibitor Substitution | Phosphate- and silicate-free alternatives validate extended service intervals under EU Green Deal mandates. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance technical buyers combined with secondary validation from EPA RCRA hazardous waste provisions, REACH Annex XIV authorization databases, and vehicle production records. Bottom-up triangulation across product-type, application, and distribution channel segments reconciled with top-down macroeconomic drivers across the analysis window.
Data-stream reconciliation balanced volume and value outputs across segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from modeled growth trajectories incorporating aluminum radiator adoption rates, drain interval compression patterns, and EV thermal system penetration. Industry-specific forecast inputs included MIIT fuel efficiency mandate compliance timelines and PLI scheme incentive disbursement schedules.
Several conditions sit outside the modeled scope, including abrupt crude oil price shocks, unanticipated REACH authorization accelerations, and OEM thermal architecture standardization shifts. Forecasts reflect documented assumptions regarding ethylene glycol feedstock stability and certification protocol durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Trioctyldodecyl Citrate Market
Additives
High Performing Matting Agents Market
Additives
Octane Improver Fuel Additives Market
Additives
Anti-Wear Additives Market
Additives
Epoxy Type Stabilizers Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Global PVC Additives Market
Additives
Global Lubricating Oil Additives Market
Additives
Global Pearlizing Agent Market
Additives
Anti Crystallizing Agents Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Global Feed Acidifiers Market
Additives
Global Performance Additives Market
Additives
Defoaming Coating Additives Market
Additives
Global Chelated Trace Minerals Market
Additives
Global Cement Additives Market