
 Ukraine Freight and Logistics Market | 2026-2036
Ukraine Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Ukraine Freight and Logistics Market Analytics
Market Context
Modular service bundling is decoupling as Ukrainian shippers unbundle freight forwarding from warehousing to optimize working capital. Ukrzaliznytsia leverages its monopoly on east-west rail corridors to sustain bulk grain and ore movements despite infrastructure damage. NOVA Group dominates parcel last-mile delivery through dense locker networks and digital routing. Kuehne + Nagel navigates customs complexity by positioning bonded warehousing near Polish border crossings.
Technical and Segment Structure
Ukraine freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across road, rail, air, and sea modes, typically measured in ton-kilometers and container TEU equivalents, with core functions spanning cargo consolidation, transit documentation, and multimodal handoff coordination. Road freight leads volume recovery due to flexible routing around damaged rail nodes, while rail freight retains structural importance for agricultural bulk exports through Black Sea corridor alternatives. Warehousing services are expanding fastest as EU-bound exporters require temporary storage for phytosanitary inspections and origin certification.
Regulatory Environment
Ukraine's Ministry of Infrastructure and State Customs Service enforce EU Association Agreement alignment on transport standards, while the National Bank of Ukraine regulates cross-border payment settlements for logistics services. These frameworks shape market access by mandating TIR carnet compliance, electronic advance cargo information filing, and gradual adoption of EU vehicle emission classifications for road operators. Stakeholders must monitor corridor security arrangements and customs union negotiation progress to calibrate network investments against transit time volatility.
Market Dynamics
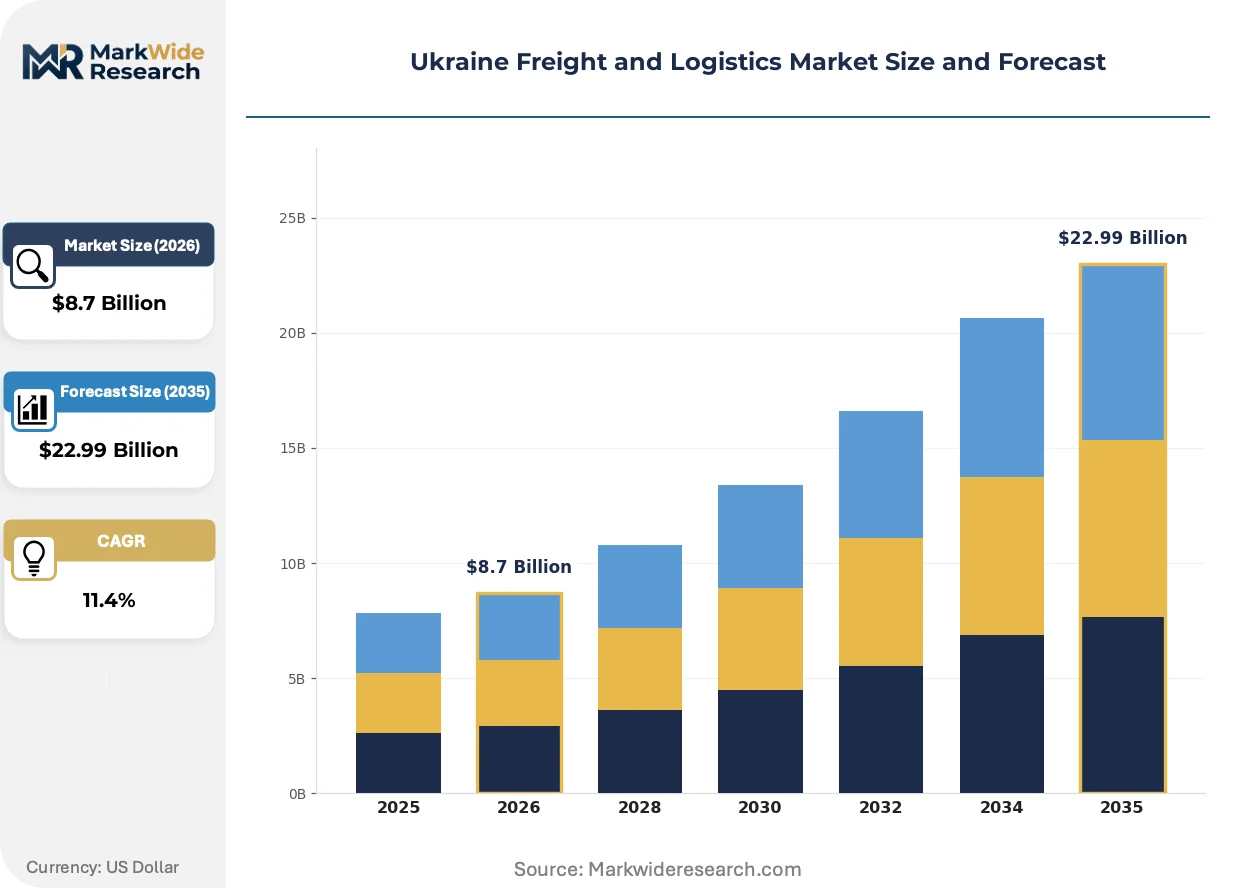
Rail infrastructure damage from military activity has triggered permanent modal shift toward road freight and cross-border warehousing clusters near Poland. This structural displacement is rewiring network economics across Ukrainian logistics corridors.
Growth Catalysts
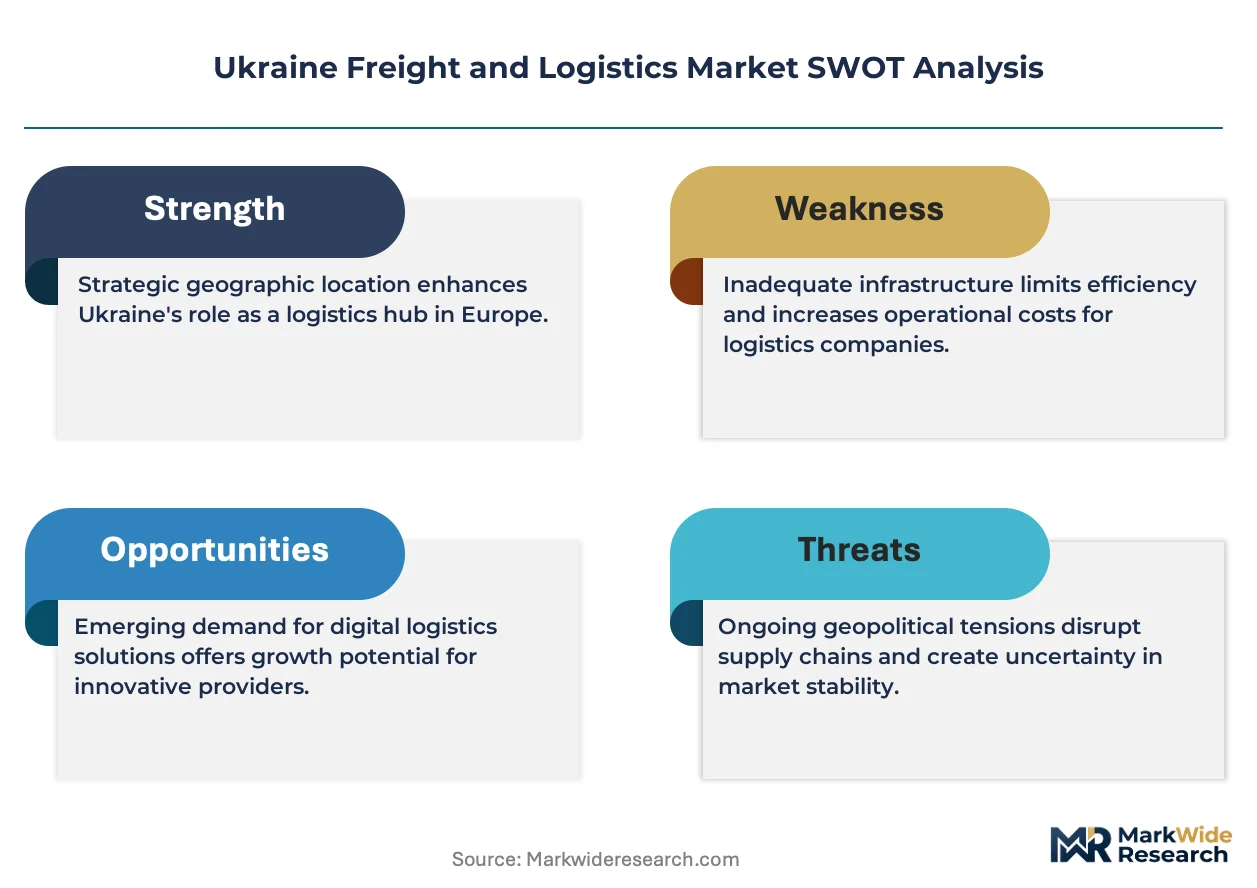
- EU Association Agreement alignment:Customs modernization mandates electronic advance cargo information filing, compressing border clearance times for exporters routing through Lviv Oblast.
- Black Sea corridor alternatives:Agricultural bulk exporters are diversifying through Romanian and Polish port access, sustaining grain movement volumes despite eastern rail node outages.
- Digital locker networks:Parcel last-mile density is expanding through automated pickup infrastructure, reducing delivery cost per unit in urban centers.
Market Restraints
- Fuel cost volatility:Road freight operators face diesel price instability that directly erodes margins on long-haul routes to Polish border crossings.
- Rail monopoly concentration:Ukrzaliznytsia controls all east-west bulk corridors, limiting shipper negotiating leverage on agricultural export rates.
- Phytosanitary certification delays:EU border inspection capacity constraints create queuing at BCPs, extending transit times for grain and oilseed shipments.
Strategic Opportunities
- Western Oblast warehousing:Temporary storage demand is surging in Lviv and Ivano-Frankivsk as exporters stage cargo for EU origin certification and inspection.
- Multimodal handoff infrastructure:Cross-dock facilities at Polish-Ukrainian border points enable rail-to-road transfer for containers avoiding damaged eastern networks.
- TIR carnet digitization:Electronic guarantee systems are reducing customs documentation friction for road carriers operating under EU transit conventions.
Industry Challenges
- Qualified driver scarcity:Military mobilization and emigration have depleted the pool of certified heavy goods vehicle operators for international routes.
- Warehousing construction timelines:Bonded facility development requires extended permitting through State Customs Service, delaying network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ukraine Freight and Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Road, Rail, Air, Sea Service Type: Freight Forwarding, Warehousing, Customs Brokerage, Last-Mile Delivery End User: Manufacturing, Retail, Automotive, Pharmaceuticals Technology: Telematics, TMS, RFID, Blockchain |
| Companies Covered | Raben Group, Ukrainian Railways (Ukrzaliznytsia), Kuehne + Nagel, Ukrposhta, NOVA Group (Nova Post LLC), DSV A/S (Including DB Schenker), Ekol Logistics, A.P. Moller – Maersk, FM Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ukraine Freight and Logistics Market Evolving Landscape
Digital trade documentation and automated border processing are compressing customs clearance cycles. These technologies are enabling Ukrainian exporters to maintain EU market access despite physical infrastructure constraints.
Electronic advance cargo information systems are consolidating fragmented customs filing processes into unified digital platforms. Agricultural exporters and freight forwarders are adopting these systems fastest to preempt phytosanitary inspection delays. This consolidation is eliminating paper-based TIR carnet processing at Polish border crossings.
EU Association Agreement transport standards are mandating progressive vehicle emission classification adoption for Ukrainian road operators. The State Customs Service enforces these provisions through transit permit allocations. Road freight segments serving manufacturing hubs in Lviv Oblast are retrofitting fleets fastest to maintain corridor access.
Shippers are unbundling freight forwarding from warehousing contracts to optimize working capital deployment. Manufacturing exporters in western Ukraine are driving this pattern, separating cargo movement from storage obligations. This behavior concentrates demand around third-party logistics providers offering standalone warehousing near Yagodyn and Krakovets border points.
Ukraine Freight and Logistics Market Segmentation
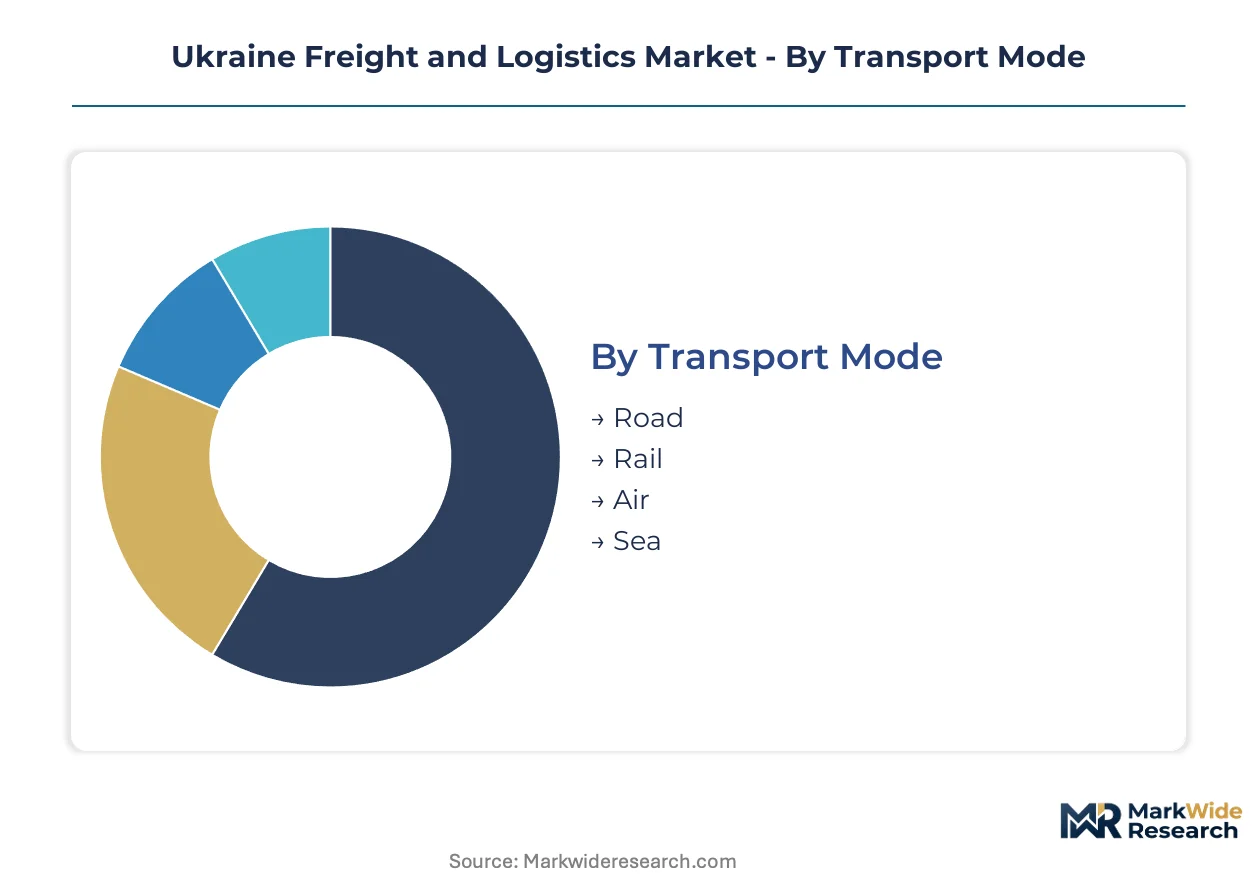
Modal displacement from damaged eastern rail corridors has fragmented demand across alternative transport modes and service combinations. Shippers now configure logistics procurement around corridor security and border clearance velocity rather than pure cost optimization.
Transport Mode:
Rail infrastructure renewal cycles are accelerating modal rebalancing as operators seek alternatives to damaged eastern networks.
- Road:Flexible routing around damaged nodes dominates volume recovery. Demand concentrates on Lviv-to-Poland corridors where Ukrzaliznytsia rail outages force agricultural exporters onto long-haul trucking.
- Rail:Retains structural importance for bulk grain and ore through Black Sea corridor alternatives. Ukrzaliznytsia's monopoly on surviving east-west lines limits shipper rate negotiation leverage.
- Air:Express cargo and high-value pharmaceuticals bypass surface corridor risks. Limited capacity serves time-critical manufacturing inputs for western Ukrainian hubs.
- Sea:Romanian and Polish port access sustains agricultural export volumes. Multimodal handoffs at Constanta and Gdansk replace direct Black Sea routing.
Road sits at the top of the volume ranking, with air climbing the fastest on pharmaceutical and electronics corridor demand.
Service Type:
Cost tier stratification separates integrated providers from standalone specialists as working capital constraints reshape procurement patterns.
- Freight Forwarding:Shippers unbundle forwarding from warehousing to optimize capital deployment. Western manufacturing exporters drive demand for standalone customs coordination.
- Warehousing:Bonded facilities near Yagodyn and Krakovets border points stage cargo for EU phytosanitary inspection. State Customs Service permitting delays constrain expansion timelines.
- Customs Brokerage:Digital advance cargo information filing compresses clearance cycles. EU Association Agreement mandates accelerate platform consolidation.
- Last-Mile Delivery:Automated locker networks reduce urban delivery cost per unit. NOVA Group's dense infrastructure dominates parcel density in Lviv and Kyiv.
Warehousing commands the steepest expansion trajectory as EU-bound exporters require temporary storage for origin certification.
End User:
Application-driven procurement separates heavy bulk shippers from time-sensitive manufacturing supply chains.
- Manufacturing:Western Ukrainian industrial hubs in Lviv Oblast reroute inputs through Polish border crossings. Electronics and machinery exporters prioritize customs velocity over transport cost.
- Retail:E-commerce parcel volumes concentrate around automated pickup infrastructure. Urban locker density determines last-mile provider selection.
- Automotive:Just-in-time component flows require bonded warehousing near border inspection points. Supply chain resilience investments displace pure cost optimization.
- Pharmaceuticals:Temperature-controlled corridors and express air freight bypass surface network risks. EU GDP compliance mandates shape logistics provider qualification.
Manufacturing anchors current volume, with pharmaceuticals gaining share fastest on cold-chain infrastructure investment.
Technology:
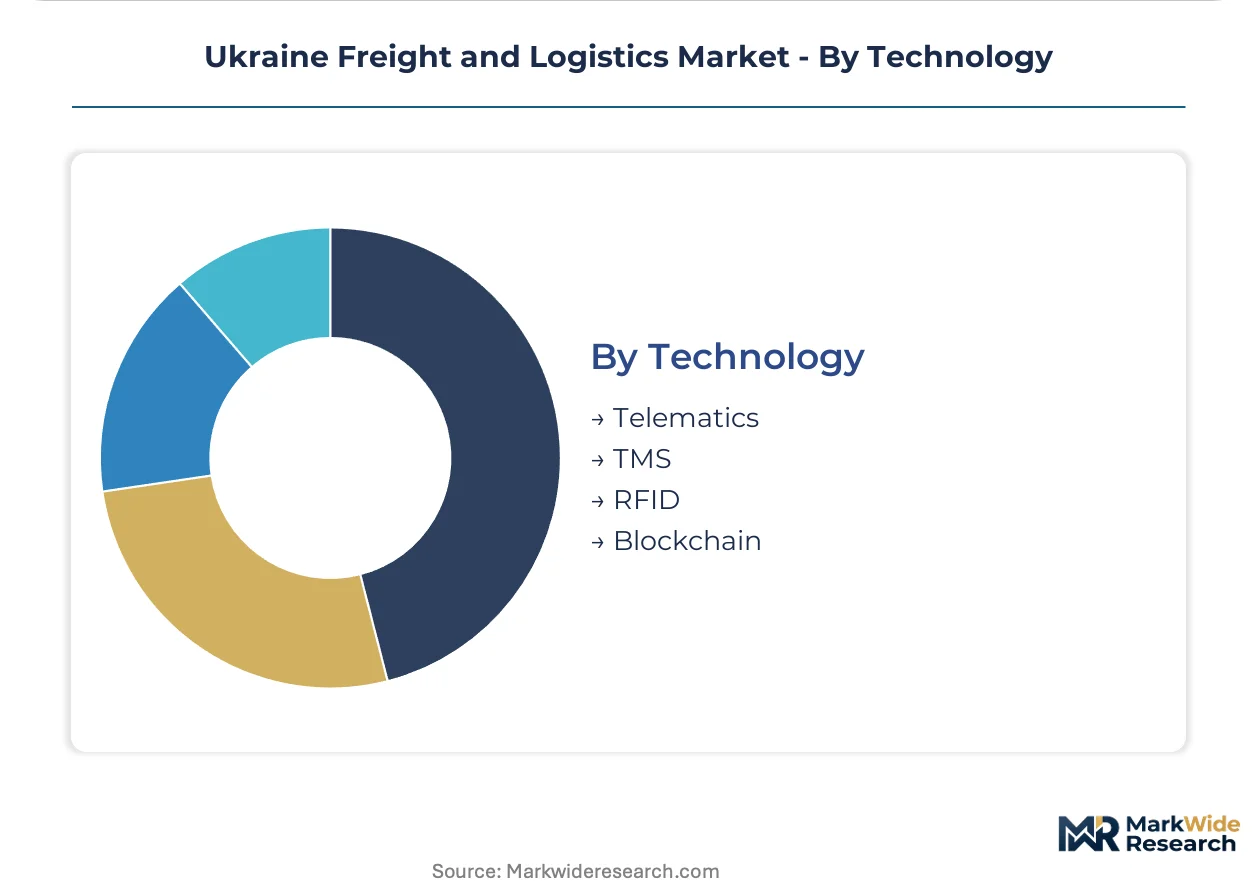
Customer-type segmentation separates early digital adopters from compliance-driven implementers.
- Telematics:Fleet tracking and route optimization reduce fuel cost exposure on long-haul Polish corridors. Road operators deploy real-time positioning to manage diesel price volatility.
- TMS:Transport management platforms consolidate fragmented carrier procurement. Freight forwarders adopt fastest to manage multimodal handoff complexity.
- RFID:Automated cargo identification accelerates warehouse throughput at cross-dock facilities. EU-bound agricultural exporters deploy for origin certification traceability.
- Blockchain:Digital trade documentation reduces TIR carnet processing friction. Pilot implementations target customs guarantee automation at Polish border crossings.
TMS leads current deployment, with blockchain expanding most quickly on customs modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukraine's freight and logistics infrastructure coalesced around Soviet-era rail corridors connecting Black Sea ports to industrial heartlands. The post-2014 pivot toward EU integration redirected investment toward western border crossings. Current corridor damage has accelerated this reorientation, concentrating operational capacity in Lviv Oblast and adjacent regions.
Lviv Oblast
Manufacturing exporters in Lviv and Ivano-Frankivsk drive warehousing demand near Yagodyn and Krakovets border points. The State Customs Service enforces EU Association Agreement electronic advance cargo information mandates, compressing clearance cycles. Lviv anchors multimodal handoff infrastructure where rail-to-road transfers bypass damaged eastern networks.
Kyiv Region
Pharmaceutical and electronics shippers sustain express air cargo volumes through Boryspil International Airport. The National Bank of Ukraine regulates cross-border payment settlements for logistics services originating from capital-based forwarders. Kyiv's automated locker networks reduce last-mile delivery cost per unit through dense urban pickup infrastructure.
Odesa Oblast
Agricultural bulk exporters diversify through Romanian port access at Constanta when Black Sea corridor risks escalate. Ukrzaliznytsia retains structural importance for grain movement through surviving rail spurs. Odesa warehouses stage cargo for phytosanitary inspection queues that extend transit times for EU-bound oilseed shipments.
Dnipro Region
Metallurgical and mining supply chains reroute through Dnipro's surviving rail nodes toward Polish border crossings. Military activity has severed direct eastern corridor access, forcing circuitous routing. Industrial shippers in this region prioritize bonded warehousing capacity over pure transport cost optimization.
Zakarpattia Oblast
Cross-border road freight concentrates at Chop and Mali Selmenci checkpoints into Hungary and Slovakia. EU vehicle emission classifications mandated by transport standards alignment filter fleet eligibility for this corridor. Zakarpattia's mountainous terrain favors smaller-capacity trucking configurations over rail alternatives.
Ukraine Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across customs brokerage complexity and bonded warehousing proximity to EU border inspection points. The market structure fragments between state-controlled rail monopoly, international forwarder networks, and domestic parcel specialists. Three archetypes dominate: integrated multimodal operators with Polish border infrastructure, digital-native last-mile platforms with locker density, and state incumbents controlling surviving east-west bulk corridors. Competitive moves concentrate on cross-dock facility expansion near Yagodyn and Krakovets, and strategic partnerships securing TIR carnet digitization capabilities.
Within the integrated forwarder tier, Kuehne + Nagel and DSV A/S occupy positions defined by bonded warehousing scale near priority border crossings. Among state-controlled infrastructure, Ukrainian Railways anchors bulk agricultural export movements through corridor segments avoiding active conflict zones. On the domestic parcel vector, NOVA Group exemplifies locker-network density strategies that compress urban last-mile economics. These three anchors illustrate how geographic positioning and modal control separate margin tiers.
| Leading Market Players |
|---|
| Raben Group |
| Ukrainian Railways (Ukrzaliznytsia) |
| Kuehne + Nagel |
| Ukrposhta |
| NOVA Group (Nova Post LLC) |
| DSV A/S (Including DB Schenker) |
| Ekol Logistics |
| A.P. Moller – Maersk |
| FM Logistics |
| Others |
Value Network & Pricing Analysis
EU-bound agricultural exporters unbundling freight forwarding from warehousing contracts are forcing logistics providers to price standalone services competitively while absorbing customs coordination complexity. This procurement shift concentrates negotiating leverage with shippers staging cargo through Lviv Oblast border points.
Pricing Analysis
Contract-based long-term offtake agreements dominate agricultural bulk movements through Ukrzaliznytsia corridors, while spot-market pricing prevails for road freight circumventing damaged rail nodes. Price differentiation hinges on customs brokerage certification tier and proximity to bonded warehousing at Yagodyn and Krakovets crossings. Cost compression in standard road freight is intensifying because diesel price volatility erodes operator margins on Polish corridor routes. Manufacturing exporters in western Ukraine exhibit lowest price sensitivity, prioritizing clearance velocity over transport cost.
Supply Chain Analysis
Domestic-content mandates under Ukraine's customs modernization agenda are reshaping sourcing toward local warehousing construction and fleet retrofitting for EU emission compliance. Geographic supply concentration draws from Poland, Romania, and Slovakia for cross-border infrastructure equipment and digital customs platforms. Raw material dependencies center on steel for bonded facility construction, diesel for long-haul trucking, and electronic components for telematics systems. Single-source vulnerability sits with Ukrzaliznytsia's monopoly on surviving east-west bulk corridors. Distribution runs through multimodal handoff points at Polish border crossings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Association Agreement compliance costs in Ukraine trade against Polish warehousing rental differentials across the border.
For Market Incumbents: Deploy bonded warehousing capacity expansion near Krakovets and Yagodyn to capture staging demand from agricultural exporters facing phytosanitary inspection delays. Threat substitution from digital-native customs platforms demands accelerated TIR carnet digitization partnerships. Backward integration into fleet retrofitting for EU emission standards secures corridor access permits from the State Customs Service.
For New Entrants and Emerging Players: Regional logistics associations in Ivano-Frankivsk offer partnership pathways into warehousing services unbundled from forwarding contracts. White-space targets concentrate on standalone customs brokerage for manufacturing exporters in Lviv Oblast. The most penetrable segment comprises mid-sized agricultural shippers bypassing damaged eastern rail networks. A direct-sales team targeting procurement officers at western Ukrainian industrial hubs provides viable go-to-market positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with cross-dock facility operators controlling Polish-Ukrainian border handoff infrastructure. Long-term viability over a multi-year horizon rests on reconstruction timeline assumptions for eastern rail corridors. Acquisition target archetypes include regional road freight operators with certified international driver pools. The signal to watch is State Customs Service permitting velocity for bonded warehouse approvals.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehousing Expansion | Captures staging demand from EU-bound agricultural exporters facing phytosanitary queues. |
| TIR Carnet Digitization Partnership | Reduces customs friction at Yagodyn and Krakovets border crossings under EU transit conventions. |
| Fleet Retrofitting for EU Emissions | Secures transit permit allocations from State Customs Service for Lviv Oblast corridors. |
| Cross-Dock Infrastructure Development | Enables rail-to-road transfer for containers avoiding damaged eastern Ukrzaliznytsia networks. |
| Automated Locker Network Density | Compresses urban last-mile economics in Kyiv and Lviv through NOVA Group-scale pickup infrastructure. |
Research Methodology
Direct dialogue with freight forwarding executives, State Customs Service officials, agricultural export procurement managers, bonded warehouse operators, and cross-border trucking fleet managers grounded qualitative assessments. Secondary validation drew from Ukrzaliznytsia operational disclosures, EU Association Agreement implementation reports, Polish customs authority trade statistics, and National Bank of Ukraine cross-border payment regulations. Bottom-up carrier capacity estimates and top-down trade flow projections were triangulated against corridor-specific volume data.
Bottom-up modeling aggregated modal capacity across road, rail, and warehousing segments, while top-down analysis calibrated against Black Sea corridor alternative trade volumes. Segmentation dimensions included transport mode, service type unbundling patterns, end-use industry procurement behavior, and technology adoption tier across the analysis window. CAGRs were derived from reconstruction investment timelines and EU integration policy implementation schedules. Forecast inputs incorporated corridor security risk weightings and customs modernization platform deployment rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to eastern rail reconstruction timelines and EU customs union negotiation progress. Assumptions reflect documented infrastructure damage assessments and Association Agreement compliance schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Germany Contract Logistics Market