
 Celiac Disease Treatment Market | 2026-2036
Celiac Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Celiac Disease Treatment Market Analysis
North American pharmaceutical capacity is fragmenting as contract manufacturing organizations expand biologic drug substance facilities across the United States and Canada. Takeda Pharmaceutical Company Limited leverages its gastroenterology heritage to sustain development pipelines in immune-modulating therapies. Teva Pharmaceutical Industries Ltd. competes through generic gluten-free medication formulations and broad pharmacy distribution. Amgen Inc. anchors its position via biologic manufacturing scale and inflammation-targeting R&D intensity.
Celiac disease treatment encompasses dietary management, enzymatic interventions, and emerging pharmacologic therapies designed to prevent gluten-triggered autoimmune damage to small intestinal villi. Gluten-free foods remain the dominant consumption category, though margin pools increasingly shift toward prescription enzyme products and nutritional supplements as patients seek alternatives to strict lifelong dietary adherence. Medications represent the fastest-expanding segment, driven by pipeline candidates targeting zonulin pathway modulation and gluten peptide neutralization. Distribution through pharmacies controls the highest-value channel for prescription-grade formulations, while online retail captures volume growth in consumer-directed nutritional supplements.
FDA oversight of celiac-targeted biologics demands rigorous gluten-challenge trial designs, while EMA's MDR framework shapes device-drug combination product standards for enzyme delivery systems. The EU Green Deal's sustainable manufacturing requirements are pressuring reformulation of excipient sourcing and packaging for European market access. Stakeholders must monitor regulatory divergence between gluten threshold labeling standards and emerging pharmacologic approval pathways to align portfolio investments with reimbursable treatment paradigms.
Market Dynamics
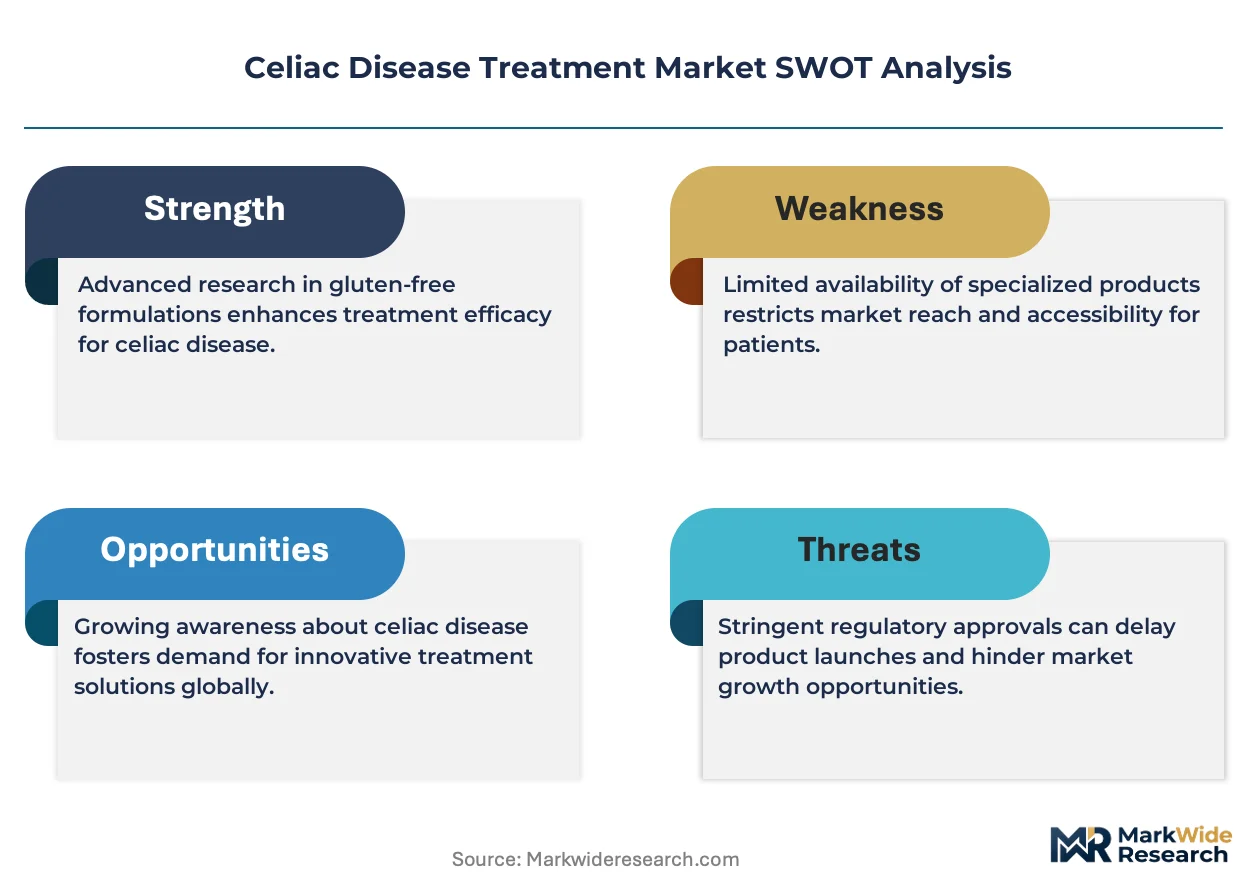
FDA gluten-challenge trial mandates are compressing development timelines for pharmacologic candidates while simultaneously elevating capital requirements for market entry. This regulatory architecture favors sponsors with existing gastroenterology infrastructure and biologic manufacturing scale.
Growth Catalysts
- Diagnostic protocol expansion:Serological screening integration into primary care protocols across Germany, Italy, and the United States is enlarging the addressable diagnosed population. Earlier detection compresses time-to-treatment initiation.
- EMA MDR pathway clarity:Device-drug combination standards for enzyme delivery systems have crystallized, reducing regulatory uncertainty for novel delivery formats. Sponsors now navigate predictable conformity assessment routes.
- Homecare administration models:Self-injected biologic candidates and oral enzyme therapies are shifting site-of-care from infusion centers to patient homes. This reconfiguration expands pharmacy channel capture rates.
Market Restraints
- Gluten-free diet substitution economics:Zero-cost dietary elimination remains the clinical standard, creating price ceiling pressure on reimbursable pharmacologic alternatives. Payers benchmark novel therapies against this free baseline.
- Trial recruitment bottlenecks:Gluten-challenge protocols require histologically confirmed active disease, shrinking eligible patient pools. CRO capacity constraints in North America and Western Europe extend enrollment timelines.
- Excipient supply concentration:Pharmaceutical-grade enzyme stabilizers and enteric coating materials concentrate among three European specialty chemical suppliers. Any disruption propagates through formulation pipelines.
Strategic Opportunities
- India diagnostic penetration:Under-recognized celiac prevalence in South Asian populations presents whitespace for serology-based screening programs. CDSCO pathways for orphan indications offer expedited review timelines.
- Zonulin modulation convergence:Combination therapies pairing tight-junction stabilizers with gluten-neutralizing enzymes represent untargeted mechanistic territory. First movers capture mechanistic exclusivity.
- Specialty pharmacy integration:Limited distribution networks for biologic celiac therapies enable direct patient data capture and adherence monitoring. This infrastructure supports outcomes-based contracting with payers.
Industry Challenges
- Histopathology reader variability:Villous atrophy scoring lacks standardization across central laboratories, introducing noise into Phase III efficacy endpoints. Sponsors must invest in reader training and digital pathology validation.
- Legacy dietary counseling infrastructure:Gastroenterology practices remain organized around dietitian-led gluten-free education. Pharmacologic prescribing requires physician behavior modification and reimbursement code navigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celiac Disease Treatment Market |
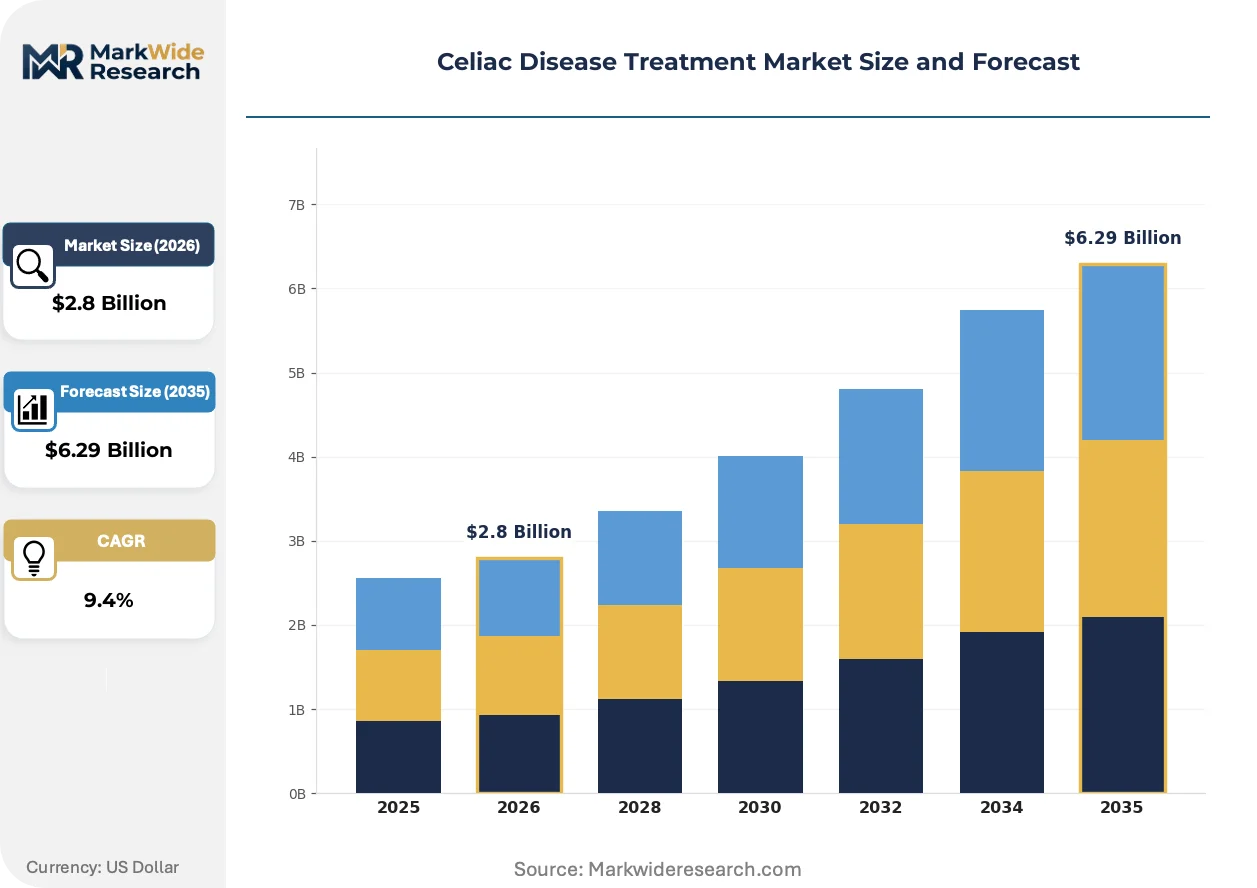
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free Foods, Nutritional Supplements, Enzyme Products, Medications Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies End User: Hospitals, Clinics, Homecare, Retail Customers Formulation: Tablets, Powders, Capsules, Liquid |
| Companies Covered | Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Amgen Inc., Novartis Pharmaceuticals Corporation, F. Hoffmann-La Roche Ltd., 9 Meters Biopharma, ImmunogenX, BioLineRx Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celiac Disease Treatment Market Emerging Trajectories
Biologic manufacturing advances and regulatory science evolution are compressing traditional development paradigms while opening mechanistic frontiers previously inaccessible to celiac therapeutics. Three forces merit particular attention.
Recombinant enzyme engineering is rendering obsolete the native enzyme extracts that dominated early-generation glutenase products. Second-generation candidates from microbial expression systems achieve superior specific activity and batch consistency. Specialty pharmacies are prioritizing these reformulated products in their formularies.
EU Green Deal sustainable manufacturing requirements are forcing excipient sourcing audits and packaging redesign for European market access. The regulation's carbon accounting mandates propagate through supplier qualification processes. Biologic sponsors with existing ESG infrastructure capture competitive positioning advantages.
Patient advocacy organizations are consolidating purchasing influence through disease-specific foundations that negotiate supplemental access programs. These entities are displacing traditional patient assistance program structures with direct manufacturer contracting. The United States exhibits the most advanced foundation-pharmacy integration.
Celiac Disease Treatment Market Segmentation
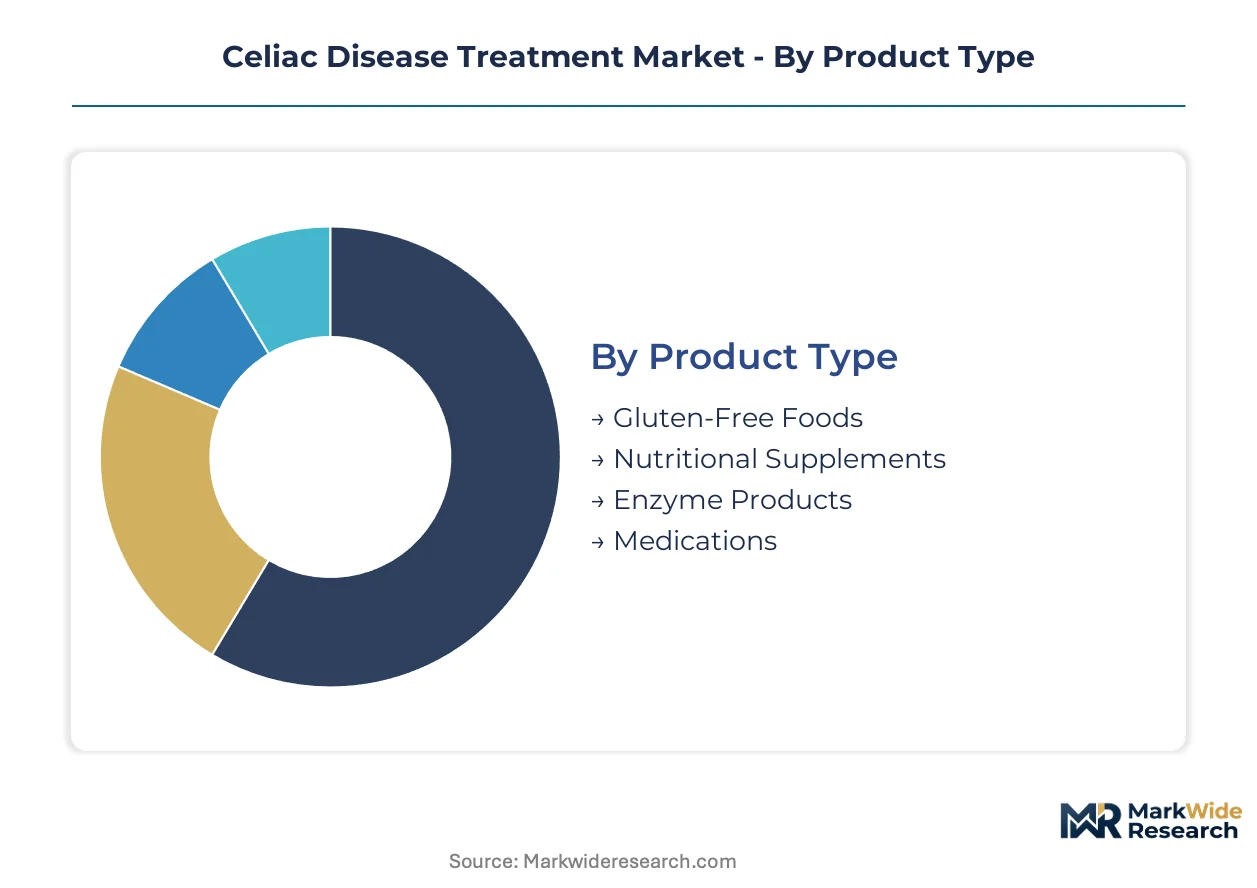
Treatment modality segmentation reveals divergent margin profiles across the celiac therapeutic landscape. Product type distinctions separate commodity dietary goods from prescription-grade interventions, while distribution channel stratification maps patient acuity to purchase behavior.
Product Type:
Inventory velocity varies dramatically across this category, with perishable gluten-free foods turning fastest and development-stage medications exhibiting the longest commercialization cycles.
- Medications:Pharmacologic candidates targeting zonulin pathway modulation and gluten peptide neutralization command premium pricing through specialty pharmacy channels. Clinical trial pipelines concentrate in the United States and Western Europe, where FDA and EMA gluten-challenge protocols compress development timelines while elevating capital barriers.
- Enzyme Products:Second-generation recombinant glutenases from microbial expression systems displace native enzyme extracts through superior specific activity and batch-to-batch consistency. Homecare administration models accelerate pharmacy channel capture for self-administered formulations.
- Nutritional Supplements:Micronutrient replacement products address malabsorption sequelae in newly diagnosed patients, with demand clustering around iron, B12, and vitamin D formulations.
- Gluten-Free Foods:Dietary staples including bread, pasta, and prepared meals constitute the highest-volume consumption category despite thin margin pools and zero reimbursability.
Gluten-free foods anchor the volume base while medications gain share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply by patient acuity, with prescription fulfillment commanding service premiums and direct-to-consumer routes capturing convenience-seeking segments.
- Pharmacies:Specialty and retail pharmacy networks control access to prescription enzyme therapies and emerging biologics, with limited distribution models enabling adherence monitoring and outcomes data capture.
- Online Retail:E-commerce platforms aggregate consumer-directed nutritional supplements and gluten-free pantry staples, with subscription models penetrating highest in the United States and Germany.
- Supermarkets:Mainstream grocery expansion of dedicated gluten-free aisle space has commoditized staple categories while compressing price points for private-label alternatives.
- Health Food Stores:Independent natural products retailers retain loyalty among patients seeking practitioner-grade supplements and novel gluten-free specialty items.
Pharmacies concentrate the highest-value transactions while online retail scales most rapidly in patient-direct supplement sales.
End User:
Site-of-care migration patterns reshape procurement authority, with institutional buyers ceding ground to patient-directed purchasing decisions.
- Homecare:Self-administered enzyme therapies and oral biologic candidates are displacing infusion-dependent models, expanding pharmacy channel capture and reducing site-of-care costs.
- Retail Customers:Direct-to-consumer purchasing dominates gluten-free food and over-the-counter supplement categories, with digital discovery driving trial conversion.
- Hospitals:Acute care settings manage celiac crisis presentations and refractory cases, with pharmacy formularies prioritizing parenteral nutrition and immunosuppressive protocols.
- Clinics:Gastroenterology and allergy practices function as diagnostic gatekeepers and dietary counseling hubs, with limited prescribing of pharmacologic alternatives.
Retail customers generate the highest transaction frequency while homecare absorbs the steepest prescription volume growth.
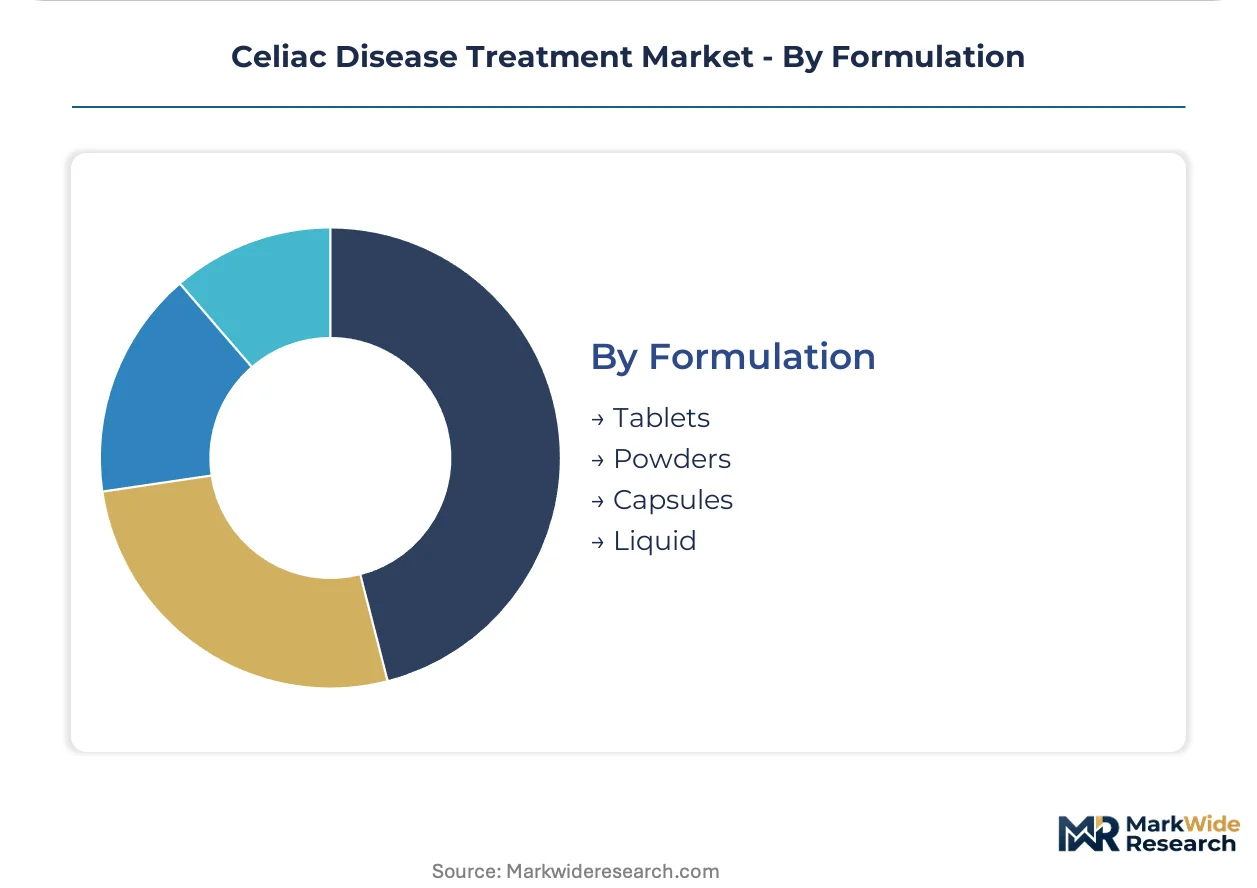
Formulation:
Manufacturing complexity and stability requirements segment production economics, with liquid and powder formats demanding distinct supply chain infrastructure versus solid dosage forms.
- Capsules:Enteric-coated and acid-resistant capsule technologies protect enzyme activity through gastric transit, with European excipient suppliers concentrating supply of specialized coating materials.
- Tablets:Compressed solid dosage forms dominate prescription medication categories, with high-speed tableting lines amortizing costs across large-batch biologic and small-molecule production.
- Powders:Bulk enzyme preparations and nutritional supplement blends offer dose flexibility and pediatric palatability, with sachet packaging dominating European and Asian market preferences.
- Liquid:Suspension formulations address swallowing difficulties in pediatric and elderly populations, with cold-chain requirements limiting distribution reach for probiotic-containing products.
Tablets retain the largest installed manufacturing base while capsules expand most quickly in enzyme delivery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic manufacturing capacity for celiac-targeted therapies clusters in the United States and Western Europe, with contract development organizations scaling mammalian cell culture facilities in Massachusetts, North Carolina, and Bavaria to meet gluten-challenge trial demand.
United States
Specialty pharmacy networks in Boston and the Research Triangle Park absorb prescription enzyme volume as gastroenterology practices integrate pharmacologic alternatives into care pathways. FDA gluten-challenge protocols compress Phase III timelines while elevating capital requirements for market entry. Cambridge, Massachusetts anchors biologic R&D concentration with multiple sponsors advancing zonulin pathway modulators through IND-enabling studies.
Germany
Serological screening integration into primary care protocols across Bavaria and North Rhine-Westphalia enlarges the diagnosed addressable population. EMA MDR framework clarity for device-drug combination products reduces regulatory uncertainty for novel enzyme delivery formats. Heidelberg and Munich host central laboratories developing standardized villous atrophy scoring methodologies to reduce histopathology reader variability in clinical trials.
Italy
Lombardy and Emilia-Romagna exhibit elevated celiac prevalence among pediatric populations, driving demand for micronutrient replacement formulations and dietary counseling infrastructure. EMA orphan designation pathways for gluten-targeting biologics offer expedited review timelines for sponsors with Italian regulatory submissions. Milan concentrates contract research organization capacity for gluten-challenge protocol execution.
India
Under-recognized celiac prevalence in South Asian populations presents whitespace for serology-based screening programs in Maharashtra and Gujarat. CDSCO pathways for orphan indications offer expedited review timelines for first movers in zonulin modulation therapies. Hyderabad and Bangalore contract manufacturers are qualifying pharmaceutical-grade enzyme stabilizer supply chains for export formulation.
Canada
Health Canada alignment with FDA gluten-challenge standards enables parallel submission strategies for sponsors targeting North American approval. Toronto and Montreal gastroenterology centers participate in multi-site histopathology validation studies to standardize villous atrophy endpoints. British Columbia health authorities pilot outcomes-based contracting models for specialty biologic distribution through limited pharmacy networks.
Celiac Disease Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in enzyme engineering and enteric coating technologies. The market exhibits tiered concentration with large-cap biopharmaceutical sponsors controlling biologic development pipelines and mid-cap specialists dominating recombinant glutenase formulation. Three archetypes predominate: gastroenterology heritage multinationals with inflammation R&D infrastructure, generic manufacturers diversifying into gluten-free medication alternatives, and biologic scale operators leveraging mammalian cell culture capacity. Competitive dynamics center on M&A activity targeting zonulin pathway intellectual property and strategic partnerships securing European excipient supply for enzyme stabilizers.
Within the gastroenterology heritage tier, Takeda Pharmaceutical Company Limited occupies a position exemplifying immune-modulating therapy development infrastructure. Among Israel-based specialists, BioLineRx Ltd. and ImmunogenX represent the emerging biologics archetype with pipeline concentration in tight-junction modulation. At the scale-driven end, Amgen Inc. anchors biologic manufacturing positioning through inflammation-targeting R&D intensity.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Amgen Inc. |
| Novartis Pharmaceuticals Corporation |
| F. Hoffmann-La Roche Ltd. |
| 9 Meters Biopharma |
| ImmunogenX |
| BioLineRx Ltd. |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Heidelberg and Munich laboratory clusters concentrate pharmaceutical-grade enzyme stabilizer production, granting European specialty chemical suppliers outsized leverage in downstream glutenase formulation pricing. This geographic concentration propagates cost volatility through enteric coating supply chains whenever batch consistency requirements tighten.
Pricing Analysis
FDA gluten-challenge trial mandates dictate the pricing tier structure across prescription enzyme therapies and emerging biologics. Three-tier pricing structure across premium, standard, and economy levels separates zonulin pathway modulators from second-generation recombinant glutenases and native enzyme extracts. Price differentiation hinges on clinical validation depth and specialty pharmacy distribution exclusivity. Cost compression in the enzyme product tier is intensifying because gluten-free diet substitution economics create zero-cost competitive benchmarks. Retail customers exhibit highest price sensitivity, while hospital formularies demonstrate lowest sensitivity due to bundled reimbursement codes.
Supply Chain Analysis
EU Green Deal carbon accounting mandates function as de facto export-control barriers for non-compliant excipient sourcing, limiting formulation material flows into European markets. Supply concentrates in Germany, Italy, and India for pharmaceutical-grade enzyme stabilizers, enteric coating polymers, and recombinant microbial expression systems. Raw material dependencies include European specialty chemical excipients, Indian API intermediates, and North American biologic cell culture media. Single-source vulnerability permeates the three-supplier concentration for acid-resistant coating materials. Distribution runs through limited specialty pharmacy networks for prescription tiers and direct-to-consumer e-commerce for nutritional supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty pharmacy platform consolidation is creating interoperability standards for patient adherence data, repositioning pharmacologic celiac therapies within outcomes-based reimbursement ecosystems.
For Market Incumbents: Entrench gastroenterology practice relationships through embedded dietitian-pharmacist care coordination teams before pipeline competitors secure formulary access. Deepen backward integration into recombinant enzyme manufacturing to neutralize European excipient supply concentration risks. Prioritize villous atrophy scoring standardization investments to reduce Phase III endpoint variability that threatens approval timelines. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated diagnostic whitespace through CDSCO orphan indication pathways for zonulin modulation candidates. Target Maharashtra and Gujarat for serology-based screening program partnerships that enlarge addressable diagnosed populations. Deploy direct-to-clinic sampling programs that bypass established pharmacy channel gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with existing ESG infrastructure over component specialists exposed to EU Green Deal compliance costs. Long-term viability hinges on mechanistic exclusivity in tight-junction modulation rather than commodity enzyme replacement. Acquisition targets should demonstrate captive biologic manufacturing capacity or secured European excipient supply agreements. Watch for FDA guidance revisions on gluten-challenge protocol endpoints as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Gluten-challenge protocol standardization reduces histopathology reader variability across Heidelberg and Munich central laboratories. |
| Manufacturing Scale-Up | Recombinant microbial expression system expansion displaces native enzyme extracts through superior batch consistency metrics. |
| Regulatory Approval Pathway | EMA MDR conformity assessment clarity accelerates device-drug combination product timelines for novel delivery formats. |
| Pipeline Diversification | Zonulin pathway modulation candidates capture mechanistic exclusivity in untargeted tight-junction stabilization territory. |
| Licensing Agreement | European excipient supply partnerships mitigate single-source vulnerability in pharmaceutical-grade enzyme stabilizer sourcing. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population sizing and top-down pharmaceutical revenue triangulation anchored market estimates. Primary interviews captured gluten-challenge protocol execution constraints and specialty pharmacy channel economics.
Demand-supply-balance framing structured the analytical approach across the analysis window. Segmentation dimensions modeled include treatment modality, formulation type, distribution channel, and regional regulatory cluster. CAGRs were derived from patient population growth trajectories, diagnostic protocol expansion rates, and pipeline candidate probability-weighted revenue forecasts. Industry-specific inputs incorporated villous atrophy scoring standardization timelines and EU Green Deal carbon accounting compliance costs.
Stress conditions across diagnostic penetration rates, excipient supply disruptions, and gluten-challenge recruitment bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway clarity and payer reimbursement code expansion. Material shifts in FDA gluten-challenge endpoint requirements or EMA MDR device-drug combination standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Laser Therapy Market