
 Asia-Pacific Water Free/ Waterless Urinals Market | 2026-2036
Asia-Pacific Water Free/ Waterless Urinals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Free/ Waterless Urinals Market Insights
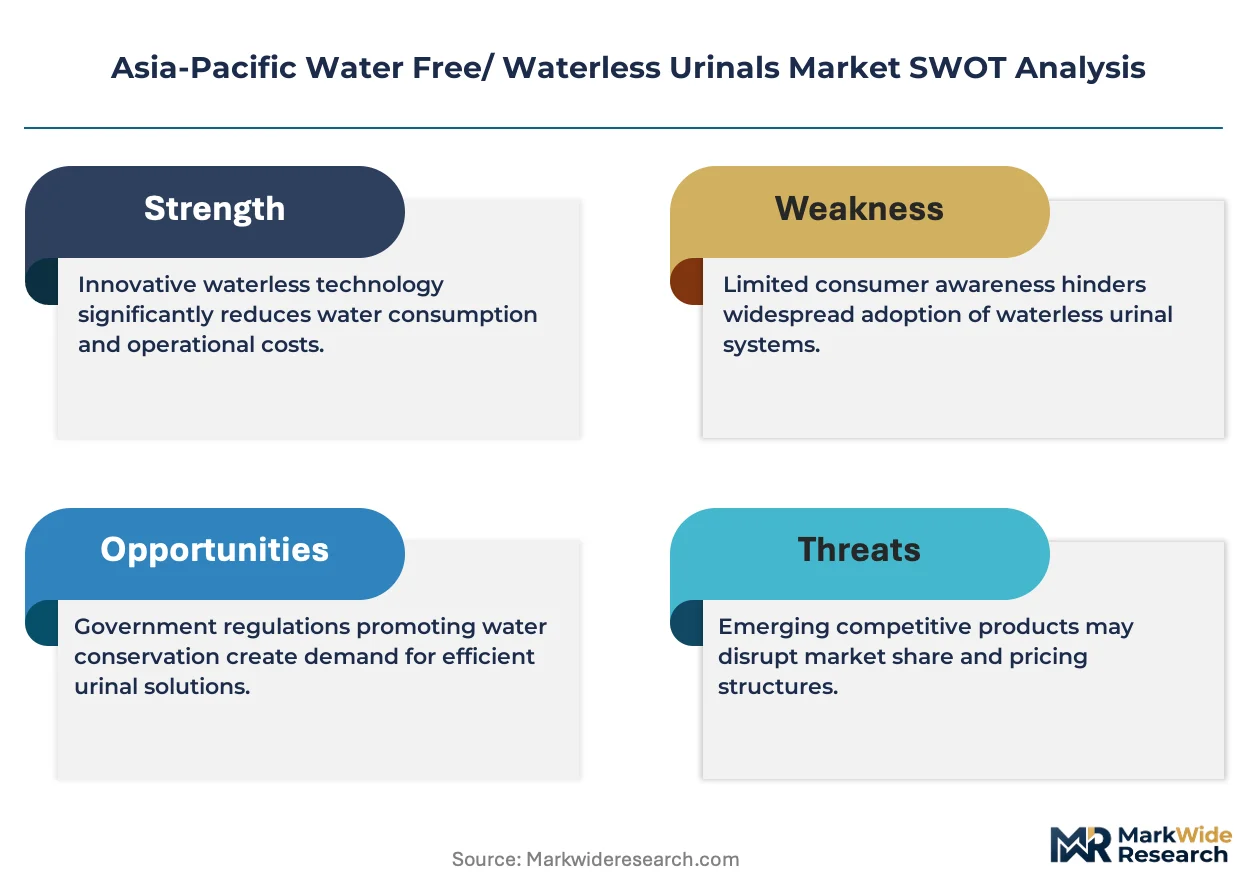
The performance gap between premium sensor-activated systems and basic manual units is broadening across Asia-Pacific procurement channels. Falcon Waterfree Technologies leverages its proprietary cartridge technology to anchor high-specification projects in Australian commercial towers. Kohler competes through extensive distributor networks spanning Tier-1 Indian cities. Toto sustains manufacturing scale advantages at its regional production bases, while Duravit differentiates through design-led positioning in Southeast Asian hospitality developments.
Asia-Pacific water free urinals are plumbing fixtures that eliminate flush water through sealed cartridge, membrane, or biological trap mechanisms, typically rated for zero liters per use and constructed from vitreous china or stainless steel with odor-blocking seals. Their primary purpose is to reduce building water consumption and sewer discharge volumes in high-traffic restroom environments. Sensor-activated units command premium positioning due to touchless hygiene alignment with post-pandemic building standards, while retrofit converters represent the fastest-growing installation category as existing structures seek compliance without full plumbing replacement. Commercial buildings generate the dominant end-user demand pool, though public restroom upgrades in Indian and Chinese municipal programs are expanding fastest.
India's Bureau of Indian Standards and Central Public Health and Environmental Engineering Organisation shape product certification requirements for waterless fixtures in government-backed infrastructure. China's Ministry of Ecology and Environment enforces building water-efficiency benchmarks that directly influence urinal specification in new construction permits. Australia's WaterMark certification scheme controls market access for plumbing products. Stakeholders must monitor evolving municipal green building codes across these jurisdictions to anticipate specification shifts before tender cycles close.
Market Dynamics
Dual carbon mandates across China and water-efficiency procurement rules in India are compressing specification cycles, forcing building operators to choose between retrofit cartridge systems and full fixture replacement before tender deadlines close.
Growth Catalysts
- BIS water-efficiency mandates:India's Bureau of Indian Standards certification requirements for government infrastructure projects are mandating zero-liter fixtures in new public restroom construction.
- Sensor-activated hygiene alignment:Touchless activation mechanisms are capturing specification share in Australian green-certified commercial towers seeking post-pandemic building standards compliance.
- China's dual carbon goals:The Ministry of Ecology and Environment is tightening building water-efficiency benchmarks that directly influence urinal permitting in Tier-1 metro new construction.
Market Restraints
- Vitified china input volatility:Ceramic raw material costs fluctuate with energy pricing in Chinese manufacturing clusters, compressing margin buffers for specification-grade producers.
- Cartridge supply concentration:Proprietary sealing mechanisms depend on limited specialty chemical suppliers in Japan and South Korea, creating single-source vulnerability.
- Biological trap performance limits:Membrane-based odor blocking degrades in high-humidity tropical climates, restricting deployment in Southeast Asian coastal facilities.
Strategic Opportunities
- Indian smart city restroom infrastructure:Municipal programs in 100 designated urban centers are bundling waterless fixtures into public sanitation upgrades with centralized procurement.
- Retrofit converter category expansion:Cartridge-based conversion kits for existing flush urinals open compliance pathways without full plumbing replacement in aging Australian office stock.
- Green building certification stacking:Australia's Green Star and India's GRIHA rating systems are awarding incremental points for zero-water fixtures, creating specification pull in premium developments.
Industry Challenges
- WaterMark certification timeline compression:Australia's plumbing product approval process creates 4-6 month lag between product submission and market entry, misaligning with fast-track construction schedules.
- Legacy drainage integration complexity:Existing sewer line slopes and trap configurations in 1990s-era Southeast Asian commercial buildings require case-by-case engineering assessment before waterless retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Free/ Waterless Urinals Market |
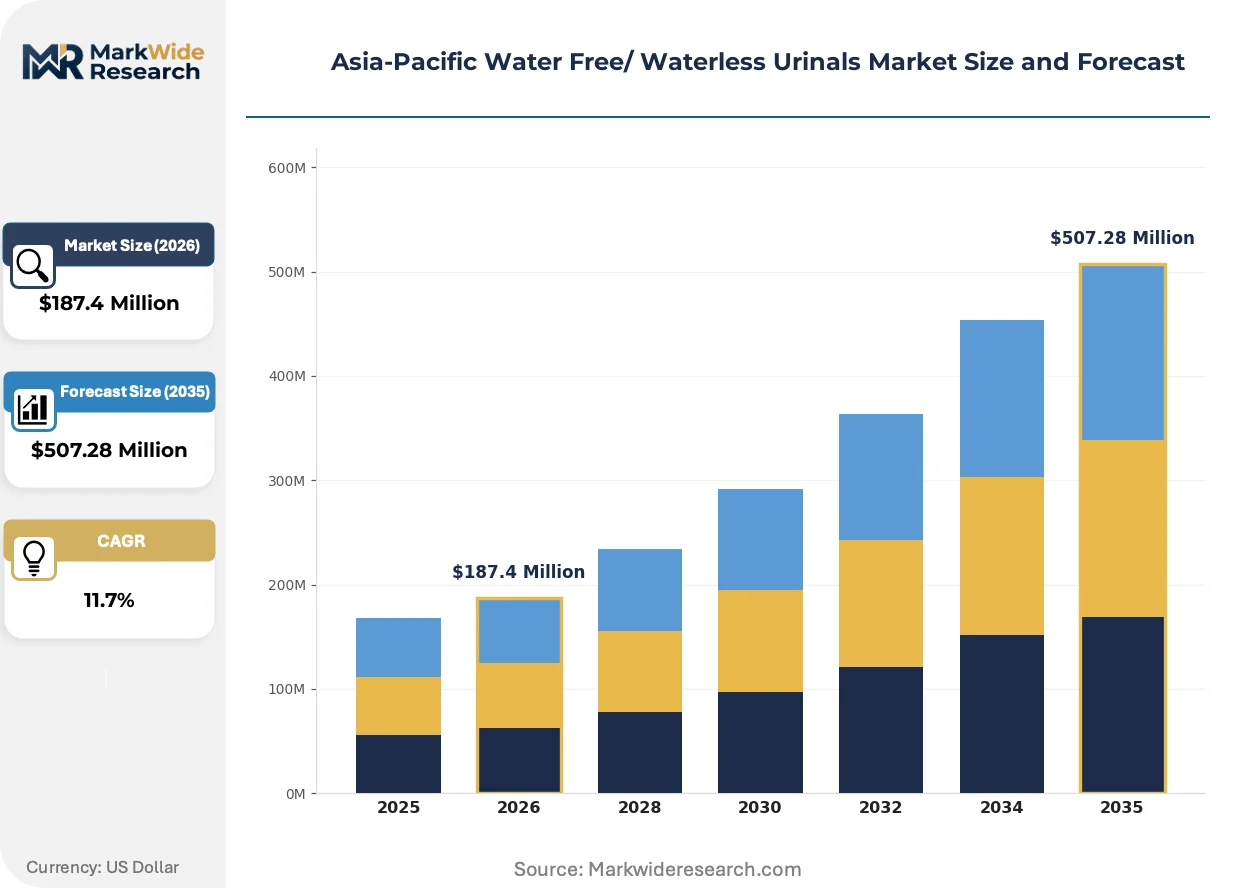
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-Activated, Manual, Retrofits, Converters Installation Type: New Installations, Renovations, Upgrades, Temporary Installations End User: Commercial Buildings, Public Restrooms, Residential, Industrial Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Installers |
| Companies Covered | Falcon Waterfree Technologies, Kohler, Duravit, Caroma, Toto, American Standard, Roca, Sloan Valve Company, Waterless Co. Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Free/ Waterless Urinals Market Trends and Innovations
Specification-grade sensor integration is unifying hygiene performance with water elimination, collapsing the historical trade-off between touchless operation and zero-flush functionality that previously segmented the product hierarchy.
Sealed cartridge technology is unifying odor blocking with maintenance interval extension through biodegradable sealing liquid formulations. Australian commercial tower operators are specifying these systems in 18-24 month replacement cycles rather than quarterly servicing. This unifying architecture is compressing the premium tier by eliminating the separate maintenance contract layer that previously justified higher upfront pricing.
China's Ministry of Ecology and Environment is enforcing building water-efficiency benchmarks through construction permit conditionalities. Developers in Shanghai and Shenzhen must demonstrate fixture specifications meeting zero-liter ratings before occupancy authorization. High-rise commercial projects are responding by pre-specifying sensor-activated waterless units in architectural tender packages to accelerate approval timelines.
Facility management outsourcing is consolidating purchasing authority across multi-site commercial portfolios. Australian property services firms are centralizing urinal specification decisions for entire office towers under single procurement desks. This concentration is visible most acutely in Sydney and Melbourne green-certified stock where sustainability performance reporting drives standardization across building clusters.
Asia-Pacific Water Free/ Waterless Urinals Market Segmentation
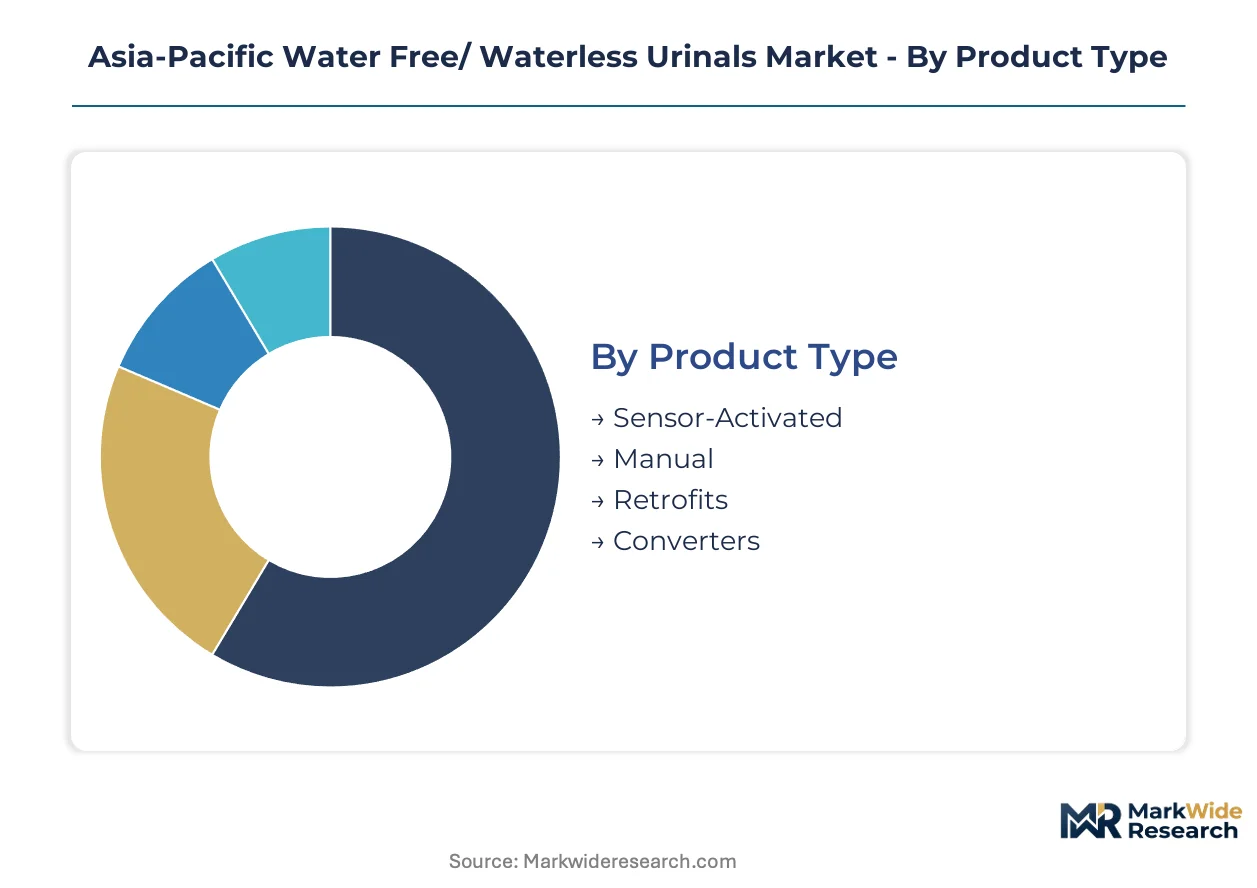
Specification decisions across Asia-Pacific waterless urinals diverge sharply by procurement authority and installation context. Building operators prioritize sensor activation for hygiene compliance, while municipal buyers favor retrofit economics in aging infrastructure.
Product Type:
Premium positioning hinges on touchless activation mechanisms that satisfy post-pandemic building standards across Australian commercial towers and Indian metro developments.
- Sensor-Activated:Touchless infrared or capacitive triggering eliminates physical contact while maintaining zero-flush functionality. Australian Green Star-certified office stock in Sydney and Melbourne specifies these units for hygiene audit compliance. India's smart city restroom tenders increasingly mandate sensor activation for public sanitation infrastructure.
- Manual:Basic lever or push-button mechanisms without electronic components reduce upfront cost and maintenance complexity. Deployment concentrates in Southeast Asian hospitality developments where labor costs favor attendant-serviced facilities over automated systems.
- Retrofits:Cartridge-based conversion systems adapt existing flush urinal housings for zero-water operation without full fixture replacement. Australian property services firms specify these for 1990s-era office stock seeking WaterMark certification compliance.
- Converters:Modular sealing mechanisms that insert into standard drain openings, enabling rapid field conversion. Indian municipal programs in Tier-2 cities deploy converters to accelerate public restroom upgrades within compressed procurement cycles.
Volume sits with Manual units; growth tilts toward Sensor-Activated systems.
Installation Type:
Project timeline urgency determines specification flexibility, with fast-track developments accepting temporary solutions while flagship assets pursue full integration.
- New Installations:Factory-integrated waterless fixtures specified during architectural design phase for Shanghai and Shenzhen high-rise commercial projects. China's Ministry of Ecology and Environment construction permit conditionalities drive pre-specification to accelerate occupancy authorization timelines.
- Renovations:Comprehensive restroom overhauls replacing legacy flush systems with sealed-cartridge units. Australian green-certified building retrofits favor 18-24 month maintenance interval specifications to reduce facility management contract complexity.
- Upgrades:Targeted fixture replacement within otherwise intact restroom environments. India's Bureau of Indian Standards water-efficiency mandates for government infrastructure push upgrade specifications in existing public facilities.
- Temporary Installations:Rapid-deployment units for construction sites, events, or emergency sanitation. Deployment clusters around Southeast Asian infrastructure projects requiring modular compliance without permanent plumbing investment.
Renovations dominate current procurement volume; New Installations are climbing the fastest as Tier-1 metro construction accelerates.
End User:
Water cost exposure and regulatory scrutiny intensity segment demand concentration across building typologies.
- Commercial Buildings:High-traffic office towers, retail complexes, and hospitality assets with centralized facility management. Australian property services consolidation drives standardization across multi-site portfolios with sustainability reporting obligations.
- Public Restrooms:Municipal sanitation infrastructure including transit hubs, parks, and government facilities. India's 100 smart cities program bundles waterless fixtures into centralized procurement for public restroom upgrades.
- Residential:High-density apartment developments and luxury housing with sustainability marketing positioning. Limited penetration due to odor perception concerns in humid Southeast Asian climates.
- Industrial Facilities:Manufacturing plants, warehouses, and logistics centers with high workforce density and water cost sensitivity. China's dual carbon goals tighten water-efficiency benchmarks for industrial construction permits.
Commercial Buildings anchor procurement volume; Public Restrooms are gaining share fastest through municipal program scale.
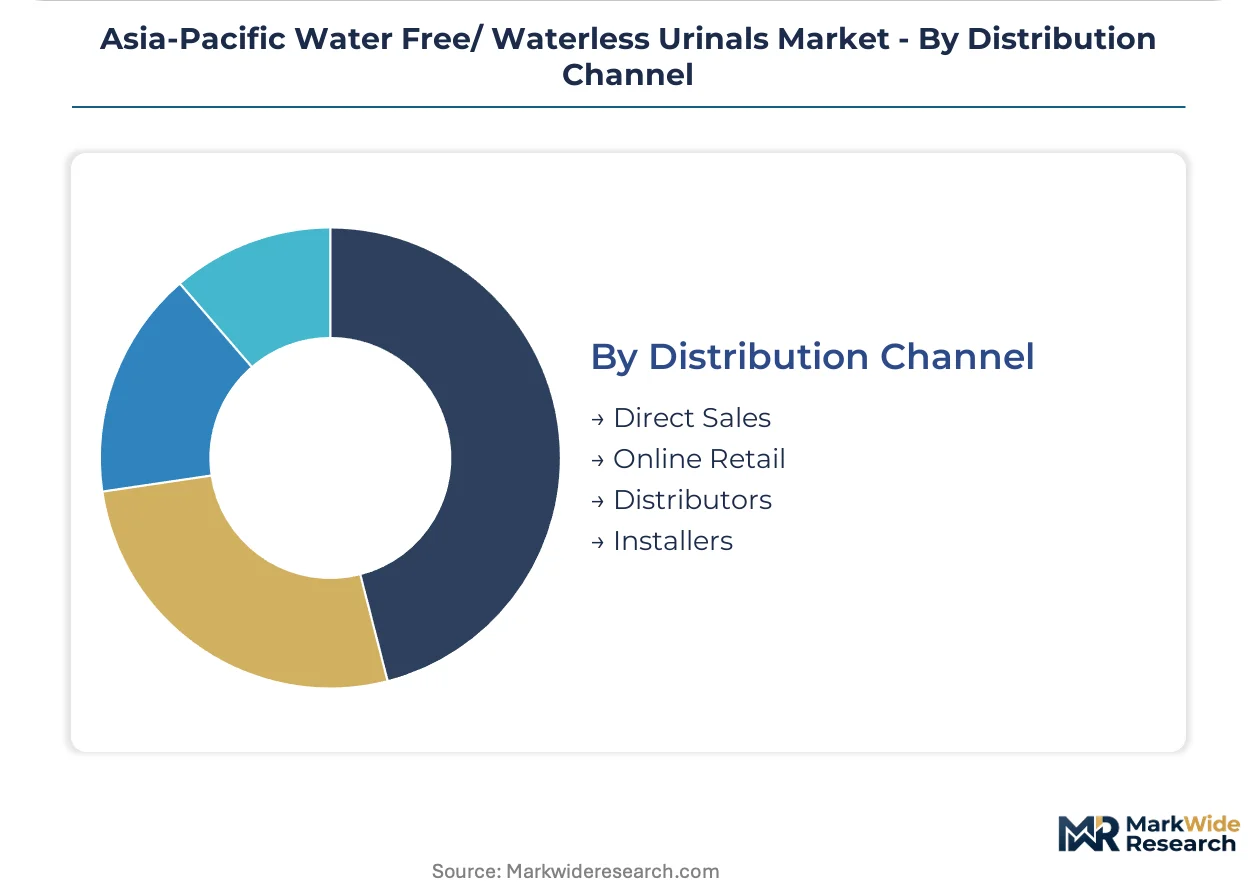
Distribution Channel:
Specification authority concentration among facility management outsourcers reshapes channel economics and relationship requirements.
- Direct Sales:Manufacturer engagement with large property developers, government procurement desks, and multi-site facility managers. Australian commercial tower operators centralize purchasing authority under single procurement desks.
- Online Retail:E-commerce platforms serving small contractors and residential replacement demand. Limited penetration for specification-grade sensor-activated systems requiring technical consultation.
- Distributors:Regional inventory and logistics networks spanning Tier-1 Indian cities and Southeast Asian construction hubs. Kohler competes through extensive distributor coverage in Indian metro markets.
- Installers:Plumbing contractors and facility maintenance firms specifying through trade relationships. WaterMark certification requirements create 4-6 month lag that misaligns with fast-track construction schedules.
Distributors handle the greatest transaction volume; Direct Sales are expanding most quickly as procurement authority consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne green-certified commercial towers concentrate specification demand for sensor-activated waterless urinals, while procurement authority consolidates under Australian property services firms with multi-site sustainability reporting obligations.
Australia
Green Star-certified office stock in Sydney and Melbourne drives specification for touchless waterless fixtures with 18-24 month maintenance intervals. WaterMark certification requirements create 4-6 month approval lags that misalign with fast-track construction schedules. Property services firms centralize purchasing authority across entire office tower portfolios.
China
Shanghai and Shenzhen high-rise commercial projects pre-specify sensor-activated units to accelerate Ministry of Ecology and Environment construction permit approvals. Dual carbon goals tighten water-efficiency benchmarks for new building occupancy authorization. Tier-1 metro developers bundle zero-liter fixtures into architectural tender packages.
India
Municipal programs across 100 designated smart cities bundle waterless fixtures into centralized public restroom procurement. Bureau of Indian Standards certification mandates zero-liter fixtures for government infrastructure construction. Tier-2 cities deploy cartridge converters to accelerate upgrades within compressed tender cycles.
Japan
Specialty chemical suppliers in Japanese manufacturing clusters provide proprietary sealing liquids for cartridge-based odor blocking systems. Domestic producers maintain captive supply relationships with regional fixture assemblers. Tokyo commercial developments specify extended-maintenance sealed systems for high-traffic environments.
Southeast Asia
Hospitality developments in humid coastal zones favor manual mechanisms over membrane-based systems due to biological trap degradation concerns. Singapore and Bangkok commercial towers prioritize design-led positioning in premium restroom fit-outs. Retrofit economics dominate procurement for 1990s-era building stock with legacy drainage configurations.
Asia-Pacific Water Free/ Waterless Urinals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and maintenance interval dimensions, with specification-grade sensor-activated systems commanding position above basic manual units in procurement hierarchies. The vendor base organizes into three strategic archetypes: proprietary technology licensors with cartridge-based sealing systems, design-led positioning specialists targeting hospitality developments, and scale-driven manufacturers with regional production footprints. Competitive moves concentrate on distributor network expansion across Tier-1 Indian cities and direct engagement with consolidating Australian property services procurement desks.
Within the proprietary technology tier, Falcon Waterfree Technologies exemplifies cartridge-based system positioning, while Kohler anchors extensive distributor coverage across Indian metro markets. Toto occupies a scale-driven position with regional manufacturing presence. These three represent distinct competitive vectors: sealed-cartridge intellectual property, channel density in high-growth jurisdictions, and production scale advantages respectively.
| Leading Market Players |
|---|
| Falcon Waterfree Technologies |
| Kohler |
| Duravit |
| Caroma |
| Toto |
| American Standard |
| Roca |
| Sloan Valve Company |
| Waterless Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Vitreous china raw material costs originating from Chinese manufacturing clusters cascade through three distinct pricing tiers before reaching Australian commercial tower operators and Indian municipal procurement desks. Energy pricing volatility in ceramic production zones compresses margin buffers for specification-grade producers while amplifying the spread between sensor-activated premium units and basic manual alternatives.
Pricing Analysis
Maintenance-interval guarantees anchor value-based pricing for sealed-cartridge systems, with Australian property services firms paying premiums for 18-24 month service cycles versus quarterly alternatives. Three-tier pricing structure across premium, standard, and economy levels separates WaterMark-certified sensor units from uncertified manual fixtures and disposable converter kits. Cost compression in the economy tier intensifies because Indian Tier-2 municipal buyers prioritize retrofit economics over performance specifications. Public restroom procurement teams exhibit highest price sensitivity; green-certified commercial developers show lowest.
Supply Chain Analysis
WaterMark certification gating creates 4-6 month approval lags that filter which manufacturers can supply Australian fast-track construction schedules. Manufacturing concentrates in China, India, and Japan, with vitreous china forming and specialty chemical sealing liquid production anchoring regional clusters. Proprietary cartridge mechanisms draw from limited Japanese and South Korean chemical suppliers, creating single-source vulnerability for odor-blocking formulations. Distribution runs through regional plumbing distributors in Tier-1 Indian cities and direct sales to consolidating Australian facility management outsourcers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's Bureau of Indian Standards water-efficiency mandates erect a compliance moat that rewards certified incumbents while raising capital barriers for unqualified entrants. The cost-of-compliance story favors players who pre-invested in BIS certification before tender cycles compressed.
For Market Incumbents: Anticipate cartridge supply concentration risk by securing dual-source agreements with Japanese and South Korean chemical suppliers before single-source vulnerabilities trigger shortages. Defend specification share in Australian green-certified towers by extending maintenance-interval guarantees beyond 24 months, matching Falcon Waterfree Technologies' proprietary positioning. Counter emerging Chinese scale manufacturers by deepening WaterMark certification investment to accelerate approval timelines.
For New Entrants and Emerging Players: Tier-2 Indian municipal buyers represent the most penetrable white-space target, with compressed tender cycles favoring agile converter-kit suppliers over established fixture manufacturers. Southeast Asian hospitality developers seeking design-led manual units offer secondary entry path with lower certification barriers. Pursue private-label partnerships with regional Indian distributors to bypass direct BIS certification timelines.
For Investors and Strategic Acquirers: Consolidation of Australian property services procurement authority is the leading indicator that specification-grade sensor-activated systems will capture disproportionate margin pools. Long-term viability rests on proprietary sealing technology or captive cartridge chemistry rather than commodity fixture assembly. Target acquisition archetype: mid-scale manufacturers with existing WaterMark or BIS certification and underutilized regional production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Investment | Compressing WaterMark approval lags aligns supply capability with Australian fast-track construction demand. |
| Cartridge Chemistry Backward Integration | Captive sealing liquid production insulates margin from Japanese and South Korean supplier concentration. |
| Municipal Procurement Desk Direct Engagement | India's 100 smart cities program centralizes authority under single buyers, favoring direct manufacturer relationships. |
| Extended Maintenance Interval Product Development | 18-24 month service cycles command premium positioning in Australian sustainability-reporting commercial portfolios. |
| Retrofit Converter Category Expansion | Cartridge-based conversion kits open compliance pathways without full plumbing replacement in aging Southeast Asian stock. |
Research Methodology
Multi-period observation of tender cycle compression, certification timeline evolution, and municipal procurement bundling patterns anchored the trend analysis, supplemented by interviews with facility management directors, plumbing contractor specification leads, municipal sanitation procurement officers, and ceramic manufacturing plant managers. Secondary validation drew from Bureau of Indian Standards certification registries, WaterMark approval databases, Australian Green Star project listings, and China Ministry of Ecology and Environment construction permit disclosures. Bottom-up fixture shipment tracking and top-down building stock water-efficiency mandate analysis were triangulated for segmentation sizing.
Input-output matrix modeling connected regulatory mandate intensity to specification-grade demand across product type, installation context, and end-user categories over the projection horizon. Segmentation dimensions included activation mechanism, installation type, building typology, and distribution channel, with regional regulatory cluster treated as a cross-cutting modifier. CAGRs were derived from elasticity-adjusted demand curves reflecting mandate implementation timelines and building stock turnover rates. Industry-specific inputs incorporated ceramic raw material cost indices and facility management outsourcing penetration rates.
Revisions become necessary when BIS mandate enforcement intensity shifts, WaterMark approval timelines compress or extend, or dual carbon goal implementation accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory implementation cadence and building stock replacement cycles. A model refresh is warranted upon material change in municipal procurement centralization patterns or cartridge chemistry supplier consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Process Water Treatment Market