
 North America Biopesticides Market | 2026-2036
North America Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biopesticides Market Analytics
Microbial fermentation extracts are realigning cost structures for biochemical formulations, enabling parity with conventional pesticide price points in row-crop applications. Certis Biologicals leverages domestic Bacillus thuringiensis production to anchor supply security for fruit and vegetable growers across Mexico. Bayer AG competes through its biologicals pipeline integration with seed treatment platforms, while Valent BioSciences LLC specializes in biorational chemistry for specialty crop protection.
Biopesticides comprise naturally derived pest control agents including microbial organisms, biochemical compounds, and plant-derived substances formulated to suppress agricultural pathogens and pests through non-toxic modes of action. These products typically require EPA registration under FIFRA with data packages demonstrating target organism specificity and environmental fate profiles. Microbial formulations dominate current volume given established fermentation infrastructure and broad-spectrum applicability, while plant extracts command premium positioning in organic production systems where residue restrictions are strictest. Agricultural applications absorb the majority of sector output, though horticulture segments exhibit faster expansion as greenhouse operators adopt zero-residue protocols for export compliance.
EPA registration pathways under the Federal Insecticide, Fungicide, and Rodenticide Act determine market access timelines, with the agency's Biopesticides and Pollution Prevention Division streamlining reviews for naturally occurring substances. Health Canada's Pest Management Regulatory Authority enforces parallel standards for cross-border product uniformity, while Mexico's COFEPRIS coordinates import authorization with domestic agricultural health mandates. Stakeholders must track evolving residue tolerance harmonization between the three NAFTA successor jurisdictions to anticipate formulation reformulation requirements and label expansion opportunities.
Market Dynamics
EPA registration acceleration for biological active ingredients is compressing commercialization timelines, while microbial fermentation scale-up in the US corn-soy belt realigns supply economics against synthetic chemical incumbents.
Growth Catalysts
- Integrated Pest Management Mandates:Row-crop protocols across the Midwest now prioritize microbial solutions over synthetic rotations, pulling Bacillus-based formulations into standard rotation schedules.
- Residue Harmonization Pressure:Health Canada's PMRA and Mexico's COFEPRIS are aligning tolerance standards with EPA benchmarks, reducing reformulation burdens for cross-border label expansions.
- Fermentation Infrastructure:Domestic Bacillus thuringiensis production capacity in California and Florida is anchoring supply security for specialty crop exporters facing zero-residue protocols.
Market Restraints
- Input Cost Volatility:Fermentation feedstock prices for corn-derived substrates fluctuate with ethanol demand cycles, compressing margin stability for biochemical manufacturers.
- Technical Efficacy Limitations:Microbial formulations exhibit narrower temperature stability windows than synthetic alternatives, restricting application timing in northern tier states.
- Regulatory Data Burden:EPA's FIFRA registration requires extensive environmental fate studies for novel organisms, extending pre-revenue timelines beyond synthetic chemical pathways.
Strategic Opportunities
- Greenhouse Export Compliance:Zero-residue protocols in Mexican protected agriculture are opening premium positioning for plant extract formulations in berry and tomato production.
- Seed Treatment Convergence:Biological active integration with precision application equipment is creating bundled service models in the Dakotas and Nebraska corn belt.
- Organic Transition Incentives:USDA conservation programs in the Midwest are subsidizing biological input adoption during synthetic-to-organic farm conversions.
Industry Challenges
- Formulation Stability Expertise:Shortage of fermentation process engineers with agricultural biologicals experience is constraining scale-up velocity in Great Lakes manufacturing hubs.
- Legacy Equipment Integration:Retrofitting synthetic chemical spray systems for microbial suspension handling requires capital outlays that mid-size cooperatives defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biopesticides Market |
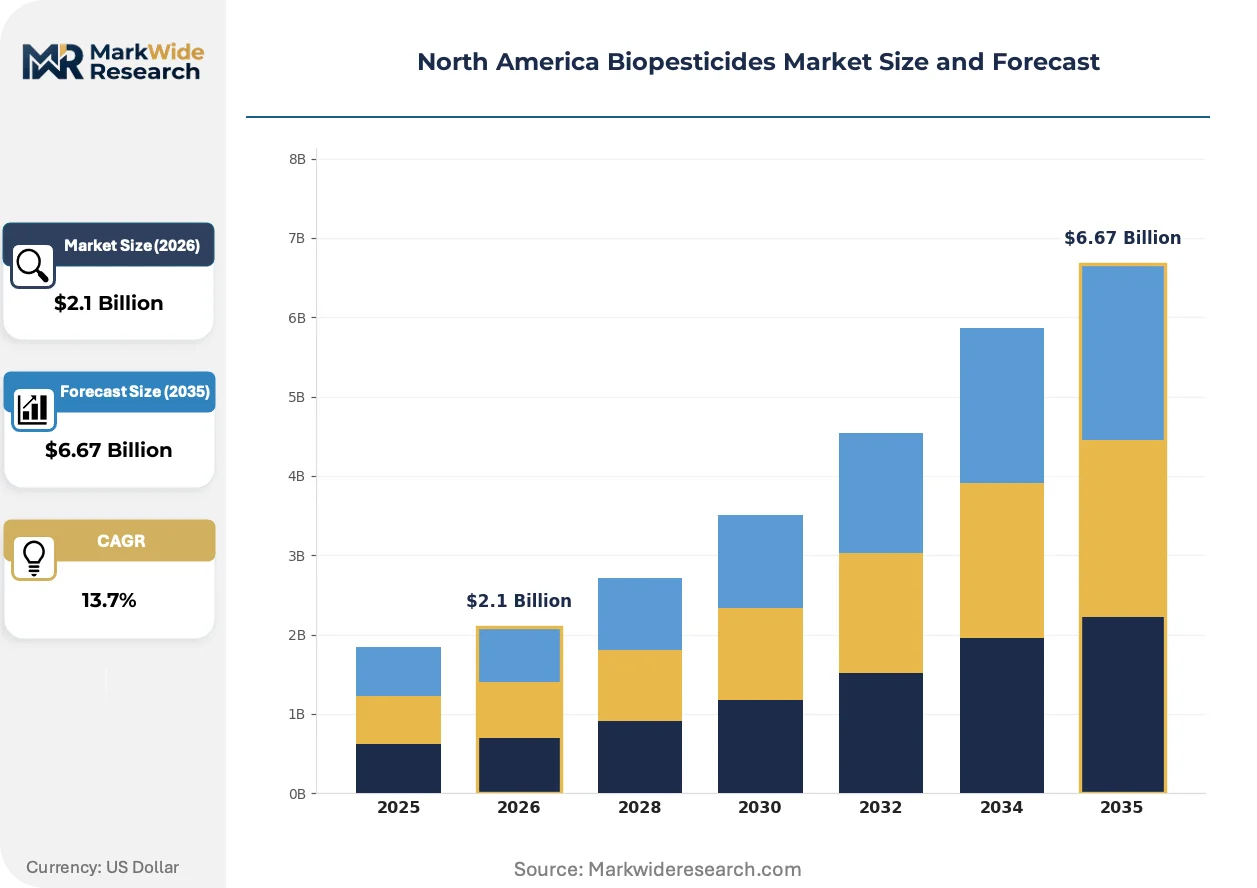
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.67 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biochemical, Plant Extracts, Beneficial Insects Application: Agricultural, Horticulture, Turf, Forestry End User: Farmers, Gardeners, Agricultural Cooperatives, Organic Producers Distribution Channel: Retail, Online, Direct, Wholesalers |
| Companies Covered | Corteva Agriscience, Certis Biologicals, Valent BioSciences LLC, Marrone Bio Innovations, BioWorks Inc., FMC Corporation, Bayer AG, Syngenta AG, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biopesticides Market Evolving Landscape
Biological product development is pivoting from standalone pest control toward system-integrated crop health management, with formulation science and digital agriculture tools merging into unified service offerings.
RNA interference technology is converging with microbial delivery platforms to enable species-specific pest suppression without off-target ecological effects. Specialty vegetable producers in California's Central Valley are piloting these combinations for lepidopteran control in leafy greens. The structural consequence is compressing the addressable market for broad-spectrum synthetics in high-value crop segments.
EPA's Biopesticides and Pollution Prevention Division has streamlined data requirements for naturally occurring substances, reducing review timelines relative to conventional chemical registrations. This regulatory efficiency is redirecting R&D investment toward microbial discovery pipelines rather than synthetic optimization. Fruit and vegetable growers in Florida are the primary beneficiaries, accessing novel Bacillus strains for citrus disease management ahead of traditional chemical alternatives.
Buyer concentration among large-scale Midwest grain cooperatives is consolidating procurement authority into fewer decision-makers with technical specification power. Biological suppliers now bypass traditional distribution channels to establish direct technical service relationships with these buying entities. The Dakotas and Nebraska exhibit the most pronounced channel compression, where cooperative agronomists specify microbial programs for member farms.
North America Biopesticides Market Segmentation
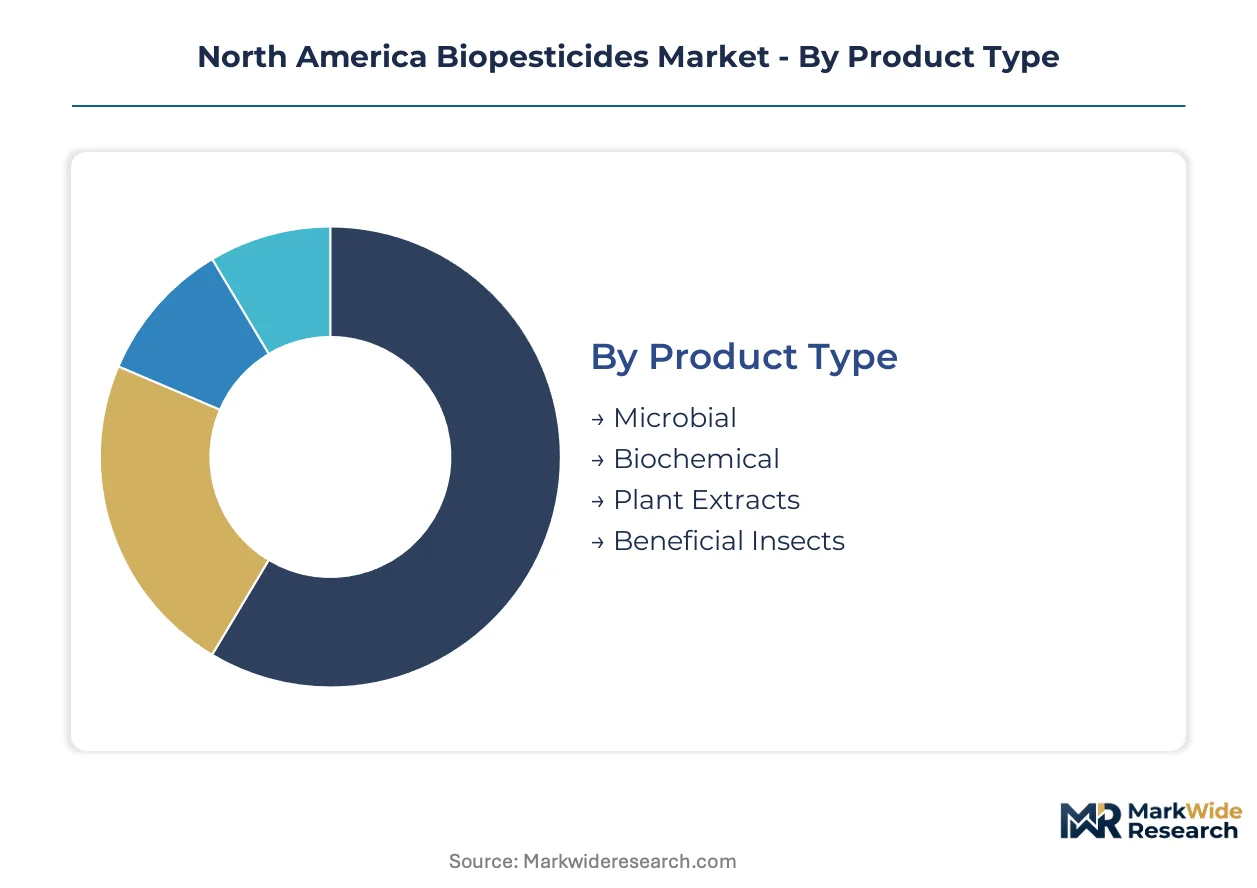
Segmentation in the North America biopesticides market reveals how formulation chemistry, crop value intensity, and procurement authority concentrate demand across distinct commercial channels. Understanding these axes exposes where microbial fermentation scale competes against plant-extract premiums and which buyer types command technical specification power.
Product Type:
Formulation chemistry determines manufacturing infrastructure requirements, registration pathway complexity, and price positioning against synthetic alternatives.
- Microbial:Fermentation-derived organisms including Bacillus thuringiensis and Trichoderma species dominate volume through established production infrastructure in the US corn-soy belt. EPA's streamlined Biopesticides and Pollution Prevention Division reviews compress registration timelines relative to synthetic pathways, pulling these formulations into standard Midwest row-crop rotations.
- Biochemical:Naturally occurring compounds such as insect pheromones and plant growth regulators command mid-tier pricing through semi-synthetic processing requirements. Demand concentrates in California specialty crops where residue tolerance harmonization between EPA and Health Canada's PMRA enables cross-border label efficiency for export-oriented growers.
- Plant Extracts:Botanical formulations including neem and pyrethrin derivatives.
- Beneficial Insects:Macro-organism solutions for greenhouse and orchard systems.
Microbial leads on scale; biochemical leads on momentum.
Application:
Crop value intensity and residue protocol stringency segment demand across open-field and controlled-environment production systems.
- Agricultural:Row-crop and broad-acre applications absorb the majority of sector volume through cooperative procurement consolidation in the Dakotas and Nebraska. Integrated pest management mandates in the Midwest now specify microbial rotations, displacing synthetic chemical dominance in corn and soybean protection protocols.
- Horticulture:High-value fruit, vegetable, and ornamental production in Florida and California's Central Valley drives premium formulation demand. Zero-residue export requirements to Mexico and Canada force rapid adoption of biopesticide programs ahead of regulatory harmonization deadlines.
- Turf:Golf course and recreational grass management applications.
- Forestry:Silviculture and reforestation pest suppression programs.
Agricultural commands volume concentration; horticulture exhibits the steepest expansion trajectory.
End User:
Buyer scale and technical sophistication determine whether procurement flows through distributed retail or consolidated cooperative specification.
- Farmers:Individual growers across the Midwest and Great Plains.
- Gardeners:Residential and small-scale hobbyist purchasers.
- Agricultural Cooperatives:Consolidated buying entities in the corn-soy belt now direct technical service relationships with biological suppliers, bypassing traditional distribution. Member farm aggregation enables volume pricing on Bacillus-based programs while agronomists specify application protocols.
- Organic Producers:Certified operations in California and Florida face strictest residue constraints, driving plant-extract premiums and zero-tolerance compliance investments that synthetic alternatives cannot satisfy.
Agricultural cooperatives lead on procurement scale; organic producers lead on specification intensity.
Distribution Channel:
Channel structure reflects technical support requirements, buyer concentration, and inventory turnover economics for living microbial formulations.
- Retail:Farm supply stores and garden centers serving dispersed smallholders.
- Online:E-commerce platforms expanding access for specialty crop inputs.
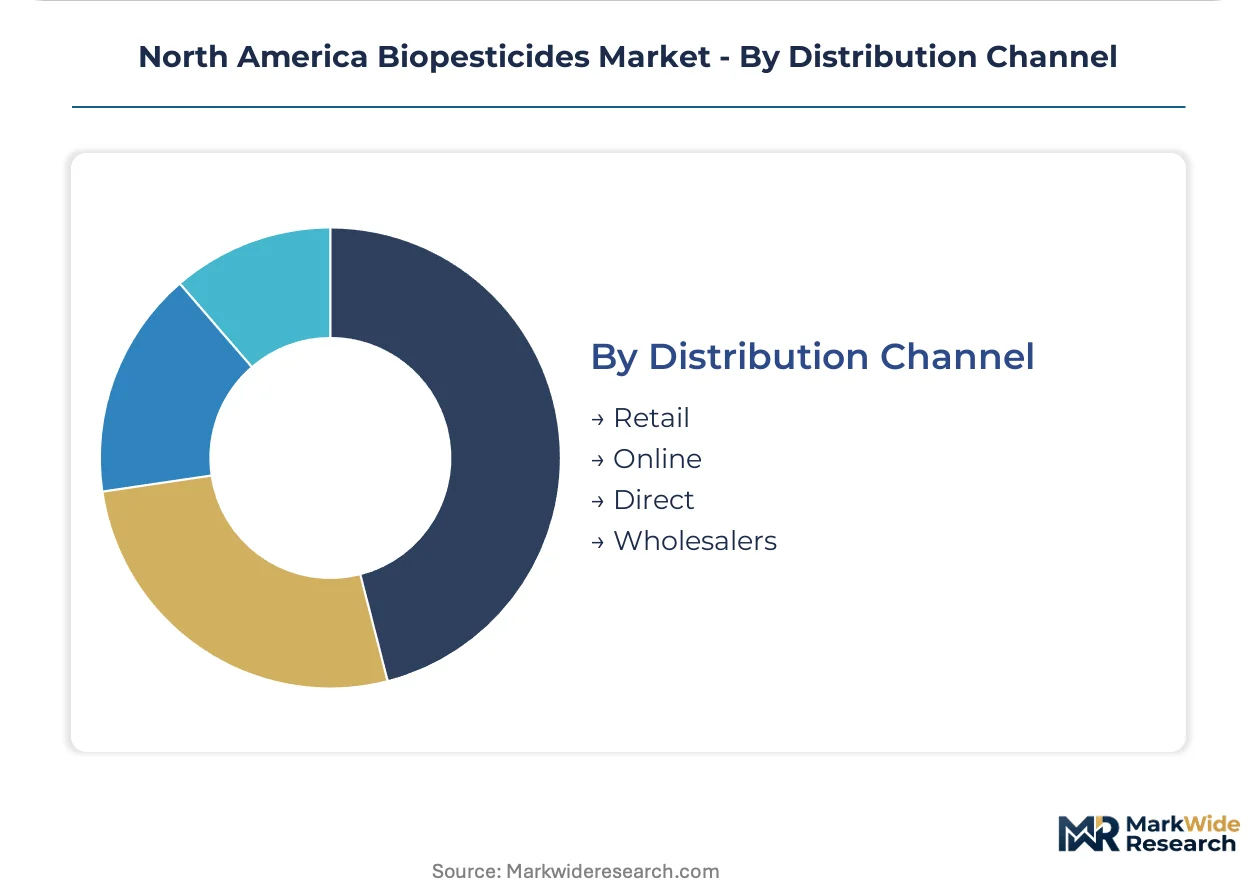
- Direct:Manufacturer-to-grower relationships dominate in the Dakotas and Nebraska where cooperative agronomists specify microbial programs. Biological suppliers bypass distributors to establish technical service partnerships with concentrated buying authority.
- Wholesalers:Regional distributors handling formulation stability and cold-chain logistics for temperature-sensitive microbial suspensions in northern tier states.
Direct channels gain share fastest; wholesalers retain infrastructure scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US corn-soy belt anchors North American biopesticide demand through cooperative procurement consolidation and integrated pest management mandates. EPA registration acceleration under FIFRA is compressing commercialization timelines across all three NAFTA successor jurisdictions.
United States
Midwest row-crop cooperatives in the Dakotas and Nebraska now specify microbial rotations as standard protocol, displacing synthetic chemical dominance in corn and soybean protection. EPA's Biopesticides and Pollution Prevention Division has streamlined data requirements for naturally occurring substances, reducing review timelines relative to conventional chemical pathways. California's Central Valley specialty vegetable producers pilot RNA interference technology with microbial delivery platforms for lepidopteran control in leafy greens.
Canada
Health Canada's PMRA enforces residue tolerance standards parallel to EPA benchmarks, enabling cross-border label efficiency for export-oriented growers in Ontario and Quebec. Prairie grain operations adopt Bacillus-based formulations as synthetic-to-organic farm conversions accelerate under federal conservation incentives. British Columbia greenhouse operators face zero-residue protocols for berry exports to US and Mexican markets.
Mexico
COFEPRIS coordinates import authorization with domestic agricultural health mandates while protected agriculture in Sinaloa and Baja California drives premium demand for plant extract formulations. Zero-residue requirements for tomato and berry exports to the United States force rapid biopesticide program adoption ahead of regulatory harmonization deadlines. Certis Biologicals leverages domestic Bacillus thuringiensis production to anchor supply security for fruit and vegetable growers across the country.
North America Biopesticides Market Competitive Landscape
Global majors compete with regional champions across registration expertise and fermentation infrastructure, creating a tiered structure where scale advantages meet specialized formulation capabilities. The market exhibits moderate consolidation around integrated agrochemical portfolios and dedicated biologicals specialists. Three archetypes dominate: diversified conglomerates with biologicals pipelines, pure-play microbial fermentation specialists, and seed treatment platform integrators. Competitive moves center on direct technical service relationships with cooperative agronomists and backward integration into domestic fermentation capacity.
Among the diversified conglomerates, Bayer AG and Syngenta AG exemplify the seed treatment convergence strategy, while Corteva Agriscience occupies a position bridging chemical and biological portfolios. FMC Corporation represents the mid-tier specialist archetype with focused biorational chemistry capabilities. At the pure-play end, Certis Biologicals, Valent BioSciences LLC, and BioWorks Inc. anchor the dedicated biologicals tier with concentrated expertise in microbial formulation science and EPA registration navigation.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Certis Biologicals |
| Valent BioSciences LLC |
| Marrone Bio Innovations |
| BioWorks Inc. |
| FMC Corporation |
| Bayer AG |
| Syngenta AG |
| Lallemand Inc. |
| Others |
Value Network & Pricing Analysis
Fermentation feedstock costs for corn-derived substrates cascade through biochemical manufacturing tiers, compressing margins for mid-scale producers while concentrated buyers in the Dakotas and Nebraska extract volume discounts on Bacillus-based formulations.
Pricing Analysis
Input-cost pass-through from volatile ethanol demand cycles creates pricing pressure across microbial formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified plant extracts from conventional microbial suspensions and generic biochemical alternatives. Price differentiation rests on EPA registration tier and fermentation scale, with cooperative procurement consolidation driving softness in standard-tier Bacillus products. Specialty crop growers in Florida exhibit lowest price sensitivity due to zero-residue export premiums, while Midwest grain cooperatives negotiate aggressively on volume.
Supply Chain Analysis
Regional distribution centers in California and Florida anchor hub-and-spoke patterns for temperature-sensitive microbial suspensions requiring cold-chain integrity. Manufacturing concentrates in the United States corn-soy belt, with secondary fermentation capacity in Mexico drawing from domestic agricultural feedstocks. Raw material dependencies include corn-derived substrates, specialized nitrogen sources, and sterile packaging materials. Single-source vulnerability around Bacillus thuringiensis strain libraries creates concentration risk. Distribution runs through direct manufacturer-to-cooperative channels in the Dakotas and Nebraska, supplemented by wholesale cold-chain logistics for northern tier states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from microbial fermentation scale economies achieving parity with synthetic chemical price points, enabling premium capture in organic transition segments.
For Market Incumbents: Anticipate EPA registration acceleration compressing competitive moats around novel microbial strains. Defensive moves should prioritize backward integration into domestic fermentation capacity in California and Florida to secure supply against feedstock volatility, while deepening technical service relationships with cooperative agronomists to lock in specification authority before generic biochemical alternatives proliferate.
For New Entrants and Emerging Players: EPA's streamlined Biopesticides and Pollution Prevention Division registration pathways in the United States open a window for specialized RNA interference delivery platforms. White-space targets include greenhouse export compliance in Mexican protected agriculture and seed treatment convergence in the Dakotas and Nebraska. Go-to-market positioning should emphasize zero-residue protocol certification for berry and tomato producers facing harmonized EPA-Health Canada tolerance standards.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play microbial fermentation specialists because cooperative procurement consolidation is compressing distributor margins and rewarding direct technical service capabilities. Long-term viability favors targets with EPA registration expertise and captive Bacillus strain libraries. Signal to monitor: Health Canada-EPA residue harmonization completion rates as inflection indicator for cross-border label expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Bacillus thuringiensis production insulates Certis Biologicals against corn-substrate price volatility in California. |
| Direct Technical Service Partnerships | Biological suppliers bypass distributors to secure specification authority with cooperative agronomists in Nebraska. |
| RNA Interference Platform Development | Species-specific pest suppression without off-target effects compresses addressable market for broad-spectrum synthetics in Central Valley. |
| Zero-Residue Certification Investment | Plant extract formulations command premium positioning in Mexican greenhouse berry exports to US markets. |
| Seed Treatment Convergence | Biological active integration with precision application equipment creates bundled service models in Dakotas corn belt. |
Research Methodology
Direct dialogue with EPA registration consultants, cooperative agronomists in the Dakotas and Nebraska, fermentation process engineers, and specialty crop growers in California's Central Valley grounded qualitative insights. Secondary validation drew from EPA Biopesticides and Pollution Prevention Division registration databases, Health Canada PMRA tolerance standards, COFEPRIS import authorization records, and USDA conservation program disclosures. Bottom-up volume estimates triangulated against top-down market sizing across microbial, biochemical, and plant extract formulation categories.
Bottom-up modeling aggregated county-level adoption rates for Bacillus-based rotations in Midwest row-crop systems with greenhouse operator surveys in Florida and Mexico. Segmentation dimensions included formulation chemistry, crop value intensity, and procurement channel concentration. CAGRs derived from regression analysis against EPA registration velocity, fermentation capacity expansion timelines, and organic acreage conversion trajectories. Industry-specific inputs incorporated temperature stability windows for northern tier applications and residue harmonization progress between NAFTA successor jurisdictions.
Revisions become necessary when EPA registration timelines extend beyond modeled assumptions, fermentation feedstock prices decouple from ethanol demand cycles, or Health Canada-EPA tolerance harmonization stalls. Forecasts reflect documented assumptions around cooperative procurement consolidation velocity and microbial formulation stability improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Canada Biofertilizers Market