
 Plant Based Biosurfactants Market | 2026-2036
Plant Based Biosurfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Biosurfactants Market Analytics
Multi-source fermentation feedstock procurement is pivoting as manufacturers reduce reliance on single-origin agricultural inputs. BASF SE leverages its integrated biotechnology platforms to secure consistent rhamnolipid yields across European facilities. Evonik Industries AG anchors its position through specialized sophorolipid production tailored to industrial cleaning applications. Unilever PLC competes by embedding biosurfactant formulations directly into its consumer product lines, bypassing merchant market exposure.
Plant based biosurfactants comprise microbially produced amphiphilic molecules, typically glycolipids or lipopeptides, derived from renewable carbohydrate and lipid feedstocks via controlled fermentation at pH ranges of 4.0 to 7.0 and temperatures between 25°C and 35°C. These compounds reduce surface tension to below 30 mN/m, enabling their primary function as petroleum-free emulsifiers, detergents, and dispersants across formulated products. Rhamnolipids dominate current commercial volumes due to established production protocols and broad pH stability, while sophorolipids capture expanding share in personal care where mildness and biodegradability command formulation priority. Trehalose lipids occupy niche positions in high-value pharmaceutical and food applications where thermal stability and low cytotoxicity justify premium positioning.
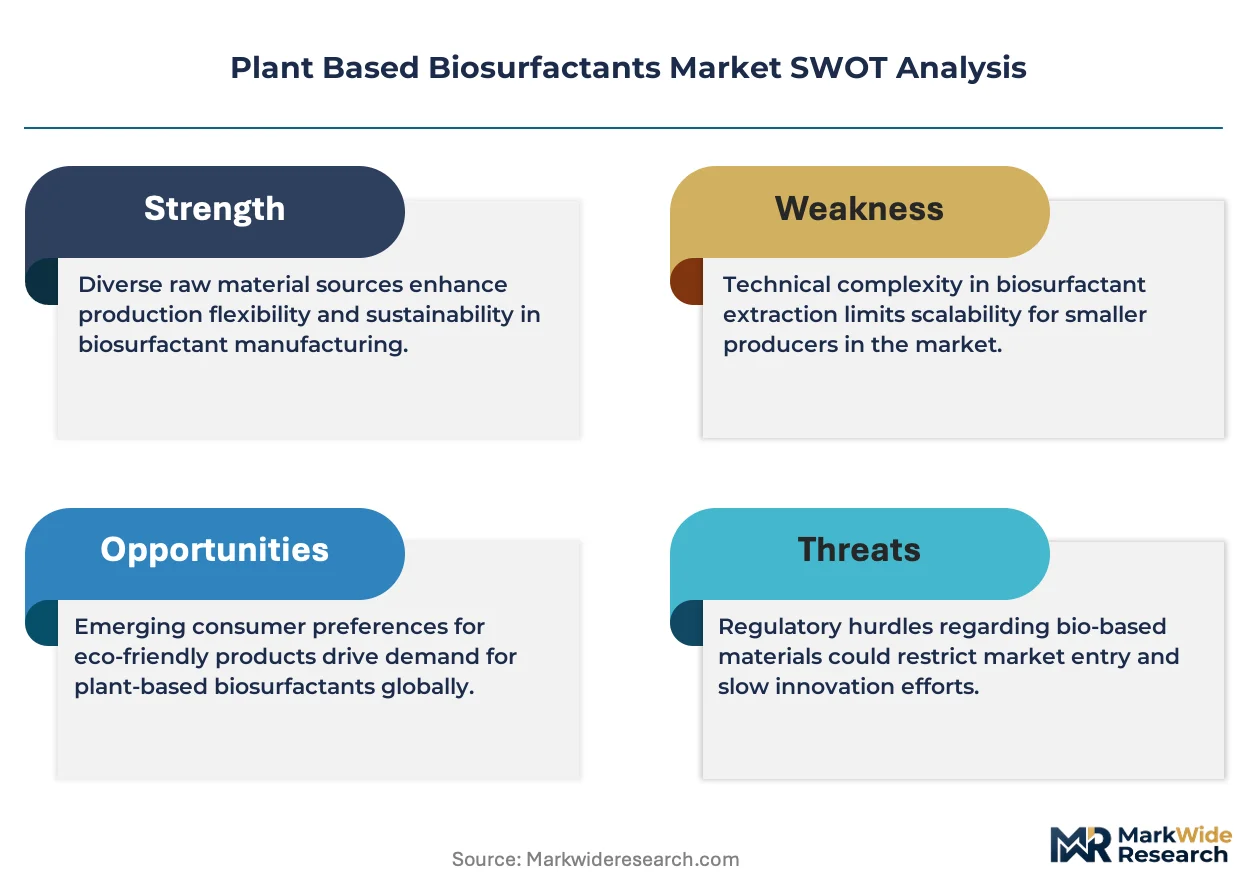
EMA guidelines on excipient biocompatibility, REACH Annex XVII restrictions on persistent organic pollutants, and EPA Safer Choice program criteria collectively elevate plant derived surfactants above petrochemical alternatives in regulatory compliance value. ECHA substance evaluation protocols now explicitly weight biodegradation kinetics in surfactant authorization decisions, directly channeling formulation investments toward fermentation-derived options. Stakeholders must monitor how EU Green Deal chemical sustainability targets and emerging state-level restrictions on per- and polyfluoroalkyl substances reshape competitive access across key consumer markets.
Market Dynamics
REACH Annex XVII restrictions on persistent organic pollutants are forcing personal care and industrial cleaning formulators to abandon petrochemical surfactants, redirecting procurement budgets toward fermentation-derived rhamnolipids and sophorolipids.
Growth Catalysts
- EPA Safer Choice program criteria:Federal procurement guidelines now explicitly favor biodegradable surfactants in institutional cleaning contracts, accelerating rhamnolipid adoption across US government facilities.
- Personal care formulators:Major cosmetic brands are embedding sophorolipids into premium skincare lines to satisfy consumer demand for petroleum-free emulsifiers with demonstrated mildness profiles.
- Fermentation infrastructure scaling:Brazil's sugarcane-derived feedstock advantages and established bioethanol processing clusters enable cost-competitive sophorolipid production for Latin American detergent manufacturers.
Market Restraints
- Feedstock cost volatility:Rapeseed oil and corn syrup price swings directly compress rhamnolipid production margins, particularly for European facilities dependent on Ukrainian agricultural inputs.
- Technical limitation:Current fermentation protocols struggle to achieve sophorolipid yields above 100 g/L without lactose supplementation, constraining unit economics against mature petrochemical alternatives.
- Substitution threat:Synthetic biology-derived surfactants from engineered yeast platforms threaten to undercut plant-based glycolipids on production consistency and tailored molecular structures.
Strategic Opportunities
- EU Green Deal chemical sustainability targets:Mandatory carbon footprint disclosures for formulated products create preferential market access for fermentation-derived surfactants with verified life-cycle assessments.
- Agricultural co-product valorization:Olive mill wastewater and citrus processing residues offer underexploited carbohydrate streams for trehalose lipid production in Mediterranean economies.
- Pharmaceutical excipient certification:EMA guidelines on excipient biocompatibility open premium positioning for low-cytotoxicity biosurfactants in parenteral drug delivery systems.
Industry Challenges
- Fermentation scale-up expertise gap:Industrial microbiologists with demonstrated commercial glycolipid production experience command premium compensation, constraining talent acquisition for mid-cap entrants.
- Downstream processing capex intensity:Membrane filtration and chromatographic purification systems for food-grade sophorolipid recovery require capital commitments that strain unproven market entrants.
- REACH registration timelines:Novel biosurfactant substances face 18-24 month authorization delays, freezing formulation integration until full toxicological dossiers receive ECHA approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Biosurfactants Market |
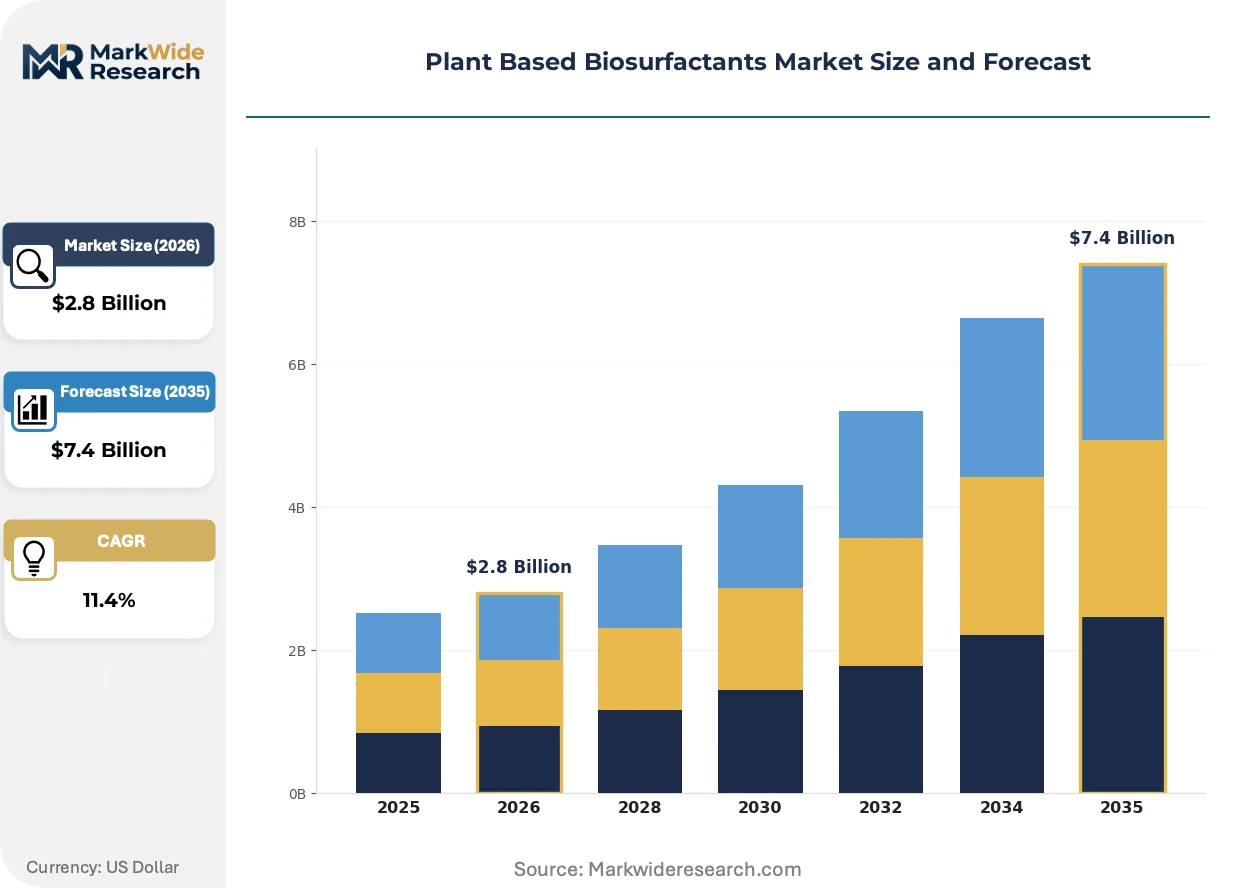
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhamnolipids, Sophorolipids, Mannosylerythritol Lipids, Trehalose Lipids Application: Personal Care, Cleaning Agents, Food Industry, Oil Recovery End User: Cosmetic Manufacturers, Food Processors, Oil Industry, Household Consumers Form: Liquid, Powder, Concentrate, Suspension |
| Companies Covered | BASF SE, Evonik Industries AG, Unilever PLC, Kraton Corporation, Clariant AG, Solvay SA, Procter & Gamble Co., Dow Inc., Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Biosurfactants Market Evolving Landscape
Continuous fermentation technology and modular bioreactor designs are compressing capital requirements for biosurfactant production, enabling distributed manufacturing models that challenge centralized petrochemical supply chains.
Cell-free enzymatic synthesis is decentralizing rhamnolipid production by eliminating the need for live Pseudomonas aeruginosa cultures and associated biosafety containment infrastructure. Specialty chemical distributors in Germany and the Netherlands are piloting containerized production units for on-demand glycolipid supply to regional formulators. This distributed architecture is compressing logistics costs and enabling just-in-time inventory models previously unavailable to biosurfactant buyers.
REACH authorization decisions now explicitly weight biodegradation kinetics in surfactant evaluations, creating regulatory friction for petrochemical alternatives with poor aquatic toxicity profiles. Industrial cleaning compound manufacturers face reformulation deadlines as ECHA substance evaluation protocols tighten persistent organic pollutant screening criteria. Personal care brands targeting European markets are accelerating sophorolipid integration to preempt compliance-driven supply disruptions.
Direct procurement relationships between personal care brands and fermentation specialists are displacing traditional surfactant distributors, compressing channel margins and demanding technical collaboration on formulation compatibility. Specialty chemical distributors in France and Italy report declining biosurfactant volumes as Unilever and similar integrated manufacturers internalize supply through captive fermentation partnerships. This channel consolidation is most visible in premium cosmetic segments where proprietary glycolipid variants confer formulation differentiation.
Plant Based Biosurfactants Market Segmentation
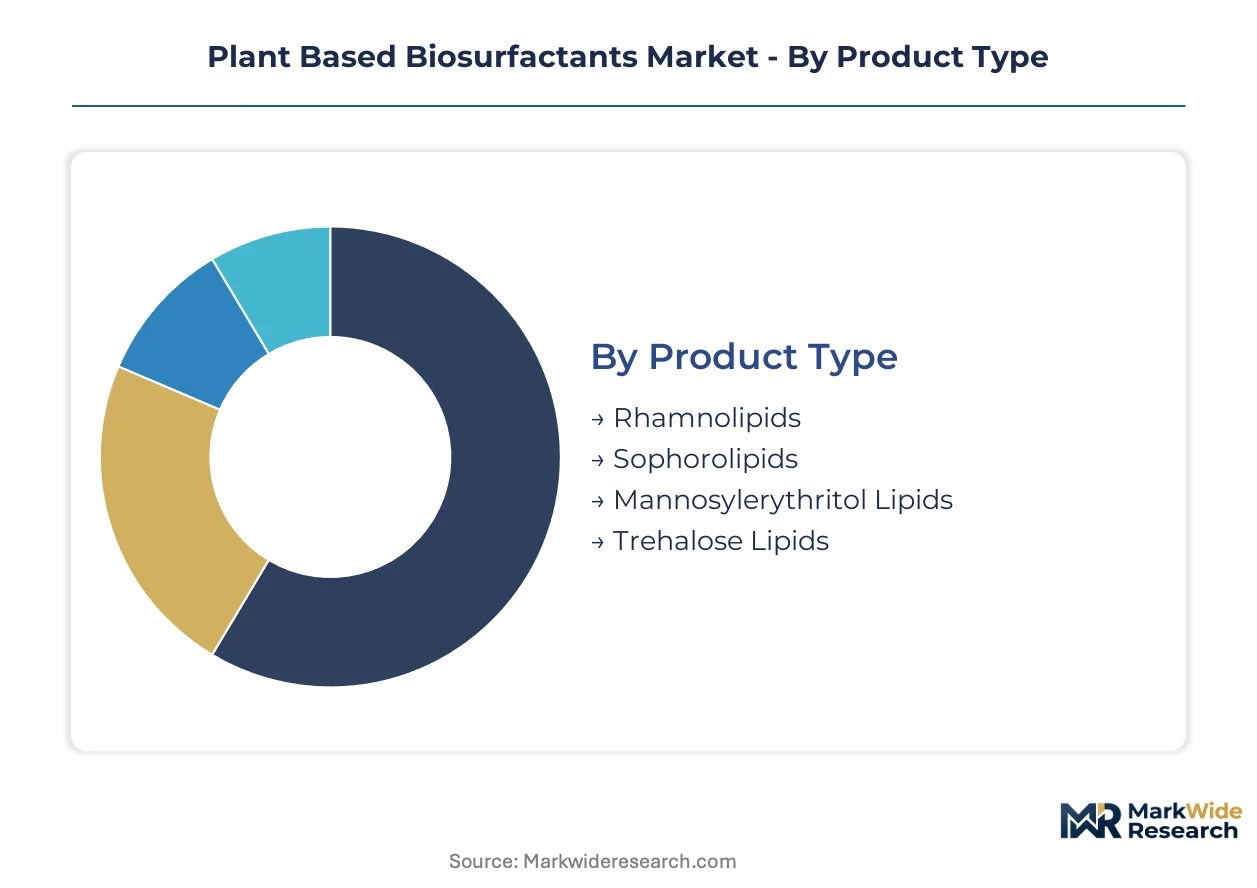
Segmentation in plant based biosurfactants reveals how technical specifications, application requirements, and supply chain configurations create distinct commercial battlegrounds. Manufacturers optimize fermentation protocols and downstream processing differently depending on whether glycolipids serve standalone industrial cleaners or embedded cosmetic formulations.
Product Type:
Integration depth varies sharply across glycolipid chemistries, with some variants functioning as drop-in surfactant replacements while others require complete formulation architecture redesigns.
- Rhamnolipids:These di-rhamnolipid and mono-rhamnolipid mixtures achieve surface tension reduction below 30 mN/m across broad pH and temperature ranges. Demand concentrates in industrial cleaning compounds and oil recovery fluids where established production protocols from German and Brazilian fermentation facilities ensure supply security.
- Sophorolipids:Lactonic and acidic forms derived from Candida bombicola fermentation demonstrate superior mildness profiles and biodegradability kinetics. Personal care formulators in France and Italy embed these into premium skincare emulsions to satisfy ECHA REACH Annex XVII compliance timelines.
- Mannosylerythritol Lipids:High-purity variants command pharmaceutical excipient positioning due to demonstrated low cytotoxicity in parenteral applications.
- Trehalose Lipids:Thermal stability above 80°C suits food-grade emulsification where process tolerance justifies premium procurement.
Volume placements concentrate in rhamnolipids; the faster expansion belongs to sophorolipids.
Application:
Cost tier differentiation separates commodity-scale industrial applications from specification-driven consumer segments with divergent margin structures.
- Personal Care:Premium cosmetic brands demand fermentation-derived sophorolipids and rhamnolipids with documented biodegradability certifications and excipient-grade purity. Formulation integration requires technical collaboration on emulsion stability and sensory profiles, creating stickier supplier relationships.
- Cleaning Agents:Institutional and household detergent manufacturers prioritize unit economics and supply reliability over molecular customization. EPA Safer Choice program criteria channel federal procurement toward verified biodegradable surfactants, accelerating rhamnolipid adoption in US government facility contracts.
- Food Industry:Trehalose lipids serve as emulsifiers in processed foods where thermal processing stability and regulatory clearance for direct food contact apply.
- Oil Recovery:Enhanced oil recovery operations deploy rhamnolipid formulations to reduce interfacial tension in reservoir conditions.
Revenue margins peak in personal care; steepest volume expansion trajectory runs through cleaning agents.
End User:
Customer type determines whether biosurfactant procurement flows through merchant market distributors or captive fermentation partnerships.
- Cosmetic Manufacturers:Integrated beauty conglomerates internalize sophorolipid supply through direct fermentation partnerships, bypassing traditional surfactant distributors. Technical collaboration on proprietary glycolipid variants creates formulation differentiation in premium skincare segments.
- Food Processors:Processed food manufacturers source trehalose lipids through specialized food ingredient distributors with documented supply chain traceability.
- Oil Industry:Petroleum operators procure rhamnolipid concentrates for enhanced recovery applications through industrial chemical distributors.
- Household Consumers:End-user demand manifests indirectly through retail product purchases, with biodegradability claims influencing brand selection.
Supply concentration sits with cosmetic manufacturers; food processors are gaining share fastest.
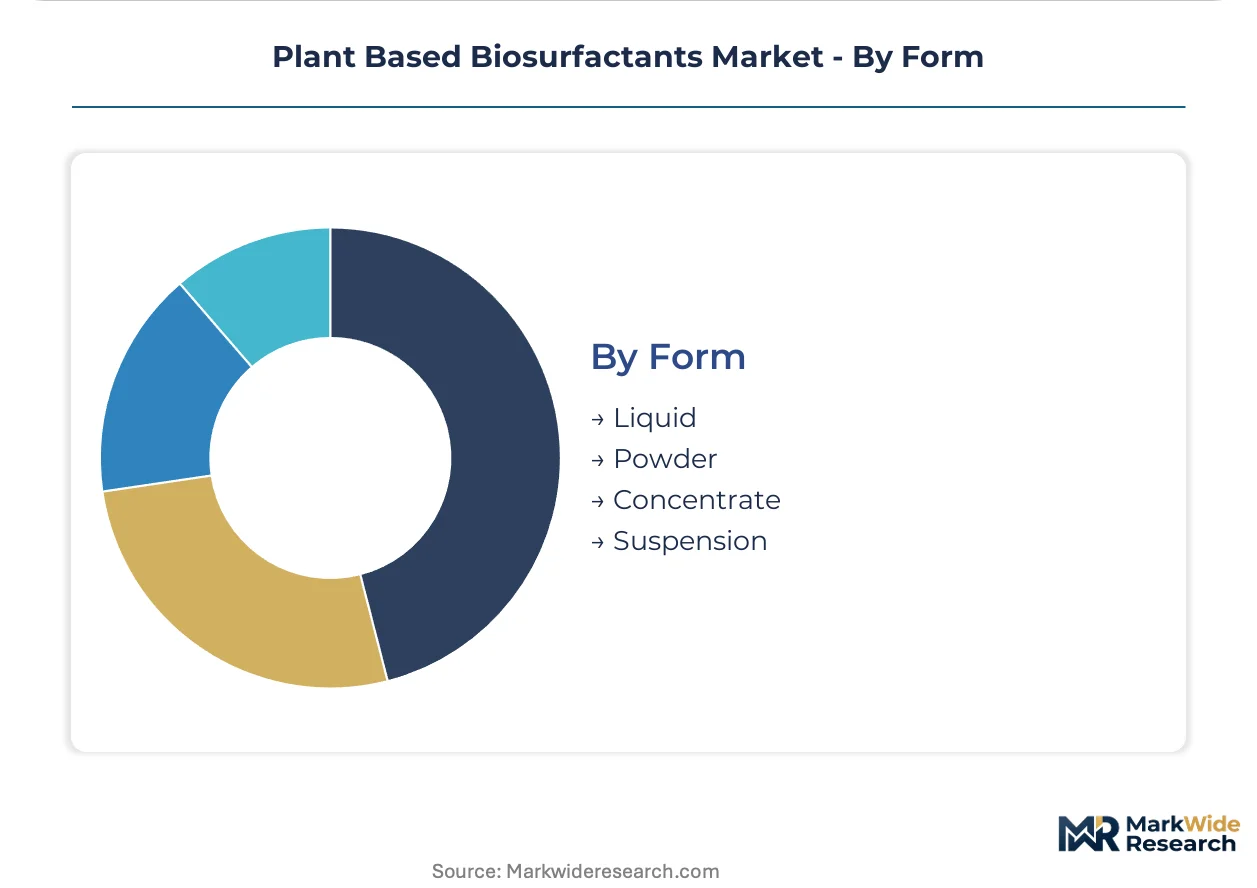
Form:
Supply chain configuration and logistics economics favor certain physical forms for specific application delivery modes.
- Liquid:Ready-to-dose aqueous solutions dominate industrial cleaning and oil recovery where bulk tanker delivery and automated dosing systems integrate seamlessly. Brazilian fermentation facilities ship liquid sophorolipid concentrates to Latin American detergent manufacturers via established bioethanol logistics corridors.
- Powder:Spray-dried formulations reduce shipping weights for personal care compounders in Germany and the Netherlands importing from distributed production units.
- Concentrate:High-active formulations enable just-in-time dilution at formulation facilities, compressing inventory carrying costs.
- Suspension:Stabilized dispersions address applications requiring controlled release or extended shelf stability.
Shipment volumes concentrate in liquid form; powder formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane cultivation belts in Brazil's São Paulo state anchor the largest fermentation feedstock reserves for sophorolipid production. German chemical clusters leverage established bioreactor infrastructure to dominate rhamnolipid output. Indian oleochemical processors are repurposing palm fatty acid distillates for glycolipid fermentation trials.
Germany
REACH Annex XVII enforcement drives personal care formulators toward rhamnolipid substitutes for restricted petrochemical surfactants. ECHA substance evaluation protocols now mandate biodegradation kinetic documentation for new surfactant registrations. The Rhine-Ruhr chemical corridor hosts BASF SE's integrated biotechnology platforms producing consistent glycolipid yields for European cosmetic manufacturers.
United States
EPA Safer Choice program criteria channel federal procurement contracts toward verified biodegradable surfactants for institutional cleaning. Corn syrup price volatility from Midwest agricultural belts directly compresses rhamnolipid production margins for domestic fermentation facilities. Houston-area petrochemical complexes are retrofitting idle bioethanol tanks for sophorolipid concentrate storage and distribution.
Brazil
Sugarcane-derived carbohydrate streams enable cost-competitive sophorolipid production for Latin American detergent manufacturers. ANVISA's evolving cosmetic ingredient guidelines align with EU biodegradability standards, easing export pathway construction. São Paulo state's established bioethanol processing clusters provide ready fermentation infrastructure for glycolipid capacity scaling.
India
Palm oil refining residues from Kerala and Gujarat offer underexploited lipid feedstocks for trehalose lipid fermentation trials. CDSCO's draft excipient biocompatibility guidelines create regulatory runway for pharmaceutical-grade biosurfactant positioning. Maharashtra's Mumbai-Pune industrial belt hosts pilot-scale bioreactor installations serving domestic personal care compounders.
France
Olive mill wastewater from Provence-Alpes-Côte d'Azur agriculture provides carbohydrate-rich streams for specialty glycolipid fermentation. ANSM's cosmetic surveillance protocols increasingly scrutinize petrochemical surfactant persistence in aquatic environments. Lyon-based chemical distributors are consolidating biosurfactant procurement relationships to bypass traditional merchant market channels.
Plant Based Biosurfactants Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation infrastructure scales across established chemical clusters. The vendor base organizes around three strategic tiers: integrated multinational chemical conglomerates with captive biotechnology platforms, mid-cap fermentation specialists serving merchant markets, and consumer goods manufacturers internalizing supply through backward integration. Two competitive moves define current positioning: strategic partnerships between feedstock suppliers and fermentation operators, and geographic expansion of modular bioreactor installations to compress logistics costs.
Within the integrated chemical conglomerate tier, BASF SE, Evonik Industries AG, and Solvay SA exemplify archetypes leveraging established European fermentation infrastructure to secure consistent glycolipid yields. These Germany-based and Belgium-based entities occupy positions where biotechnology platforms intersect with formulated product distribution networks, representing the scale-driven end of competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Unilever PLC |
| Kraton Corporation |
| Clariant AG |
| Solvay SA |
| Procter & Gamble Co. |
| Dow Inc. |
| Croda International |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII biodegradability mandates gate qualified supply access and premium-tier pricing power for fermentation-derived surfactants. ECHA substance evaluation protocols now require documented kinetic data for surfactant registrations, compressing merchant market volumes toward certified suppliers and stratifying pricing across compliance tiers.
Pricing Analysis
Service bundling separates technical formulation support from commodity concentrate supply, with Unilever and similar integrated manufacturers absorbing in-house expertise costs while merchant buyers pay premiums for application guidance. Three-tier pricing structure across excipient-grade, industrial-grade, and feedstock-grade rhamnolipids reflects certification investment and purity variance. Pricing pressure stems from corn syrup and rapeseed oil feedstock volatility, particularly for European facilities drawing from Ukrainian agricultural belts. Household detergent manufacturers exhibit highest price sensitivity, while pharmaceutical compounders accept premiums for EMA-documented biocompatibility.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Ruhr corridor and São Paulo's bioethanol clusters anchor hub-and-spoke patterns for liquid concentrate delivery. Fermentation capacity concentrates in Germany, Brazil, and the United States, with downstream processing drawing from membrane filtration equipment suppliers in the Netherlands and chromatography resin providers in Switzerland. Supply chain risk centers on single-source dependency for lactose supplementation in high-yield sophorolipid protocols. Distribution runs through specialty chemical distributors in France and Italy, though direct procurement relationships are displacing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH registration timelines and fermentation scale-up capital requirements force sub-scale operators toward exit or acquisition.
For Market Incumbents: Deploy captive biotechnology platforms to secure rhamnolipid yield consistency against synthetic biology substitutes from engineered yeast competitors. BASF SE and Evonik Industries AG should expand modular bioreactor installations in Brazil's sugarcane belt to compress logistics costs for Latin American detergent manufacturers. Backward integration into olive mill wastewater and citrus processing residue streams in Mediterranean economies defends feedstock cost position against agricultural commodity volatility. For New Entrants and Emerging Players: EPA Safer Choice program criteria in the United States open a window for institutional cleaning concentrate suppliers without legacy petrochemical surfactant exposure. Trehalose lipid production for pharmaceutical excipient applications offers the most penetrable white-space, given EMA guidelines on parenteral drug delivery biocompatibility and limited incumbent specialization. Go-to-market execution should target direct procurement relationships with mid-cap cosmetic manufacturers bypassing distributor markups. For Investors and Strategic Acquirers: CDSCO draft excipient guidelines publication in India is the leading indicator that pharmaceutical-grade biosurfactant demand will inflect toward verified suppliers. Mid-cap fermentation specialists with demonstrated commercial glycolipid production and existing ECHA registration dossiers represent prime acquisition targets over the coming decade. Watch for ANVISA cosmetic ingredient guideline alignment with EU standards as the signal for Brazilian export pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Brazilian sugarcane belt installations leverage established bioethanol infrastructure for sophorolipid cost positioning. |
| Backward Integration | Olive mill wastewater capture in Provence-Alpes-Côte d'Azur reduces carbohydrate feedstock cost volatility for trehalose lipids. |
| Green Manufacturing Transition | Continuous fermentation technology adoption compresses capital requirements and enables distributed production models. |
| Long-term Supply Agreement | Direct procurement relationships with Unilever and similar consumer goods manufacturers displace distributor channel margins. |
| Joint Venture | Feedstock supplier partnerships with Ukrainian agricultural input providers hedge rapeseed oil price exposure for European facilities. |
Research Methodology
Multi-period observation of fermentation yield improvements, REACH registration timelines, and feedstock price indices anchored the trend analysis, supplemented by interviews with fermentation plant managers, personal care formulation chemists, specialty chemical distribution channel partners, and ECHA regulatory affairs consultants. Secondary validation drew from ECHA substance evaluation protocols, EPA Safer Choice program criteria documentation, ANVISA cosmetic ingredient guidelines, customs trade data for glycolipid concentrate shipments, and SEC filings from integrated chemical conglomerates. Bottom-up capacity estimates from identified fermentation facilities triangulated against top-down demand projections from end-use application segments.
Segment-weighting approaches distributed value and volume across rhamnolipid, sophorolipid, mannosylerythritol lipid, and trehalose lipid chemistries, further disaggregated by personal care, cleaning agents, food industry, and oil recovery applications. CAGRs were derived from regression analysis of historical production capacity scaling against regulatory compliance timeline acceleration across the projection horizon. Forecast inputs incorporated EMA excipient biocompatibility guideline evolution and EU Green Deal chemical sustainability target implementation schedules.
The model assumes a particular technology adoption path favoring live culture fermentation over cell-free enzymatic synthesis; alternative pathways for Pseudomonas aeruginosa-free rhamnolipid production would alter the outlook for biosafety containment capital requirements. Forecasts reflect stated assumptions regarding REACH authorization timeline durations and feedstock price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Silage Inoculant and Enzyme Market