
 Spain Biopesticides Market | 2026-2036
Spain Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Biopesticides Market Analytics
EU Green Deal is rebalancing the cost-of-entry calculus for biopesticide registration and residue compliance across Spanish agriculture. BASF SE leverages its microbial formulation pipeline to anchor supply relationships with large agricultural cooperatives in Extremadura. Bayer AG competes through specialized distribution networks that reach smaller vineyard operators in La Rioja and Ribera del Duero. Syngenta sustains R&D intensity in bacterial biopesticide strains tailored to Mediterranean pest pressures.
Biopesticides comprise living organisms or naturally derived substances that suppress agricultural pests through biological mechanisms rather than synthetic chemistry, typically formulated as liquid suspensions or wettable powders containing specified colony-forming units per gram. These products serve commercial agriculture by targeting specific pest species while preserving beneficial insect populations and meeting stringent residue thresholds for export crops. Microbial formulations lead volume demand among Spanish growers due to established efficacy against olive fly and grape moth, while plant extract segments capture premium positioning in organic certification channels. Liquid formulations dominate application logistics for mechanized vineyard spraying, though granular formats gain traction in orchard floor management where drift control matters.
Spain's Ministry of Agriculture, Fisheries and Food enforces EU Green Deal targets through national integrated pest management mandates that reduce chemical active ingredient allowances per hectare. EFSA residue standards shape export viability for Spanish citrus and stone fruit destined for Northern European retail chains. The EU AI Act introduces emerging compliance layers for precision agriculture platforms that pair biopesticide deployment with drone-based monitoring systems. Stakeholders must monitor how rapidly Spanish regional governments translate Brussels sustainability targets into enforceable farm-level obligations.
Market Dynamics
Spain's biopesticide sector is being fundamentally restructured by the EU Green Deal's Farm to Fork Strategy, which mandates a 50% reduction in chemical pesticide use and is forcing olive and vineyard operators to rebuild their pest management protocols around biological alternatives.
Growth Catalysts
- EFSA residue thresholds:Northern European retail chains now reject Spanish citrus and stone fruit exceeding strict chemical residue limits, pushing growers toward microbial formulations that register zero synthetic traces.
- Andalusian olive cooperatives:Large agricultural collectives in Jaén and Córdoba are consolidating procurement power to negotiate volume contracts for Bacillus thuringiensis-based products targeting olive fly infestations.
- Precision fermentation:Advances in controlled bioreactor production are lowering per-unit costs for entomopathogenic fungi, making these formulations cost-competitive with conventional pyrethroids in mechanized vineyard spraying.
Market Restraints
- Active ingredient supply concentration:Spanish formulators depend on imported microbial mother cultures from Danish and Dutch biotech suppliers, creating vulnerability to cross-border logistics disruptions.
- Registration timeline friction:Spain's Ministry of Agriculture, Fisheries and Food applies EFSA's 3-year efficacy evaluation period uniformly, delaying market entry for novel bacterial strains even when data packages are complete.
- Shelf-stability limitations:Liquid suspensions of live organisms require cold-chain distribution through Castilla-La Mancha's summer heat, raising spoilage rates versus synthetic chemical alternatives.
Strategic Opportunities
- Extremadura almond expansion:New irrigated orchards in Badajoz province lack established pest resistance profiles, creating first-mover advantage for biopesticide suppliers who embed with early planting cycles.
- Drone-based spot application:Convergence of UAV platforms with hyperspectral pest detection allows vineyard operators in La Rioja to deploy pheromone disruptors with meter-scale precision, reducing waste.
- EU AI Act compliance services:Precision agriculture platforms pairing biopesticide deployment with automated monitoring systems require algorithmic transparency documentation, opening advisory revenue streams for agritech intermediaries.
Industry Challenges
- Formulation chemist scarcity:Spanish universities produce fewer than 40 graduates annually with dual training in microbiology and agricultural application engineering, constraining R&D pipeline velocity for domestic startups.
- Integrated Pest Management certification complexity:Growers seeking official IPM status must document three consecutive seasons of reduced chemical use before biopesticide costs become subsidy-eligible, stretching cash flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Biopesticides Market |
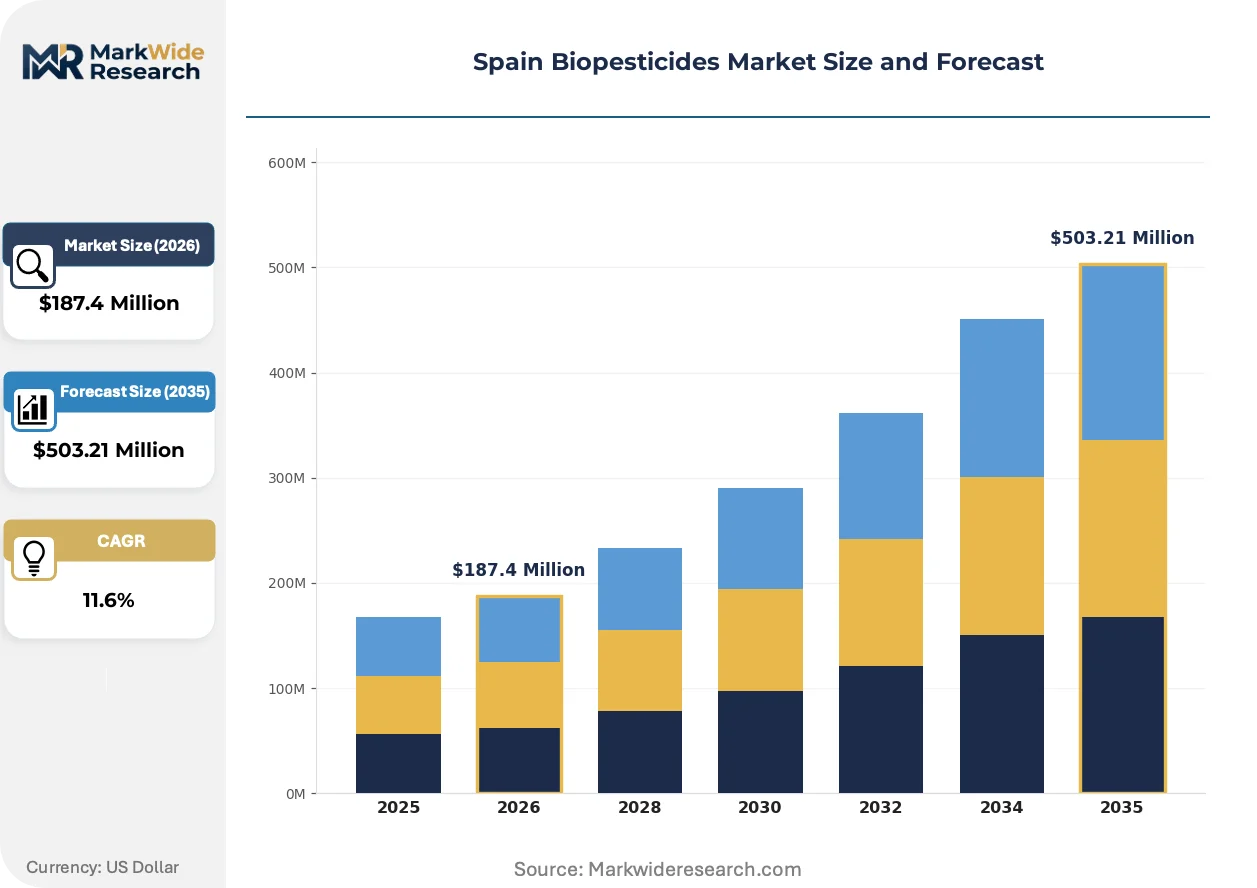
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Plant Extracts, Microbial Application: Agricultural Crops, Horticulture, Specialty Crops, Turf Management End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Formulation: Liquid, Granular, Powder, Concentrate |
| Companies Covered | BASF SE, Bayer AG, Syngenta, Koppert Biological Systems, Corteva Agriscience, Lallemand Plant Care, Valent Biosciences, Gowan Company, Agrauxine SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Biopesticides Market Evolving Landscape
Biological pest suppression is displacing synthetic chemistry through formulation advances, regulatory compression of chemical allowances, and buyer-side consolidation among export-oriented agricultural cooperatives.
RNA interference technology is overtaking conventional microbial sprays as the precision tool for grape moth management in Ribera del Duero. Vineyard operators with organic certification mandates are adopting double-stranded RNA formulations at twice the rate of conventional growers. This shift is compressing demand for broad-spectrum Bacillus products while opening premium pricing tiers for sequence-specific solutions.
Spain's Ministry of Agriculture is enforcing EU Green Deal targets through hectare-based caps on chemical active ingredient volumes, with penalties tied to CAP subsidy eligibility. Olive growers in Andalusia now face automatic deduction of 15% from direct payments if annual chemical use exceeds baseline averages. Cooperatives are responding by pooling biopesticide procurement to meet volume thresholds for manufacturer rebates.
Buyer consolidation among La Rioja wine export cooperatives is displacing fragmented individual vineyard purchasing. Large cooperatives with 500-plus hectare memberships now negotiate direct supply agreements with formulation companies, bypassing traditional agricultural distributor networks. This concentration is most visible in premium denomination of origin zones where residue documentation requirements are strictest.
Spain Biopesticides Market Segmentation
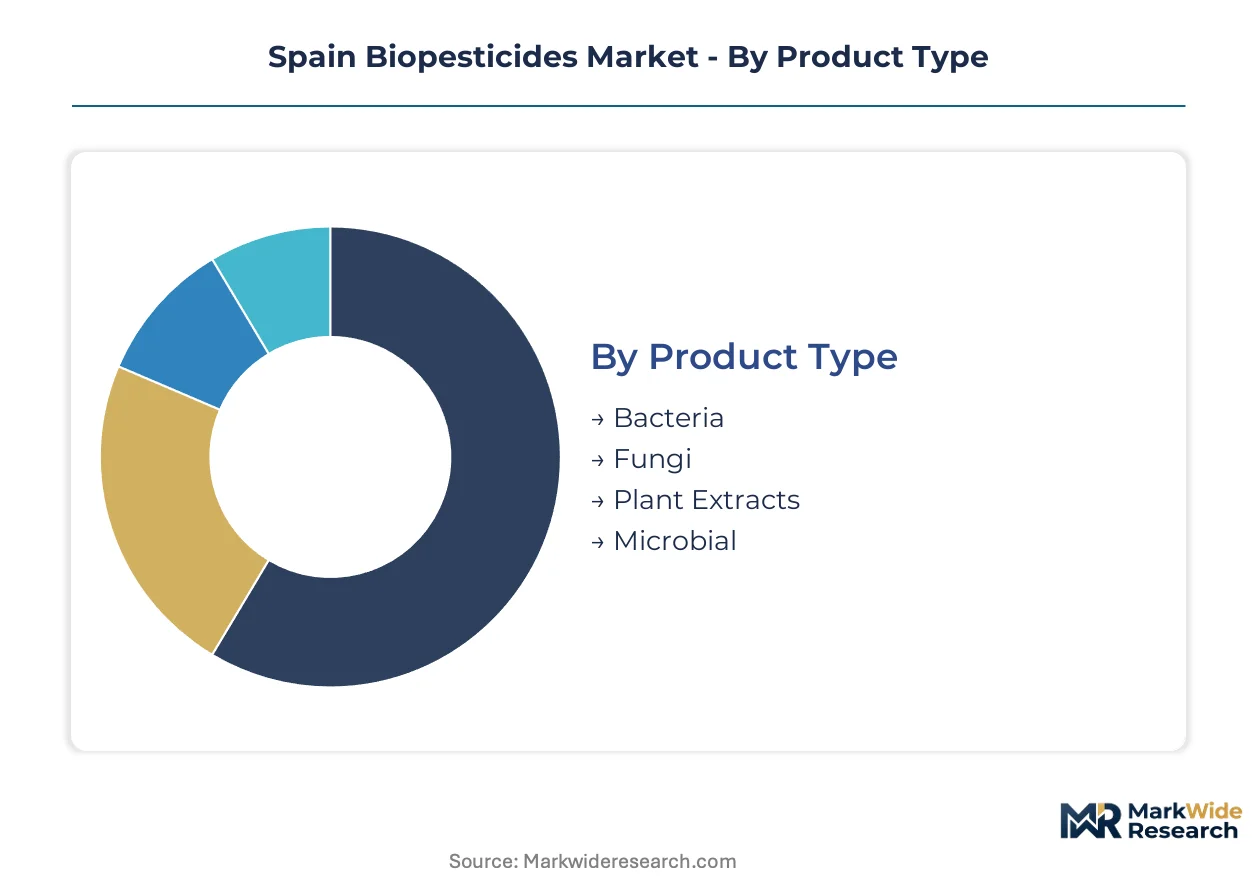
Segmentation in Spain's biopesticide market reflects how growers rebuild pest management protocols around biological alternatives. Product type and formulation choices determine efficacy against Mediterranean pest pressures, while application and end-user patterns reveal where procurement power is concentrating.
Product Type:
Upgrade cycles in Spanish agriculture favor microbial solutions that replace synthetic chemistry without disrupting established spray schedules.
- Microbial:Formulations containing specified colony-forming units of live organisms dominate procurement from large Andalusian olive cooperatives. Demand concentrates in Bacillus-based products targeting olive fly infestations across Jaén and Córdoba provinces, where EFSA residue thresholds have eliminated pyrethroid alternatives for export-bound fruit.
- Bacteria:Bacillus thuringiensis strains lead volume consumption in vineyard applications across La Rioja and Ribera del Duero. Spanish growers prioritize these formulations for grape moth management where organic certification requirements command premium pricing tiers in Northern European retail channels.
- Fungi:Entomopathogenic formulations from Metarhizium and Beauveria species serve specialty crop producers in Extremadura's expanding almond orchards.
- Plant Extracts:Pyrethrin and azadirachtin-based products capture organic certification premiums in horticultural zones around Almería.
Volume placements concentrate in Microbial formulations; the faster expansion belongs to Bacteria as RNA-interference alternatives compress broad-spectrum demand.
Application:
Cost tier differentiation separates commodity grain applications from premium residue-sensitive export crops.
- Agricultural Crops:Olive and vineyard operations across Andalusia and Castilla-La Mancha drive baseline demand, with cooperatives pooling procurement to meet manufacturer volume rebates. EFSA residue enforcement has made microbial formulations the default choice for citrus and stone fruit destined for German and Dutch supermarket chains.
- Specialty Crops:Almond and pistachio growers in Badajoz province represent emerging demand as new irrigated orchards lack established pest resistance profiles. First-mover biopesticide suppliers embedding with early planting cycles capture multi-season supply relationships before chemical protocols harden.
- Horticulture:Greenhouse vegetable producers in Murcia integrate microbial sprays into integrated pest management rotations for whitefly and thrips control.
- Turf Management:Golf course and sports field maintenance in Mediterranean coastal zones adopts fungal formulations for grub suppression.
Revenue concentrates in Agricultural Crops; Specialty Crops are gaining share fastest as Extremadura irrigation expansion outpaces mature vineyard markets.
End User:
Customer type determines whether procurement flows through consolidated cooperative channels or fragmented individual purchasing.
- Agricultural Cooperatives:Large collectives with 500-plus hectare memberships in La Rioja now negotiate direct supply agreements with formulation companies, bypassing traditional distributor networks. These entities consolidate demand documentation for EU Green Deal compliance subsidies while extracting manufacturer rebates unavailable to smaller operators.
- Farmers:Individual vineyard and olive operators below cooperative scale rely on regional distributor inventories with higher per-unit pricing. Cash flow constraints from three-season IPM certification requirements stretch adoption timelines for this segment.
- Distributors:Regional agricultural supply houses maintain cold-chain infrastructure for liquid microbial formulations across Castilla-La Mancha's summer heat.
- Retailers:Farm supply stores serve hobby and smallholder segments with packaged consumer formats.
Procurement volume concentrates in Agricultural Cooperatives; Farmers represent the steepest expansion trajectory as IPM subsidy eligibility expands.
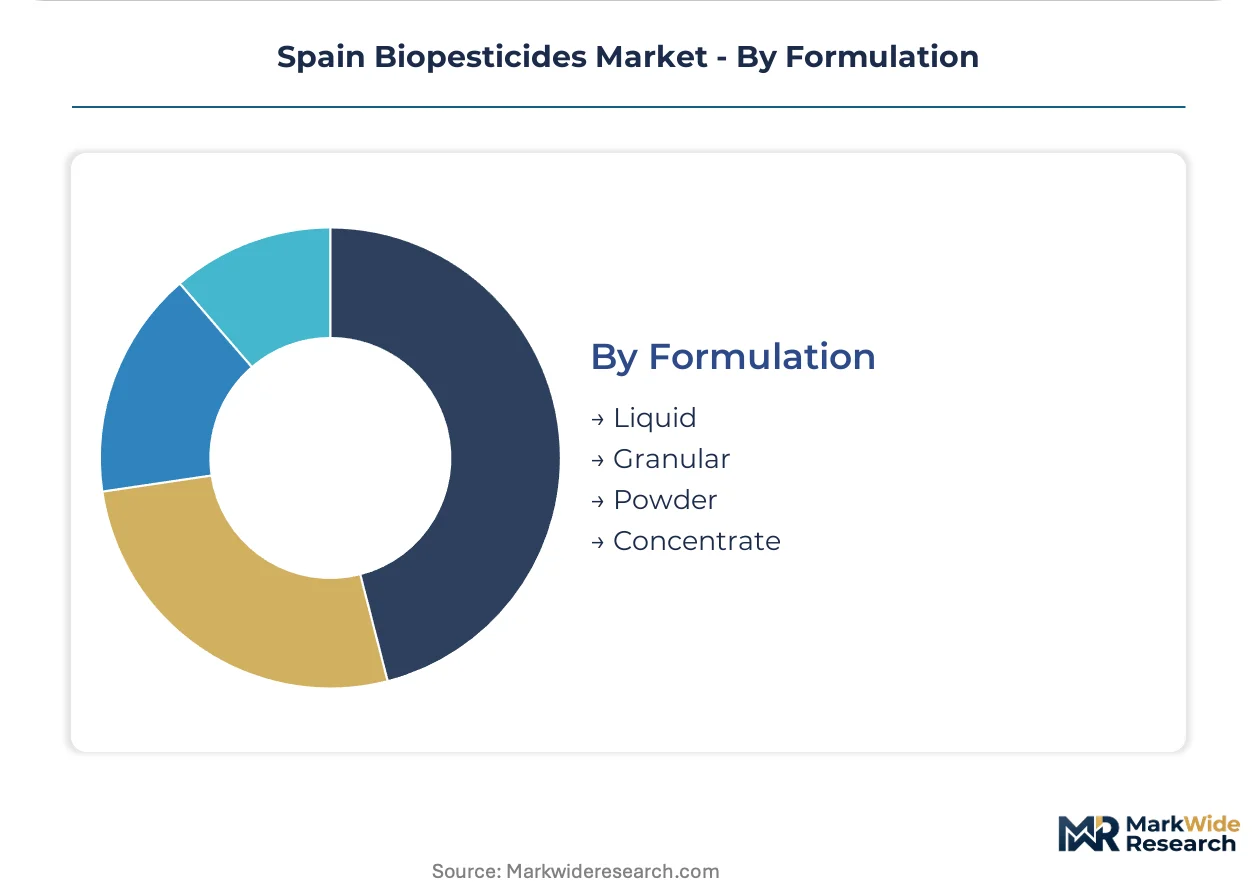
Formulation:
Application logistics and shelf-stability requirements create distinct supply chain configurations for each physical format.
- Liquid:Suspensions of live organisms dominate mechanized vineyard spraying in La Rioja and Ribera del Duero. Cold-chain distribution requirements through Castilla-La Mancha's summer heat raise spoilage rates, concentrating supply relationships with logistics-capable manufacturers.
- Granular:Orchard floor applications in Andalusian olive groves gain traction where drift control matters and beneficial insect preservation is critical. This format bypasses aerial application restrictions near populated areas.
- Powder:Wettable powders serve smaller operators with limited spray tank agitation capacity in Extremadura's emerging almond zones.
- Concentrate:High-potency dilutable formulations reduce transport costs for export-oriented cooperatives with on-farm mixing infrastructure.
Volume placements concentrate in Liquid formulations; Granular formats are climbing the fastest as drift regulation tightens near Mediterranean population centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zona Franca de Vigo and other special-economic zones in Galicia concentrate biopesticide formulation activity through tax-advantaged manufacturing infrastructure serving Atlantic export corridors.
Andalusia
Olive cooperatives in Jaén and Córdoba drive microbial biopesticide procurement for olive fly management. EFSA residue thresholds eliminate pyrethroid alternatives for export-bound fruit. Large agricultural collectives pool demand to negotiate volume contracts with Bacillus thuringiensis suppliers.
Castilla-La Mancha
Vineyard operators across La Mancha integrate bacterial formulations into mechanized spraying schedules for grape moth suppression. Spain's Ministry of Agriculture enforces hectare-based caps on chemical active ingredient volumes through CAP subsidy conditionality. Cold-chain distribution networks struggle with summer heat spoilage rates for liquid microbial suspensions.
Extremadura
New irrigated almond orchards in Badajoz province lack established pest resistance profiles, creating first-mover opportunities for entomopathogenic fungi suppliers. EU Green Deal Farm to Fork targets accelerate grower transitions before chemical protocols harden. Early planting cycles embed multi-season supply relationships with biopesticide formulators.
La Rioja
Premium denomination of origin wine cooperatives consolidate procurement power through 500-plus hectare memberships. Large collectives negotiate direct supply agreements with formulation companies, bypassing traditional agricultural distributor networks. Drone-based spot application with hyperspectral pest detection enables meter-scale precision deployment of pheromone disruptors.
Catalonia
Precision agriculture platforms in Lleida and Tarragona integrate biopesticide deployment with automated monitoring systems. EU AI Act compliance requirements create advisory revenue streams for agritech intermediaries documenting algorithmic transparency. Barcelona-based biotechnology clusters advance RNA interference research for sequence-specific pest suppression.
Spain Biopesticides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's biopesticide procurement channels. The market structure tiers between multinational agrochemical majors with microbial formulation pipelines and regional biotechnology firms with localized distribution relationships. Three archetypes dominate: integrated life-science conglomerates leveraging existing agricultural cooperative networks, specialized microbial suppliers with cold-chain logistics capabilities, and precision-biotechnology developers advancing RNA-interference platforms. Competitive moves concentrate on strategic partnerships with large agricultural cooperatives and technology licensing arrangements for novel bacterial strains.
Among the integrated life-science tier, BASF SE and Bayer AG anchor supply relationships through contrasting channel strategies. BASF SE leverages its microbial formulation pipeline to secure volume contracts with Extremadura agricultural cooperatives. Bayer AG competes through specialized distribution networks reaching smaller vineyard operators in La Rioja and Ribera del Duero. Syngenta occupies a position within the R&D-intensive segment, sustaining bacterial biopesticide strain development tailored to Mediterranean pest pressures.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta |
| Koppert Biological Systems |
| Corteva Agriscience |
| Lallemand Plant Care |
| Valent Biosciences |
| Gowan Company |
| Agrauxine SA |
| Others |
Value Network & Pricing Analysis
Bacillus thuringiensis mother culture import costs from Danish and Dutch biotech suppliers cascade through Spanish formulator pricing tiers, concentrating margin pressure on smaller operators while large Andalusian olive cooperatives extract volume rebates that compress per-unit differentials by certification grade.
Pricing Analysis
Short lead-time premiums for cold-chain liquid microbial suspensions command pricing separation from spot inventory of granular formats with extended shelf stability. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification tier and cooperative membership scale, with IPM-certified growers accessing subsidy-offset rates unavailable to conventional operators. Pricing pressure stems from EFSA residue enforcement accelerating grower conversion before registration timelines stabilize supply. Individual farmers below cooperative thresholds exhibit highest price sensitivity due to three-season certification cash flow constraints.
Supply Chain Analysis
Dual-sourcing mandates from large La Rioja wine cooperatives require qualification of at least two microbial formulation suppliers to mitigate single-source vulnerability during cross-border logistics disruptions. Spanish formulators draw from concentrated mother culture supply in Denmark, the Netherlands, and Germany, with fermentation capacity expansion in Portugal emerging as secondary sourcing. Raw material dependencies center on specific Bacillus strains, entomopathogenic fungi spores, and plant extract feedstocks from azadirachtin suppliers. Tariff exposure on Danish biotechnology imports creates structural risk. Distribution runs through regional agricultural supply houses with cold-chain infrastructure across Castilla-La Mancha's summer heat zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's biopesticide market operates as a cost-of-compliance arena where EU Green Deal Farm to Fork mandates erect regulatory moats favoring incumbents with established EFSA registration dossiers and cooperative network access.
For Market Incumbents: Acquire cold-chain logistics assets in Extremadura to anchor supply relationships with expanding almond cooperatives before chemical protocols harden. Consolidate formulation chemist talent through targeted recruitment from Spanish universities producing fewer than 40 dual-trained graduates annually. Defend against RNA interference substitution by embedding bacterial biopesticide portfolios into multi-season IPM certification workflows that stretch competitor entry timelines.
For New Entrants and Emerging Players: Begin with drone-based spot application services in La Rioja premium denomination zones where hyperspectral pest detection convergence creates advisory revenue streams outside manufacturing capital intensity. Target Extremadura's new irrigated orchards in Badajoz province for first-mover entomopathogenic fungi embedding before resistance profiles stabilize. Pursue EU AI Act compliance documentation as the go-to-market wedge, positioning algorithmic transparency services as the entry path to biopesticide deployment partnerships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized microbial suppliers with captive cold-chain infrastructure in Castilla-La Mancha during periods of logistics cost volatility. Long-term viability centers on acquisition targets with established Bacillus strain libraries and direct cooperative supply agreements bypassing distributor networks. Monitor EFSA registration timeline compression as the inflection signal—accelerated evaluation periods for novel bacterial strains would shift competitive advantage toward R&D-intensive developers over formulation distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mother Culture Production | Captive supply of Bacillus strains insulates Spanish formulators from Danish biotech supplier concentration risk. |
| Cold-Chain Infrastructure Expansion | Regional distribution hubs in Castilla-La Mancha reduce spoilage rates for liquid microbial suspensions during summer heat peaks. |
| RNA Interference Platform Licensing | Sequence-specific pest suppression technology captures premium pricing tiers in Ribera del Duero organic certification channels. |
| Cooperative Direct Supply Agreements | Bypassing agricultural distributor networks extracts manufacturer rebates from 500-plus hectare La Rioja wine collectives. |
| EU AI Act Compliance Service Development | Algorithmic transparency documentation for precision agriculture platforms opens recurring advisory revenue streams in Catalonia. |
Research Methodology
Independent corroboration across formulation company technical directors, agricultural cooperative procurement managers, and regional distributor operations heads underwrites the qualitative findings in this study. Primary fieldwork with Spanish Ministry of Agriculture enforcement officers, EFSA regulatory affairs specialists, and university microbiology department chairs combined with secondary validation from EU Green Deal implementation reports, EFSA residue threshold databases, and CAP subsidy conditionality documentation. Bottom-up demand modeling from cooperative procurement volumes triangulated against top-down market sizing from customs trade data on microbial culture imports.
Comparable-period anchoring to historical biopesticide adoption curves in Mediterranean agriculture established the forecast window baseline. The analytical framework segments by microbial formulation type, application crop category, end-user procurement channel, and physical formulation format across the projection horizon. CAGRs derive from segment-level growth trajectory analysis incorporating EFSA enforcement intensity gradients, cooperative consolidation rates, and precision agriculture platform penetration. Industry-specific forecast inputs include olive fly infestation pressure indices and vineyard organic certification conversion timelines.
Underlying measurement precision varies by segment; microbial formulation volumes carry tighter precision than plant extract premiums due to standardized colony-forming unit reporting. Forecasts reflect assumptions on EU Green Deal implementation pace, CAP subsidy eligibility expansion, and cold-chain infrastructure investment flows. Deviation in EFSA registration timeline compression or Danish biotech supplier export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Biological Seed Treatment Market