
 Aquatic Animal Vaccines Market | 2026-2036
Aquatic Animal Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Aquatic Animal Vaccines Market Insights
The EU Green Deal's sustainable aquaculture provisions is consolidating procurement standards across European seafood supply chains. Zoetis Inc. leverages its recombinant platform expertise to anchor positions in bacterial and viral vaccine portfolios for farmed salmon. Merck Animal Health competes through integrated health programs that combine diagnostics with preventive vaccination protocols. Benchmark Holdings specializes in autogenous vaccine services, allowing rapid pathogen-specific responses for regional outbreaks.
Aquatic animal vaccines comprise immunological preparations designed to induce protective immunity in finfish, crustaceans, and mollusks against specific bacterial, viral, or parasitic pathogens, typically formulated as inactivated, attenuated, or subunit compositions administered via injection, oral, or immersion routes. These products function primarily to reduce mortality losses, limit antibiotic dependence, and satisfy sanitary requirements for international seafood trade. Bacterial vaccines currently occupy the largest product segment due to persistent Streptococcus and Aeromonas challenges in warm-water aquaculture, while viral vaccines represent the fastest-expanding category as molecular engineering advances enable cost-effective production against rhabdoviruses and iridoviruses. Among species, fish dominates absolute volume, though crustacean vaccination is gaining structural attention as White Spot Syndrome Virus continues to devastate shrimp farming across tropical production belts.
The European Medicines Agency governs veterinary vaccine authorization through centralized and decentralized pathways, while the FDA and USDA jointly oversee product licensing and facility inspection within United States aquaculture operations. REACH compliance additionally constrains adjuvant chemistry selection for vaccines distributed across EU member states. Stakeholders must monitor evolving regulatory divergence between major import markets, as divergent pathogen prioritization and environmental risk assessments will determine which vaccine portfolios secure multi-jurisdictional commercial access.
Market Dynamics
EU hygiene standards for seafood exports are forcing commercial aquaculture farms across Southeast Asia to expand vaccination programs, consolidating procurement around certified suppliers while recombinant DNA platforms compress production economics.
Growth Catalysts
- Export Certification Mandates:EU hygiene standards now require documented disease control protocols for farmed seafood entering European supply chains, accelerating vaccine adoption across Vietnamese and Thai shrimp operations.
- Streptococcus iniae Pressure:Persistent bacterial mortality in warm-water tilapia farming across Indonesia and the Philippines is driving routine immunization programs previously considered optional.
- Biosecurity Mandates:Norway's Atlantic salmon farming corridors now require routine immunization against infectious salmon anemia under national aquaculture regulations.
Market Restraints
- Cold Chain Fragility:Temperature-sensitive vaccine formulations face degradation risks across archipelagic supply networks in Indonesia and the Philippines where refrigerated logistics remain underdeveloped.
- Adjuvant Chemistry Constraints:REACH compliance restricts aluminum-based adjuvant selection for vaccines distributed across EU member states, forcing reformulation investments.
- Technical Shelf-Life Limitations:Inactivated viral vaccines require strict potency monitoring within 12-18 month windows, complicating inventory management for remote farming cooperatives.
Strategic Opportunities
- Crustacean White Space:White Spot Syndrome Virus devastation across Ecuadorian and Indian shrimp farming belts creates structural demand for the first commercially viable crustacean vaccines.
- Oral Delivery Convergence:Microencapsulation technology combined with feed-grade formulations is integrating into vaccination protocols, eliminating labor-intensive injection requirements.
- EU Green Deal Tailwinds:Sustainable aquaculture provisions channel public procurement toward antibiotic-reduction certified operations, privileging preventive vaccination over therapeutic treatments.
Industry Challenges
- Autogenous Vaccine Timelines:Rapid pathogen-specific responses for regional outbreaks require 8-12 week development cycles that strain farm-level biosecurity planning.
- Diagnostic Integration Complexity:Preventive vaccination protocols demand real-time pathogen surveillance systems that many mid-scale salmon farms in Chile and Norway lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquatic Animal Vaccines Market |
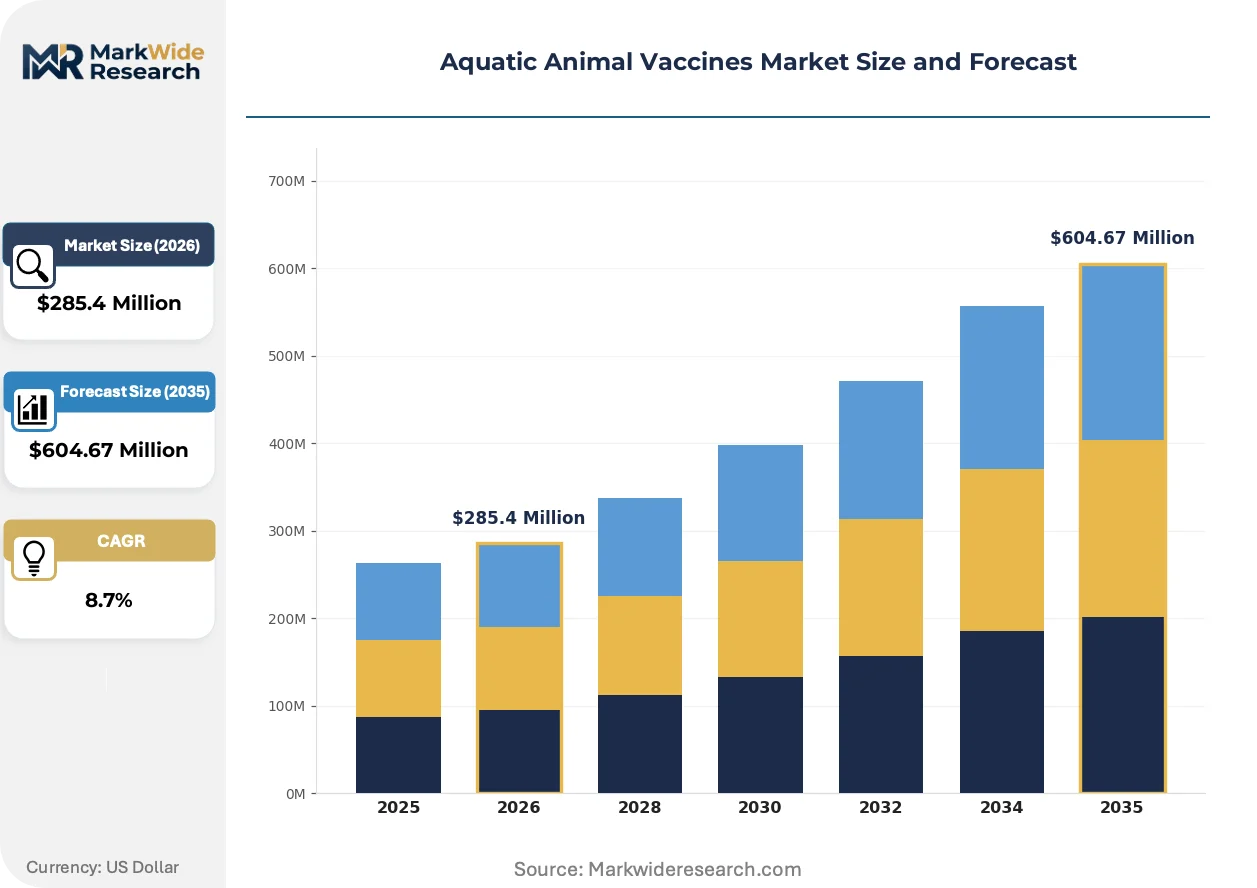
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Vaccines, Viral Vaccines, Parasitic Vaccines, Combined Vaccines Species: Fish, Crustaceans, Mollusks, Amphibians Administration Route: Oral, Injection, Bath, Spraying End User: Aquaculture Farms, Research Institutions, Fisheries, Veterinary Clinics |
| Companies Covered | HIPRA, Virbac, Zoetis Inc., Nisseiken Co., Ltd., Benchmark Holdings, Merck Animal Health, Phibro Animal Health Corporation, KBNP, Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquatic Animal Vaccines Market Trends and Innovations
Recombinant DNA platforms are displacing traditional inactivation methods across bacterial and viral vaccine production, while regulatory divergence between import markets fragments portfolio strategies.
DNA vaccine technology is integrating plasmid-based antigen expression into commercial salmonid immunization programs. Norwegian and Chilean Atlantic salmon producers are adopting these platforms at accelerating rates following EMA centralized pathway approvals. This molecular engineering approach is integrating cost structures that undercut conventional inactivated vaccine production while improving efficacy against rhabdoviruses.
REACH compliance is constraining adjuvant chemistry selection for vaccines distributed across EU member states. Industrial consequence forces manufacturers toward alternative immunostimulant formulations or regional product differentiation. Bacterial vaccines for warm-water species face the steepest reformulation costs, with several suppliers pursuing lipid-based adjuvant substitutions.
Certification-driven procurement now dominates European seafood supply chain contracting. Large-scale retail and foodservice buyers in Germany and France are consolidating supplier panels around operations demonstrating antibiotic-free production through documented vaccination protocols. This preference shift is most visible in salmon purchasing, where Norwegian exporters leveraging comprehensive immunization records command contract premiums over minimally certified competitors.
Aquatic Animal Vaccines Market Segmentation
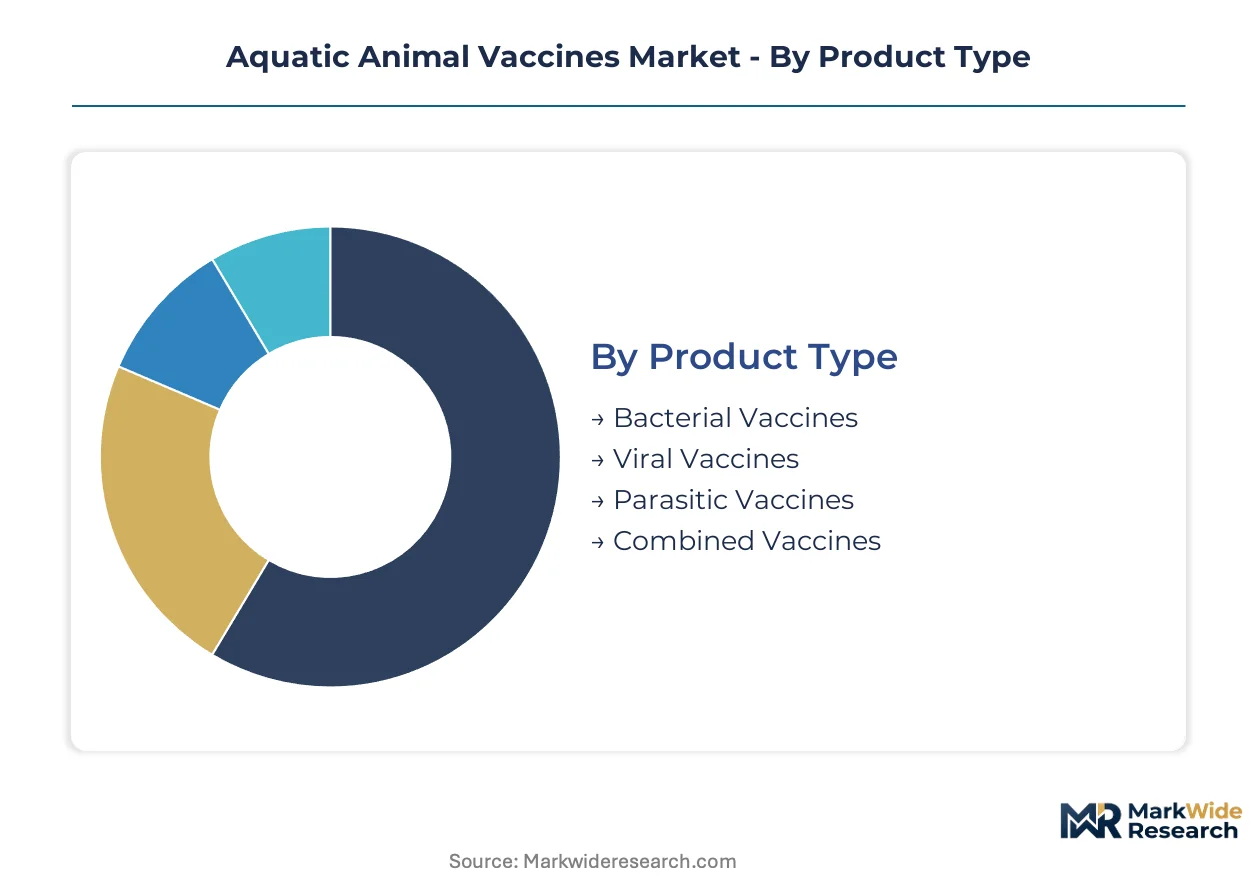
Vaccine portfolios in aquaculture must align with pathogen pressure, species physiology, and regulatory export requirements. Each segmentation dimension carries distinct commercial logic for manufacturers positioning across bacterial versus viral platforms, salmon versus shrimp operations, and injection versus oral delivery systems.
Product Type:
Cost tier separates commodity bacterial formulations from premium recombinant viral platforms requiring molecular engineering investment.
- Bacterial Vaccines:Inactivated or attenuated preparations targeting Streptococcus, Aeromonas, and Vibrio species dominate warm-water tilapia and shrimp operations across Indonesia and Vietnam. Norwegian salmon farmers deploy these alongside viral products under national biosecurity mandates requiring documented immunization against multiple bacterial pathogens.
- Viral Vaccines:Recombinant DNA and subunit platforms against infectious salmon anemia and viral hemorrhagic septicemia command premium pricing in Atlantic salmon corridors. Chilean producers are adopting these molecular formulations at accelerating rates following EMA centralized pathway approvals that validate efficacy data.
- Parasitic Vaccines:Experimental platforms targeting sea lice and gill parasites remain developmental, with no commercial products yet securing multi-jurisdictional authorization.
- Combined Vaccines:Multivalent formulations reducing injection frequency attract labor-constrained operations in Scottish and Canadian salmon farming regions.
Bacterial vaccines lead volumes today; viral platforms are gaining share fastest.
Species:
Application context distinguishes intensive monoculture systems from extensive polyculture environments with divergent biosecurity investment capacity.
- Fish:Atlantic salmon, rainbow trout, and tilapia account for absolute immunization volumes, with injection-based protocols standard in Norwegian and Chilean net-pen operations. Bacterial and viral vaccines both register strong uptake where export certification mandates documented disease control.
- Crustaceans:Shrimp farming across Ecuador, India, and Vietnam is driving structural attention toward White Spot Syndrome Virus solutions, though no commercially viable crustacean vaccines have yet achieved regulatory authorization at scale.
- Mollusks:Oyster and mussel producers in France and Spain face herpes virus pressures, but vaccine development lags due to complex immune system characteristics and limited commercial incentive.
- Amphibians:Frog farming operations in China and Vietnam represent a niche segment with minimal vaccine penetration and unstandardized regulatory pathways.
Fish dominates absolute consumption; crustacean vaccination is climbing the fastest.
Administration Route:
Customer type—labor-intensive salmon farms versus mechanized shrimp operations—determines route selection and equipment investment requirements.
- Injection:Intraperitoneal delivery ensures precise dosing and reliable immune response in Atlantic salmon smolt production, though labor costs constrain adoption in lower-margin species.
- Oral:Microencapsulated feed-grade formulations are integrating into Vietnamese and Thai shrimp vaccination protocols, eliminating handling stress and enabling mass administration across pond systems.
- Bath:Immersion delivery suits small-bodied fry stages where individual injection is impractical, common in rainbow trout hatcheries.
- Spraying:Aerosol application remains experimental for crustacean larvae, with limited commercial validation outside research settings.
Injection retains the largest installed base; oral delivery is expanding most quickly.
End User:
Volume concentration separates industrial-scale aquaculture from fragmented research and clinical service providers with divergent procurement patterns.
- Aquaculture Farms:Commercial salmon, tilapia, and shrimp operations in Norway, Chile, and Indonesia drive bulk procurement, consolidating supplier relationships around multi-year immunization programs.
- Research Institutions:Universities and government fisheries laboratories in Japan and Canada validate novel platforms and generate efficacy data supporting regulatory submissions.
- Fisheries:Wild stock enhancement programs in Alaska and New Zealand represent limited vaccine demand focused on specific pathogen threats to capture-based aquaculture.
- Veterinary Clinics:Ornamental fish and high-value broodstock operations in Germany and the Netherlands generate specialized demand for autogenous vaccine services.
Aquaculture farms anchor procurement volumes; research institutions are gaining influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway pioneered commercial salmon vaccination in the 1980s, establishing the regulatory and technical foundations that now propagate through Chilean, Scottish, and Canadian farming corridors. This Nordic lineage shapes contemporary biosecurity mandates and export certification protocols across Atlantic salmon production zones.
Norway
Atlantic salmon farming corridors in Nordland and Troms counties drive the highest vaccine penetration rates worldwide. The Norwegian Food Safety Authority enforces mandatory immunization against infectious salmon anemia under national aquaculture regulations. Bergen anchors the country's veterinary vaccine R&D cluster, where producers coordinate with the European Medicines Agency on centralized pathway approvals.
Chile
Los Lagos and Aysén regions host intensive salmon farming operations confronting persistent infectious salmon anemia and sea lice pressures. The country's national fisheries service requires documented vaccination protocols for export certification to North American and Asian markets. Puerto Montt concentrates diagnostic laboratory capacity supporting farm-level immunization programs.
Vietnam
Mekong Delta shrimp farming belts face escalating White Spot Syndrome Virus mortality, driving experimental adoption of oral vaccine formulations. The Ministry of Agriculture and Rural Development aligns disease control protocols with EU hygiene standards for seafood export access. Cà Mau province leads national shrimp production volume and biosecurity investment.
Indonesia
Streptococcus iniae outbreaks in Jambi and West Java tilapia ponds are accelerating routine bacterial vaccination programs previously considered optional. The country's national pharmaceutical regulator evaluates veterinary vaccine imports against domestic efficacy requirements. Lampung province concentrates warm-water aquaculture clusters where feed-grade vaccine integration is advancing fastest.
United States
Alaskan wild salmon enhancement programs and Pacific Northwest hatcheries generate limited but specialized demand for fry-stage immunization. The FDA and USDA jointly oversee product licensing and facility inspection for domestic aquaculture operations. Seattle anchors West Coast veterinary vaccine distribution networks serving both commercial farms and tribal fisheries.
Aquatic Animal Vaccines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across recombinant platform sophistication and regulatory pathway access. The market structures around three tiers: multinational pharmaceutical conglomerates with centralized EMA approvals, mid-cap specialists delivering autogenous vaccine services, and regional distributors serving fragmented warm-water farming belts. Consolidation pressure intensifies as export certification mandates favor suppliers with multi-jurisdictional dossiers. Strategic moves concentrate on recombinant technology licensing and backward integration into adjuvant chemistry production.
Within the multinational tier, Zoetis Inc., Merck Animal Health, and Elanco Animal Health occupy positions defined by molecular engineering capacity and salmonid portfolio depth. Virbac and Benchmark Holdings exemplify the specialist archetype through rapid-response autogenous services. HIPRA represents European-origin consolidation of bacterial and viral platform expertise. These entities collectively shape procurement standards across Norwegian, Chilean, and Southeast Asian farming corridors.
| Leading Market Players |
|---|
| HIPRA |
| Virbac |
| Zoetis Inc. |
| Nisseiken Co., Ltd. |
| Benchmark Holdings |
| Merck Animal Health |
| Phibro Animal Health Corporation |
| KBNP |
| Elanco Animal Health |
| Others |
Pricing and Supply Chain Analysis
Aluminum hydroxide benchmark pricing cascades through aquatic vaccine manufacturing into three-tier cost structures across premium recombinant platforms, standard inactivated formulations, and economy-grade bacterial products serving divergent certification requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with EMA centralized pathway approvals commanding brand premiums over decentralized authorizations. Price differentiation stems from molecular engineering complexity and cold-chain logistics coverage. Cost compression in standard-tier bacterial vaccines is intensifying because Indonesian and Vietnamese tilapia farms negotiate volume discounts. Southeast Asian shrimp cooperatives exhibit highest price sensitivity; Norwegian salmon exporters demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from EU import regulators force manufacturers to qualify backup suppliers for critical adjuvant chemistries and antigen production cell lines. Active pharmaceutical ingredient production concentrates in Denmark, Spain, and the United States. Finished formulation depends on cold-chain distribution networks, sterile fill-finish capacity, and quality release testing. Single-source vulnerability in lipid-based adjuvant feedstocks poses structural risk. Distribution runs through veterinary pharmaceutical wholesalers serving farming corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aquatic animal vaccines function as a stable compounder anchored by biosecurity mandates that institutionalize recurring immunization programs across export-oriented farming operations.
For Market Incumbents: Lock in multi-year supply agreements with Norwegian and Chilean salmon producers before patent cliffs on recombinant DNA platforms erode margin structures. Defend market position by securing backward integration into adjuvant chemistry production to circumvent REACH reformulation costs. Prioritize autogenous vaccine service capacity to capture regional outbreak response demand. For New Entrants and Emerging Players: Enter via crustacean White Spot Syndrome Virus solutions where no commercially viable vaccines yet exist, targeting Ecuadorian and Indian shrimp farming belts with oral microencapsulation delivery platforms. Pursue licensing partnerships with Vietnamese feed mills to bypass injection-based infrastructure requirements and accelerate market penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing rapid-response autogenous manufacturing capabilities and established EMA rapport. Long-term viability rests on consolidation of fragmented warm-water aquaculture service networks. Monitor EU Green Deal procurement standardization as the critical inflection signal for portfolio reallocation toward antibiotic-reduction certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Platform Licensing | EMA centralized approvals validate molecular engineering investments for Atlantic salmon corridors. |
| Autogenous Service Expansion | Rapid pathogen-specific responses capture regional outbreak demand across Southeast Asian farming belts. |
| Adjuvant Chemistry Backward Integration | In-house lipid-based formulation production circumvents REACH compliance constraints on aluminum alternatives. |
| Oral Delivery Technology Acquisition | Microencapsulation capabilities eliminate labor-intensive injection requirements in shrimp pond systems. |
| Multi-jurisdictional Dossier Investment | Simultaneous FDA and EMA pathway navigation secures access to North American and European seafood supply chains. |
Research Methodology
Bottom-up aquaculture farm modeling reconciled against top-down vaccine production tracking forms the analytical core of this study. Primary interviews with veterinary vaccine development executives, regulatory affairs specialists at EMA and FDA, salmon farm biosecurity managers, and shrimp cooperative procurement officers were combined with secondary validation. Sources include EMA centralized pathway approval databases, FDA veterinary product licensing records, Norwegian Food Safety Authority inspection reports, and customs trade data on vaccine ingredient imports. Triangulation across these channels ensures supply-side and demand-side estimates converge.
Historical trendline analysis of bacterial and viral vaccine penetration rates across Norwegian, Chilean, and Southeast Asian farming corridors established baseline growth parameters. The projection framework segments by pathogen type, species application, administration route, and regional regulatory cluster. CAGRs were derived from pathogen pressure intensity, export certification mandate expansion, and recombinant platform adoption curves. Industry-specific inputs include infectious salmon anemia outbreak frequency data and EU hygiene standard enforcement timelines.
Inputs from EMA approval databases and national fisheries service records were available through the study window; gaps in crustacean vaccine clinical trial disclosure introduce uncertainty bands around White Spot Syndrome Virus commercialization timelines. Forecasts reflect assumptions on regulatory pathway duration and cold-chain infrastructure buildout rates. Deviation in EU Green Deal procurement acceleration or REACH adjuvant restriction tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Lignocellulosic Biomass Market