
 Biostimulants Market | 2026-2036
Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Biostimulants Market Analysis
Buyer concentration among large-scale agricultural producers is shifting toward integrated crop management platforms that bundle biostimulants with precision agriculture services. Syngenta Group leverages its seed-treatment infrastructure to embed microbial amendments directly into planting protocols. BASF SE anchors its position through R&D intensity in humic substance formulations tailored to regional soil profiles. Novozymes A/S specializes in enzymatic biostimulant platforms that differentiate on nitrogen-use efficiency metrics.
Biostimulants comprise organic and inorganic substances, including seaweed extracts, humic acids, and beneficial microorganisms, applied to plants or soil to enhance nutrient uptake efficiency, abiotic stress tolerance, and crop quality parameters without direct pesticidal action. Seaweed extracts dominate current volume due to established extraction infrastructure and broad crop compatibility, while microbial amendments represent the fastest-expanding category driven by advances in strain stabilization and shelf-life extension. Foliar treatment captures the largest share of application value as growers prioritize rapid nutrient intervention during critical growth windows, though seed treatment is gaining traction for its systemic protection and labor reduction benefits.
The EU Fertilizing Products Regulation (FPR) and REACH frameworks govern biostimulant composition claims and environmental release thresholds across Europe, while the EPA regulates microbial inoculants under the Federal Insecticide, Fungicide, and Rodenticide Act in the United States, creating divergent compliance burdens for multinational suppliers. India's FSSAI and BIS standards for agricultural inputs add another layer of market access complexity for exporters targeting South Asian horticulture sectors. Stakeholders must monitor regulatory harmonization progress between the EU FPR and emerging national frameworks to anticipate where formulation registration investments will yield priority market entry.
Market Dynamics
The EU Fertilizing Products Regulation (FPR) harmonization is compressing product registration timelines while Mediterranean water stress concentrates demand for drought-tolerance formulations among specialty crop growers.
Growth Catalysts
- EU FPR Harmonization:The regulation standardizes CE-marking pathways across member states, reducing redundant national registrations and accelerating market entry for compliant biostimulant formulations.
- Seaweed Extraction Infrastructure:Established coastal processing facilities in Ireland and Norway enable cost-competitive raw material supply for volume-scale biostimulant manufacturing.
- Mediterranean Water Stress:Declining irrigation availability in Spain and Italy amplifies grower willingness to invest in abiotic stress-tolerance products with measurable yield protection.
Market Restraints
- Strain Stabilization Costs:Microbial amendment shelf-life extension requires cold-chain infrastructure and encapsulation technology that elevates per-unit production costs.
- REACH Compliance Burden:The European Chemicals Agency's substance data requirements impose documentation costs that disproportionately constrain small-formulation entrants.
- Synthetic Fertilizer Price Volatility:Ammonia and urea price swings create intermittent substitution pressure, particularly when commodity fertilizer markets oversupply.
Strategic Opportunities
- India Horticulture Expansion:The FSSAI and BIS framework evolution for agricultural inputs creates first-mover advantage for exporters establishing local formulation partnerships.
- Seed Treatment Convergence:Microbial amendment integration with precision planting equipment opens systemic protection channels previously dominated by chemical seed coatings.
- Carbon Credit Monetization:Nitrogen-use efficiency metrics from enzymatic biostimulants align with emerging soil carbon protocols in voluntary carbon markets.
Industry Challenges
- Microbiologist Talent Scarcity:Strain characterization and fermentation optimization require specialized expertise that outpaces agricultural biotechnology program output.
- Multi-Jurisdiction Label Claims:Divergent efficacy demonstration standards between EPA FIFRA microbial inoculant rules and EU FPR create formulation versioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biostimulants Market |
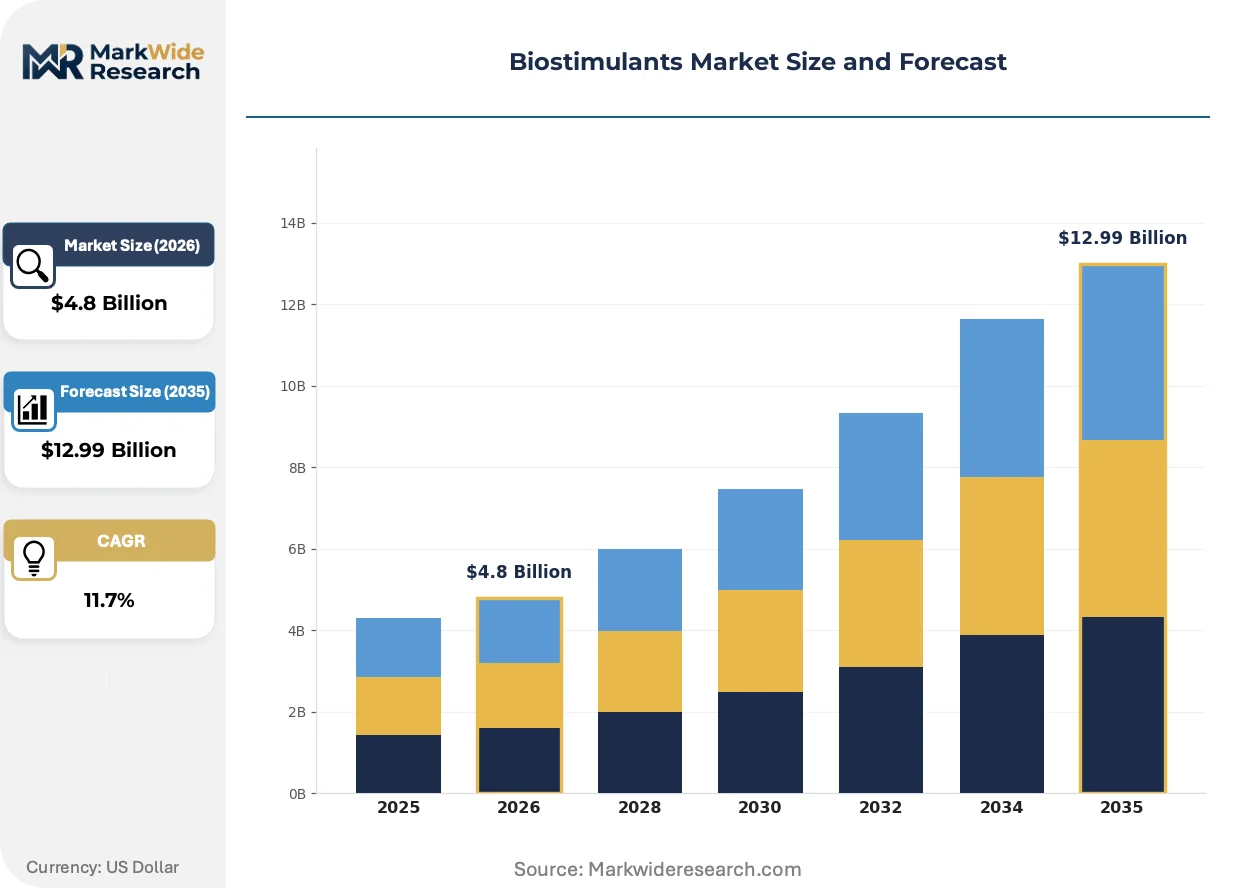
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Substances, Seaweed Extracts, Microbial Amendments, Amino Acids Application: Foliar Treatment, Soil Treatment, Seed Treatment, Fertigation End User: Agricultural Producers, Horticulturists, Greenhouse Operators, Turf Managers Distribution Channel: Online Retailers, Agrochemical Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, UPL Limited, FMC Corporation, Novozymes A/S, Valagro S.p.A., Koppert B.V., Biolchim S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biostimulants Market Emerging Trajectories
Formulation science is converging with digital agriculture infrastructure, while regulatory data requirements and procurement sophistication reshape competitive requirements.
Encapsulation technology for microbial viability preservation is consolidating competitive advantage among suppliers with in-house materials science capabilities. Large-scale vegetable producers in the Netherlands and California are specifying minimum colony-forming unit guarantees at harvest, not just at manufacture. This performance standard is compressing margins for formulation houses dependent on third-party stabilization inputs.
REACH substance data requirements are intensifying documentation obligations for humic acid suppliers sourcing from diverse peat and leonardite deposits. The European Chemicals Agency's expanded registration deadlines for complex natural substances force reformulation toward single-origin raw material streams. German and French distributors are now requiring full supply chain substance dossiers as a procurement precondition.
Buyer specification of outcome-based field performance guarantees is displacing traditional product-centric purchasing in high-value horticulture. Spanish and Italian citrus and olive cooperatives are contracting biostimulant applications through integrated crop management platforms that bundle monitoring, intervention, and yield insurance. This service integration concentrates procurement authority among platform operators with precision agriculture infrastructure.
Biostimulants Market Segmentation
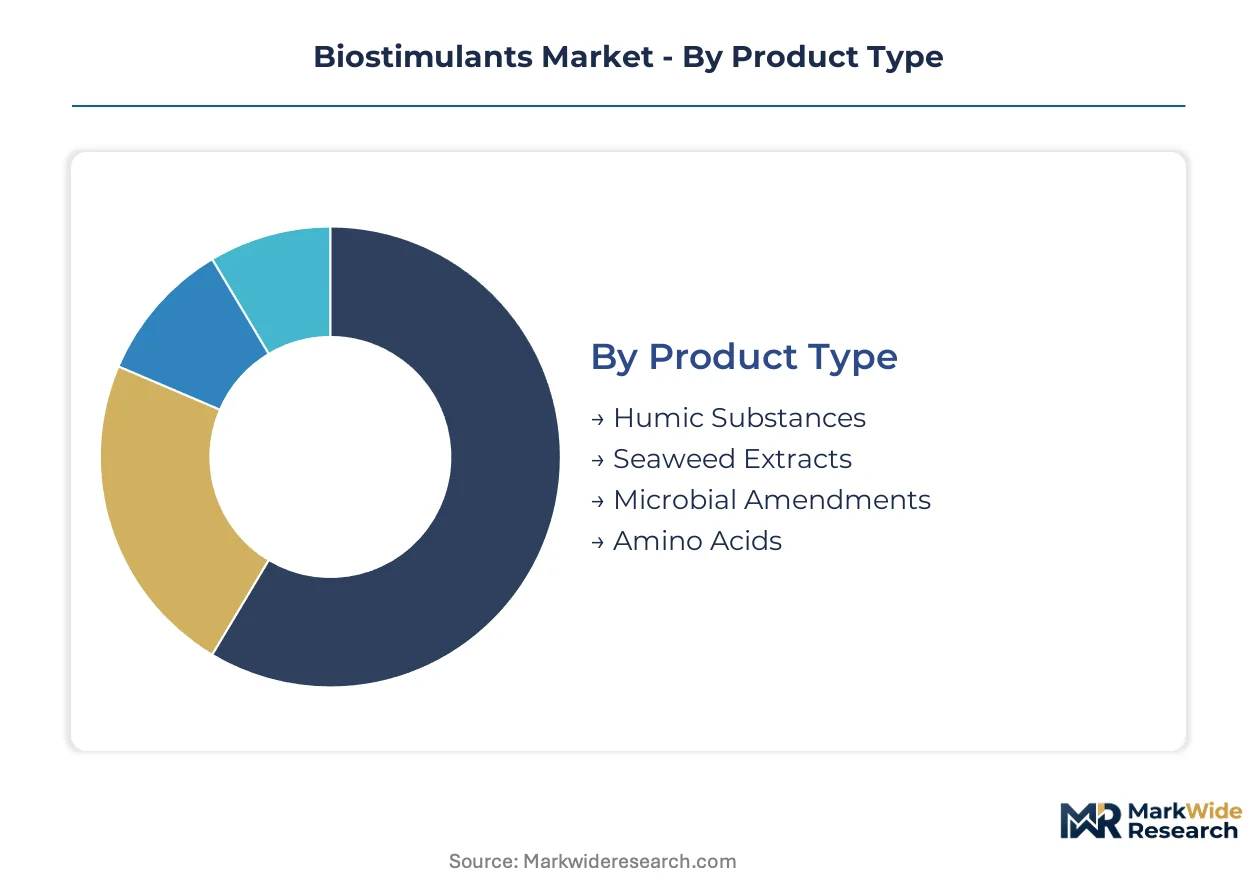
Biostimulant procurement patterns diverge sharply across product chemistry, application timing, and buyer sophistication. Segmentation reveals where formulation investments concentrate and which channels capture margin.
Product Type:
Supply concentration in coastal extraction facilities and fermentation capacity shapes competitive positioning across product categories.
- Seaweed Extracts:Derived from Ascophyllum nodosum and Macrocystis pyrifera through alkaline hydrolysis, these formulations dominate current volume due to established processing infrastructure in Ireland and Norway. Mediterranean citrus growers in Spain specify liquid concentrates with guaranteed auxin content for flowering-stage applications.
- Microbial Amendments:Comprising rhizobia, mycorrhizae, and plant growth-promoting bacteria stabilized through encapsulation or freeze-drying. Demand concentrates among specialty vegetable producers in Italy seeking nitrogen-fixation alternatives to synthetic inputs under EU Farm to Fork pressure.
- Humic Substances:Sourced from leonardite and peat deposits, valued for chelation capacity and soil conditioning. German distributors now require REACH-compliant substance dossiers tracing origin to specific mining concessions.
- Amino Acids:Hydrolyzed protein formulations supplying glutamic acid and glycine betaine for osmotic stress mitigation. Greenhouse tomato producers in the Netherlands specify purity grades above 80% free amino acid content.
Today's leader: Seaweed Extracts. Tomorrow's challenger: Microbial Amendments.
Application:
Application method selection tracks labor availability, equipment infrastructure, and the urgency of crop intervention windows.
- Foliar Treatment:Aerial or ground-rig spraying delivers rapid nutrient uptake through stomatal and cuticular penetration. Spanish olive cooperatives prioritize this method during critical flowering periods when soil uptake rates prove insufficient.
- Seed Treatment:Microbial inoculant coating applied at planting establishes systemic colonization before soil pathogen exposure. Italian maize producers adopting precision planting equipment drive adoption through labor reduction benefits.
- Soil Treatment:Pre-plant incorporation or side-dressing of humic and microbial amendments for root-zone conditioning. French viticulture regions favor this approach for established vineyard renovation.
- Fertigation:Injection into drip or pivot irrigation systems enables precise timing with phenological stages. California vegetable operations integrate biostimulant dosing with soil moisture sensor networks.
Foliar Treatment commands current value share. Seed Treatment is climbing the fastest as planting automation spreads.
End User:
Buyer sophistication determines specification rigor, from guaranteed CFU counts to outcome-based performance contracting.
- Agricultural Producers:Large-scale arable farms purchasing through integrated crop management platforms that bundle monitoring, application, and yield insurance. Procurement authority concentrates among platform operators with precision agriculture infrastructure.
- Horticulturists:High-value fruit and vegetable growers specifying minimum colony-forming unit guarantees at harvest, not manufacture. Dutch and Belgian operations lead in outcome-based contracting.
- Greenhouse Operators:Controlled-environment agriculture with closed-loop irrigation requiring biostimulant compatibility with recirculation systems. Substrate-grown tomato and cucumber producers in Almeria represent concentrated demand.
- Turf Managers:Golf course and sports field maintenance seeking abiotic stress tolerance and recovery acceleration. UK and German municipal contracts emphasize environmental release thresholds.
Agricultural Producers anchor volume. Horticulturists drive specification intensity.
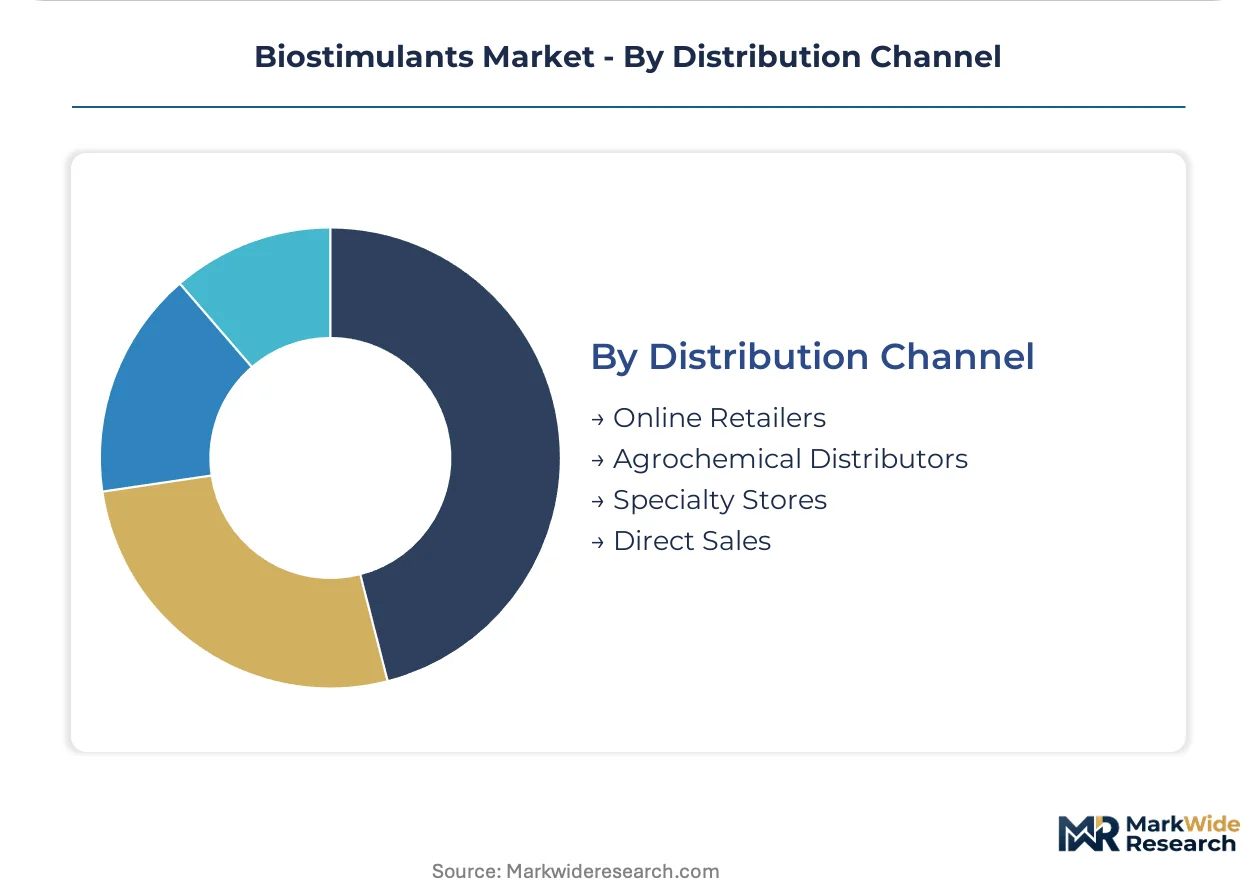
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and regulatory documentation needs.
- Agrochemical Distributors:Regional networks with agronomist staff providing field recommendation services. French and German cooperatives maintain dominant positions in specialty crop segments.
- Direct Sales:Manufacturer-to-grower relationships for large-volume accounts with customized formulation requirements. Italian citrus consortia negotiate directly with microbial amendment suppliers.
- Online Retailers:E-commerce platforms serving smallholder and hobby segments with standardized package sizes. Growing presence in UK and Netherlands home-garden markets.
- Specialty Stores:Garden center and farm supply outlets targeting turf and ornamental applications. Limited penetration in professional agriculture due to technical support gaps.
Agrochemical Distributors retain procurement influence. Direct Sales is gaining share fastest among large-scale buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation scientists and marine biologists cluster in coastal extraction zones and industrial biotechnology corridors, anchoring regional production capabilities for biostimulant manufacturing.
Spain
Specialty citrus and olive cooperatives in Valencia and Andalusia drive concentrated demand for drought-tolerance formulations. The EU Fertilizing Products Regulation (FPR) CE-marking pathway accelerates product registration timelines for compliant suppliers. Almeria's greenhouse concentration generates precise specification requirements for fertigation-compatible biostimulants.
Italy
Precision vegetable producers in Emilia-Romagna and Puglia seek nitrogen-fixation alternatives under Farm to Fork pressure. ECHA REACH substance documentation requirements force reformulation toward traceable single-origin humic deposits. Bologna-based distributors now mandate full supply chain dossiers as procurement preconditions.
Germany
Large-scale arable farms in Lower Saxony and Bavaria purchase through integrated crop management platforms bundling biostimulants with precision agriculture services. The EU Green Deal nutrient management targets create regulatory pull for nitrogen-use efficiency products. Rhineland-Palatinate viticulture regions favor soil-treatment approaches for established vineyard renovation.
United States
California vegetable operations integrate biostimulant dosing with soil moisture sensor networks in Central Valley and Salinas Valley production zones. EPA FIFRA microbial inoculant rules govern environmental release thresholds, creating compliance complexity distinct from EU frameworks. Midwest maize producers adopting precision planting equipment drive seed-treatment category expansion.
India
Maharashtra and Karnataka horticulture expansion creates first-mover opportunity for exporters establishing local formulation partnerships. FSSAI and BIS framework evolution for agricultural inputs adds market access complexity requiring adaptive registration strategies. Gujarat's specialty crop belt concentrates demand for foliar-applied stress-mitigation products.
Biostimulants Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that fragments by product chemistry and application timing. Tier-one agricultural input majors leverage seed-treatment infrastructure and distribution networks, while mid-cap fermentation houses concentrate on strain stabilization capabilities. Two strategic archetypes dominate: integrated crop management platform operators and coastal extraction specialists with captive raw material supply. Competitive intensity centers on M&A activity targeting microbial amendment capabilities and geographic expansion into underpenetrated horticulture corridors.
Within the diversified agrochemical tier, Syngenta Group, BASF SE, and Bayer AG exemplify platform-scale positioning. Syngenta's seed-treatment infrastructure anchors systemic delivery capabilities, while BASF SE occupies a position in humic substance R&D intensity. Bayer AG represents the convergence of pharmaceutical-grade fermentation expertise with agricultural application channels. Novozymes A/S sits within the enzymatic specialization vector, distinct from the integrated crop protection majors.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| UPL Limited |
| FMC Corporation |
| Novozymes A/S |
| Valagro S.p.A. |
| Koppert B.V. |
| Biolchim S.p.A. |
| Others |
Supply Flow & Price Mechanics
Encapsulation technology maturation for microbial viability preservation simultaneously compresses production economics and consolidates manufacturing among suppliers with in-house materials science capabilities. This dual effect concentrates pricing power with integrated formulation houses while fragmenting margin structures for third-party-dependent competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated crop management platforms commanding premium pricing from transactional product sales. Premium-mid-economy pricing differentiation tracks guaranteed colony-forming unit performance at harvest versus manufacture. Cost compression in standard-tier formulations is intensifying because Dutch and Belgian horticulturists now mandate outcome-based field performance guarantees. Large-scale agricultural producers purchasing through bundled platforms exhibit lowest price sensitivity, while smallholder segments served through online retailers face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from German and French distributors now mandate full supply chain substance dossiers as procurement preconditions. Raw material supply concentrates in Ireland and Norway for seaweed extraction, Italy and Spain for fermentation capacity, and Germany for leonardite humic deposits. Formulation manufacturing draws from Ascophyllum nodosum biomass, stabilized microbial strains, and peat-derived humic acids. Single-source vulnerability in cold-chain infrastructure for microbial amendments elevates supply risk. Distribution runs through agrochemical distributor networks with agronomist technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU FPR CE-marking acceleration in Europe contrasts with FSSAI and BIS framework evolution complexity in India, creating divergent cost-to-serve profiles.
For Market Incumbents: Extend seed-treatment infrastructure convergence to capture systemic delivery channels from chemical coating incumbents. Build backward integration into coastal extraction facilities in Ireland and Norway to secure captive raw material supply against REACH substance documentation requirements. Vertical integration into encapsulation technology protects margin from third-party stabilization cost inflation.
For New Entrants and Emerging Players: EU FPR harmonization across member states opens a window for compliant formulation houses to bypass redundant national registration barriers. Target Maharashtra and Karnataka horticulture corridors in India through local formulation partnerships before BIS framework consolidation raises compliance barriers. Seed treatment integration with precision planting equipment offers the most penetrable application channel.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap microbial amendment specialists because strain stabilization capability scarcity outpaces agricultural biotechnology program output. Five-to-ten year viability hinges on carbon credit monetization protocols maturing for nitrogen-use efficiency claims. Watch for EPA FIFRA microbial inoculant rule convergence with EU FPR as inflection signal for formulation versioning complexity reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Extraction | Ireland and Norway processing facilities secure cost-competitive Ascophyllum nodosum supply. |
| Encapsulation Technology Investment | In-house materials science capabilities meet Dutch greenhouse CFU-at-harvest specifications. |
| Local Formulation Partnerships | India FSSAI compliance requires adaptive registration strategies in Maharashtra and Karnataka. |
| Seed Treatment Convergence | Precision planting equipment integration opens systemic protection channels in Italian maize. |
| Carbon Credit Protocol Alignment | Nitrogen-use efficiency metrics from enzymatic platforms access voluntary soil carbon markets. |
Methodological Framework
Bottom-up horticulturist and agricultural producer modeling reconciled against top-down fermentation capacity and extraction facility tracking forms the analytical core. Primary interviews with formulation R&D directors, distributor procurement leads, greenhouse operations managers, and regulatory affairs specialists combined with secondary validation against EU FPR implementation documents, ECHA REACH substance databases, EPA FIFRA microbial inoculant registrations, and FSSAI agricultural input notifications. Triangulation across supply-side capacity assessments and demand-side purchasing pattern analysis ensures cross-verification.
Input-output matrices map product chemistry, application timing, and buyer sophistication segments across the projection horizon. Segmentation dimensions include seaweed extract versus microbial amendment versus humic substance chemistry, foliar versus seed versus soil versus fertigation application method, and agricultural producer versus horticulturist versus greenhouse operator buyer archetype. CAGRs derive from growth driver elasticity modeling against regulatory timeline acceleration and water stress intensity indicators.
Revisions become necessary when EU FPR harmonization implementation delays, EPA FIFRA rule convergence stalls, or India BIS framework consolidation accelerates beyond modeled timelines. Deviation in synthetic fertilizer price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Latin America Biopesticide Market