
 Biopesticides Market | 2026-2036
Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Biopesticides Market Analysis
Platform licensing revenue from microbial strain libraries is tilting toward integrated pest management providers that bundle biologicals with precision application services. Bayer AG leverages its proprietary fermentation infrastructure to supply high-titer bacterial concentrates across multiple geographies. Valent BioSciences anchors North American distribution through grower-cooperative channels that prioritize residue-free produce certification. UPL Limited extends its biologicals portfolio through in-house production of Bacillus thuringiensis formulations tailored to tropical pest complexes.
Biopesticides are pest-control agents derived from living organisms, natural materials, or genetically modified microbes, typically containing active concentrations of 10^8 to 10^11 colony-forming units per gram in formulated products, and function through modes including competitive exclusion, antibiosis, or host-specific pathogenicity to suppress agricultural pests below economic injury thresholds. The bacterial segment dominates current production volumes due to established fermentation scalability and broad-spectrum efficacy against lepidopteran larvae, while plant extracts represent the fastest-expanding category as extraction standardization improves and organic certification requirements tighten across import markets. Liquid formulations command premium positioning in high-value horticulture where foliar application precision reduces waste, whereas granular formats sustain volume demand in broad-acre row crops where soil incorporation aligns with planting equipment workflows.
EPA registration under FIFRA Section 3 shapes product development timelines and label claims for microbial biopesticides entering the US market, while REACH compliance in Europe governs the import and environmental fate assessment of non-microbial botanical active substances. Brazil's national agricultural regulator applies accelerated review pathways for biological products that demonstrate equivalence to registered reference strains, compressing market entry delays for foreign suppliers. Stakeholders must monitor evolving residue tolerance harmonization between Codex Alimentarius standards and national import protocols, as divergence in maximum residue limits for biological-origin compounds threatens cross-border shipment viability for treated commodities.
Market Dynamics
EPA registration pathway streamlining under FIFRA Section 3 is compressing microbial biopesticide development timelines, while Brazil's ANVISA accelerates import approvals to reduce chemical loading on sensitive biomes, reshaping competitive entry dynamics.
Growth Catalysts
- Insecticide Resistance Pressure:Soybean growers in Brazil face mounting resistance from lepidopteran pests, forcing rotation toward Bacillus thuringiensis-based biologicals as primary control agents.
- REACH Compliance Alignment:European botanical active substance assessments are standardizing extraction protocols, enabling cross-border shipment equivalence for plant-derived formulations.
- Fermentation Infrastructure Scaling:High-titer bacterial concentrate production is achieving cost parity with synthetic chemistry through continuous bioreactor optimization.
Market Restraints
- Colony-Forming Unit Volatility:Microbial formulation stability requires cold-chain logistics that inflate delivered costs in tropical climates without established distribution infrastructure.
- Reference Strain Equivalence Burden:Brazil's regulatory requirement for demonstrated equivalence to registered strains creates documentation barriers for novel microbial isolates.
- Synthetic Pheromone Substitution:Mating disruption technologies using chemically synthesized semiochemicals compete directly with biological-origin alternatives in orchard crops.
Strategic Opportunities
- Precision Application Convergence:Drone-based foliar delivery systems paired with microbial inoculants enable variable-rate biological deployment in row-crop agriculture.
- Residue-Free Certification Premium:Grower-cooperative channels prioritizing export-grade produce certification create price premiums for biological-treated commodities.
- Cerrado Biome Protection Mandates:Brazilian federal environmental policy is restricting chemical pesticide loading in sensitive savanna ecosystems, accelerating biological substitution timelines.
Industry Challenges
- Formulation Compatibility Expertise:Tank-mixing biologicals with conventional chemistries requires specialized agronomic knowledge that remains scarce in extension services.
- Maximum Residue Limit Harmonization:Divergence between Codex Alimentarius standards and national import protocols threatens cross-border shipment viability for treated commodities.
- Soil Microbiome Integration Complexity:Granular inoculant application workflows must align with existing planting equipment without disrupting seed treatment chemistry programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopesticides Market |
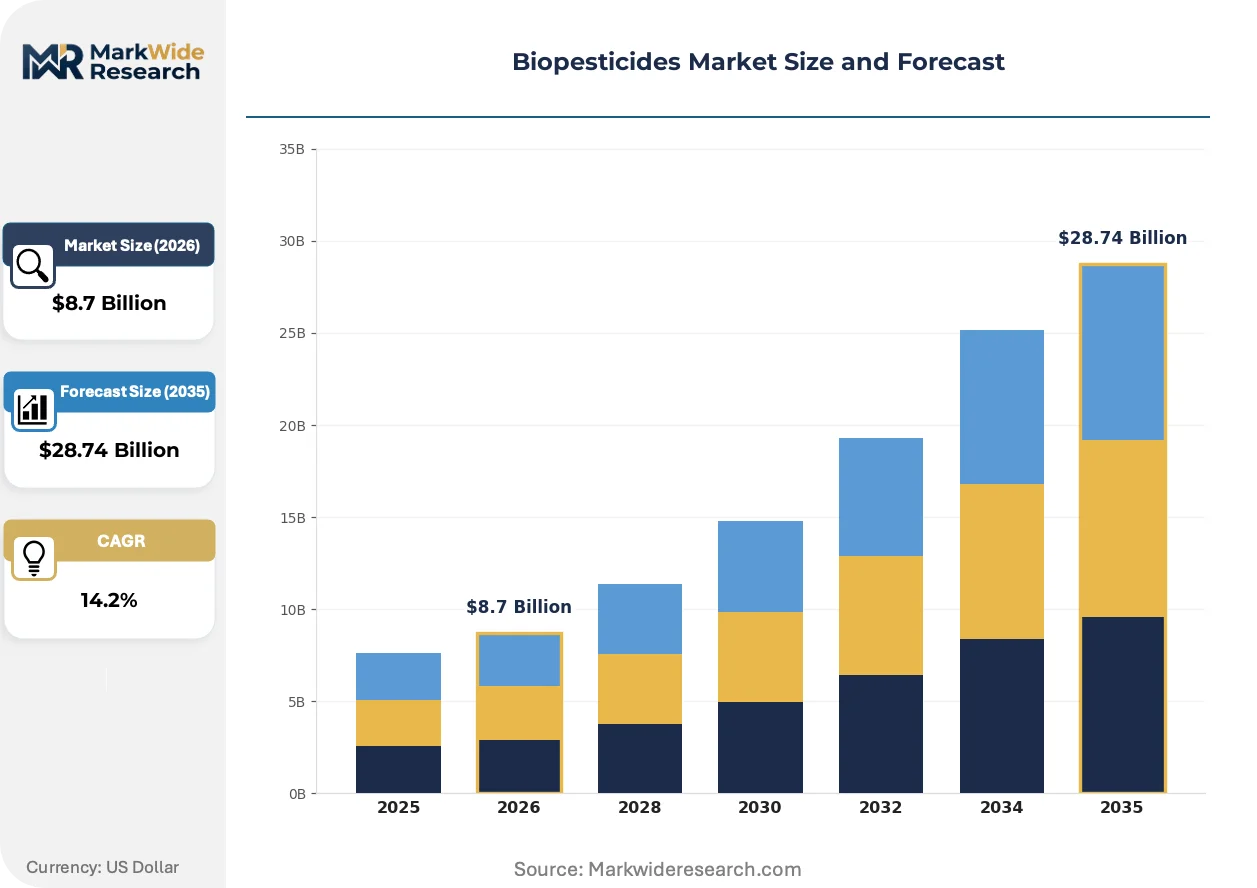
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Plant Extracts, Bioinsecticides Application: Agriculture, Horticulture, Turf, Ornamentals Formulation Type: Liquid, Granular, Powder, Microencapsulated End Use: Organic Farming, Conventional Farming, Greenhouses, Food Production |
| Companies Covered | Bayer AG, FMC Corporation, Corteva Agriscience, Sumitomo Chemical, UPL Limited, Valent BioSciences, Syngenta Crop Protection AG, Certis Biologicals, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopesticides Market Emerging Trajectories
Biological pest control is converging with digital agriculture platforms, collapsing traditional boundaries between input supply and precision services while regulatory harmonization efforts compress multi-jurisdiction market entry timelines.
RNA interference technology is collapsing the efficacy gap between biological and synthetic modes of action. Cotton and corn seed companies are integrating dsRNA traits directly into germplasm, compressing standalone biopesticide addressable markets for lepidopteran control. The structural consequence is collapsing investment timelines for external biological R&D as in-house trait pipelines internalize pest suppression functionality.
EPA's streamlined FIFRA Section 3 microbial registration pathway is compressing review timelines from 36 months to 18 months for qualified submissions. This regulatory acceleration is redirecting development resources toward US market entry ahead of EU REACH botanical assessments. Row-crop agriculture in the Midwest is responding by expanding biological integration into corn-soy rotation programs.
Certification-driven procurement is consolidating buyer power around residue-free produce standards. European supermarket chains are requiring biological input documentation for imported horticultural commodities, displacing conventional chemical documentation in supplier qualification protocols. Brazil's export-oriented soybean operations are adapting by segregating biological-treated storage streams to capture EU market premiums.
Biopesticides Market Segmentation
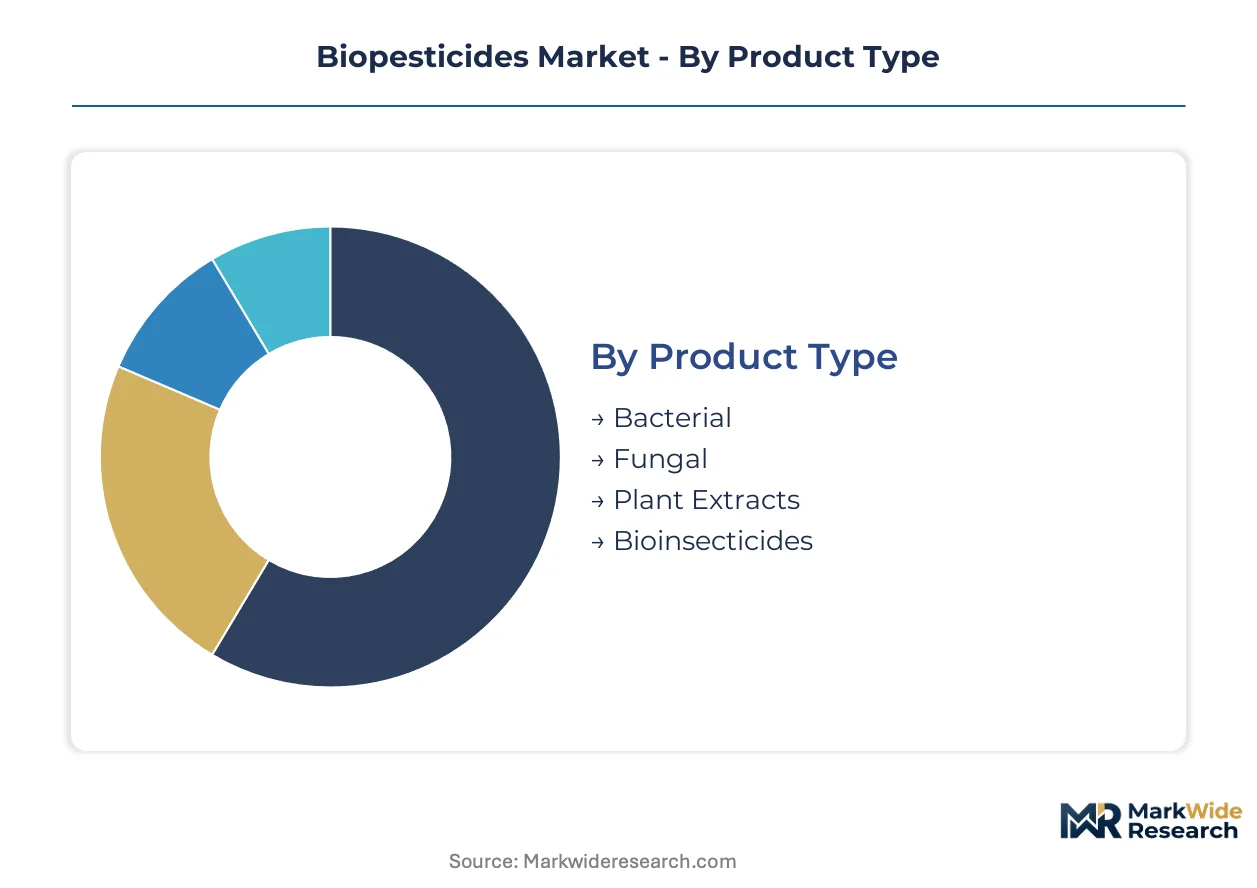
Segmentation in biopesticides reveals how formulation chemistry, application context, and farming system requirements create distinct commercial compartments. Technical specifications around colony-forming unit stability and residue certification thresholds fragment demand across product categories with minimal cross-elasticity.
Product Type:
Mature fermentation platforms anchor bacterial production, while emerging extraction standardization is unlocking botanical scalability previously constrained by batch-to-batch variability.
- Bacterial:Formulated concentrates containing 10^8 to 10^11 colony-forming units per gram dominate lepidopteran larval suppression through competitive exclusion and antibiosis modes. Soybean operations in Brazil rotate these into resistance management programs as EPA registration pathways compress development timelines. Bacterial handles the majority of throughput; Plant Extracts is the fastest mover on share.
- Fungal:Entomopathogenic and mycoparasitic strains target soil-dwelling pest complexes through host-specific pathogenicity with extended residual activity. Greenhouse producers in the Netherlands integrate Trichoderma-based formulations into substrate treatments for controlled-environment horticulture.
- Plant Extracts:Standardized botanical actives from neem, pyrethrum, and essential oil sources are gaining organic certification traction as REACH compliance aligns extraction protocols across European import markets.
- Bioinsecticides:This category spans viral, nematode, and pheromone-based modalities with narrower host ranges requiring precise application timing against specific pest pressure windows.
Cost tier separation is pronounced: bacterial fermentation achieves economies of scale that plant extracts have yet to replicate.
Application:
Volume concentration diverges sharply between broad-acre row crops and high-value protected cultivation systems with divergent residue tolerance requirements.
- Agriculture:Corn-soy rotations across the US Midwest are expanding biological integration as drone-based variable-rate delivery systems mature. Row-crop volume scales through cooperative procurement channels that aggregate grower demand for bacterial concentrate tank mixes.
- Horticulture:Foliar precision requirements in fruit and vegetable production command premium liquid formulation positioning where waste reduction justifies per-hectare cost multiples. European supermarket chain procurement standards are mandating biological input documentation for imported commodities.
- Turf:Golf course and sports field maintenance contracts specify microbial inoculant programs for root zone health management with aesthetic performance thresholds.
- Ornamentals:Nursery stock and floriculture operations prioritize residue-free certification for export-grade plant material entering phytosanitary-sensitive markets.
Agriculture absorbs the bulk of volume; Horticulture captures the steepest margin expansion.
Formulation Type:
Application equipment compatibility and climate stability requirements partition demand across physical formats with distinct supply chain infrastructure needs.
- Liquid:Aqueous suspensions and oil-based emulsions enable foliar precision in high-value crops where drift reduction and droplet adhesion determine efficacy. Cold-chain logistics requirements in tropical climates inflate delivered costs without established distribution infrastructure.
- Granular:Soil incorporation formats align with planting equipment workflows in broad-acre agriculture, sustaining volume demand despite slower release kinetics compared to foliar applications.
- Powder:Dry flowable and wettable powder formats reduce shipping weight for export markets but require reconstitution expertise at the point of application.
- Microencapsulated:Polymer-shell delivery systems extend field persistence of sensitive microbial actives, addressing UV degradation and desiccation constraints in open-field deployment.
Liquid formulations command premium positioning; Microencapsulated formats are climbing fastest on technical adoption curves.
End Use:
Certification regime intensity and residue limit stringency create four distinct buyer segments with non-overlapping procurement specifications.
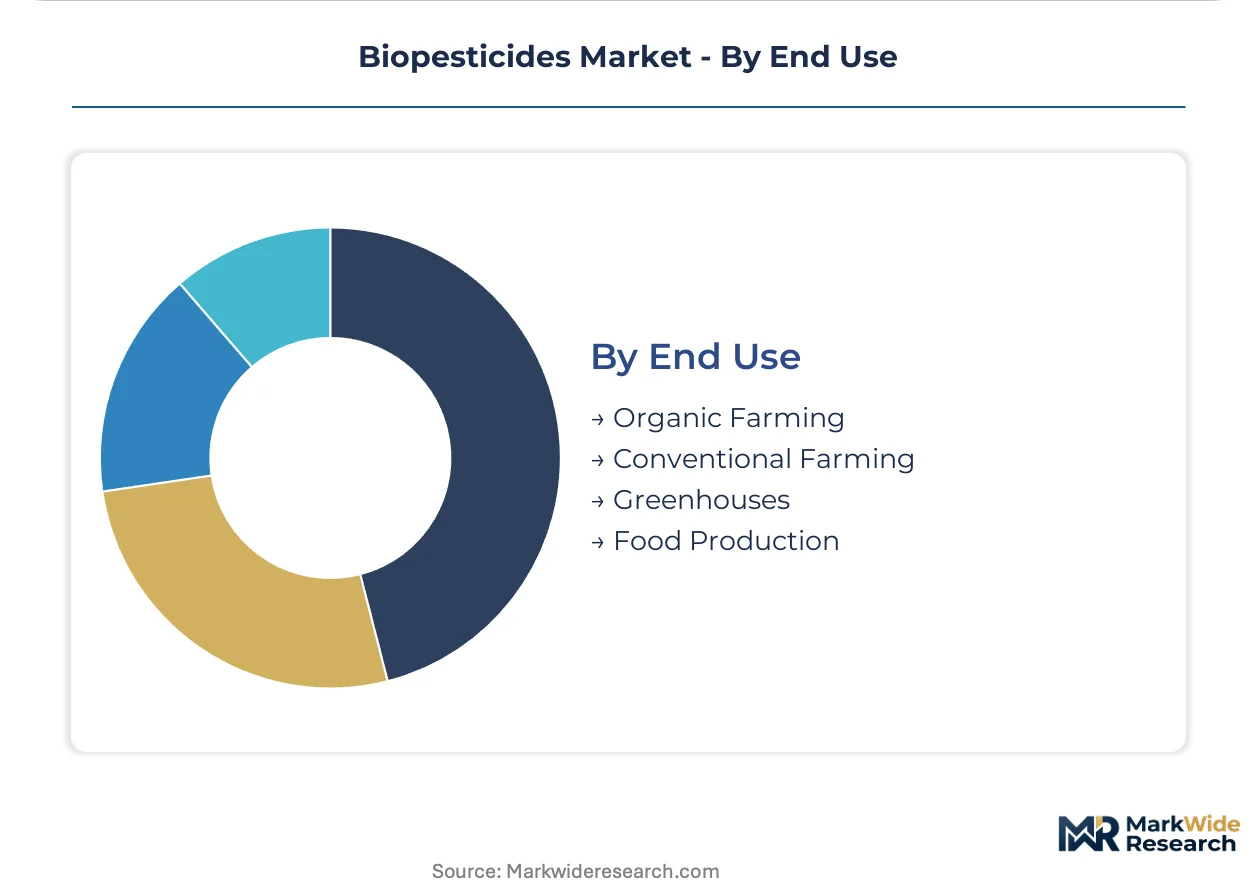
- Organic Farming:Certification bodies mandate exclusive biological input use with documentation requirements that conventional operations bypass. EU import protocols for organic commodities are tightening maximum residue limit harmonization with Codex Alimentarius standards.
- Conventional Farming:Integrated pest management programs rotate biologicals with synthetic chemistry to manage resistance pressure and pre-harvest interval constraints.
- Greenhouses:Controlled-environment agriculture enables biological agent establishment without the UV degradation and desiccation pressures of open-field systems.
- Food Production:Post-harvest and processing facility applications target stored product pest suppression with fumigation-alternative microbial treatments.
Conventional Farming generates the dominant volume base; Organic Farming is expanding most quickly on certification-driven procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: Brazilian soybean operations absorb premium biological costs to secure EU export certification, while Indian cotton growers remain highly sensitive to per-hectare input pricing.
United States
Midwest corn-soy rotations are expanding microbial integration as drone-based variable-rate delivery matures. EPA's streamlined FIFRA Section 3 pathway compresses microbial registration from 36 months to 18 months for qualified submissions. Iowa and Illinois cooperatives aggregate grower demand for bacterial concentrate tank mixes.
Brazil
Soybean growers face mounting lepidopteran resistance pressure, forcing rotation toward Bacillus thuringiensis-based biologicals as primary control agents. ANVISA accelerates import approvals to reduce chemical loading on the Cerrado biome. Mato Grosso and Paraná operations segregate biological-treated storage streams to capture EU market premiums.
Germany
REACH compliance standardizes botanical active substance extraction protocols, enabling cross-border shipment equivalence for plant-derived formulations. ECHA assessments govern environmental fate evaluation for non-microbial botanicals. Baden-Württemberg precision agriculture clusters integrate biologicals with digital farming platforms.
India
Cotton and vegetable producers adopt bacterial formulations amid tightening export residue standards for EU and Middle Eastern markets. FSSAI and APEDA coordinate maximum residue limit alignment with Codex Alimentarius. Maharashtra and Gujarat processing facilities build dedicated biological-treated commodity segregation infrastructure.
China
Domestic fermentation capacity expansion reduces import dependence for microbial active ingredients. MEE environmental compliance protocols restrict chemical pesticide discharge in Yangtze River basin agricultural zones. Jiangsu and Shandong provinces concentrate high-titer bacterial concentrate manufacturing for domestic row-crop deployment.
Biopesticides Market Vendor Landscape
Capability concentration sits with specialized microbial strain developers; scale advantage sits with diversified agrochemical conglomerates. The market structure reflects a two-tier dynamic where fermentation expertise and distribution infrastructure rarely overlap within single entities. Strategic archetypes include integrated pest management bundlers, precision application service providers, and residue-free certification enablers. Dominant competitive moves center on backward integration into fermentation capacity and geographic expansion through grower-cooperative channel partnerships.
Among diversified agrochemical conglomerates, Bayer AG and Corteva Agriscience exemplify scale-driven positions anchored by proprietary fermentation infrastructure and multi-geography supply networks. Within the biological specialization tier, Valent BioSciences and Certis Biologicals occupy positions emphasizing residue-free certification pathways and precision application convergence. UPL Limited represents the emerging-market integrated model with in-house Bacillus thuringiensis production tailored to tropical pest complexes.
| Leading Market Players |
|---|
| Bayer AG |
| FMC Corporation |
| Corteva Agriscience |
| Sumitomo Chemical |
| UPL Limited |
| Valent BioSciences |
| Syngenta Crop Protection AG |
| Certis Biologicals |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors carry bacterial concentrate feedstocks from Jiangsu fermentation hubs to European formulation facilities, with tariff exposure at EU entry points compressing margins for non-integrated distributors while residue-free certification premiums absorb logistics inflation for organic-channel suppliers.
Pricing Analysis
Long-term offtake contracts dominate microbial active ingredient procurement, with three-year supply agreements anchoring price stability for Bacillus thuringiensis concentrates while spot markets handle botanical extract volatility. Price differentiation rests on organic certification tier and cold-chain delivery infrastructure, with EU-import-compliant formulations commanding substantial premiums over conventional-channel equivalents. Cost compression in standard-grade bacterial concentrates is intensifying because Jiangsu and Shandong capacity expansion feeds oversupply into Asian markets. Indian cotton growers exhibit acute price sensitivity, whereas Brazilian soybean operations absorb premium biological costs to secure EU export certification.
Supply Chain Analysis
Upstream molasses and soy peptone feedstock markets concentrate sourcing leverage among Jiangsu, Shandong, and Maharashtra fermentation clusters, with substrate quality variability directly impacting colony-forming unit titers in finished concentrates. Supply chains draw from Chinese bacterial strain libraries, Indian botanical extraction facilities, and Dutch formulation packaging operations. Single-source vulnerability sits with proprietary Trichoderma strain collections held by limited European developers. Distribution runs through grower-cooperative procurement aggregators in the US Midwest and dedicated biologicals distributors in Brazilian Mato Grosso.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopesticide markets are crossing a platform-economics threshold where digital agriculture ecosystems bundle biological inputs with precision application services, collapsing traditional input-supplier boundaries through API interoperability between farm management software and variable-rate delivery systems.
For Market Incumbents: Harden fermentation infrastructure moats through captive supply of high-titer bacterial concentrates in tropical climate zones, insulating against Jiangsu capacity overshoot. Lock grower-cooperative channel control through residue-free certification bundling to defend margin position against precision-application service entrants. RNA interference trait integration by major seed companies threatens standalone biopesticide addressable markets for lepidopteran control. For New Entrants and Emerging Players: Pursue microencapsulated formulation white space where polymer-shell delivery systems extend field persistence of UV-sensitive microbial actives, a segment climbing fastest on technical adoption curves with limited incumbent concentration. Target greenhouse-controlled environment agriculture in the Netherlands and Spain where biological agent establishment avoids open-field degradation pressures. Go-to-market through precision agriculture platform partnerships rather than traditional distribution. For Investors and Strategic Acquirers: EPA's streamlined FIFRA Section 3 microbial registration pathway reshapes the acquisition landscape by compressing development timeline risk for qualified submissions. Five-to-ten-year viability favors specialized microbial strain developers with proprietary libraries and demonstrated fermentation scalability over formulation-only packagers. Signal to monitor: divergence between Codex Alimentarius residue standards and national import protocols threatening cross-border shipment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Jiangsu and Shandong hub expansion reduces feedstock cost exposure for integrated producers. |
| Precision Application Platform Partnership | Drone-based variable-rate delivery convergence collapses input-supplier and service-provider boundaries. |
| Residue-Free Certification Pathway Investment | EU supermarket chain procurement standards mandate biological input documentation for import qualification. |
| Microencapsulated Formulation R&D Scale-Up | Polymer-shell systems address UV degradation constraints in Brazilian Cerrado open-field deployment. |
| Grower-Cooperative Channel Control | Iowa and Illinois cooperative aggregation secures volume demand for bacterial concentrate tank mixes. |
Methodological Framework
Desk research of EPA registration databases, ANVISA import approval records, and REACH botanical substance dossiers preceded structured interviews with fermentation plant managers, biologicals distribution channel partners, grower-cooperative procurement leads, and precision agriculture platform engineers. Secondary validation drew from FIFRA Section 3 filing disclosures, ECHA environmental fate assessments, and customs trade data for microbial concentrate shipments. Bottom-up strain library valuations and top-down market size triangulation anchored segmentation outputs.
Assumptions held fixed include EPA review timeline compression at 18 months for qualified microbial submissions, REACH extraction protocol standardization sustaining botanical cross-border equivalence, and ANVISA accelerated pathways maintaining current throughput. Segmentation dimensions spanned bacterial-fungal-plant extract categories, liquid-granular-microencapsulated formats, and organic-conventional-greenhouse end uses. CAGRs were derived from installed fermentation capacity expansion curves and certification-driven procurement adoption rates across EU import markets.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, EU carbon border adjustment implementation, or Yangtze River basin environmental compliance enforcement would shift the trajectory. Forecasts reflect these assumptions without claiming certainty. Cross-checking against USDA NASS pesticide use surveys and EUROSTAT organic farming penetration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Brazil Biofertilizers Market