
 Canada Biofertilizers Market | 2026-2036
Canada Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Biofertilizers Market Insights
A capital-intensity divergence between small-batch fermentation specialists and large-scale nutrient conglomerates is redrawing competitive boundaries in the Canada biofertilizers sector. Lallemand Inc. leverages decades of yeast and bacteria cultivation expertise to dominate live culture supply chains for regional formulators. Nutrien Ltd anchors its position through backward integration into struvite recovery and in-house production of carrier materials for microbial delivery systems.
Canada biofertilizers comprise living or dormant microorganisms—primarily nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant-growth-promoting rhizobacteria—formulated in liquid suspensions, solid peat or lignite carriers, or compost-based matrices with guaranteed minimum colony-forming units per gram. These products colonize the rhizosphere to enhance nutrient mineralization and phytohormone production, serving as registered alternatives or complements to synthetic fertilizers in certified organic and conventional cropping systems. Liquid biofertilizers command premium shelf space in horticultural channels where ease of fertigation integration justifies higher per-hectare costs, while solid formulations occupy volume leadership in Prairie grain operations where mechanical spreading equipment predominates. Microbial inoculants for pulse crops sustain the fastest growth trajectory as Saskatchewan pea and lentil acreage expands under zero-till protocols that favor rhizobia establishment.
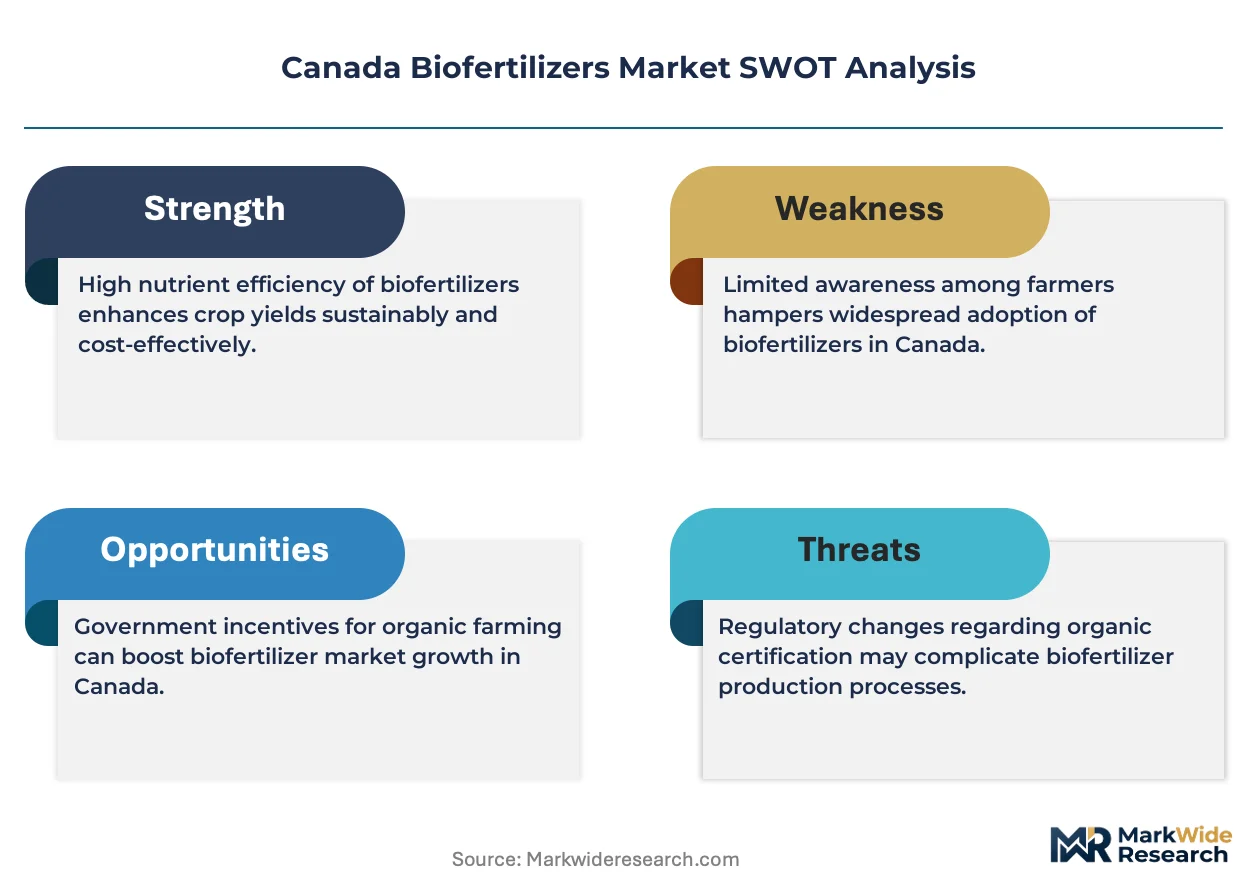
Health Canada's PMRA and the Canadian Food Inspection Agency jointly govern biofertilizer registration, with CFIA's Fertilizer Safety Section mandating guaranteed analysis labeling and contaminant limits that shape product development timelines and reformulation costs. Provincial environmental regulations in Alberta and Manitoba restrict synthetic nitrogen application rates near Lake Winnipeg and the Bow River basin, redirecting commercial farm expenditure toward verified biological alternatives. Stakeholders must monitor pending federal carbon offset protocol eligibility for biological nitrogen fixation, as certification would restructure farm-level procurement economics and distributor incentive programs.
Market Dynamics
Health Canada's PMRA efficacy verification protocols are compressing product development timelines while redirecting R&D investment toward guaranteed colony-forming unit stability in Prairie storage conditions.
Growth Catalysts
- Zero-till pulse expansion:Saskatchewan pea and lentil acreage under conservation tillage creates favorable rhizosphere conditions for microbial inoculant establishment.
- CFIA contaminant limits:Stricter heavy metal and pathogen thresholds for biological soil amendments accelerate formulator investment in quality-controlled production infrastructure.
- Watershed nitrogen restrictions:Alberta and Manitoba regulations limiting synthetic nitrogen near Lake Winnipeg and the Bow River basin redirect farm expenditure toward verified biological alternatives.
Market Restraints
- Live culture supply concentration:Dependence on specialized fermentation capacity in Quebec and Ontario creates geographic vulnerability for Prairie formulators.
- Carrier material cost volatility:Peat and lignite sourcing faces pressure from competing horticultural and energy sector demand.
- Shelf-life technical ceiling:Liquid suspension viability degrades below guaranteed CFIA thresholds within 12-18 months under variable Prairie temperature cycles.
Strategic Opportunities
- Carbon offset protocol eligibility:Pending federal certification for biological nitrogen fixation would restructure farm-level procurement economics and distributor incentive programs.
- Conservation agriculture integration:Cover crop seed coating applications in Manitoba represent underdeveloped channels for phosphate-solubilizing fungal formulations.
- Fertigation channel development:British Columbia greenhouse and orchard operations offer premium positioning for liquid biofertilizer direct injection systems.
Industry Challenges
- Microbiologist talent scarcity:Formulation science and rhizosphere ecology expertise concentrates in academic institutions with limited industry pipeline capacity.
- CFIA registration timeline compression:Guaranteed analysis verification and efficacy field trials extend product launch cycles beyond conventional fertilizer development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Biofertilizers Market |
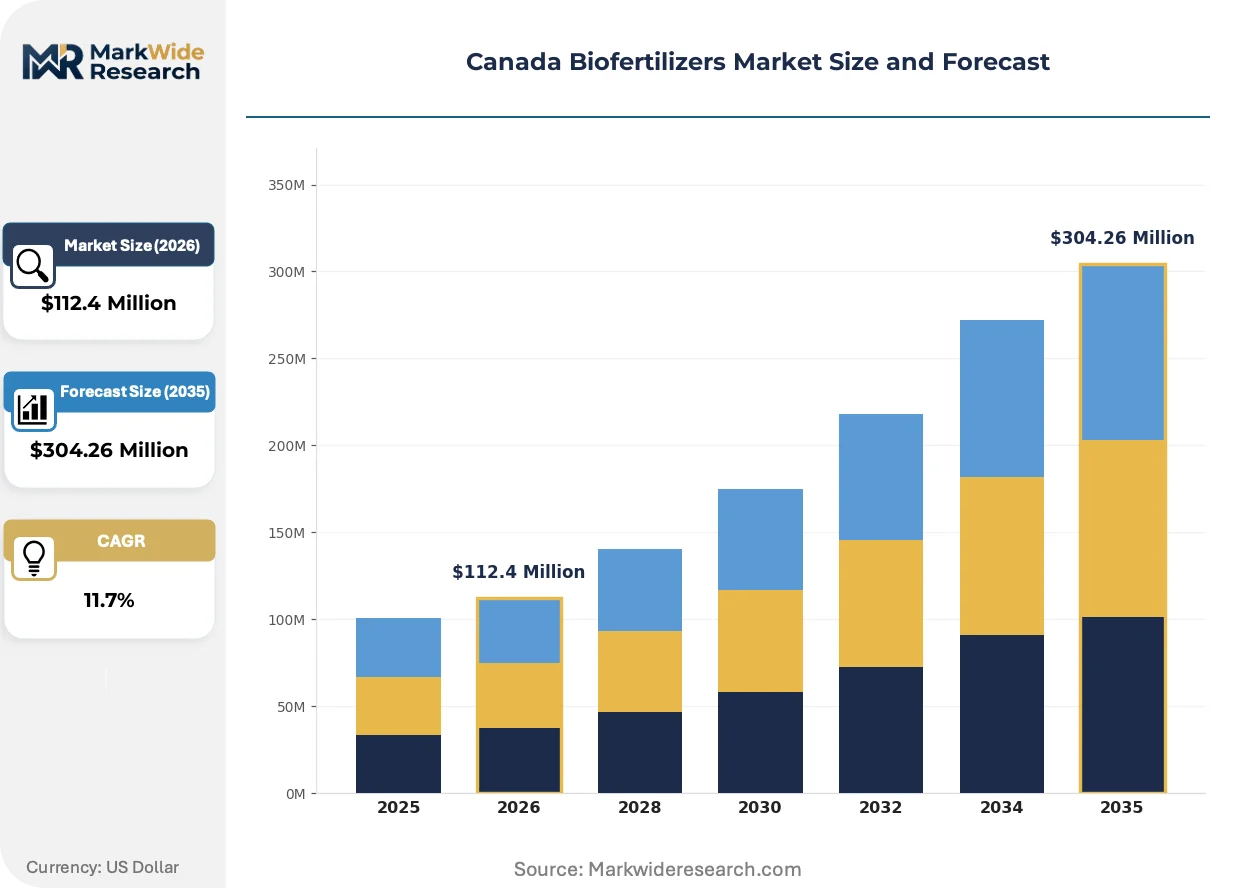
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $304.26 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Solid Biofertilizers, Microbial Inoculants, Composts End Use Industry: Agriculture, Horticulture, Turf Management, Organic Farming Distribution Channel: Online Stores, Retail Outlets, Agricultural Cooperatives, Direct Sales Application Method: Soil Application, Seed Treatment, Foliar Spray, Drip Irrigation |
| Companies Covered | Agrinos, BioWorks Inc, Nurture Growth Biofertilizer Inc., Symborg Inc., Agrium Inc, Lallemand Inc., Nutrien Ltd, Novonesis, Novozymes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Biofertilizers Market Trends and Innovations
Biological nitrogen fixation technologies are advancing from standalone inoculants toward integrated crop nutrition systems that combine microbial consortia with precision application hardware.
Encapsulation technology using alginate and polymeric matrices is decomposing traditional peat carrier dominance by extending liquid culture viability through temperature fluctuations. Prairie grain cooperatives are piloting these formulations for pre-seed treatment compatibility with high-speed planting equipment. This shift is decomposing established supply relationships between formulators and bulk peat processors.
Health Canada's PMRA and CFIA joint registration framework is tightening efficacy documentation requirements for nitrogen-fixing products, forcing manufacturers to conduct multi-site field trials across Saskatchewan, Alberta, and Manitoba growing zones. The Prairie provinces face the steepest compliance burden as regional soil temperature variability demands expanded trial protocols.
Direct-to-farm digital procurement platforms are fragmenting traditional distributor networks for microbial inoculants. Alberta grain operations are adopting subscription-based replenishment models for rhizobia products tied to crop rotation schedules. This pattern concentrates in large-scale zero-till operations where input planning integrates with farm management software systems.
Canada Biofertilizers Market Segmentation
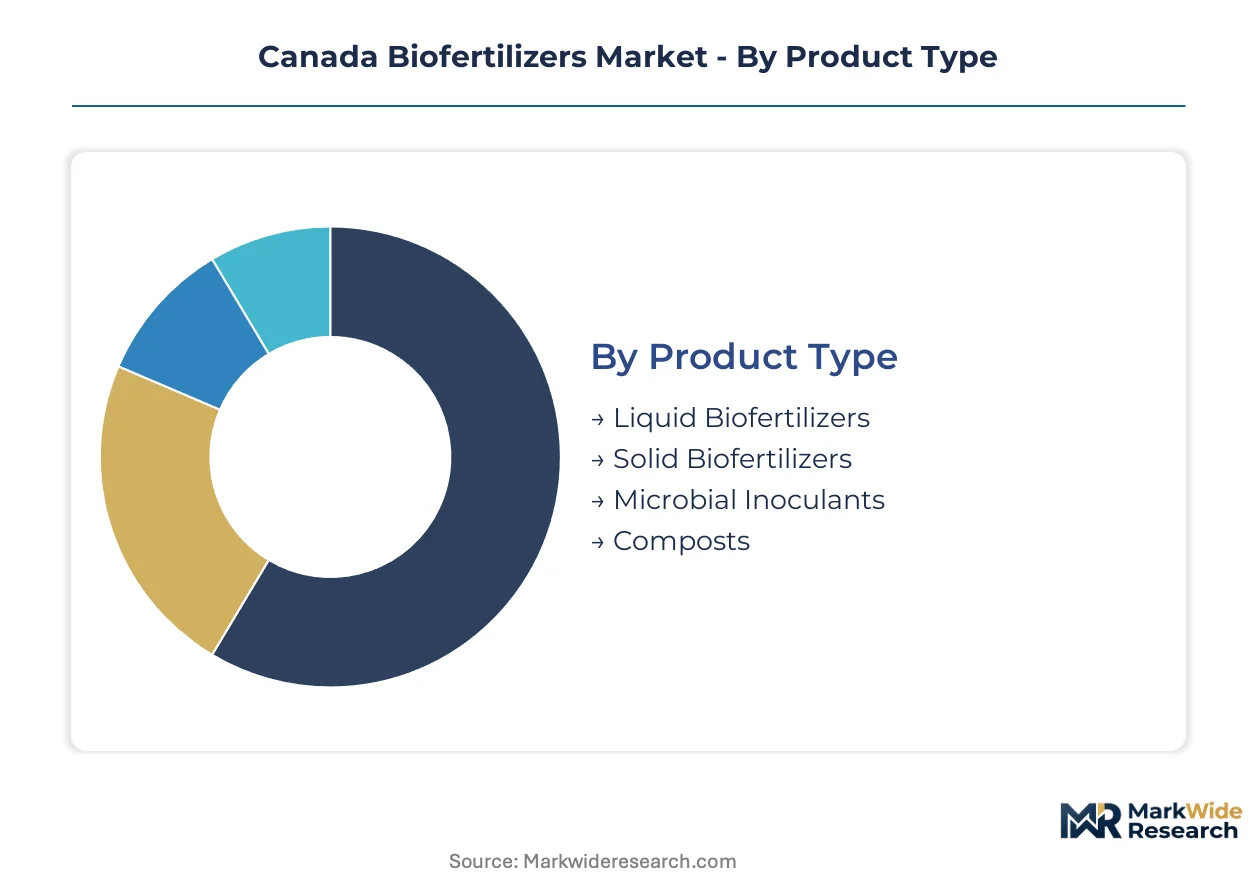
Product configuration and delivery method choices in the Canada biofertilizers sector reflect Prairie storage constraints, CFIA stability requirements, and the mechanical spreading preferences of large-scale grain operations. Segmentation strategy determines which formulators capture volume leadership versus premium positioning.
Product Type:
Domestic Prairie demand drives solid formulation volumes, while British Columbia greenhouse and orchard exports pull liquid concentrate production toward Pacific distribution channels.
- Liquid Biofertilizers:Suspensions of nitrogen-fixing bacteria and phosphate-solubilizing fungi in aqueous carriers with guaranteed colony-forming units per milliliter. British Columbia greenhouse operators and Okanagan orchardists concentrate procurement here, drawn by fertigation integration and drip line compatibility that justifies per-hectare premiums.
- Solid Biofertilizers:Peat, lignite, or compost-based matrices embedding dormant microbial cultures with mechanical spreader compatibility. Saskatchewan and Alberta grain operations under zero-till protocols anchor demand, where temperature-stable storage through Prairie winters outweighs application labor costs.
- Microbial Inoculants:Pure culture preparations of rhizobia and plant-growth-promoting rhizobacteria for pulse crop seed coating. Saskatchewan pea and lentil acreage expansion sustains fastest uptake.
- Composts:Decomposed organic matter amended with targeted microbial consortia. Organic certified operations in Manitoba and Ontario drive procurement.
Solid biofertilizers command the established base. The steepest expansion runs through microbial inoculants.
End Use Industry:
Cost tier separation distinguishes commodity grain operations from premium horticultural channels, with organic certification premiums restructuring procurement economics.
- Agriculture:Large-scale Prairie grain and oilseed operations deploying biological nitrogen fixation as synthetic fertilizer complement or replacement. Alberta and Saskatchewan zero-till acreage concentrates volume demand, pressured by watershed nitrogen restrictions near Lake Winnipeg and the Bow River basin.
- Horticulture:Greenhouse vegetable, nursery, and high-value fruit operations requiring precision nutrient delivery. British Columbia's Lower Mainland and Niagara Peninsula greenhouses drive premium liquid formulation uptake.
- Turf Management:Golf course, municipal park, and sports field maintenance. Urban centers in Ontario and Quebec sustain steady demand.
- Organic Farming:Certified operations prohibited from synthetic inputs. Prairie organic acreage expansion and CFIA-approved input lists shape procurement.
Agriculture captures volume leadership. Horticulture climbs the fastest on per-hectare value metrics.
Distribution Channel:
Customer type fragmentation separates cooperative-member grain operations from independent horticultural growers, with digital platforms disrupting traditional supply relationships.
- Online Stores:Direct-to-farm digital procurement platforms with subscription replenishment tied to crop rotation schedules. Alberta zero-till operations integrate these with farm management software systems.
- Retail Outlets:Farm supply stores and garden centers serving small-scale horticultural and organic producers. Urban and peri-urban concentration in Ontario and Quebec.
- Agricultural Cooperatives:Member-owned purchasing networks dominating Prairie grain input distribution. Saskatchewan and Alberta wheat pools and pulse grower associations anchor volume.
- Direct Sales:Manufacturer relationships with large-scale greenhouse and organic operations. British Columbia and Ontario specialty crop producers prefer technical support integration.
Agricultural cooperatives hold the volume core. Online stores gain share fastest through digital procurement adoption.
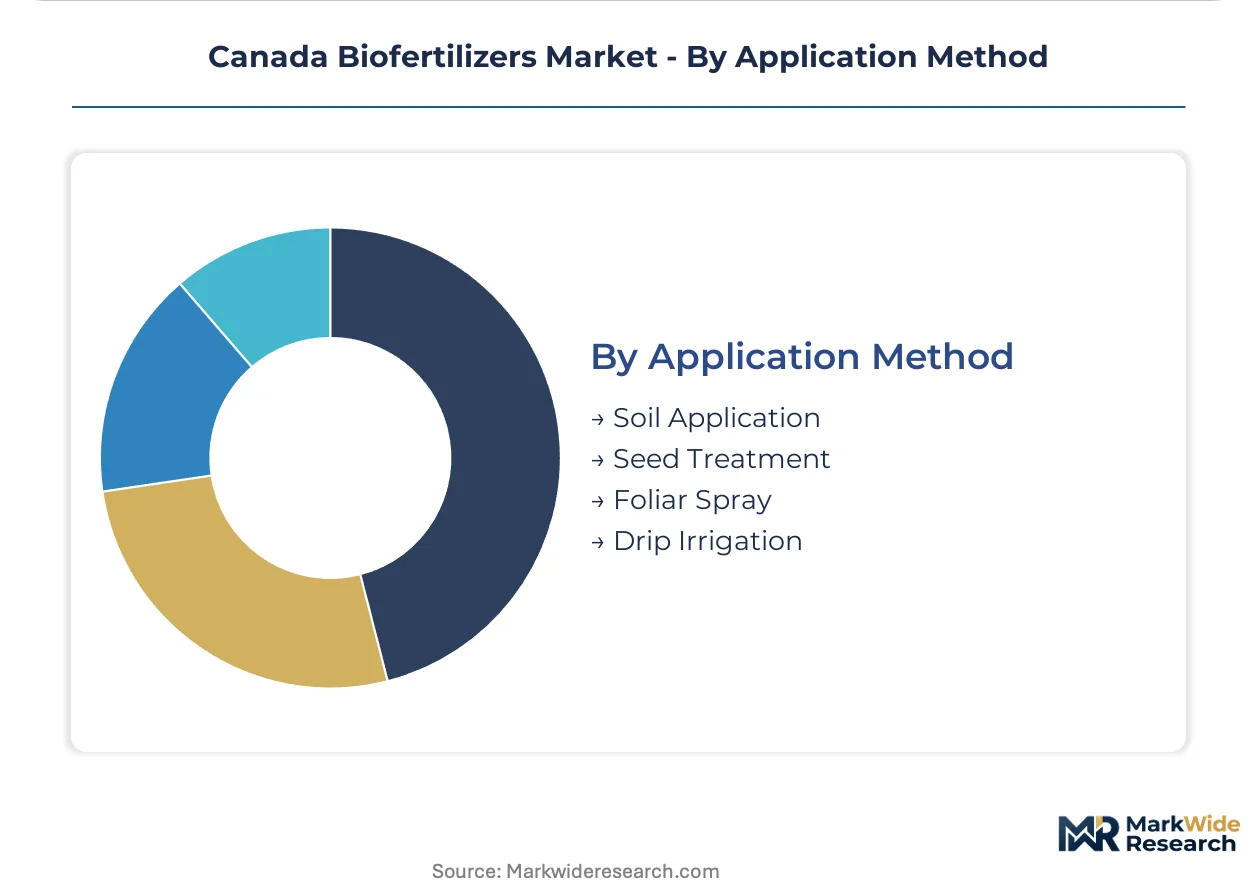
Application Method:
Supply concentration in Quebec and Ontario fermentation capacity shapes which application methods Prairie formulators can reliably serve.
- Soil Application:Broadcast or banded incorporation of solid biofertilizers into root zones. Prairie grain equipment fleets and conservation tillage compatibility sustain dominance.
- Seed Treatment:Microbial inoculant coating applied at planting. High-speed planter compatibility and rhizobia establishment timing drive pulse crop adoption in Saskatchewan.
- Foliar Spray:Liquid suspension application to plant surfaces. British Columbia greenhouse and orchard premium channels concentrate here.
- Drip Irrigation:Direct injection into fertigation systems. Technical integration requirements limit uptake to advanced horticultural operations.
Soil application maintains the installed base. Seed treatment expands most quickly through pulse acreage growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie grain operations in Saskatchewan and Alberta exhibit the highest price elasticity, while British Columbia greenhouse growers absorb premiums for fertigation-compatible liquid formulations. Ontario's organic sector occupies a mid-tier position where certification premiums partially offset cost sensitivity.
Prairie Provinces
Zero-till pulse expansion across Saskatchewan pea and lentil acreage generates concentrated demand for rhizobia inoculants. Health Canada's PMRA mandates multi-site field trials across these growing zones, extending registration timelines. Saskatoon and Regina anchor microbial formulation distribution networks serving regional wheat pools.
British Columbia
Greenhouse vegetable and Okanagan orchard operations prioritize drip-line compatible liquid suspensions over cost minimization. Provincial environmental regulations on Fraser Valley nutrient discharge accelerate biological alternative verification. The Lower Mainland concentrates technical service infrastructure for precision fertigation integration.
Ontario
Organic certification premiums in the Niagara Peninsula and Eastern Ontario restructure procurement economics toward CFIA-approved input lists. The Canadian Food Inspection Agency's Fertilizer Safety Section labeling requirements shape local formulator compliance investments. Toronto-Waterloo corridor fermentation specialists supply live cultures eastward.
Alberta
Bow River basin nitrogen restrictions redirect large-scale grain expenditure toward verified biological alternatives. Direct-to-farm digital procurement platforms fragment traditional cooperative distribution in zero-till zones. Calgary-Edmonton corridor anchors subscription-based replenishment models tied to crop rotation software.
Canada Biofertilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into carrier materials and live culture supply distinguishing the upper stratum. Nutrien Ltd leverages captive struvite recovery and in-house production of microbial delivery matrices. Lallemand Inc anchors fermentation capacity for regional formulators. Mid-tier players concentrate on application-specific formulations for pulse crops and horticultural channels. Competitive moves center on quality-controlled production infrastructure investment and direct-to-farm digital platform development.
Within the integrated tier, Nutrien Ltd and Lallemand Inc occupy positions defined by upstream control over critical inputs. Nutrien Ltd exemplifies the nutrient conglomerate archetype through captive supply of carrier materials. Lallemand Inc represents the live culture specialist model with decades of yeast and bacteria cultivation expertise. Among formulation-focused enterprises, BioWorks Inc sits within the horticultural channel specialization vector. These three anchors illustrate how competitive positioning stratifies across raw material control, technical service depth, and digital procurement integration.
| Leading Market Players |
|---|
| Agrinos |
| BioWorks Inc |
| Nurture Growth Biofertilizer Inc. |
| Symborg Inc. |
| Agrium Inc |
| Lallemand Inc. |
| Nutrien Ltd |
| Novonesis |
| Novozymes |
| Others |
Pricing and Supply Chain Analysis
Encapsulation technology displacing peat carriers redistributes production capacity toward Quebec fermentation specialists while compressing per-unit margins for legacy bulk processor relationships. This substitution simultaneously fragments Prairie formulator supply geography and intensifies price competition between temperature-stable liquid formulations and traditional solid matrices.
Pricing Analysis
Subscription replenishment revenue tied to crop rotation software drives lifetime value in Alberta zero-till operations. Three-tier pricing structure across premium liquid concentrates, standard solid formulations, and economy-grade compost amendments separates British Columbia greenhouse operators from Prairie grain cooperatives. Cost compression in solid formulations intensifies as peat sourcing competition from horticultural channels escalates. Agricultural cooperatives exhibit highest price sensitivity while greenhouse operators absorb premiums for fertigation compatibility.
Supply Chain Analysis
Inventory lead times for live culture concentrates extend through Quebec and Ontario fermentation capacity concentration. Quebec and Ontario fermentation specialists anchor upstream supply for Prairie formulators, drawing from lignite deposits in Alberta and peat bogs in Manitoba. Single-source vulnerability concentrates in specialized bacterial strain propagation. Distribution runs through agricultural cooperatives in Saskatchewan and Alberta, supplemented by direct-to-farm digital platforms fragmenting traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large-scale Prairie grain cooperatives consolidating procurement through digital platforms, compressing distributor margins and restructuring incentive structures for microbial inoculant suppliers.
For Market Incumbents: Shield formulation margins by securing captive peat and lignite reserves through backward integration into Alberta and Manitoba carrier material deposits. Invest in quality-controlled production infrastructure to preempt CFIA contaminant threshold tightening. Channel control through cooperative purchasing agreements defends against direct-to-farm platform fragmentation. For New Entrants and Emerging Players: Anchor in British Columbia greenhouse fertigation channels where technical service integration commands premium positioning and incumbent presence remains thin. Manitoba cover crop seed coating applications represent underpenetrated white space for phosphate-solubilizing fungal formulations. A go-to-market angle emphasizing precision application hardware compatibility bypasses established Prairie cooperative relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation capacity specialists with live culture supply relationships. Long-term viability over the coming decade hinges on carbon offset protocol eligibility certification restructuring farm-level procurement economics. Acquisition targets should demonstrate Quebec or Ontario fermentation infrastructure and established CFIA registration track records. The signal to watch is federal biological nitrogen fixation offset protocol finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carrier Materials | Captive lignite and peat reserves insulate Nutrien Ltd from horticultural sector sourcing competition. |
| Encapsulation Technology Scale-Up | Alginate matrix production extends liquid culture viability through Prairie temperature cycles. |
| Direct-to-Farm Digital Platform Launch | Subscription replenishment models integrate with Alberta grain operation farm management software. |
| Multi-Site Field Trial Investment | PMRA-mandated efficacy documentation across Saskatchewan, Alberta, and Manitoba accelerates registration timelines. |
| Carbon Offset Protocol Certification | Biological nitrogen fixation eligibility restructures distributor incentive programs and farm procurement economics. |
Research Methodology
Cross-validation between primary interviews with fermentation facility managers, CFIA regulatory affairs specialists, Prairie cooperative procurement directors, and greenhouse operations supervisors anchors the qualitative findings. Secondary validation draws from Health Canada PMRA registration databases, CFIA Fertilizer Safety Section labeling records, Prairie grain production statistics, and provincial environmental regulation filings. Bottom-up demand modeling triangulates against top-down market sizing across product type, end use industry, and distribution channel dimensions.
Sensitivity analysis around CFIA registration timeline compression and carbon offset protocol adoption rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, delivery method, end use industry tier, and regional growing zone regulatory cluster. CAGRs derive from volume trajectory analysis incorporating Prairie acreage expansion patterns and zero-till adoption curves. Industry-specific forecast inputs encompass rhizobia inoculant demand tied to Saskatchewan pulse crop rotation schedules and British Columbia greenhouse fertigation infrastructure investment.
Material uncertainties — pending federal carbon offset protocol eligibility, CFIA efficacy verification protocol amendments, and carrier material cost volatility — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and conservation agriculture adoption continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
GCC Biofertilizer Market