
 Japan Biofertilizer Market | 2026-2036
Japan Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Biofertilizer Market Intelligence
Japan's national carbon-neutrality commitment is pivoting agricultural input procurement toward microbial alternatives. OAT Agrio Co., Ltd. leverages its domestic fermentation infrastructure to supply specialized Rhizobium cultures for legume cultivation. EF Polymer KK anchors its position through biodegradable carrier technologies that extend microbial viability in field conditions. Nippon Biosoap Co., Ltd. competes across the organic waste-to-fertilizer conversion chain, integrating municipal compost streams into bio-organic formulations.
Biofertilizers are living microbial preparations containing bacteria, fungi, or algae that colonize plant rhizospheres to enhance nutrient availability through biological nitrogen fixation, phosphate solubilization, or phytohormone secretion; these formulations typically require cell counts exceeding 10^8 CFU per gram and are manufactured through submerged fermentation followed by stabilization in peat or liquid carriers. Liquid biofertilizers command premium shelf space in agricultural supply stores due to compatibility with Japanese precision irrigation systems, while nitrogen-fixing biofertilizers dominate volume flows into soybean and rice rotations. Compost-based segments occupy mature positions with thinner margins, whereas bio-organic fertilizer blends targeting JAS-certified organic operations sustain stronger pricing power.
METI's Green Growth Strategy and the Ministry of Agriculture, Forestry and Fisheries' environmental labeling standards shape product registration pathways and subsidy eligibility for domestic manufacturers. JAS organic certification requirements and Fertilizer Regulation Act amendments restrict synthetic additive thresholds, compelling reformulation investments across the supply base. Stakeholders must monitor prefectural soil health incentive programs and evolving bio-input quality benchmarks to secure channel positioning ahead of regulatory tightening.
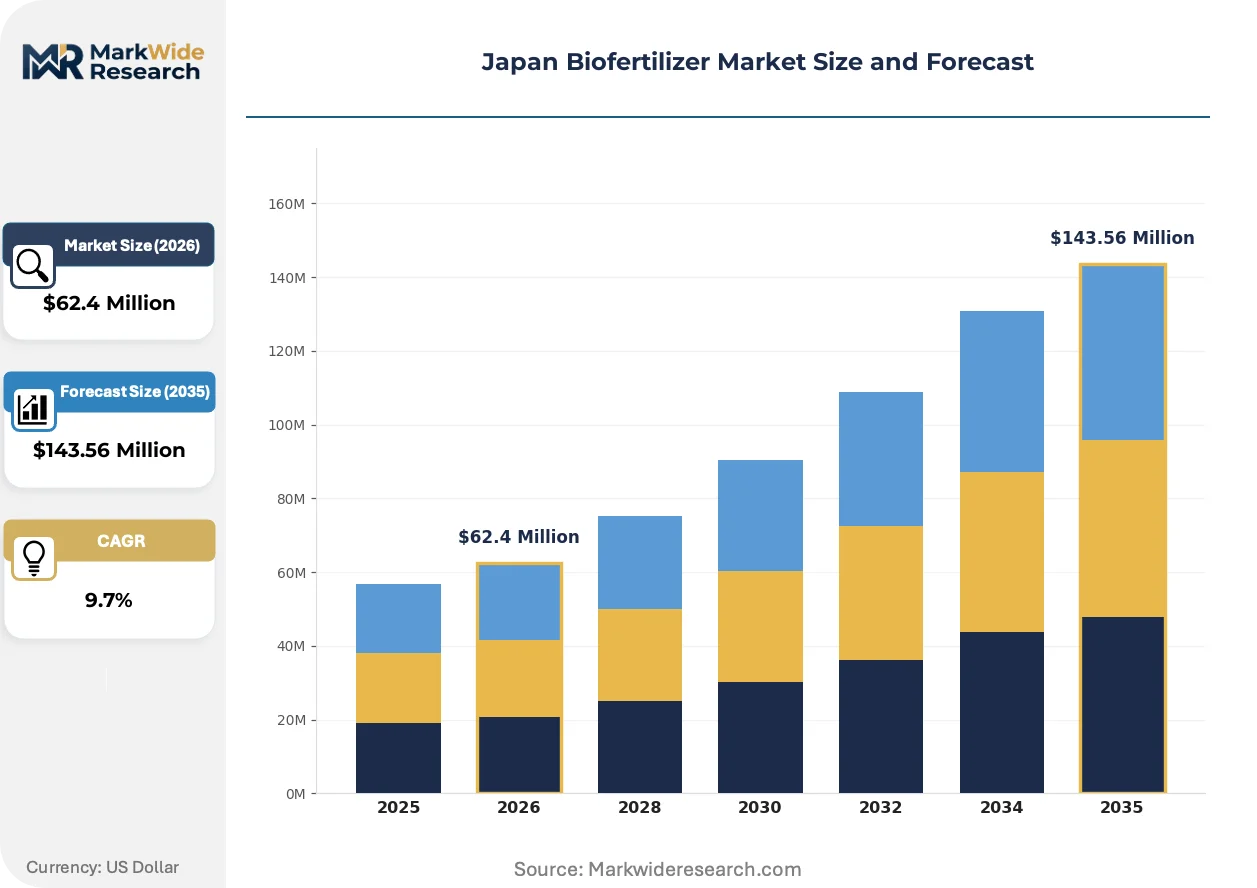
Market Dynamics
METI's Green Growth Strategy is compressing chemical fertilizer procurement timelines across Japan's agricultural cooperatives, forcing rapid reformulation of input supply chains toward microbial alternatives. This regulatory pivot is restructuring competitive positioning around fermentation capacity and JAS certification pathways.
Growth Catalysts
- Nitrogen-Fixing Microbial Formulations:Rice farming cooperatives in Hokkaido are expanding Rhizobium and Azospirillum inoculant use to meet soil health targets under prefectural environmental incentive programs.
- Peri-Urban Protected Horticulture:Tokyo's vegetable belt is absorbing liquid biofertilizer volumes compatible with precision drip irrigation systems serving JAS-certified organic operations.
- Fertilizer Regulation Act Amendments:Tighter synthetic additive thresholds are compelling conventional fertilizer blenders to integrate bio-organic components to maintain product registration eligibility.
Market Restraints
- Peat Carrier Supply Concentration:Domestic sourcing of sterilized peat for microbial stabilization depends on limited Hokkaido extraction operations, creating input bottlenecks during spring planting windows.
- Technical Shelf-Life Constraints:Liquid formulations require cold-chain distribution to maintain cell viability above 10^8 CFU per gram, restricting rural market penetration.
- Compost-Based Segment Margin Compression:Mature municipal waste-to-fertilizer conversion operations face pricing pressure from subsidized chemical alternatives in conventional rice rotations.
Strategic Opportunities
- Tohoku Soil Health Incentives:Prefectural programs targeting degraded paddy fields are creating dedicated procurement channels for phosphate-solubilizing bacterial formulations.
- Biodegradable Carrier Convergence:Integration of microbial cultures with polymer-based extended-release matrices is opening protected cultivation applications beyond traditional peat carriers.
- Direct-to-Cooperative Distribution:Agricultural supply stores are consolidating bio-input procurement for rice farming associations, bypassing conventional wholesaler markups.
Industry Challenges
- Microbial Strain Registration Timelines:MAFF quality benchmarks require multi-season field validation studies, extending product commercialization cycles for novel bacterial isolates.
- Fermentation Scale-Up Capex:Submerged bioreactor infrastructure for industrial-scale inoculant production demands capital commitments that strain mid-tier domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Biofertilizer Market |
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $143.56 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Liquid Biofertilizers, Bio-Organic Fertilizers, Nitrogen-Fixing Biofertilizers Application: Agronomy, Horticulture, Forestry, Turf Management End User: Farmers, Agricultural Cooperatives, Research Institutions, Nursery Owners Distribution Channel: Online Retail, Wholesale Distributors, Agricultural Supply Stores, Direct Sales |
| Companies Covered | OAT Agrio Co., Ltd., EF Polymer KK, Nippon Biosoap Co., Ltd., Mapleton Agri Biotech Pty Ltd., SDS Biotech, T. Stanes & Company Ltd., Chubu Ecotec Co., Ltd., TAISEINOZAI, Seiwa Fertilizer Industry Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Biofertilizer Market Strategic Shifts & Innovations
Japan's biofertilizer sector is absorbing fermentation technology advances and carrier material science to extend microbial viability under field conditions. These shifts are compressing product development cycles and reconfiguring supply relationships between agricultural cooperatives and input manufacturers.
Encapsulation technology is absorbing polymer science advances to protect nitrogen-fixing bacteria from desiccation and UV exposure in open-field applications. Protected horticulture operations around Osaka and Nagoya are adopting alginate-matrix formulations at accelerating rates. This innovation is absorbing premium positioning from conventional liquid carriers by enabling reduced application frequency.
METI's Green Growth Strategy implementation guidelines are tightening chemical fertilizer reduction targets for rice and soybean rotations. The industrial consequence is mandatory procurement quota adjustments across agricultural cooperatives in Hokkaido and Tohoku. Liquid biofertilizer segments are responding with expanded technical service teams to assist cooperatives in irrigation system calibration.
Buyer concentration among rice farming associations is consolidating procurement decisions into fewer agricultural cooperative federations with dedicated bio-input specialists. Traditional agricultural supply stores are losing share to direct technical partnerships between manufacturers and cooperative agronomists. This pattern is most visible in Hokkaido's large-scale mechanized farming districts where input standardization across member farms is accelerating.
Japan Biofertilizer Market Segmentation
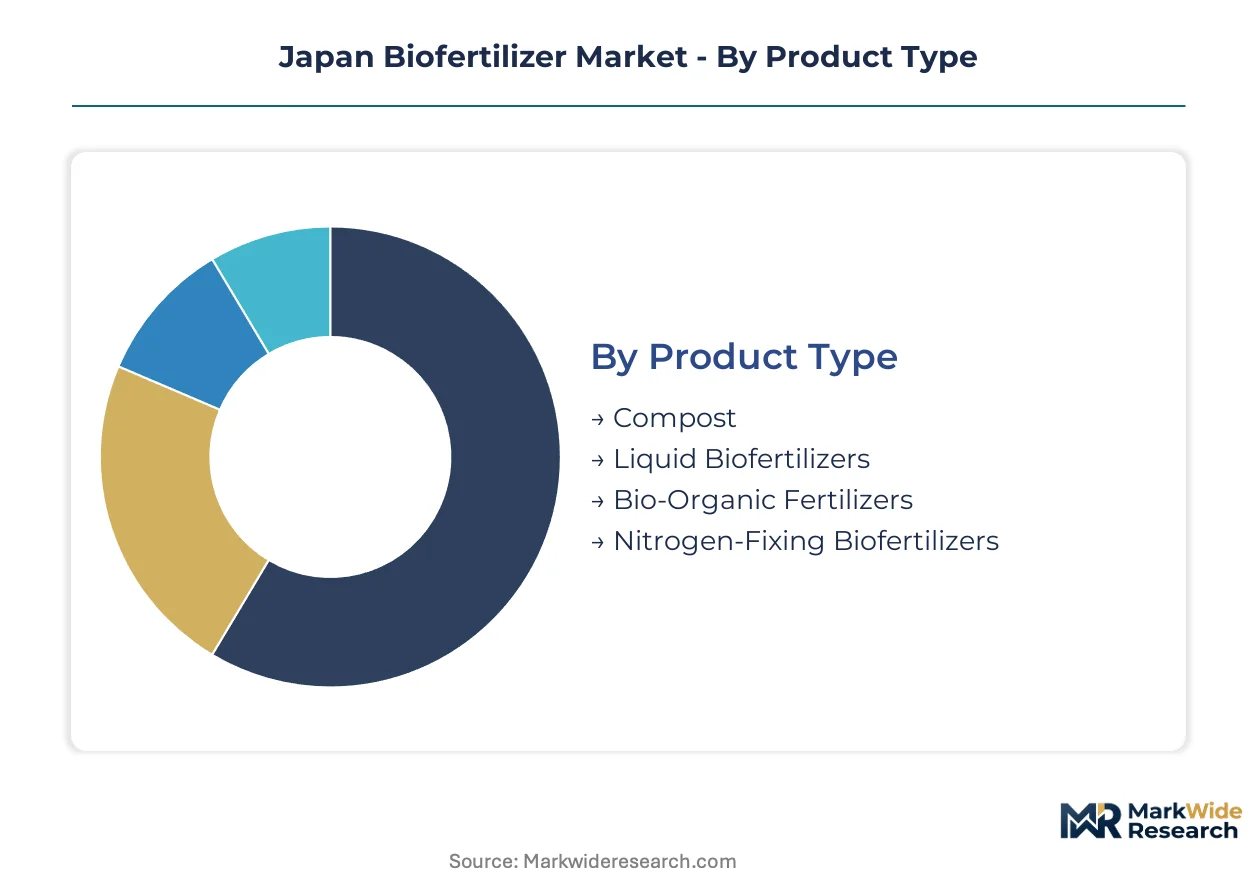
Segmentation in Japan's biofertilizer market reveals how microbial input procurement diverges between integrated cooperative systems and fragmented independent operations. Understanding these divides exposes where fermentation capacity investments concentrate and which distribution pathways command premium positioning.
Product Type:
Standalone microbial formulations dominate precision agriculture applications, while embedded bio-organic blends serve broader soil amendment programs across Japan's farming cooperatives.
- Nitrogen-Fixing Biofertilizers:Living preparations of Rhizobium, Azospirillum, or Azotobacter cultures with cell counts exceeding 10^8 CFU per gram. Hokkaido rice farming cooperatives are absorbing volumes under prefectural soil health incentive programs targeting chemical fertilizer reduction mandates.
- Liquid Biofertilizers:Submerged fermentation products stabilized in aqueous carriers for precision irrigation compatibility. Tokyo's peri-urban vegetable belt demands these formulations for JAS-certified protected horticulture operations requiring drip system integration.
- Compost:Municipal organic waste conversion outputs with mature microbial communities. Pricing pressure from subsidized chemical alternatives constrains margins in conventional rice rotations.
- Bio-Organic Fertilizers:Blended formulations combining microbial inoculants with organic matter substrates. JAS certification requirements sustain stronger pricing power than standalone compost segments.
Nitrogen-fixing formulations lead volumes today; liquid biofertilizers are gaining share fastest.
Application:
Protected cultivation systems absorb premium microbial inputs, while open-field agronomy drives volume procurement through cooperative aggregation.
- Agronomy:Large-scale row crop and paddy field applications dominate tonnage flows. Tohoku rice cooperatives are expanding phosphate-solubilizing bacterial procurement under degraded soil recovery programs.
- Horticulture:Protected vegetable and fruit cultivation in greenhouse environments. Osaka and Nagoya metropolitan supply zones demand alginate-matrix encapsulated formulations for reduced application frequency.
- Forestry:Reforestation and plantation establishment uses. Limited commercial penetration outside government-funded restoration projects.
- Turf Management:Golf course and sports field maintenance applications. Niche positioning with concentrated demand in Greater Tokyo and Kansai urban corridors.
Agronomy commands absolute volume; horticulture shows the steepest expansion trajectory.
End User:
Procurement concentration among cooperative federations is displacing fragmented independent farmer purchasing across Japan's major agricultural regions.
- Agricultural Cooperatives:Federated purchasing bodies aggregating input demand across member farms. Hokkaido's mechanized farming districts are consolidating bio-input procurement through dedicated agronomist partnerships.
- Farmers:Independent operators purchasing through retail channels. Cold-chain distribution requirements for liquid formulations restrict rural market penetration.
- Research Institutions:Universities and MAFF-affiliated stations conducting strain validation studies. Multi-season field trials extend product commercialization timelines for novel bacterial isolates.
- Nursery Owners:Specialized propagation operations requiring consistent microbial inoculation. Limited scale relative to field crop segments.
Agricultural cooperatives dominate procurement value; research institutions anchor technology validation pipelines.
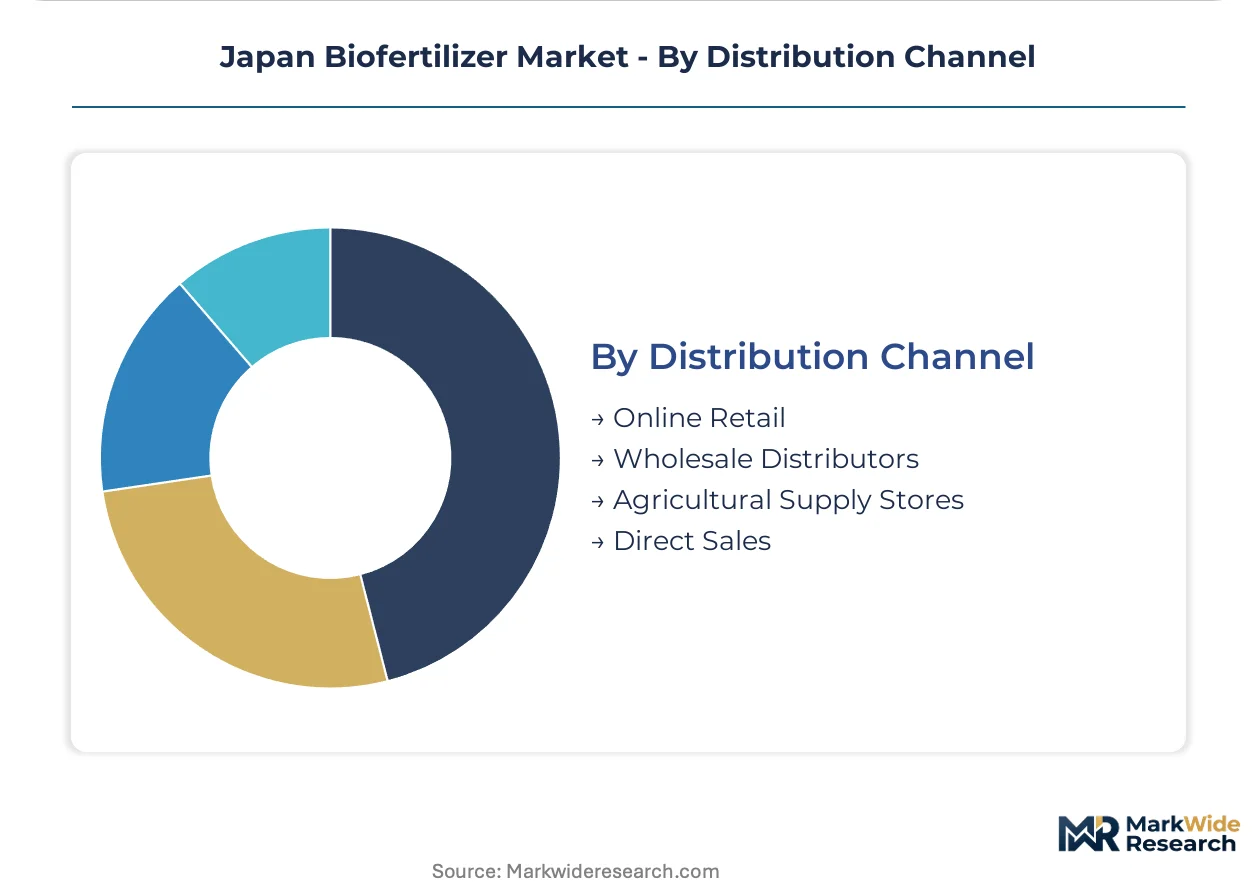
Distribution Channel:
Channel structure reflects the technical service intensity required for microbial input deployment versus commodity fertilizer transactions.
- Direct Sales:Manufacturer-to-cooperative technical partnerships with dedicated agronomist support. Bypassing wholesaler markups accelerates in Hokkaido and Tohoku rice belt consolidation.
- Agricultural Supply Stores:Traditional retail points losing share to direct manufacturer relationships. Retain relevance for independent farmers outside cooperative membership.
- Wholesale Distributors:Intermediary layers facing margin compression as cooperatives consolidate procurement. Concentrated in legacy chemical fertilizer distribution networks.
- Online Retail:E-commerce platforms serving small-scale operators and specialty crop producers. Limited penetration for temperature-sensitive liquid formulations requiring cold-chain integrity.
Direct sales channels capture the fastest volume growth; agricultural supply stores retain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's biofertilizer talent concentrates in fermentation engineering clusters across Hokkaido and Tohoku, where agricultural cooperative technical staff coordinate microbial inoculant deployment. Prefectural soil health programs anchor demand generation in these northern farming belts.
Hokkaido
Rice farming cooperatives in Hokkaido absorb nitrogen-fixing Rhizobium and Azospirillum formulations under METI's Green Growth Strategy chemical reduction mandates. The prefectural government operates soil health incentive programs targeting degraded paddy fields. Large-scale mechanized farming districts around Obihiro and Asahikawa consolidate bio-input procurement through dedicated agronomist partnerships with manufacturers.
Tohoku
Degraded soil recovery programs in Tohoku drive phosphate-solubilizing bacterial procurement through agricultural cooperative federations. MAFF environmental labeling standards shape product registration eligibility for domestic manufacturers supplying the region. The Sendai agricultural corridor aggregates demand from rice rotations across Miyagi and Yamagata prefectures.
Kanto
Tokyo's peri-urban vegetable belt commands liquid biofertilizer volumes compatible with precision drip irrigation systems serving JAS-certified organic operations. The Fertilizer Regulation Act amendments tighten synthetic additive thresholds for products entering protected horticulture supply chains. Chiba and Ibaraki greenhouse clusters absorb alginate-matrix encapsulated formulations for reduced application frequency.
Kansai
Osaka and Nagoya metropolitan supply zones demand encapsulated nitrogen-fixing formulations for protected cultivation operations. Municipal organic waste conversion streams in Kyoto and Osaka prefectures feed compost-based segments facing margin pressure from subsidized chemical alternatives. Biodegradable carrier technologies from regional polymer specialists extend microbial viability in greenhouse applications.
Kyushu
Soybean rotations in Kyushu absorb Rhizobium inoculant volumes as agricultural cooperatives adjust procurement quotas under national carbon-neutrality commitments. Prefectural extension services coordinate technical calibration of precision irrigation systems for liquid biofertilizer deployment. The Fukuoka-Tosu industrial corridor hosts fermentation infrastructure supplying specialized cultures for legume cultivation.
Japan Biofertilizer Market Key Industry Players
Capital-heavy fermentation infrastructure operators compete with asset-light formulation specialists across Japan's biofertilizer supply base. The market structure tiers around submerged bioreactor ownership, JAS certification pathways, and direct cooperative relationships. Three archetypes dominate: integrated fermentation-to-field manufacturers, polymer-based carrier technology developers, and municipal waste-to-fertilizer conversion operators. Competitive moves concentrate on direct-to-cooperative distribution bypasses and biodegradable carrier convergence with microbial cultures.
Among integrated fermentation specialists, OAT Agrio Co., Ltd. and Chubu Ecotec Co., Ltd. occupy positions anchored in domestic bioreactor infrastructure. EF Polymer KK exemplifies the carrier technology tier, representing biodegradable matrix developers extending microbial viability in field conditions. Nippon Biosoap Co., Ltd. sits within the organic waste conversion archetype, integrating municipal compost streams into bio-organic formulations. These three company types collectively map the competitive terrain: fermentation capacity owners, material science specialists, and circular economy operators.
| Leading Market Players |
|---|
| OAT Agrio Co., Ltd. |
| EF Polymer KK |
| Nippon Biosoap Co., Ltd. |
| Mapleton Agri Biotech Pty Ltd. |
| SDS Biotech |
| T. Stanes & Company Ltd. |
| Chubu Ecotec Co., Ltd. |
| TAISEINOZAI |
| Seiwa Fertilizer Industry Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Agricultural cooperative procurement consolidation across Hokkaido and Tohoku is forcing fermentation capacity owners to bundle technical agronomist services with microbial inoculant shipments, compressing standalone product margins while elevating solution-based pricing tiers.
Pricing Analysis
Bundled technical service contracts versus unbundled commodity biofertilizer sales now define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates JAS-certified organic formulations from conventional blends and municipal compost outputs. Price differentiation hinges on certification grade and after-sales irrigation calibration support. Pricing pressure stems from subsidized chemical fertilizer alternatives in conventional rice rotations. Independent farmers exhibit highest price sensitivity; large cooperative federations absorb premium tiers for guaranteed supply security.
Supply Chain Analysis
Sterilized peat substrate supply rests on limited Hokkaido extraction operations, creating spring planting bottlenecks for microbial stabilization carriers. Specialized fermentation equipment draws from domestic Japanese and select South Korean precision engineering sources. Cold-chain distribution for liquid formulations hinges on regional logistics networks with temperature-controlled integrity. Single-source vulnerability concentrates in peat carrier supply. Distribution runs through direct manufacturer-to-cooperative technical partnerships bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's biofertilizer sector functions as a stable compounder anchored by METI's irreversible chemical fertilizer reduction mandates, ensuring sustained procurement quota growth for microbial alternatives across agricultural cooperative systems.
For Market Incumbents: Deepen backward integration into domestic peat extraction and polymer-based biodegradable carrier production to defend against input bottlenecks and emerging material science competitors. Secure exclusive JAS certification pathways ahead of Fertilizer Regulation Act threshold tightening. Lock in multi-year direct technical partnerships with Hokkaido and Tohoku cooperative federations to entrench switching costs. For New Entrants and Emerging Players: Independent vegetable growers in Chiba and Ibaraki greenhouse clusters outside major cooperative membership represent the most penetrable buyer archetype for alginate-matrix encapsulated formulations with reduced application frequency. Target peri-urban protected horticulture operators seeking JAS certification compliance without cooperative procurement gatekeepers. Lead with precision irrigation compatibility and on-farm technical calibration services as the go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation infrastructure owners possessing submerged bioreactor scale and existing MAFF strain registration portfolios. Five-to-ten-year viability favors integrated manufacturers over standalone formulation blenders given capital intensity barriers. Monitor prefectural soil health incentive program budget allocations as the critical inflection signal for demand acceleration beyond baseline regulatory mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peat Extraction | Captive substrate supply secures microbial stabilization capacity against Hokkaido sourcing bottlenecks. |
| Biodegradable Carrier Technology Licensing | Polymer matrix partnerships extend microbial viability for protected horticulture applications beyond peat limitations. |
| Direct Cooperative Technical Partnerships | Bypassing agricultural supply store markups captures margin expansion in consolidated procurement channels. |
| JAS Certification Pre-Positioning | Early compliance with tightening organic additive thresholds locks in premium pricing tier eligibility. |
| Phosphate-Solubilizing Strain Registration | MAFF-validated bacterial isolates open Tohoku degraded soil recovery program procurement channels. |
Research Approach
Bottom-up agricultural cooperative procurement modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with agricultural cooperative agronomists, biofertilizer plant managers, MAFF regulatory affairs officers, and precision irrigation system engineers combined with secondary validation from MAFF environmental labeling standard filings, METI Green Growth Strategy implementation guidelines, prefectural soil health program budgets, and JAS organic certification registry data. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map microbial inoculant production volumes through application segments and distribution channels across the projection horizon. Segmentation dimensions include product type, cultivation system, end-user procurement structure, and regional regulatory incentive intensity. CAGRs derive from trend extrapolation of cooperative procurement quota adjustments and fermentation capacity expansion announcements. Industry-specific forecast inputs incorporate MAFF strain registration timelines and prefectural soil health incentive program budget trajectories.
Underlying measurement precision varies by segment; liquid biofertilizer and nitrogen-fixing formulation categories carry tighter precision than mature compost-based segments due to more concentrated buyer visibility. Forecasts reflect documented assumptions regarding METI mandate enforcement consistency and MAFF registration pathway stability. Material deviation in prefectural incentive program funding levels or Fertilizer Regulation Act amendment timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Biological Control Market