
 Latin America Biostimulants Market | 2026-2036
Latin America Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biostimulants Market Intelligence
A shift from single-source chemical suppliers toward multi-source biological input portfolios is repositioning procurement strategy across Latin American row-crop operations. Novozymes A/S leverages its enzyme fermentation expertise to dominate microbial inoculant supply chains in Brazil and Argentina. BASF SE sustains competitive pressure through integrated seed-treatment-to-foliar platforms that bundle biostimulants with conventional crop protection. Valagro SpA anchors its position in specialty fruit and vegetable segments through seaweed-extract formulations tailored to high-value export crops.
Biostimulants comprise substances and microorganisms applied to plants or soil to stimulate natural processes that enhance nutrient uptake, stress tolerance, and crop quality without direct pesticidal or fertilizing action; humic acid formulations typically contain 50-70% humic and fulvic acids derived from leonardite or peat oxidation. Microbial products lead volume demand in Brazil's soybean and corn systems where Bradyrhizobium and Trichoderma inoculants reduce nitrogen fertilizer rates. Seaweed extracts command premium positioning in Mexico's avocado and berry export sectors where residue limits from importing countries drive biological input substitution.
Brazil's MAPA oversees biostimulant registration under Law 14.785, while Mexico's SADER and COFEPRIS jointly regulate agricultural biologicals through the Fertilizantes, Fertilizantes Orgánicos y Sustratos standard; ANVISA in Brazil and Argentina's SENASA both scrutinize microbial strain safety for worker exposure and environmental release. These frameworks create compliance barriers that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor pending harmonization between Mercosur and Pacific Alliance registration protocols, as divergent approval timelines could fragment market access for new entrants.
Market Dynamics
Law 14.785 in Brazil is consolidating biostimulant registration under MAPA while Mexico's SADER tightens organic input certification, forcing suppliers to build dedicated regulatory affairs capabilities or exit formal channels. This regulatory compression favors established players with compliance infrastructure and raises barriers for microbial formulation entrants.
Growth Catalysts
- MAPA Registration Consolidation:Brazil's unified biostimulant framework under Law 14.785 eliminates state-level fragmentation, reducing approval timelines for microbial inoculants in soybean and corn systems.
- Export-Driven Residue Limits:Mexico's avocado and berry sectors face tightening MRL standards from US and EU buyers, accelerating biological input substitution for synthetic plant growth regulators.
- Bradyrhizobium Inoculant Adoption:Large-scale producers in Brazil's Cerrado are integrating rhizobia-based nitrogen fixation to reduce urea dependency amid volatile fertilizer import costs.
Market Restraints
- COFEPRIS-SADER Dual Approval:Mexico's joint regulatory oversight of agricultural biologicals creates overlapping compliance requirements that extend product launch timelines by 18-24 months.
- Strain Sourcing Concentration:Brazil's microbial inoculant industry relies on concentrated domestic fermentation capacity, creating supply vulnerability when ANVISA mandates additional safety screening.
- Seaweed Extract Import Dependency:Latin American processors depend on Ascophyllum nodosum harvested from North Atlantic coastlines, exposing formulators to freight cost volatility and currency fluctuation.
Strategic Opportunities
- Argentina's Underpenetrated Corn Belt:SENASA's evolving microbial strain guidelines create first-mover advantage for suppliers establishing local fermentation partnerships ahead of harmonized Mercosur standards.
- Digital Agronomy Integration:Biostimulant dosing protocols are converging with precision agriculture platforms, enabling variable-rate application tied to real-time soil microbiome monitoring.
- Pacific Alliance Regulatory Harmonization:Pending alignment between Chile, Colombia, Mexico and Peru on biological input standards would unlock cross-border formulation registration and regional scale economies.
Industry Challenges
- Microbial Strain Characterization:ANVISA and SENASA both require whole-genome sequencing for novel inoculant candidates, demanding capital investment in molecular diagnostics capabilities that mid-tier suppliers lack.
- Field Efficacy Validation:Biostimulant performance varies across Brazil's edaphoclimatic zones, forcing suppliers to conduct multi-location trials that compress margin structures before MAPA approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biostimulants Market |
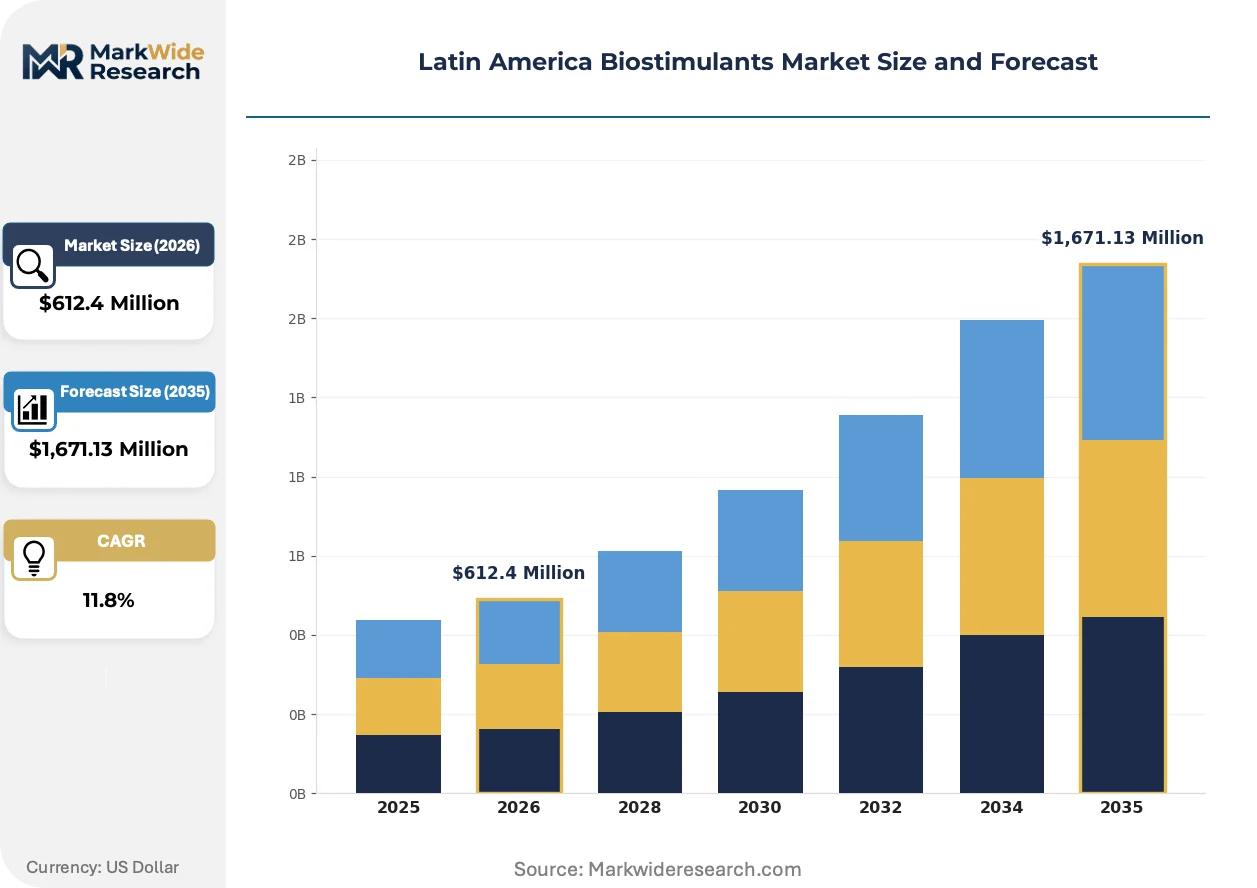
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,671.13 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Microbial Products, Amino Acids Application: Fruits, Vegetables, Cereals, Ornamentals Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Agricultural Producers, Gardeners, Nurseries, Commercial Growers |
| Companies Covered | Novozymes A/S, Isagro SpA, BASF SE, Trade Corporation International, Koppert Biological Systems, Syngenta, Biolchim SpA, Vittia Group, Valagro SpA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biostimulants Market Strategic Shifts & Innovations
Biological input platforms are converging with data-driven agronomy, rewiring how Latin American row-crop operations evaluate return on biological investment. This integration is compressing traditional supplier-buyer relationships and elevating technical service capabilities.
Microbial consortia engineering is converging with synthetic biology toolkits to develop multi-strain inoculants that colonize root zones more persistently than single-species products. Argentina's SENASA is fielding more applications for genetically characterized Bradyrhizobium-Trichoderma combinations. This technology is converging with precision delivery systems, enabling suppliers to command premium positioning in Brazil's southern soybean belt where input cost scrutiny is most intense.
COFEPRIS in Mexico is expanding residue testing protocols for biological inputs used on export-oriented horticulture, forcing suppliers to document metabolite profiles beyond active ingredient claims. SADER's Fertilizantes Orgánicos standard now requires third-party verification of microbial counts at point-of-sale. Berry packers in Michoacán and avocado exporters in Jalisco are restructuring supplier qualification around these certification requirements, disqualifying informal channel products.
Large-scale cooperatives in Brazil's Mato Grosso are consolidating procurement decisions for biological inputs through centralized technical committees, displacing individual farm-level purchasing. These committees demand multi-year efficacy data and integrated crop nutrition programs rather than standalone biostimulant transactions. The concentration of buying power is most visible among grain trading houses that now bundle biological inputs with output marketing contracts.
Latin America Biostimulants Market Segmentation
Biostimulant procurement in Latin America fragments across distinct product chemistries, crop systems, and channel structures. Suppliers must align formulation development with specific regulatory pathways and end-use performance requirements to capture value.
Product Type:
Supply concentration tilts toward fermentation-derived and extraction-based manufacturing, with domestic production capacity unevenly distributed across active ingredient categories.
- Humic Acids:Formulations contain 50-70% humic and fulvic acids derived from leonardite or peat oxidation. Demand concentrates in Brazil's Cerrado soybean belt where producers apply these products to improve phosphorus availability in highly weathered oxisols amid volatile fertilizer import costs.
- Microbial Products:Bradyrhizobium and Trichoderma inoculants dominate volume, with strain development concentrated among suppliers maintaining dedicated fermentation infrastructure. Brazil's southern soybean belt and Argentina's corn belt absorb the majority of rhizobia-based nitrogen fixation products as large-scale operations reduce urea dependency.
- Seaweed Extracts:Ascophyllum nodosum harvested from North Atlantic coastlines supplies Latin American formulators serving Mexico's avocado and berry export sectors where residue limits from US and EU buyers drive biological substitution.
- Amino Acids:Hydrolyzed protein formulations target high-value horticulture in Mexico's protected agriculture clusters and Brazil's specialty vegetable regions.
Microbial products absorb the bulk of installed capacity; seaweed extracts are expanding most quickly.
Application:
Cost tier differentiation separates commodity row-crop applications from premium horticulture segments where residue compliance commands price premiums.
- Fruits:Mexico's avocado orchards in Jalisco and Michoacán deploy biostimulants to meet tightening MRL standards from US and EU importers. Berry packers restructure supplier qualification around SADER's third-party verification requirements.
- Cereals:Brazil's soybean and corn systems lead microbial inoculant adoption, with cooperatives in Mato Grosso consolidating procurement through centralized technical committees demanding multi-year efficacy data.
- Vegetables:Protected agriculture operations in Mexico's Bajío region and Brazil's Southeast integrate seaweed extracts and amino acids into precision fertigation protocols.
- Ornamentals:Nursery operations in Colombia's flower export belt and Brazil's urban landscaping sectors drive smaller-volume demand for growth-regulating biostimulant applications.
Cereals command the largest volume position; fruits carry the steepest expansion trajectory.
Distribution Channel:
Customer type and purchase scale determine channel selection, with large-scale operations bypassing traditional retail networks.
- Wholesale:Agricultural cooperatives and grain trading houses in Brazil's Mato Grosso and Rio Grande do Sul bundle biological inputs with output marketing contracts, displacing individual farm-level purchasing.
- Direct Sales:Suppliers with technical service capabilities engage directly with large-scale producers requiring integrated crop nutrition programs rather than standalone transactions.
- Retail:Regional distributors serve medium-scale operations in Brazil's interior and Argentina's peripheral corn belt with established brand portfolios.
- Online:Emerging channel for specialty formulations and smaller-volume users, constrained by SADER and MAPA requirements for point-of-sale microbial count verification.
Wholesale channels handle the majority of volume throughput; direct sales are gaining share fastest among large-scale accounts.
End User:
Application sophistication varies sharply between commercial production systems and consumer gardening segments.
- Agricultural Producers:Large-scale soybean and corn operations in Brazil's Cerrado and southern belt integrate biostimulants into precision agriculture platforms with variable-rate application tied to soil microbiome monitoring.
- Commercial Growers:Mexico's berry and avocado exporters restructure input procurement around COFEPRIS-SADER dual approval requirements, disqualifying informal channel products lacking metabolite profile documentation.
- Nurseries:Propagation specialists in Colombia's flower clusters and Brazil's citrus nursery regions demand consistent formulation quality for root development protocols.
- Gardeners:Urban consumer segment in São Paulo and Mexico City metro areas drives retail-packaged seaweed and humic acid products through garden center channels.
Agricultural producers account for the dominant share of tonnage; commercial growers are climbing the fastest on a value basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leonardite deposits in Brazil's southern states anchor humic acid supply chains for the region's largest biostimulant consumer. Mexico's SADER certification protocols and Argentina's SENASA microbial guidelines create divergent compliance environments across the three dominant markets.
Brazil
Soybean cooperatives in Mato Grosso and Rio Grande do Sul drive microbial inoculant procurement through centralized technical committees. MAPA's Law 14.785 consolidates biostimulant registration under federal authority, eliminating state-level fragmentation. The Cerrado region absorbs the majority of Bradyrhizobium applications as large-scale operations reduce urea dependency amid volatile fertilizer import costs.
Mexico
Avocado orchards in Jalisco and Michoacán deploy seaweed extracts to meet tightening MRL standards from US and EU importers. COFEPRIS and SADER jointly regulate agricultural biologicals through overlapping approval requirements that extend product launch timelines. Berry packers in Michoacán restructure supplier qualification around third-party verification of microbial counts at point-of-sale.
Argentina
Corn producers in the Pampas region integrate rhizobia-based nitrogen fixation as SENASA evolves microbial strain guidelines. The country's underpenetrated corn belt creates first-mover advantage for suppliers establishing local fermentation partnerships. Buenos Aires province concentrates domestic fermentation infrastructure serving both domestic demand and cross-border supply to Uruguay and Paraguay.
Chile
Specialty fruit exporters in the Central Valley face residue limits from European markets that accelerate biological input substitution. Pending Pacific Alliance regulatory harmonization would align Chile's agricultural input standards with Mexico, Colombia, and Peru. Vineyard operations in the Maipo Valley experiment with amino acid formulations for premium wine grape production.
Colombia
Flower export clusters in the Bogotá savanna drive demand for growth-regulating biostimulant applications in nursery propagation. The country's national agricultural regulator maintains distinct approval pathways for microbial versus extract-based products. Coffee growers in the Zona Cafetera test humic acid formulations to improve phosphorus availability in Andean volcanic soils.
Latin America Biostimulants Market Key Industry Players
Strategic partnerships dominate the current landscape as suppliers seek to bridge regulatory compliance gaps across fragmented national frameworks. The vendor base clusters around three distinct tiers: multinational agrochemical conglomerates with integrated seed-treatment platforms, specialized microbial fermentation houses with dedicated strain libraries, and regional formulators serving export-oriented horticulture. Market consolidation accelerates through acquisition of local registration expertise, while portfolio diversification into bundled biological-nutrition programs displaces standalone biostimulant transactions.
Within the microbial specialization tier, Novozymes A/S and BASF SE exemplify contrasting scale approaches to Latin American market development. Novozymes A/S occupies a position anchored in enzyme fermentation expertise that translates directly to microbial inoculant supply chains. BASF SE represents the integrated platform archetype, bundling biostimulants with conventional crop protection through seed-treatment-to-foliar systems. Valagro SpA sits within the specialty extraction segment, with seaweed-derived formulations targeting high-value export horticulture where residue compliance commands premium positioning.
| Leading Market Players |
|---|
| Novozymes A/S |
| Isagro SpA |
| BASF SE |
| Trade Corporation International |
| Koppert Biological Systems |
| Syngenta |
| Biolchim SpA |
| Vittia Group |
| Valagro SpA |
| Others |
Cost & Logistics Intelligence
SADER's third-party verification mandate for microbial counts gates qualified supply access and premium-tier pricing eligibility for Mexico's avocado and berry exporters. Buyers lacking documented metabolite profiles face exclusion from formal procurement channels while certified suppliers command residue-compliant premiums in Jalisco and Michoacán orchards.
Pricing Analysis
Multi-year efficacy data bundling separates premium-tier suppliers from transactional competitors in Brazil's Mato Grosso cooperatives. Price differentiation rests on MAPA registration status and integrated crop nutrition program depth, with standalone biostimulant vendors facing cost compression from grain trading houses consolidating input-output contracts. Large-scale soybean producers in the Cerrado exhibit lowest price sensitivity due to sustainability premium capture, while medium-scale operators in Brazil's interior retail channels remain most cost-conscious.
Supply Chain Analysis
Direct-to-producer technical service channels handle large-scale cooperative demand in Brazil and Argentina, displacing traditional distributor networks. Supply concentration centers on domestic fermentation infrastructure in São Paulo and Buenos Aires provinces, with seaweed extract processors drawing from North Atlantic Ascophyllum nodosum harvests. Single-source vulnerability runs through ANVISA-mandated strain safety screening, which can bottleneck Brazilian inoculant output when additional molecular diagnostics requirements deploy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive fermentation capacity and strain library ownership constitutes the dominant vertical-integration race, as regulatory compliance timelines favor suppliers with in-house molecular characterization capabilities.
For Market Incumbents: Hedge against SENASA's evolving microbial guidelines by securing local fermentation partnerships in Argentina's underpenetrated corn belt before Mercosur harmonization closes first-mover windows. Prioritize MAPA registration maintenance investments to defend against emerging microbial consortia specialists gaining technical committee access in Mato Grosso cooperatives. For New Entrants and Emerging Players: Capture white-space in Chile's Central Valley specialty fruit sector where Pacific Alliance regulatory alignment would unlock cross-border formulation scale. Target Peru's pending biological input standardization as the most penetrable Pacific Alliance entry point, deploying COFEPRIS-SADER dual-approval documentation as competitive credential. For Investors and Strategic Acquirers: Pending Mercosur-Pacific Alliance regulatory harmonization is the leading indicator that regional scale economies will consolidate around multi-country registration expertise. Position acquisition screening toward mid-tier Brazilian formulators with established MAPA dossiers and transferable strain characterization capabilities, monitoring ANVISA whole-genome sequencing mandate expansion as the signal for molecular diagnostics capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Fermentation Partnership | Buenos Aires province infrastructure anchors supply security for Argentina's corn belt expansion. |
| MAPA Registration Dossier Acquisition | Law 14.785 compliance infrastructure eliminates 18-24 month approval disadvantages for new entrants. |
| Precision Agriculture Platform Integration | Variable-rate application protocols in Mato Grosso compress supplier-buyer relationships around technical service. |
| Seaweed Extract Supply Agreement | North Atlantic Ascophyllum nodosum sourcing locks in residue-compliant raw material for Mexican exporters. |
| Microbial Consortia R&D Investment | Genetically characterized Bradyrhizobium-Trichoderma combinations command premium in Brazil's southern soybean belt. |
Research Approach
Document review covered MAPA regulatory filings, SADER certification protocols, and ANVISA safety screening guidelines, complemented by interviews with fermentation plant managers, agricultural cooperative procurement leads, and berry packer technical directors. Secondary validation drew from customs trade data, SEC filings of listed biological input suppliers, and regional agricultural input association reports. Bottom-up demand modeling from crop hectarage and application rates triangulated against top-down market sizing from supplier revenue disclosures.
Cross-referencing historical registration timelines against expert panel input on pending regulatory harmonization shaped the projection framework. Segmentation dimensions included product chemistry, crop system intensity, and distribution channel concentration across the modeling period. CAGRs derived from elasticity-adjusted adoption curves for microbial inoculants in Brazil's soybean belt and seaweed extract penetration in Mexican export horticulture.
The model holds under stable regulatory approval timelines and continued fertilizer cost volatility; deviation in Mercosur-Pacific Alliance harmonization pace or ANVISA screening intensity would shift trajectory. Forecasts reflect assumptions around SENASA guideline evolution and SADER verification enforcement scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
China Biofuels Market