
 Global Biometrics Middleware Market | 2026-2036
Global Biometrics Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometrics Middleware Market Foresight
Cloud-native API architectures are repositioning legacy on-premise middleware stacks toward subscription-based delivery models. Daon leverages its multi-modal platform to anchor large-scale airline and banking deployments across North America and Europe. Precise Biometrics specializes in algorithm licensing, sustaining margin pools through royalty structures rather than full-stack competition. BioCatch differentiates via behavioral biometrics, occupying a defensive niche against template-based fingerprint and facial recognition commoditization.
Biometrics middleware denotes software layers that abstract sensor hardware from application logic, enabling interoperability across fingerprint, facial, iris, and voice recognition modalities through standardized API protocols such as BioAPI or custom REST frameworks. Its primary commercial purpose is to reduce integration complexity for enterprises deploying multi-vendor biometric ecosystems without rewriting core applications. Authentication middleware commands the largest installed base among middleware types, though identity management middleware captures disproportionate R&D investment as zero-trust architectures expand. Facial recognition dominates transaction volumes within biometric technology segments, while vein pattern recognition leads in high-assurance access control deployments where spoof resistance justifies premium positioning.
The EU AI Act, GDPR, and ISO/IEC 30107-3 liveness detection standards collectively constrain algorithm deployment, mandating explicit consent frameworks and anti-spoofing certifications that filter non-compliant vendors from European procurement pipelines. In the United States, NIST testing protocols and state-level biometric privacy laws in Illinois and Texas fragment compliance obligations, raising middleware engineering costs for national deployments. Stakeholders must monitor regulatory divergence between privacy-first European mandates and performance-oriented U.S. federal standards when architecting product roadmaps and geographic prioritization.
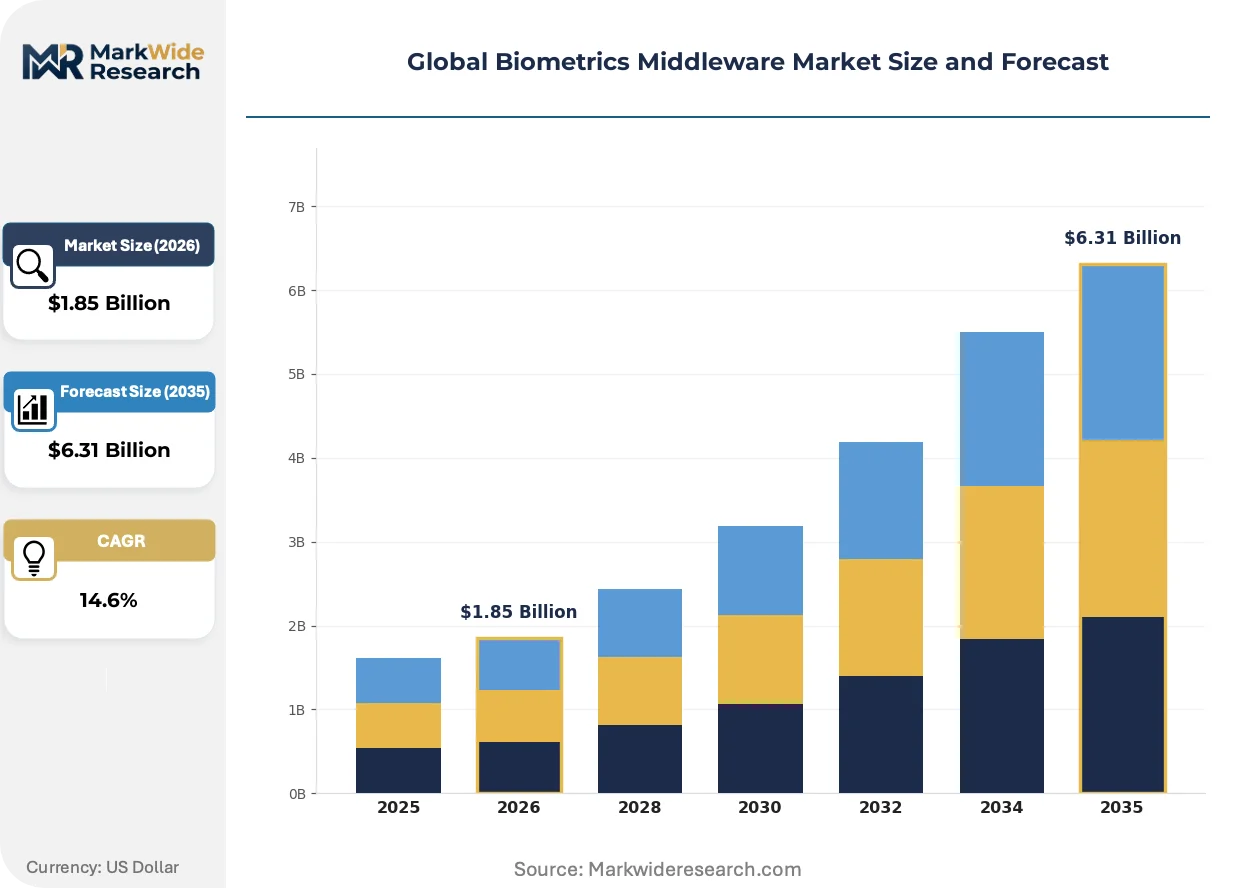
Market Dynamics
Cloud-native API architectures are dismantling legacy on-premise middleware stacks, forcing vendors to reengineer subscription delivery models while embedding privacy-preserving compliance layers demanded by divergent regulatory regimes across North America and Europe.
Growth Catalysts
- Zero-trust architecture mandates:Federal agencies and commercial banks in the United States are accelerating multi-factor biometric deployments, expanding middleware integration requirements for identity verification workflows.
- GDPR and EU AI Act compliance:European privacy frameworks compel middleware vendors to embed explicit consent mechanisms and liveness detection certifications, filtering non-compliant competitors from procurement pipelines.
- Behavioral biometrics differentiation:Continuous authentication models for fraud prevention are capturing investment in financial services, creating middleware demand that transcends template-based fingerprint commoditization.
Market Restraints
- Algorithm licensing cost volatility:Royalty structures for biometric matching engines concentrate margin pressure on middleware vendors lacking captive algorithm development.
- European supply concentration:ISO/IEC 30107-3 certification requirements limit qualified liveness detection providers, creating bottleneck dependencies for anti-spoofing middleware modules.
- State-level regulatory fragmentation:Illinois Biometric Information Privacy Act and Texas biometric laws impose conflicting consent frameworks, raising engineering overhead for United States national deployments.
Strategic Opportunities
- India digital identity expansion:Aadhaar-linked authentication ecosystems present middleware integration opportunities for vendors adapting to BIS standards and RBI financial inclusion mandates.
- Vein pattern recognition convergence:High-assurance access control in healthcare and critical infrastructure is converging with contactless hygiene requirements, opening premium middleware positioning.
- API-first distribution channels:Developer-centric marketplaces and embedded finance platforms are emerging as alternative routes to enterprise buyers, bypassing traditional systems integrator gatekeepers.
Industry Challenges
- Legacy system integration complexity:Mainframe banking cores and government identity registries require custom middleware adapters, extending deployment timelines and professional services dependency.
- Cross-border data residency compliance:GDPR data localization requirements and United States CLOUD Act tensions force architectural bifurcation, complicating single-stack product strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometrics Middleware Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Middleware Type: Authentication Middleware, Identity Management Middleware, Biometric Data Processing Middleware, Access Control Middleware, Transaction Management Middleware Biometric Technology: Fingerprint Recognition, Facial Recognition, Iris Scanning, Voice Recognition, Vein Pattern Recognition, Hand Geometry Recognition Use Case: Time & Attendance, Border Control, Secure Banking, Healthcare Access, Workplace Security, Customer Verification End User Industry: Government Agencies, Financial Institutions, Telecommunication Operators, Education Sector, Transportation Providers, Retail Corporations |
| Companies Covered | Zvetco Biometrics, Assa Abloy, BioCatch, Centrify Corporation, ImageWare Systems, Daon, Precise Biometrics, Fischer International Systems, Aware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometrics Middleware Market Shifts & Advancements
Biometric middleware is undergoing architectural transformation as edge computing, federated identity standards, and privacy-enhancing technologies simultaneously reshape deployment patterns and competitive differentiation vectors.
Edge-based biometric processing is converging with on-device neural network acceleration, enabling real-time template matching without cloud round-trips. Airlines and border control agencies in Germany and the Netherlands are piloting these architectures to reduce latency in high-throughput passenger processing. This convergence is compressing centralized middleware value capture, forcing vendors to reposition toward orchestration and policy management layers.
The EU AI Act's risk-based classification system is restructuring algorithm deployment requirements for biometric identification in public spaces. High-risk system designations now mandate conformity assessments and post-market monitoring, elevating compliance engineering to core product functionality. Middleware vendors serving European law enforcement and transportation hubs are responding by embedding audit trails and explainability modules directly into API gateways.
Financial institutions are unbundling authentication from core banking platforms, procuring biometric middleware through cloud marketplaces rather than traditional enterprise software channels. This purchasing pattern shift is most pronounced in the United States, where regional banks and credit unions bypass legacy vendor relationships to access API-driven identity services. Channel disintermediation is compressing sales cycles while intensifying price transparency and feature comparability pressures.
Global Biometrics Middleware Market Segmentation
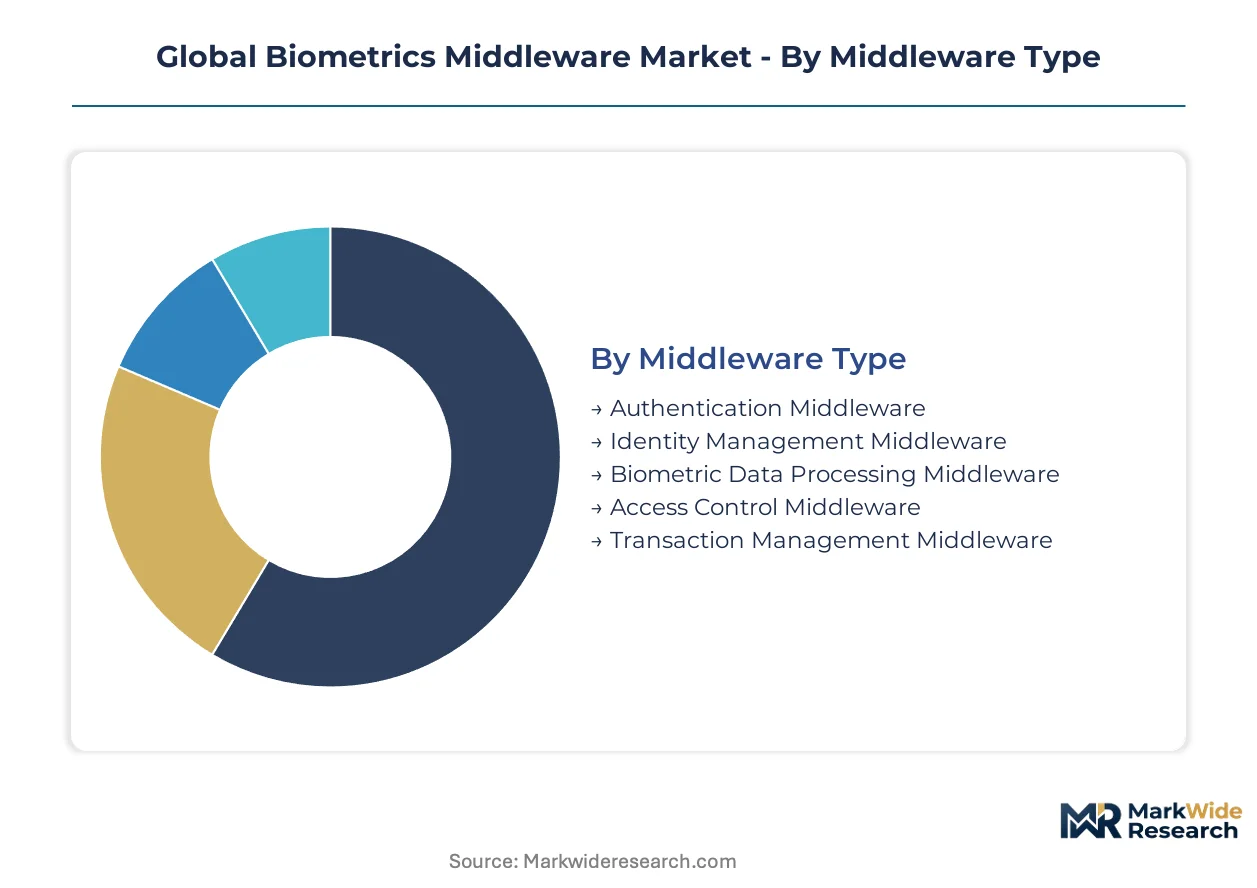
Middleware architectures fragment across functional layers, biometric modalities, and deployment contexts. Each segmentation axis reveals distinct integration patterns, vendor positioning strategies, and procurement decision frameworks that shape competitive dynamics.
Middleware Type:
Standalone middleware deployments dominate high-security environments requiring air-gapped architectures, while embedded middleware layers integrate directly into cloud-native application stacks.
- Authentication Middleware:Core software layer validates biometric credentials against enrolled templates through standardized API protocols. Demand concentrates in United States federal agencies implementing zero-trust mandates, where NIST testing protocols filter vendor qualification.
- Identity Management Middleware:Orchestrates lifecycle operations including enrollment, template storage, and revocation across distributed systems. Financial institutions in Germany and the Netherlands are expanding procurement for federated identity architectures.
- Biometric Data Processing Middleware:Handles template extraction, quality scoring, and format conversion between sensor outputs and matching engines.
- Access Control Middleware:Bridges physical security systems with logical identity repositories for unified perimeter management.
- Transaction Management Middleware:Secures payment authorization workflows through step-up biometric challenges in mobile banking applications.
Volume placements concentrate in Authentication Middleware; the faster expansion belongs to Identity Management Middleware.
Biometric Technology:
Cost tiers separate commodity template-based modalities from premium liveness-certified alternatives, with pricing stratifying across certification grade and spoof resistance levels.
- Fingerprint Recognition:Mature sensor ecosystem with standardized minutiae extraction algorithms. Workplace security deployments in Japan and South Korea sustain volume, though commoditization compresses middleware margins.
- Facial Recognition:Dominates transaction volumes through smartphone-integrated authentication and border processing lanes. United States airports and EU Schengen entry points are expanding procurement despite GDPR Article 9 restrictions on biometric processing.
- Iris Scanning:Delivers highest accuracy-per-template ratios for de-duplication in large-scale identity registries.
- Voice Recognition:Enables passive authentication in call center environments without dedicated hardware.
- Vein Pattern Recognition:Contactless palm vascular imaging resists spoofing through liveness inherent in blood flow detection.
- Hand Geometry Recognition:Legacy modality persisting in time-clock applications with low security requirements.
Facial Recognition captures the largest installed base; Vein Pattern Recognition is climbing the fastest on hygiene and anti-spoofing premiums.
Use Case:
Application maturity varies from compliance-driven time tracking to mission-critical border infrastructure, with procurement cycles stretching from weeks to multi-year government tenders.
- Secure Banking:Multi-factor authentication for high-value transactions and account recovery workflows. RBI mandates in India and PSD2 strong customer authentication in Europe are accelerating middleware integration timelines.
- Border Control:Automated gate systems matching biometric credentials against watchlists and visa databases. Germany's Federal Police and Netherlands Royal Marechaussee are piloting edge-based processing to reduce cloud latency.
- Time & Attendance:Workforce tracking with union-compliant audit trails.
- Healthcare Access:Patient identity matching against master patient indices to prevent record duplication.
- Workplace Security:Physical access integration with HR systems for terminated employee revocation.
- Customer Verification:Remote onboarding through selfie-to-document matching in digital banking.
Secure Banking leads current procurement volumes; Border Control shows the steepest expansion trajectory on post-pandemic travel recovery and security modernization budgets.
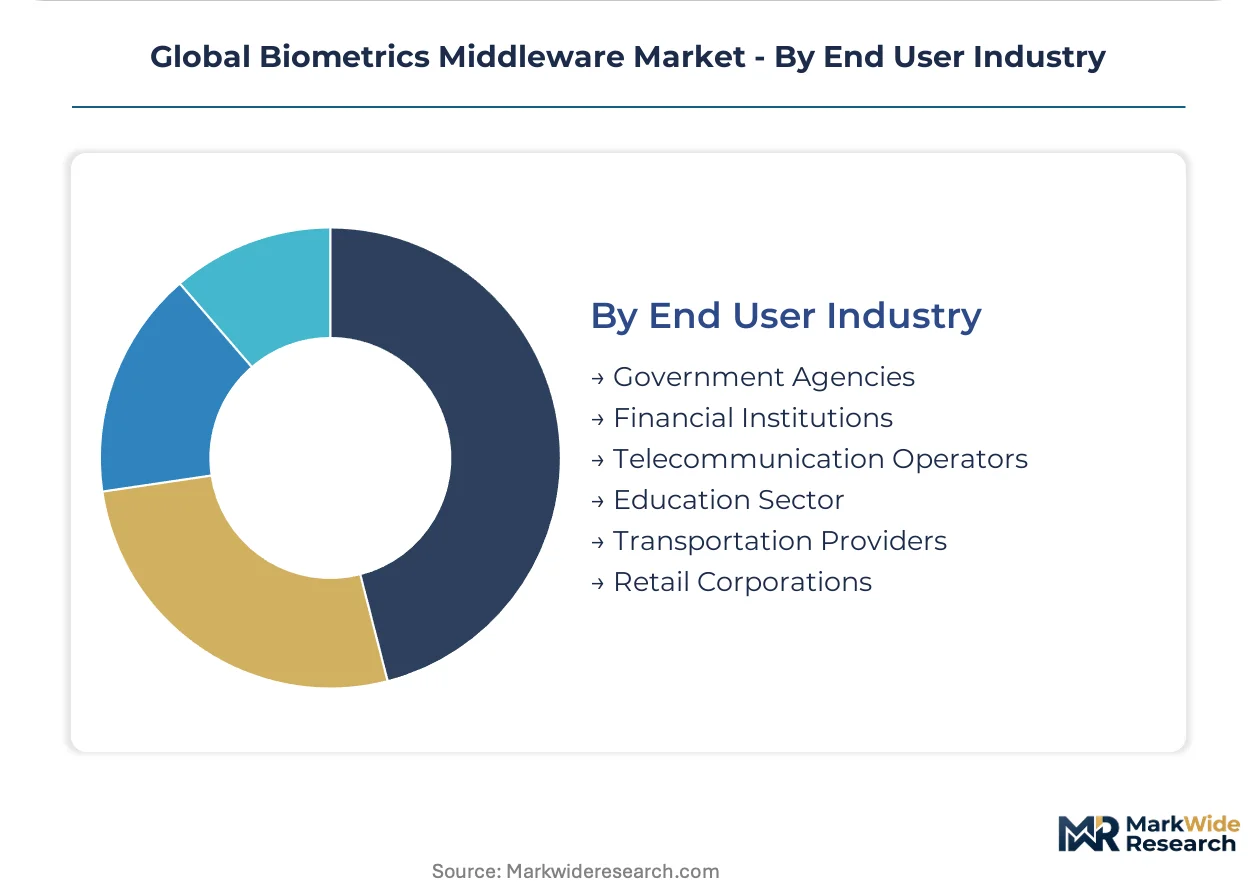
End User Industry:
Customer type determines contract structure, with government tenders favoring multi-year maintenance clauses and financial services preferring consumption-based API pricing.
- Government Agencies:National identity registries, law enforcement AFIS networks, and border management systems. India's UIDAI and Nigeria's NIMC are expanding middleware procurement for biometric de-duplication at population scale.
- Financial Institutions:Retail banking, payment networks, and insurance fraud prevention. United States regional banks are bypassing traditional integrators to procure directly through cloud marketplaces.
- Telecommunication Operators:Subscriber identity verification for SIM registration mandates.
- Education Sector:Campus access and examination proctoring applications.
- Transportation Providers:Airline passenger processing and port worker credentialing.
- Retail Corporations:Loyalty program authentication and employee access management.
Government Agencies anchor current deployments; Financial Institutions are gaining share fastest on digital transformation and fraud prevention priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen, Dubai International Financial Centre, and Bangalore Electronics City concentrate middleware R&D through tax incentives and streamlined IP frameworks.
United States
Federal zero-trust mandates and NIST testing protocols drive authentication middleware procurement across defense agencies and commercial banks. Illinois Biometric Information Privacy Act and Texas biometric laws create state-level compliance fragmentation. Greater Washington DC and New York Metro anchor enterprise identity management deployments for financial services and government contractors.
Germany
Federal Police and Netherlands Royal Marechaussee pilot edge-based biometric processing for border control modernization. EU AI Act high-risk system classifications mandate conformity assessments for public-space biometric identification. Frankfurt Rhine-Main cluster hosts middleware engineering centers serving Schengen Area transportation hubs.
India
UIDAI Aadhaar expansion and RBI financial inclusion mandates accelerate middleware integration for biometric de-duplication at population scale. BIS standards compliance requirements filter vendor qualification for national identity ecosystems. Bangalore Electronics City and Hyderabad HITEC City concentrate software development for Aadhaar-linked authentication platforms.
United Arab Emirates
Dubai International Financial Centre tax incentives attract biometric middleware vendors serving Gulf Cooperation Council banking modernization. UAE central bank digital identity frameworks mandate multi-factor authentication for payment systems. Dubai and Abu Dhabi anchor smart city deployments integrating facial recognition for airport and hospitality workflows.
Netherlands
Schiphol Airport and Rotterdam port modernization budgets drive procurement for passenger processing and worker credentialing middleware. GDPR Article 9 restrictions on biometric processing require explicit consent frameworks in public-space deployments. Amsterdam metropolitan area hosts privacy-preserving technology R&D for EU-compliant liveness detection modules.
Global Biometrics Middleware Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack platform vendors capturing enterprise accounts while algorithm licensors penetrate through royalty structures. The vendor base concentrates around three strategic archetypes: multi-modal platform providers, behavioral biometrics specialists, and pure-play algorithm licensors. M&A activity targets API-first startups with cloud-native architectures, while incumbents expand through strategic partnerships with systems integrators.
Within the multi-modal platform tier, Daon and Aware exemplify vendors anchoring large-scale airline and federal deployments across North American and European markets. BioCatch occupies a distinct position representing behavioral biometrics differentiation against template-based commoditization. Precise Biometrics sits within the algorithm licensing archetype, sustaining margin pools through royalty structures rather than competing on full-stack implementation.
| Leading Market Players |
|---|
| Zvetco Biometrics |
| Assa Abloy |
| BioCatch |
| Centrify Corporation |
| ImageWare Systems |
| Daon |
| Precise Biometrics |
| Fischer International Systems |
| Aware |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up middleware specialists have consolidated algorithm licensing portfolios across North America and Europe, tightening supply discipline while embedding ISO/IEC 30107-3 certification costs into premium-tier pricing structures for federal and financial services buyers.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to anti-spoofing middleware modules with certified liveness detection, while spot inventory of legacy fingerprint SDKs trades at contracted discounts. Subscription-based SaaS tiers dominate authentication middleware procurement, with price differentiation anchored in NIST test score tiers and EU AI Act conformity assessment status. Cost compression in facial recognition middleware is intensifying because smartphone-integrated matching engines commoditized template extraction. Regional banks and credit unions exhibit highest price sensitivity, whereas defense agencies and border control authorities demonstrate lowest elasticity due to mandate-driven procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States federal agencies and Indian UIDAI contractors, while cloud marketplaces serve mid-market financial institutions. Algorithm development concentrates in the United States, Sweden, and Israel, with template extraction hardware sourcing from Taiwan and South Korea. Supply chains draw from specialized neural network accelerators, liveness detection sensor arrays, and federated identity protocol stacks. Single-source vulnerability in ISO/IEC 30107-3 certified liveness detection providers creates bottleneck risk for European procurement pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive algorithm development and edge-computing hardware stacks has become the defining competitive race, as middleware vendors seek margin defense against royalty-bearing licensing structures and cloud-hyperscaler orchestration layers.
For Market Incumbents: Acquire specialized liveness detection engineering teams to internalize ISO/IEC 30107-3 certification capabilities and reduce dependency on bottlenecked European suppliers. Consolidate API gateway platforms through selective tuck-in acquisitions of cloud-native authentication startups, defending against displacement by hyperscaler-native identity services. Channel control through embedded finance partnerships represents the priority defensive lever. For New Entrants and Emerging Players: Enter via API-first developer marketplaces targeting United States regional banks and Indian fintechs underserved by legacy integrator relationships. White-space concentration exists in vein pattern recognition middleware for healthcare access control, where contactless hygiene requirements and anti-spoofing premiums justify greenfield positioning. Go-to-market execution should anchor in RBI-compliant Aadhaar integration services. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithm-licensing specialists with royalty-contract backlogs in Germany and the Netherlands, where EU AI Act compliance investments have compressed near-term cash conversion. Long-term viability hinges on five-to-ten year contractual visibility with federal identity modernization programs. Watch NIST test protocol updates as the critical inflection signal for middleware vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Consolidation | Captive matching engine development defends margin pools against royalty outflows to Swedish and Israeli specialists. |
| Edge Computing Architecture Migration | On-device template processing reduces cloud latency for Germany's Federal Police and Netherlands Royal Marechaussee border deployments. |
| EU AI Act Compliance Engineering | Embedded audit trails and explainability modules filter non-conforming competitors from European law enforcement procurement. |
| API-First Distribution Expansion | Cloud marketplace channels bypass traditional systems integrators serving United States regional banking segments. |
| Vein Pattern Recognition Development | Contactless palm vascular imaging addresses healthcare hygiene mandates and high-assurance access control premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with biometric middleware engineering directors, federal procurement officers at United States agencies, European data protection compliance leads, and cloud marketplace integration specialists. Primary fieldwork combined with NIST test result databases, UIDAI vendor qualification registries, SEC 10-K disclosures from listed identity management vendors, and EU AI Act implementation guidance documents. Bottom-up deployment estimates across authentication, identity management, and access control middleware segments were triangulated against top-down market sizing from royalty-reported algorithm licensing volumes.
Data-stream reconciliation across sensor hardware shipment records, API call volume telemetry from cloud identity platforms, and government contract award notifications informed the analytical framework. Segmentation modeling spanned middleware type, biometric modality, deployment architecture, and end-user industry vertical throughout the projection horizon. CAGRs were derived from trend extrapolation of federal zero-trust mandate implementation timelines and RBI financial inclusion authentication volume targets. Industry-specific forecast inputs included Aadhaar-linked transaction growth trajectories and Schengen Area border modernization budget allocations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between GDPR Article 9 enforcement and United States state-level biometric privacy law expansion. Periodic stress-testing of base assumptions is recommended, particularly regarding ISO/IEC 30107-3 certification bottleneck resolution and cloud-hyperscaler identity service competitive encroachment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market