
 Bio-Based Levulinic Acid Market | 2026-2036
Bio-Based Levulinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Levulinic Acid Market Outlook
European biorefinery capacity is restructuring around second-generation carbohydrate feedstocks as producers scale levulinic acid output from lignocellulosic biomass. GFBiochemicals anchors its position through backward integration into raw agricultural residue supply in Italy. Avantium leverages catalytic process technology to sustain cost parity against conventional petrochemical routes. Segetis differentiates through specialized levulinic acid esters for personal care and coatings applications.
Bio-based levulinic acid is a five-carbon keto acid (C5H8O3) produced via acid-catalyzed dehydration of hexose sugars from biomass, typically operating at reaction temperatures between 150 and 200 degrees Celsius with sulfuric acid or heterogeneous solid acid catalysts. The compound functions primarily as a platform chemical for synthesizing solvents, plasticizers, fuel additives, and pharmaceutical precursors. Pure levulinic acid dominates current revenue as established industrial buyers prioritize certified high-purity grades for pharmaceutical and food additive specifications. Levulinic acid derivatives represent the fastest-expanding structural category as formulators seek tailored esters and salts for cosmetics and agrochemical applications. Chemical intermediates command the deepest margin pools where custom synthesis contracts lock in multi-year offtake agreements with specialty chemical distributors.
The EPA oversees bio-preferred procurement standards in the United States while REACH governs chemical registration and hazard communication across European member states. ECHA substance evaluation protocols directly shape market access timelines for new levulinic acid derivatives entering cosmetics and food contact applications. Stakeholders must monitor evolving bio-based content certification schemes as downstream buyers increasingly require chain-of-custody documentation from feedstock origin through final formulation.
Market Dynamics
Pharmaceutical product manufacturers are driving structural demand for certified high-purity bio-based levulinic acid as REACH compliance and EU Green Deal specifications tighten requirements for renewable chemical intermediates across European polymer and solvent supply chains.
Growth Catalysts
- REACH compliance mandates:European chemical registration protocols now require hazard documentation for petroleum-derived alternatives, creating regulatory pull for bio-based substitutes in cosmetics and food contact applications.
- Second-generation carbohydrate feedstocks:Industrial biorefinery capacity is scaling lignocellulosic biomass processing, expanding raw material availability for acid-catalyzed levulinic acid production.
- Germany's chemical cluster integration:Industrial buyers in Rhineland-Palatinate and North Rhine-Westphalia actively incorporate levulinic acid into polymer and solvent formulations, anchoring regional demand.
Market Restraints
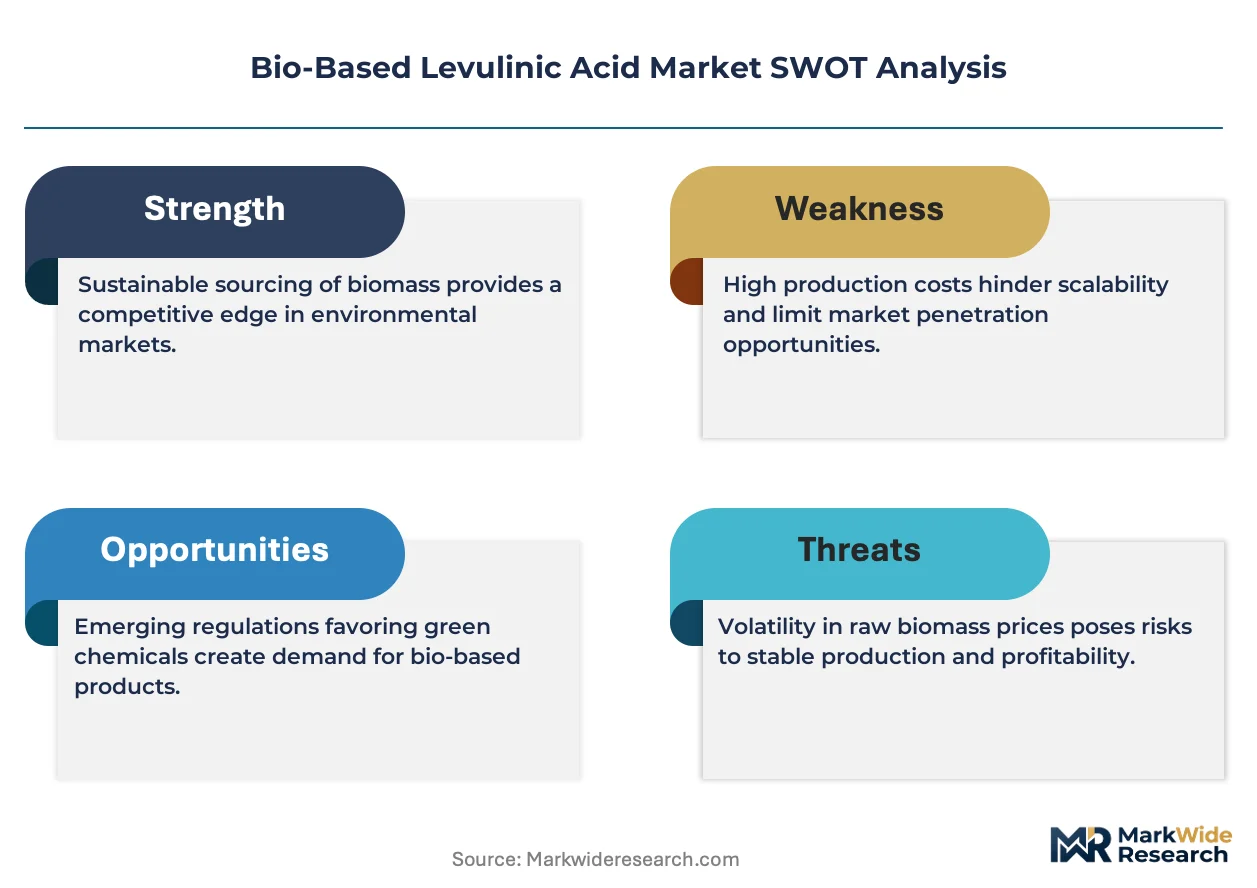
- Sulfuric acid input volatility:Concentrated acid prices fluctuate with sulfur commodity markets, compressing margins for producers using homogeneous catalyst systems.
- Petrochemical route cost parity:Conventional levulinic acid synthesis from fossil feedstocks maintains established supply chains and economies of scale that bio-based alternatives struggle to match.
- ECHA substance evaluation timelines:New levulinic acid derivative registrations face extended hazard assessment protocols, delaying market access for novel esters and salts.
Strategic Opportunities
- Agrochemical formulation expansion:Levulinic acid salts and esters are penetrating crop protection applications as formulators seek biodegradable active ingredient carriers.
- EU Green Deal carbon accounting:Chain-of-custody certification schemes for bio-based content create premium positioning for producers with verified agricultural residue sourcing.
- Personal care channel diversification:Specialized levulinic acid derivatives are entering cosmetic formulations through direct relationships with beauty contract manufacturers.
Industry Challenges
- Heterogeneous catalyst engineering talent:Solid acid catalyst development requires rare expertise in surface chemistry and reactor design, constraining process innovation.
- Multi-year offtake negotiation complexity:Custom synthesis contracts for chemical intermediates demand extended technical validation periods that strain working capital.
- ISO bio-based content certification:Third-party verification of feedstock origin through final formulation adds documentation burden and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Levulinic Acid Market |
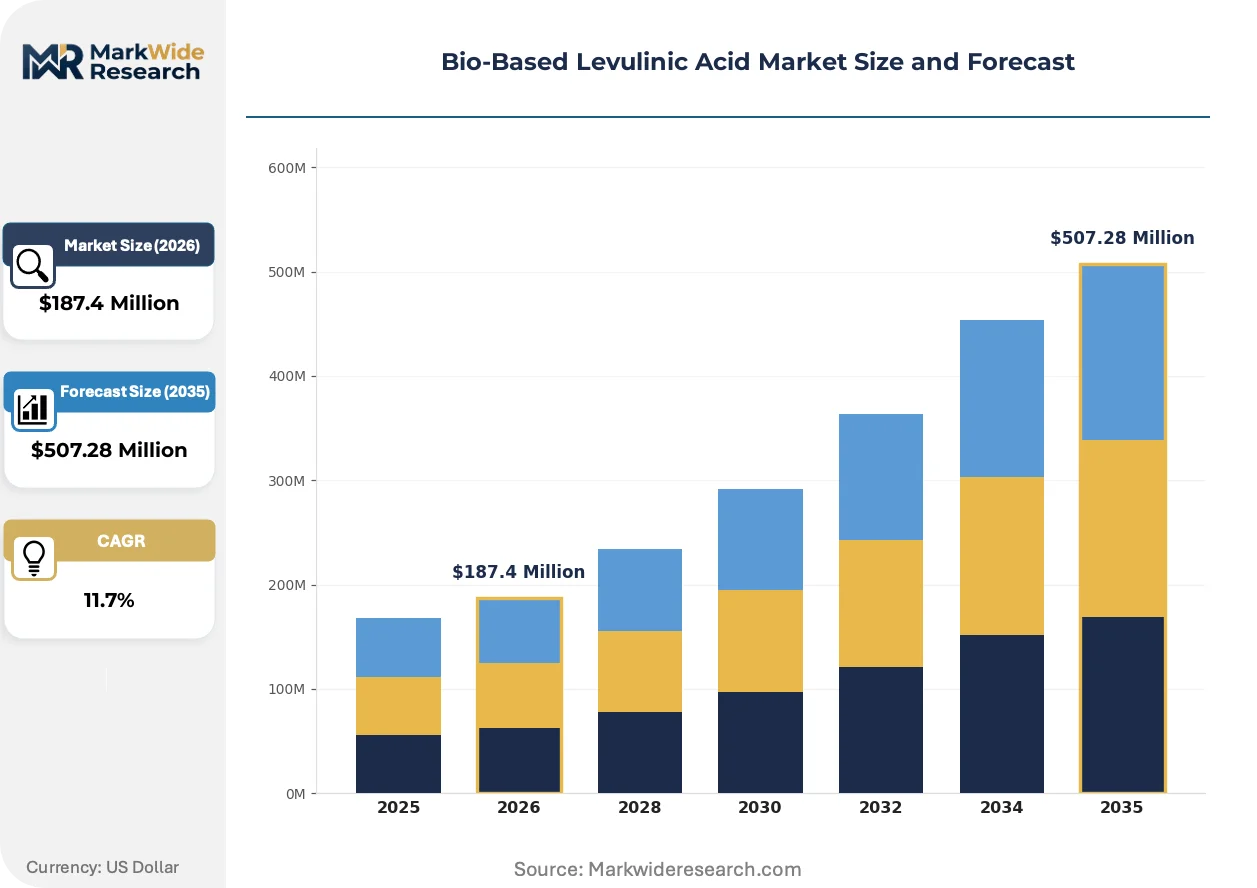
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Levulinic Acid, Levulinic Acid Derivatives, Liquid Formulations, Solid Formulations Application: Solvent Production, Food Additives, Chemical Intermediates, Pharmaceutical Products End User: Cosmetics Industry, Food and Beverage Sector, Agrochemicals, Industrial Chemicals Distribution Channel: Direct Sales, Online Retail, Distributor Network, Third-Party Retail |
| Companies Covered | Avantium, GreenSolRes, GFBiochemicals, Langfang Triple Well Chemicals Co. Ltd, Heroy Chemical Industry Co., Biofine Technology, Segetis, Zhonglan Industry Co., NXTLEVVEL Biochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Levulinic Acid Market Strategic Shifts
Catalytic process technology is actively reshaping competitive economics in bio-based levulinic acid production, while regulatory frameworks and procurement patterns are simultaneously reconfiguring how value flows through chemical intermediate supply chains.
Solid acid heterogeneous catalysts are integrating into commercial levulinic acid production as producers seek to eliminate sulfuric acid handling costs and wastewater treatment burdens. Pharmaceutical manufacturers and food additive formulators are adopting these catalytic systems fastest, driven by purity specifications and process safety requirements. This technology integration is compressing the cost gap against petrochemical routes while enabling modular, distributed biorefinery deployment closer to agricultural residue sources.
REACH substance evaluation protocols are tightening hazard communication requirements for levulinic acid derivatives entering cosmetics and food contact applications. ECHA's expanded dossier review scope is extending registration timelines and increasing testing expenditure for novel esters and salts. Specialty chemical distributors serving personal care and agrochemical end-uses are responding by consolidating supplier relationships with established registrants who possess complete toxicological datasets.
Certification-driven procurement patterns are restructuring buyer-supplier relationships as downstream formulators increasingly require ISO-compliant chain-of-custody documentation. Beauty and personal care manufacturers are displacing spot-market purchasing with multi-year supply agreements that bundle bio-based content verification. Germany's industrial chemical clusters exhibit this behavioral shift most visibly, where polymer and solvent producers now embed certification requirements directly into technical specifications.
Bio-Based Levulinic Acid Market Segmentation
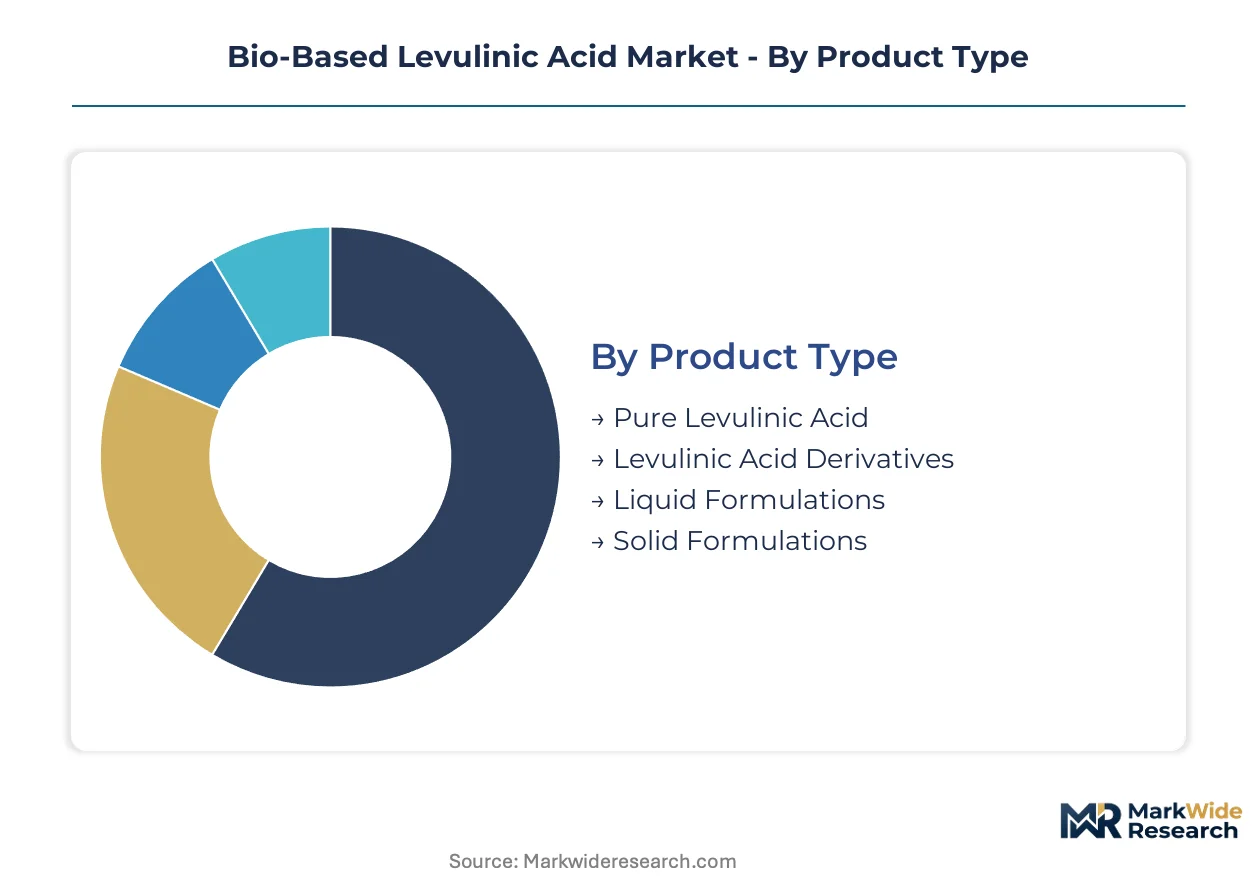
Levulinic acid segmentation reflects divergent purity requirements and formulation complexity across pharmaceutical, food, and industrial end-uses. Buyers prioritize certified grades for regulated applications while seeking customized derivatives for specialty chemical synthesis.
Product Type:
Purity specifications and formulation state determine handling protocols, storage economics, and end-use eligibility across regulated industries.
- Pure Levulinic Acid:Certified high-purity grades meeting pharmaceutical and food additive specifications command premium positioning through REACH-registered supply chains. German polymer producers and solvent manufacturers anchor demand for bulk pure acid in Rhineland-Palatinate industrial clusters.
- Levulinic Acid Derivatives:Tailored esters and salts enable functional customization for cosmetics and agrochemical applications. Specialty chemical distributors in Italy and the Netherlands are consolidating multi-year offtake agreements for derivative grades with verified bio-based content certification.
- Liquid Formulations:Ready-to-use aqueous solutions reduce handling complexity for mid-scale chemical processors.
- Solid Formulations:Crystalline or powdered forms optimize transport economics and extended shelf stability.
Pure levulinic acid leads on scale; derivatives lead on momentum.
Application:
Functional role in downstream manufacturing determines specification stringency and contract structure across buyer segments.
- Chemical Intermediates:Custom synthesis contracts for platform chemical derivatives lock in multi-year relationships with specialty distributors. ECHA substance evaluation protocols extend registration timelines for novel intermediate grades entering European supply chains.
- Pharmaceutical Products:Keto acid functionality supports active pharmaceutical ingredient precursors and excipient formulations. FDA bio-preferred procurement standards and REACH compliance mandates are displacing petroleum-derived alternatives in certified drug manufacturing.
- Solvent Production:Ester derivatives replace conventional petroleum-based solvents in coatings and cleaning formulations.
- Food Additives:Flavor and preservative applications require EFSA-compliant purity grades with full toxicological dossiers.
Chemical intermediates dominate volume throughput; pharmaceutical applications show steepest specification premium expansion.
End User:
Industry-specific regulatory exposure and formulation complexity shape procurement patterns and supplier qualification requirements.
- Industrial Chemicals:Polymer plasticizer and solvent manufacturers integrate levulinic acid into continuous process chemistry. Germany's North Rhine-Westphalia chemical cluster exhibits the deepest backward integration into agricultural residue supply chains.
- Cosmetics Industry:Beauty contract manufacturers are displacing spot-market purchasing with ISO-compliant chain-of-custody agreements. EU Green Deal carbon accounting requirements are restructuring supplier relationships toward verified bio-based content documentation.
- Agrochemicals:Biodegradable active ingredient carriers penetrate crop protection formulations through salt and ester derivatives.
- Food and Beverage Sector:Flavor enhancement and preservation applications demand EFSA-registered grades with full hazard communication dossiers.
Industrial chemicals anchor procurement volume; cosmetics drives certification complexity.
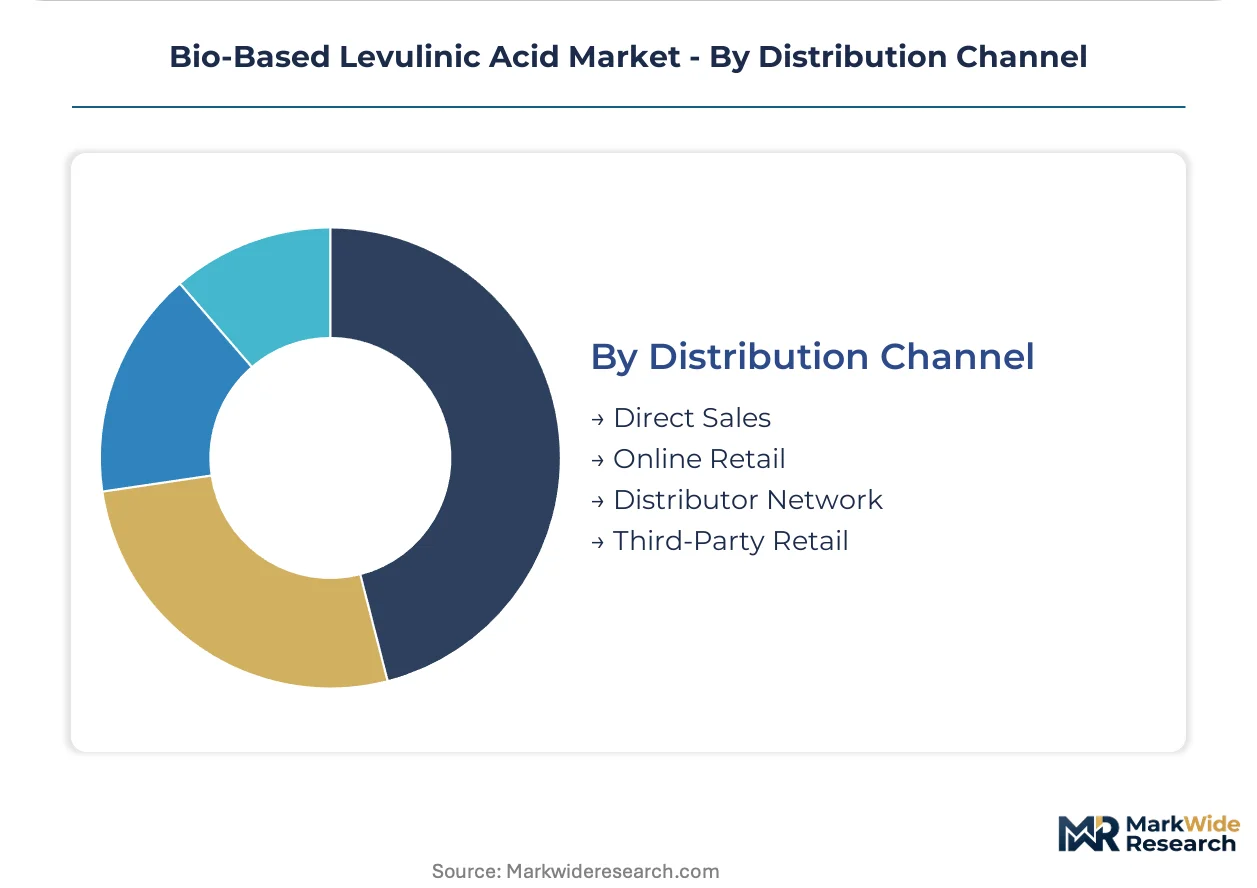
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and documentation burden across buyer sophistication tiers.
- Direct Sales:Large-volume chemical processors negotiate captive supply agreements with integrated biorefinery operators. GFBiochemicals and Avantium leverage direct relationships to embed chain-of-custody verification into multi-year contracts.
- Distributor Network:Specialty chemical distributors consolidate fragmented personal care and agrochemical demand through technical service bundling. REACH-registered distributors with complete toxicological datasets are capturing derivative market share from unregistered competitors.
- Online Retail:Small-scale research and pilot-scale buyers access catalog purity grades through digital procurement platforms.
- Third-Party Retail:Regional chemical merchants serve intermittent demand from compounders and formulators without direct supplier relationships.
Direct sales command the deepest margin pools; distributor networks are gaining share fastest in derivative segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting bio-based levulinic acid investment toward jurisdictions where REACH compliance costs and EU Green Deal carbon accounting create asymmetric advantages for verified renewable feedstock producers.
Germany
Industrial chemical clusters in Rhineland-Palatinate and North Rhine-Westphalia anchor European demand for pharmaceutical-grade levulinic acid. ECHA substance evaluation protocols under REACH tighten hazard documentation requirements, favoring established registrants with complete toxicological datasets. The Leverkusen-Dormagen chemical corridor actively integrates bio-based intermediates into polymer plasticizer and solvent supply chains.
United States
Pharmaceutical manufacturers and food additive formulators drive procurement of certified high-purity grades. EPA bio-preferred procurement standards create federal demand pull for renewable chemical intermediates displacing petroleum-derived equivalents. The Gulf Coast petrochemical corridor hosts emerging biorefinery capacity targeting lignocellulosic feedstock processing at scale.
Italy
Agricultural residue availability from northern Po Valley farming operations supports backward integration into raw material supply. EU Green Deal carbon accounting requirements incentivize chain-of-custody certification from feedstock origin through final formulation. The Porto Torres industrial zone on Sardinia concentrates biorefinery infrastructure development for second-generation carbohydrate processing.
China
Chemical intermediate producers scale acid-catalyzed levulinic acid output to serve domestic agrochemical and solvent formulation demand. Dual carbon goals under national climate policy create regulatory pressure for bio-based platform chemical development. The Shandong Peninsula chemical cluster concentrates heterogeneous catalyst engineering capacity for sulfuric acid replacement.
Netherlands
Specialty chemical distributors consolidate fragmented European demand for levulinic acid derivatives in personal care and coatings applications. EFSA compliance requirements for food contact materials extend registration timelines and testing expenditure for novel esters. The Rotterdam-Antwerp port complex facilitates feedstock import logistics for integrated biorefinery operations.
Bio-Based Levulinic Acid Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue derivative specialization and catalytic process technology licensing. The vendor base stratifies across integrated biorefinery operators, catalytic technology licensors, and specialty ester formulators. Three archetypes dominate: backward-integrated agricultural residue processors, heterogeneous catalyst technology providers, and custom synthesis contract specialists. Capacity expansion and multi-year offtake negotiation constitute the dominant competitive moves as producers lock in pharmaceutical and industrial chemical buyer relationships.
Within the integrated biorefinery tier, GFBiochemicals and Avantium exemplify contrasting geographic and technological positioning. GFBiochemicals represents European backward integration into agricultural residue supply chains. Avantium occupies the catalytic process technology vector with Dutch-origin engineering focus. Segetis anchors the derivative specialization archetype through levulinic acid ester development for personal care applications. Langfang Triple Well Chemicals Co. Ltd exemplifies Chinese-scale chemical intermediate production capacity. These four entities collectively illustrate the competitive structure spanning feedstock control, process innovation, and formulation customization.
| Leading Market Players |
|---|
| Avantium |
| GreenSolRes |
| GFBiochemicals |
| Langfang Triple Well Chemicals Co. Ltd |
| Heroy Chemical Industry Co. |
| Biofine Technology |
| Segetis |
| Zhonglan Industry Co. |
| NXTLEVVEL Biochem |
| Others |
Value Chain & Pricing Dynamics
Heterogeneous catalyst adoption is compressing production economics while redistributing supply power toward producers with in-house solid acid engineering capabilities, tightening margins for sulfuric acid-dependent operators and rewarding capital-intensive technology licensors.
Pricing Analysis
Distributor margins in specialty chemical channels absorb 15-25 point markups for levulinic acid derivatives, while direct-to-industrial contracts trade at volume-scaled discounts. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and feedstock-grade levels separates certified REACH-registered supply from unregistered commodity streams. Cost compression in technical-grade tiers is intensifying because Chinese intermediate producers are scaling acid-catalyzed output. Pharmaceutical manufacturers show least price sensitivity due to regulatory compliance requirements; agrochemical formulators exhibit highest elasticity.
Supply Chain Analysis
Agricultural residue supply rests on Italian Po Valley farming operations, Chinese Shandong Peninsula corn stover collection, and German Rhineland-Palatinate wheat straw aggregation. Sulfuric acid, heterogeneous catalyst substrates, and lignocellulosic biomass constitute the three critical input dependencies. Single-source vulnerability concentrates in specialty zeolite catalyst supply from Japanese and German engineering houses. Distribution runs through Rotterdam-Antwerp port complexes for European derivative formulation, with direct rail links serving German industrial chemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based levulinic acid functions as a stable compounder anchored by REACH compliance mandates that structurally displace petroleum-derived intermediates regardless of commodity cycle position.
For Market Incumbents: To counter margin erosion from Chinese-scale sulfuric acid producers, deepen backward integration into agricultural residue collection networks in Italy and Germany while accelerating ISO bio-based content certification investment to lock in cosmetics industry multi-year offtake agreements. For New Entrants and Emerging Players: Launch via specialty distributor partnerships targeting agrochemical salt and ester derivatives, the least penetrated application segment with unconsolidated buyer bases. White-space concentrates in biodegradable crop protection carriers for European formulators seeking EFSA-registered active ingredient alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among heterogeneous catalyst technology licensors with proven pilot-scale data but pre-commercial revenue. Five-to-ten year viability hinges on solid acid process cost parity achievement. The signal to watch is ECHA substance evaluation timeline compression for novel derivative registrations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Supply | GFBiochemicals' Italian Po Valley sourcing secures feedstock cost stability against commodity biomass volatility. |
| Heterogeneous Catalyst Technology Licensing | Avantium's solid acid engineering eliminates sulfuric acid handling costs while enabling modular biorefinery deployment. |
| Long-term Supply Agreement with Pharmaceutical Manufacturers | REACH-registered producers lock in multi-year offtake through certified high-purity grade contracts. |
| Joint Venture for Second-Generation Feedstock Processing | Porto Torres industrial zone partnerships aggregate Sardinian agricultural residue for commercial-scale lignocellulosic output. |
| Green Manufacturing Transition to Solid Acid Systems | Segetis' catalytic process shift reduces wastewater treatment burden while meeting EU Green Deal carbon accounting requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biorefinery plant managers, specialty chemical procurement leads at downstream polymer manufacturers, distribution channel partners in Rotterdam-Antwerp logistics hubs, and technical R&D directors at catalyst engineering firms with secondary validation through ECHA substance evaluation databases, Cefic chemical industry trade statistics, customs and trade flow records, and SEC filings from listed chemical intermediate producers. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting applied product type splits across pure acid and derivative categories, application modeling through chemical intermediate, pharmaceutical, solvent, and food additive channels, and end-user industry differentiation between industrial chemicals, cosmetics, agrochemicals, and food and beverage sectors. CAGRs derived from regression analysis against feedstock cost trajectories and regulatory compliance cost curves. Forecast inputs incorporated REACH registration timeline probabilities and EU Green Deal carbon accounting implementation schedules.
Several conditions sit outside the modeled scope, including unannounced ECHA substance evaluation protocol changes, sulfur commodity price shocks exceeding historical volatility bands, and breakthrough fermentation-based levulinic acid production at commercial scale. Forecasts reflect documented assumptions around catalyst technology adoption rates and agricultural residue supply elasticity. A small set of named triggers warrants ongoing watch: ECHA evaluation timeline acceleration, Chinese dual carbon policy enforcement intensity, and German industrial chemical cluster demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market