
 Europe Biopesticides Market | 2026-2036
Europe Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biopesticides Market Foresight
CE marking under the EU Fertilising Products Regulation is rotating as the primary gatekeeper for microbial biostimulant and biopesticide market access across member states. Koppert B.V. anchors its position through controlled production of beneficial nematodes and parasitic wasps in dedicated facilities across the Netherlands and Italy. Corteva Agriscience competes by extending its biologicals pipeline through in-house fermentation capacity and distribution partnerships with European agricultural cooperatives.
Biopesticides comprise living organisms, naturally occurring substances, and metabolites formulated to suppress agricultural pests through modes including competition, antibiosis, or induced systemic resistance in host plants. Liquid formulations dominate commercial deployment due to compatibility with existing spray equipment and foliar application protocols used in vineyard and orchard systems. Bacterial product types, particularly Bacillus thuringiensis and Bacillus subtilis strains, occupy the largest share of active ingredient registrations. Agricultural crops represent the deepest application segment, though horticulture is gaining share as greenhouse operators adopt zero-residue protocols for export-bound produce.
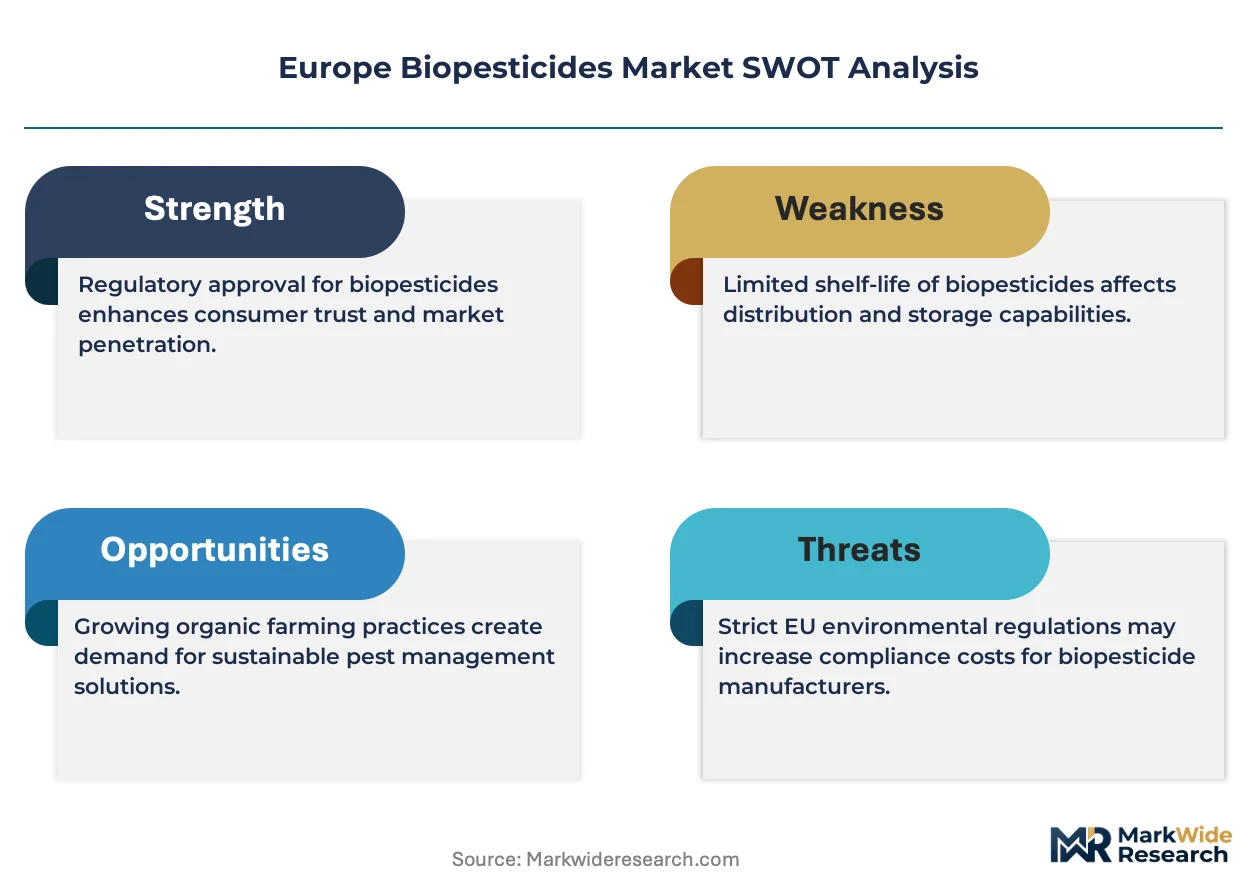
EMA and EFSA jointly evaluate microbial active substances under Regulation 1107/2009, creating a dual-track review process that extends development timelines but elevates product credibility with risk-averse distributors. The EU Green Deal's 50% pesticide reduction target is forcing national regulators in France, Germany, and Spain to accelerate biopesticide registration queues and expand approved substance lists. Stakeholders must monitor how the forthcoming revision of sustainable use directives reshapes reimbursement and advisory support for biological crop protection at member-state level.
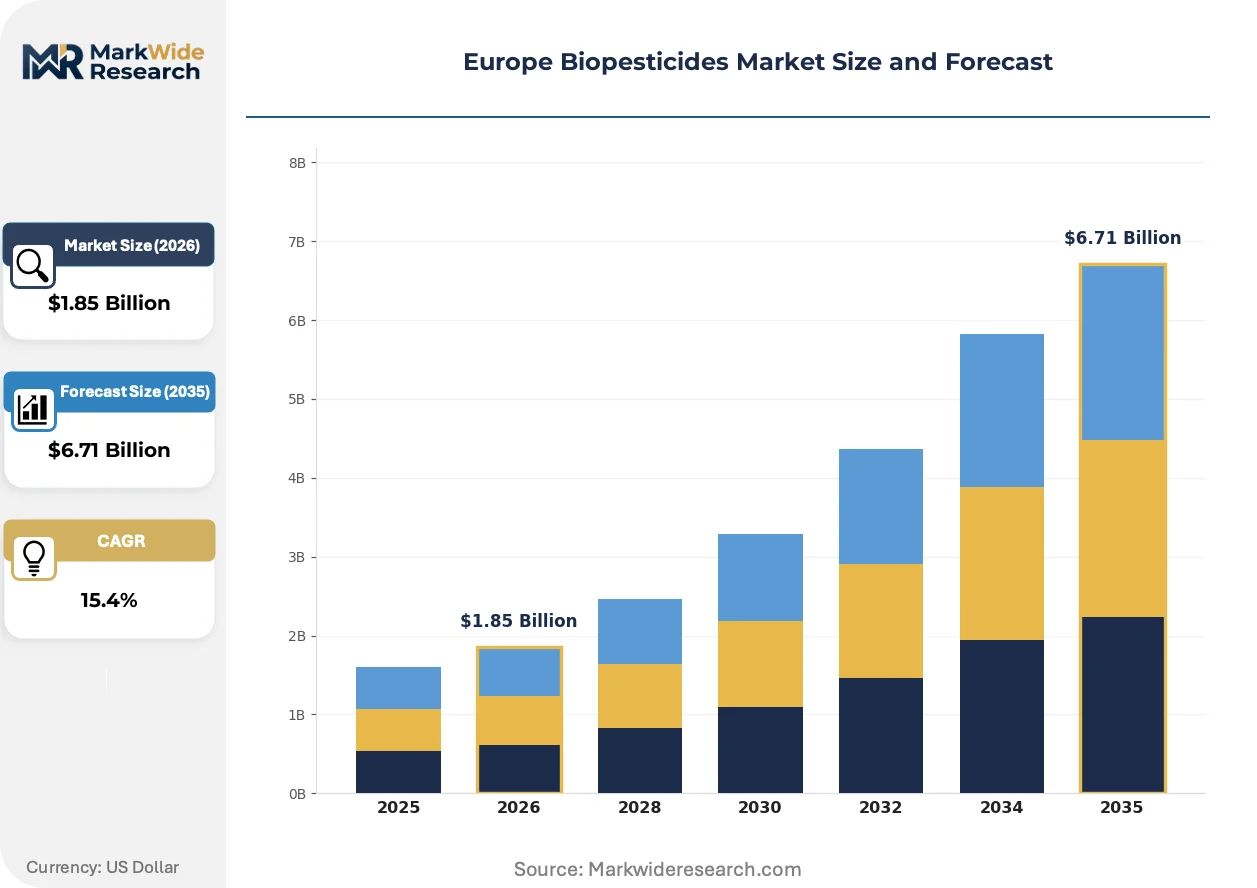
Market Dynamics
The EU Green Deal's 50% synthetic pesticide reduction mandate is compressing substitution timelines and forcing national regulators to expand approved biopesticide substance lists faster than technical validation cycles can match.
Growth Catalysts
- Farm to Fork strategy:The EU's binding 2030 targets for chemical pesticide reduction are creating mandatory pull-through demand for biological alternatives in member state agricultural programs.
- EMA-EFSA dual-track review:Joint microbial active substance evaluation under Regulation 1107/2009 elevates product credibility with risk-averse distributors and accelerates insurance-backed financing for growers.
- Mediterranean specialty crop expansion:Vineyard and orchard operators across France, Spain, and Italy are scaling integrated pest management mandates that specify microbial inoculant protocols.
Market Restraints
- Fermentation input volatility:Molasses and soy-derived nutrient media prices fluctuate with commodity grain markets, compressing margin predictability for Bacillus strain producers.
- Registrant concentration:A handful of Dutch and German contract research organizations control the majority of GLP-compliant ecotoxicology studies required for EFSA dossiers.
- Shelf-life technical limits:Viable spore counts in liquid formulations degrade below label claims under temperature excursions common in southern European distribution chains.
Strategic Opportunities
- Polish and Romanian horticulture:Greenhouse vegetable exports to German and Nordic retailers are adopting zero-residue protocols that specify biopesticide-only crop protection windows.
- Drone-based aerial application:Ultralow-volume spray systems are enabling microbial biopesticide deployment in vineyard terrain inaccessible to ground equipment.
- CE marking expansion:The EU Fertilising Products Regulation's biostimulant-biopesticide interface is creating unified market access pathways previously fragmented across member state fertilizer laws.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set combining microbial physiology with adjuvant compatibility testing is concentrated among retiring cohorts at legacy agrochemical firms.
- Batch-to-batch certification lag:Each production lot requires viability confirmation before release, creating inventory carry costs that strain working capital for smaller registrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biopesticides Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.71 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Plant Extracts, Biofungicides Application: Agricultural Crops, Horticulture, Turf, Ornamentals End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Formulation: Granules, Liquids, Powders, Emulsifiable Concentrates |
| Companies Covered | Certis Europe B.V., Corteva Agriscience, Koppert B.V., Seipasa S.A., Biolchim SPA, Andermatt Group AG, Valent Biosciences LLC, Bionema, Atlántica Agrícola, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biopesticides Market Shifts & Advancements
Biological crop protection is fragmenting into two parallel development tracks: precision-formulated microbial consortia for high-value permanent crops versus commoditized single-strain products for broadacre arable systems.
RNA interference biopesticides are bifurcating the competitive landscape. These sequence-specific molecules silence essential pest genes without environmental persistence. Large-scale greenhouse operators in the Netherlands and Belgium are piloting RNAi programs against thrips and whitefly. The technology is compressing traditional chemical insecticide replacement cycles from decade-long resistance management rotations to season-by-season trait customization.
REACH registration requirements for novel microbial metabolites are tightening substance identification thresholds. ECHA's 2023 guidance on complex substances demands higher-resolution analytical characterization of fermentation supernatants. Suppliers of plant extract-based biopesticides face reformulation costs to meet the new specifications, with Mediterranean herb-derived products most affected due to batch variability in wild-harvested raw material.
Cooperative procurement consortia are displacing individual farm input purchasing across French cereal regions. Groups of 50-200 growers now negotiate multi-year biopesticide supply agreements with guaranteed offtake volumes. This concentration is shifting pricing power toward buyers and forcing suppliers to absorb inventory risk previously held at distributor level, with the Loire Valley and Champagne-Ardenne cooperatives most advanced in this transition.
Europe Biopesticides Market Segmentation
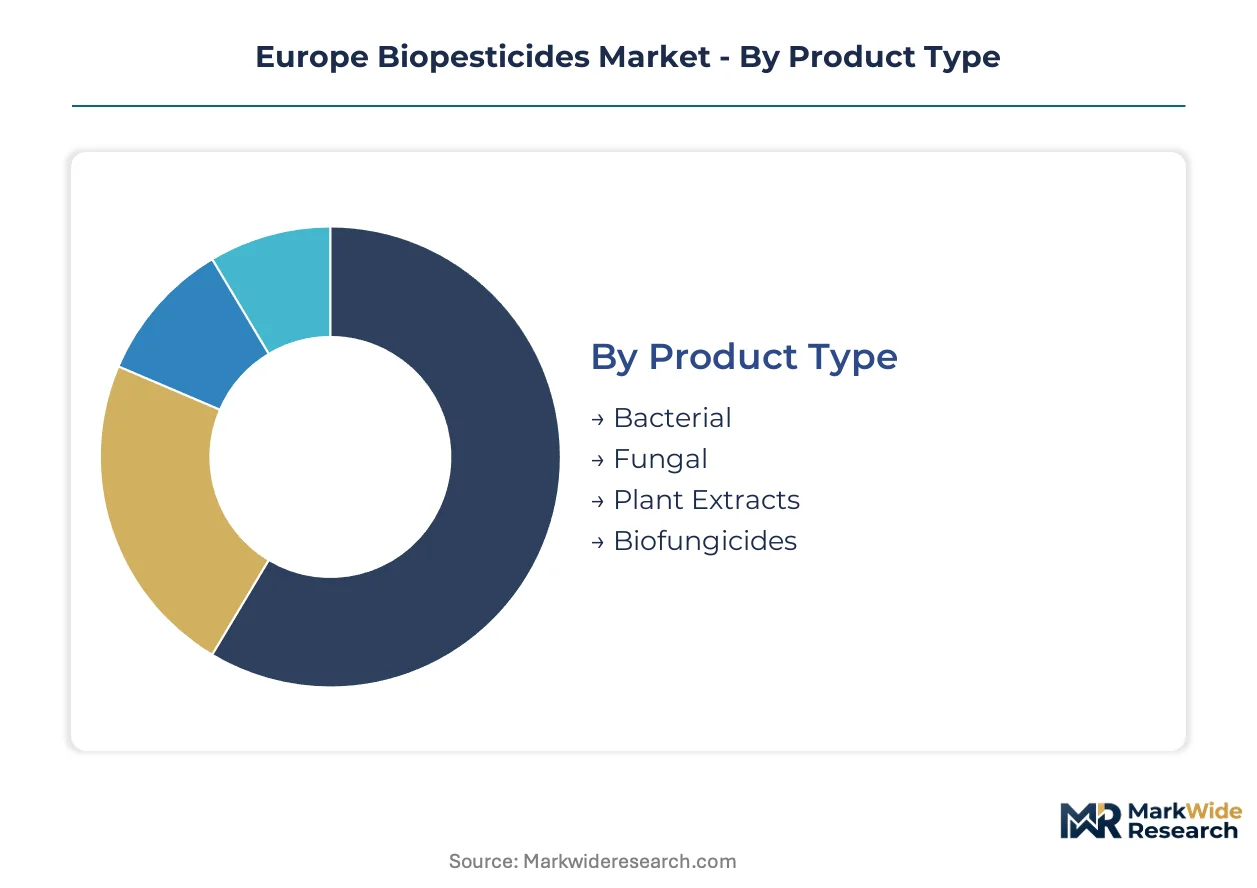
Segmentation in the Europe biopesticides market reflects divergent regulatory pathways and application economics. EFSA dossier requirements vary sharply by active substance class, while formulation choices determine compatibility with existing spray infrastructure across Mediterranean vineyards and northern European arable systems.
Product Type:
EMA-EFSA evaluation timelines differ substantially across microbial kingdoms, with bacterial submissions benefiting from established toxicology protocols while fungal and plant-derived actives face evolving guidance documents.
- Bacterial:Bacillus thuringiensis and Bacillus subtilis strains dominate commercial registrations due to well-characterized protein crystal toxins and surfactant lipopeptides. French vineyard operators specify bacterial biofungicides in IPM protocols for downy mildew suppression, though fermentation batch variability creates certification bottlenecks at EFSA.
- Fungal:Trichoderma and Beauveria bassiana products command premium positioning in greenhouse horticulture where contact-only activity suffices. Italian tomato producers in Puglia and Sicily are scaling Trichoderma harzianum programs for soil-borne pathogen suppression ahead of export certification deadlines.
- Plant Extracts:Mediterranean herb-derived pyrethrins and azadirachtin face REACH metabolite identification hurdles under ECHA's complex substances guidance.
- Biofungicides:This functional category spans multiple organism types but clusters regulatory attention on post-harvest decay control in Spanish citrus export supply chains.
Established volume favors bacterial platforms; emerging adoption favors fungal formulations in protected cultivation.
Application:
Margin structures diverge sharply between broadacre commodity systems and high-value permanent crops, with the latter absorbing price premiums for zero-residue certification.
- Agricultural Crops:Cereal and oilseed growers across France's Bassin Parisien and Germany's Schleswig-Holstein deploy bacterial biopesticides within cooperative procurement frameworks. The segment trades volume for margin, with Loire Valley cereal cooperatives negotiating multi-year supply agreements that shift inventory risk to suppliers.
- Horticulture:Greenhouse vegetable operators in the Netherlands and Belgium pilot RNAi biopesticides against thrips and whitefly, compressing replacement cycles from decade-long rotations to seasonal trait customization. Polish and Romanian exporters to German retailers adopt biopesticide-only windows to meet zero-residue protocols.
- Turf:Golf course and sports field maintenance in the UK and Ireland drives demand for granular formulations with extended residual activity.
- Ornamentals:Dutch floriculture clusters specify liquid microbial consortia for integrated pest management in rose and chrysanthemum propagation.
Revenue concentration sits with agricultural crops; steepest expansion trajectory belongs to horticulture as protected cultivation scales.
End User:
Procurement authority is consolidating toward fewer, larger decision-makers with technical validation capabilities.
- Farmers:Individual vineyard and orchard operators in Italy's Veneto and Spain's La Rioja specify biopesticide rotations within mandated IPM frameworks, though technical advisory dependence remains high.
- Agricultural Cooperatives:French cereal groups of 50-200 members now negotiate direct supply agreements, displacing traditional distributor intermediaries and compressing available margin pools.
- Distributors:Risk-averse agronomy service providers demand EMA-EFSA dual-track credibility for insurance-backed grower financing programs.
- Retailers:German and Nordic supermarket chains impose zero-residue specifications that cascade through Polish and Romanian greenhouse supply chains.
Direct farmer engagement dominates premium segments; cooperative concentration is accelerating in commodity crop systems.
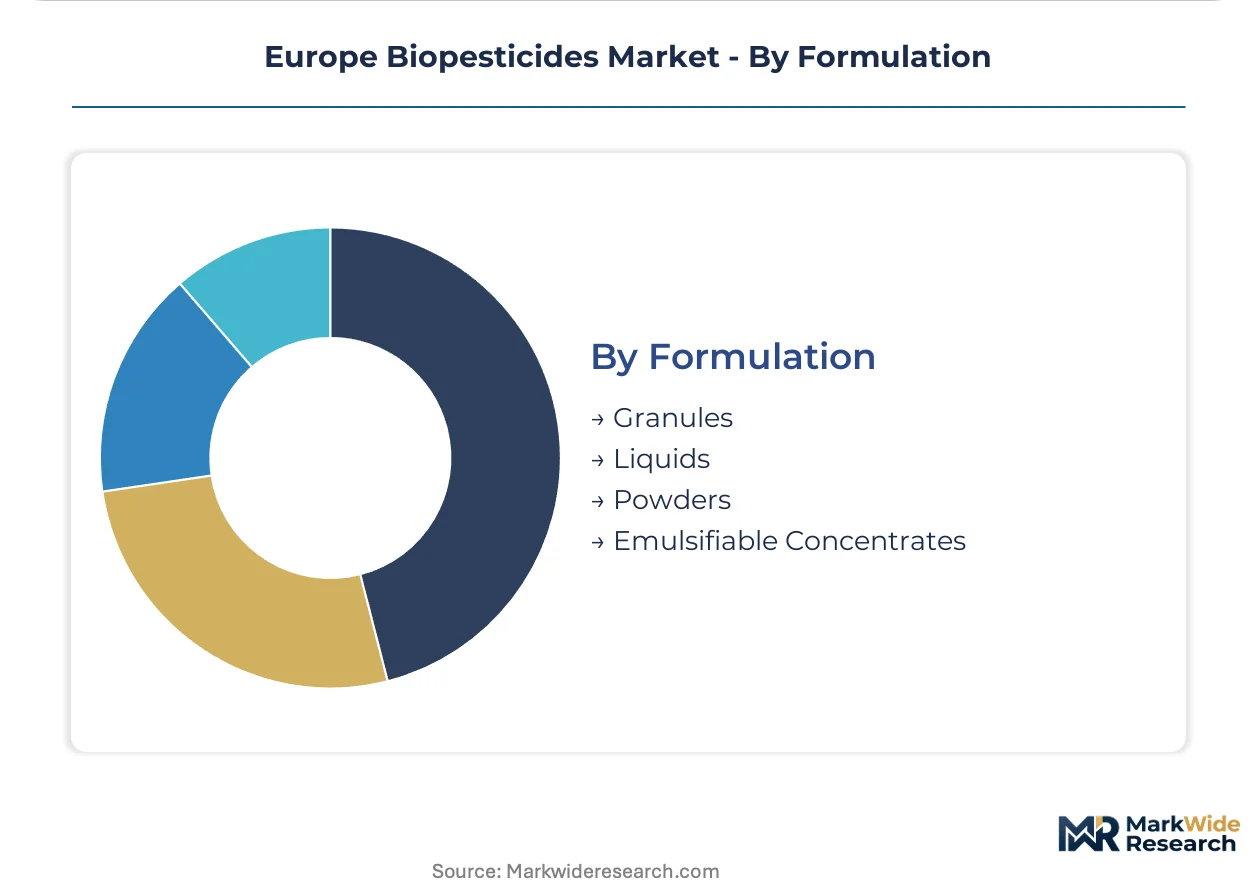
Formulation:
Physical form determines supply chain viability, with temperature excursion sensitivity creating geographic constraints on distribution reach.
- Liquids:Compatibility with existing vineyard and orchard spray equipment drives dominance in Mediterranean permanent crop systems. Viable spore counts degrade below label claims under southern European distribution temperature profiles, constraining shelf-life claims.
- Granules:Soil application in turf and certain horticultural systems benefits from extended residual activity and reduced drift liability.
- Powders:Dry formulations offer logistics advantages for export to regions with limited cold-chain infrastructure, though reconstitution protocols add operational complexity at farm level.
- Emulsifiable Concentrates:Oil-based carriers enhance cuticular penetration for foliar biofungicides in high-value fruit crops.
Liquid formats command current volume; granule adoption is climbing in turf and soil-application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's binding pesticide reduction targets are redrawing procurement patterns across member states, with national regulators accelerating biopesticide registration queues to meet 2030 deadlines.
France
Vineyard operators in Bordeaux and Champagne specify bacterial biofungicides within mandated IPM protocols for downy mildew suppression. ANSM and national agricultural regulators enforce strict residue monitoring that elevates credibility requirements for distributor insurance programs. The Loire Valley cereal cooperative clusters now negotiate direct multi-year supply agreements, displacing traditional intermediaries.
Spain
Andalusian greenhouse exporters adopt zero-residue protocols for German and Nordic retail chains, specifying biopesticide-only crop protection windows. The Ministry of Agriculture coordinates with EFSA to fast-track microbial active substance approvals under Farm to Fork acceleration measures. Valencia's citrus export supply chains cluster regulatory attention on post-harvest decay control certification.
Italy
Puglia and Sicilian tomato producers scale Trichoderma harzianum programs for soil-borne pathogen suppression ahead of export deadlines. Veneto vineyard operators face technical advisory dependence within mandated rotation frameworks. The Emilia-Romagna agricultural machinery corridor integrates drone-based aerial application systems for vineyard terrain inaccessible to ground equipment.
Netherlands
Large-scale greenhouse operators in Westland pilot RNA interference biopesticides against thrips and whitefly, compressing replacement cycles to seasonal customization. Koppert B.V. anchors production of beneficial nematodes and parasitic wasps in dedicated facilities across the country. The Dutch food safety authority enforces CE marking compliance under the EU Fertilising Products Regulation for unified market access.
Germany
Schleswig-Holstein cereal growers deploy bacterial biopesticides within cooperative procurement frameworks that shift inventory risk to suppliers. The Federal Office of Consumer Protection coordinates EMA-EFSA dual-track microbial evaluations that extend development timelines. Bavarian agricultural research stations validate fermentation batch consistency for Bacillus strain producers facing certification bottlenecks.
Europe Biopesticides Market Competitive Landscape
Listed leaders compete with private specialists across regulatory credibility and fermentation capacity. The vendor base spans Dutch biologicals pioneers, Swiss precision agriculture groups, and Spanish plant extract specialists. Three archetypes dominate: integrated agrochemical majors with in-house fermentation, dedicated biologicals pure-plays with controlled production facilities, and regional herb-derived extract houses with wild-harvesting networks. Competitive moves concentrate on EFSA dossier acceleration and cooperative procurement lock-ins.
Within the pure-play biologicals tier, Koppert B.V. and Andermatt Group AG exemplify controlled-production archetypes with dedicated facilities across multiple member states. Corteva Agriscience represents the integrated major model, extending biologicals pipelines through captive fermentation capacity. Seipasa S.A. anchors the Mediterranean plant-extract specialist position. Each occupies a distinct regulatory pathway position under REACH and the EU Fertilising Products Regulation.
| Leading Market Players |
|---|
| Certis Europe B.V. |
| Corteva Agriscience |
| Koppert B.V. |
| Seipasa S.A. |
| Biolchim SPA |
| Andermatt Group AG |
| Valent Biosciences LLC |
| Bionema |
| Atlántica Agrícola |
| Others |
Supply & Pricing Matrix
Multi-year cooperative procurement agreements between French cereal cooperatives and Bacillus strain suppliers lock in volume commitments and price visibility, insulating growers from fermentation input volatility while transferring inventory risk to registrants.
Pricing Analysis
Certification level under EMA-EFSA dual-track review creates the primary spread between premium and standard tiers, with CE-marked biostimulant-biopesticide interface products commanding higher positioning. Three-tier pricing structure across premium, standard, and economy levels reflects batch-to-batch viability confirmation costs and advisory service bundling. Cost compression in standard-tier bacterial formulations is intensifying because cooperative procurement consortia consolidate bargaining power. French vineyard operators show least price sensitivity due to zero-residue certification premiums, while Polish greenhouse exporters exhibit highest sensitivity to input cost fluctuations.
Supply Chain Analysis
The Netherlands and Italy anchor controlled production of beneficial nematodes and parasitic wasps through Koppert B.V.'s dedicated facility network. Fermentation capacity draws from molasses and soy-derived nutrient media sourced from commodity grain markets, with viable spore counts degrading under southern European temperature profiles. Single-source vulnerability concentrates in Dutch and German contract research organizations controlling GLP-compliant ecotoxicology studies for EFSA dossiers. Distribution runs through agricultural cooperatives displacing traditional distributor intermediaries, particularly in France's Loire Valley and Champagne-Ardenne clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory pathways and application economics creates niche opportunities as the EU Green Deal's pesticide reduction targets accelerate substitution demand across member states.
For Market Incumbents: Compound regulatory credibility advantages by accelerating EFSA dossier submissions for microbial consortia before guidance documents harden. Backward integration into fermentation capacity insulates margin position from molasses price volatility threatening Bacillus strain producers. Expand in-house production of beneficial nematodes to match Koppert B.V.'s controlled-facility model across Mediterranean markets. For New Entrants and Emerging Players: Technical advisory gaps in Italian Veneto and Spanish La Rioja vineyard regions present white-space opportunities where incumbent coverage remains thin. Polish and Romanian horticulture exporters to German retailers offer the most penetrable entry point through zero-residue protocol compliance. Pursue drone-based aerial application partnerships with Emilia-Romagna agricultural machinery corridors as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Regional herb-derived extract houses with wild-harvesting networks in Mediterranean markets represent compelling acquisition targets as REACH metabolite identification requirements tighten. Long-term viability hinges on CE marking expansion under the EU Fertilising Products Regulation unifying previously fragmented member state access. Monitor ECHA guidance revisions on complex substances as the inflection indicator for reformulation cost exposure among plant extract specialists.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Acceleration | Compresses development timelines under Farm to Fork pressure in France, Germany, and Spain. |
| Fermentation Capacity Expansion | Captures margin pool from cooperative procurement consolidation shifting inventory risk. |
| Drone Application Partnership | Unlocks vineyard terrain in Italy's Emilia-Romagna corridor inaccessible to ground equipment. |
| CE Marking Pathway Investment | Secures unified market access under EU Fertilising Products Regulation across member states. |
| RNAi Pipeline Development | Positions for seasonal trait customization replacing decade-long resistance rotations in Netherlands greenhouses. |
Research Methodology
The analysis maps bacterial, fungal, plant extract, and biofungicide sub-sectors, each validated through fermentation technologists, regulatory affairs leads at registrants, cooperative procurement managers, and EFSA dossier consultants. Primary interviews with Dutch biologicals producers, Mediterranean herb extract harvesters, and French cereal cooperative buyers combined with secondary validation from EMA submission databases, REACH registration filings, and EU agricultural policy directives. Bottom-up strain-level production estimates and top-down member state substitution targets underwent triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include active substance class, application crop type, formulation physical state, and end-user procurement authority. CAGRs derived from regulatory queue acceleration rates, cooperative adoption curves, and greenhouse export certification deadlines. Forecast inputs incorporated Farm to Fork target enforcement variance and ECHA complex substances guidance evolution.
Forecasts assume regulatory continuity in EU Green Deal implementation and EMA-EFSA dual-track evaluation protocols; material policy shifts would require re-modeling. Specific risks include fermentation input commodity price spikes, batch certification bottlenecks, and REACH metabolite identification threshold changes. Recalibration cycles align with material shifts in sustainable use directive revisions and member state reimbursement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Agricultural Biologicals Market