
 Biofuel Enzymes Market | 2026-2036
Biofuel Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Biofuel Enzymes Market Analysis
Enzyme formulation services is tilting toward integrated biotechnology platforms that combine strain development with on-site fermentation support. Novozymes leverages its Danish R&D base to sustain leadership in thermostable cellulase engineering for lignocellulosic feedstocks. BASF SE anchors its position through backward integration into microbial strain libraries, while DSM-Firmenich competes via specialized enzyme cocktails optimized for corn-starch ethanol throughput.
Biofuel enzymes are protein biocatalysts, typically operating at temperatures between 50°C and 70°C and pH ranges of 4.0 to 6.0, that accelerate the hydrolysis of complex carbohydrates and lipids into fermentable sugars and fatty acid esters for renewable fuel production. Cellulases dominate current revenue pools due to their critical role in breaking down lignocellulosic biomass, though amylases retain mature, high-volume positions in first-generation starch ethanol. Genetic engineering platforms represent the fastest-expanding technology segment, as CRISPR-edited fungal strains yield enzymes with improved specific activity and reduced inhibitor sensitivity.
The US EPA enforces renewable volume obligations under the Renewable Fuel Standard, while the EU applies RED III targets and F-Gas Regulation constraints on process emissions, collectively mandating cleaner conversion pathways that favor advanced enzymatic systems over chemical catalysis. Brazil's national biofuel policy and India's PLI scheme for biomass-based fuels are extending compliance architectures that directly stimulate enzyme procurement decisions. Stakeholders must monitor how carbon intensity scoring methodologies evolve, as these metrics increasingly determine which enzyme technologies qualify for premium fuel credits.
Market Dynamics
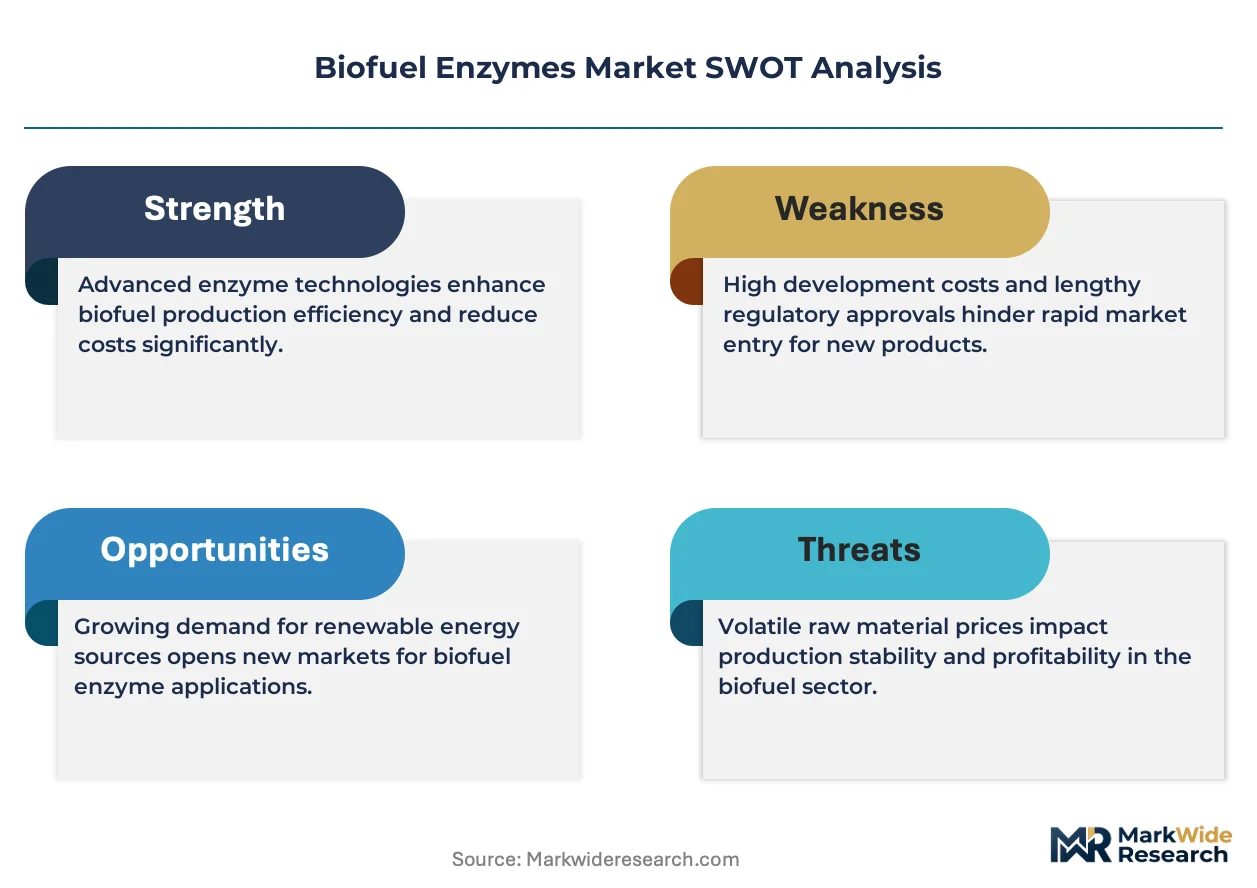
Tighter renewable fuel mandates are compressing the window for enzymatic conversion efficiency gains, forcing enzyme producers to engineer biocatalysts that tolerate higher inhibitor loads while maintaining throughput at commercial scale.
Growth Catalysts
- EPA Renewable Fuel Standard:Blending obligations under the US framework mandate advanced biofuel volumes that require cellulase-intensive conversion pathways, pulling enzyme procurement decisions toward high-activity formulations.
- Lignocellulosic feedstock expansion:Agricultural residue collection infrastructure in Brazil and India is scaling, creating addressable substrate volumes for second-generation enzyme systems.
- CRISPR-edited strain development:Fungal engineering platforms are yielding cellulases with improved thermostability, reducing cooling costs in continuous fermentation operations.
Market Restraints
- Specialized fermentation feedstock costs:Dextrose and yeast extract prices fluctuate with agricultural commodity cycles, compressing margin buffers for enzyme manufacturers.
- Single-source supplier concentration:Thermostable cellulase IP remains concentrated among Danish and Dutch biotechnology clusters, creating procurement vulnerability for fuel refiners.
- Enzyme storage stability limits:Liquid cellulase formulations require cold-chain logistics that constrain distribution reach into tropical processing regions.
Strategic Opportunities
- India PLI scheme for biomass-based fuels:Production-linked incentives are stimulating domestic enzyme manufacturing capacity that currently imports the majority of biocatalyst demand.
- Waste oil transesterification:Lipase cocktails optimized for non-edible feedstocks are opening enzymatic biodiesel pathways that bypass food-fuel competition constraints.
- On-site fermentation service contracts:Integrated biotechnology platforms that combine strain development with localized production are displacing bulk enzyme shipment models.
Industry Challenges
- Scale-up validation timelines:Moving CRISPR-edited strains from pilot to commercial fermentation requires 18-24 month regulatory dossier preparation for EPA and ECHA notifications.
- Legacy starch ethanol retrofit complexity:First-generation facilities face mechanical constraints when integrating cellulase hydrolysis trains designed for lignocellulosic feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofuel Enzymes Market |
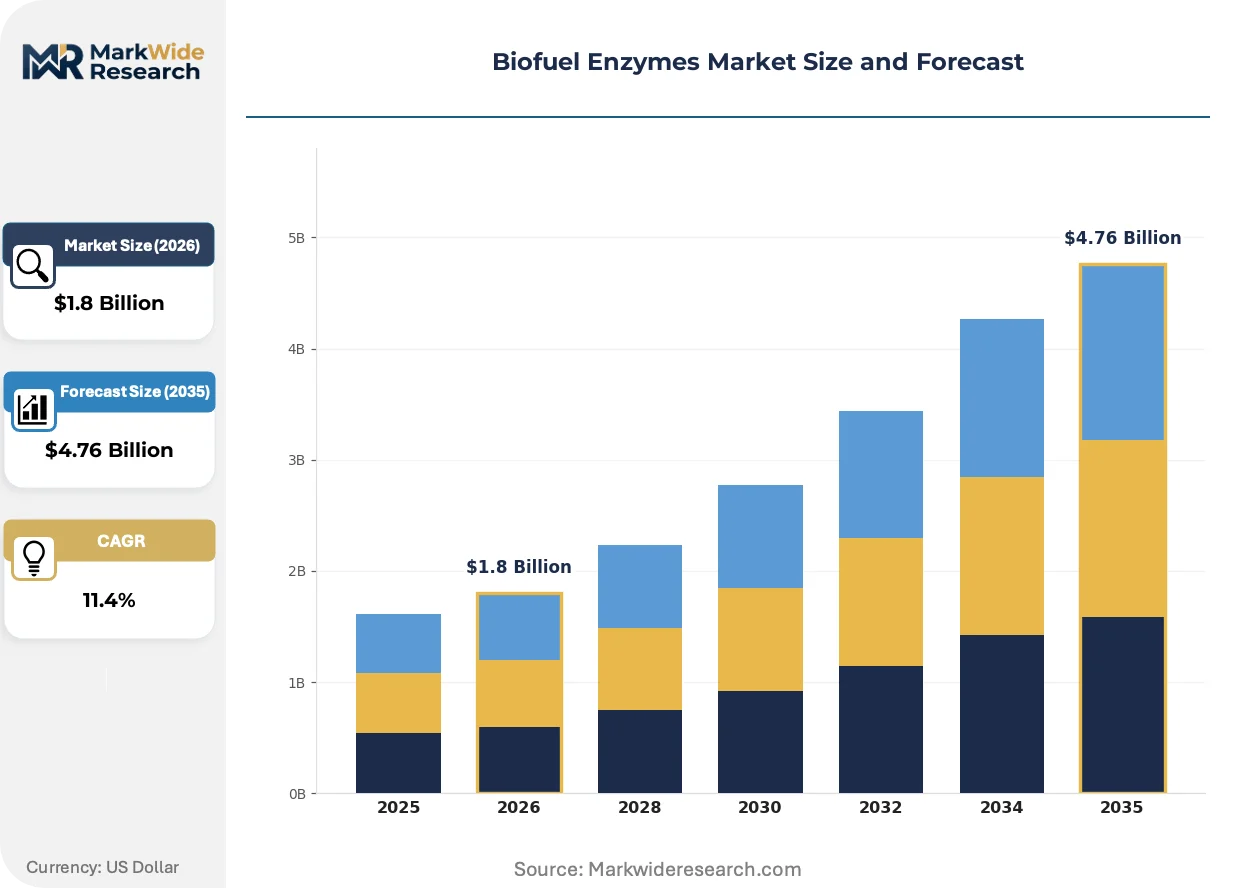
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulases, Amylases, Lipases, Proteases Source: Microbial, Plant, Fungal, Animal Application: Biodiesel Production, Bioethanol Production, Biomass Conversion, Waste Treatment Technology: Fermentation Technology, Genetic Engineering, Enzymatic Hydrolysis, Liquid-State Fermentation |
| Companies Covered | BASF SE, International Flavors & Fragrances Inc., Novozymes, Dyadic International, Kerry Group, DuPont Industrial Biosciences, AB Enzymes, Advanced Enzyme Technologies, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofuel Enzymes Market Emerging Trajectories
Enzyme engineering platforms are converging with digital bioprocess control, creating feedback loops where real-time fermentation data directly informs strain optimization cycles.
Cellulase-amylase co-formulations are hybridizing hydrolysis steps for mixed-feedstock refineries, enabling simultaneous starch and cellulose breakdown in single-reactor configurations. Brazilian sugarcane ethanol processors are piloting these systems at 10,000-liter scale, compressing capex requirements for facility retrofits by eliminating dedicated pretreatment units.
The EU F-Gas Regulation is constraining process emissions from chemical catalysis routes, redirecting capital toward enzymatic pathways in German and Dutch renewable diesel projects. Fuel producers are qualifying enzyme suppliers against carbon intensity scoring methodologies that determine premium credit eligibility under RED III compliance architectures.
Refiner procurement patterns are fragmenting as integrated oil companies internalize enzyme strain development through captive biotechnology acquisitions. This vertical consolidation is compressing the addressable market for standalone enzyme suppliers in North American and European biofuel corridors, though Brazilian and Indian processors remain reliant on external biocatalyst sourcing.
Biofuel Enzymes Market Segmentation
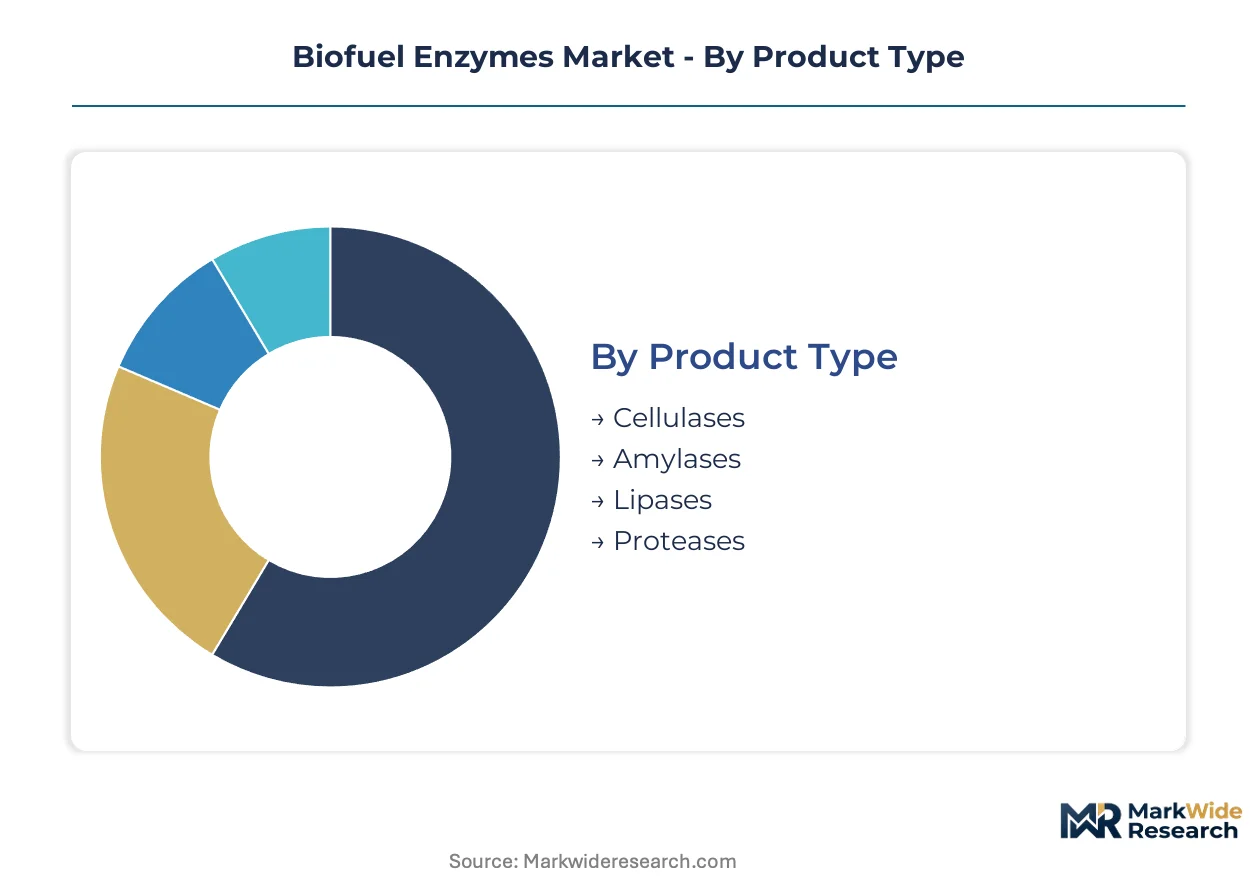
Enzyme performance requirements diverge sharply across biofuel conversion pathways, with substrate chemistry and process temperature dictating formulation specifications. Procurement decisions cluster around thermostability thresholds and inhibitor tolerance profiles that separate first-generation starch ethanol from second-generation lignocellulosic systems.
Product Type:
Cost tier positioning separates commodity biocatalysts from precision-engineered enzyme cocktails optimized for specific feedstock chemistries.
- Cellulases:These multi-enzyme complexes cleave beta-1,4-glycosidic bonds in cellulose chains, operating optimally at 50-60°C with specific activities exceeding 100 FPU/g. Demand concentrates in Brazilian sugarcane residue processing facilities where bagasse-to-ethanol retrofits require thermostable formulations that tolerate phenolic inhibitors from lignin depolymerization.
- Amylases:Alpha-amylase and glucoamylase variants hydrolyze starch polymers into fermentable glucose, functioning at broader pH ranges of 4.0-6.5. US corn-ethanol refineries in Iowa and Illinois anchor mature procurement volumes, though facility age is compressing pricing power as legacy plants defer enzyme upgrades.
- Lipases:Triacylglycerol hydrolases catalyzing esterification for fatty acid methyl ester production.
- Proteases:Peptide bond-cleaving enzymes deployed for cell lysis in algal biofuel extraction pathways.
Amylases command the established base. The steepest expansion runs through cellulases.
Source:
Application requirements for thermal stability and production scalability determine whether microbial, fungal, or alternative expression platforms secure procurement contracts.
- Microbial:Bacterial expression systems, predominantly Bacillus subtilis and Escherichia coli platforms, deliver high-yield amylase production with fermentation cycles under 48 hours. Indian PLI scheme beneficiaries in Maharashtra and Gujarat are scaling microbial cellulase capacity to reduce import dependence from Danish suppliers.
- Fungal:Aspergillus niger and Trichoderma reesei strains secrete cellulase cocktails with superior specific activity against crystalline cellulose. Brazilian processors in São Paulo state specify fungal-sourced thermostable variants for continuous hydrolysis operations where cooling costs erode margins.
- Plant:Transgenic expression in tobacco and maize for bulk enzyme accumulation.
- Animal:Pancreatic lipase extracts for specialized transesterification catalysts.
Fungal sources command the established base. Microbial platforms are climbing the fastest on production-linked incentive tailwinds.
Application:
Volume concentration in fuel-type segments tracks national blending mandate architectures and feedstock availability geography.
- Bioethanol Production:Starch and lignocellulosic fermentation pathways consume 60-70% of industrial enzyme volumes by mass, with cellulase loading rates of 10-20 mg protein per gram cellulose. US EPA renewable volume obligations pull procurement toward high-activity formulations that maximize glucose yields from corn stover in Midwest processing corridors.
- Biodiesel Production:Lipase-catalyzed transesterification of waste cooking oils and non-edible feedstocks operates at milder temperatures than chemical routes, reducing energy intensity scores under EU RED III carbon accounting. German renewable diesel projects in Hamburg and Rotterdam qualification zones specify enzymatic pathways to secure premium fuel credits.
- Biomass Conversion:Pre-treatment enzyme cocktails for anaerobic digestion and syngas fermentation.
- Waste Treatment:Lipase-protease blends for fat-oil-grease degradation in municipal biogas facilities.
Bioethanol production commands the established base. Biodiesel production is gaining share fastest on waste-oil feedstock expansion.
Technology:
Customer type stratification separates integrated biorefineries with in-house strain development from merchant enzyme purchasers dependent on external fermentation services.
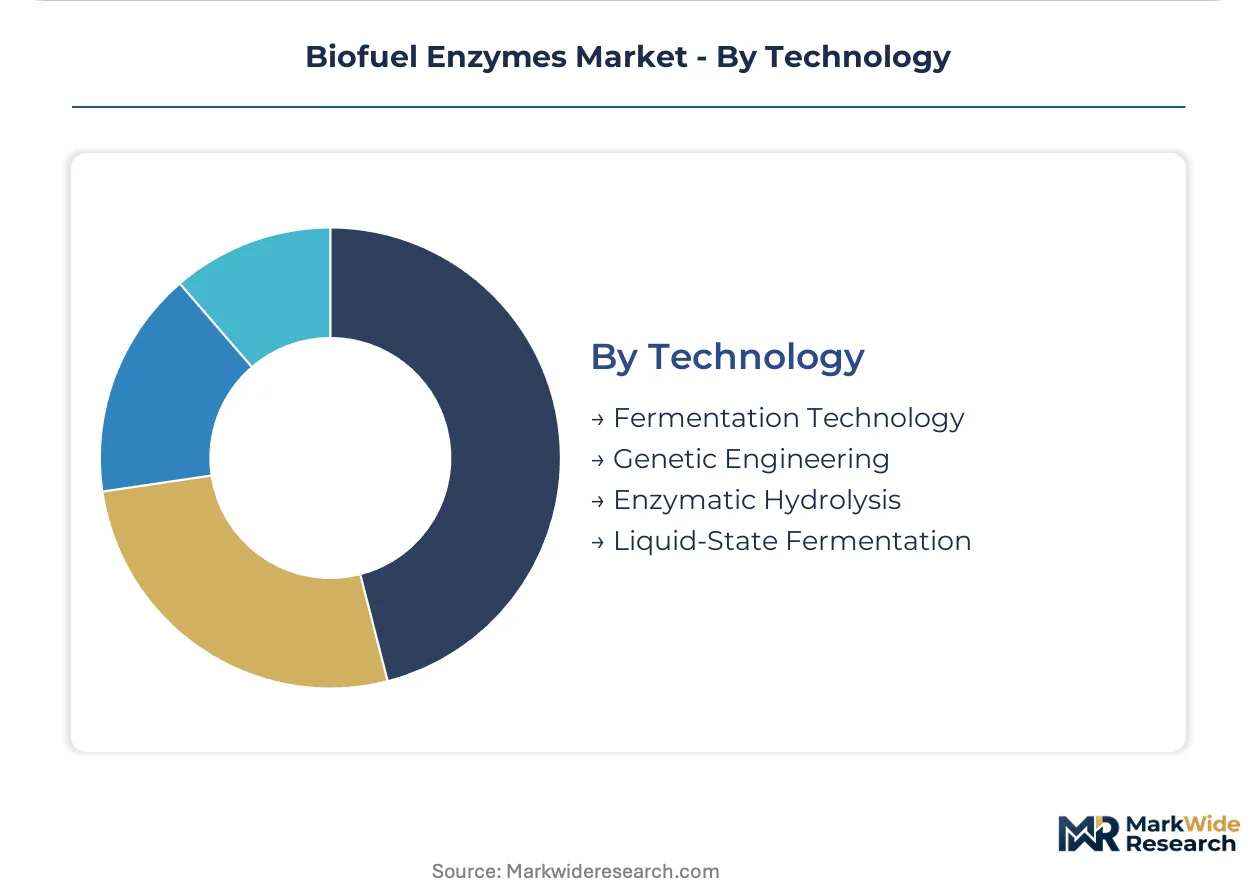
- Genetic Engineering:CRISPR-edited fungal strains yield cellulases with 15-30% improved thermostability and reduced glucose inhibition, compressing enzyme dosing requirements. Pilot-to-commercial scale-up timelines of 18-24 months for EPA and ECHA notifications constrain deployment velocity for novel constructs.
- Fermentation Technology:Submerged and solid-state production systems for bulk enzyme manufacturing with titer optimization through fed-batch protocols. Brazilian sugarcane processors contract on-site fermentation services to eliminate cold-chain logistics costs for liquid cellulase distribution.
- Enzymatic Hydrolysis:Process intensification through cellulase-amylase co-formulations for mixed-feedstock refineries.
- Liquid-State Fermentation:Standardized aerobic cultivation for high-volume amylase production.
Fermentation technology commands the established base. Genetic engineering is expanding most quickly on CRISPR platform maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme buyers in India and Brazil exhibit the highest price sensitivity due to import dependence and currency volatility, while US and EU refiners prioritize performance metrics and carbon intensity scores over unit cost.
United States
Corn-ethanol refineries in Iowa and Illinois drive mature amylase procurement volumes, though facility age compresses pricing power. The EPA's Renewable Fuel Standard mandates advanced biofuel volumes that pull enzyme decisions toward high-activity cellulase formulations. Midwest processing corridors in Nebraska and Minnesota are retrofitting corn stover conversion trains to access cellulosic ethanol credits.
Brazil
Sugarcane ethanol processors in São Paulo state specify thermostable fungal cellulases for continuous hydrolysis operations where cooling costs erode margins. ANVISA and the national biofuel policy framework extend compliance architectures that directly stimulate enzyme procurement. Bagasse-to-ethanol retrofits in Piracicaba and Ribeirão Preto are scaling next-generation cellulase systems to access higher-yield fermentation technology.
Germany
Renewable diesel projects in Hamburg and Rotterdam qualification zones specify enzymatic pathways to secure premium fuel credits under RED III carbon accounting. The EU F-Gas Regulation constrains process emissions from chemical catalysis routes, redirecting capital toward biocatalyst systems. Industrial biotechnology clusters in North Rhine-Westphalia are qualifying enzyme suppliers against carbon intensity scoring methodologies.
India
Maharashtra and Gujarat-based processors are scaling microbial cellulase capacity to reduce import dependence from Danish suppliers. The PLI scheme for biomass-based fuels stimulates domestic enzyme manufacturing capacity that currently imports the majority of biocatalyst demand. Agricultural residue collection infrastructure in Punjab and Haryana is creating addressable substrate volumes for second-generation enzyme systems.
China
Dual carbon goals and provincial renewable fuel targets are accelerating lignocellulosic ethanol pilot projects in Shandong and Jilin provinces. The Ministry of Ecology and Environment enforces process emission standards that favor enzymatic conversion over chemical routes. Industrial biotechnology parks in the Yangtze River Delta are developing CRISPR-edited fungal strains for thermostable cellulase production.
Biofuel Enzymes Market Vendor Landscape
Integrated biotechnology platforms and standalone enzyme suppliers split the market along the fault line of in-house strain development capability versus external fermentation dependence. Danish and Dutch biotechnology clusters concentrate thermostable cellulase intellectual property, creating procurement vulnerability for fuel refiners in tropical processing regions. Three archetypes dominate: captive biotechnology divisions of integrated oil companies, specialized enzyme houses with backward integration into microbial strain libraries, and contract fermentation service providers. Competitive moves center on geographic capacity expansion into PLI-subsidized jurisdictions and technology licensing partnerships that accelerate CRISPR strain commercialization timelines.
Within the integrated biotechnology tier, Novozymes and BASF SE exemplify divergent strategic positions. Novozymes leverages its Danish R&D base to sustain leadership in thermostable cellulase engineering. BASF SE anchors its position through upstream control over microbial strain libraries. DSM-Firmenich occupies a specialized niche via precision-engineered enzyme cocktails optimized for corn-starch ethanol throughput.
| Leading Market Players |
|---|
| BASF SE |
| International Flavors & Fragrances Inc. |
| Novozymes |
| Dyadic International |
| Kerry Group |
| DuPont Industrial Biosciences |
| AB Enzymes |
| Advanced Enzyme Technologies |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Danish and Dutch thermostable cellulase IP compresses pricing tier spreads while forcing tropical refiners into premium cold-chain logistics or on-site fermentation service contracts. This concentration dynamic simultaneously elevates procurement vulnerability for Brazilian and Indian processors and widens the cost gap between bulk commodity amylases and precision-engineered lignocellulosic formulations.
Pricing Analysis
On-site fermentation service contracts drive lifetime value through multi-year technical support bundles that displace per-kilogram transactional pricing. Three-tier pricing structure across premium thermostable cellulases, standard amylase formulations, and economy lipase blends separates performance tiers by specific activity thresholds and inhibitor tolerance profiles. Pricing pressure stems from Indian PLI scheme beneficiaries scaling domestic microbial capacity and undercutting import premiums. Brazilian sugarcane processors exhibit highest price sensitivity due to currency volatility and cooling cost exposure, while German renewable diesel projects prioritize carbon intensity scores over unit economics.
Supply Chain Analysis
Dextrose and yeast extract feedstock costs fluctuate with agricultural commodity cycles, tethering enzyme manufacturing margins to corn and wheat futures in the US Midwest and Black Sea corridors. Supply concentrates in Denmark and the Netherlands for fungal cellulase IP, China for bulk fermentation equipment, and India for emerging microbial capacity under PLI subsidies. Single-source vulnerability for thermostable formulations creates procurement chokepoints when ANVISA or EPA regulatory dossiers delay strain approvals. Distribution runs through cold-chain liquid formulations for tropical regions and on-site fermentation service contracts for integrated Brazilian processors seeking to eliminate logistics costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as integrated oil companies internalize enzyme strain development through captive biotechnology acquisitions, fragmenting procurement patterns and compressing the addressable market for standalone suppliers.
For Market Incumbents: Pre-empt vertical consolidation by locking Brazilian and Indian refiners into decade-long on-site fermentation service contracts before captive biotechnology divisions achieve scale. Anchor microbial strain library control through backward integration into CRISPR platform licensing, neutralizing the threat of PLI-subsidized domestic capacity in Maharashtra and Gujarat. Prioritize thermostability R&D to maintain performance premiums against emerging microbial competitors. For New Entrants and Emerging Players: Build out waste oil transesterification lipase capacity targeting German renewable diesel projects in Hamburg and Rotterdam qualification zones where RED III carbon accounting favors enzymatic pathways. Penetrate the India PLI scheme beneficiary tier through joint venture structures with Maharashtra-based processors seeking to reduce Danish import dependence. Lead with enzymatic hydrolysis process guarantees rather than per-kilogram pricing to differentiate from established bulk suppliers. For Investors and Strategic Acquirers: EPA Renewable Fuel Standard volume obligation expansions reshape the acquisition landscape toward enzyme suppliers with validated CRISPR strain dossiers and Brazilian on-site fermentation infrastructure. Long-term viability hinges on carbon intensity scoring methodology alignment as RED III compliance architectures mature. Target acquisition archetypes: specialized fungal cellulase houses with thermostable IP and contracted Brazilian processor relationships. Watch for ANVISA approval velocity as inflection indicator for strain commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Commercialization | Accelerates EPA and ECHA approval timelines for thermostable cellulase deployment. |
| On-Site Fermentation Service Contracts | Eliminates cold-chain logistics costs for Brazilian sugarcane processors in São Paulo state. |
| Backward Integration into Microbial Libraries | Secures upstream control over Bacillus subtilis and Trichoderma reesei strain IP. |
| India PLI Scheme Joint Ventures | Captures production-linked incentive tailwinds in Maharashtra and Gujarat enzyme corridors. |
| Cellulase-Amylase Co-Formulation Development | Enables single-reactor mixed-feedstock processing for Brazilian bagasse-to-ethanol retrofits. |
Methodological Framework
The analysis maps cellulase, amylase, lipase, and protease sub-sectors, each validated through fermentation process engineers, biofuel refinery procurement managers, strain development scientists, and regulatory affairs specialists at EPA and ECHA. Primary interviews with enzyme formulation technical directors and Brazilian sugarcane processor operations heads combined with secondary validation from customs trade data, SEC 10-K biotechnology filings, ANVISA approval databases, and EU RED III implementation guidance. Bottom-up titer and dosing rate modeling triangulated against top-down national blending mandate volume obligations.
Assumptions held fixed include current EPA renewable volume obligation trajectories and EU F-Gas Regulation emission constraint stringency, while enzyme thermostability improvement curves and India PLI scheme disbursement velocity were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, source organism, application pathway, and technology platform across the projection horizon. CAGRs derived from enzyme loading rate trends, facility retrofit capex cycles, and carbon intensity scoring adoption curves in German and Dutch renewable diesel qualification zones.
Sensitivities concentrate around EPA volume obligation political revisions, CRISPR strain regulatory approval delays, and Brazilian currency volatility affecting import-dependent processor procurement. Forecasts reflect documented assumptions on lignocellulosic feedstock collection infrastructure scaling in Punjab and Haryana agricultural corridors. Cross-checking against IEA biofuel production statistics and national renewable fuel registry data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Animal Eubiotics Market