
 China Agricultural Biologicals Market | 2026-2036
China Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
China Agricultural Biologicals Market Insights
Synthetic chemical nitrogen is decoupling from premium crop economics as biological nitrogen fixation gains cost parity in greenhouse and horticulture systems. Genliduo Bio-tech Corporation Ltd leverages domestic fermentation capacity to anchor supply security for microbial inoculants. Valent Biosciences LLC differentiates through specialized biopesticide formulations targeting high-value fruit crops. Zhejiang Qianjiang Biochemical Co., Ltd. dominates regional distribution channels across eastern China's intensive agriculture belt.
Agricultural biologicals comprise living organisms, derived metabolites, and natural substances formulated to enhance crop productivity, suppress pests, or improve soil function, typically requiring viable cell counts exceeding colony-forming unit thresholds and pH stabilization for field efficacy. Biofungicides and microbial inoculants lead product type revenue pools, while biopesticide demand accelerates fastest under tightening residue limits for export-oriented horticulture. Foliar application and soil treatment capture the dominant share of application-method value, with post-harvest biological treatments emerging as a margin-rich niche in cold-chain-dependent supply chains.
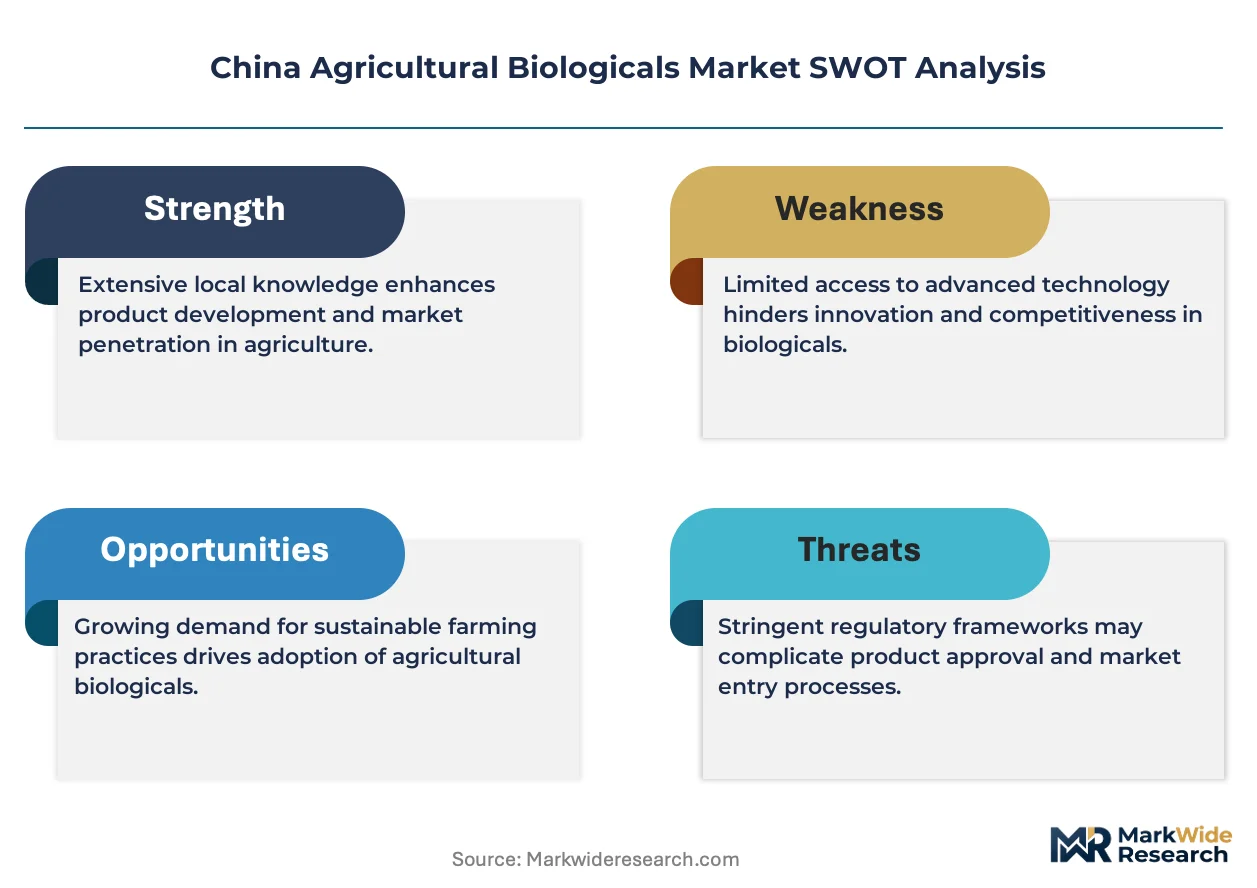
China's Ministry of Agriculture and Rural Affairs (MARA), the National Medical Products Administration (NMPA), and GB standards collectively govern biological input registration, safety testing, and label claims, with MARA's streamlined biopesticide review pathway reducing entry barriers for domestic innovators. The dual carbon policy framework rewards biological inputs that sequester soil carbon or reduce synthetic fertilizer-derived emissions, reshaping subsidy eligibility and procurement criteria. Stakeholders must monitor evolving GB standard revisions and provincial pilot programs to anticipate which product categories gain preferential market access.
Market Dynamics
The dual carbon policy framework is decoupling agricultural biologicals from synthetic input subsidies, redirecting procurement incentives toward soil carbon sequestration and emission reduction metrics that favor microbial inoculants over chemical fertilizers.
Growth Catalysts
- GB Standards Streamlining:MARA's accelerated biopesticide registration pathway compresses product approval timelines, enabling domestic innovators to commercialize microbial formulations faster than synthetic chemical counterparts.
- Yangtze River Delta Greenhouse Expansion:Intensive horticulture clusters around Shanghai and Hangzhou are standardizing biological input protocols for export-oriented vegetable production, creating concentrated demand pull.
- Soil Carbon Incentives:Provincial pilot programs in Shandong and Yunnan reward verified carbon sequestration from microbial soil treatments, embedding biologicals into carbon credit monetization schemes.
Market Restraints
- Fermentation Input Volatility:Domestic molasses and agricultural residue feedstock prices fluctuate with sugar policy adjustments, compressing margins for microbial inoculant manufacturers dependent on carbohydrate substrates.
- Technical Shelf-Life Limitations:Viable cell count degradation during summer transport through southern China's humid logistics corridors restricts distribution reach for temperature-sensitive biofungicide formulations.
- Synthetic Fertilizer Substitution Threat:Urea price collapses following coal-to-ammonia capacity expansions in Inner Mongolia periodically reverse grower switching economics in grain-producing provinces.
Strategic Opportunities
- Post-Harvest Biological Treatments:Cold-chain expansion into southwestern China creates whitespace for biocontrol coatings on premium fruit exports, a segment currently dominated by chemical fungicides.
- CRISPR-Enhanced Strain Development:Convergence of gene editing with traditional fermentation is enabling targeted microbiome engineering for drought-stressed soils in northwestern provinces.
- E-Commerce Input Platforms:Alibaba's agricultural vertical and Pinduoduo's farm-direct channels are disintermediating county-level distributors, opening direct-to-greenhouse sales for specialized biopesticide blends.
Industry Challenges
- Microbiologist Talent Scarcity:Industrial fermentation expertise concentrates in pharmaceutical hubs around Suzhou and Tianjin, leaving agricultural biological producers competing for limited strain optimization specialists.
- GB Standard Revision Uncertainty:Pending updates to microbial product labeling and efficacy testing protocols create compliance timeline risk for registration pipelines, forcing dual-track development investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Agricultural Biologicals Market |
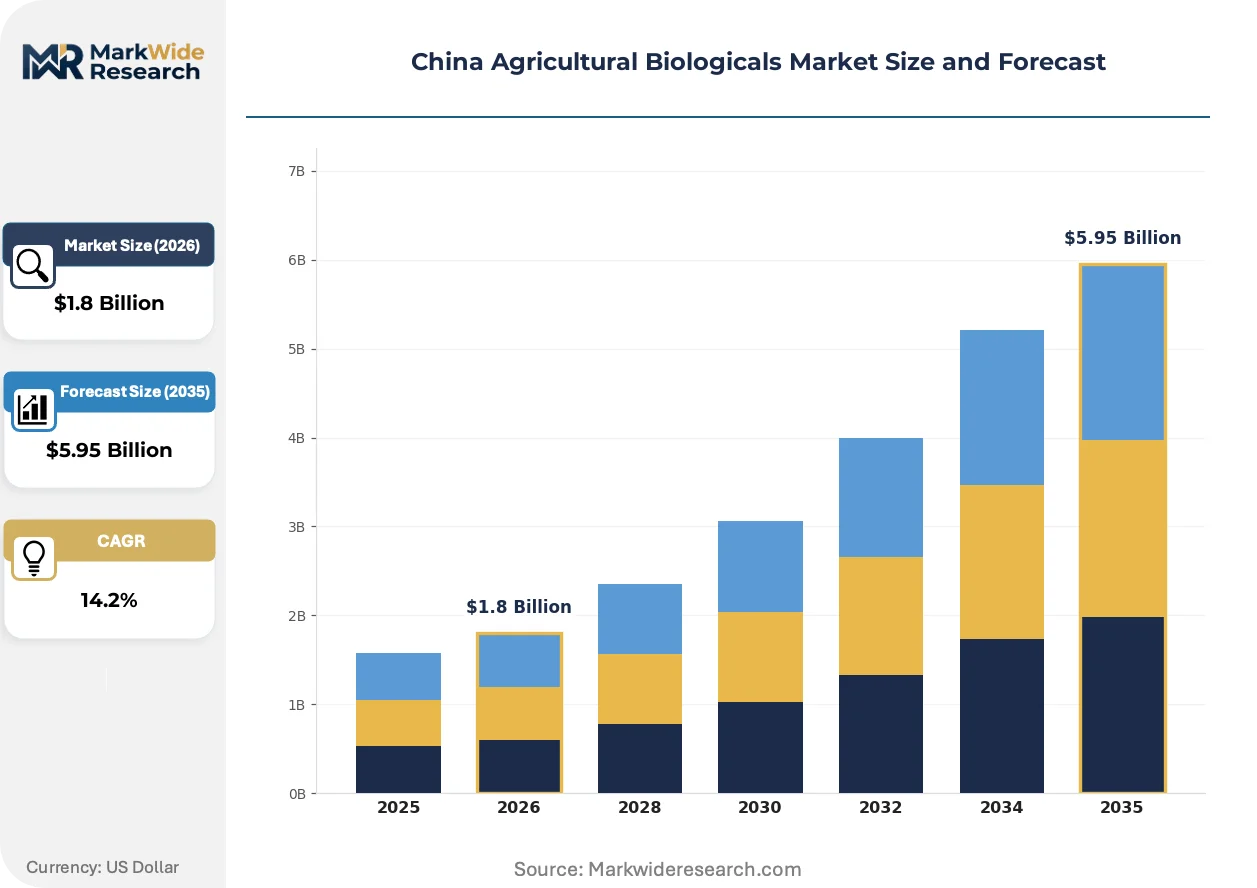
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofungicides, Biopesticides, Bioherbicides, Microbial Inoculants Application: Soil Treatment, Seed Treatment, Foliar Application, Post-Harvest End Use Industry: Crops, Horticulture, Turf & Ornamentals, Greenhouse Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | Genliduo Bio-tech Corporation Ltd, Biobest Group NV, Valent Biosciences LLC, Shanxi Haozhida Biotechnology Co., Ltd., Biolchim S.p.A., Beijing Bioseen Crop Sciences Co., Ltd, Zhejiang Qianjiang Biochemical Co., Ltd., Koppert Biological Systems, UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Agricultural Biologicals Market Trends and Innovations
Biological input development is pivoting from standalone products to integrated crop management systems, with formulation science and digital agriculture converging to enable precision microbiome management in controlled environments.
Consortia-based microbial inoculants containing nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant growth-promoting rhizobacteria are integrating into greenhouse fertigation systems as drop-in replacements for synthetic starter fertilizers. Shandong vegetable cooperatives are adopting these multi-strain blends at scale, compressing the payback period for biological input transitions through reduced synthetic nitrogen purchases and improved soil organic matter retention.
GB standards for biological input registration are tightening residue testing and environmental fate requirements, extending safety evaluation timelines for novel microbial strains. This regulatory compression favors established domestic manufacturers with existing toxicology dossiers, while forcing smaller innovators toward contract research organization partnerships or licensing arrangements to navigate MARA's evolving technical criteria.
Export-oriented horticulture operations are unbundling input procurement from bundled agrochemical packages, establishing separate biological input specifications for EU and Japanese supermarket compliance. Zhejiang strawberry and grape producers now maintain dual input registries—synthetic protocols for domestic wholesale markets and biological-only treatments for certified export channels—creating parallel demand streams that reward formulation flexibility over volume scale.
China Agricultural Biologicals Market Segmentation
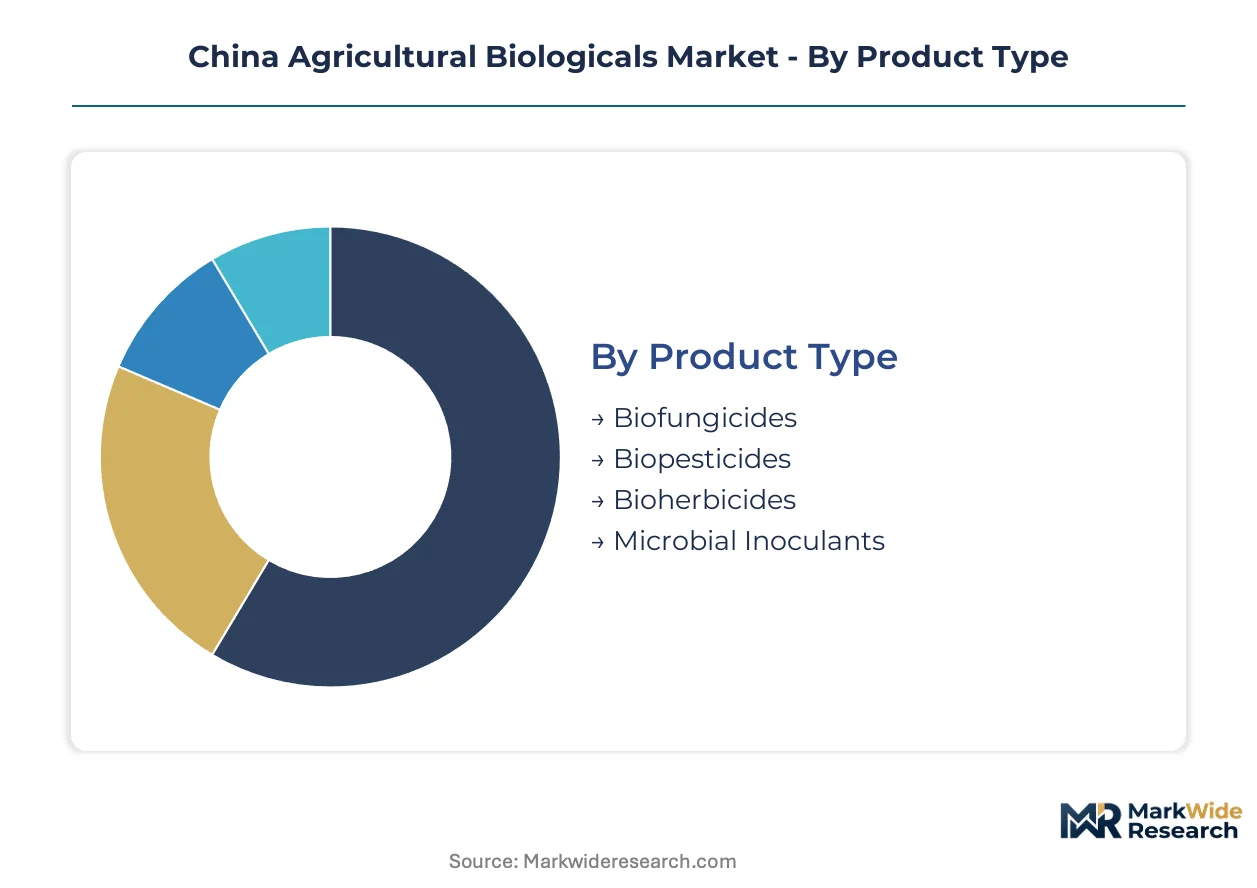
Segmentation in China's agricultural biologicals market reveals distinct commercial logics across product formulations, application protocols, and procurement channels. Each dimension carries unique regulatory, technical, and margin characteristics that shape supplier positioning and grower adoption curves.
Product Type:
Standardization dominates commodity-grade biopesticides while microbial inoculants demand strain-specific customization for soil microbiome matching.
- Biofungicides:Formulated from Trichoderma and Bacillus subtilis strains with colony-forming unit counts exceeding 10^8 per gram. Greenhouse vegetable operations in the Yangtze River Delta specify these for export compliance under tightening EU residue limits.
- Microbial Inoculants:Multi-strain consortia containing nitrogen-fixing bacteria and phosphate-solubilizing fungi. Shandong fruit cooperatives embed these into fertigation systems as synthetic nitrogen substitutes, with carbon credit verification driving provincial procurement tenders.
- Biopesticides:Targeted entomopathogenic formulations for lepidopteran and coleopteran pests. MARA's accelerated registration pathway compresses approval timelines relative to synthetic chemical counterparts.
- Bioherbicides:Plant-derived phytotoxins and microbial metabolites for selective weed suppression. Limited adoption in grain monocultures due to application timing constraints.
Leading the category by volume: Microbial Inoculants. Expanding most quickly: Biopesticides.
Application:
Application method selection tracks crop value intensity and labor availability, with high-value horticulture favoring precision delivery systems.
- Soil Treatment:Pre-plant microbial inoculation and biofungicide drenching. Yunnan province's vegetable belt standardizes these protocols for soil-borne disease suppression in continuous cropping systems.
- Foliar Application:Aerial and ground-based spraying of biopesticides and biostimulants. Greenhouse clusters around Hangzhou integrate automated fogging systems for uniform canopy coverage.
- Seed Treatment:Microbial coating of vegetable and field crop seeds. Domestic seed companies embed biologicals into certified seed lines for differentiated positioning.
- Post-Harvest:Biocontrol coatings and antagonistic microbial sprays for cold-chain fruit. Southwestern China's expanding premium fruit export infrastructure creates whitespace for biological fungicide replacements.
Soil Treatment commands the largest revenue pool. Post-Harvest carries the steepest expansion trajectory.
End Use Industry:
Customer sophistication separates greenhouse contract growers from open-field grain producers, with input specifications diverging across domestic and export market channels.
- Greenhouse:Controlled-environment vegetable and berry production with integrated biological input protocols. Zhejiang export-oriented operations maintain dual registries—synthetic for domestic wholesale, biological-only for certified EU and Japanese supermarket channels.
- Horticulture:Open-field fruit and vegetable cultivation with seasonal biological application windows. Shandong strawberry producers adopt microbial inoculants for soil organic matter retention and synthetic nitrogen reduction.
- Crops:Field-scale grain and oilseed production. Urea price volatility periodically reverses switching economics, though dual carbon incentives embed biologicals into provincial carbon credit schemes.
- Turf & Ornamentals:Golf course and landscaping applications with aesthetic performance thresholds. Limited penetration relative to food crop sectors due to cost sensitivity.
Greenhouse generates the highest input expenditure per hectare. Horticulture is gaining share fastest.
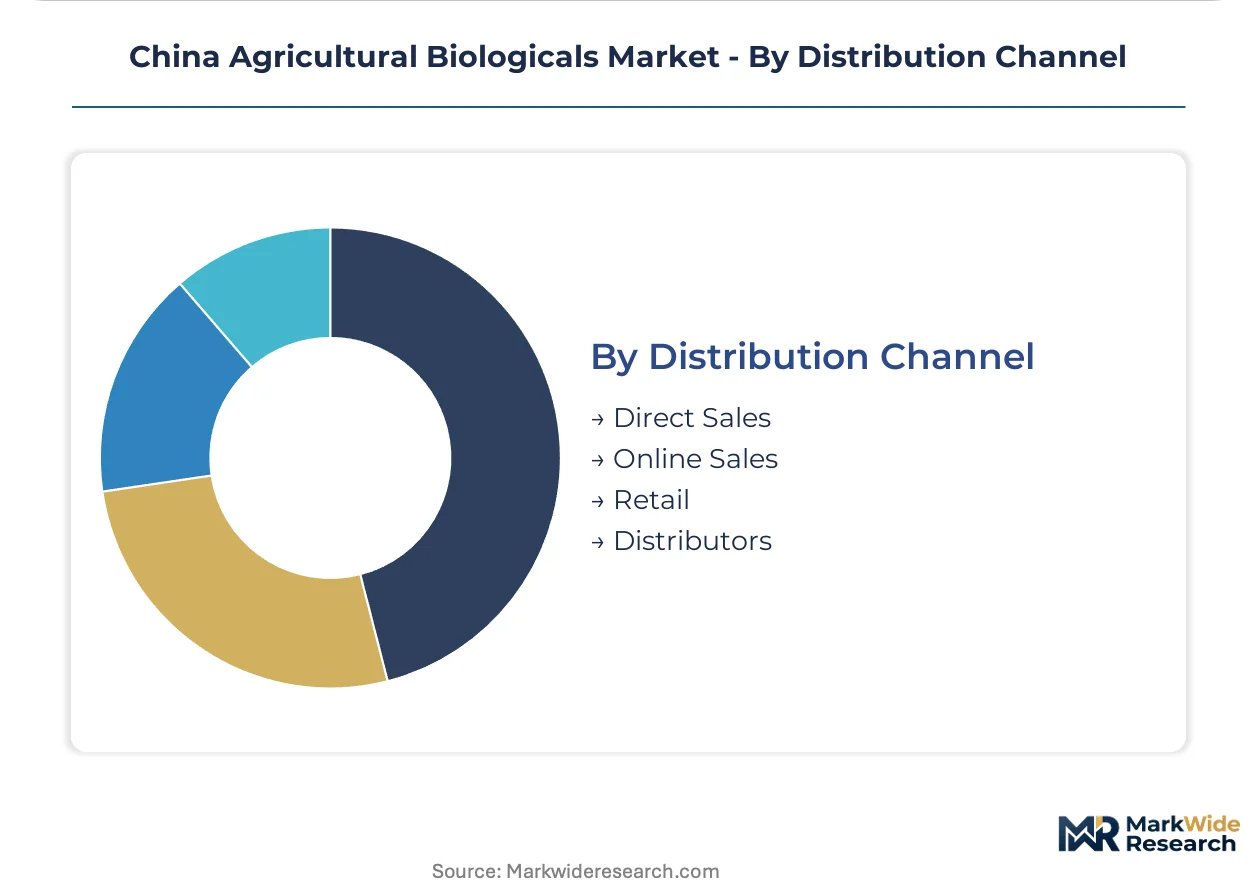
Distribution Channel:
Channel selection reflects grower scale and technical support requirements, with digital platforms disintermediating traditional county-level distribution.
- Distributors:County and prefecture-level agricultural supply networks with technical advisory services. Eastern China's intensive agriculture belt maintains dense distributor coverage for microbial inoculant and biofungicide stocking.
- Direct Sales:Manufacturer-to-greenhouse contracts for large-scale cooperative procurement. Genliduo Bio-tech and Zhejiang Qianjiang Biochemical anchor supply security through direct relationships with Shandong vegetable federations.
- Online Sales:Alibaba agricultural vertical and Pinduoduo farm-direct channels. Specialized biopesticide blends reach smallholder greenhouse operators with disintermediated pricing.
- Retail:Township agricultural supply stores serving fragmented smallholder demand. Temperature-sensitive biofungicide formulations face shelf-life degradation in humid southern retail environments.
Distributors still handle the greatest transaction volume. Online Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's agricultural biologicals demand concentrates in eastern and southwestern provinces where greenhouse horticulture and export-oriented fruit production create concentrated procurement pull. Provincial carbon credit pilots and GB standards implementation are reshaping regional adoption curves.
Shandong Province
Vegetable cooperatives in Shandong's intensive agriculture belt are embedding multi-strain microbial consortia into fertigation systems as synthetic nitrogen substitutes. Provincial pilot programs reward verified soil carbon sequestration from microbial treatments, embedding biologicals into carbon credit monetization schemes. The Shandong Peninsula's strawberry and tomato clusters now maintain dual input registries for domestic and export channels.
Yunnan Province
Yunnan's high-altitude vegetable belt standardizes soil treatment protocols for soil-borne disease suppression in continuous cropping systems. Dual carbon policy incentives accelerate procurement tenders for microbial inoculants that demonstrate emission reduction metrics. The Kunming-Dali corridor anchors distribution networks for temperature-sensitive biofungicide formulations serving southwestern cold-chain expansion.
Jiangsu Province
Jiangsu's Yangtze River Delta greenhouse clusters around Suzhou and Nanjing standardize biological input protocols for EU and Japanese supermarket compliance. MARA's accelerated biopesticide registration pathway enables faster commercialization of microbial formulations for export-oriented vegetable production. The province's pharmaceutical fermentation expertise pools supply industrial microbiology talent for strain optimization.
Zhejiang Province
Zhejiang's Hangzhou Bay horticulture operations unbundle input procurement from bundled agrochemical packages, establishing separate biological specifications for certified export channels. Strawberry and grape producers maintain parallel demand streams that reward formulation flexibility over volume scale. The province's dense distributor coverage anchors regional supply security for microbial inoculant stocking.
Sichuan-Chongqing Region
The Sichuan-Chongqing vegetable basin adopts CRISPR-enhanced strain development for drought-stressed soils in northwestern cultivation zones. Provincial agricultural extension services promote biological input transitions through reduced synthetic fertilizer purchase requirements. Chengdu's biotech corridors converge gene editing capabilities with traditional fermentation infrastructure.
China Agricultural Biologicals Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers scale fermentation infrastructure to capture provincial carbon credit procurement tenders. The vendor base stratifies across three tiers: multinational specialists with GB registration dossiers, domestic mid-scale innovators leveraging regional distribution density, and state-affiliated agricultural input conglomerates with bundled supply contracts. Strategic archetypes include fermentation-scale players optimizing molasses feedstock security, formulation specialists targeting export compliance niches, and platform-integrated distributors disintermediating county-level networks. M&A activity and strategic partnerships concentrate in the Yangtze River Delta corridor where technical talent scarcity drives consolidation logic.
Among domestic biotechnology specialists, Genliduo Bio-tech Corporation Ltd exemplifies the fermentation-scale archetype with supply security positioning, while Zhejiang Qianjiang Biochemical Co., Ltd. occupies a position within the regional distribution-anchored tier. Valent Biosciences LLC represents the multinational specialist archetype navigating MARA's registration pathways. These three occupy distinct competitive vectors—feedstock security, channel density, and regulatory navigation—that collectively map the strategic terrain for market positioning.
| Leading Market Players |
|---|
| Genliduo Bio-tech Corporation Ltd |
| Biobest Group NV |
| Valent Biosciences LLC |
| Shanxi Haozhida Biotechnology Co., Ltd. |
| Biolchim S.p.A. |
| Beijing Bioseen Crop Sciences Co., Ltd |
| Zhejiang Qianjiang Biochemical Co., Ltd. |
| Koppert Biological Systems |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Family-owned fermentation specialists across Shandong and Jiangsu provinces anchor production capacity, linking molasses feedstock security to pricing discipline through backward integration into agricultural residue sourcing. Their control over carbohydrate substrate supply buffers margin compression when sugar policy adjustments spike input costs, while direct contracts with vegetable cooperatives bypass distributor markups for volume buyers.
Pricing Analysis
Volume-scale microbial inoculants trade on thin margins through provincial procurement tenders, while specialized biopesticide formulations for export-oriented horticulture capture premium pricing through MARA registration dossiers and residue compliance certification. Price differentiation rests on GB standard tiering and viable cell count thresholds, with greenhouse operators in the Yangtze River Delta least sensitive to unit cost given carbon credit monetization offsets. Pricing pressure intensifies in commodity-grade biofungicides as domestic fermentation capacity expansion outpaces horticulture demand growth.
Supply Chain Analysis
Direct-to-greenhouse channels handle large-scale cooperative procurement, while county-level distributors manage fragmented smallholder demand across eastern China's intensive agriculture belt. Manufacturing concentrates in Shandong, Jiangsu, and Zhejiang provinces, with fermentation infrastructure drawing from domestic molasses, corn steep liquor, and agricultural residue feedstocks. Supply chain risk centers on temperature-sensitive logistics through southern China's humid corridors, where viable cell count degradation restricts biofungicide distribution reach. Distribution runs through Alibaba's agricultural vertical and Pinduoduo farm-direct platforms for disintermediated biopesticide blends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around fermentation-scale players as GB standard revision uncertainty forces dual-track compliance investments that strain smaller innovators. MARA's evolving toxicology requirements favor established manufacturers with existing registration dossiers.
For Market Incumbents: Anticipate strain optimization talent scarcity in Suzhou and Tianjin pharmaceutical hubs by embedding contract research partnerships into product development pipelines. Secure molasses feedstock through backward integration into sugar refinery offtake agreements, and defend position against synthetic fertilizer price volatility by anchoring carbon credit verification protocols with provincial agricultural extension services.
For New Entrants and Emerging Players: Southwestern China's cold-chain expansion into Yunnan and Sichuan provinces offers whitespace for post-harvest biocontrol coatings on premium fruit exports, a segment currently dominated by chemical fungicides. Target drought-stressed cultivation zones in northwestern provinces with CRISPR-enhanced microbial consortia, leveraging Chengdu's gene editing infrastructure for differentiated strain development.
For Investors and Strategic Acquirers: MARA's accelerated biopesticide registration pathway compressing approval timelines is the leading indicator that domestic formulation specialists will command scarcity premiums. The analysis window favors fermentation-scale mid-caps with captive feedstock security and existing GB dossiers over early-stage strain discovery platforms. Watch for provincial carbon credit pilot program expansions beyond Shandong and Yunnan as the signal for embedded biological demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures provincial carbon credit procurement tenders in Shandong and Yunnan. |
| Backward Integration into Feedstock | Molasses security buffers margin compression from sugar policy volatility. |
| GB Standard Registration Investment | Accelerated MARA pathway favors established toxicology dossiers over entrants. |
| Direct-to-Greenhouse Channel Development | Disintermediates county distributors for large-scale cooperative procurement. |
| CRISPR-Enhanced Strain Development | Converges Chengdu gene editing with fermentation for drought-stressed soils. |
Research Methodology
Independent corroboration across MARA registration filings, provincial agricultural extension program documentation, and dual carbon policy implementation records underwrites the qualitative findings. Primary interviews with fermentation plant managers, greenhouse cooperative procurement leads, microbial strain optimization specialists, and county-level distributor operators combined with secondary validation from customs trade data, GB standard revision notices, and carbon credit pilot program disclosures. Bottom-up strain-level production estimates and top-down provincial expenditure triangulation anchor volume assessments.
Comparable-period analysis anchored historical microbial inoculant adoption curves to synthetic fertilizer price volatility episodes and carbon credit pilot launch dates across the projection horizon. Segmentation modeling spans product formulation tiers, application method intensity, end-use industry sophistication, and distribution channel structure, with CAGRs derived from province-level procurement tender trajectories and export compliance specification shifts. Strain viability degradation curves and fermentation feedstock cost indices inform margin projections.
Revisions become necessary when MARA announces GB standard protocol changes, provincial carbon credit schemes expand or contract, or synthetic fertilizer price collapses reverse grower switching economics. Forecasts reflect assumptions about dual carbon policy continuity, temperature-controlled logistics infrastructure rollout, and fermentation talent pool expansion. Periodic stress-testing of base assumptions against molasses price volatility and export market residue limit tightening is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Nannochloropsis Market