
 United States Cookies Market | 2026-2036
United States Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cookies Market Analytics
Alternative sweeteners such as monk fruit and allulose is realigning cost structures across the cookie category, pressuring legacy formulations to adapt. Mondelēz International leverages its North American baking infrastructure to maintain cost discipline in chocolate chip production. General Mills Inc. anchors its cookie portfolio through sustained investment in whole-grain and reduced-sugar variants. Kellanova competes aggressively in the peanut butter segment through direct-store-delivery networks that control in-store placement.
Cookies are baked flour-based confections typically composed of wheat flour, sugar, fat, and leavening agents, formed into discrete portions and baked until crisp or chewy, serving primarily as shelf-stable retail snacks and foodservice dessert items. Chocolate chip formulations occupy the largest volume position, though oatmeal raisin variants are gaining traction among consumers seeking perceived whole-grain benefits. The distribution channel structure tilts heavily toward supermarkets, where slotting fees and promotional calendars determine visibility, while online stores represent the fastest-growing outlet as subscription snack boxes and direct-to-consumer bakery brands bypass traditional wholesale gatekeepers.
The FDA governs ingredient declarations, allergen labeling, and health claims on cookie packaging, while USDA organic certification shapes premium positioning for brands targeting clean-label shoppers. State-level sugar taxes and school nutrition standards in jurisdictions such as California and New York further constrain formulation choices and channel access. Stakeholders must monitor evolving FTC guidance on environmental marketing claims, as sustainability assertions on cookie packaging face escalating scrutiny from both regulators and class-action litigants.
Market Dynamics
Convenience-store snack aisles are absorbing more premium cookie SKUs as on-the-go consumption patterns solidify, forcing manufacturers to reconfigure packaging formats and shelf-life engineering for ambient retail environments.
Growth Catalysts
- FDA Nutrition Facts Revisions:The updated labeling requirements for added sugars are accelerating reformulation toward monk fruit and allulose, expanding permissible health claims on packaging.
- California Metropolitan Corridors:Specialty and better-for-you cookie brands command disproportionate shelf space in Los Angeles and San Francisco retail networks, concentrating demand pull in high-margin segments.
- Whole-Grain Positioning:Oatmeal raisin variants are gaining traction among consumers seeking perceived nutritional benefits, creating volume expansion in the functional snack category.
Market Restraints
- Alternative Sweetener Cost Volatility:Monk fruit and allulose supply chains face pricing instability relative to cane sugar and high-fructose corn syrup, compressing margin structures for reformulated products.
- Slotting Fee Concentration:Supermarket channel control by a limited number of retail banners concentrates gatekeeper power, raising barriers for emerging brands seeking physical distribution.
- School Nutrition Standards:State-level restrictions in California and New York constrain formulation choices and channel access for products targeting institutional foodservice.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Online stores represent the fastest-growing outlet as bakery brands bypass traditional wholesale gatekeepers through snack box partnerships.
- USDA Organic Certification Tailwinds:Clean-label positioning for premium brands is accelerating as certification shapes shopper preference in natural and specialty retail channels.
- Chocolate Chip Premiumization:Unfilled white space exists for heritage-positioned variants using single-origin cacao and artisan production claims in the largest volume segment.
Industry Challenges
- FTC Environmental Marketing Scrutiny:Sustainability assertions on cookie packaging face escalating investigation from regulators and class-action litigants, requiring legal review of all green claims.
- Legacy Distributor Integration:Direct-store-delivery networks require substantial capital reconfiguration to accommodate temperature-controlled logistics for cleaner-label formulations with reduced preservative loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cookies Market |
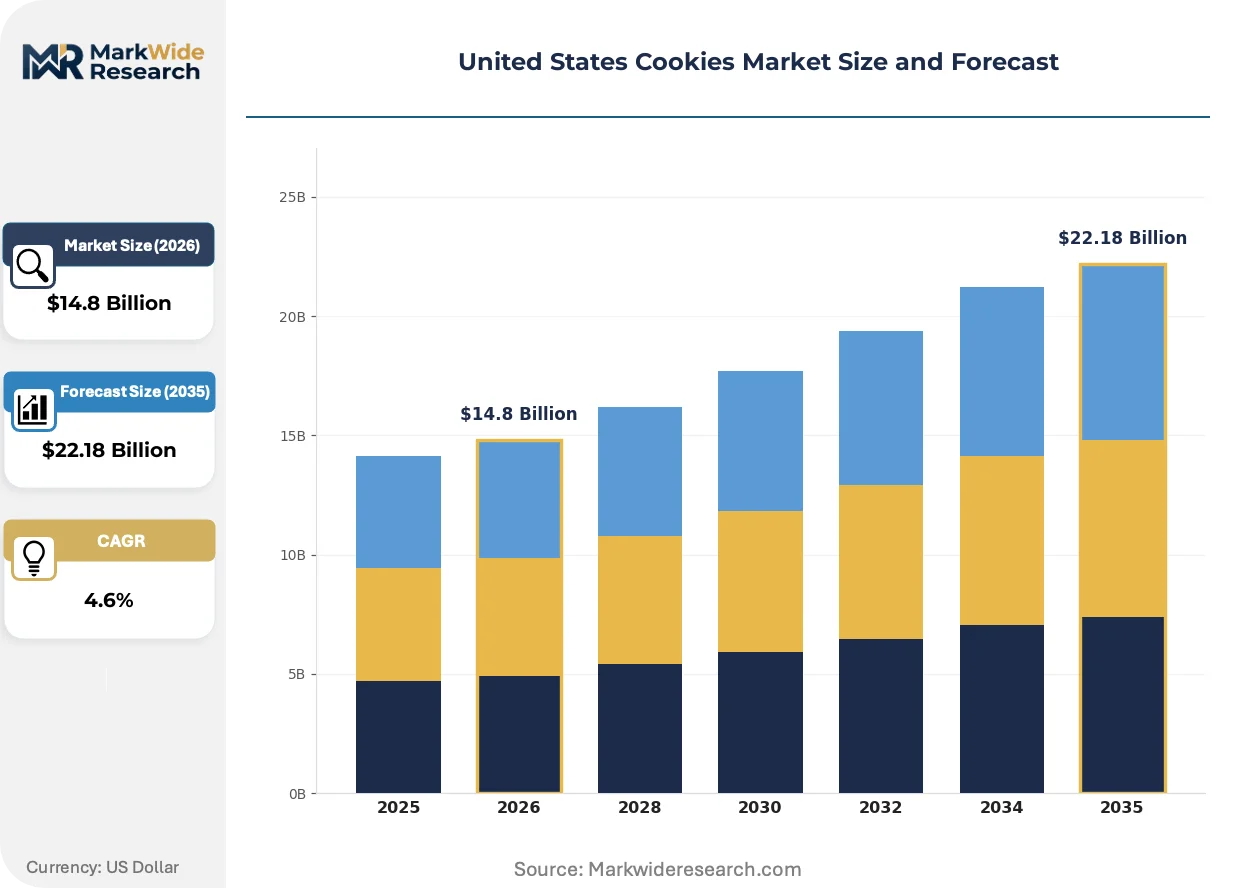
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Oatmeal Raisin, Peanut Butter, Sugar Distribution Channel: Retail Stores, Online Stores, Wholesale, Supermarkets Packaging Type: Bags, Boxes, Tins, Pouches Price Tier: Premium, Mid-range, Budget, Value |
| Companies Covered | Mondelēz International, General Mills Inc., Ferrero Group, McKee Foods Corporation, The Campbell Soup Company, Grupo Bimbo S.A.B. de C.V., Hostess Brands, LLC, PepsiCo Inc., Kellanova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cookies Market Evolving Landscape
Reformulation chemistry and packaging engineering are converging to address shelf-stability demands while satisfying clean-label preferences, reshaping competitive positioning across the category.
Precision fermentation-derived proteins and fats are unifying texture and mouthfeel functions previously delivered by synthetic emulsifiers and hydrogenated oils. Mid-tier manufacturers are adopting these ingredients at accelerated pace to meet clean-label benchmarks. The technology is unifying formulation teams previously siloed between R&D and procurement functions, compressing product development cycles.
California's state-level sugar tax proposals and New York's school nutrition standards are constraining permissible formulation ranges for products distributed through institutional channels. Industrial consequence includes accelerated migration toward alternative sweetener systems and portion-size reduction. The K-12 foodservice segment is most affected, with suppliers reformulating to maintain contract eligibility.
Subscription snack box procurement is displacing traditional wholesale purchasing for premium cookie brands seeking direct consumer relationships. Direct-to-consumer channels are capturing share from supermarket impulse sections, particularly among millennial and Gen-Z households. This behavioral shift is most visible in coastal metropolitan markets where delivery infrastructure density supports rapid fulfillment expectations.
United States Cookies Market Segmentation
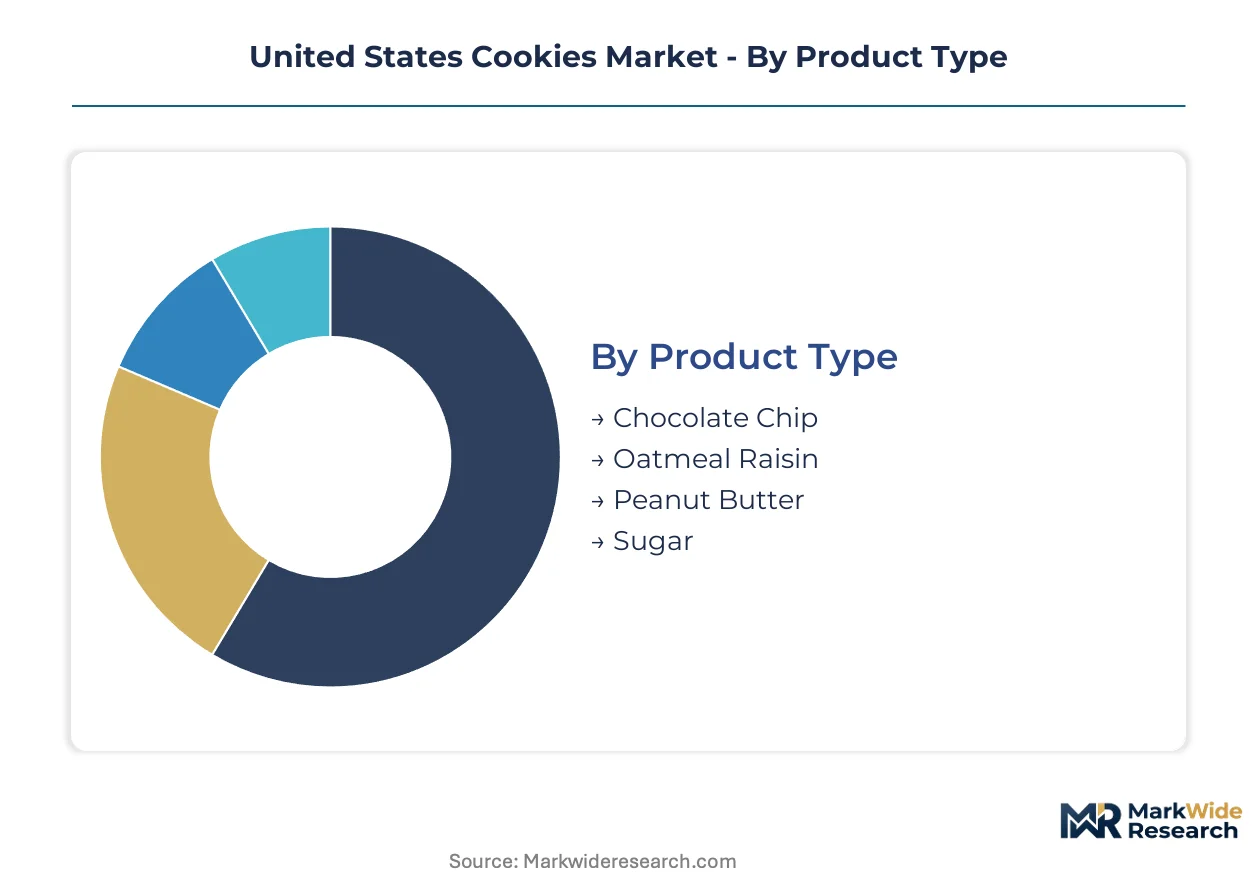
Cookie manufacturers configure production lines around distinct demand profiles that shape ingredient sourcing, shelf-life engineering, and channel negotiation strategies. Segmentation reveals where margin pools concentrate and which formulation investments align with consumption occasions.
Product Type:
Customization spans from heritage recipes demanding specific flour protein contents to standardized formats optimized for automated depositing and baking systems.
- Chocolate Chip:Wheat-flour bases carry discrete chocolate inclusions at calibrated melt points for texture control. California metropolitan corridors absorb disproportionate volume of single-origin cacao variants as better-for-you positioning penetrates coastal retail networks.
- Oatmeal Raisin:Rolled oat integration delivers soluble fiber claims while raisin hydration requires moisture management protocols distinct from chocolate chip production. Whole-grain positioning concentrates demand pull in natural and specialty channels where USDA organic certification commands shelf space.
- Peanut Butter:Ground legume paste replaces partial fat content in dense, crumb-resistant formulations favored by institutional foodservice.
- Sugar:Simple butter-sugar-flour ratios enable longest production runs and lowest ingredient complexity for commodity pricing tiers.
Leading the category by volume: Chocolate Chip. Expanding most quickly: Oatmeal Raisin.
Distribution Channel:
Channel selection determines packaging format, promotional calendar alignment, and working capital requirements across ambient supply chains.
- Retail Stores:Convenience-store snack aisles absorb premium SKUs as on-the-go consumption patterns solidify, forcing manufacturers to reconfigure shelf-life engineering for ambient environments.
- Online Stores:Subscription snack box procurement displaces traditional wholesale purchasing for premium brands seeking direct consumer relationships.
- Wholesale:Institutional foodservice contracts demand portion-controlled formats compliant with state-level school nutrition standards.
- Supermarkets:Slotting fees and promotional calendars concentrate gatekeeper power among limited retail banners.
Capturing dominant share: Supermarkets. Gaining share fastest: Online Stores.
Packaging Type:
Barrier properties and format economics segment procurement decisions between impulse purchase optimization and pantry stocking efficiency.
- Bags:Flexible film structures with modified atmosphere capabilities dominate single-serve and family-size configurations for retail velocity.
- Boxes:Rigid paperboard enables vertical shelf presentation and gift-positioning premiums in seasonal periods.
- Tins:Metal containers support extended shelf stability and heritage brand positioning for premium gifting occasions.
- Pouches:Stand-up formats with resealable closures address portion-control demand in better-for-you segments.
Standard format by volume: Bags. Steepest expansion trajectory: Pouches.
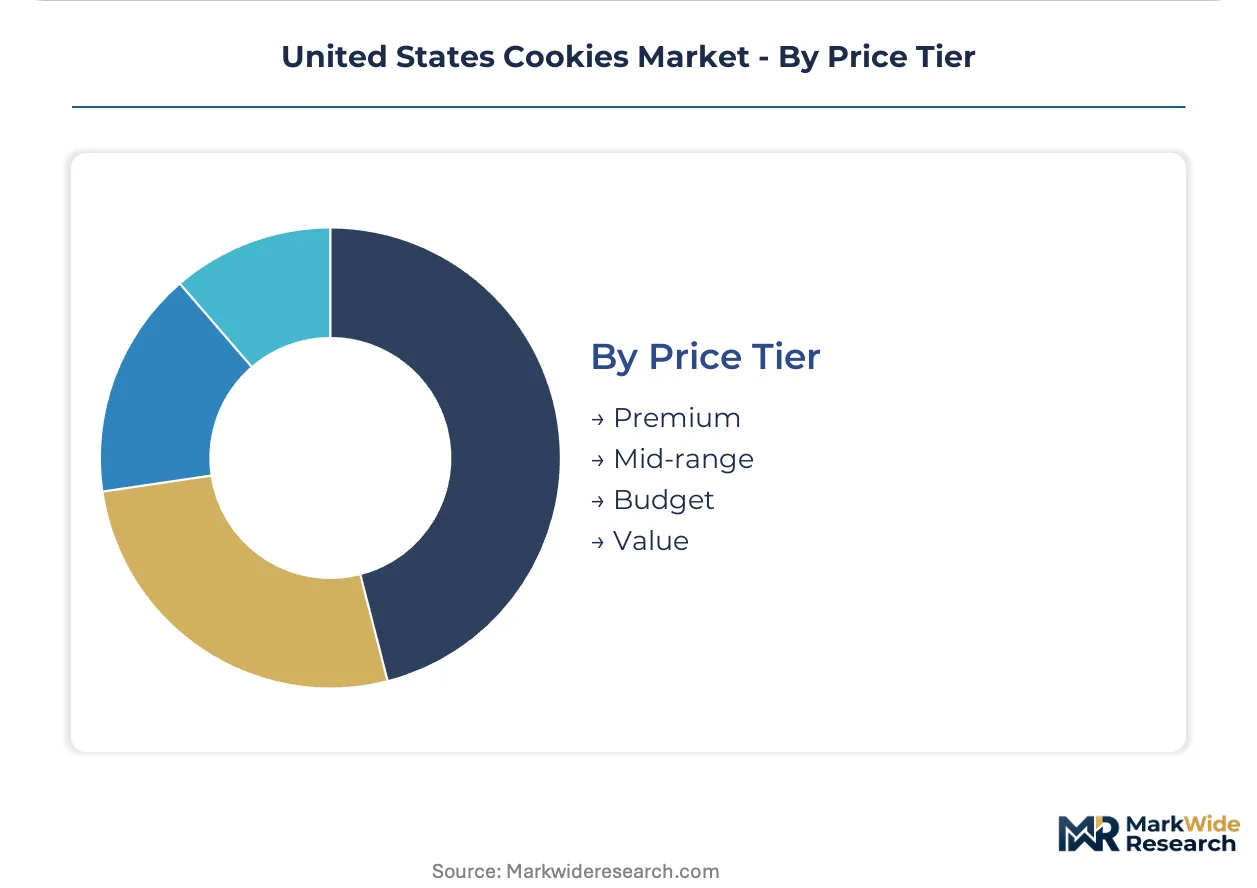
Price Tier:
Ingredient provenance, certification status, and production scale separate accessible entry points from margin-rich premium positioning.
- Premium:Single-origin cacao, heritage grain varieties, and small-batch production claims justify price multiples through artisan credentials and clean-label positioning.
- Mid-range:Reformulated variants with reduced sugar or whole-grain content bridge mass-market accessibility and health-conscious positioning.
- Budget:High-fructose corn syrup and palm oil formulations minimize input costs for price-sensitive household penetration.
- Value:Private-label production leverages identical manufacturing infrastructure with reduced marketing overhead for retailer margin capture.
Revenue concentration: Mid-range. Climbing the fastest: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in California's metropolitan retail corridors, where specialty and better-for-you cookie brands command disproportionate shelf space. Los Angeles and San Francisco absorb premium SKUs at accelerated velocity. State-level sugar tax proposals and school nutrition standards constrain formulation choices nationwide.
California
Los Angeles and San Francisco retail networks absorb disproportionate volume of single-origin cacao variants and USDA organic certified products. The state's school nutrition standards constrain permissible formulations for institutional foodservice contracts. San Diego's specialty food manufacturing corridor hosts emerging better-for-you brands targeting coastal consumer preferences.
New York
The New York metropolitan area anchors Northeast distribution infrastructure for premium cookie imports and domestic heritage brands. State-level school nutrition standards in K-12 foodservice channels accelerate reformulation toward alternative sweetener systems. Brooklyn's artisan food manufacturing cluster supports small-batch production for direct-to-consumer subscription channels.
Texas
Dallas-Fort Worth and Houston retail corridors absorb volume-tier and mid-range cookie SKUs serving price-sensitive household penetration. The Texas Department of Agriculture's food safety protocols shape regional distribution compliance requirements. Austin's food technology startup ecosystem incubates precision fermentation ingredient suppliers serving cleaner-label reformulation demands.
Illinois
Chicago's central logistics position anchors national distribution networks for commodity and value-tier cookie production. The Illinois Department of Public Health enforces allergen labeling compliance across interstate shipping corridors. The city's food manufacturing heritage supports contract baking infrastructure for private-label retail programs.
Pennsylvania
Philadelphia and Pittsburgh metropolitan areas concentrate snack food manufacturing infrastructure with legacy baking expertise. The Pennsylvania Department of Agriculture oversees interstate commerce certification for shelf-stable baked goods. Hershey's adjacent confectionery corridor creates ingredient supplier clustering for chocolate-inclusive cookie production.
United States Cookies Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational portfolios dominating supermarket shelf space while regional artisans capture subscription channel velocity. The vendor structure organizes around three strategic archetypes: diversified snack conglomerates with North American baking infrastructure, pure-play cookie specialists leveraging direct-store-delivery networks, and contract manufacturers serving private-label retail programs. Dominant competitive moves include portfolio diversification into better-for-you variants and backward integration into alternative sweetener supply chains.
Among diversified snack conglomerates, Mondelēz International, General Mills Inc., and Kellanova occupy positions exemplifying scale-driven cost discipline and national distribution reach. These entities represent the archetype of integrated baking infrastructure supporting multi-brand portfolios across price tiers. Their geographic concentration in legacy Midwest and Northeast manufacturing corridors anchors supply chain density for chocolate chip and oatmeal raisin production at industrial scale.
| Leading Market Players |
|---|
| Mondelēz International |
| General Mills Inc. |
| Ferrero Group |
| McKee Foods Corporation |
| The Campbell Soup Company |
| Grupo Bimbo S.A.B. de C.V. |
| Hostess Brands, LLC |
| PepsiCo Inc. |
| Kellanova |
| Others |
Value Network & Pricing Analysis
Supermarket retail banner concentration anchors pricing power in the US cookies market, locking shelf access behind slotting fee structures that favor scale over innovation. This buyer archetype dominance enforces a volume-versus-premium split where commodity formulations absorb price pressure while heritage-positioned variants capture margin through clean-label certification.
Pricing Analysis
Volume tiers anchored by chocolate chip SKUs operate on thin spreads driven by high-fructose corn syrup and palm oil input costs, while premium oatmeal raisin and single-origin cacao variants command multiples through USDA organic certification and artisan production claims. Price differentiation rests on ingredient provenance and clean-label status rather than functional performance. Pricing pressure intensifies in budget tiers as private-label production leverages identical manufacturing infrastructure with reduced marketing overhead. Institutional foodservice buyers exhibit highest price sensitivity due to state-level school nutrition compliance costs, while direct-to-consumer subscription channels show lowest sensitivity as delivery convenience overrides per-unit economics.
Supply Chain Analysis
Freight cost volatility from Midwest manufacturing corridors to coastal metropolitan markets compresses margins for temperature-sensitive cleaner-label formulations with reduced preservative loads. Domestic wheat flour supply concentrates in Great Plains states, while cacao sourcing draws from West African and Latin American origins through trader-managed commodity channels. Single-source vulnerability in monk fruit and allulose alternative sweetener supply chains creates reformulation risk as FDA added-sugar labeling requirements accelerate adoption. Distribution runs through direct-store-delivery networks controlled by Mondelēz International, General Mills Inc., and Kellanova, with emerging brands bypassing wholesale gatekeepers through online store partnerships and subscription snack box procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cookies market functions as a cost-of-compliance arena where FDA Nutrition Facts revisions and state-level school nutrition standards erect regulatory moats favoring incumbents with dedicated regulatory affairs infrastructure and reformulation R&D budgets.
For Market Incumbents: Hedge against alternative sweetener cost volatility through backward integration into monk fruit and allulose supply chains or long-term offtake agreements with fermentation-derived ingredient suppliers. Defensive consolidation should prioritize acquiring direct-to-consumer subscription brands with established millennial and Gen-Z household penetration, as this channel captures share fastest from supermarket impulse sections.
For New Entrants and Emerging Players: Begin with precision fermentation-derived protein and fat formulations that unify texture functions without synthetic emulsifiers, targeting the white space in heritage-positioned chocolate chip variants using single-origin cacao claims. The most penetrable entry point lies in USDA organic certified oatmeal raisin products for natural and specialty retail channels in California metropolitan corridors, with go-to-market execution through subscription snack box partnerships that bypass slotting fee barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with private-label retail programs and precision fermentation ingredient supplier relationships in Austin's food technology startup ecosystem over capital-intensive branded portfolios. Long-term viability across the next decade hinges on clean-label reformulation capabilities and direct-to-consumer channel infrastructure. The signal to watch is FTC enforcement action on environmental marketing claims, which will separate compliant sustainability positioning from litigation-exposed legacy assertions.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Sweetener Supply Integration | Backward integration into monk fruit and allulose sourcing mitigates FDA-driven reformulation cost volatility. |
| Direct-to-Consumer Channel Expansion | Subscription snack box partnerships bypass supermarket slotting fees and capture coastal millennial household demand. |
| USDA Organic Certification Investment | Clean-label positioning commands shelf space in California specialty retail and justifies premium pricing multiples. |
| Precision Fermentation Adoption | Biotechnology-derived proteins and fats satisfy clean-label preferences while maintaining industrial-scale texture consistency. |
| Sustainability Claims Legal Review | Preemptive FTC compliance audit prevents class-action exposure on packaging environmental assertions. |
Research Methodology
Multi-period observation of slotting fee structures, alternative sweetener pricing indices, and direct-to-consumer subscription channel velocity anchored the trend analysis, supplemented by interviews with brand managers at diversified snack conglomerates, category buyers at supermarket retail banners, supply planners managing wheat flour and cacao procurement, and regulatory affairs leads navigating FDA labeling requirements. Secondary validation drew from Nielsen retail audit data, USDA organic certification databases, SEC 10-K filings of publicly traded food manufacturers, and FDA guidance document repositories. Bottom-up segment sizing triangulated against top-down category value estimates to ensure consistency across the analysis window.
Input-output matrix modeling connected ingredient cost trajectories to finished product pricing tiers across chocolate chip, oatmeal raisin, peanut butter, and sugar product types, with distribution channel segmentation by retail stores, online stores, wholesale, and supermarkets. CAGRs were derived from regression analysis of historical consumption patterns adjusted for regulatory catalysts and channel shift dynamics. Forecast inputs included California and New York state-level nutrition policy implementation timelines and precision fermentation technology adoption curves in contract baking infrastructure.
Underlying measurement precision varies by segment; online store and subscription channel estimates carry tighter precision than institutional foodservice projections due to data availability disparities. Forecasts reflect documented assumptions regarding FDA enforcement consistency and alternative sweetener supply chain scaling. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Biscuit Mixes Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Bakers Yeast Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Teaseed Cake Market
Bakery Products
Dough Whitener Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Pastries Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Lentil Bread Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Pancake Mixes Market
Bakery Products
Low Calorie Bread Market