
 Glider Aircraft Market | 2026-2036
Glider Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Glider Aircraft Market Analysis
Aftermarket service revenue is tilting toward composite airframe refurbishment and avionics retrofitting as original equipment margins compress. Alexander Schleicher GmbH & Co. sustains dominance in high-performance sailcraft through in-house wing manufacturing. Lange Aviation GmbH differentiates via electric self-launch propulsion systems. Schempp-Hirth Flugzeug-Vertriebs GmbH controls the premium competition segment with carbon-fiber fuselage expertise.
A glider aircraft is a fixed-wing aerodyne designed for unpowered flight, utilizing rising air currents for lift, with typical glide ratios exceeding 40:1 for high-performance models and empty weights ranging from 150 kg for single-seat ultralights to over 800 kg for two-seat motorized variants; its primary purpose spans pilot training, recreational soaring, competitive cross-country racing, and military surveillance applications. Composite materials dominate new airframe construction due to strength-to-weight advantages and moldable aerodynamic profiles, while metal substructures persist in training fleets for damage tolerance and repairability. Two-seat configurations anchor the training and commercial instruction segments, whereas motorized gliders are capturing interest among private owners seeking operational independence from tow aircraft and winch launches.
EASA airworthiness directives govern type certification and ongoing operational compliance across European manufacturing and registration jurisdictions, with FAA Part 21 and Part 103 standards shaping access for US experimental and ultralight categories. The EU Green Deal aviation decarbonization pathway is channeling R&D investment toward electric propulsion integration and sustainable manufacturing processes for airframe components. Stakeholders must monitor evolving certification timelines for battery-electric self-launch systems and anticipate how club-level fleet renewal cycles interact with emerging sustainability-linked financing instruments.
Market Dynamics
EASA composite airworthiness certification updates are forcing manufacturers to requalify resin systems and laminate processes, compressing time-to-market for new sailcraft designs while elevating entry barriers for smaller airframe builders.
Growth Catalysts
- EU Green Deal aviation decarbonization pathway:The framework channels R&D investment toward electric propulsion integration, accelerating battery-electric self-launch system development for private owner segments.
- Alpine corridor club fleet renewal:Recreational aviation associations across Austria, Switzerland, and southern Germany are expanding orders for two-seat training gliders with modern avionics packages.
- Carbon-fiber fuselage expertise diffusion:Moldable aerodynamic profiles enable high-performance competition models with glide ratios exceeding 50:1, attracting cross-country racing participants.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray and Hexcel dominate aerospace-grade composite feedstock, exposing airframe builders to price volatility and allocation constraints.
- EASA type certification timelines:New electric propulsion integrations face extended validation periods for battery thermal runaway containment and electromagnetic compatibility testing.
- Winch launch infrastructure decay:Grass airfield closures across rural Germany reduce accessible launch options for pure sailcraft owners.
Strategic Opportunities
- Underpenetrated Nordic instruction market:Norway and Sweden maintain low glider pilot density relative to Germany, presenting fleet expansion potential for training-school operators.
- Sustainability-linked financing instruments:Green bond frameworks and ESG-tied club loans are emerging to fund electric self-launch fleet conversions.
- Avionics retrofitting aftermarket:Legacy fleet owners seek glass-cockpit upgrades and ADS-B Out compliance, creating service revenue streams independent of new airframe sales.
Industry Challenges
- Composite repair technician scarcity:Certified laminate specialists capable of scarf repairs on carbon-fiber primary structures remain concentrated at OEM facilities.
- Battery-electric certification pathway uncertainty:EASA has not finalized endurance reserve requirements for self-launch systems, freezing product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glider Aircraft Market |
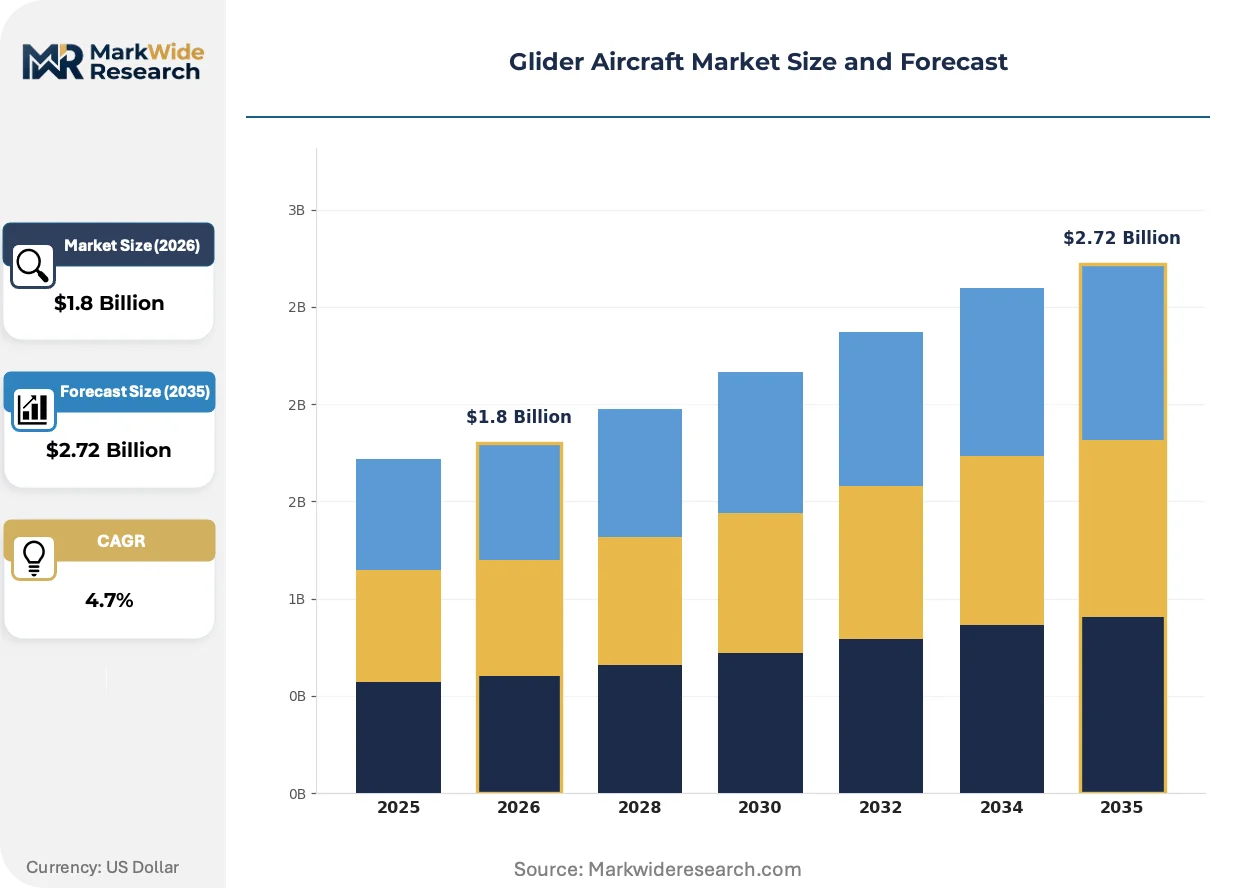
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Single-Seat, Two-Seat, Motorized, Experimental Material: Composite, Metal, Wood, Fabric Application: Aerobatics, Training, Cross-Country, Recreational End User: Commercial, Military, Private, Educational |
| Companies Covered | Schempp-Hirth Flugzeug-Vertriebs GmbH, Aeros Company, DG Aviation GmbH, Moyes Delta Gliders, North Wing, Lange Aviation GmbH, Airborne Windsports, Bautek Fluggeräte GmbH, Alexander Schleicher GmbH & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glider Aircraft Market Emerging Trajectories
Digital instrumentation and electric propulsion are converging to redefine operational autonomy in unpowered aviation, shifting competitive advantage toward integrated system architectures rather than standalone airframe performance.
Glass-cockpit avionics suites are digitizing flight instrumentation across the training and private-owner segments. Flight schools in Germany and Austria are mandating electronic flight bag integration for new instructor certifications. This capability compression is eliminating the aftermarket for standalone variometers and mechanical altimeters.
REACH chemical substance restrictions are tightening allowable resin formulations in composite airframe manufacturing. German and Czech builders must reformulate epoxy systems to eliminate SVHC-classified hardeners. The premium competition segment is absorbing compliance costs through captive in-house resin development.
Club-level procurement is consolidating around turn-key fleet packages bundling airframe, insurance, and maintenance. Austrian and Swiss soaring associations are abandoning piecemeal acquisition in favor of multi-airframe framework agreements with single-source OEMs. This concentration is visible most acutely in the two-seat training category where standardization reduces instructor conversion costs.
Glider Aircraft Market Segmentation
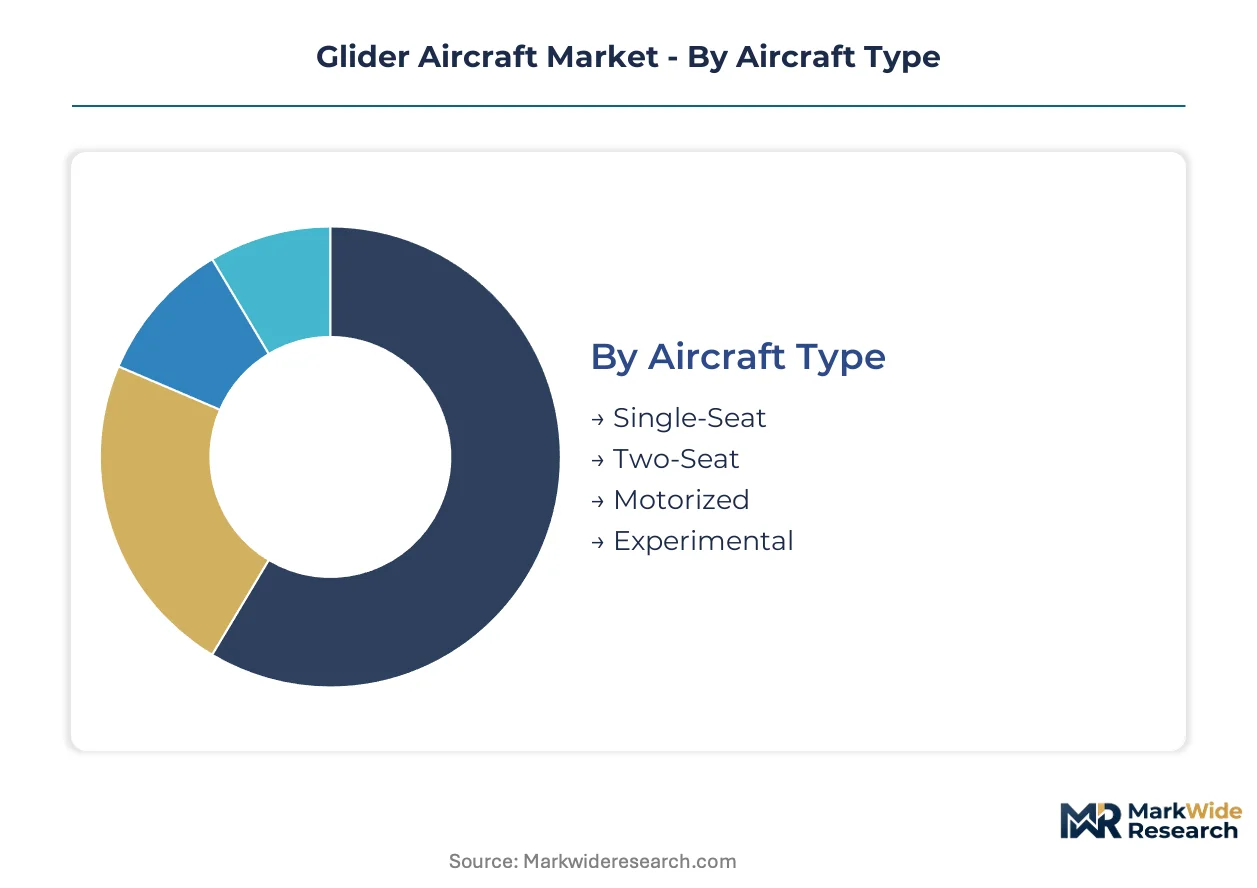
Glider aircraft segmentation reveals how operational purpose, construction economics, and user economics intersect. Manufacturers configure airframes, materials, and avionics around distinct flight profiles rather than pursuing universal platforms.
Aircraft Type:
Mature configurations dominate club fleets while emerging propulsion architectures reshape private ownership economics.
- Single-Seat:Ultralight structures with empty weights below 300 kg optimize for thermal soaring efficiency. Austrian and Swiss alpine clubs concentrate demand here for solo cross-country certification progression, constrained by winch launch infrastructure availability.
- Two-Seat:Dual-cockpit designs with reinforced fuselage structures accommodate instruction workloads and shared pilot weight margins. German recreational aviation associations drive fleet renewal orders, prioritizing standardized avionics packages that reduce instructor conversion costs.
- Motorized:Retractable propulsion systems enable self-launch capability and engine-assisted cruise.
- Experimental:Amateur-built categories under FAA Part 103 and EASA Annex II permit custom aerodynamic development.
Two-Seat retains volume leadership; Motorized holds the steepest expansion curve.
Material:
Cost tier stratification separates premium competition builds from training fleet durability requirements.
- Composite:Carbon-fiber and glass-reinforced polymer laminates deliver strength-to-weight ratios exceeding 40:1 glide performance. EASA airworthiness certification updates are forcing resin system requalification among German and Czech manufacturers, compressing development timelines.
- Metal:Aluminum alloy substructures with riveted joints persist in high-cycle training environments. Damage tolerance and field repairability concentrate demand within French and Polish instructional fleets where rough-field operations predominate.
- Wood:Traditional spruce and plywood construction survives in heritage restoration and amateur-built segments.
- Fabric:Doped polyester or Dacron coverings over metal tube frames serve cost-sensitive ultralight categories.
Composite captures premium positioning; Metal anchors volume in training economics.
Application:
Customer type divergence separates institutional procurement from discretionary enthusiast spending.
- Training:Forgiving stall characteristics and dual-control redundancy define instructional specifications. German, Austrian, and Swiss soaring clubs concentrate procurement here, bundling insurance and maintenance into multi-airframe framework agreements.
- Cross-Country:High-aspect-ratio wingspans exceeding 20 meters optimize for distance racing performance. Private owners across the European alpine corridor drive demand, attracted by carbon-fiber fuselage expertise enabling 50:1 glide ratios.
- Aerobatics:Reinforced wing structures and symmetric airfoils withstand negative load factors.
- Recreational:Moderate performance specifications balance acquisition cost against weekend usability.
Training commands institutional procurement volume; Cross-Country gains share fastest among discretionary buyers.
End User:
Volume concentration clusters within educational and commercial operators while margin extraction favors private segments.
- Commercial:Flight schools and touring operators amortize airframe costs across high utilization rates. Austrian and German training-school operators dominate procurement, leveraging sustainability-linked financing instruments for electric self-launch fleet conversions.
- Private:Individual owners prioritize operational autonomy and customization flexibility. Battery-electric self-launch systems attract this segment, though EASA has not finalized endurance reserve requirements, freezing product roadmaps.
- Military:Surveillance and silent reconnaissance applications drive specialized procurement.
- Educational:University aeronautical programs and technical colleges acquire platforms for research and pilot development.
Commercial absorbs production volume; Private commands margin premiums through specification customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes glider aircraft for club-based instruction while Austria and Switzerland prioritize high-performance cross-country racing, creating divergent procurement specifications across the alpine corridor.
Germany
Recreational aviation associations in Bavaria and Baden-Württemberg are expanding two-seat training fleet orders with standardized avionics packages. EASA airworthiness certification updates are forcing resin system requalification among domestic manufacturers. The Wasserkuppe region in Hesse maintains concentrated glider manufacturing and flight training infrastructure.
Switzerland
Private owners across the Swiss Alps are driving demand for carbon-fiber competition models with glide ratios exceeding 50:1. Swissmedic regulates aviation medical certification for pilot licensing. The Interlaken-Oberhasli corridor hosts dense cross-country racing activity and specialized airframe maintenance clusters.
Austria
Austrian soaring clubs are consolidating procurement around turn-key fleet packages bundling airframe, insurance, and maintenance. The EU Green Deal aviation decarbonization pathway channels R&D investment toward electric propulsion integration. The Tyrol and Salzburg alpine regions concentrate both recreational flying activity and composite airframe refurbishment services.
France
Instructional fleets in the French Alps and Pyrenees favor metal-substructure gliders for damage tolerance in rough-field operations. ANSM oversees aviation medical standards harmonized with EASA frameworks. The Grenoble-Chambéry corridor supports metal airframe repair clusters serving training-school operators.
Poland
Cost-sensitive training operators are sustaining demand for metal and fabric-construction ultralights. The country's national aviation regulator aligns type certification with EASA standards for EU market access. The Podkarpackie and Lesser Poland regions host emerging flight school networks and legacy airframe refurbishment capabilities.
Glider Aircraft Market Vendor Landscape
Capability concentration sits with specialized composite airframe builders; scale advantage sits with diversified recreational aviation manufacturers serving multiple unpowered aircraft categories. The vendor base separates into three tiers: premium competition specialists with captive carbon-fiber expertise, mid-market training fleet suppliers with standardized product lines, and ultralight fabricators competing on acquisition cost. Dominant competitive moves include backward integration into wing manufacturing and strategic partnerships for electric propulsion system integration.
Among German-based manufacturers, Alexander Schleicher GmbH & Co. and Lange Aviation GmbH exemplify divergent specialization archetypes—one representing in-house composite manufacturing depth, the other occupying electric self-launch system development. Schempp-Hirth Flugzeug-Vertriebs GmbH anchors the premium competition tier through carbon-fuselage expertise. These three entities collectively illustrate how geographic proximity to the alpine corridor correlates with positioning across performance and propulsion segments.
| Leading Market Players |
|---|
| Schempp-Hirth Flugzeug-Vertriebs GmbH |
| Aeros Company |
| DG Aviation GmbH |
| Moyes Delta Gliders |
| North Wing |
| Lange Aviation GmbH |
| Airborne Windsports |
| Bautek Fluggeräte GmbH |
| Alexander Schleicher GmbH & Co. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Czech and Polish metal-airframe production is compressing supplier pricing power while elevating buyer leverage across Central European training fleets. This utilization asymmetry between composite-specialist OEMs and metal-fabrication subcontractors feeds divergent margin trajectories across material tiers.
Pricing Analysis
Long-term framework agreements dominate club-level procurement, with Austrian and Swiss soaring associations locking multi-airframe bundles spanning five-to-seven-year horizons. Price differentiation hinges on EASA certification tier and avionics integration depth, with glass-cockpit packages commanding substantial premiums over analog configurations. Cost compression in the metal-training tier is intensifying because Polish and Czech fabricators compete for shrinking grass-airfield demand. Commercial flight-school operators exhibit highest price sensitivity, whereas private competition-segment buyers prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Extended payment terms from German OEMs to Toray and Hexcel are straining prepreg carbon-fiber supplier cash conversion cycles. Aerospace-grade composite feedstock concentrates in Japan and the United States, while metal-substructure components source from Czech and Polish fabrication clusters. Supply chain risk centers on single-source vulnerability for high-modulus carbon-fiber tow, with no qualified secondary vendors for EASA-certified laminate specifications. Distribution runs through OEM-direct channels for premium competition models, whereas training fleets procure via consolidated association frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric propulsion integration represents a high-growth disruption as EU Green Deal decarbonization mandates rechannel R&D investment toward battery-electric self-launch architectures.
For Market Incumbents: Entrench composite manufacturing depth through captive wing production and in-house resin formulation capabilities. EASA battery-electric certification uncertainty threatens product roadmap stability; prioritize thermal-runaway containment engineering investment to accelerate type-validation timelines. For New Entrants and Emerging Players: Pursue the underpenetrated Nordic instruction market, where Norway and Sweden maintain glider pilot density ratios below German benchmarks. Electric self-launch retrofit kits for legacy airframes offer a service-based entry vector with lower certification barriers than clean-sheet designs. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because EU Green Deal aviation decarbonization pathways will eventually mandate electric propulsion adoption across recreational aviation segments. Acquisition targets should demonstrate composite repair technician training infrastructure and EASA Part-21 design organization approvals. The signal to watch is finalization of EASA endurance reserve requirements for battery-electric self-launch systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wing Manufacturing | Alexander Schleicher GmbH & Co. sustains competitive moats through captive carbon-fiber laminate production. |
| Electric Propulsion System Partnership | Lange Aviation GmbH differentiates via integrated battery-electric self-launch architecture development. |
| Multi-Airframe Framework Agreement | Austrian and Swiss soaring associations consolidate procurement power through standardized fleet packages. |
| Composite Repair Technician Certification Program | OEM facilities address scarcity of certified laminate specialists capable of scarf repairs on primary structures. |
| Avionics Retrofit Service Expansion | Aftermarket operators capture glass-cockpit upgrade demand from legacy fleet owners seeking ADS-B Out compliance. |
Methodological Framework
Desk research of EASA type certification databases, EU Green Deal policy documentation, and recreational aviation association fleet registries preceded structured interviews with glider OEM engineering directors, composite airframe repair technicians, flight-school procurement managers, and alpine club fleet coordinators. Secondary validation drew from national aviation authority regulatory filings, customs trade data for aerospace-grade composite imports, and soaring association annual reports. Bottom-up airframe shipment tallies triangulated against top-down market value estimates derived from disclosed OEM revenue ranges.
Assumptions held EASA certification timeline trajectories and EU Green Deal aviation decarbonization policy implementation as fixed boundary conditions, while battery-electric propulsion adoption rates and club-level fleet renewal cycle timing varied across sensitivity scenarios. Segmentation modeling spanned aircraft type, construction material, operational application, and end-user category, with geographic clustering across the European alpine corridor. CAGRs were derived from slope-intercept fitting of historical shipment data against projected replacement demand and expansion fleet orders. Industry-specific inputs included winch launch infrastructure closure rates and electric self-launch system certification pathway progression.
Sensitivities concentrate around EASA battery-electric endurance reserve requirement finalization and prepreg carbon-fiber allocation constraints from Toray and Hexcel. Forecasts reflect documented assumptions regarding club procurement consolidation trends and REACH chemical substance restriction compliance costs. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
America Attack Helicopter Market
Aircraft
Aircraft Seals Market
Aircraft
US Military Aviation Market
Aircraft
Military Helicopters Market
Aircraft
Commercial Aircraft Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Aircraft Fairings Market
Aircraft
Attack Helicopter Market
Aircraft
Europe Aviation Market
Aircraft
Light and Very Light Jets Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Control Surface Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Aero Wing Market
Aircraft
Aircraft Band Clamps Market