
 Nigeria Commercial Vehicles Lubricants Market | 2026-2036
Nigeria Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Commercial Vehicles Lubricants Market Foresight
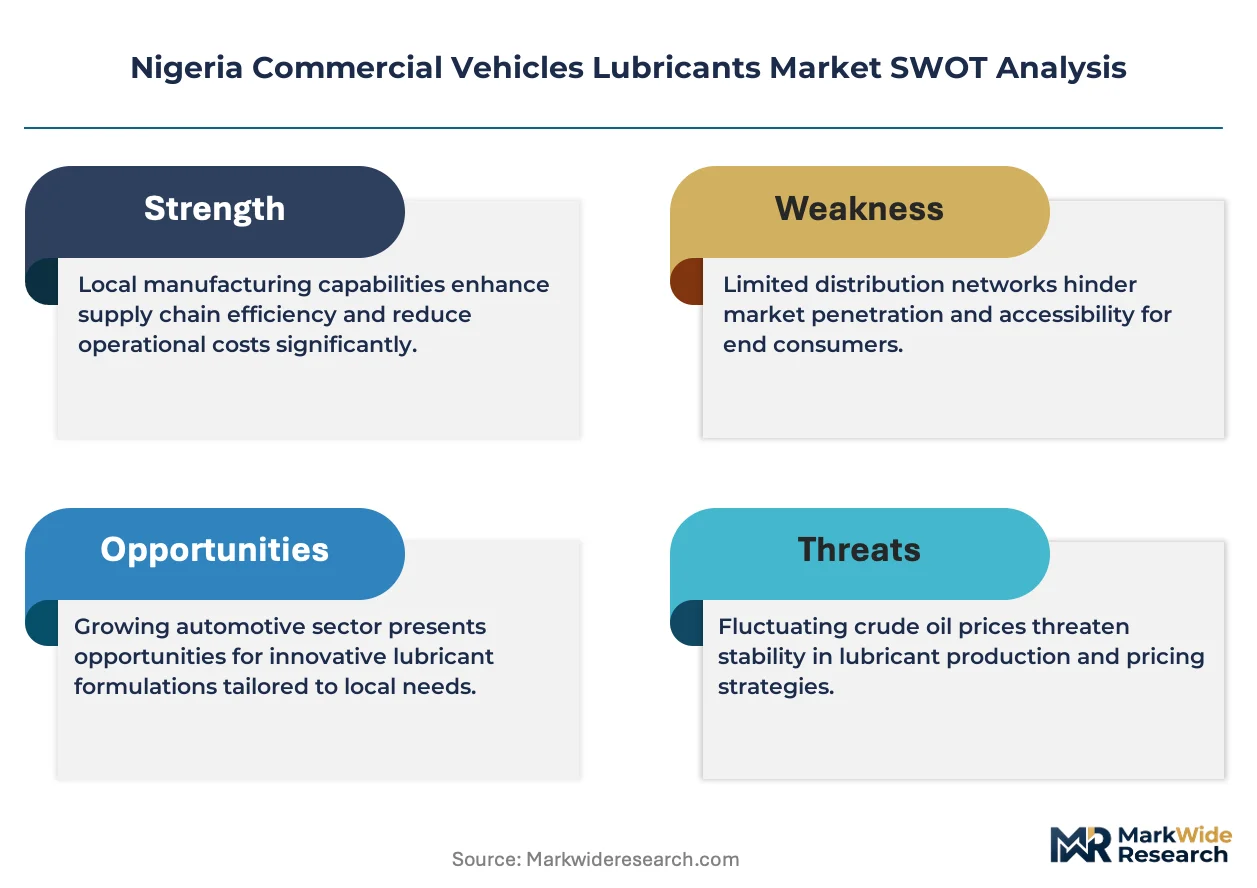
Aftermarket service revenue is tilting from simple product sales toward bundled oil-change and fleet-maintenance contracts. TotalEnergies Marketing Nigeria Plc leverages its extensive retail network to anchor long-term supply agreements with logistics operators. Oando Plc competes through backward integration into base oil blending, while Mobil Oil Nigeria specializes in high-performance formulations for tropical operating conditions.
Nigeria commercial vehicles lubricants comprise refined petroleum-based or synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in diesel engines operating under high load factors and ambient temperatures exceeding 35°C. These products typically meet API CK-4 or FA-4 specifications for heavy-duty cycles and serve to extend engine overhaul intervals in commercial trucking and construction equipment. Engine oil commands the dominant share of product-type value pools due to higher consumption frequency and premium pricing for synthetic grades. Fleet operators represent the fastest-expanding end-user category as third-party logistics providers professionalize maintenance protocols. Direct sales channels capture the most attractive margins by bypassing distributor markups for large-volume accounts.
The Standards Organisation of Nigeria enforces mandatory lubricant labeling and quality certification under its product registration scheme, while the Department of Petroleum Resources monitors fuel and lubricant standards across downstream operations. The National Agency for Food and Drug Administration and Control additionally regulates grease products used in food-contact transport applications. Stakeholders must monitor enforcement intensity at state-level motor parks and border entry points where substandard imports persist.
Market Dynamics
Fleet consolidation across the Lagos-Kano trucking corridor is compressing procurement timelines and forcing lubricant suppliers to restructure around direct-to-fleet service models rather than traditional distributor networks.
Growth Catalysts
- API CK-4/FA-4 specifications:The Standards Organisation of Nigeria's quality enforcement is phasing out obsolete lubricant grades and creating upgrade cycles across commercial vehicle fleets operating in high-thermal conditions.
- Third-party logistics providers:Professionalized maintenance protocols among fleet operators are standardizing preventive oil-change intervals and expanding contracted lubricant volumes.
- Apapa port complex:Container throughput growth is intensifying heavy-duty trucking activity along the northern industrial corridor and accelerating lubricant consumption rates.
Market Restraints
- Base oil import dependency:Nigeria lacks domestic refining capacity for Group II/III base stocks, exposing blenders to currency volatility and freight cost fluctuations from Middle Eastern suppliers.
- Substandard import penetration:Unregistered lubricant products continue entering through porous border checkpoints in Kano and Borno states, undercutting certified product pricing.
- Extended drain interval technology:Synthetic formulations with 50,000+ kilometer service life are compressing per-vehicle lubricant volume requirements despite premium pricing.
Strategic Opportunities
- On-site fleet maintenance:Mobile oil-change services at Lagos motor parks and industrial zones are bypassing traditional retail channels and capturing direct fleet relationships.
- Used oil re-refining infrastructure:Regulatory pressure from the Department of Petroleum Resources is creating openings for circular economy investments in base oil recovery.
- Construction equipment segment:Earthmoving fleets in Abuja and Port Harcourt remain underpenetrated by synthetic formulations relative to long-haul trucking.
Industry Challenges
- Technical certification backlog:Product registration delays at the Standards Organisation of Nigeria are extending time-to-market for new lubricant formulations by six to twelve months.
- Skilled technician scarcity:Fleet maintenance depots in northern Nigeria face shortages of personnel trained in oil analysis and condition-based monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Commercial Vehicles Lubricants Market |
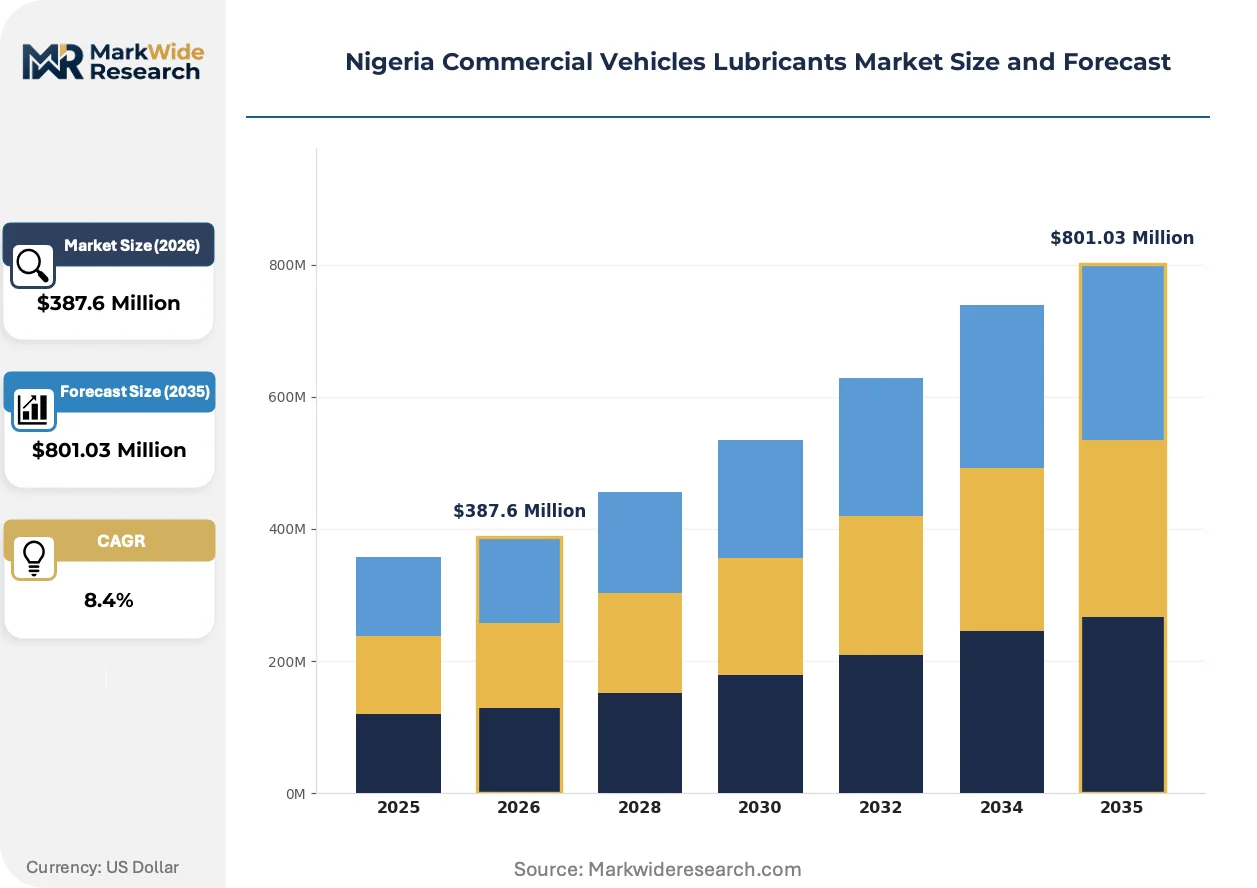
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Fluid End User: Logistics Companies, Fleet Operators, Construction Firms, Public Transport Distribution Channel: Retail Outlets, Online Platforms, Direct Sales, Wholesalers Service Type: Maintenance Services, Repair Services, Oil Change Services, Consultation |
| Companies Covered | 11 Plc, Ardova Plc, Conoil Plc, MRS Oil Nigeria Plc, Oando Plc, TotalEnergies Marketing Nigeria Plc, Shell Petroleum Development Company, Chevron Nigeria, Mobil Oil Nigeria, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Commercial Vehicles Lubricants Market Shifts & Advancements
Telematics integration and predictive maintenance systems are restructuring how fleet operators specify, procure, and consume lubricant products across Nigeria's commercial vehicle base.
Remote oil condition monitoring is digitizing fleet maintenance decisions. Sensors measuring viscosity degradation, soot loading, and oxidation levels transmit data to centralized fleet management platforms. Large logistics operators in Lagos State are deploying these systems across 200+ vehicle fleets. Real-time alerts are compressing unscheduled downtime and enabling just-in-time lubricant delivery scheduling.
The Standards Organisation of Nigeria's mandatory product registration scheme is tightening quality enforcement. Random sampling at state motor parks and border entry points has intensified seizure rates for unregistered imports. Blenders are responding by accelerating SON certification timelines and reformulating products to meet declared specifications. The policy is consolidating market share toward certified domestic producers.
Long-term supply contracting is displacing spot purchasing among fleet operators. Third-party logistics providers are negotiating annual volume agreements with fixed pricing and embedded technical service support. Direct sales teams from major suppliers are establishing dedicated account management for accounts exceeding 500 vehicles. The model is most advanced along the Apapa-Kano corridor where fleet density supports route-based delivery logistics.
Nigeria Commercial Vehicles Lubricants Market Segmentation
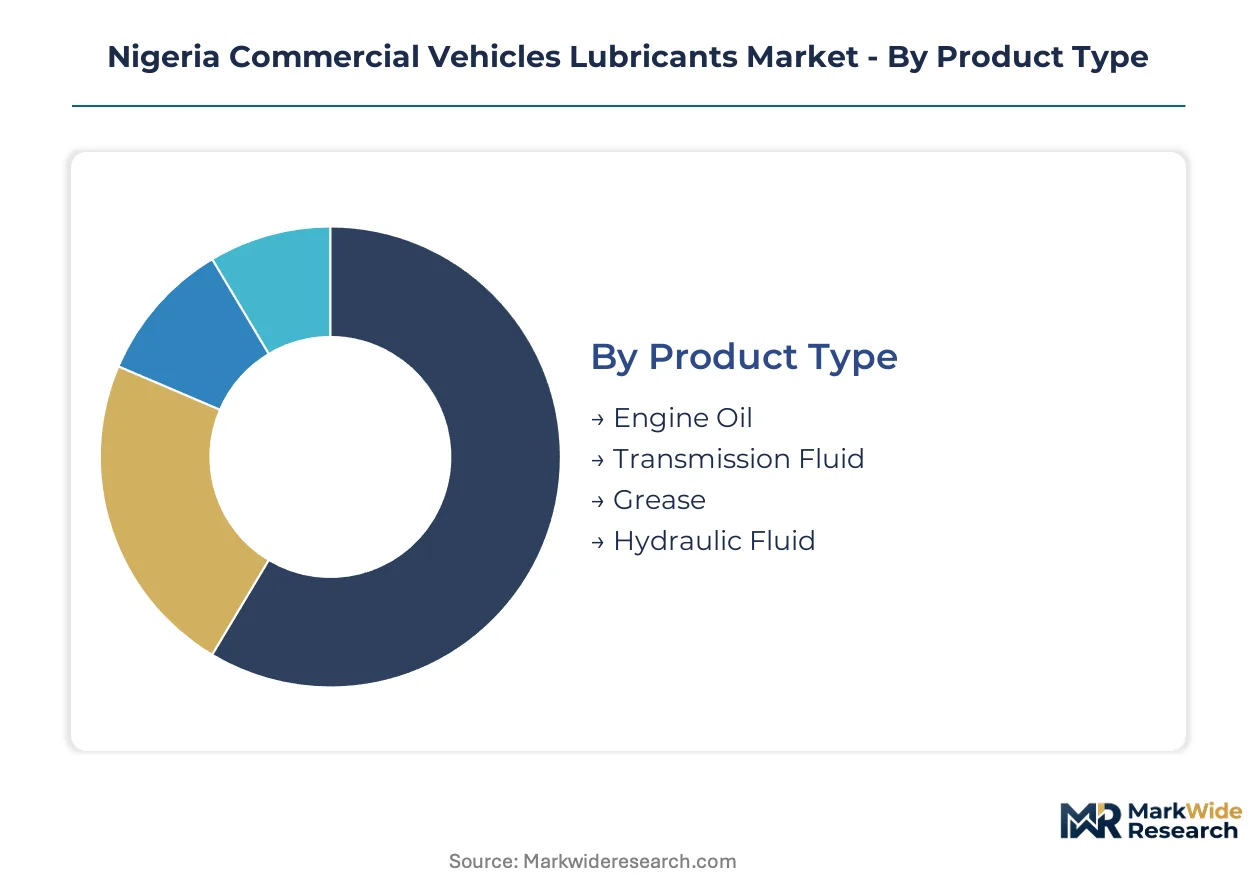
Segmentation in Nigeria's commercial vehicles lubricants market reveals how procurement patterns diverge across fleet sophistication levels and service intensity requirements. Understanding these divisions exposes where margin pools concentrate and which customer relationships demand differentiated technical support.
Product Type:
After-sales-service intensity varies dramatically by lubricant category, with engine oil demanding the most frequent technical intervention and hydraulic fluid requiring specialized application engineering.
- Engine Oil:Refined petroleum-based or synthetic formulations meeting API CK-4 or FA-4 specifications for heavy-duty diesel cycles. Demand concentrates among long-haul trucking fleets along the Apapa-Kano corridor where thermal stress from ambient temperatures exceeding 35°C accelerates consumption frequency and drives upgrade cycles toward synthetic grades.
- Transmission Fluid:Formulations engineered for automated manual and automatic transmissions in commercial vehicles operating under high load factors. Fleet operators in Lagos State are standardizing preventive replacement intervals, expanding contracted volumes through bundled maintenance agreements with direct suppliers.
- Grease:Lithium-complex and calcium-sulfonate thickeners for chassis, wheel bearings, and fifth-wheel applications. Construction equipment operators in Abuja and Port Harcourt represent concentrated demand for high-temperature formulations.
- Hydraulic Fluid:Anti-wear formulations for construction and material-handling equipment. Earthmoving fleets require specialized viscosity grades for tropical operating conditions.
By volume, Engine Oil leads. By growth pace, Transmission Fluid is ahead.
End User:
Customer procurement maturity determines whether lubricant supply follows transactional spot purchasing or integrated fleet management contracting.
- Fleet Operators:Third-party logistics providers with professionalized maintenance protocols. These operators negotiate annual volume agreements with fixed pricing and embedded technical service support, representing the steepest expansion trajectory as consolidation accelerates across the Lagos-Kano trucking corridor.
- Logistics Companies:Asset-light operators relying on contracted haulage services. Lubricant procurement typically flows through vehicle leasing arrangements rather than direct purchasing.
- Construction Firms:Earthmoving and material-handling equipment operators in Abuja and Port Harcourt. Synthetic formulation penetration lags long-haul trucking due to fragmented equipment ownership and project-based maintenance cycles.
- Public Transport:State-managed bus fleets and interstate coach operators. Procurement follows government tender processes with extended payment terms and mandatory SON certification requirements.
By contract value, Fleet Operators dominate. By addressable expansion, Construction Firms show the widest gap.
Distribution Channel:
Channel economics reflect fleet scale thresholds and the cost-to-serve tradeoffs between personalized technical support and transactional efficiency.
- Direct Sales:Supplier-to-fleet relationships bypassing distributor markups for accounts exceeding 500 vehicles. Major suppliers deploy dedicated account managers along high-density corridors where route-based delivery logistics minimize per-drop costs.
- Wholesalers:Regional distributors serving smaller fleet operators and independent garages. Kano and Lagos wholesale networks consolidate procurement for northern and southwestern coverage zones respectively.
- Retail Outlets:Branded service stations and independent lubricant shops. Individual owner-operators and small fleets rely on these points for emergency top-ups and unscheduled maintenance.
- Online Platforms:Emerging digital procurement channels for standardized product grades. Adoption concentrates among younger fleet managers in Lagos State seeking price transparency and consolidated invoicing.
By margin capture, Direct Sales leads. By coverage breadth, Wholesalers span the most geography.
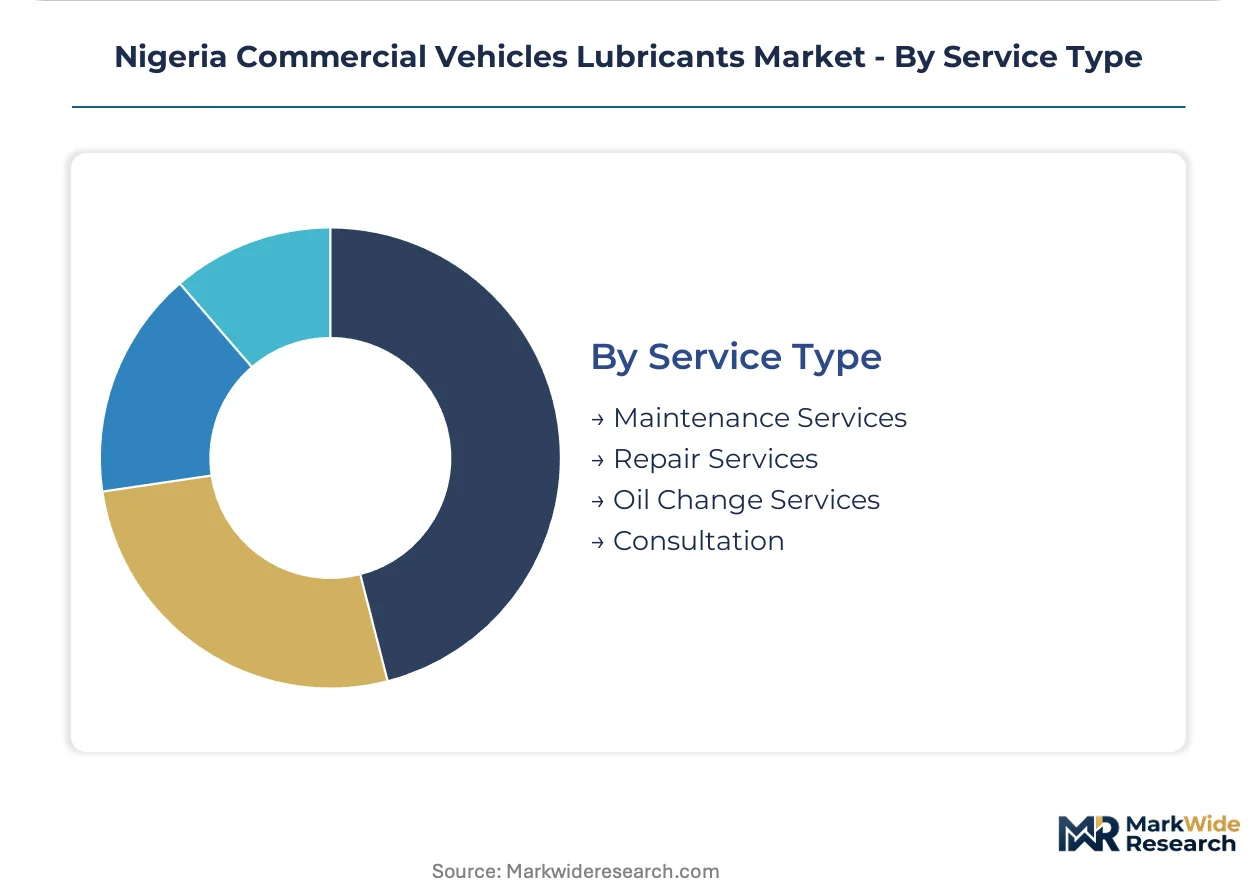
Service Type:
Service bundling intensity separates premium supplier relationships from commodity lubricant transactions.
- Oil Change Services:Scheduled preventive maintenance including fluid replacement, filter changes, and used oil collection. Mobile service units at Lagos motor parks and industrial zones are capturing direct fleet relationships through on-site execution.
- Maintenance Services:Comprehensive fleet care programs integrating lubricant supply with condition monitoring and overhaul scheduling. Large logistics operators deploy telematics-integrated platforms for predictive maintenance.
- Repair Services:Corrective interventions following component failures. Lubricant suppliers provide technical root-cause analysis to distinguish material defects from maintenance protocol failures.
- Consultation:Oil analysis programs and lubricant specification advisory. Fleet operators in northern Nigeria face scarcity of personnel trained in condition-based monitoring protocols, creating service gaps.
By revenue per vehicle, Maintenance Services leads. By expansion velocity, Oil Change Services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Nigerian sub-markets. Fleet operators in Lagos demonstrate lowest sensitivity to premium synthetic grades, while owner-operators in northern corridors remain highly responsive to per-liter pricing. Construction zones in the south-south exhibit intermediate elasticity tied to project cash-flow cycles.
Lagos State
Container throughput at Apapa port drives heavy-duty trucking density along the northern industrial corridor. The Standards Organisation of Nigeria operates its most intensive enforcement regime here, with random sampling at motor parks and fuel depots. Third-party logistics providers in Ikeja and Oshodi industrial zones negotiate annual volume agreements with embedded technical service support.
Kano State
Trans-Saharan freight corridors concentrate long-haul fleet activity with elevated thermal stress from desert operating conditions. Border checkpoints face persistent unregistered lubricant penetration from neighboring markets. Dala and Sabon Gari industrial clusters host wholesale distribution networks consolidating procurement for northern coverage zones.
Rivers State
Port Harcourt's oilfield services and construction equipment base generates specialized demand for high-temperature grease formulations. The Department of Petroleum Resources maintains downstream monitoring presence across petroleum product depots. Onne and Trans Amadi industrial layouts remain underpenetrated by synthetic formulations relative to long-haul trucking segments.
Federal Capital Territory
Abuja's earthmoving fleets for infrastructure projects operate on project-based maintenance cycles with fragmented equipment ownership. Public transport procurement follows government tender processes with extended payment terms. Gwagwalada and Kubwa satellite towns concentrate independent garage networks serving smaller fleet operators.
Ogun State
Agbara and Sagamu industrial corridors anchor manufacturing logistics with dense commercial vehicle deployment. Proximity to Lagos creates pricing arbitrage opportunities for fleet operators sourcing across state boundaries. Mobile oil-change services are capturing direct fleet relationships through on-site execution at motor parks.
Nigeria Commercial Vehicles Lubricants Market Competitive Landscape
Capability concentration sits with integrated blenders controlling base oil supply; scale advantage sits with marketing networks with extensive retail infrastructure. The market structures around three tiers: multinational majors with full synthetic portfolios, domestic integrated blenders with backward supply control, and regional distributors serving fragmented owner-operator segments. Dominant competitive moves include long-term supply contracting with large fleet accounts and mobile service deployment bypassing traditional wholesale channels.
Among Nigeria-based integrated marketers, Oando Plc and 11 Plc occupy positions emphasizing captive blending capacity and direct fleet relationships. TotalEnergies Marketing Nigeria Plc and Mobil Oil Nigeria exemplify the multinational tier with premium formulation specialization and technical service bundling. Ardova Plc and Conoil Plc sit within the domestic distributor tier consolidating procurement for smaller operators across regional coverage zones.
| Leading Market Players |
|---|
| 11 Plc |
| Ardova Plc |
| Conoil Plc |
| MRS Oil Nigeria Plc |
| Oando Plc |
| TotalEnergies Marketing Nigeria Plc |
| Shell Petroleum Development Company |
| Chevron Nigeria |
| Mobil Oil Nigeria |
| Others |
Supply & Pricing Matrix
The Apapa-Kano trucking corridor concentrates freight cost dynamics that amplify supply-side pricing power while fragmenting downstream price differentiation across fleet sophistication tiers. Base oil import dependency and distributor network density interact to create tiered margin capture that favors direct-to-fleet suppliers over wholesale-dependent competitors.
Pricing Analysis
Long-term offtake contracts with annual volume agreements and fixed pricing dominate procurement between major suppliers and fleet operators exceeding 500 vehicles, while spot purchasing persists among owner-operators and smaller fleets. Price differentiation separates API CK-4 certified synthetic grades from unregistered economy products, with volume scale and embedded technical service bundling as secondary drivers. Cost compression in the wholesale tier intensifies as substandard imports penetrate border checkpoints, eroding certified product margins. Fleet operators in Lagos State demonstrate lowest price sensitivity due to professionalized maintenance protocols, while northern corridor owner-operators remain highly responsive to per-liter pricing.
Supply Chain Analysis
Base oil blending capacity concentrates among integrated marketers with captive supply arrangements, while independent blenders draw from Middle Eastern Group II/III stock imports through Lagos port terminals. Raw material dependencies rest on imported base oils, additive packages from European suppliers, and domestic packaging materials. Single-source vulnerability runs through the Apapa port complex where customs clearance delays and currency volatility disrupt input flows. Distribution runs through direct sales teams for large fleet accounts, regional wholesalers in Kano and Lagos, and mobile service units bypassing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet consolidation across the Lagos-Kano corridor is shifting procurement leverage toward fewer, larger buyers with professionalized technical requirements and contracted volume expectations.
For Market Incumbents: Insulate market position by accelerating SON certification timelines for new formulations and deploying dedicated account management along high-density trucking corridors. Substandard import penetration at northern border checkpoints threatens certified product pricing integrity. Backward integration into base oil blending secures margin control against currency-driven input volatility. For New Entrants and Emerging Players: Abuja and Port Harcourt construction equipment segments offer underpenetrated white-space for synthetic formulation adoption, with earthmoving fleets operating on fragmented project-based maintenance cycles. Mobile oil-change services at Lagos motor parks provide a direct fleet relationship channel that bypasses entrenched wholesale networks. Technical certification investment unlocks access to government tender processes for public transport procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational majors seeking to divest non-core lubricant marketing operations in sub-Saharan Africa. Long-term viability rests on positioning for fleet consolidation trends and circular economy infrastructure buildout. Monitor seizure rates for unregistered imports at state motor parks as an inflection indicator for certified product market share expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Blending | Oando Plc's captive blending capacity insulates margin structure from Middle Eastern supply volatility. |
| Long-term Supply Agreement | TotalEnergies anchors fleet relationships through annual volume contracts with embedded technical service support. |
| Mobile Service Deployment | On-site oil-change units at Lagos motor parks bypass distributor markups and capture direct fleet access. |
| SON Certification Acceleration | Rapid product registration compliance consolidates market share as enforcement intensifies at border checkpoints. |
| Used Oil Re-refining Investment | Department of Petroleum Resources pressure creates circular economy openings for base oil recovery infrastructure. |
Research Methodology
Cross-validation between fleet operator procurement data and Standards Organisation of Nigeria enforcement records anchors the qualitative findings on market structure evolution. Primary interviews with logistics procurement managers, lubricant blending plant operators, motor park service providers, and Department of Petroleum Resources officials combined with secondary validation from customs trade data, SON product registration databases, and company SEC filings. Bottom-up volume modeling triangulates against top-down market sizing across product type, end user, and distribution channel segments.
Calibration against historical consumption patterns and fleet expansion trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions include product grade tier, fleet sophistication level, channel structure, and regional thermal stress profile. CAGRs derive from elasticity-adjusted volume projections and premium pricing capture assumptions. Forecast inputs incorporate container throughput growth at Apapa port, API specification upgrade cycles, and telematics adoption rates among third-party logistics providers.
Practitioners should monitor base oil import cost movements, SON enforcement intensity at border checkpoints, and synthetic formulation penetration rates in construction equipment for early signals of forecast deviation. Quarterly review of fleet consolidation announcements, used oil re-refining regulatory developments, and mobile service unit expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Tire Mold Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Center and Drag Link Market