
 Boat and Ship Telematics Market | 2026-2036
Boat and Ship Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Boat and Ship Telematics Market Outlook
Silicon-based sensor arrays are restructuring the cost architecture of vessel monitoring hardware, displacing legacy electromechanical gauges across commercial fleets. Kongsberg Digital leverages its offshore automation heritage to dominate integrated bridge-to-shore platforms. Wartsila anchors its position through captive engine diagnostics tied to its propulsion installed base. ORBCOMM competes on satellite-agnostic connectivity that spans L-band and VSAT constellations without proprietary lock-in.
Boat and ship telematics encompasses GPS positioning, engine parameter logging, two-way maritime communication, and environmental safety alerting transmitted via satellite, cellular, or short-range radio links to shoreside operations centers. Systems typically sample engine temperature, fuel flow, and hull stress at sub-minute intervals, compressing telemetry through Iridium or Inmarsat satellite pipes when cellular towers sit beyond horizon. GPS tracking and engine monitoring command the largest installed revenue pools, while safety sensors represent the fastest structural expansion as insurers mandate collision-avoidance and man-overboard detection. Fleet management applications concentrate margin in subscription analytics, whereas navigation hardware faces commoditization from open-standards chart plotters.
The International Maritime Organization enforces global emissions reporting through its Data Collection System, while the EU MRV Regulation imposes granular CO2 disclosure on voyages touching European ports. The US Coast Guard mandates automatic identification system carriage for most commercial vessels, creating baseline connectivity infrastructure that telematics vendors exploit for upsell. Stakeholders must weigh satellite spectrum auctions against cellular maritime coverage expansion when committing to decade-long fleet communication contracts.
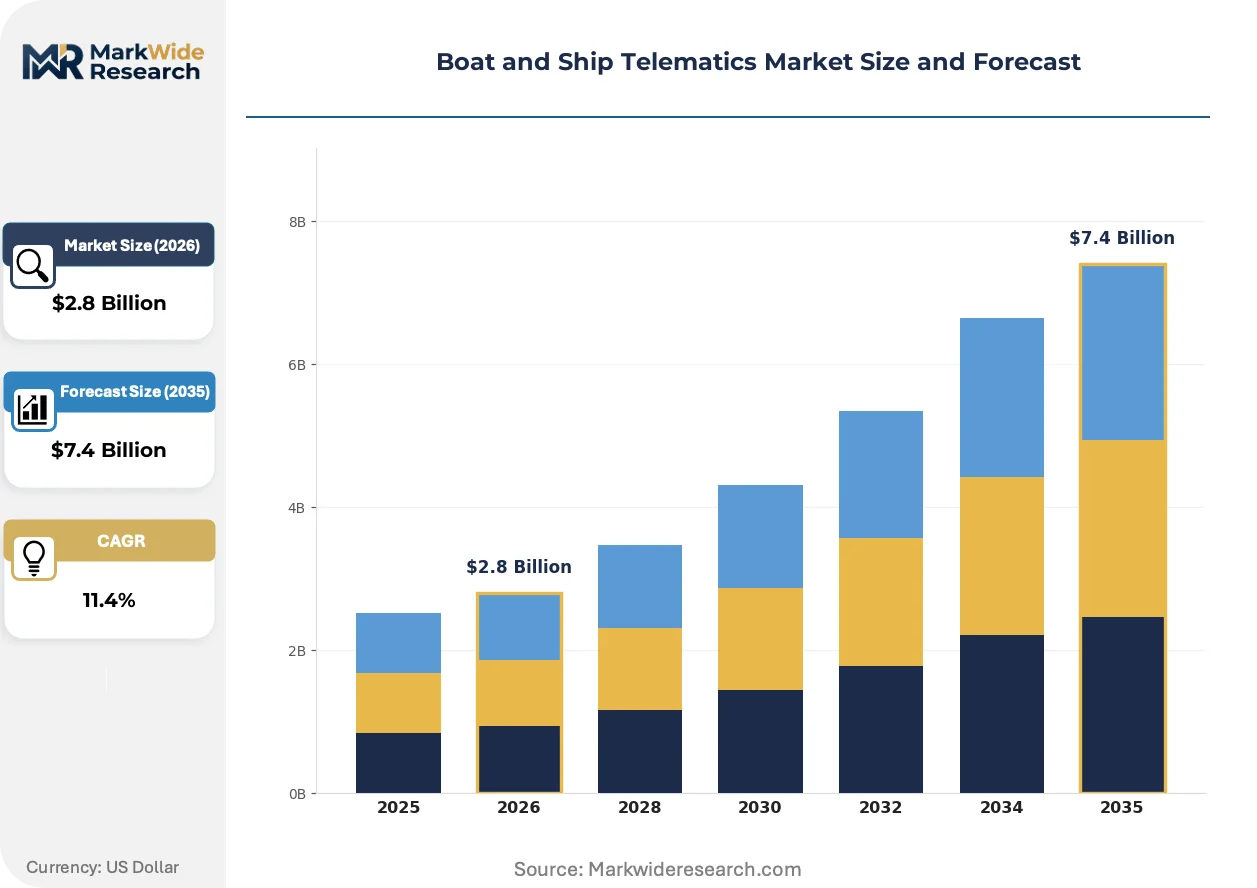
Market Dynamics
Silicon-based sensor arrays are compressing hardware costs while IMO emissions mandates force real-time data transmission infrastructure across commercial fleets, restructuring supplier economics toward subscription analytics.
Growth Catalysts
- IMO Data Collection System:Mandatory emissions reporting compels vessel operators to install continuous monitoring systems, creating baseline demand for satellite-linked telemetry hardware.
- Fuel optimization algorithms:Commercial shipping fleets deploy predictive routing analytics to reduce bunker consumption, driving recurring revenue in fleet management software.
- Norway's maritime technology corridor:Dense clustering of system integrators and offshore automation specialists accelerates R&D spillover into integrated bridge-to-shore platforms.
Market Restraints
- L-band spectrum scarcity:Satellite capacity constraints limit real-time data throughput for deep-ocean vessels beyond cellular coverage, forcing costly VSAT upgrades.
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers creates input volatility for autonomous buoy and drifter deployments.
- Saltwater corrosion failure modes:Submerged sensor housings require titanium or marine-grade stainless steel, elevating hardware replacement cycles versus terrestrial telematics.
Strategic Opportunities
- EU MRV Regulation expansion:Granular CO2 disclosure requirements on European port calls create compliance-driven upgrade cycles for existing AIS infrastructure.
- Autonomous vessel trials:Remote-operated and unmanned surface vehicle programs in Baltic and North Sea corridors demand redundant telemetry stacks.
- Insurer-mandated safety sensors:Collision-avoidance and man-overboard detection systems are becoming policy prerequisites for hull and protection indemnity coverage.
Industry Challenges
- Maritime cybersecurity certification:IEC 62443 compliance timelines for connected bridge systems extend product development cycles by 12-18 months.
- Legacy engine protocol fragmentation:Proprietary J1939, NMEA 2000, and manufacturer-specific CAN bus implementations complicate universal gateway design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat and Ship Telematics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Tracking, Engine Monitoring, Communication Systems, Safety Sensors End User: Commercial Vessels, Recreational Boats, Shipping Companies, Government Agencies Connectivity: Satellite, Cellular, Wi-Fi, Bluetooth Application: Fleet Management, Navigation, Cargo Tracking, Maintenance Monitoring |
| Companies Covered | Kongsberg Digital, ABB Marine & Ports, Wartsila, ORBCOMM, Inmarsat Global Limited, Garmin Ltd., Marlink, Furuno Electric, Navico Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat and Ship Telematics Market Strategic Shifts
Edge computing architectures are migrating analytics from shoreside servers to vessel-mounted gateways, reducing satellite transmission costs while enabling sub-second alerting for critical safety events.
Silicon MEMS pressure and temperature sensors are consolidating multiple legacy electromechanical gauges into single-chip arrays. Deep-sea fishing fleets and offshore supply vessels are retrofitting engine rooms with these compact modules. Component count reduction is consolidating supplier tiers and compressing hardware margin pools toward semiconductor foundries.
EU MRV Regulation amendments are tightening verification requirements for reported CO2 data. Third-party accredited service providers must now certify monitoring equipment installation and calibration. Container lines and bulk carriers operating Rotterdam, Hamburg, and Antwerp routes are prioritizing type-approved systems to avoid detention risk.
Charterers are bundling telematics subscriptions into vessel hire agreements rather than treating connectivity as operator-owned infrastructure. Tanker and dry bulk spot markets in Singapore and London are standardizing performance transparency clauses. Greek and Japanese shipowners are responding by pre-installing open-architecture platforms to preserve negotiating flexibility across chartering desks.
Boat and Ship Telematics Market Segmentation
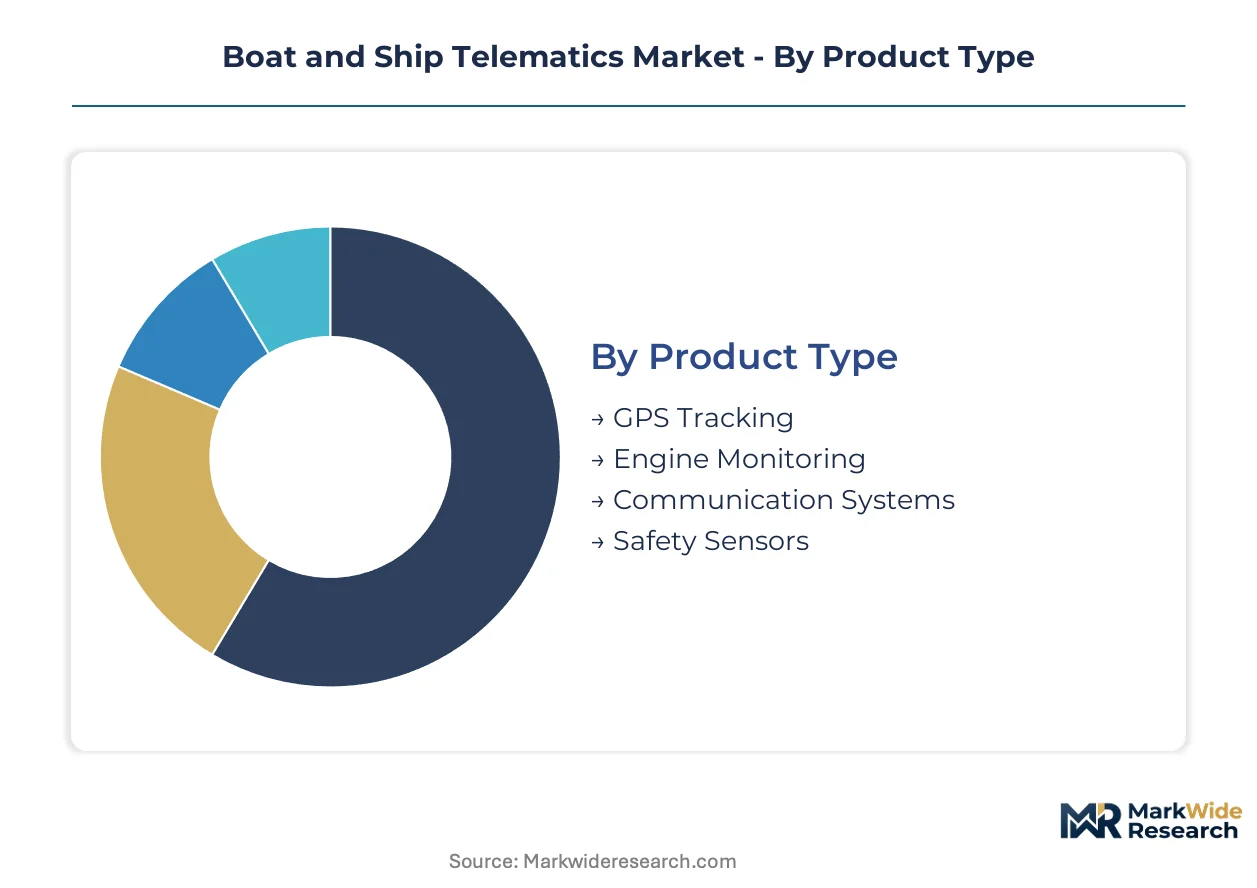
Segmentation in boat and ship telematics reveals distinct hardware replacement cycles and compliance upgrade paths across vessel categories. Understanding these divisions clarifies where subscription revenue concentrates versus one-time equipment sales.
Product Type:
Fleet operators phase hardware upgrades around IMO compliance deadlines and sensor obsolescence curves, creating predictable refresh windows for each equipment category.
- GPS Tracking:Multi-constellation receivers process L1/L2/L5 signals from GPS, Galileo, and GLONASS networks with sub-meter accuracy for dynamic positioning. Container lines operating Singapore-to-Rotterdam routes mandate redundant GNSS cores to prevent signal spoofing incidents in high-traffic chokepoints.
- Engine Monitoring:CAN bus gateways sample J1939 and NMEA 2000 protocols to capture fuel flow, cylinder temperature, and crankcase pressure. Greek bulk carriers retrofitting older tonnage for EU MRV compliance drive concentrated demand for integrated engine-telemetry packages.
- Communication Systems:Dual-mode terminals switch between Iridium L-band and Inmarsat VSAT based on latitude and data urgency.
- Safety Sensors:MEMS-based man-overboard beacons and radar fusion modules for collision avoidance.
Volume placements concentrate in GPS Tracking; the faster expansion belongs to Safety Sensors.
End User:
Customer procurement authority varies sharply between owner-operated fleets and third-party managed vessels, reshaping sales channel economics.
- Commercial Vessels:Deep-sea fishing trawlers and offshore supply ships require continuous connectivity beyond cellular range. Norwegian operators in the North Sea corridor prioritize integrated bridge systems that bundle telemetry with dynamic positioning.
- Recreational Boats:Yacht owners in Mediterranean and Caribbean marinas favor cellular-first architectures with seasonal satellite backup. Premium installations in Monaco and Fort Lauderdale cluster around integrated multifunction displays from marine electronics specialists.
- Shipping Companies:Container lines and tanker operators standardize fleet-wide platforms to enable voyage optimization analytics.
- Government Agencies:Coast guard and naval patrol craft demand encrypted, sovereign-controlled data paths.
Procurement scale peaks with Shipping Companies; Recreational Boats gain share fastest as cellular coverage expands in coastal cruising grounds.
Connectivity:
Link selection determines both transmission cost structure and real-time capability, with satellite retaining monopoly beyond terrestrial range.
- Satellite:Iridium Certus and Inmarsat FleetBroadband provide global coverage through L-band and Ka-band constellations. Deep-ocean bulk carriers on Cape routes depend exclusively on satellite pipes for emissions reporting to flag-state authorities.
- Cellular:LTE-M and NB-IoT modems serve coastal traffic with per-megabyte economics an order of magnitude below satellite. Baltic Sea short-sea shipping operators in Sweden, Finland, and Estonia exploit dense shore-based tower networks for near-shore fleet management.
- Wi-Fi:Harbor and marina hot-spot offload for bulk data sync during port calls.
- Bluetooth:Short-range pairing between wearables and vessel gateways for crew safety alerting.
Revenue tilts toward Satellite; Cellular climbs the fastest as maritime LTE coverage densifies along continental coastlines.
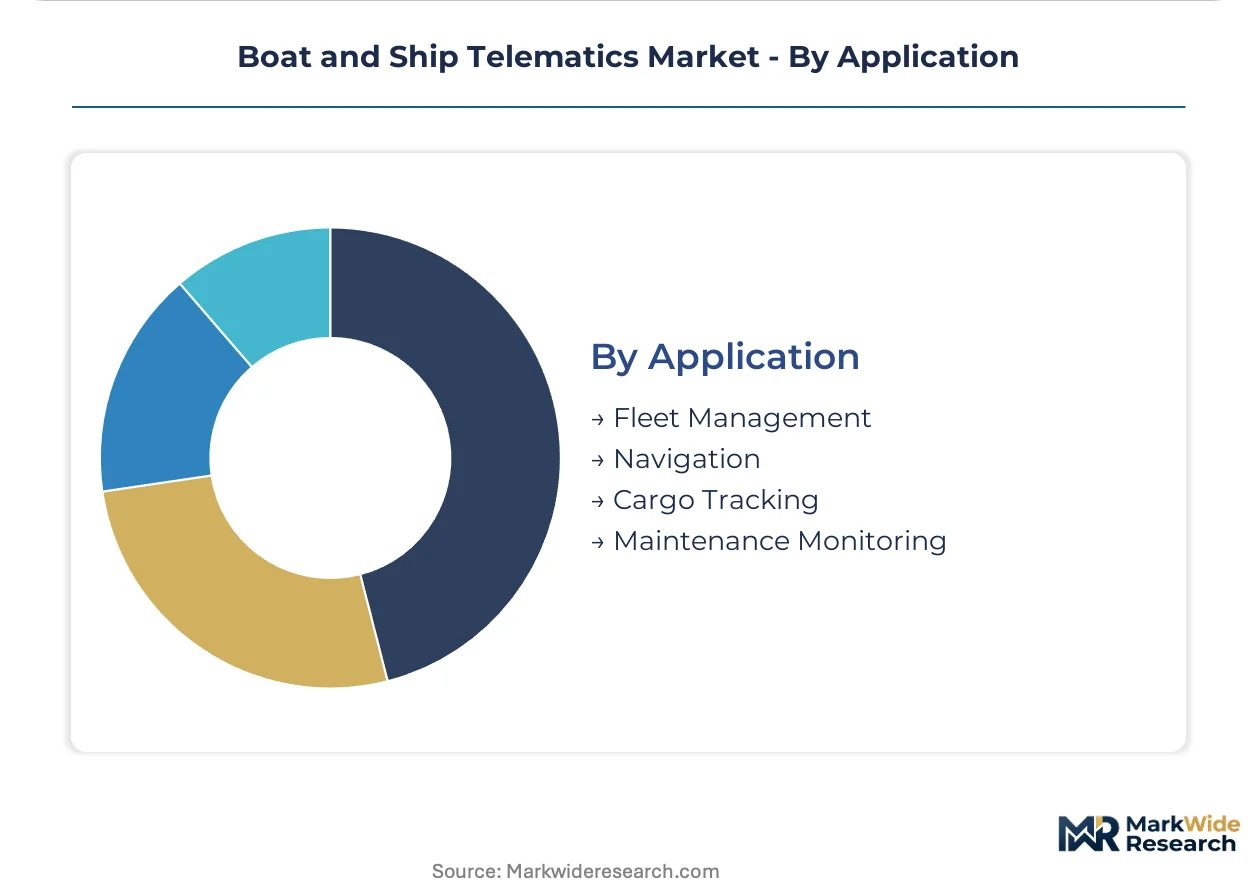
Application:
Software functionality segmentation separates compliance-driven baseline deployments from premium analytics layers that extract operational value.
- Fleet Management:Shoreside dashboards aggregate vessel position, fuel consumption, and maintenance status across owned and chartered tonnage. Japanese shipowners operating mixed fleets of owned and spot-chartered vessels use these platforms to benchmark operator performance against market benchmarks.
- Navigation:Electronic chart display and information systems integrate real-time tidal, weather, and traffic data. German inland waterway operators on the Rhine-Danube corridor deploy enhanced navigation packages to optimize lock transit scheduling.
- Cargo Tracking:Reefer container monitoring with temperature, humidity, and atmosphere control telemetry.
- Maintenance Monitoring:Predictive algorithms flag machinery degradation before failure.
Adoption density centers on Fleet Management; Maintenance Monitoring expands most quickly as machine learning models mature for maritime propulsion systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway concentrates the highest density of vessel telematics demand per capita, driven by offshore automation mandates and North Sea fleet modernization. Commercial shipping operators in Singapore and Hamburg anchor procurement scale for deep-sea installations. Japanese shipowners standardize fleet-wide platforms across mixed owned-chartered tonnage.
Norway
Offshore supply vessel operators and fishing trawlers drive concentrated hardware demand for integrated bridge-to-shore systems. The Norwegian Maritime Authority enforces strict emissions verification protocols aligned with EU MRV implementation. Kongsberg Digital anchors supplier activity from its Kongsberg headquarters, serving North Sea and Barents Sea operators with automation-heritage platforms.
Germany
Rhine-Danube inland waterway operators and Hamburg-based container lines generate dual demand for navigation optimization and fleet management analytics. The Federal Maritime and Hydrographic Agency enforces AIS carriage mandates that create baseline connectivity infrastructure. The Port of Hamburg clusters system integrators serving Baltic and North Sea routes with type-approved emissions monitoring packages.
Japan
Shipowners operating mixed fleets of bulk carriers and tankers prioritize standardized telemetry for voyage optimization benchmarking. METI promotes maritime digitalization through subsidies for IoT-enabled vessel monitoring. Tokyo and Osaka house engineering divisions of major classification societies certifying equipment for IMO Data Collection System compliance.
Singapore
Tanker and dry bulk spot market operators drive demand for open-architecture platforms that preserve chartering flexibility. The Maritime and Port Authority mandates electronic data interchange for port clearance, accelerating shoreside integration investments. The Tuas maritime hub clusters technology providers serving Southeast Asian and Indian Ocean routes.
United States
Coastal towing operators and Great Lakes freighters deploy cellular-first architectures with seasonal satellite backup for route efficiency. The US Coast Guard mandates automatic identification system carriage for commercial vessels, creating upsell pathways for enhanced telemetry. Seattle and Houston anchor marine electronics distribution serving Pacific and Gulf Coast fleets.
Boat and Ship Telematics Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend from hardware into subscription analytics. The vendor base separates into three tiers: integrated bridge system specialists, satellite connectivity pure-plays, and marine electronics generalists. Two archetypes command attention: automation-heritage integrators leveraging offshore oil and gas expertise, and engine-captive diagnostics providers tied to propulsion installed bases. Strategic partnerships between sensor manufacturers and satellite operators accelerate, while M&A concentrates subscription revenue under platform umbrellas.
Within the automation-heritage tier, Kongsberg Digital exemplifies offshore-to-shore platform consolidation, while Wartsila occupies a position as engine-captive diagnostics anchor. ORBCOMM represents the satellite-agnostic connectivity archetype, spanning multiple constellations without proprietary infrastructure lock-in. These three companies illustrate how supplier economics tilt toward recurring analytics revenue rather than commoditized hardware margins.
| Leading Market Players |
|---|
| Kongsberg Digital |
| ABB Marine & Ports |
| Wartsila |
| ORBCOMM |
| Inmarsat Global Limited |
| Garmin Ltd. |
| Marlink |
| Furuno Electric |
| Navico Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between IMO type-approved systems and uncertified hardware creates divergent margin pools that reshape both procurement premiums and supplier tiering across Norwegian, German, and Japanese manufacturing corridors. This divergence concentrates pricing power with accredited integrators while compressing commodity sensor margins toward semiconductor foundries in East Asia.
Pricing Analysis
Volume placements concentrate in standardized GPS tracking hardware with thin margins, while subscription analytics for fleet management software capture expanded recurring revenue. Price differentiation hinges on IEC 62443 cybersecurity certification tier and after-sales service bundling with shoreside support desks. Pricing pressure stems from silicon MEMS sensor commoditization displacing legacy electromechanical gauges. Charterers and spot-market operators exhibit highest price sensitivity, whereas offshore supply vessel operators in Norway's North Sea corridor demonstrate lowest sensitivity due to automation-heritage platform lock-in.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from container lines and tanker operators, while marine electronics distributors serve fragmented recreational boat owners through marina retail networks. Hardware assembly concentrates in South Korea, Japan, and Taiwan, with lithium battery cells sourcing predominantly from Chinese and South Korean manufacturers. Raw material dependencies include titanium for submerged sensor housings, marine-grade stainless steel for corrosion resistance, and rare earth elements for satellite communication magnetics. Single-source vulnerability in L-band satellite transceiver modules creates supply chain risk. Distribution runs through authorized system integrators for commercial fleets and e-commerce platforms for recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boat and ship telematics sector sits at a technology-transition inflection where edge-computing vessel gateways displace shoreside server architectures, restructuring supplier economics toward localized analytics and reduced satellite transmission costs.
For Market Incumbents: To counter silicon MEMS commoditization eroding hardware margins, Kongsberg Digital and Wartsila should deepen captive engine diagnostics integration and secure IEC 62443 certification ahead of compliance deadlines. Vertical integration into satellite-agnostic connectivity modules preserves negotiating leverage against Iridium and Inmarsat pricing power. Capacity addition in Singapore's Tuas maritime hub captures charterer demand for open-architecture platforms. For New Entrants and Emerging Players: Cellular-first architectures exploiting LTE-M densification along Baltic Sea coastlines offer the most penetrable wedge for coastal short-sea shipping operators in Sweden, Finland, and Estonia. Autonomous vessel trial programs in the North Sea corridor present white-space demand for redundant telemetry stacks. A go-to-market angle bundling predictive maintenance algorithms with hardware subscriptions bypasses incumbent software lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with automation-heritage integrators possessing offshore oil and gas expertise given IMO emissions mandate expansion across commercial fleets. Long-term viability over a multi-year window favors suppliers with captive propulsion diagnostics and bridge-to-shore platform consolidation. The signal to watch is charterer adoption of performance transparency clauses standardizing telematics subscription bundling in vessel hire agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bridge-to-shore unification reduces satellite transmission costs for North Sea operators. |
| Strategic Partnership | Sensor manufacturer alliances with satellite operators accelerate certified hardware deployment. |
| Acquisition of Specialist Firm | Cybersecurity certification boutiques compress IEC 62443 compliance timelines by 12-18 months. |
| Geographic Expansion | Singapore hub establishment captures charterer demand for open-architecture flexibility. |
| Product Launch | Edge-computing vessel gateways enable sub-second safety alerting without shoreside latency. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this boat and ship telematics analysis, combined with primary interviews spanning fleet operations directors at container lines, marine electronics procurement managers, offshore supply vessel technical superintendents, and classification society surveyors. Secondary validation drew from IMO Data Collection System submissions, EU MRV Regulation compliance databases, Inmarsat and Iridium service provider disclosures, and Norwegian Maritime Authority enforcement records. Bottom-up equipment shipment tallies and top-down fleet penetration estimates were triangulated against subscription revenue disclosures.
Granularity-level modeling tracked vessel category splits across commercial shipping, recreational boats, offshore supply, and government patrol craft, with connectivity mode segmentation for satellite, cellular, Wi-Fi, and Bluetooth architectures. Product type dimensions covered GPS tracking, engine monitoring, communication systems, and safety sensors. Application splits captured fleet management, navigation, cargo tracking, and maintenance monitoring. CAGRs were derived from installed base growth curves and replacement cycle timing, with cross-referencing against bunker fuel price volatility and emissions compliance deadline clustering.
Forecast precision tightens around the base case; tail outcomes carry wider variance under L-band spectrum auction disruptions or lithium battery supply chain shocks. Periodic stress-testing of base assumptions is recommended given maritime cybersecurity certification timeline extensions and legacy engine protocol fragmentation complicating universal gateway design.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Global Car Sharing Telematics Market