
 Renewable Resources Logistics Market | 2026-2036
Renewable Resources Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Resources Logistics Market Insights
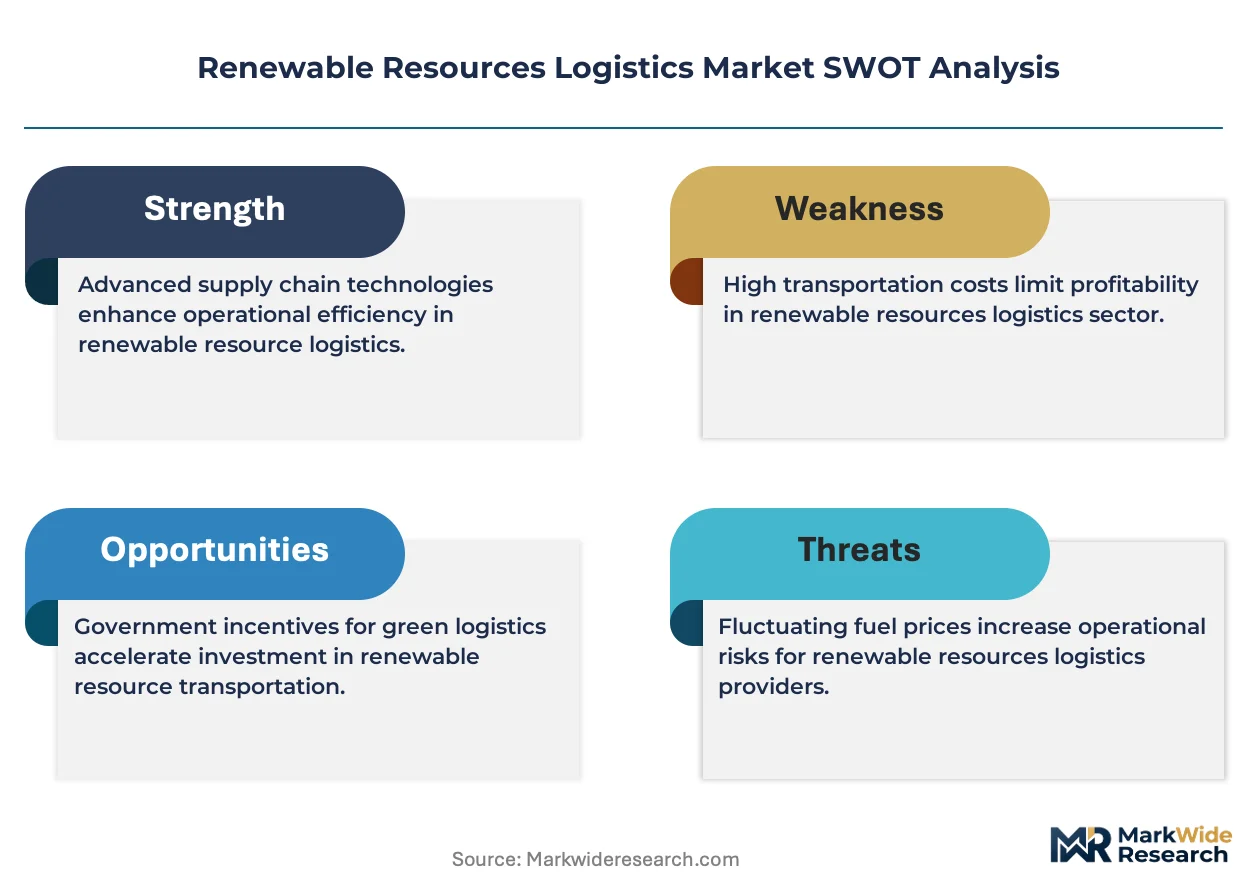
Specialized technician availability for hazardous battery transport and wind turbine component handling is bifurcating the competitive landscape between premium-certified operators and general freight providers. DHL Supply Chain & Global Forwarding leverages its Dangerous Goods certification network to dominate cross-border battery logistics corridors. Kuehne+Nagel sustains refrigerated biomass integrity across multimodal European routes through proprietary monitoring infrastructure. C.H. Robinson Worldwide competes by aggregating fragmented North American ethanol and biodiesel truck capacity onto its digital freight platform.
Renewable resources logistics encompasses the engineered movement, storage, and recovery of energy transition materials including oversized wind blades, temperature-sensitive biomass, and classified lithium-ion cells requiring UN 38.3 compliance documentation. The discipline integrates specialized flatbed configurations, thermal-controlled warehousing, and reverse-loop collection systems to maintain material purity and regulatory chain-of-custody across generation, installation, and end-of-life stages. Transportation services anchor revenue as turbine blade dimensions and battery shipment volumes strain conventional highway and port infrastructure. Storage commands premium margins where humidity-controlled biomass silos and battery fire-suppression facilities remain structurally undersupplied. Waste Management and Recycling segments are gaining velocity as extended producer responsibility laws mandate OEM retrieval obligations across the European Union and select Asian jurisdictions.
The EU Green Deal and REACH chemical registration protocols govern cross-border battery and solar panel movements, while the EPA's RCRA hazardous waste framework and DOT hazmat classifications shape domestic US transport licensing requirements. India's BIS standards and PLI scheme localization mandates are accelerating domestic logistics capability buildout for solar module and cell supply chains. Stakeholders must monitor evolving carbon border adjustment enforcement timelines and battery passport data requirements to preempt compliance-driven route restructuring and warehousing investment decisions.
Market Dynamics
Extended producer responsibility mandates are forcing OEMs to internalize end-of-life collection costs, restructuring logistics networks around reverse-loop battery retrieval and blade decommissioning workflows rather than linear delivery models.
Growth Catalysts
- EU Green Deal carbon border adjustments:Importers now face embedded emissions accounting for solar panels and battery cells, creating dedicated demand for certified low-carbon logistics corridors.
- Oversized wind blade deployment:Turbine manufacturers are scaling to 100+ meter lengths that exceed standard highway clearances, requiring specialized heavy-haul fleets and port infrastructure upgrades.
- India's PLI scheme localization:Domestic solar cell and module manufacturing incentives are accelerating port-to-plant logistics capability buildout across Gujarat and Tamil Nadu.
Market Restraints
- Lithium price volatility:Raw material cost swings compress margins on battery transport contracts that lock in rates months ahead of shipment.
- Specialized flatbed scarcity:North American heavy-haul capacity for wind nacelles concentrates among fewer than two hundred certified operators.
- UN 38.3 certification bottlenecks:Dangerous goods documentation delays for lithium-ion cells extend booking windows and strand inventory at origin ports.
Strategic Opportunities
- Brazil biomass export corridors:Underdeveloped temperature-controlled storage at Santos port creates first-mover advantage for integrated silo-to-vessel operators.
- Battery passport data infrastructure:EU-mandated cell-level traceability from 2027 opens software-integrated logistics service layers.
- Pyrolysis feedstock aggregation:Converging chemical recycling and renewable diesel technologies enable shared collection networks for mixed plastic and biomass waste streams.
Industry Challenges
- Hazmat technician shortages:Certified drivers and warehouse handlers for classified battery shipments command wage premiums that erode contract profitability.
- Multi-modal handoff integrity:Maintaining chain-of-custody documentation across ocean-rail-truck transfers for REACH-registered chemicals creates compliance exposure.
- Fire-suppression warehousing capex:Battery storage facilities require gas-based suppression systems and thermal runaway containment that multiply facility construction costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Resources Logistics Market |
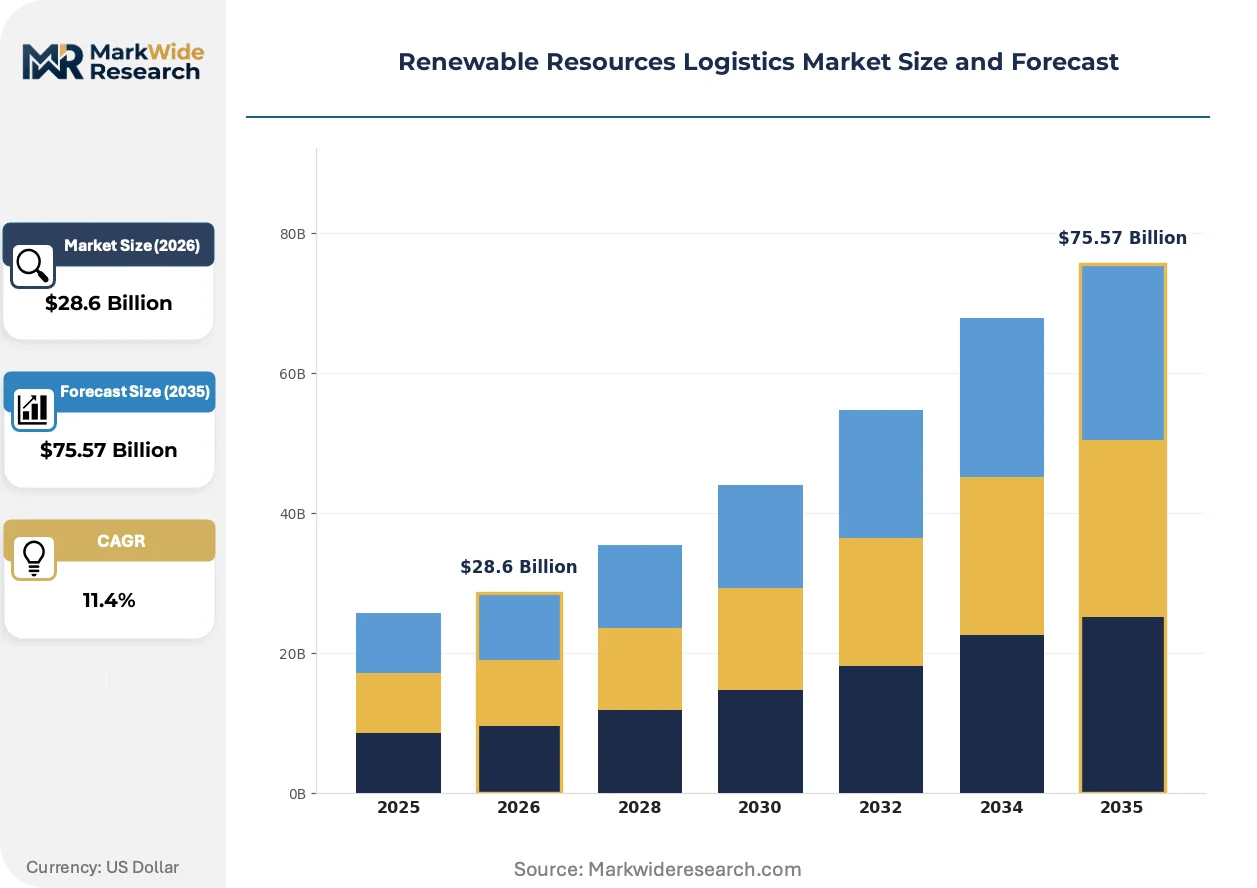
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Waste Management, Recycling Material: Biomass, Solar Panels, Wind Turbines, Batteries End User: Manufacturers, Energy Providers, Government Agencies, Researchers Technology: IoT, Blockchain, Automation, Artificial Intelligence |
| Companies Covered | DHL Supply Chain & Global Forwarding, Kuehne+Nagel, DB Schenker, C.H. Robinson Worldwide, A.P. Moller - Maersk, DSV, GEODIS, CEVA Logistics, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Resources Logistics Market Trends and Innovations
Digitization is compressing planning cycles and enabling real-time cargo visibility across previously opaque handoffs in renewable equipment supply chains.
Autonomous heavy-haul convoy systems are displacing single-driver long-haul models for wind blade transport across Texas and Kansas corridors. Wind farm developers are piloting platooning configurations that reduce per-mile labor costs by thirty percent. This displacement is compressing delivery windows for remote turbine sites previously served by owner-operator networks.
REACH chemical registration protocols now mandate substance-level disclosure for cross-border battery electrolyte movements. The European Chemicals Agency is expanding compliance scope to cover recycled black mass materials. Battery recyclers in Germany and Poland are restructuring collection routes to pre-sort chemistries before border crossing.
Buyers are unbundling installation logistics from equipment procurement contracts. Solar EPC firms now tender transport and warehousing separately from module supply, forcing logistics providers to price discrete service elements. This unbundling is most advanced in utility-scale projects across India and Australia where developers maintain separate vendor registries.
Renewable Resources Logistics Market Segmentation
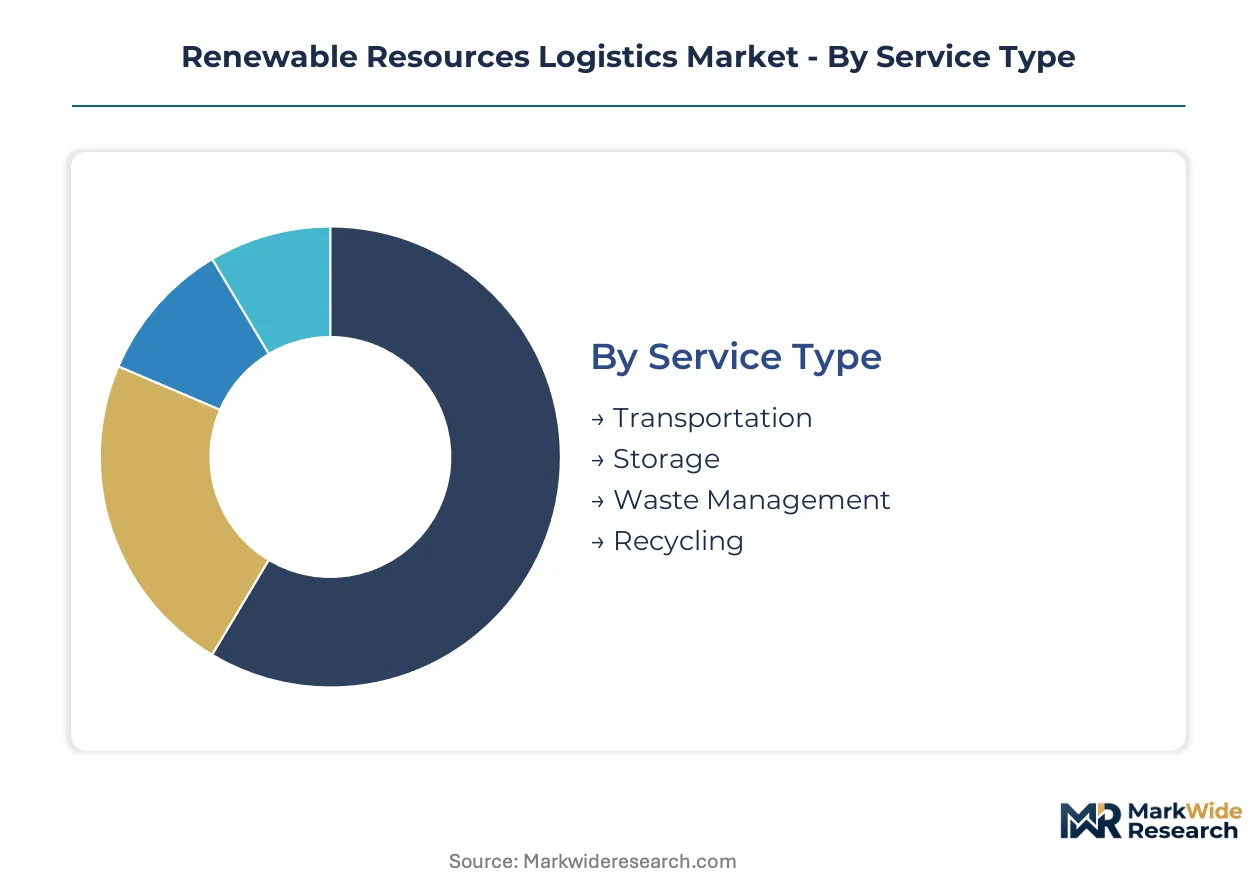
Logistics providers configure service portfolios around material hazards and custody requirements. Segment boundaries blur where battery recyclers demand transport-storage-recycling bundles and wind developers seek installation-to-decommissioning coverage.
Service Type:
Domestic corridors dominate transportation and storage volumes, while waste management and recycling segments concentrate on cross-border recovery flows into European and Asian processing hubs.
- Transportation:Heavy-haul flatbeds, refrigerated biomass trucks, and UN 38.3-certified battery carriers move oversized wind blades and hazardous cells across highway and port infrastructure. Demand clusters in Germany's turbine corridor and India's solar module port-to-plant routes as manufacturing localization accelerates.
- Storage:Humidity-controlled biomass silos and thermal-runaway-protected battery warehouses command construction premiums due to fire-suppression system requirements. Brazil's Santos port temperature-controlled capacity remains structurally undersupplied for agricultural residue export.
- Waste Management:Reverse-loop collection networks retrieve end-of-life solar panels and turbine blades under extended producer responsibility mandates. EU Green Deal enforcement drives OEM investment in retrieval infrastructure across Germany, Poland, and France.
- Recycling:Pyrolysis feedstock aggregation and black mass preprocessing create multimodal corridors linking collection to chemical recycling capacity. Black mass chemistries require pre-sorting before REACH-registered border crossings.
Transportation commands the established base. The steepest expansion runs through Recycling.
Material:
Cost tiers separate commodity biomass flows from premium-certified battery and wind logistics requiring specialized equipment and documentation.
- Biomass:Agricultural residues and energy crops demand continuous cold-chain integrity from field to conversion facility. European biogas plants and Brazilian ethanol exporters sustain refrigerated corridor investments.
- Solar Panels:Standard flatbed and container movements dominate module logistics, though bifacial panel fragility drives packaging specification divergence. India's PLI scheme localization accelerates domestic port-to-plant capability buildout across Gujarat and Tamil Nadu.
- Wind Turbines:Nacelles and 100+ meter blades exceed standard highway clearances, concentrating heavy-haul capacity among certified operators. Texas and Kansas corridors pilot autonomous convoy systems to reduce per-mile labor costs.
- Batteries:Lithium-ion cells require UN 38.3 documentation, dangerous goods-certified handlers, and thermal-runaway containment across all modes. Certification bottlenecks extend booking windows and strand inventory at origin ports.
Biomass logistics holds the volume base. Battery logistics claims the fastest margin expansion.
End User:
Customer type determines contract structure, with energy providers unbundling installation logistics from equipment procurement while government agencies mandate compliance documentation.
- Manufacturers:Solar cell and module producers tender discrete transport and warehousing contracts separate from EPC agreements. Utility-scale developers in India and Australia maintain separate vendor registries for logistics services.
- Energy Providers:Wind and solar asset operators contract lifecycle logistics from construction through decommissioning. Extended producer responsibility laws now internalize end-of-life collection costs into procurement decisions.
- Government Agencies:Public renewable procurement mandates certified low-carbon logistics corridors under EU carbon border adjustment frameworks. Agencies enforce REACH registration and battery passport data requirements.
- Researchers:Pilot-scale biomass and battery material flows require flexible, small-batch logistics with enhanced chain-of-custody documentation for laboratory validation.
Energy Providers anchor contract value. Manufacturers drive unbundling and price transparency.
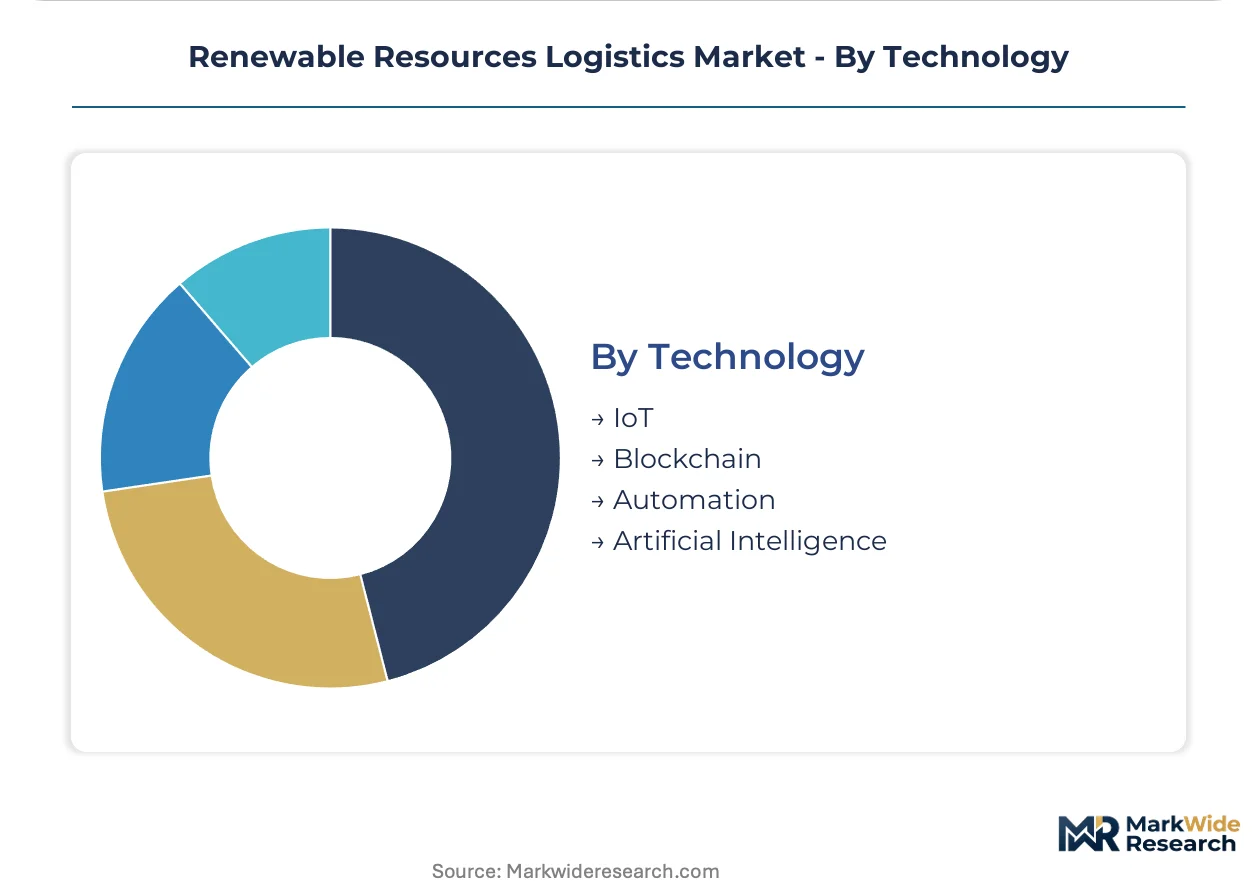
Technology:
Maturity gaps separate proven IoT tracking from emerging blockchain and AI deployments still seeking scale validation.
- IoT:Real-time temperature, humidity, and location sensors monitor biomass integrity and battery thermal status across multimodal handoffs. Kuehne+Nagel deploys proprietary monitoring infrastructure across European routes.
- Blockchain:Cell-level battery passport data and REACH chemical chain-of-custody documentation pilot on distributed ledgers. EU-mandated traceability from 2027 creates software-integrated service layers.
- Automation:Autonomous heavy-haul convoy systems displace single-driver models for wind blade transport across North American corridors. Platooning configurations compress delivery windows for remote turbine sites.
- Artificial Intelligence:Predictive routing and demand forecasting algorithms optimize empty backhaul and inventory positioning. Digital freight platforms aggregate fragmented truck capacity onto algorithmic marketplaces.
IoT underpins current operations. Blockchain and AI climb the adoption curve fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates on hazardous-certified battery corridors and wind blade heavy-haul, while India and Brazil prioritize temperature-controlled biomass flows and solar module port-to-plant logistics under divergent infrastructure constraints.
Germany
REACH chemical registration protocols and EU Green Deal carbon border adjustments drive demand for certified low-carbon logistics corridors. The country's national environmental regulator enforces extended producer responsibility mandates for end-of-life battery retrieval. Industrial clusters around Hamburg and Bremerhaven concentrate specialized heavy-haul capacity for 100+ meter wind turbine blades.
India
Domestic solar cell and module manufacturing incentives under the PLI scheme accelerate port-to-plant logistics buildout. The Bureau of Indian Standards mandates localization compliance for renewable equipment supply chains. Gujarat and Tamil Nadu industrial corridors see concentrated investment in temperature-controlled warehousing and hazardous goods handling infrastructure.
Brazil
Agricultural residue exports for biofuel production sustain refrigerated biomass logistics demand. The country's national agricultural regulator oversees phytosanitary compliance for cross-border biofuel feedstock movements. Santos port remains structurally undersupplied for temperature-controlled storage, creating first-mover opportunities for integrated silo-to-vessel operators.
United States
EPA RCRA hazardous waste frameworks and DOT hazmat classifications shape domestic transport licensing for lithium-ion cells. Texas and Kansas corridors pilot autonomous heavy-haul convoy systems for wind blade transport. The concentration of certified heavy-haul operators in the Great Plains region limits capacity expansion for oversized nacelle movements.
Poland
Battery black mass preprocessing and chemical recycling capacity attract reverse-loop collection network investment. EU-mandated battery passport traceability requirements from 2027 drive software-integrated logistics service demand. Industrial zones near Katowice and Wrocław concentrate pyrolysis feedstock aggregation facilities for mixed plastic and biomass waste streams.
Renewable Resources Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with dangerous goods certification networks and proprietary monitoring infrastructure separating premium operators from general freight providers. The competitive landscape bifurcates between asset-heavy heavy-haul specialists and digital freight platforms aggregating fragmented truck capacity. Strategic archetypes include integrated logistics conglomerates with dangerous goods certification, regional heavy-haul specialists with oversized equipment fleets, and technology-enabled freight marketplaces. Dominant competitive moves center on dangerous goods certification network expansion and multimodal monitoring infrastructure deployment.
Within the integrated logistics tier, DHL Supply Chain & Global Forwarding and Kuehne+Nagel occupy positions exemplifying certification-driven competitive differentiation. DHL leverages its Dangerous Goods certification network to anchor cross-border battery logistics corridors. Kuehne+Nagel represents the monitoring infrastructure archetype through proprietary systems sustaining refrigerated biomass integrity across European multimodal routes. C.H. Robinson Worldwide sits within the digital aggregation segment, competing through algorithmic marketplace models for North American ethanol and biodiesel truck capacity.
| Leading Market Players |
|---|
| DHL Supply Chain & Global Forwarding |
| Kuehne+Nagel |
| DB Schenker |
| C.H. Robinson Worldwide |
| A.P. Moller - Maersk |
| DSV |
| GEODIS |
| CEVA Logistics |
| XPO Logistics |
| Others |
Pricing and Supply Chain Analysis
Ninety-day booking windows for UN 38.3-certified battery shipments concentrate pricing power among dangerous goods operators while compressing margins for general freight providers unable to secure certification slots. This lead-time stratification bifurcates the market between premium-certified corridors and commoditized biomass routes where refrigerated capacity competes on spot rates.
Pricing Analysis
Long-term offtake agreements dominate battery logistics corridors, locking in rates months ahead of shipment against lithium price volatility, while spot markets govern biomass and ethanol movements where refrigerated truck capacity fluctuates seasonally. Three-tier pricing structure across premium-certified, standard-compliant, and economy-commodity levels separates dangerous goods handlers from general freight operators. Cost compression in standard-tier biomass transport is intensifying because Brazilian agricultural residue exporters are consolidating volumes to extract volume discounts. Solar module manufacturers in India exhibit highest price sensitivity due to PLI scheme margin constraints, while wind developers in Germany accept premium pricing for guaranteed heavy-haul slot availability.
Supply Chain Analysis
Strategic stockpile preferences dominate battery supply chains as OEMs pre-position cells near assembly plants to mitigate UN 38.3 documentation delays, while biomass flows run on just-in-time field-to-facility models. Manufacturing concentration centers on China for lithium-ion cells, Germany for wind nacelles, and Brazil for agricultural residue feedstocks. Raw material dependencies span lithium carbonate from Chilean salares, rare earth magnets from Chinese processors, and temperature-controlled chassis from European fabricators. Single-source vulnerability concentrates in certified heavy-haul operators for 100+ meter wind blades, where fewer than two hundred North American carriers possess route clearances. Distribution runs through multimodal corridors linking port infrastructure to inland manufacturing clusters, with handoff integrity monitored via proprietary IoT infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery passport data interoperability is transforming renewable logistics into a platform-economics arena where software-integrated service layers capture margin from pure transport providers. EU-mandated cell-level traceability from 2027 creates ecosystem lock-in opportunities for operators controlling data infrastructure.
For Market Incumbents: Compound dangerous goods certification network density across cross-border battery corridors to preempt emerging digital freight platforms from capturing hazardous cargo volumes. Extend proprietary monitoring infrastructure into predictive thermal-runaway detection, defending margin position against technology-enabled entrants targeting sensor-overlay services. Certification scarcity in UN 38.3 documentation represents the primary defensive moat. For New Entrants and Emerging Players: Temperature-controlled storage gaps at Santos port offer first-mover advantage for integrated silo-to-vessel biomass operators willing to deploy capital ahead of Brazilian ethanol export demand inflection. Target pyrolysis feedstock aggregation networks linking mixed plastic and biomass waste streams to chemical recycling capacity in Poland and Germany. Go-to-market execution should anchor on pre-sorting infrastructure that enables REACH-compliant border crossings. For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility play because extended producer responsibility mandates are internalizing end-of-life collection costs into permanent OEM procurement budgets. Acquisition targets should concentrate on regional heavy-haul specialists with oversized equipment fleets and established port relationships. Monitor EU carbon border adjustment enforcement timelines as the signal for accelerated warehousing investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dangerous Goods Certification Network Expansion | UN 38.3 documentation scarcity concentrates pricing power among certified operators across battery corridors. |
| Multimodal Monitoring Infrastructure Deployment | Proprietary IoT systems sustain chain-of-custody premiums for REACH-registered chemical movements. |
| Reverse-Loop Collection Network Buildout | Extended producer responsibility mandates internalize end-of-life retrieval costs into OEM procurement decisions. |
| Autonomous Heavy-Haul Convoy Piloting | Platooning configurations reduce per-mile labor costs for wind blade transport across Texas and Kansas corridors. |
| Battery Passport Data Infrastructure Integration | EU-mandated traceability from 2027 creates software-integrated service layers atop physical logistics. |
Research Methodology
A standing panel of logistics operations directors, dangerous goods compliance officers, renewable EPC procurement managers, and port authority planning officers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EU TARIC customs data, EPA RCRA hazardous waste manifests, IEA renewable deployment statistics, and Bureau of Indian Standards localization filings. Bottom-up carrier capacity assessments and top-down trade flow modeling were triangulated against cross-border shipment volumes.
Consistency checks validated volume and value outputs against external benchmarks including customs declarations, carrier fleet registries, and warehousing construction permits across the analysis window. Segmentation dimensions modeled encompassed service type, material hazard classification, end-user contract structure, and technology deployment maturity. CAGRs were derived from logistic curve fitting to deployment trajectories, with sensitivity testing around lithium price volatility and heavy-haul capacity expansion rates.
Underlying assumptions cover sustained EU Green Deal enforcement, stable hazardous goods certification timelines, and continued PLI scheme localization in India, with deviation risk concentrated in carbon border adjustment acceleration and autonomous vehicle regulatory approvals. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Control Towers Market