
 Automotive Insulation Market | 2026-2036
Automotive Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Insulation Market Analysis
NVH-grade specification upgrades is rotating demand toward denser, multi-layer acoustic assemblies. Owens Corning leverages its mineral wool expertise to anchor North American OEM supply relationships. BASF SE competes through polyurethane foam chemistry tailored to electric vehicle battery pack enclosures. Covestro AG specializes in polycarbonate-based thermal barriers that differentiate its portfolio from commodity fiberglass alternatives.
Automotive insulation encompasses engineered materials engineered to attenuate sound transmission, block thermal transfer, and dampen mechanical vibration within vehicle cabins and powertrain compartments. These systems typically deploy fiberglass batts with densities of 10-48 kg/m³, closed-cell polyurethane foams, or compressed rubber composites bonded to aluminum foil facing for radiant heat reflection. Thermal barrier segments lead material value capture as battery-electric architectures demand expanded underbody and firewall protection. Acoustic insulation occupies mature margin pools in internal combustion passenger vehicles but faces displacement risk as electric powertrains reduce engine noise signatures. Foam material chemistry is accelerating fastest among material categories, driven by weight-reduction imperatives in electric vehicle platforms.
EPA tailpipe standards and the EU Green Deal's embedded carbon requirements are forcing reformulation of traditional blowing agents and resin systems. NHTSA safety protocols for battery thermal runaway protection are expanding mandatory insulation thickness specifications in electric vehicle architectures. OEMs and Tier-1 suppliers must monitor how REACH chemical restrictions and forthcoming EPA rules on perfluorinated compounds constrain foam material sourcing across their supplier networks.
Market Dynamics
Battery-electric vehicle architectures are compressing traditional acoustic insulation demand while expanding thermal barrier specifications across underbody and firewall applications. OEMs now specify multi-functional materials that simultaneously manage heat flux and NVH in single-layer assemblies.
Growth Catalysts
- EU Green Deal embedded carbon mandates:Vehicle manufacturers must document cradle-to-gate emissions for insulation materials, favoring recycled-content fiberglass and bio-based polyurethane formulations in European assembly plants.
- NHTSA battery thermal runaway protocols:Mandatory insulation thickness specifications for electric vehicle battery enclosures are expanding material volume per vehicle in United States production corridors.
- Closed-cell polyurethane chemistry:Weight-reduction imperatives in electric platforms are accelerating foam density optimization to replace heavier rubber-composite heat shields.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs for polyurethane production fluctuate with crude oil indices, compressing margin stability for foam specialists.
- REACH chemical restrictions:ECHA substance of very high concern listings constrain legacy blowing agent formulations, forcing costly reformulation cycles ahead of sunset dates.
- Commodity fiberglass substitution:Denser mineral wool and aerogel blankets threaten traditional batt insulation in premium thermal management applications.
Strategic Opportunities
- India PLI scheme for electric mobility:Domestic battery assembly incentives are creating localized demand for thermal barrier materials in Chennai and Pune manufacturing clusters.
- Recyclable mono-material designs:Single-polymer insulation assemblies compatible with automotive shredder residue recovery systems address end-of-life regulations in Germany and France.
- Direct OEM contracting:Bypassing Tier-1 supplier intermediaries for battery pack thermal management materials captures margin and specification control.
Industry Challenges
- Multi-physics simulation expertise:Coupled thermal-acoustic finite element modeling skills are scarce among material suppliers attempting to prove performance in OEM virtual validation workflows.
- Homologation timeline compression:Accelerated electric vehicle platform development cycles compress material qualification from 36 months to 18 months, straining testing laboratory capacity.
- Legacy combustion NVH portfolio management:Suppliers must maintain acoustic insulation capacity for internal combustion programs while retooling for thermal-dominant electric vehicle specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Insulation Market |
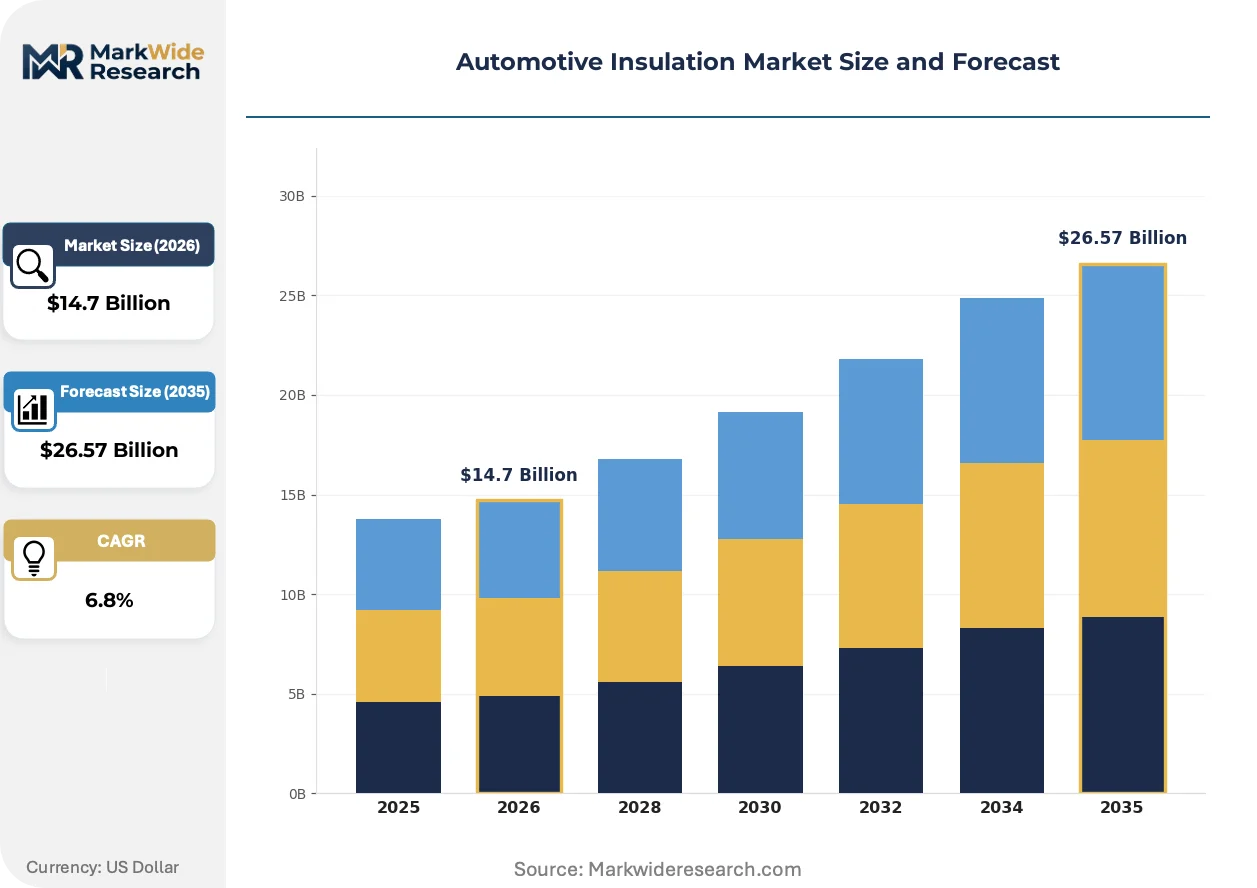
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Insulation, Heat Insulation, Thermal Barriers, Vibration Dampening Material: Fiberglass, Foam, Rubber, Polystyrene Application: Passenger Vehicles, Heavy-Duty Trucks, Electric Vehicles, Motorcycles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships |
| Companies Covered | Owens Corning, Covestro AG, 3M Company, Armacell, Autoneum, BASF SE, Johns Manville, Freudenberg Group, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Insulation Market Emerging Trajectories
Material convergence is collapsing the traditional separation between thermal management and acoustic attenuation functions. Suppliers now engineer single-layer assemblies that satisfy both performance domains while reducing mass and assembly complexity.
Aerogel-infused nonwoven blankets are supplanting multi-layer fiberglass assemblies in battery pack and firewall applications. Premium electric vehicle platforms from German and South Korean OEMs have adopted these materials for their sub-150 kg/m³ density and compression resistance. The technology is compressing part counts from three-layer thermal-acoustic systems to single-component solutions, reducing assembly labor and logistics overhead.
EPA rules on perfluorinated compounds are forcing reformulation of fluorinated blowing agents in closed-cell polyurethane production. Foam producers must validate hydrocarbon and hydrofluoroolefin alternatives without sacrificing dimensional stability or fire performance. United States-based battery enclosure manufacturers are most affected, accelerating qualification timelines for next-generation foam systems ahead of proposed restriction dates.
Buyer concentration among battery-electric vehicle specialists is consolidating procurement decisions at platform-architecture level rather than commodity-sourcing level. Tier-1 acoustic suppliers face disintermediation as cell manufacturers and OEM battery engineering teams specify thermal materials directly. This pattern is most visible in China, where CATL and BYD vertical integration extends to insulation selection for their supplied pack designs.
Automotive Insulation Market Segmentation
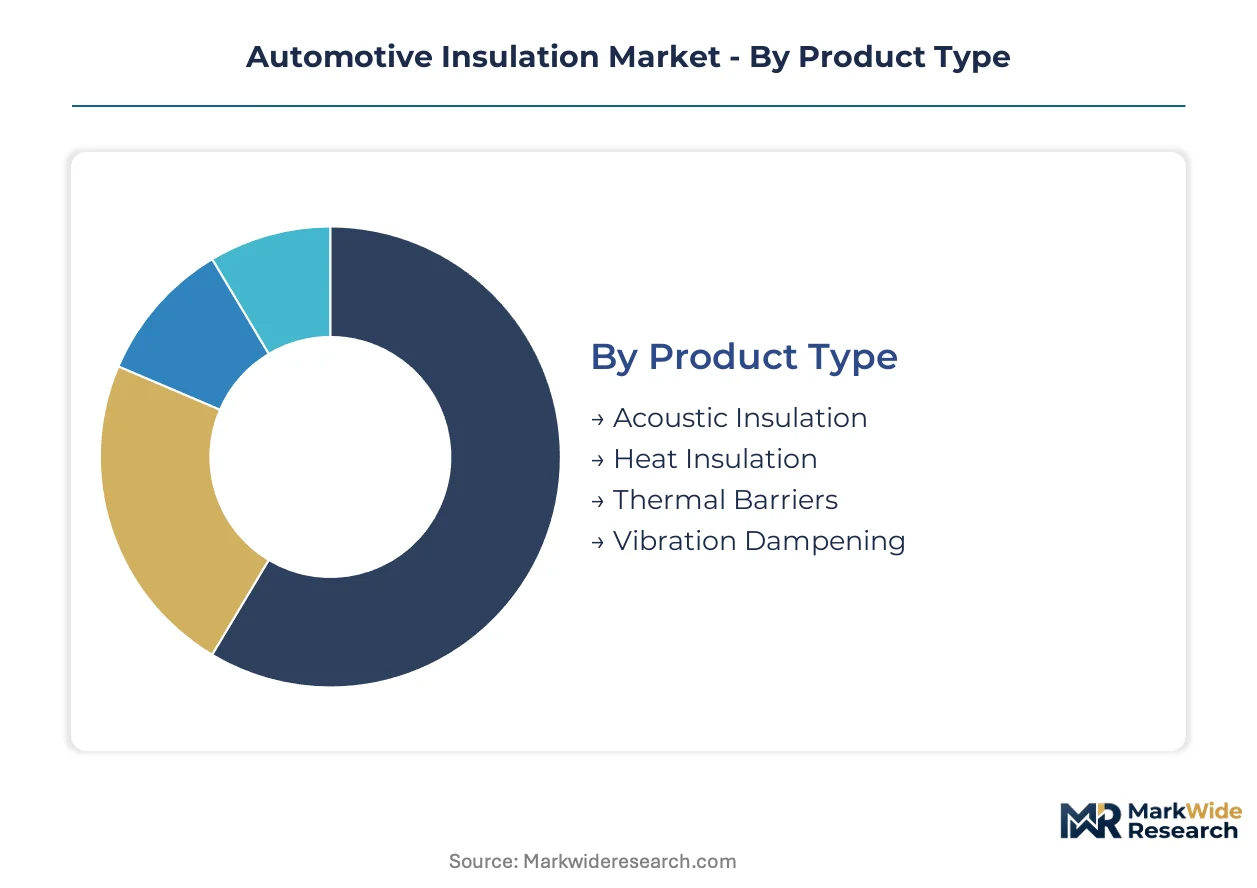
Automotive insulation segmentation reflects divergent supply chain configurations across electric and combustion platforms. Material specifications now bifurcate between thermal-dominant battery architectures and acoustic-heavy internal combustion programs.
Product Type:
Domestic production in Germany, China, and the United States concentrates on thermal barrier systems for local battery assembly, while acoustic insulation exports flow from established European NVH manufacturing bases to global combustion vehicle programs.
- Thermal Barriers:Multi-layer assemblies combining aluminum foil facing with compressed fiber cores manage heat flux in battery enclosures and firewall applications. United States NHTSA protocols mandate expanded thickness specifications, driving volume per vehicle in Detroit and Austin manufacturing corridors.
- Acoustic Insulation:Denser mineral wool and multi-layer nonwoven assemblies attenuate powertrain noise in passenger cabins. German OEMs source these systems domestically for premium internal combustion platforms, though demand faces compression as electric powertrains eliminate engine noise signatures.
- Heat Insulation:Radiant heat shields protect exhaust-adjacent components in heavy-duty trucks.
- Vibration Dampening:Constrained-layer composites isolate cabin structures from road-induced oscillations.
Thermal barriers hold the largest share; momentum sits with acoustic insulation repurposed for electric vehicle wind and tire noise management.
Material:
Cost tiers separate commodity fiberglass from premium foam formulations, with chemistry investments determining margin capture.
- Foam:Closed-cell polyurethane systems with hydrocarbon blowing agents replace rubber-composite heat shields in electric vehicle underbody protection. European REACH restrictions on fluorinated compounds force reformulation cycles at BASF SE and Covestro AG ahead of sunset dates.
- Fiberglass:Recycled-content batts with densities of 10-48 kg/m³ serve mature internal combustion acoustic applications. Owens Corning anchors North American supply relationships through mineral wool expertise, though denser aerogel alternatives threaten premium positioning.
- Rubber:Compressed nitrile and EPDM composites bond to metal substrates for vibration isolation.
- Polystyrene:Expanded bead foam provides low-cost thermal protection in commercial vehicle applications.
Foam materials command premium pricing; fiberglass retains volume leadership in established combustion platforms.
Application:
Customer type determines specification intensity, with battery-electric platforms demanding multi-functional thermal-acoustic assemblies absent from legacy programs.
- Electric Vehicles:Battery pack enclosures and firewalls require expanded insulation thickness per NHTSA thermal runaway protocols. Chinese cell manufacturers CATL and BYD specify materials directly, disintermediating traditional Tier-1 acoustic suppliers.
- Passenger Vehicles:Internal combustion cabins drive mature demand for NVH-grade acoustic systems, primarily sourced through established European and North American supply chains.
- Heavy-Duty Trucks:Diesel powertrains and sleeper cabs combine thermal and acoustic requirements in long-haul configurations.
- Motorcycles:Compact thermal shields protect riders from engine heat in high-displacement models.
Passenger vehicles maintain installed base dominance; electric vehicles are expanding most quickly by specification intensity per vehicle.
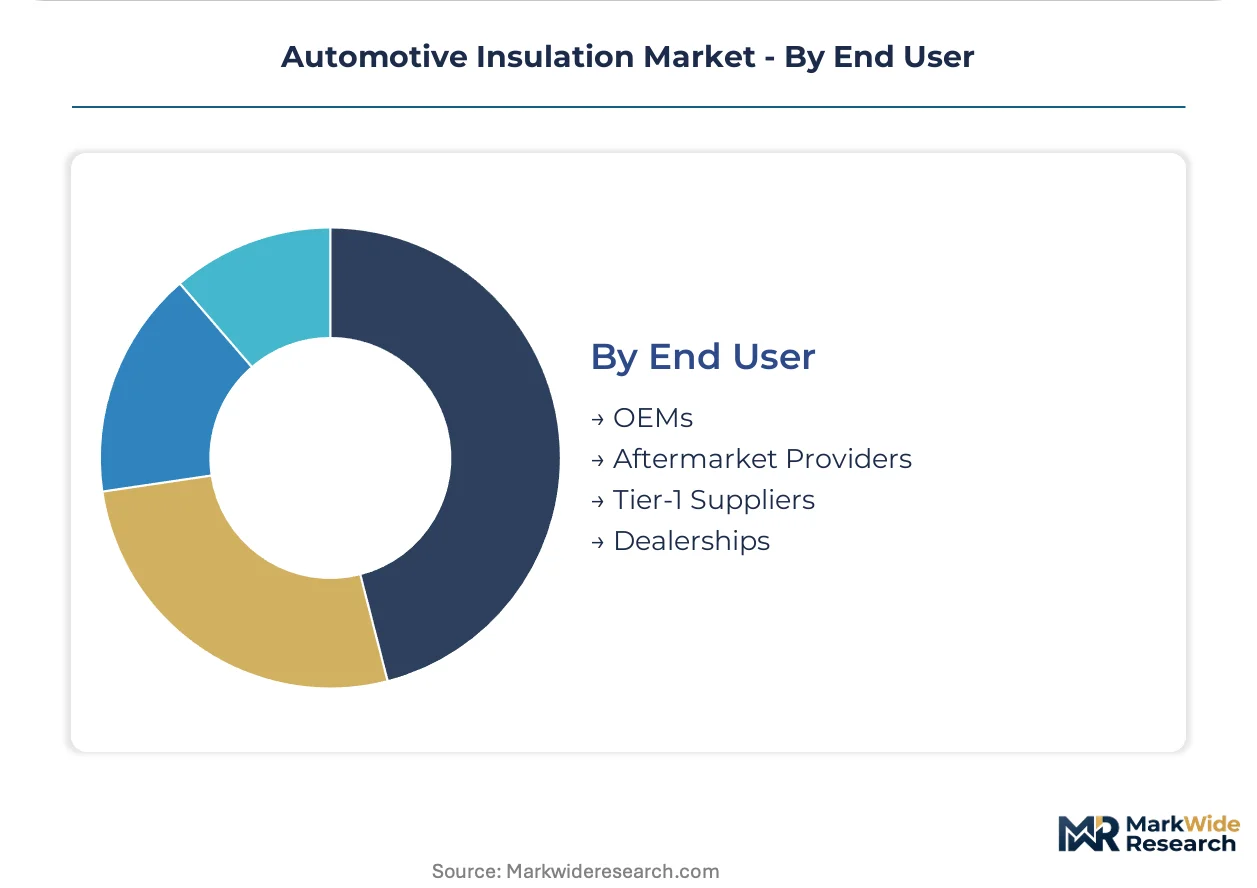
End User:
Procurement concentration varies by platform maturity, with direct OEM contracting gaining ground in battery thermal management.
- OEMs:Platform-architecture teams specify thermal materials directly for battery enclosures, bypassing traditional Tier-1 intermediaries. This pattern concentrates in China and Germany where cell-to-pack integration is deepest.
- Tier-1 Suppliers:Acoustic system integrators manage NVH assembly for internal combustion programs, though their role contracts in electric architectures.
- Aftermarket Providers:Replacement insulation serves vehicle repair and restoration channels.
- Dealerships:Service departments install OEM-approved thermal and acoustic upgrades.
OEMs capture specification control in emerging electric platforms; Tier-1 suppliers defend position in legacy combustion volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German insulation exports flow to battery assembly plants in China and the United States, establishing a transatlantic supply corridor for thermal barrier materials. Chinese domestic production now captures the majority of local electric vehicle demand. United States manufacturing corridors expand capacity to serve Detroit and Austin battery pack assembly.
United States
Detroit and Austin manufacturing corridors drive thermal barrier demand for battery pack enclosures. NHTSA battery thermal runaway protocols mandate expanded insulation thickness specifications. Austin-based Tesla Gigafactory and Detroit-area Ford Rouge Electric Vehicle Center anchor domestic material consumption.
Germany
Premium electric vehicle platforms from BMW and Mercedes-Benz specify advanced thermal-acoustic assemblies. EU Green Deal embedded carbon mandates favor recycled-content fiberglass and bio-based polyurethane formulations. Stuttgart and Munich engineering centers direct material specifications across European assembly networks.
China
CATL and BYD vertical integration extends to direct insulation selection for supplied pack designs. MIIT dual carbon goals accelerate adoption of low-emission material formulations. Ningde and Shenzhen battery manufacturing clusters concentrate domestic thermal barrier demand.
South Korea
LG Energy Solution and Samsung SDI battery exports drive thermal material specifications for global OEM customers. KBA homologation requirements align with EU thermal protection standards. Ulsan and Gwangju production corridors serve Hyundai-Kia electric platform assembly.
India
Domestic battery assembly incentives under the PLI scheme create localized thermal barrier demand. BIS standards for electric vehicle safety expand material testing requirements. Chennai and Pune manufacturing clusters attract insulation suppliers for emerging cell-to-pack production.
Automotive Insulation Market Vendor Landscape
Listed leaders compete with private specialists across material chemistry and geographic coverage. The supplier base organizes into three tiers: integrated chemical conglomerates with foam expertise, dedicated automotive acoustic specialists, and regional mineral wool fabricators. Two dominant competitive moves shape positioning: direct OEM contracting for battery thermal management and recyclable mono-material designs addressing end-of-life regulations.
Within the chemical conglomerate tier, BASF SE and Covestro AG exemplify polyurethane chemistry leadership for electric vehicle battery enclosures. Owens Corning anchors North American supply relationships through mineral wool expertise. These three entities represent distinct strategic archetypes: European chemical integration, North American fiber specialization, and cross-material platform coverage.
| Leading Market Players |
|---|
| Owens Corning |
| Covestro AG |
| 3M Company |
| Armacell |
| Autoneum |
| BASF SE |
| Johns Manville |
| Freudenberg Group |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese foam chemical plants shapes global price floors for polyurethane insulation systems, compressing margin structures for European and North American producers while elevating bargaining power for OEMs with battery platform scale.
Pricing Analysis
Next-generation aerogel-infused assemblies command substantial premiums over incumbent fiberglass batts and first-generation polyurethane foams. Pricing stratifies across premium, standard, and economy tiers based on thermal performance certification grade and volume commitment scale. Cost compression in commodity fiberglass is intensifying because Chinese mineral wool capacity expansion feeds global spot markets. Aftermarket providers exhibit highest price sensitivity, while German premium OEMs prioritize performance specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of polyol and isocyanate precursors dominates procurement behavior among major foam producers, insulating against petrochemical feedstock volatility. Manufacturing concentrates in Germany, China, and the United States, with each corridor serving regional battery assembly demand. Raw material flows draw from Saudi Arabian petrochemical complexes, Belgian polyol specialists, and domestic isocyanate plants. Single-source vulnerability sits with fluorinated blowing agent suppliers facing REACH sunset dates. Distribution runs through Tier-1 acoustic system integrators for combustion platforms and direct OEM contracting channels for electric vehicle thermal management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation between thermal-dominant electric architectures and acoustic-heavy combustion programs creates specialized supply niches, rewarding focused material chemistry investments over commodity scale plays.
For Market Incumbents: Shield legacy NVH revenue streams by maintaining acoustic insulation capacity for internal combustion programs while accelerating thermal barrier qualification for battery platforms. Aerogel substitution threats in premium segments demand R&D investment in compression-resistant fiber formulations. Backward integration into recycled-content fiberglass feedstock secures EU Green Deal compliance margin. For New Entrants and Emerging Players: Differentiate on mono-material recyclability compatible with automotive shredder residue recovery systems, targeting German and French end-of-life regulatory requirements. The India PLI scheme for electric mobility represents the most penetrable geography, with Chennai and Pune manufacturing clusters lacking established thermal barrier supply bases. Direct OEM contracting for battery pack specifications bypasses entrenched Tier-1 supplier relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foam chemistry specialists with long-term supply agreements to cell manufacturers and platform-architecture teams. Five-to-ten year viability hinges on successful fluorinated blowing agent reformulation ahead of regulatory sunset dates. Acquisition targets should demonstrate multi-physics simulation capabilities for coupled thermal-acoustic validation. The signal to watch is NHTSA expansion of mandatory insulation thickness specifications beyond current battery enclosure protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Direct thermal material contracting with CATL or BYD secures volume anchors for foam chemistry investments. |
| Green Manufacturing Transition | Bio-based polyurethane formulations satisfy EU Green Deal embedded carbon mandates for European assembly plants. |
| Backward Integration | Captive production of recycled fiberglass feedstock insulates against mineral wool substitution in acoustic applications. |
| Long-term Supply Agreement | Multi-year polyol offtake contracts with Saudi petrochemical producers stabilize input cost volatility. |
| Joint Venture | Localized production partnerships in India PLI corridors capture emerging battery assembly demand without full greenfield exposure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including OEM platform engineers, Tier-1 supplier procurement leads, foam chemistry R&D directors, and aftermarket distribution channel managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA and NHTSA regulatory filings, and ECHA REACH substance listings. Bottom-up segmentation modeling triangulated against top-down market sizing from chemical producer capacity disclosures and customs trade flows.
Across the analysis window, forecasts integrated vehicle production projections by propulsion architecture, content-per-vehicle assumptions for thermal and acoustic specifications, and regional regulatory adoption curves. Segmentation dimensions modeled include material chemistry, application type, end-user procurement channel, and regional production cluster. CAGRs derived from logistic diffusion curves fitted to electric vehicle platform penetration rates and NHTSA thermal protection protocol expansion timelines.
Material uncertainties — petrochemical price volatility, REACH chemical restriction acceleration, and aerogel manufacturing scale-up — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and OEM platform launch schedules. Revision becomes warranted when battery thermal runaway protection mandates cross thresholds beyond current NHTSA specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Door Panel Market