
 Automotive Crankshaft Materials Market | 2026-2036
Automotive Crankshaft Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crankshaft Materials Market Analytics
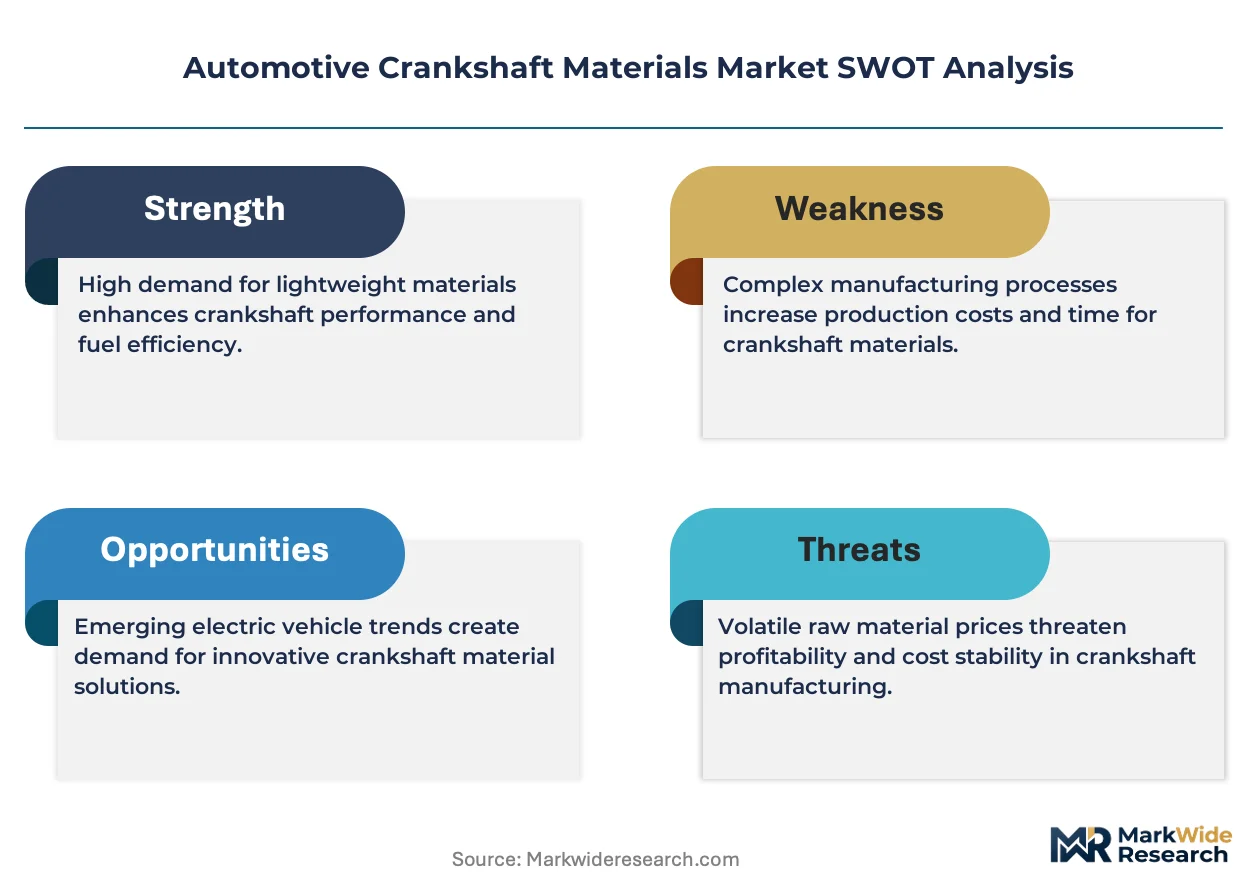
Light commercial vehicle demand is shifting toward higher-displacement diesel and hybrid powertrains that impose greater torsional loads on crankshaft assemblies. Thyssenkrupp AG leverages captive steelmaking and forging capacity to supply integrated crankshaft-steel solutions for European OEMs. Bharat Forge Limited anchors high-volume forged crankshaft exports from India to global commercial vehicle programs. Nippon Steel Integrated Crankshaft LLC competes on metallurgical consistency for Japanese and North American passenger car engines.
Automotive crankshaft materials are ferrous and non-ferrous alloys engineered to withstand cyclic bending and torsional stresses at rotational speeds exceeding 6,000 RPM, with forged steel grades typically achieving tensile strengths above 800 MPa through controlled austenitizing and quenching protocols. Cast iron dominates unit volume in entry-level passenger car engines where cost sensitivity outweighs mass reduction targets. Forged steel leads margin pools in heavy-duty and performance applications where fatigue life determines warranty exposure. Aluminum alloy occupies a narrow but expanding niche in hybrid engine architectures where reciprocating mass reduction directly improves stop-start efficiency and NVH performance.
EPA tailpipe standards and Euro 7 proposals from the European Commission are forcing crankshaft suppliers to certify materials for extended service intervals under higher mean effective pressures. NHTSA fuel economy regulations in the United States and China's MIIT dual carbon goals are converging on lighter crankshaft solutions without compromising bearing surface durability. Stakeholders must monitor how additive manufacturing process qualifications from ISO and national standards bodies redefine acceptable defect thresholds in high-stress fillet regions.
Market Dynamics
EPA Tier 4 and Euro 7 emissions standards are forcing crankshaft suppliers to redesign fatigue-resistant microstructures for higher combustion pressures. OEMs now specify forged steel grades with verified endurance limits above 800 MPa, compressing supplier qualification timelines.
Growth Catalysts
- Light commercial vehicle powertrain upsizing:Fleet operators in North America and Europe are specifying larger-displacement diesel and hybrid engines that impose torsional loads exceeding cast iron capacity. Forged steel crankshaft demand concentrates in platforms above 2.5L displacement.
- Euro 7 emissions architecture:The European Commission's proposed particulate and NOx limits require extended service intervals, pushing OEMs toward nitrided forged steel fillets with documented 500,000-kilometer fatigue life.
- Hybrid stop-start efficiency targets:Reciprocating mass reduction in hybrid powertrains is expanding aluminum alloy crankshaft applications in 48V mild-hybrid architectures where NVH performance determines platform selection.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face input cost swings of 30-40% on ferrous scrap grades, compressing forging margin pools and forcing long-term supply agreements with steel mills.
- German forging cluster concentration:Precision crankshaft forging capacity concentrates in the Ruhr industrial corridor, creating single-source risk for European OEMs qualifying new engine platforms.
- Cast iron substitution ceiling:Entry-level passenger car engines below 1.6L displacement remain locked in vermicular cast iron due to cost floors, limiting forged steel penetration in high-volume A-segment vehicles.
Strategic Opportunities
- India commercial vehicle export manufacturing:Bharat Forge and affiliated suppliers have installed 12,000-ton press capacity for crankshaft exports to global truck and bus programs, capturing cost-advantaged production for Euro 6-compliant engines.
- Additive manufacturing fillet repair:Directed energy deposition processes are qualifying for crankshaft remanufacturing, enabling service-life extension for heavy-duty diesel engines in mining and marine applications.
- China MIIT dual carbon alignment:Domestic OEMs are qualifying lightweight forged steel grades with 15% mass reduction to meet corporate average fuel consumption targets, opening specification windows for foreign material suppliers.
Industry Challenges
- Metallurgical technician scarcity:Controlled austenitizing and quenching protocol expertise concentrates among aging workforce cohorts in European and Japanese forging operations, constraining capacity expansion.
- ISO 9001 and IATF 16949 recertification timelines:Supplier audits for crankshaft-specific special process validation now require 18-24 months, delaying new entrant qualification for OEM platform awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crankshaft Materials Market |
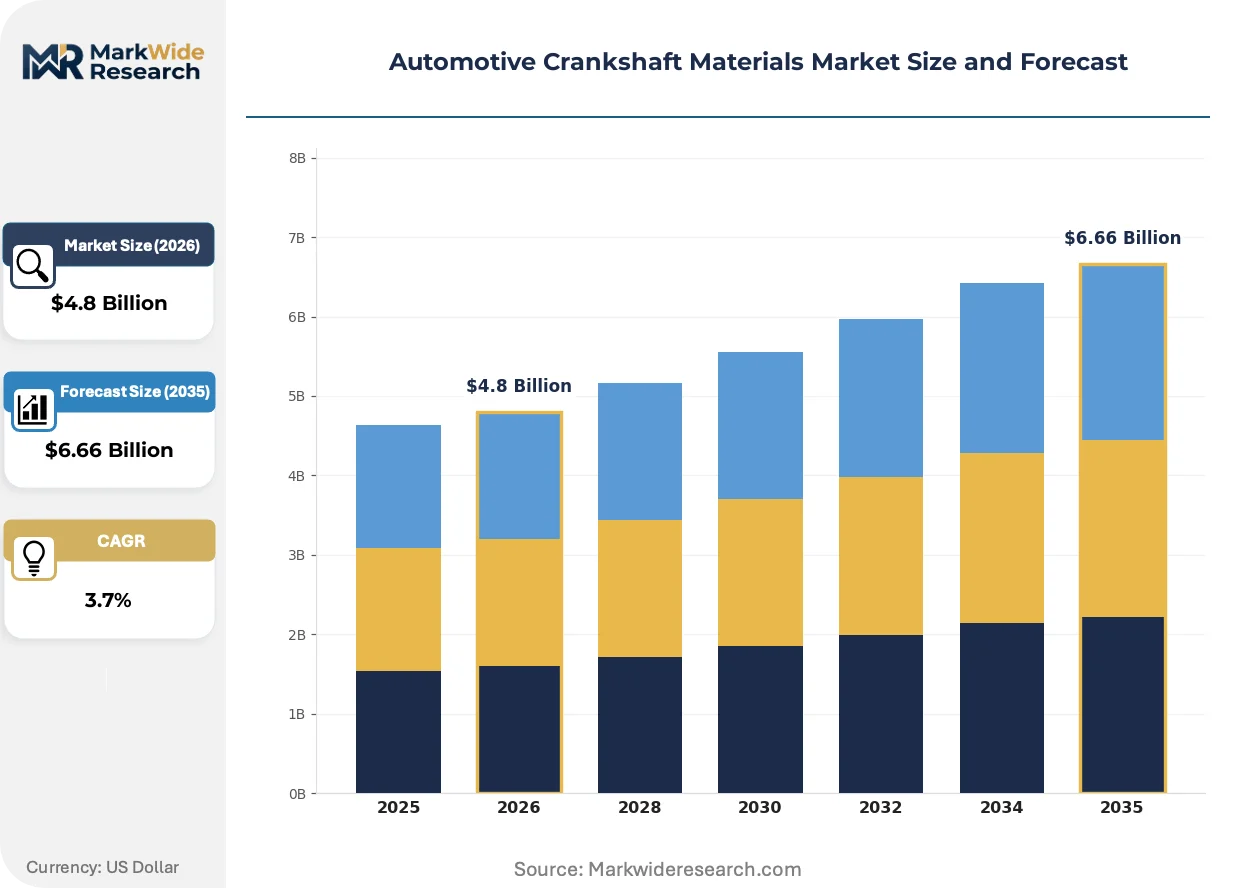
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Cast Iron, Aluminum Alloy, Carbon Fiber Engine Type: Piston Engine, Diesel Engine, Rotary Engine, Hybrid Engine Manufacturing Process: Forging, Casting, Machining, Additive Manufacturing End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Thyssenkrupp AG, MAHLE GmbH, Bharat Forge Limited, Maschinenfabrik Alfing Kessler GmbH, Nippon Steel Integrated Crankshaft LLC, NSI Crankshaft Company, Tianrun Crankshaft Co., Ltd., Rheinmetall AG, Crower Cams & Equipment Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crankshaft Materials Market Evolving Landscape
Material science advances are compressing the performance gap between forged steel and emerging alternatives. Three converging developments are redefining crankshaft specification criteria across passenger car, commercial vehicle, and powertrain architectures.
Tailored forging processes using finite element simulation are optimizing grain flow orientation in high-stress fillet regions. Japanese and German OEMs are adopting these simulation-validated designs for downsized turbocharged engines. The technology is integrating predictive microstructure modeling into supplier qualification protocols, compressing prototype-to-production cycles.
EPA Tier 4 Final and pending Euro 7 proposals are mandating crankshaft endurance testing under elevated mean effective pressure conditions. These regulations are disqualifying legacy cast iron grades from medium-duty diesel platforms. North American heavy-duty engine manufacturers are responding with nitrided forged steel specifications that document 10^7 cycle fatigue life.
Fleet procurement departments are consolidating crankshaft sourcing under powertrain system contracts rather than discrete component awards. Commercial vehicle OEMs are bundling crankshaft supply with engine block and connecting rod procurement, displacing standalone forging specialists. This concentration is most visible in European and North American long-haul truck programs where total cost of ownership modeling dominates supplier selection.
Automotive Crankshaft Materials Market Segmentation
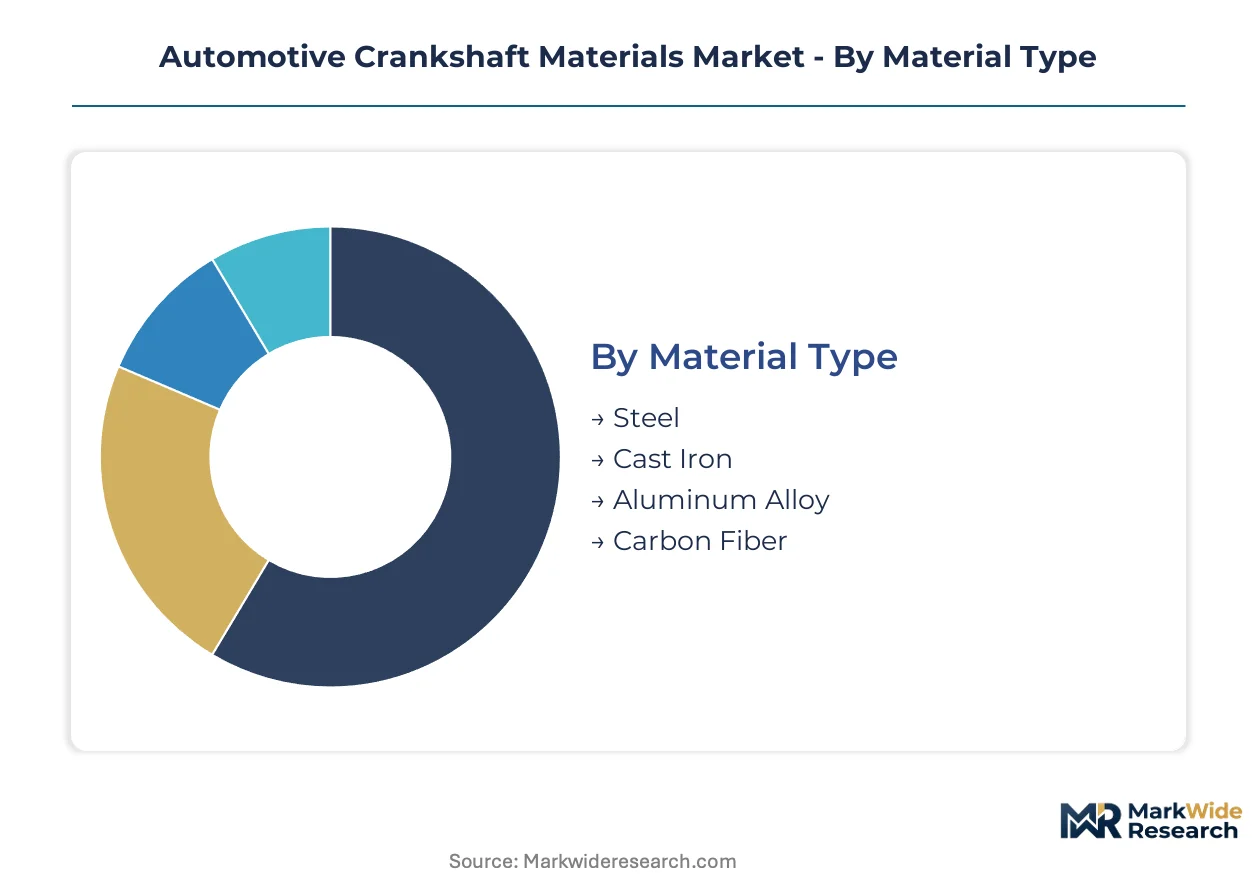
Crankshaft material selection directly determines fatigue life, warranty exposure, and manufacturing economics across engine platforms. Specification patterns diverge sharply between mass-market cost floors and premium durability requirements.
Material Type:
Forged steel commands premium margin pools while cast iron anchors unit volume in cost-sensitive applications.
- Steel:Controlled austenitizing and quenching protocols yield tensile strengths above 800 MPa. Demand concentrates in heavy-duty diesel platforms above 2.5L displacement where EPA Tier 4 and Euro 7 endurance requirements disqualify cast alternatives.
- Cast Iron:Vermicular graphite grades dominate entry-level passenger car engines below 1.6L displacement. German and Indian foundries supply European and Asian OEMs where cost sensitivity outweighs mass reduction targets.
- Aluminum Alloy:Reciprocating mass reduction drives 48V mild-hybrid adoption.
- Carbon Fiber:Experimental motorsport applications only.
Mature deployment sits with Cast Iron. Newer deployment is concentrated in Aluminum Alloy.
Engine Type:
Powertrain electrification is redistributing specification authority across combustion, hybrid, and alternative architectures.
- Diesel Engine:Compression ignition imposes peak cylinder pressures exceeding 200 bar. Nitrided forged steel fillets with documented 500,000-kilometer fatigue life now serve European commercial vehicle platforms under Euro 7 proposals.
- Hybrid Engine:Stop-start cycling frequency demands optimized reciprocating mass. Japanese OEMs specify aluminum alloy crankshafts in 48V architectures where NVH performance determines platform selection.
- Piston Engine:Gasoline spark-ignition spans cast iron to forged steel grades.
- Rotary Engine:Wankel configurations remain niche in range-extender applications.
Specification authority concentrates in Diesel Engine. Fastest specification change is occurring in Hybrid Engine.
Manufacturing Process:
Process selection locks in grain structure, defect tolerance, and production economics.
- Forging:Closed-die hammer and press forming optimize grain flow orientation in high-stress fillet regions. Thyssenkrupp and Bharat Forge operate 12,000-ton press capacity serving European and North American OEM qualification protocols.
- Casting:Green sand and investment processes serve vermicular iron volume production. Chinese foundries supply domestic OEMs meeting MIIT dual carbon corporate average fuel consumption targets.
- Machining:CNC crankshaft grinding follows forging or casting operations.
- Additive Manufacturing:Directed energy deposition qualifies for fillet repair and remanufacturing.
Production scale sits with Forging. Process innovation is concentrating in Additive Manufacturing.
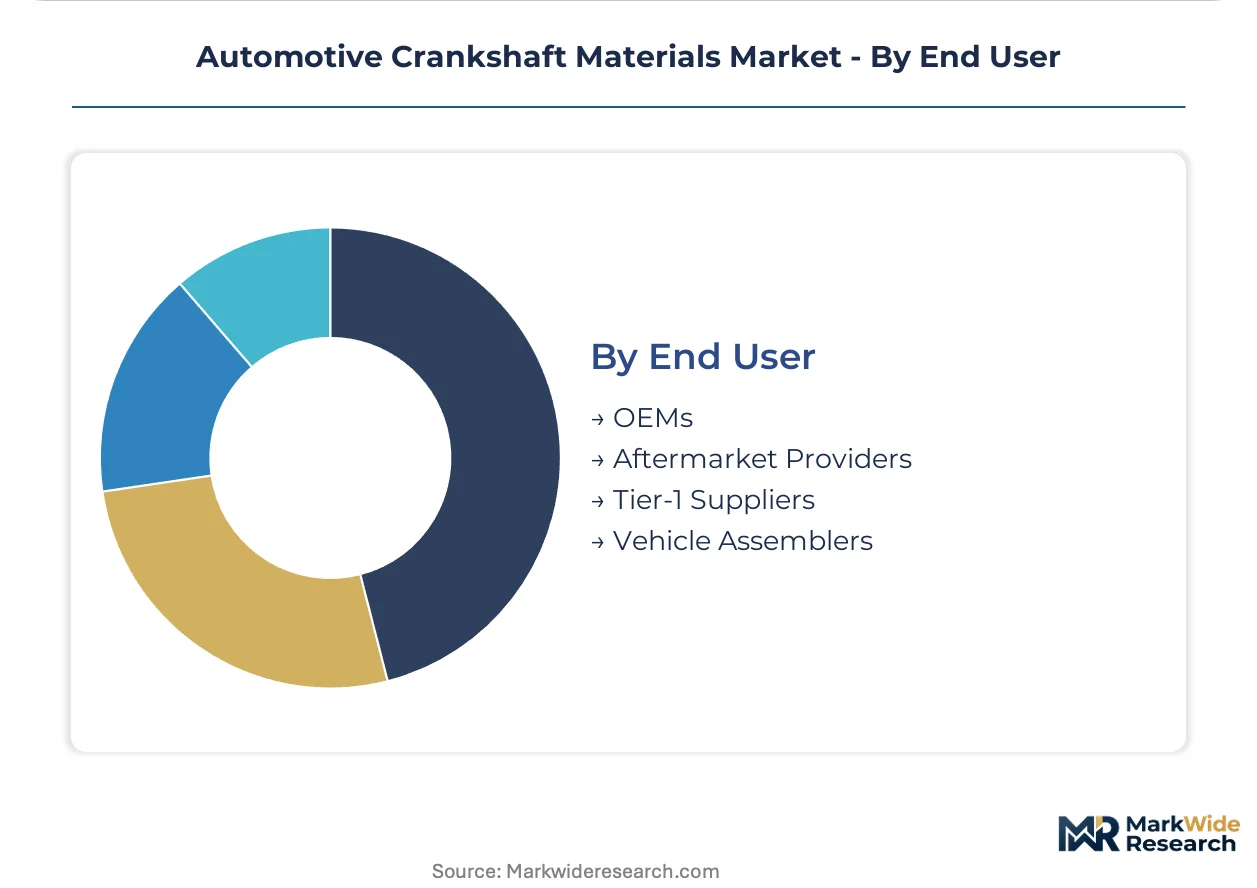
End User:
Procurement consolidation is displacing standalone component suppliers.
- OEMs:Volkswagen, Toyota, and Ford now bundle crankshaft sourcing within powertrain system contracts. Direct material qualification compresses supplier margins while extending warranty liability upstream.
- Tier-1 Suppliers:Mahle and Federal-Mogul integrate crankshaft supply with bearing and connecting rod procurement. North American long-haul truck programs favor total cost of ownership modeling over discrete component awards.
- Aftermarket Providers:Independent remanufacturers serve service-life extension demand.
- Vehicle Assemblers:Contract manufacturers in emerging markets source locally.
Contracting authority concentrates with OEMs. Margin compression is most severe for Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and India's dedicated automotive corridors concentrate crankshaft forging capacity through tax abatements and duty-free import regimes for capital equipment. These zones anchor regional supply networks serving both domestic OEM assembly and export manufacturing programs.
China
MIIT dual carbon targets drive lightweight forged steel qualification among domestic OEMs seeking corporate average fuel consumption compliance. The Yangtze River Delta hosts integrated forging clusters supplying BYD and Geely hybrid platforms with mass-reduced crankshaft grades. Shanghai and Jiangsu province foundries scale vermicular cast iron output for entry-level gasoline engines.
Germany
Euro 7 emissions proposals mandate nitrided forged steel fillets with documented 500,000-kilometer fatigue life for commercial vehicle platforms. The Ruhr industrial corridor concentrates precision forging capacity through Thyssenkrupp and Rheinmetall operations serving Volkswagen and BMW powertrain programs. North Rhine-Westphalia's steel-forging ecosystem anchors European OEM qualification protocols.
India
Bharat Forge anchors high-volume crankshaft exports from Pune and Satara facilities to global truck and bus programs meeting Euro 6 standards. The government's PLI scheme for automotive components incentivizes 12,000-ton press capacity expansion. Maharashtra's Chakan industrial belt supplies forged steel crankshafts to European and North American commercial vehicle OEMs.
Japan
METI fuel economy regulations push aluminum alloy crankshaft adoption in 48V mild-hybrid architectures where NVH performance determines platform selection. Toyota and Honda specification authority concentrates in Aichi and Tokyo metropolitan forging networks. Nippon Steel Integrated Crankshaft LLC supplies metallurgical consistency for domestic and North American passenger car engines.
United States
EPA Tier 4 Final standards disqualify legacy cast iron grades from medium-duty diesel platforms above 2.5L displacement. NHTSA fuel economy regulations converge with commercial fleet total cost of ownership modeling in Michigan and Ohio engine manufacturing corridors. Detroit-based OEMs bundle crankshaft sourcing within powertrain system contracts favoring nitrided forged steel specifications.
Automotive Crankshaft Materials Market Competitive Landscape
Top-tier vendors anchor integrated steelmaking-to-forging operations, while mid-tier specialists compete on process technology and geographic proximity to OEM assembly plants. The vendor base stratifies across three tiers: captive forge divisions of multinational steel groups, independent high-volume commercial vehicle suppliers, and regional foundry operators serving cost-sensitive passenger car programs. Dominant competitive moves include backward integration into specialty steel production and qualification of additive manufacturing processes for remanufacturing applications.
Within the integrated steel-forging tier, Thyssenkrupp AG and Nippon Steel Integrated Crankshaft LLC exemplify metallurgical consistency strategies spanning captive raw material supply through precision forging. Bharat Forge Limited occupies a position among high-volume independent suppliers leveraging Indian manufacturing cost structures for global commercial vehicle export programs. These three entities represent distinct archetypes: European integrated material-forging solutions, Japanese metallurgical precision positioning, and emerging-market scale-driven export manufacturing.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| MAHLE GmbH |
| Bharat Forge Limited |
| Maschinenfabrik Alfing Kessler GmbH |
| Nippon Steel Integrated Crankshaft LLC |
| NSI Crankshaft Company |
| Tianrun Crankshaft Co., Ltd. |
| Rheinmetall AG |
| Crower Cams & Equipment Co., Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned German forging specialists anchor precision crankshaft supply networks through multi-generational equity structures that resist short-term margin compression. Their captive control over Ruhr corridor production assets translates into pricing discipline when electric arc furnace scrap volatility squeezes mid-tier competitors.
Pricing Analysis
Premium lead-time pricing commands 15-20% markups over contract baselines when OEM platform launches compress qualification windows. Pricing stratifies across nitrided forged steel, standard forged grades, and vermicular cast iron tiers based on fatigue certification documentation and EPA Tier 4 compliance verification. Cost compression in cast iron supply pools is intensifying as Chinese foundries absorb scrap steel volatility through state-backed raw material reserves. Fleet procurement departments at commercial vehicle OEMs exhibit lowest price sensitivity given total cost of ownership modeling that weights warranty exposure above unit procurement cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Pune maintain 6-8 week finished goods buffers against forging cycle variability. Supply concentrates in Germany, India, and China where Thyssenkrupp, Bharat Forge, and Yangtze River Delta clusters command 12,000-ton press capacity. Ferrous scrap grades, specialty alloy additives, and nitriding gas feedstocks constitute critical input dependencies. Single-source vulnerability pervades European OEM qualification protocols locked into Ruhr industrial corridor metallurgical expertise. Distribution runs through powertrain system contracts that bundle crankshaft supply with engine block and connecting rod procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive crankshaft materials is consolidating toward integrated steel-forging operations as ISO 9001 and IATF 16949 recertification timelines stretch to 24 months, forcing standalone specialists into exit or acquisition.
For Market Incumbents: Lock in captive steelmaking capacity through backward integration into specialty billet production, insulating margin pools from scrap volatility that compresses electric arc furnace operators. Extend warranty liability coverage to OEM platform engineers as a channel control lever against emerging Indian export competitors. Defend against aluminum alloy substitution in hybrid architectures by accelerating nitrided forged steel qualification for 48V mild-hybrid programs at Toyota and Honda. For New Entrants and Emerging Players: Independent aftermarket remanufacturers represent an underserved buyer archetype with unconsolidated procurement and limited metallurgical protocol enforcement. Penetrate heavy-duty diesel service-life extension demand through directed energy deposition fillet repair capabilities targeting mining and marine applications. Pursue qualification partnerships with Chinese domestic OEMs seeking MIIT dual carbon compliance through lightweight forged steel grades, leveraging faster certification timelines than European or Japanese incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier forging specialists with existing IATF 16949 certification in Maharashtra or Jiangsu provinces where PLI scheme incentives offset capital equipment costs. Long-term viability centers on metallurgical technician apprenticeship pipelines that address workforce aging in European and Japanese operations. Monitor EPA Tier 4 Final enforcement intensity as inflection indicator for cast iron displacement velocity in medium-duty diesel platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Thyssenkrupp's captive billet supply locks in metallurgical consistency for Euro 7 nitrided crankshaft specifications. |
| Qualification for Additive Manufacturing Repair | Directed energy deposition fillet remanufacturing extends service intervals for Caterpillar and Komatsu mining engines. |
| 12,000-Ton Press Capacity Expansion | Bharat Forge's Pune facility captures export share from European forging clusters facing energy cost inflation. |
| Aluminum Alloy Crankshaft Development | Toyota's 48V hybrid platforms specify Aichi-forged aluminum grades to optimize stop-start NVH performance. |
| Long-Term Supply Agreement with Steel Mills | Mahle's scrap price hedging contracts insulate forging margins against 30-40% volatility in electric arc furnace inputs. |
Research Methodology
Document review covered EPA Tier 4 Final regulatory filings, Euro 7 proposal impact assessments, and MIIT dual carbon policy documentation, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement directors, forging plant metallurgists, and aftermarket remanufacturing operators. Secondary validation drew from vehicle production databases, steel trade association capacity reports, and SEC filings of listed automotive component suppliers. Bottom-up segment modeling triangulated against top-down macroeconomic demand projections.
Cross-referencing historical forging capacity utilization against panel input from commercial vehicle fleet procurement departments established demand elasticity parameters across the analysis window. Segmentation dimensions modeled include material type, engine architecture, manufacturing process, and regional production cluster. CAGRs derived from spline interpolation of annual production forecasts weighted by content-per-vehicle assumptions for hybrid and diesel platforms. Industry-specific inputs incorporated nitriding protocol adoption curves and aluminum alloy penetration rates in 48V mild-hybrid architectures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Euro 7 particulate limit finalization, scrap steel price volatility, and Chinese domestic OEM import substitution policies. Forecasts reflect documented assumptions regarding EPA enforcement continuity and IATF 16949 recertification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Global Truck Refrigeration Unit Market