
 North America Automotive Parts Die Casting Market | 2026-2036
North America Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Parts Die Casting Market Analytics
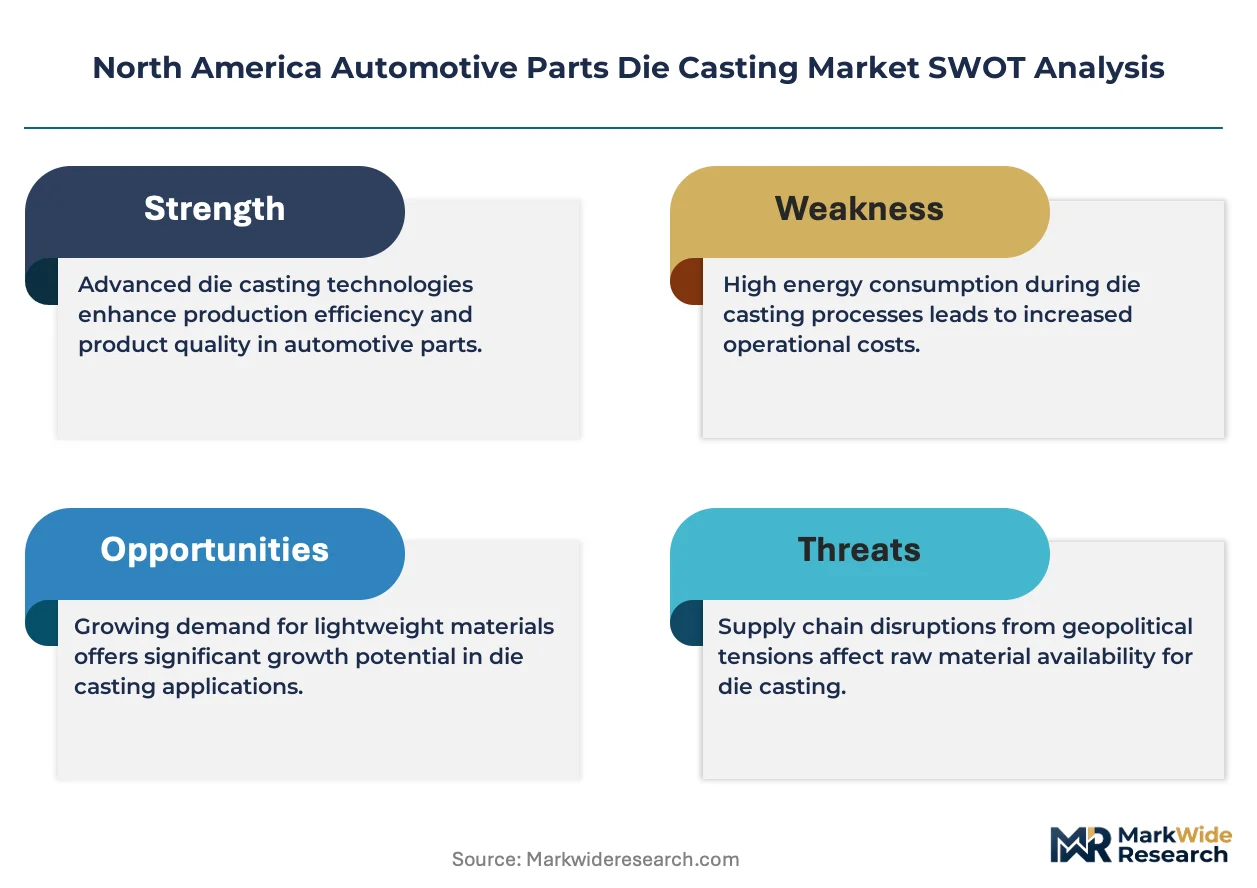
High-pressure die casting is narrowing the weight gap between aluminum and steel structural components across North American vehicle architectures. Nemak, S.A.B. de C.V. leverages its captive aluminum smelting capacity to control raw material costs across Mexican and US plants. Pace Industries anchors its position through dedicated EV-dedicated casting cells in the southeastern United States. Linamar Corporation differentiates via integrated machining capabilities that reduce downstream supplier complexity for Detroit-based OEMs.
Automotive parts die casting involves injecting molten non-ferrous alloys—typically aluminum with 7-12% silicon content—into hardened steel molds at pressures exceeding 1,000 bar to produce near-net-shape components with wall thicknesses below 3 millimeters. The process serves primarily to manufacture powertrain housings, suspension nodes, and structural cross-members that must withstand cyclic mechanical loads while minimizing vehicle curb weight. Engine Components and Transmission Housings retain the largest share of current output volume, though Structural Parts represents the fastest-expanding category as unibody electric platforms displace traditional stamped-steel assemblies. Aluminum dominates material selection due to its strength-to-weight ratio and established recycling infrastructure, while Magnesium competes for select interior and secondary structural applications where every kilogram reduction carries premium value.
The EPA tailpipe emissions standards and NHTSA Corporate Average Fuel Economy requirements directly shape alloy selection and part consolidation strategies across the value chain. Mexico's environmental regulator SEMARNAT and Industry Canada both enforce aligned protocols that permit cross-border component flows without duplicate certification burdens. Stakeholders must monitor how the US Inflation Reduction Act's domestic content thresholds for EV tax credits redirect sourcing decisions for die-cast battery enclosures and motor housings.
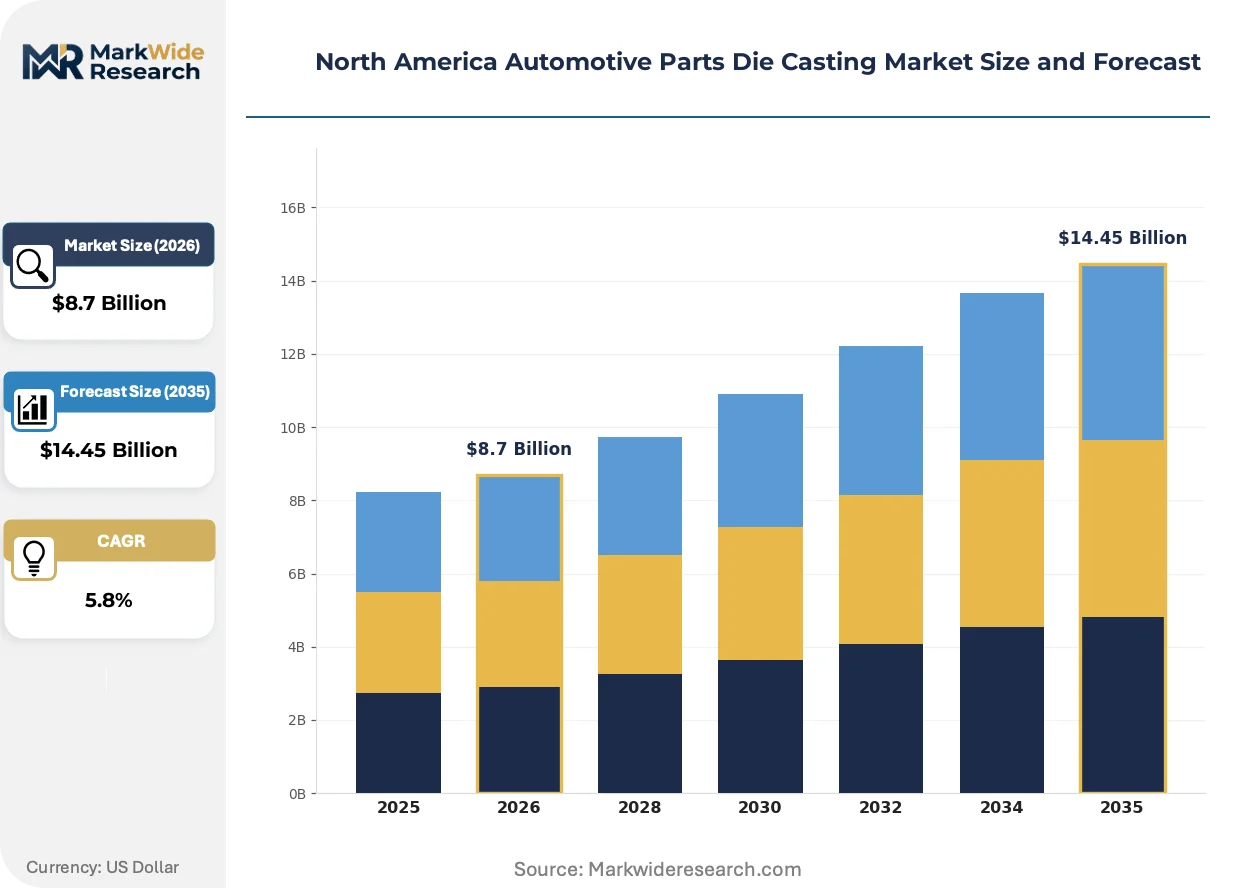
Market Dynamics
Electric vehicle platform architectures are compressing multi-part stamped steel assemblies into single aluminum die-cast structural nodes, redrawing supplier relationships across the Great Lakes manufacturing corridor.
Growth Catalysts
- EPA Tailpipe Standards:Tightening emissions mandates force automakers toward aluminum-intensive powertrain housings and structural cross-members that shed curb weight without compromising crash performance.
- High-Pressure Die Casting:Advances in 1,000+ bar injection systems enable wall thicknesses below three millimeters, opening previously steel-dominated suspension nodes and battery enclosure applications to aluminum.
- Great Lakes Manufacturing Corridor:Concentrated OEM engineering centers in Michigan, Ohio, and Ontario create localized demand pull that reduces logistics costs for complex, just-in-sequence structural castings.
Market Restraints
- Primary Aluminum Volatility:London Metal Exchange price swings for A-grade ingot directly compress foundry margins, with Mexican smelter capacity constraints amplifying regional supply risk.
- Tooling Lead Times:Hardened steel mold fabrication for large structural parts requires 20-30 week delivery cycles, locking capital and constraining foundry responsiveness to demand spikes.
- Magnesium Substitution Ceiling:Flammability concerns and limited North American secondary alloy supply restrict magnesium to interior brackets, capping penetration against aluminum in primary structural applications.
Strategic Opportunities
- Southeastern EV Clusters:New battery and assembly plants in Tennessee, South Carolina, and Georgia create greenfield demand for localized die-cast motor housings and thermal management components.
- US Inflation Reduction Act:Domestic content thresholds for EV tax credits redirect sourcing decisions toward US-based foundries for battery enclosures and electric drive unit housings.
- Multi-Material Bonding:Hybrid joining of die-cast aluminum nodes to carbon fiber reinforced plastic panels enables mixed-material unibody platforms that optimize strength-to-weight across vehicle architectures.
Industry Challenges
- Process Control Talent:Shortage of technicians trained in real-time porosity detection and thermal management for large structural castings limits foundry yield optimization.
- Dimensional Certification Burden:NHTSA crashworthiness validation and OEM geometric dimensioning requirements extend qualification timelines for new battery tray and motor housing designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Parts Die Casting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Structural Parts, Electrical Enclosures Material: Aluminum, Zinc, Magnesium, Copper End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Lightweighting, High-Volume Production, Design Flexibility, Cost Reduction |
| Companies Covered | Nemak, S.A.B. de C.V., Pace Industries, Form Technologies, Ryobi Die Casting, Linamar Corporation, Martinrea International, Bocar, Shiloh Industries, Madison-Kipp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Parts Die Casting Market Evolving Landscape
Process intensification and regulatory alignment are compressing development cycles while expanding the addressable component envelope for non-ferrous casting across North American vehicle programs.
Structural die-cast aluminum is migrating from secondary brackets and housings to primary load-bearing vehicle architecture. OEMs including Detroit Three electric truck programs now specify single-piece rear underbody castings exceeding 100 kilograms. This migration from multi-part assemblies eliminates welding distortion and reduces bill-of-material complexity while demanding new simulation capabilities for thermal stress prediction.
SEMARNAT and Industry Canada have synchronized environmental protocols with EPA emissions frameworks, enabling cross-border component flows without duplicate certification. This regulatory alignment reduces compliance overhead for foundries operating plants across Michigan, Ontario, and Querétaro. Battery enclosure suppliers now design single qualification packages that satisfy all three jurisdictions simultaneously.
Fleet procurement departments now specify total landed cost models that internalize recycling value and end-of-life material recovery. Tier-1 suppliers respond with closed-loop aluminum agreements that guarantee 85%+ post-consumer content in new castings. This preference shift is most visible in California and Quebec, where extended producer responsibility regulations assign material accountability to vehicle manufacturers.
North America Automotive Parts Die Casting Market Segmentation
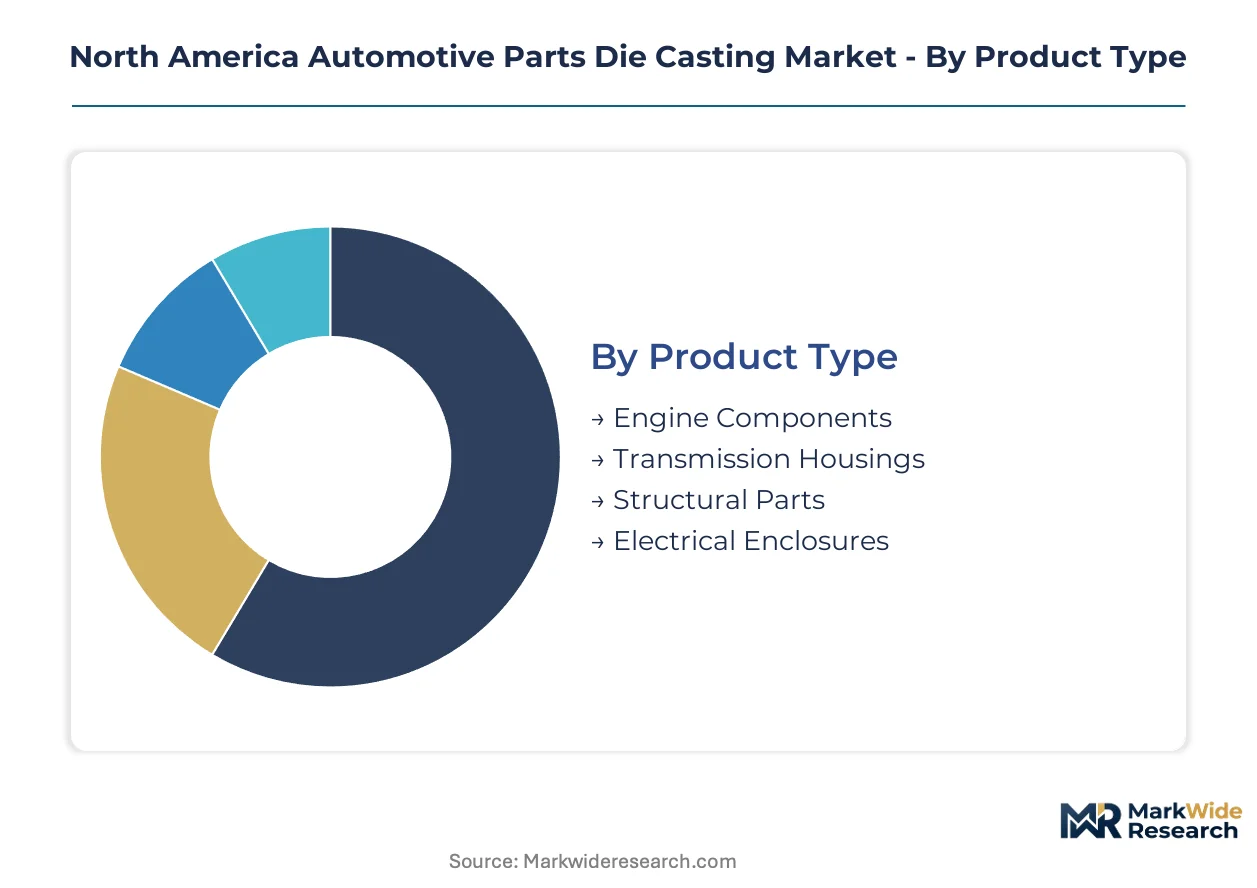
Die casting segmentation reveals how alloy selection and component geometry align with divergent OEM strategies across internal combustion, hybrid, and battery-electric platforms. Understanding these category boundaries clarifies where capital deployment and technical capability investments concentrate most intensively.
Product Type:
Mature powertrain castings coexist with emerging structural mega-castings that compress multi-part assemblies into single aluminum nodes.
- Engine Components:Pistons, cylinder heads, and oil pans in aluminum-silicon alloys withstand thermal cycling above 150°C. Detroit Three engine plants in Michigan and Ohio sustain demand for these legacy powertrain elements even as electrification accelerates.
- Transmission Housings:Bell housings and valve bodies require pressure-tight integrity for ATF fluid retention. Mexican foundries in Querétaro and Ramos Arizpe capture substantial volume from transmission plants co-located with vehicle assembly.
- Structural Parts:Rear underbody castings exceeding 100 kilograms displace stamped-steel assemblies in electric truck platforms.
- Electrical Enclosures:Battery trays and motor housings demand enhanced EMI shielding and thermal management properties.
Engine Components retains volume leadership; Structural Parts holds the steepest expansion curve.
Material:
Cost tier differentiation separates commodity aluminum from premium magnesium where gram-level weight reduction commands substantial value capture.
- Aluminum:A380 and Silafont-36 alloys with 7-12% silicon content deliver optimal castability and strength-to-weight ratios. The Great Lakes corridor's closed-loop recycling infrastructure supports 85%+ post-consumer content in new castings for California and Quebec compliance.
- Magnesium:AZ91D and AM60B alloys achieve 33% weight savings versus aluminum for interior brackets and secondary structural nodes. Flammability concerns and limited North American secondary supply constrain penetration to non-structural applications.
- Zinc:Zamak alloys serve decorative trim and small functional components with excellent surface finish.
- Copper:High-conductivity alloys enable thermal management components and electrical busbar connections.
Aluminum dominates installed base; Magnesium offers the most constrained but highest-margin niche.
End User:
Customer type determines specification intensity, with OEM direct relationships demanding deeper engineering collaboration than aftermarket channels.
- OEMs:Ford, GM, and Stellantis specify geometric dimensioning and tolerancing protocols that extend qualification timelines. Direct OEM contracts require in-house simulation capabilities for thermal stress and porosity prediction.
- Tier-1 Suppliers:Magna, Dana, and Aptiv aggregate die-cast components into subsystem modules, buffering foundries from program-specific volume volatility.
- Aftermarket Providers:Independent distributors source replacement transmission housings and engine covers through secondary channels.
- Vehicle Assemblers:Contract manufacturers and specialty EV builders procure standardized enclosures without full OEM qualification burdens.
Tier-1 Suppliers intermediate the largest production volumes; OEM direct relationships yield the steepest technical capability requirements.
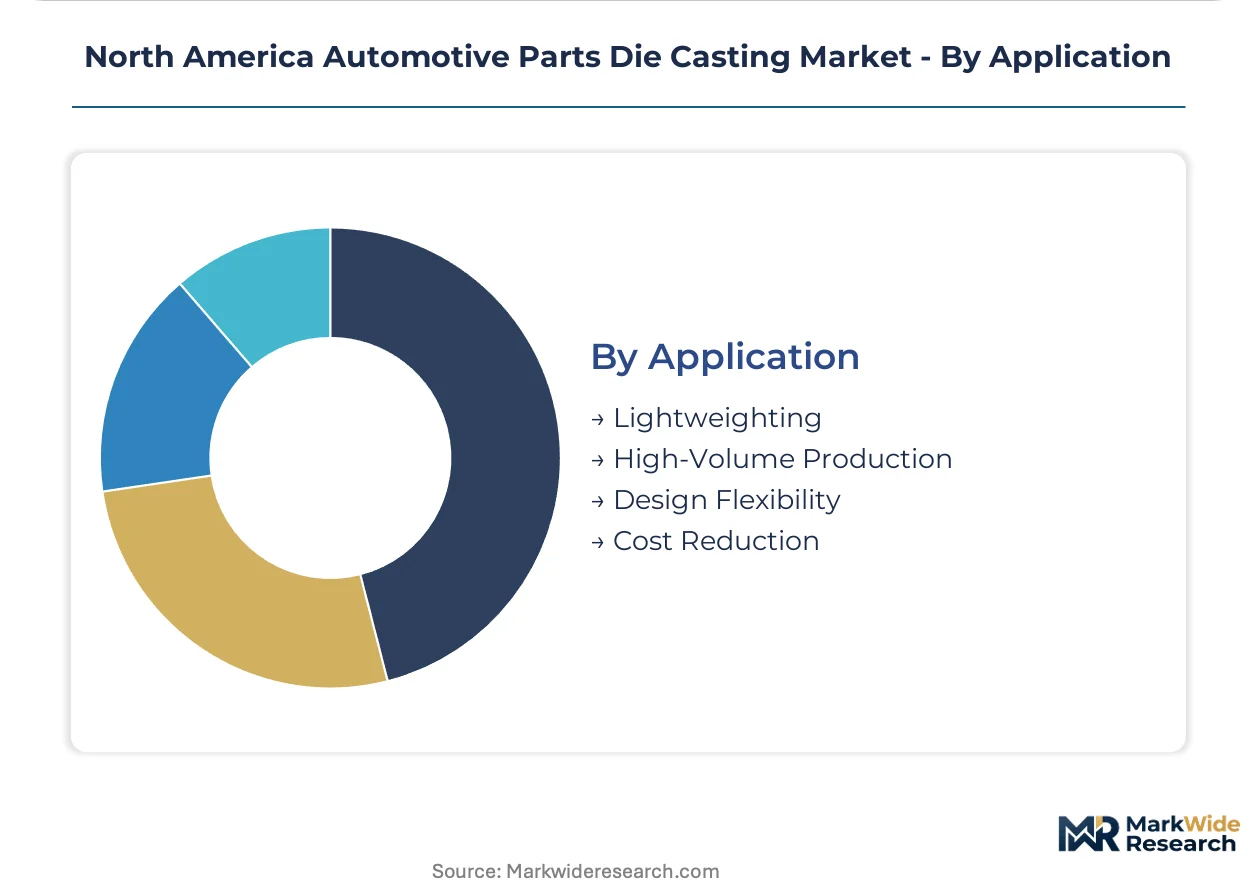
Application:
Application focus separates mass-production efficiency plays from engineering-intensive lightweighting programs that justify premium tooling investments.
- Lightweighting:Every kilogram removed from vehicle curb weight translates to extended EV range or improved ICE fuel economy. Tesla's Cybertruck and Ford's F-150 Lightning specify single-piece rear castings that eliminate 70+ welded joints.
- High-Volume Production:Transmission valve bodies and engine brackets demand 500,000+ annual unit economics. High-pressure die casting cells in Tennessee and South Carolina achieve 90-second cycle times through automated extraction and trim.
- Design Flexibility:Complex internal geometries and variable wall thicknesses enable integrated cooling channels and mounting features impossible with stamped alternatives.
- Cost Reduction:Part consolidation reduces assembly labor and supply chain transaction costs despite higher per-unit casting expenses.
High-Volume Production anchors current revenue; Lightweighting commands the most aggressive capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican foundries export die-cast structural components across the Great Lakes manufacturing corridor, supplying Detroit-based OEM assembly plants with just-in-sequence aluminum castings.
United States
EPA tailpipe standards and NHTSA fuel economy mandates drive aluminum-intensive designs for electric truck platforms. The US Inflation Reduction Act's domestic content thresholds redirect sourcing toward US-based foundries for battery enclosures. Tennessee, South Carolina, and Georgia host expanding EV battery plants that pull localized die-cast motor housing production.
Canada
Industry Canada enforces environmental protocols aligned with EPA frameworks, enabling cross-border component certification without duplication. Ontario's engineering centers concentrate demand for complex structural castings serving Detroit Three programs. Quebec's extended producer responsibility regulations assign material accountability to vehicle manufacturers, accelerating closed-loop aluminum agreements.
Mexico
SEMARNAT environmental regulations synchronize with US and Canadian standards, facilitating duty-free component flows under USMCA. Querétaro and Ramos Arizpe foundries capture transmission housing volume from co-located assembly plants. Captive aluminum smelting capacity in northern Mexico controls raw material costs for cross-border supply chains.
North America Automotive Parts Die Casting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier base. The market structure consolidates around vertically integrated metal producers and independent foundry networks serving overlapping OEM programs. Two strategic archetypes dominate: captive aluminum smelters with backward integration into primary metal supply, and machining-integrated fabricators that reduce downstream supplier complexity. Competitive moves concentrate on capacity expansion for EV-dedicated casting cells and strategic partnerships for closed-loop recycling agreements.
Within the captive smelting tier, Nemak, S.A.B. de C.V. exemplifies vertical control over raw material costs across Mexican and US manufacturing locations. Pace Industries and Linamar Corporation occupy positions on the machining-integrated vector, with the latter reducing supplier complexity for Detroit-based OEMs through in-house finishing capabilities. These three entities represent distinct competitive positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| Nemak, S.A.B. de C.V. |
| Pace Industries |
| Form Technologies |
| Ryobi Die Casting |
| Linamar Corporation |
| Martinrea International |
| Bocar |
| Shiloh Industries |
| Madison-Kipp Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Mexican aluminum smelting through 2026 has compressed spot ingot premiums, forcing Great Lakes foundries to absorb margin erosion while OEMs exploit buyer leverage for multi-year contract renegotiations.
Pricing Analysis
High-pressure die casting equipment generations create pricing stratification across premium, standard, and economy tiers, with next-generation 1,000+ bar cells commanding 15-20% premiums over legacy 600-bar installations. Price differentiation hinges on porosity detection certification levels and captive aluminum smelting integration, with Detroit Three OEMs least sensitive due to total-cost-of-ownership models while aftermarket distributors face acute compression from Chinese import competition. Pricing pressure stems from London Metal Exchange volatility transmission into contract structures, squeezing independent foundries without backward integration into primary metal supply.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate Tier-1 supplier contracts, with supply-chain finance facilities emerging as critical working capital bridges for mid-cap foundries. Geographic supply concentration centers on Mexico, Canada, and the southeastern United States, with raw material dependencies on A-grade aluminum ingot, hardened steel tooling, and silicon additive master alloys. Single-source vulnerability looms over large structural mold fabrication, where 20-30 week lead times lock capital and constrain responsiveness. Distribution runs through just-in-sequence delivery to Great Lakes assembly plants and cross-border consolidated freight to southeastern EV clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of technicians trained in real-time thermal management and porosity simulation for mega-castings above 100 kilograms constrains yield optimization across the supplier base, creating asymmetric value capture for foundries that solve this capability gap.
For Market Incumbents: Entrench market position through captive aluminum smelting expansion in northern Mexico and dedicated EV casting cell investments in Tennessee and South Carolina. Magnesium substitution threats from interior bracket applications require aluminum alloy R&D to close the 33% weight gap in secondary structural nodes. Certification investment in SEMARNAT-EPA-Industry Canada harmonized protocols defends against regulatory fragmentation risk. For New Entrants and Emerging Players: Southeastern EV battery plant corridors in Georgia and South Carolina represent the most penetrable entry point, where localized motor housing and thermal management component demand outstrips qualified supply. Querétaro-Ramos Arizpe transmission housing subcontracting offers lower capital barriers than direct OEM qualification. Go-to-market leverage rests on closed-loop recycling agreements guaranteeing 85%+ post-consumer aluminum content for California and Quebec compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mega-casting tooling above 100 kilograms, favoring asset-light machining-integrated fabricators over pure-play foundries. Long-term viability over the next decade hinges on simulation software capabilities for thermal stress prediction and porosity control. Acquisition targets should display in-house geometric dimensioning and tolerancing engineering teams. The signal to watch is OEM direct contract share versus Tier-1 intermediary dependence as a proxy for pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Smelting Expansion | Nemak's vertical control over raw material costs across Mexican and US plants demonstrates margin defense against LME volatility. |
| EV-Dedicated Casting Cell Investment | Pace Industries' southeastern US capacity anchors localized supply for Tennessee and Georgia battery plant demand pull. |
| Closed-Loop Recycling Agreements | California and Quebec extended producer responsibility regulations assign material accountability, accelerating 85%+ post-consumer content guarantees. |
| In-House Machining Integration | Linamar Corporation reduces downstream supplier complexity for Detroit-based OEMs through combined casting and finishing capabilities. |
| Multi-Material Bonding Partnerships | Hybrid joining of die-cast aluminum nodes to carbon fiber panels enables mixed-material unibody platforms for electric truck architectures. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement data anchors the qualitative findings in observable capacity deployment patterns. Primary interviews with die casting plant managers, OEM lightweighting engineers, aluminum procurement leads, and thermal simulation software specialists informed demand-side assumptions. Secondary validation drew from EPA emissions filings, NHTSA fuel economy compliance data, USMCA trade statistics, and SEC 10-K disclosures from publicly traded automotive suppliers. Bottom-up casting cell capacity counts and top-down vehicle production forecasts triangulate volume estimates.
Calibration against historical aluminum content per vehicle trajectories and electric platform adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material alloy grade, end-user relationship tier, and application intensity. CAGRs derive from compound growth mechanics applied to baseline capacity utilization and announced greenfield investments. Industry-specific forecast inputs incorporate EPA tailpipe standard stringency schedules and Inflation Reduction Act domestic content threshold implementation.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum prices, interest rate environments affecting tooling capital expenditure, or USMCA tariff renegotiation would shift the trajectory. Forecasts embed assumptions regarding SEMARNAT-EPA-Industry Canada regulatory alignment persistence and high-pressure die casting technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Market