
 Arthroscopy Procedures and Products Market | 2026-2036
Arthroscopy Procedures and Products Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopy Procedures and Products Market Analysis
The capital-intensity divergence between integrated platform vendors and instrument specialists is unwinding traditional competitive boundaries. Arthrex, Inc. leverages vertical integration across implants and visualization to control surgeon training channels. Stryker Corporation anchors its position through robotic-assisted delivery systems that bundle hardware with disposable revenue streams. Smith & Nephew plc competes in advanced wound care adjacencies that extend arthroscopy into postoperative recovery protocols.
Arthroscopy procedures and products encompass minimally invasive joint inspection and intervention using fiberoptic cameras, irrigation systems, and specialized mechanical or radiofrequency instruments designed for operative access through sub-centimeter portals. Visualization systems incorporating 4K resolution and fluorescence contrast now define technical performance benchmarks for new platform purchases. Knee arthroscopy retains the largest procedure volume among all joint types, though hip arthroscopy generates disproportionate instrument revenue per case due to longer operative times and specialized traction requirements. Minimally invasive surgery as a delivery mode commands premium pricing over open alternatives while robotic-assisted surgery segments attract capital equipment budgets that reshape hospital procurement cycles.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU Medical Device Regulation mandates notified body conformity assessments that extend timelines for European market entry. ISO 13485 quality management certification operates as a baseline supplier qualification across all major jurisdictions, effectively filtering contract manufacturers and component vendors. Stakeholders must monitor reimbursement parity between inpatient and ambulatory settings as site-of-service differentials determine capital allocation for new visualization platforms.
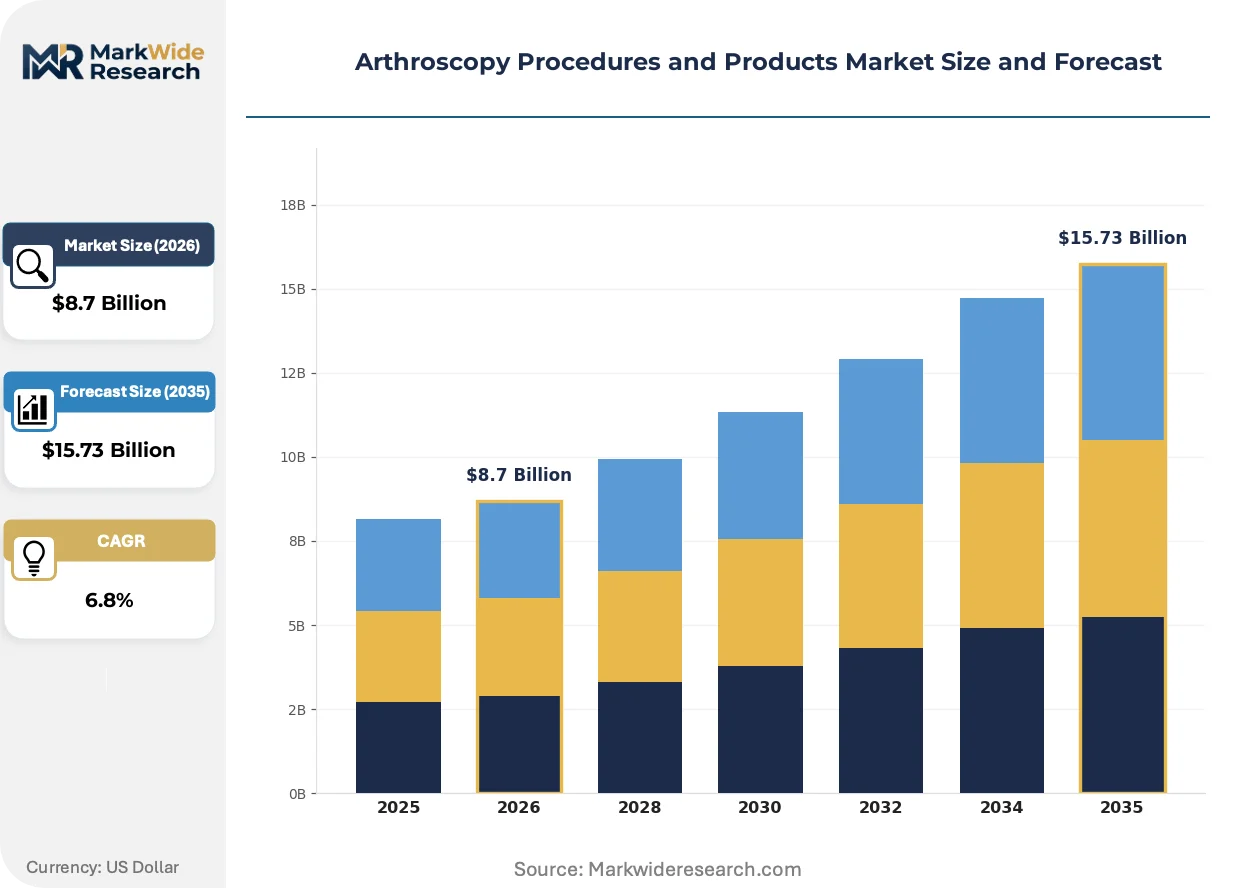
Market Dynamics
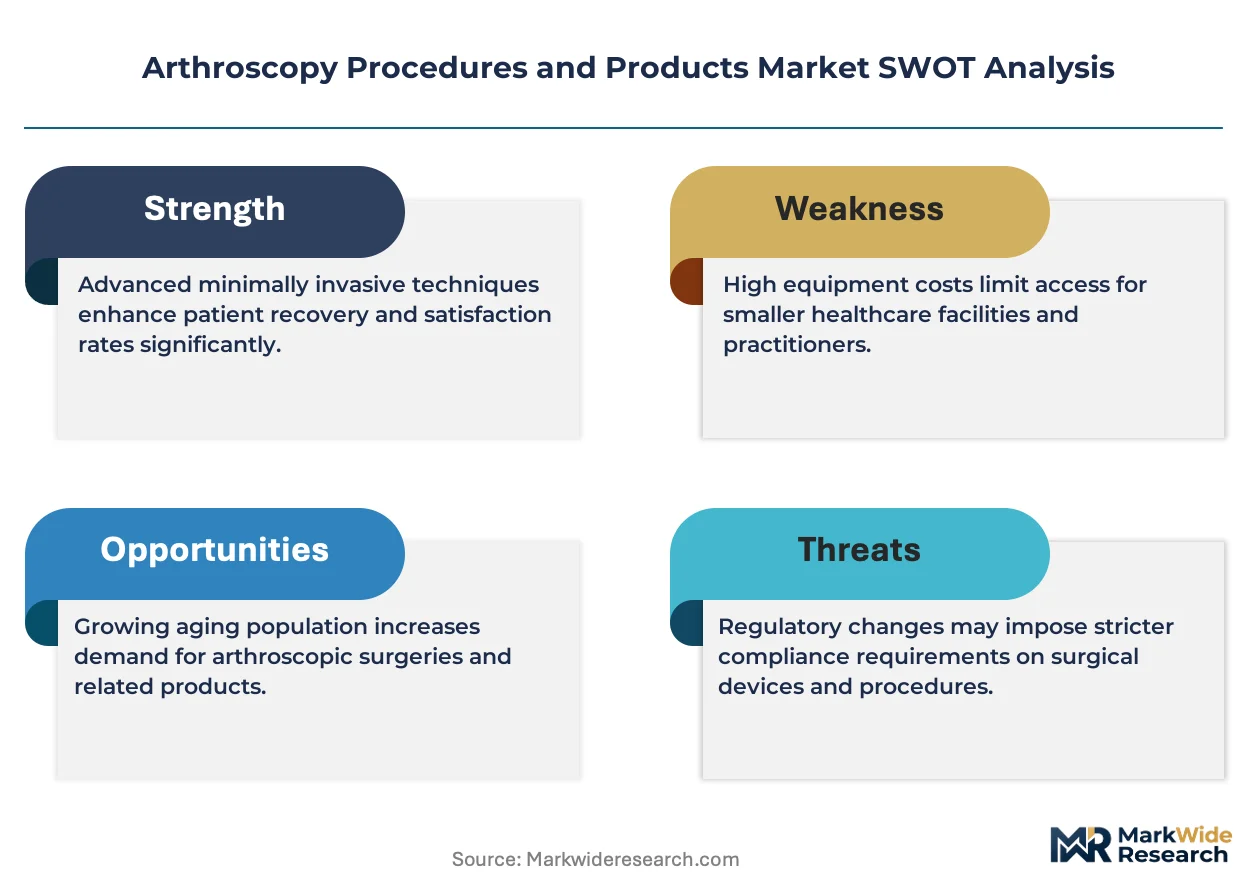
Outpatient migration is compressing procedure volumes into ambulatory surgical centers, forcing manufacturers to rebundle capital equipment and disposables around site-of-service economics rather than traditional hospital procurement cycles.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for visualization systems and powered instruments accelerates product development timelines and reduces regulatory friction for incremental innovations in arthroscopic platforms.
- Sports Medicine Expansion:Academic medical centers are building dedicated arthroscopy service lines to capture rising athlete and aging active-population demand for joint preservation procedures.
- Fluorescence-Guided Surgery:Near-infrared contrast agents integrated with 4K arthroscopes enable real-time tissue perfusion assessment, expanding the addressable case mix toward complex revision surgeries.
Market Restraints
- Capital Equipment Intensity:Integrated visualization platforms require substantial upfront investment, creating procurement bottlenecks at mid-tier hospitals and limiting vendor switching.
- Notified Body Capacity Constraints:EU Medical Device Regulation conformity assessment backlogs extend European market entry timelines by 12-18 months for novel instrument submissions.
- Single-Use Instrument Cost Premium:Disposable shavers and radiofrequency probes carry per-procedure costs three to five times above reusable alternatives, pressuring ASC reimbursement margins.
Strategic Opportunities
- Hip Arthroscopy Underpenetration:Longer operative times and specialized traction requirements create instrument revenue per case multiples above knee procedures, rewarding dedicated product development.
- Postoperative Recovery Integration:Advanced wound care adjacencies extend arthroscopy value capture into recovery protocols, creating service-line bundling opportunities for integrated vendors.
- Robotic-Assisted Delivery Convergence:Capital equipment budgets for surgical robotics are reshaping hospital procurement cycles, enabling platform vendors to anchor disposable revenue streams through hardware lock-in.
Industry Challenges
- Surgeon Training Channel Control:Cadaveric lab access and proctorship programs require sustained investment to maintain preference among fellowship-trained sports medicine specialists.
- ISO 13485 Certification Burden:Quality management system audits operate as baseline supplier qualifications across all major jurisdictions, filtering contract manufacturers and extending component qualification timelines.
- Site-of-Service Reimbursement Parity:Inpatient-ambulatory payment differentials determine capital allocation for new visualization platforms, creating demand forecasting complexity across customer segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopy Procedures and Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Knee Arthroscopy, Shoulder Arthroscopy, Ankle Arthroscopy, Hip Arthroscopy Product Type: Arthroscopes, Surgical Instruments, Visualization Systems, Implants End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Delivery Mode: Open Surgery, Minimally Invasive Surgery, Robotic-Assisted Surgery, Outpatient Procedures |
| Companies Covered | Arthrex, Inc., Stryker Corporation, Smith & Nephew plc, Johnson & Johnson, CONMED Corporation, Zimmer Biomet Holdings, Inc., KARL STORZ SE & Co. KG, Olympus Corporation, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopy Procedures and Products Market Emerging Trajectories
Visualization performance benchmarks are ratcheting upward as 4K resolution becomes table stakes and fluorescence contrast emerges as the next differentiation axis, while procurement authority migrates toward value-analysis committees.
4K arthroscopy systems with integrated fluorescence capability are supplanting standard-definition and early HD platforms in new capital purchases. Ambulatory surgical centers with high knee and shoulder volumes are adopting these systems within 18-24 month replacement cycles. The technology is compressing price positioning for legacy HD inventory and forcing manufacturers to accelerate trade-in programs.
EU Medical Device Regulation notified body conformity assessments now govern all arthroscopic instrument commercialization in Europe. Extended assessment timelines are delaying product launches and concentrating European market entry resources among larger vendors with dedicated regulatory affairs infrastructure. Hip arthroscopy specialists with novel traction or access instruments face the steepest compliance burden.
Hospital value-analysis committees have consolidated procurement authority for capital visualization platforms. Traditional surgeon preference cards are yielding to total cost-of-ownership models that weight disposable contracts, service agreements, and training commitments. United States academic medical centers exhibit the most pronounced shift toward committee-driven vendor selection.
Arthroscopy Procedures and Products Market Segmentation
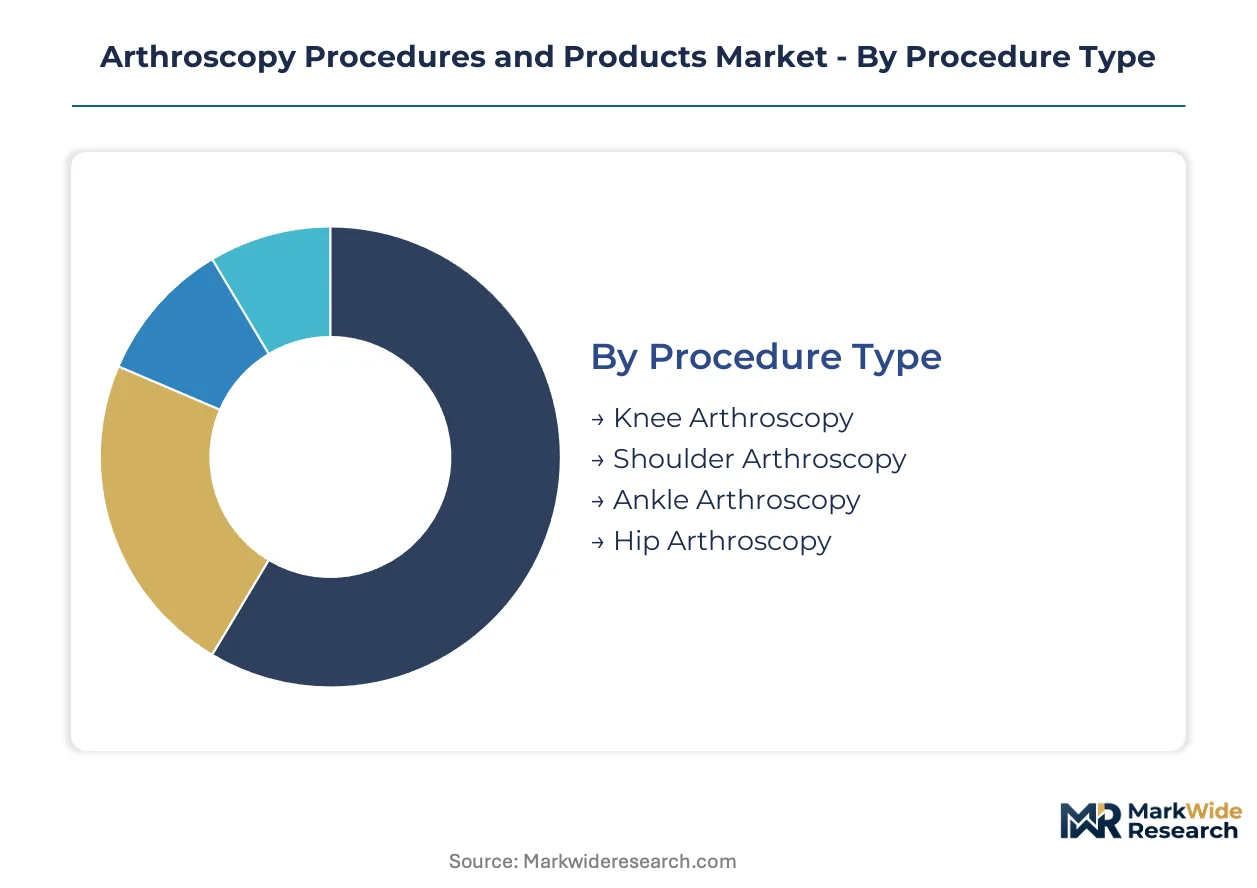
Segmentation in arthroscopy reveals how procedural economics and site-of-service migration reshape purchasing authority across customer types. Manufacturers must align product bundling with the divergent capital constraints of academic medical centers versus ambulatory surgical centers.
Procedure Type:
Substitution pressure from non-operative management and biologic therapies weighs most heavily on knee procedures, while hip arthroscopy faces minimal alternative interventions for femoroacetabular impingement.
- Knee Arthroscopy:Meniscal repair and chondroplasty constitute the foundational volume driver, with diagnostic scopes declining as MRI accuracy improves. Demand concentrates in United States ambulatory surgical centers where bundled payments compress per-procedure economics.
- Shoulder Arthroscopy:Rotator cuff repair and subacromial decompression require specialized beach-chair positioning systems. Academic medical centers in Germany and Switzerland drive adoption of advanced suture anchor configurations for complex revision cases.
- Hip Arthroscopy:Labral repair and cam/pincer resection demand longer operative times and specialized traction tables.
- Ankle Arthroscopy:Syndesmotic fixation and osteochondral lesion treatment serve niche sports medicine applications.
Knee arthroscopy retains volume leadership; hip arthroscopy holds the steepest expansion curve.
Product Type:
Cost tier stratification separates capital equipment purchasers from disposable-heavy buyers, with visualization platforms commanding multi-year amortization against per-case instrument spend.
- Visualization Systems:4K resolution with fluorescence capability now defines the premium tier, replacing HD platforms on 18-24 month cycles at high-volume United States ASCs. Procurement committees in academic medical centers weight total cost-of-ownership models including service agreements and training commitments.
- Surgical Instruments:Motorized shavers and radiofrequency ablation devices generate recurring disposable revenue. German hospitals favor reusable instrument programs to manage per-procedure costs under DRG reimbursement.
- Arthroscopes:Rigid rod-lens and chip-on-tip configurations serve diagnostic and operative applications.
- Implants:Suture anchors and interference screws anchor tissue-to-bone fixation.
Visualization systems capture the largest capital allocation; surgical instruments deliver the most predictable recurring revenue stream.
End User:
Application concentration shifts toward outpatient settings as procedure complexity migrates from inpatient wards, reshaping vendor sales force deployment and service infrastructure.
- Ambulatory Surgical Centers:High-volume knee and shoulder procedures dominate, with 4K platform adoption compressed into rapid replacement cycles. United States ASCs now perform the majority of elective arthroscopy, driving demand for compact, mobile visualization systems.
- Hospitals:Complex revision surgeries and trauma cases retain inpatient status, particularly in France and Italy where public hospital procurement favors integrated platform vendors with training infrastructure.
- Orthopedic Clinics:Diagnostic arthroscopy and minor interventions serve office-based settings.
- Rehabilitation Centers:Postoperative monitoring and conservative management extend care pathways.
Ambulatory surgical centers are gaining share fastest; hospitals retain complex case concentration.
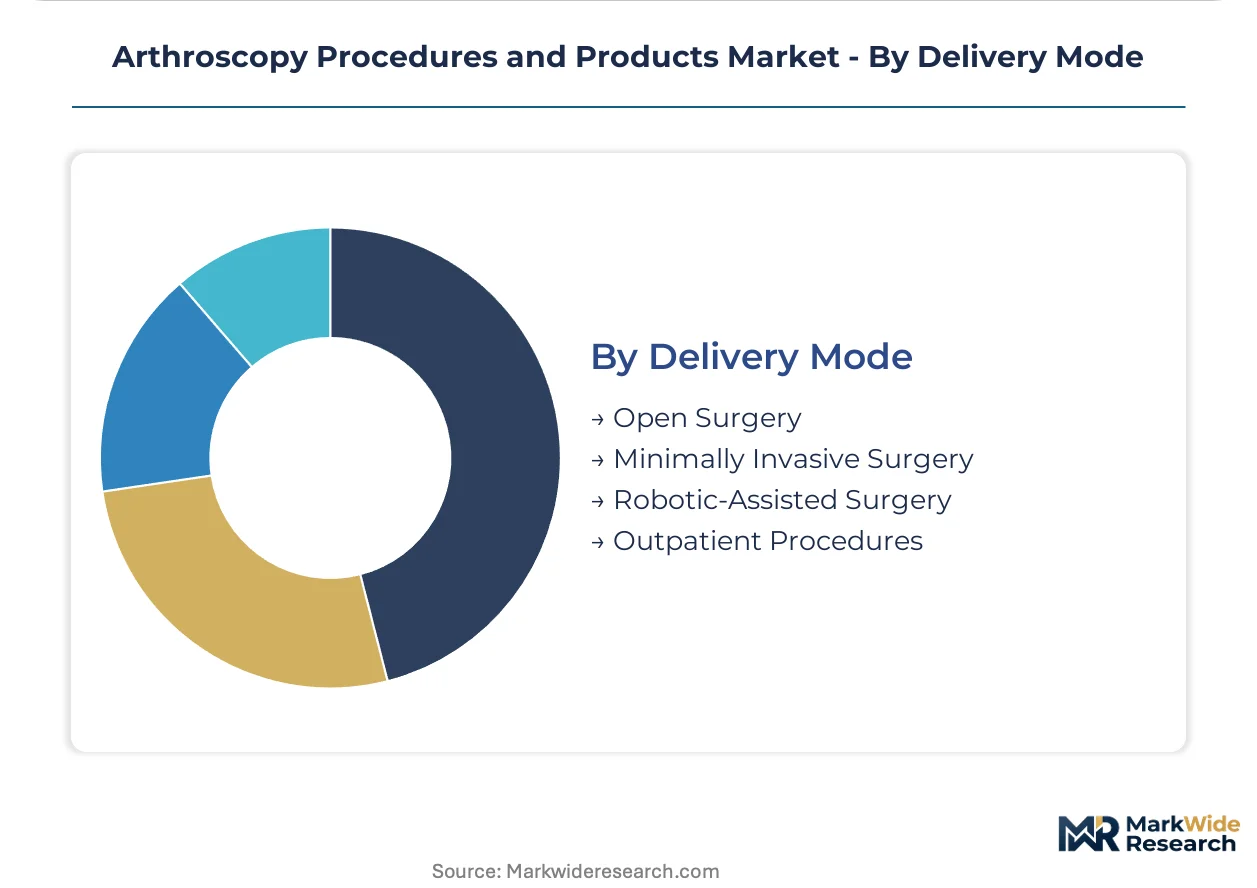
Delivery Mode:
Customer type fragmentation separates traditional open procedures from capital-intensive robotic platforms, with reimbursement parity determining site-of-service economics.
- Minimally Invasive Surgery:Standard arthroscopic portals and irrigation systems define contemporary practice, commanding premium pricing over open alternatives. United States sports medicine specialists drive volume through fellowship-trained networks.
- Robotic-Assisted Surgery:Capital equipment budgets reshape hospital procurement cycles, with Stryker's Mako platform anchoring disposable revenue through hardware lock-in. Academic medical centers in Japan and South Korea evaluate robotic integration for hip arthroscopy applications.
- Open Surgery:Revision cases and severe deformity corrections persist in select indications.
- Outpatient Procedures:Same-day discharge protocols dominate knee and shoulder volumes.
Minimally invasive surgery holds volume dominance; robotic-assisted delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by substantial margins, reflecting divergent reimbursement structures and site-of-service economics that reshape vendor strategy across Atlantic markets.
United States
Ambulatory surgical centers now perform the majority of knee and shoulder procedures, compressing capital equipment replacement cycles to 18-24 months for 4K visualization platforms. FDA 510(k) clearance pathways streamline premarket notification for powered instruments and visualization systems. The Phoenix and Dallas-Fort Worth metro corridors concentrate high-volume ASC networks where bundled payments drive disposable-heavy procurement models.
Germany
Academic medical centers in Munich and Heidelberg anchor demand for complex revision arthroscopy and advanced suture anchor configurations. EU Medical Device Regulation notified body conformity assessments extend market entry timelines for novel instruments. The Baden-Württemberg cluster around Tübingen and Stuttgart hosts specialized orthopedic research institutes that validate fluorescence-guided surgical techniques.
Japan
Academic medical centers in Tokyo and Osaka evaluate robotic-assisted delivery integration for hip arthroscopy applications. METI industrial policy supports domestic manufacturing of surgical visualization equipment through targeted R&D subsidies. The Kansai region around Kyoto concentrates precision optics suppliers that serve arthroscope component markets across East Asia.
Switzerland
Swissmedic certification requirements for implantable devices create a premium regulatory tier that filters mid-market competitors from orthopedic trauma segments. The Lake Geneva corridor between Lausanne and Geneva hosts sports medicine research institutes that collaborate with alpine trauma centers on joint preservation protocols. Zürich-based university hospitals drive adoption of integrated visualization platforms through fellowship-trained surgeon networks.
South Korea
Seoul Capital Area academic medical centers import fluorescence-capable arthroscopy systems for athlete care programs tied to professional sports franchises. MFDS medical device registration mandates local clinical data for Class III instrument approvals, extending timelines for foreign vendors. The Daegu-Gyeongbuk medical device manufacturing cluster supplies disposable shavers and radiofrequency probes to domestic ASC chains.
Arthroscopy Procedures and Products Market Vendor Landscape
Concentration sits with integrated platform vendors that bundle visualization hardware with disposable revenue streams and surgeon training infrastructure. The vendor base spans three tiers: diversified orthopedic conglomerates with robotic-assisted delivery systems, specialized arthroscopy firms with vertical control over implants and visualization, and regional instrument specialists focused on single-use mechanical devices. M&A activity targets fluorescence imaging capabilities and hip arthroscopy traction technologies, while strategic partnerships lock in ASC disposable contracts through capital equipment leasing structures.
Within the integrated platform tier, Arthrex, Inc. and Stryker Corporation exemplify divergent approaches to surgeon channel control—Arthrex through captive training lab networks, Stryker through robotic hardware lock-in that anchors per-procedure disposable spend. Smith & Nephew plc occupies a position bridging arthroscopy instrumentation with advanced wound care adjacencies that extend into postoperative recovery protocols. These three entities represent the dominant competitive archetypes reshaping procurement authority as hospital value-analysis committees displace individual surgeon preference in capital platform selection.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Stryker Corporation |
| Smith & Nephew plc |
| Johnson & Johnson |
| CONMED Corporation |
| Zimmer Biomet Holdings, Inc. |
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month replacement cycles for 4K visualization platforms concentrate procurement authority among high-volume United States ambulatory surgical centers, compressing supplier margins on legacy HD inventory while amplifying pricing power for fluorescence-capable system vendors with captive training infrastructure.
Pricing Analysis
The customization-premium spread between configured-to-order visualization platforms and standard instrument bundles defines transactional pricing in arthroscopy. Three-tier pricing structure across premium, standard, and economy levels segments buyers by procedure volume and training commitment scale. Price differentiation hinges on FDA 510(k) clearance tier and bundled service agreement scope. Pricing pressure stems from single-use instrument cost premiums three to five times above reusable alternatives. Ambulatory surgical centers exhibit acute price sensitivity; academic medical centers with dedicated sports medicine service lines demonstrate lowest sensitivity due to training lock-in effects.
Supply Chain Analysis
EU Medical Device Regulation notified body capacity constraints create regulatory chokepoints that extend European market entry timelines by 12-18 months for novel instrument submissions. Component manufacturing concentrates in Germany, Switzerland, and Japan, with precision optics suppliers in the Kansai region feeding arthroscope assembly across East Asia. Supply chains draw from rare earth elements for fluorescence imaging sensors, surgical-grade stainless steel for shaver assemblies, and medical-grade polymers for disposable cannulae. Single-source vulnerability pervades fluorescence contrast agent supply. Distribution runs through hospital value-analysis committees and ambulatory surgical center GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence-guided surgery adoption in hip arthroscopy applications signals early-cycle expansion, with near-infrared contrast integration expanding addressable case mix toward complex revision surgeries previously managed through open approaches.
For Market Incumbents: Compound defensive moats through captive cadaveric lab networks that control fellowship-trained surgeon channel access. Deepen backward integration into fluorescence imaging sensor supply to offset single-source vulnerability. Anchor disposable revenue through hardware leasing structures that lock ambulatory surgical centers into multi-year instrument contracts. Prioritize ISO 13485 certification maintenance as baseline supplier qualification filters contract manufacturers. For New Entrants and Emerging Players: Postoperative recovery protocol integration represents a service-layer gap where incumbents under-serve, creating white-space for wound care adjacency bundling. Hip arthroscopy traction technology remains the most penetrable segment due to specialized operative requirements and limited dedicated vendors. Target mid-tier United States ambulatory surgical centers with compact, mobile visualization systems that bypass capital equipment intensity barriers. Pursue direct-to-facility disposable contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core arthroscopy instrument lines. Long-term viability over the projection horizon rests on fluorescence imaging capability ownership and surgeon training infrastructure scale. Acquisition target archetype: specialized hip arthroscopy instrument developers with novel traction technologies and European regulatory submission readiness. Monitor FDA 510(k) clearance pathway streamlining announcements as inflection indicator for product development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescence Imaging Capability Acquisition | Near-infrared contrast integration enables real-time tissue perfusion assessment in revision surgeries. |
| Surgeon Training Lab Network Expansion | Cadaveric lab access controls preference among fellowship-trained sports medicine specialists. |
| CE Marking Pathway Investment | EU MDR notified body readiness filters mid-market competitors from European commercialization. |
| Ambulatory Surgical Center Partnership | Bundled payment structures in United States ASCs drive disposable-heavy procurement models. |
| Reimbursement Strategy Development | Site-of-service parity between inpatient and ambulatory settings determines capital allocation. |
Methodological Framework
A spread of perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and ambulatory surgical center administrators converged on the working assumptions underlying this analysis. Primary interviews with sports medicine fellowship directors and GPO contracts managers combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare reimbursement files. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Segmentation dimensions modeled encompass procedure type, product category, end-user facility type, and delivery mode across the analysis window. CAGRs derive from regression analysis against historical replacement cycle compression and site-of-service migration patterns. Procedure volume forecasts incorporate sports medicine service line expansion at academic medical centers and ambulatory surgical center network growth trajectories. Capital equipment intensity thresholds and disposable instrument cost premiums inform pricing elasticity assumptions.
Underlying assumptions cover FDA 510(k) clearance pathway continuity, EU MDR notified body capacity normalization, and reimbursement parity stability between inpatient and ambulatory settings, with deviation risk concentrated in regulatory timeline extensions and site-of-service payment differential shifts. Forecasts reflect these documented assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market