
 North America and Europe Retail Automation Market | 2026-2036
North America and Europe Retail Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Retail Automation Market Analytics
North American kiosk manufacturers is restructuring production networks to shorten lead times for grocery and convenience store chains. Honeywell International Inc leverages its industrial automation heritage to anchor self-checkout hardware deployments across the United States. NCR Voyix Corporation sustains software differentiation through cloud-native point-of-sale architectures. Diebold Nixdorf Incorporated competes on embedded security modules that protect payment data at the terminal edge.
North America and Europe Retail Automation encompasses self-service terminals, intelligent shelving, robotic fulfillment systems, and connected payment infrastructure designed to reduce labor dependency and accelerate transaction throughput. These systems typically integrate RFID tag readers, computer vision cameras, and edge processors operating below 50-millisecond latency to enable real-time inventory tracking and frictionless checkout. Self-Checkout systems command the largest installed base among product types, though Inventory Management solutions are gaining share as RFID tag costs decline. AI-driven applications within Workforce Management are expanding fastest, particularly for demand forecasting and automated scheduling in supermarket chains.
The EU AI Act and GDPR shape algorithm transparency requirements for customer-facing automation, while the FDA's oversight of food traceability systems influences inventory management specifications in the United States. ECHA REACH compliance adds material disclosure burdens for kiosk housings and printed circuit assemblies sold across European markets. Stakeholders must weigh regulatory fragmentation against standardization incentives when selecting architecture partners for cross-border deployments.
Market Dynamics
The North America and Europe Retail Automation Market is experiencing structural compression between labor scarcity and edge-computing infrastructure mandates, forcing grocery chains and hypermarkets to reconfigure store architectures around data-localization requirements.
Growth Catalysts
- EU AI Act compliance pressure:Retailers across Germany and France are accelerating edge-processor deployment to keep customer biometric data within store premises, bypassing cross-border cloud transmission restrictions.
- RFID tag cost erosion:Unit economics for passive inventory tags now support item-level tracking in mid-tier supermarket chains, expanding addressable market for automated shelf-monitoring systems.
- Midwest warehouse automation spillover:United States distribution center robotics investments in Illinois and Ohio are feeding downstream demand for synchronized store-level replenishment systems.
Market Restraints
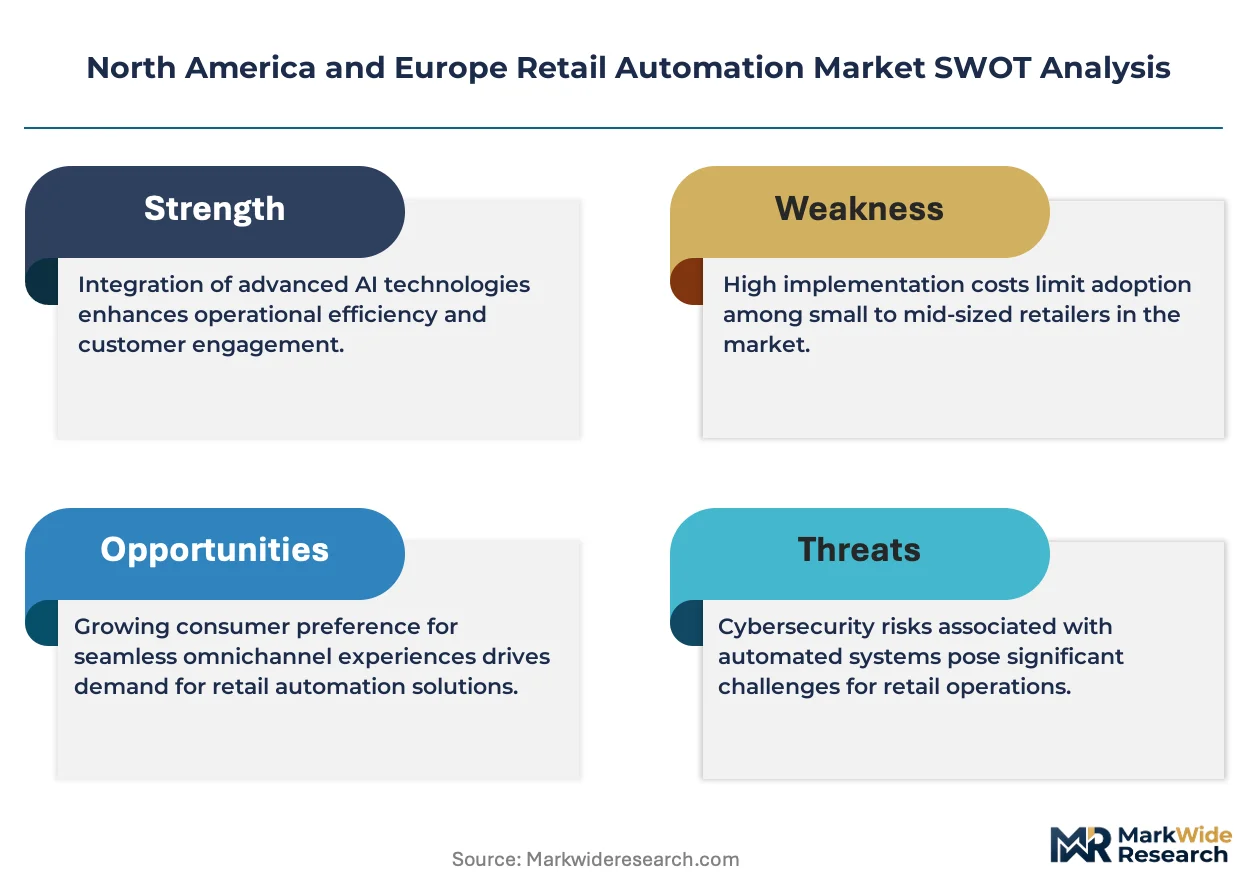
- Semiconductor supply concentration:Edge-computing chip sourcing remains dependent on Taiwan-based foundry capacity, creating 16-24 week lead time vulnerability for kiosk manufacturers.
- ECHA REACH material disclosure:Kiosk housing and PCB assemblies sold across European markets face escalating documentation burdens for flame-retardant chemistries and rare earth elements.
- Legacy POS integration friction:Cloud-native self-checkout architectures encounter protocol incompatibilities with decade-old payment switches still operational in 40% of United States convenience store networks.
Strategic Opportunities
- United Kingdom convenience sector:Petrol station chains and urban express formats remain underpenetrated by self-checkout relative to grocery, presenting first-mover expansion terrain.
- FDA food traceability alignment:Section 204 of the Food Safety Modernization Act mandates granular lot-tracking, creating regulatory tailwind for RFID-enabled inventory management in United States fresh produce retail.
- Computer vision and weight-sensor fusion:Converging technologies enable theft-resistant checkout-free stores, with pilot deployments concentrated in Netherlands and California urban corridors.
Industry Challenges
- Edge-AI engineering talent scarcity:Retail technology vendors compete with automotive and medical device sectors for firmware developers capable of sub-50-millisecond latency optimization.
- GDPR audit complexity:Automated customer-tracking systems require continuous algorithmic transparency documentation, stretching compliance teams across multi-format retail portfolios.
- Intergenerational hardware interoperability:Mixed estates of RFID, barcode, and vision-based systems create data synchronization failures during peak transaction periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Retail Automation Market |
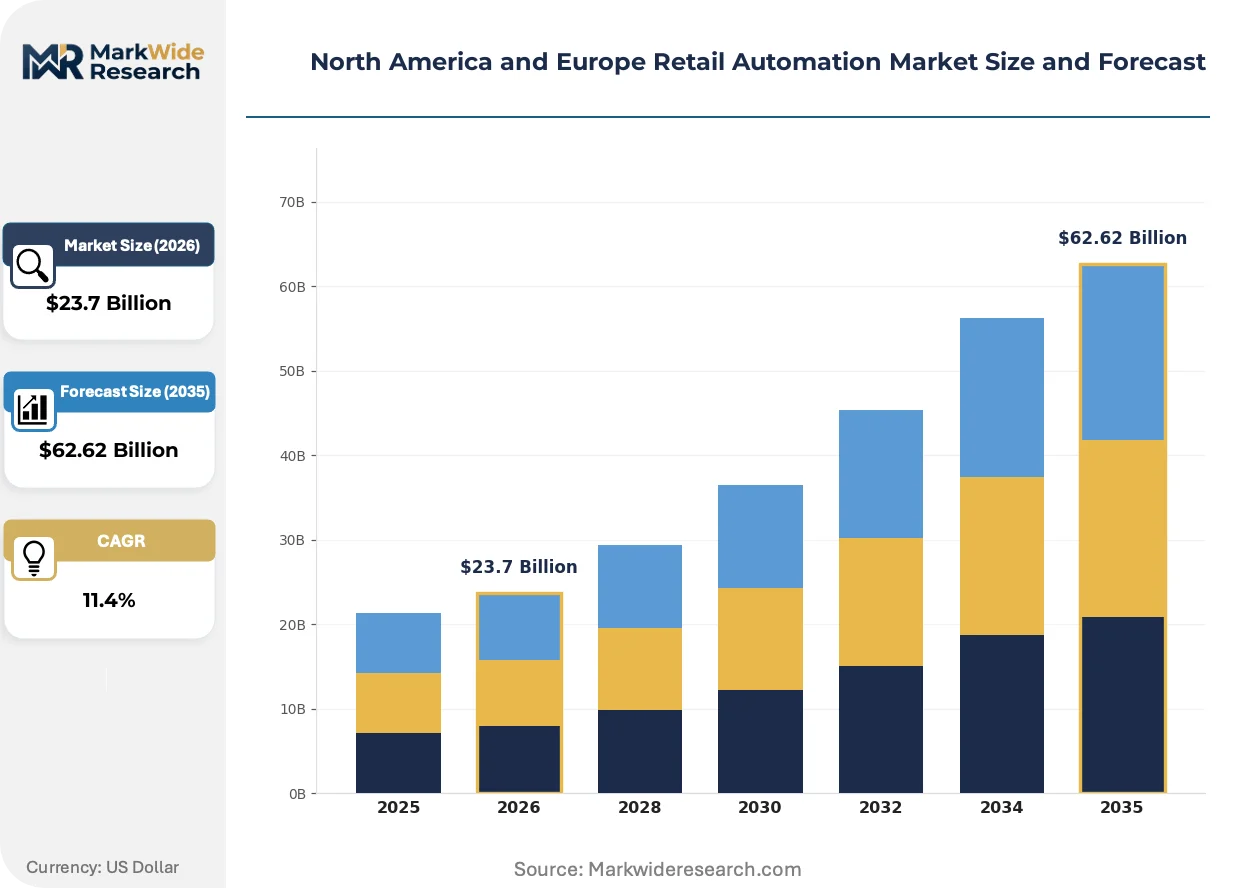
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Checkout, Point of Sale, Inventory Management, Digital Signage Customer Type: Brick-and-Mortar Stores, E-Commerce Platforms, Supermarkets, Convenience Stores Technology: RFID, AI, Mobile Payment, Cloud Computing Application: Customer Experience, Payment Processing, Supply Chain Management, Workforce Management |
| Companies Covered | Honeywell International Inc, NCR Voyix Corporation, Diebold Nixdorf Incorporated, Zebra Technologies Corporation, Datalogic S.p.A., ECR Software Corporation, Fujitsu Limited, Pricer AB, Kuka AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Retail Automation Market Evolving Landscape
Retail automation is pivoting from labor substitution toward data-sovereignty architectures, with regulatory pressure and hardware convergence rewriting deployment priorities across formats.
Computer vision with embedded neural inference is rewriting checkout friction economics. Grocery chains in the United Kingdom and Netherlands are retrofitting existing self-checkout lanes with camera arrays that eliminate barcode scanning entirely. The technology is compressing transaction times by 30-40% while reducing hardware touchpoints requiring sanitization protocols.
GDPR Article 35 data protection impact assessments now govern customer-facing automation deployments across European Union member states. Retailers must document algorithmic decision-making logic for loyalty pricing and biometric age-verification systems. Fresh food segments in France and Germany are responding by localizing inference processing at store edge rather than enterprise cloud.
Buyer concentration among top-ten United States grocery banners is compressing vendor negotiation cycles from annual to quarterly review. Regional cooperative purchasing organizations are disintermediating traditional distribution channels for kiosk hardware. The phenomenon is most visible in Southeastern retail corridors where Publix and Kroger procurement alliances dominate self-checkout specification standards.
North America and Europe Retail Automation Market Segmentation
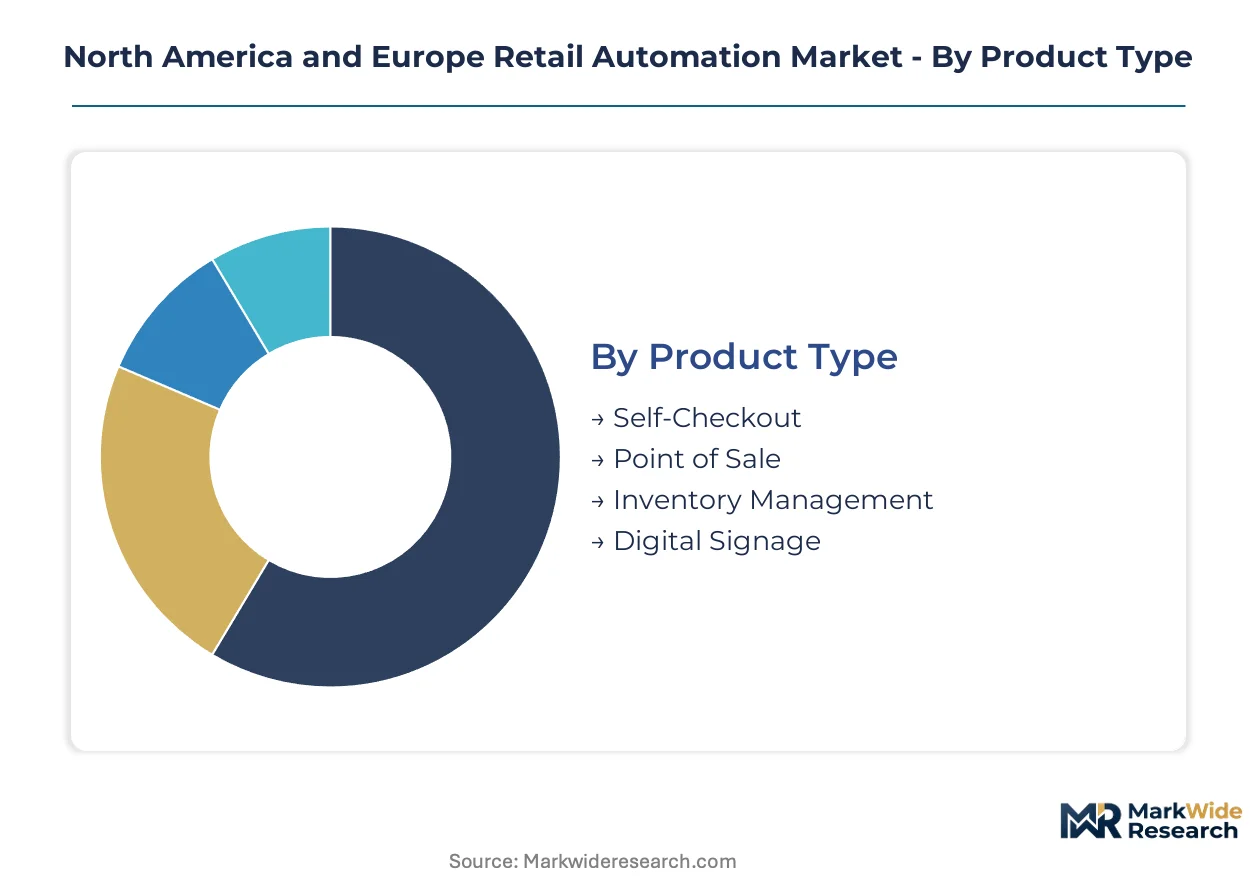
Retail automation purchasing patterns diverge sharply across format types and technology maturity levels. Grocery chains prioritize transaction throughput and labor displacement, while convenience operators emphasize footprint minimization and payment flexibility.
Product Type:
Hardware differentiation centers on latency performance, biometric handling, and legacy system interoperability.
- Self-Checkout:Terminal architectures integrate edge processors operating below 50-millisecond latency to satisfy GDPR data-localization mandates. German and United Kingdom hypermarkets are retrofitting lanes with computer vision arrays that eliminate barcode scanning entirely. Self-Checkout leads volumes today; Inventory Management is gaining share fastest.
- Point of Sale:Cloud-native architectures from NCR Voyix and competing stacks encounter protocol friction with decade-old payment switches still operational in 40% of United States convenience store networks. PCI-DSS compliance and embedded security modules anchor procurement specifications.
- Inventory Management:RFID-enabled shelf monitoring expands as passive tag unit economics support item-level tracking in mid-tier supermarket chains. FDA Section 204 food traceability mandates drive fresh produce retail adoption.
- Digital Signage:Edge-computing content delivery reduces cloud transmission volumes for EU AI Act compliance.
Self-Checkout commands the largest installed base; Inventory Management solutions are climbing the fastest as RFID tag costs decline.
Customer Type:
Format scale determines automation sophistication, with purchasing concentration and labor cost exposure driving specification tiers.
- Supermarkets:Full-format grocery banners in the United States Midwest and Southeast retail corridors dominate procurement volumes. Warehouse automation spillover from Illinois and Ohio distribution centers feeds synchronized store-level replenishment demand.
- Convenience Stores:United Kingdom petrol station chains and urban express formats remain underpenetrated relative to grocery, presenting first-mover terrain. Footprint constraints favor compact self-checkout terminals over full-lane configurations.
- Brick-and-Mortar Stores:Mixed estates of RFID, barcode, and vision-based systems create data synchronization failures during peak transaction periods.
- E-Commerce Platforms:Dark store and micro-fulfillment automation for last-mile delivery integration.
Supermarkets anchor current revenue concentration; Convenience Stores offer the steepest expansion trajectory through format conversion.
Technology:
Architecture choices increasingly reflect regulatory geography rather than pure performance optimization.
- AI:Computer vision with embedded neural inference compresses transaction times by 30-40% in Netherlands and California pilot deployments. GDPR Article 35 data protection impact assessments govern algorithmic transparency for loyalty pricing and biometric age-verification.
- RFID:Passive inventory tags now support automated shelf-monitoring in mid-tier chains previously priced out of item-level tracking.
- Mobile Payment:Protocol standardization lags across United States convenience store networks with legacy payment switches.
- Cloud Computing:Edge-computing architectures displace centralized processing for EU AI Act and GDPR compliance.
RFID leads current deployment volumes; AI applications within Workforce Management are expanding most quickly for demand forecasting and automated scheduling.
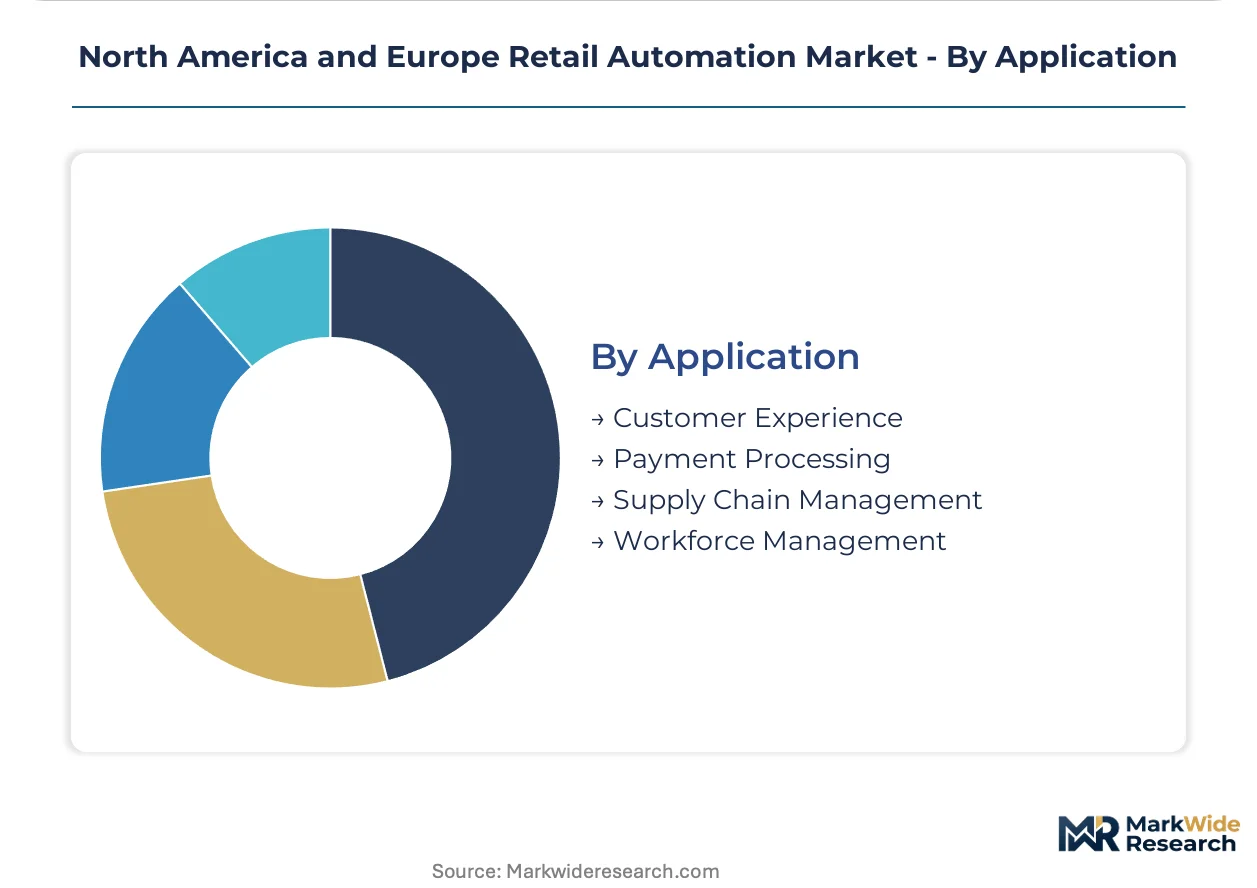
Application:
Functional priorities split between customer-facing friction reduction and back-of-house operational control.
- Payment Processing:Embedded security modules protect terminal-edge payment data against PCI-DSS audit failure. Diebold Nixdorf and competing hardware vendors compete on tamper-resistant architectures.
- Customer Experience:Checkout-free store pilots in Netherlands and California urban corridors converge computer vision and weight-sensor fusion for theft-resistant operation.
- Supply Chain Management:FDA food traceability alignment creates regulatory tailwind for RFID-enabled lot-tracking in United States fresh produce retail.
- Workforce Management:AI-driven demand forecasting and automated scheduling expand fastest in supermarket chains facing labor scarcity.
Payment Processing dominates current system value; Workforce Management applications are gaining share fastest as labor costs climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail automation hardware production is migrating toward jurisdictions with streamlined compliance pathways, creating divergence between EU member states enforcing GDPR Article 35 assessments and US states with lighter biometric data restrictions.
United States
Midwest distribution center robotics in Illinois and Ohio are feeding synchronized store-level replenishment demand across supermarket banners. FDA Section 204 of the Food Safety Modernization Act mandates granular lot-tracking for fresh produce, accelerating RFID-enabled inventory management adoption. California and Texas urban corridors host pilot deployments of checkout-free stores converging computer vision with weight-sensor fusion.
Germany
Hypermarket chains are retrofitting self-checkout lanes with edge processors operating below 50-millisecond latency to satisfy GDPR data-localization requirements. The EU AI Act drives algorithmic transparency documentation for biometric age-verification systems. Industrial automation heritage in Bavaria and North Rhine-Westphalia anchors kiosk manufacturing clusters serving pan-European grocery networks.
United Kingdom
Petrol station chains and urban express convenience formats remain underpenetrated by self-checkout relative to grocery, presenting first-mover expansion terrain. Post-Brexit regulatory divergence from EU AI Act frameworks creates compliance complexity for cross-border retail technology vendors. London and Southeast England concentrate software development talent for cloud-native point-of-sale architectures.
France
Fresh food segments are responding to GDPR Article 35 data protection impact assessments by localizing inference processing at store edge rather than enterprise cloud. CNIL enforcement actions against automated customer-tracking systems have elevated compliance team staffing across multi-format retail portfolios. The Île-de-France region hosts pilot deployments of computer vision arrays eliminating barcode scanning entirely.
Netherlands
Checkout-free store pilots are concentrated in urban corridors where converging technologies enable theft-resistant operation without hardware touchpoints. ECHA REACH compliance adds material disclosure burdens for kiosk housings and printed circuit assemblies entering European markets. The Randstad region anchors edge-computing engineering talent pools competing with automotive and medical device sectors for firmware developers.
North America and Europe Retail Automation Market Competitive Landscape
United States producers anchor one tier with industrial automation heritage and cloud-native software stacks; European specialists hold another with embedded security modules and GDPR-compliant edge architectures. The vendor base splits between consolidated hardware fabricators with captive semiconductor sourcing and fragmented software boutiques serving format-specific compliance requirements. Three archetypes dominate: industrial conglomerates with cross-sector automation portfolios, payment-terminal specialists with PCI-DSS certification depth, and RFID-centric inventory management pure-plays. Competitive moves center on strategic partnerships bridging legacy POS protocol gaps and geographic expansion into underpenetrated convenience formats.
Among United States-based industrial conglomerates, Honeywell International Inc exemplifies the cross-sector automation archetype, leveraging heritage in control systems for self-checkout hardware deployments. NCR Voyix Corporation occupies a position within the cloud-native software tier, sustaining differentiation through point-of-sale architectures. Diebold Nixdorf Incorporated represents the embedded security specialist archetype, anchoring procurement specifications for tamper-resistant payment data protection at terminal edge.
| Leading Market Players |
|---|
| Honeywell International Inc |
| NCR Voyix Corporation |
| Diebold Nixdorf Incorporated |
| Zebra Technologies Corporation |
| Datalogic S.p.A. |
| ECR Software Corporation |
| Fujitsu Limited |
| Pricer AB |
| Kuka AG |
| Others |
Value Network & Pricing Analysis
Captive semiconductor sourcing from Taiwan-based foundries anchors both hardware cost structures and vendor pricing power across self-checkout and edge-computing terminal markets. This integration choice forces kiosk manufacturers to absorb 16-24 week lead time premiums or cede margin to distributors holding buffer inventory.
Pricing Analysis
Distributor margin layers in European markets now absorb ECHA REACH compliance documentation costs for flame-retardant chemistries and rare earth elements. Three-tier pricing structure across premium, standard, and economy levels stratifies by edge-processor latency performance and PCI-DSS certification grade. Cost compression in mid-tier supermarket chains intensifies because RFID tag unit economics now support item-level tracking previously reserved for premium banners. Regional cooperative purchasing organizations in the United States Southeast exhibit highest price sensitivity, while German hypermarket chains prioritize GDPR-compliant architectures over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for edge-computing chips now mandate multi-supplier qualification across Taiwan, South Korea, and United States foundry capacity. Component dependencies rest on advanced node semiconductors, passive RFID inlays, and flame-retardant PCB substrates. Single-source vulnerability concentrates in Taiwan-based foundry capacity for sub-7 nanometer inference processors. Distribution runs through regional cooperative purchasing organizations disintermediating traditional hardware distributors in United States retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in retail automation hinges on RFID tag cost-down curves enabling premium-tier self-checkout deployments in mid-tier supermarket chains previously priced out of computer vision arrays.
For Market Incumbents: Cement cloud-native software differentiation through API architectures that bridge legacy POS protocol gaps in United States convenience store networks. Deepen captive semiconductor sourcing relationships to defend against emerging edge-AI engineering talent scarcity. Priority lever rests on vertical integration into firmware development for sub-50-millisecond latency optimization competing with automotive and medical device sectors. For New Entrants and Emerging Players: Enter via United Kingdom petrol station chains and urban express convenience formats where self-checkout penetration lags grocery hypermarkets by substantial margins. Target computer vision retrofit kits eliminating barcode scanning as the most penetrable application tier. Go-to-market angle centers on GDPR Article 35 compliance-as-a-service bundling edge-processor hardware with algorithmic transparency documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented software boutiques serving format-specific compliance requirements lack scale to negotiate quarterly vendor review cycles demanded by top-ten United States grocery banners. Long-term viability favors acquisition targets with embedded security module certification depth and pan-European GDPR-compliant edge architectures. Signal to watch is buyer concentration among Southeastern retail cooperative purchasing organizations compressing specification standards toward single-vendor lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Localization | EU AI Act compliance mandates store-level inference processing bypassing cross-border cloud transmission restrictions. |
| Computer Vision Retrofit Deployment | German and United Kingdom hypermarkets eliminate barcode scanning entirely through camera array lane retrofits. |
| RFID-Enabled Inventory Management Scale-Up | FDA Section 204 food traceability mandates drive fresh produce retail adoption across United States Midwest corridors. |
| Strategic Partnership with Regional Cooperatives | Southeastern purchasing alliances dominate self-checkout specification standards disintermediating traditional distribution channels. |
| GDPR Compliance-as-a-Service Bundling | CNIL enforcement actions elevate algorithmic transparency documentation staffing across multi-format retail portfolios. |
Research Methodology
Multiple input streams — executive interviews with kiosk hardware procurement directors, primary fieldwork with edge-computing firmware developers, and secondary validation through SEC 10-K filings and ECHA REACH substance databases — were reconciled using bottom-up and top-down triangulation. Stakeholder roles included supermarket category technology officers, convenience store operations directors, PCI-DSS audit specialists, and cooperative purchasing organization contract managers.
Cross-reference between historical deployment trajectories and panel input from German hypermarket technology executives shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type latency tiers, customer format scale, regulatory compliance geography, and edge-processor inference capability. CAGRs derived from unit economics tracking RFID tag cost erosion and labor cost trajectories in United States retail corridors.
Inputs from ECHA substance registration databases and FDA food traceability guidance documents were available through the study window; gaps in real-time edge-AI engineering compensation benchmarking introduce uncertainty bands around workforce management application adoption curves. Deviation in Taiwan-based foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Sortation Systems Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Europe SCADA Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Modular Automation and Services Market