
 Industrial Automation Services Market | 2026-2036
Industrial Automation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Services Market Intelligence
Buyer concentration in automotive and semiconductor manufacturing is decoupling from traditional process industries as new entrants in battery cell production and biologics manufacturing fragment the client base. ABB leverages its robotics heritage to anchor large-scale deployments in electric vehicle battery assembly. Siemens sustains technology leadership through its digital twin platforms that integrate PLC and SCADA layers. Emerson Electric competes on process automation depth across oil refineries and chemical complexes where safety-system redundancy commands premium pricing.
Industrial automation services encompass the engineering, deployment, commissioning, and ongoing optimization of control systems, instrumentation, and software platforms that govern machine-level and plant-wide operations without continuous human intervention. These services typically involve configuring PLC cycle times below 10 milliseconds, calibrating SCADA historian databases for sub-second data logging, and tuning machine learning models for defect detection on high-speed production lines. Predictive maintenance services capture expanding margin pools as sensor density rises and OEMs shift from break-fix contracts to uptime-guarantee arrangements. Systems integration work is accelerating fastest where brownfield facilities must retrofit legacy DCS architectures with edge-computing nodes and cloud-connected analytics layers.
FDA validation requirements for automated systems in pharmaceutical manufacturing shape software documentation and change-control protocols that automation vendors must embed in their service deliverables. OSHA machine-guarding standards and the EU Machinery Directive mandate risk assessments before commissioning collaborative robot installations, extending project timelines but creating recurring compliance-audit revenue streams for qualified integrators. IEC 62443 cybersecurity frameworks for industrial control systems are becoming de facto prerequisites for contracts in power generation and water treatment sectors. Stakeholders must weigh whether to build in-house integration capabilities or deepen partnerships with vendors that certify engineers across multiple regulatory jurisdictions.
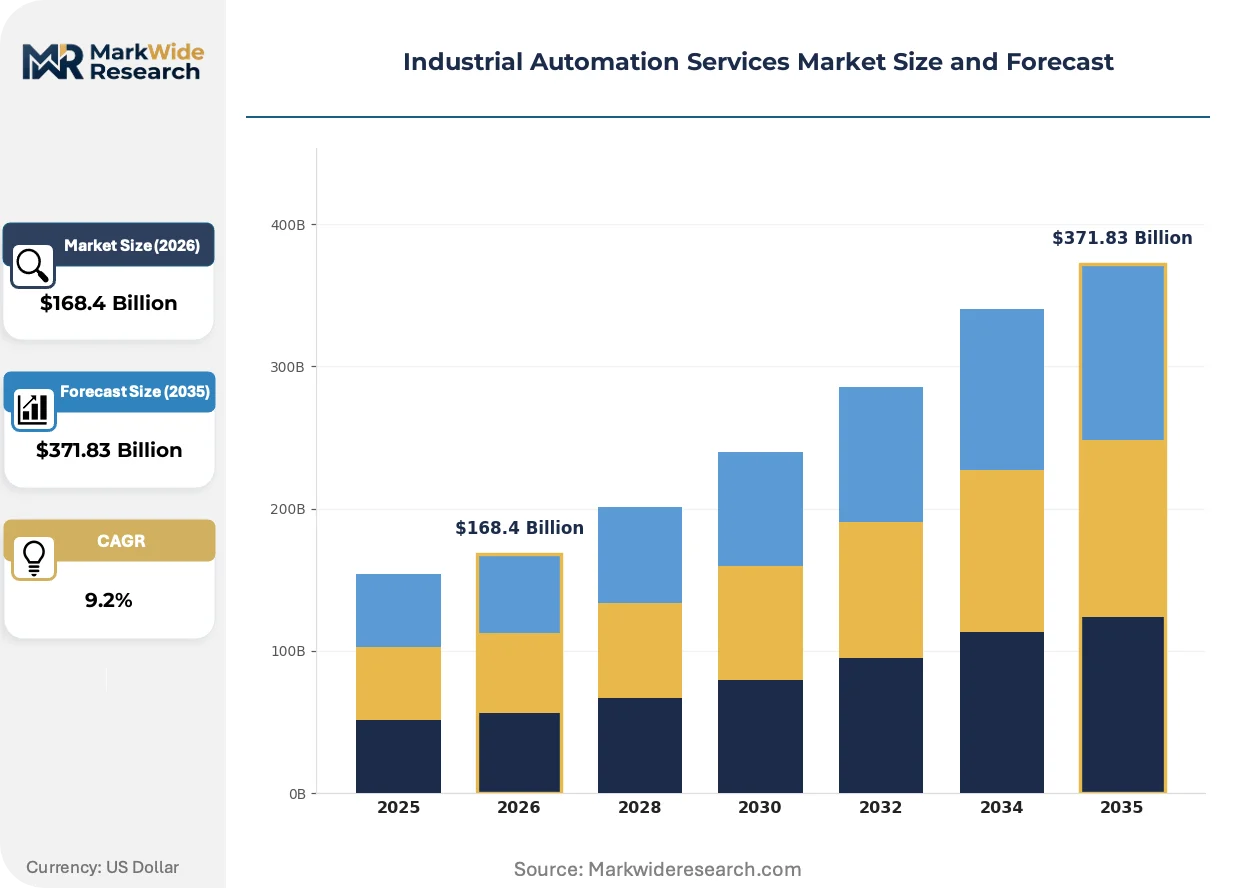
Market Dynamics
Automotive manufacturers are consolidating predictive maintenance contracts and robotics integration services into multi-year uptime-guarantee arrangements, compressing project margins for integrators while locking in recurring revenue streams that reshape competitive positioning in factory automation.
Growth Catalysts
- EU AI Act compliance mandates:European factories must certify autonomous systems before deployment, generating sustained demand for validation and documentation services from qualified automation vendors.
- Battery cell manufacturing expansion:Electric vehicle production lines in Germany and China require high-speed defect detection systems and synchronized robotic assembly cells.
- IEC 62443 cybersecurity frameworks:Power generation and water treatment sectors now require certified industrial control system hardening, creating contract prerequisites for service providers.
Market Restraints
- Semiconductor component volatility:PLC and edge-computing hardware lead times extend project commissioning schedules and inflate working capital requirements for systems integrators.
- Specialized engineering talent scarcity:Control systems programmers with dual expertise in legacy DCS architectures and cloud-connected analytics command premium compensation that erodes project margins.
- EU Machinery Directive risk assessments:Mandatory pre-commissioning safety evaluations for collaborative robot installations extend timelines by 8-14 weeks on average.
Strategic Opportunities
- Brownfield retrofit acceleration:Aging chemical complexes and oil refineries in the United States require edge-computing node integration without production line shutdowns.
- Pharmaceutical FDA validation services:Automated biologics manufacturing facilities demand software documentation and change-control protocols that create recurring compliance-audit revenue.
- Digital twin convergence with SCADA:Real-time simulation layers merging process historian data with predictive models enable new subscription-based optimization services.
Industry Challenges
- Multi-jurisdictional engineer certification:Service firms must maintain qualified personnel across OSHA machine-guarding standards, EU Machinery Directive requirements, and FDA validation protocols simultaneously.
- Legacy DCS-cloud integration complexity:Brownfield facilities operate proprietary communication protocols that resist standard edge-gateway connectivity without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Services Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $371.83 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Maintenance, Process Automation, Remote Monitoring, Systems Integration End User: Manufacturers, Warehouses, Oil Refineries, Power Plants Technology: SCADA, PLC, Robotics, Machine Learning Application: Energy Management, Quality Control, Inventory Management, Assembly Line |
| Companies Covered | ABB, Siemens, Emerson Electric, Rockwell Automation, Honeywell International, Schneider Electric, Mitsubishi Electric, Omron Corporation, Yokogawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Services Market Strategic Shifts & Innovations
Edge-computing architectures are displacing centralized SCADA hierarchies in high-speed production environments, compressing data latency from plant-floor sensors to sub-10 millisecond response windows for real-time defect intervention.
Digital twin platforms are consolidating PLC cycle-time optimization, SCADA historian analytics, and machine learning model training into unified software environments. Automotive battery assembly lines in Germany and China deploy these integrated stacks to synchronize robotic weld sequencing with thermal management systems. The technology is consolidating vendor relationships as manufacturers reduce separate software licensing contracts in favor of single-platform subscriptions.
The EU AI Act risk-classification framework is mandating conformity assessments for autonomous decision-making systems deployed in European factories. Machinery manufacturers must document algorithmic transparency and human oversight mechanisms before commissioning. High-risk applications in collaborative robotics and automated quality inspection face the steepest compliance burdens, driving demand for specialized validation engineering services.
Service contract structures are fragmenting from capital-intensive upfront system sales toward performance-linked uptime guarantees. Semiconductor fabs and pharmaceutical manufacturers in the United States now specify mean-time-between-failure thresholds and penalty clauses for unplanned downtime. Channel intermediaries face margin compression as OEMs build direct service relationships with end-users to capture recurring optimization revenue.
Industrial Automation Services Market Segmentation
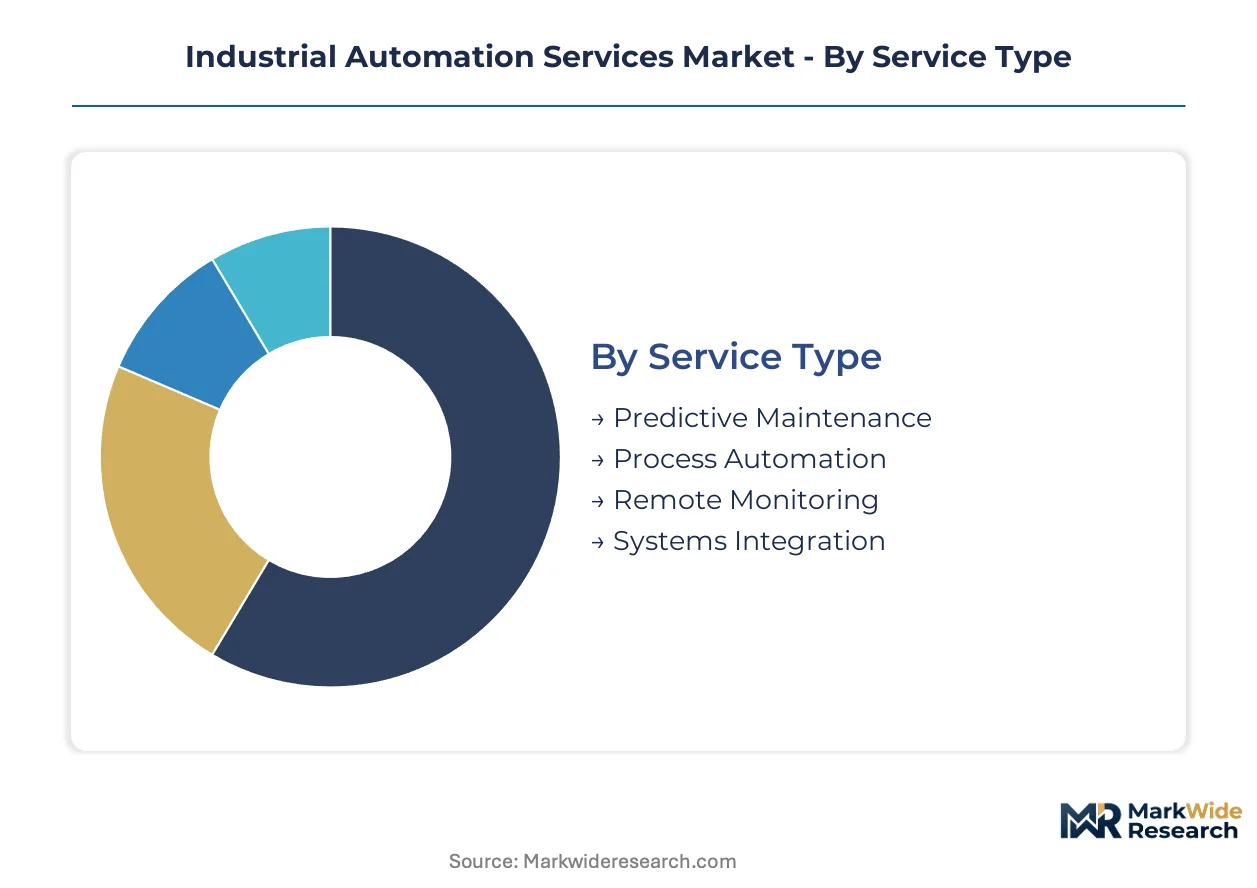
Industrial automation services fragment across technical capabilities, operational environments, and regulatory exposure zones. Buyers select service tiers based on asset criticality, downtime tolerance, and compliance burden rather than uniform technology specifications.
Service Type:
Predictive maintenance buyers prioritize uptime guarantees over capital expenditure, while systems integration purchasers seek brownfield retrofit expertise without production disruption.
- Predictive Maintenance:Sensor-driven failure forecasting services calibrate vibration analysis and thermal imaging algorithms to specific equipment fleets. Automotive battery manufacturers in Germany and China contract multi-year uptime arrangements as defect tolerance approaches zero in high-speed cell assembly.
- Systems Integration:Edge-computing node deployment and legacy DCS-cloud bridging demand engineers certified across IEC 62443 cybersecurity protocols and proprietary industrial communication standards. Oil refineries in the United States commission these services for non-disruptive retrofit of aging control architectures.
- Process Automation:Continuous loop tuning and batch control optimization for chemical and pharmaceutical manufacturing.
- Remote Monitoring:Cloud-connected SCADA historian access and alert management for distributed asset fleets.
Predictive maintenance leads volumes today; systems integration is gaining share fastest.
End User:
Operational intensity and regulatory scrutiny separate buyers more than scale or industry vertical alone.
- Manufacturers:Automotive and semiconductor producers demand sub-10 millisecond PLC cycle times synchronized with robotic weld sequencing and automated quality inspection. FDA validation requirements for biologics facilities in the United States shape software documentation protocols that automation vendors must embed in service deliverables.
- Oil Refineries:Safety-system redundancy and SIL-rated instrumentation calibration command premium pricing tiers. OSHA process safety management standards and EPA emissions monitoring mandates require specialized compliance engineering that extends project timelines.
- Power Plants:IEC 62443 cybersecurity hardening for critical infrastructure protection.
- Warehouses:Collaborative robot commissioning and automated storage retrieval system integration.
Manufacturers anchor current demand; oil refineries show the steepest expansion trajectory as brownfield retrofit accelerates.
Technology:
Latency requirements and data sovereignty concerns determine technology selection more than feature breadth.
- SCADA:Historian database configuration for sub-second data logging and operator interface customization. Water treatment facilities deploy these layers under IEC 62443 frameworks that mandate encrypted communication pathways between field devices and central control rooms.
- Robotics:Collaborative robot risk assessment and guarding verification per EU Machinery Directive requirements. Pre-commissioning safety evaluations extend project timelines by 8-14 weeks on average, creating recurring compliance-audit revenue for qualified integrators.
- PLC:Ladder logic programming and cycle-time optimization for deterministic control loops.
- Machine Learning:Defect detection model training on high-speed production line imagery.
SCADA dominates installed base; robotics is climbing the fastest as collaborative installations multiply.
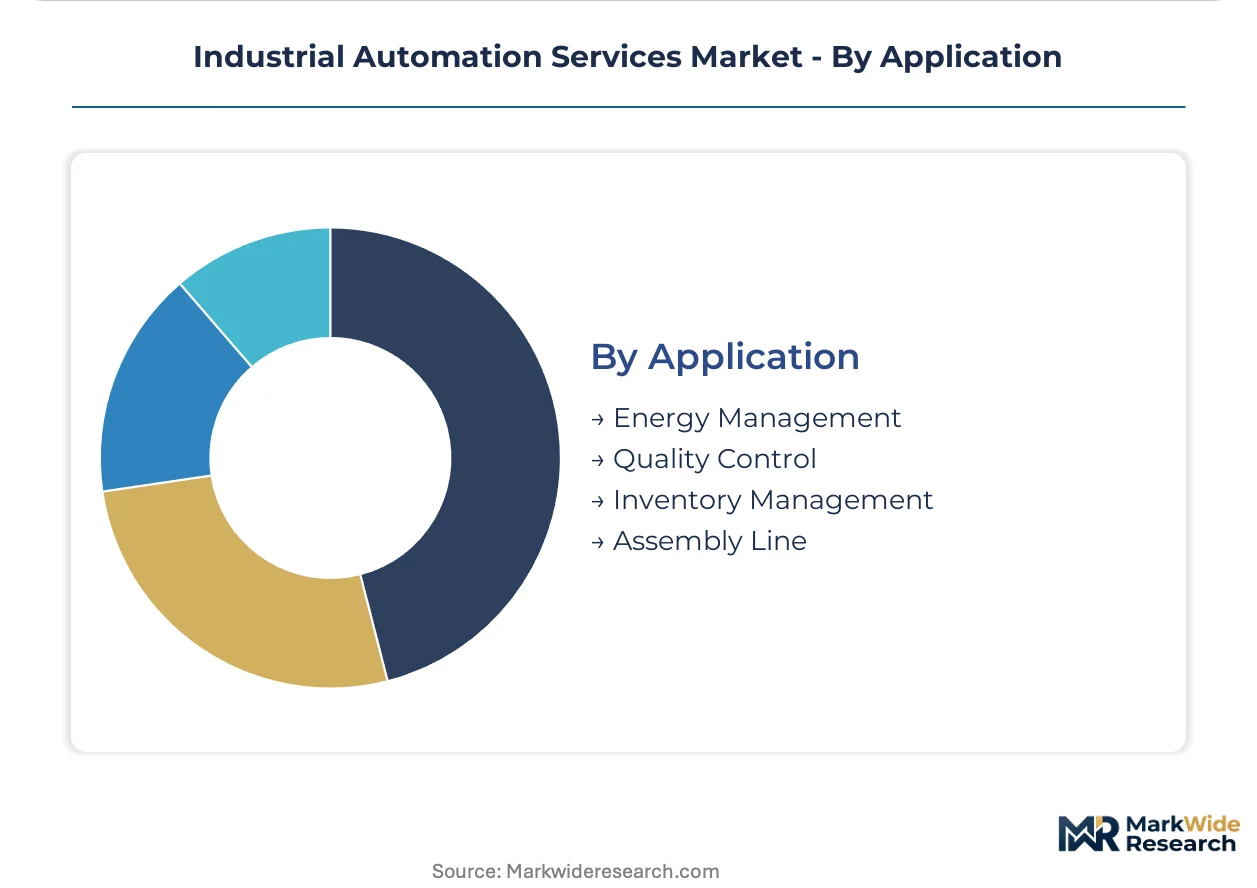
Application:
Margin capture varies by application based on performance metric measurability and penalty clause enforceability.
- Quality Control:Machine vision calibration and statistical process control integration for zero-defect manufacturing targets. Semiconductor fabs specify mean-time-between-failure thresholds with penalty clauses for unplanned downtime, compressing integrator margins while locking in recurring optimization revenue.
- Assembly Line:Robotic cell synchronization and throughput optimization for electric vehicle battery production. German and Chinese facilities deploy digital twin convergence layers merging process historian data with predictive models.
- Energy Management:Power consumption monitoring and demand response automation.
- Inventory Management:Automated tracking and warehouse management system integration.
Quality control commands premium pricing today; assembly line applications are expanding most quickly with battery manufacturing buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China are diverging in automation deployment patterns, with German factories prioritizing compliance-heavy retrofit services while Chinese facilities emphasize greenfield robotics integration at scale.
Germany
Automotive battery manufacturers in Stuttgart and Munich are commissioning synchronized robotic assembly cells for electric vehicle production lines. The EU AI Act and Machinery Directive mandate pre-deployment conformity assessments for autonomous quality inspection systems. The Baden-Württemberg industrial corridor anchors demand for validation engineering services as machinery OEMs document algorithmic transparency protocols.
China
Electric vehicle production facilities in Shanghai and Shenzhen require high-speed defect detection systems with sub-10 millisecond PLC response windows. MIIT cybersecurity standards and GB certification frameworks govern industrial control system deployments in critical manufacturing infrastructure. The Yangtze River Delta concentration of battery cell producers is fragmenting procurement patterns away from traditional systems integrators toward specialized robotics vendors.
United States
Oil refineries along the Gulf Coast and chemical complexes in Texas are retrofitting legacy DCS architectures with edge-computing nodes without production shutdowns. OSHA process safety management standards and EPA emissions monitoring mandates extend project timelines for safety-system redundancy upgrades. The Houston Ship Channel petrochemical cluster commands premium pricing tiers for SIL-rated instrumentation calibration services.
Japan
Semiconductor fabs in Kyushu and automotive plants in Nagoya are specifying mean-time-between-failure thresholds with penalty clauses for unplanned downtime. METI industrial cybersecurity guidelines and JIS standards shape procurement requirements for cloud-connected SCADA historian systems. The Chubu region's precision manufacturing base is consolidating vendor relationships around single-platform digital twin subscriptions.
India
Pharmaceutical manufacturers in Maharashtra and Gujarat are automating biologics production lines under FDA-aligned documentation protocols. The PLI scheme for advanced chemistry cell manufacturing is attracting automation service contracts for greenfield battery facilities. The Mumbai-Pune industrial belt is emerging as a compliance engineering hub where integrators certify engineers across multiple regulatory jurisdictions simultaneously.
Industrial Automation Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across contract tiers, with consolidated relationships in automotive and fragmented procurement in pharmaceutical manufacturing. European electrical engineering groups and Japanese factory automation houses anchor premium service tiers through captive hardware-software integration. Two strategic archetypes dominate: full-stack platform vendors bundling digital twin layers with maintenance contracts, and niche integrators capturing brownfield retrofit work through proprietary middleware expertise. Competitive moves center on multi-year uptime guarantee arrangements and cross-jurisdictional engineer certification programs.
Within the diversified conglomerate tier, ABB, Siemens, and Emerson Electric exemplify contrasting geographic and technological anchoring strategies. ABB leverages its Swiss-Swedish robotics heritage to anchor large-scale deployments in electric vehicle battery assembly across German and Chinese facilities. Siemens sustains technology leadership through its German-engineered digital twin platforms that integrate PLC and SCADA layers for process manufacturers. Emerson Electric occupies a position in North American process automation depth, commanding premium pricing across oil refineries and chemical complexes where safety-system redundancy requirements dominate procurement criteria.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Emerson Electric |
| Rockwell Automation |
| Honeywell International |
| Schneider Electric |
| Mitsubishi Electric |
| Omron Corporation |
| Yokogawa Electric |
| Others |
Cost & Logistics Intelligence
Copper and rare-earth magnet price indices cascade through industrial automation supply chains, compressing margins on PLC and servo-motor assemblies while amplifying cost differentials between certified IEC 62443 integrators and uncertified competitors. German and Chinese battery manufacturers absorb these input swings through multi-year uptime-guarantee contracts that lock in service pricing tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for robotics integration services, forcing European incumbents to defend premium positioning through IEC 62443 certification bundling. Three-tier pricing structure across premium, standard, and economy levels separates safety-system redundancy specialists from commodity SCADA configurators. Cost compression in mid-tier systems integration is intensifying because semiconductor component lead times extend project working capital cycles. Pharmaceutical manufacturers show least price sensitivity due to FDA validation requirements, while warehouse operators exhibit highest elasticity on collaborative robot deployments.
Supply Chain Analysis
Refurbishment flows for legacy DCS controllers and remanufactured servo drives are creating secondary supply channels that undercut OEM spare-part pricing. Component sourcing concentrates in Germany, Japan, and Taiwan for precision motion controllers, while edge-computing hardware draws from South Korean and Chinese semiconductor fabs. Supply chain risk centers on single-source vulnerability for SIL-rated safety instrumented systems. Distribution runs through authorized systems integrator networks that maintain certified engineer rosters across multiple regulatory jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial automation services function as a stable compounder anchored by irreversible brownfield retrofit demand and tightening regulatory compliance burdens that deepen vendor switching costs.
For Market Incumbents: Cement technology leadership through captive digital twin platform development that merges PLC, SCADA, and machine learning layers into unified subscription stacks. Defend against emerging pure-play robotics specialists by deepening backward integration into edge-computing hardware design. Prioritize cross-jurisdictional engineer certification programs spanning OSHA machine-guarding standards, EU Machinery Directive requirements, and FDA validation protocols. For New Entrants and Emerging Players: Cloud-native remote monitoring platforms offer the lowest barrier-to-entry route for capturing pharmaceutical and water treatment accounts seeking IEC 62443-compliant SCADA historian access without legacy infrastructure overhaul. Target India's PLI-subsidized battery cell manufacturing corridor where procurement patterns remain fragmented and specialized integrators can bypass established vendor relationships. Lead with outcome-based uptime guarantees rather than capital-intensive system sales. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier systems integrators possessing proprietary middleware expertise for legacy DCS-cloud bridging. Long-term viability hinges on recurring revenue share from compliance-audit services rather than one-time project margins. Watch for inflection when battery manufacturers consolidate procurement around single-platform digital twin subscriptions, signaling vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Engineer Certification Program | Unlocks EU AI Act and FDA validation service contracts that competitors cannot bid. |
| Proprietary Edge-Computing Middleware Development | Captures brownfield retrofit work where legacy DCS protocols resist standard gateway connectivity. |
| Digital Twin Platform Integration | Consolidates vendor relationships as manufacturers reduce separate software licensing contracts. |
| Uptime-Guarantee Contract Structuring | Locks in recurring revenue streams and reshapes competitive positioning against break-fix competitors. |
| Cybersecurity Hardening Service Line | Addresses IEC 62443 prerequisites now mandatory in power generation and water treatment procurement. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation against SEC filings, customs and trade data, IEC standards documentation, and hyperscaler industrial IoT capex disclosures. Bottom-up project pipeline aggregation and top-down macroeconomic factor weighting were triangulated to anchor market sizing.
Comparable-period anchoring linked historical automation service contract volumes to forward projection assumptions across the analysis window. Segmentation dimensions modeled include service type, end-user industry, technology layer, and application criticality. CAGRs were derived from regression-weighted growth rate convergence across geographic clusters, with specific inputs including electric vehicle battery manufacturing capacity announcements and pharmaceutical FDA 483 observation trends.
Semiconductor component availability, regulatory enforcement intensity variations, and battery manufacturing capital commitment delays are the dominant revision risks. Forecasts reflect documented assumptions regarding brownfield retrofit acceleration rates and compliance timeline extensions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Process Automation Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Europe ICS Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Grippers Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Industrial Fieldbus Solution Market