
 Low-Fat Low-Calorie Desserts Market | 2026-2036
Low-Fat Low-Calorie Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Low-Calorie Desserts Market Foresight
Asset-light co-manufacturing partnerships are tilting competitive dynamics toward brands that outsource production while retaining formulation control. Danone leverages its dairy infrastructure and probiotic expertise to dominate refrigerated yogurt-based desserts across European retail channels. Unilever competes through global freezer-network scale that sustains ice cream distribution in emerging markets. Nestlé differentiates via in-house sweetener R&D pipelines that reduce caloric density without taste trade-offs.
Low-fat low-calorie desserts are formulated food products containing reduced lipid content, typically under 3 grams of fat per serving, and diminished energy density achieved through sugar substitution, aeration, or bulking agents such as soluble fiber and sugar alcohols. These products serve commercial food service and retail channels seeking to satisfy indulgence-oriented consumption within regulated or self-imposed dietary constraints. Yogurts lead volume share among product types due to established consumer acceptance of tart flavor profiles and live-culture health claims, while ice creams represent the fastest-growing segment as overrun technology and fat-mimetic emulsifiers improve mouthfeel. Natural sweeteners command premium shelf positioning, though dairy alternatives are accelerating as oat and coconut bases resolve previous texture limitations in frozen formats.
The FDA governs nutrient-content claims and serving-size declarations, while the European Food Safety Authority evaluates novel sweetener approvals that determine formulation options across EU member states. Health Canada and the FSSAI in India impose parallel labeling standards that exporters must navigate for market access, creating compliance complexity for multi-territory portfolios. Stakeholders must monitor evolving sweetener safety assessments and front-of-pack warning label expansions that could disqualify current formulations from preferred retail placement.
Market Dynamics
Reformulation pressures from front-of-pack labeling mandates are compressing product development cycles while expanding R&D budgets across the category. Manufacturers must now validate taste-equivalence under accelerated timelines as regulatory disclosure requirements tighten in multiple jurisdictions simultaneously.
Growth Catalysts
- FDA Nutrition Facts Modernization:Updated serving-size rules and added-sugar line-item disclosure push manufacturers toward cleaner label architectures that favor low-calorie positioning.
- Quick-service restaurant penetration:Institutional food service channels now designate reduced-fat desserts as standard menu components, creating captive volume pipelines.
- Aeration and overrun advances:Fat-mimetic emulsifiers and controlled air-injection systems improve mouthfeel in frozen applications without caloric penalty.
Market Restraints
- Novel sweetener approval bottlenecks:EFSA safety evaluations and FDA GRAS determinations for emerging sugar alcohols create multi-year formulation lock-in periods.
- Dairy input concentration:Specialized milk protein and yogurt culture supply chains cluster in Northern European cooperatives, exposing margin pressure from agricultural commodity swings.
- Texture-performance ceiling:Current soluble fiber bulking agents hit viscosity limits in high-overrun ice cream applications, constraining caloric reduction depth.
Strategic Opportunities
- Direct-to-consumer subscription channels:Refrigerated logistics networks now support recurring delivery of fresh yogurt-based desserts outside traditional retail placement.
- EU Green Deal procurement standards:Public sector cafeteria contracts increasingly require sustainability-certified ingredient sourcing, favoring reformulated low-fat portfolios.
- Oat and coconut base convergence:Dairy alternative frozen desserts resolve previous crystallization defects through enzymatic hydrolysis, opening vegan-adjacent positioning.
Industry Challenges
- Cross-jurisdictional label compliance:Simultaneous adherence to FDA, EFSA, and Health Canada serving-size protocols fragments packaging runs and extends SKU proliferation.
- Sensory scientist scarcity:Specialized formulation talent capable of balancing caloric reduction with hedonic rating targets commands premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Low-Calorie Desserts Market |
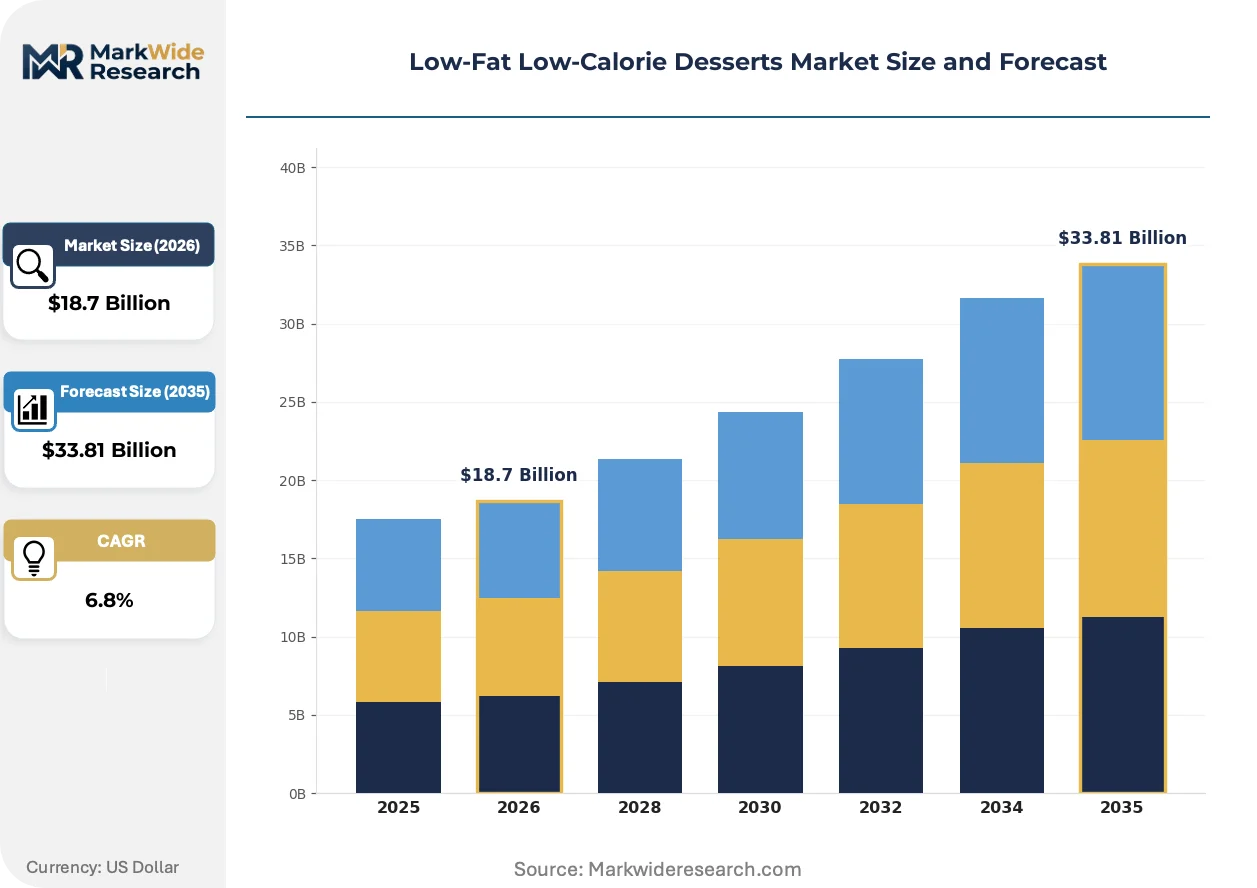
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurts, Puddings, Cakes, Ice Creams Ingredient Type: Natural Sweeteners, Artificial Sweeteners, Dairy Alternatives, Fruit Bases Delivery Mode: Retail, Online, Food Service, Subscription Target Demographic: Health-Conscious Consumers, Diabetics, Fitness Enthusiasts, Weight Watchers |
| Companies Covered | Danone, Mondelez International, Pinnacle Foods Group, Stanmar International, Unilever, General Mills, J&J Snack Foods, The Jel Sert Company, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Low-Calorie Desserts Market Shifts & Advancements
Sweetener technology and regulatory disclosure frameworks are converging to reshape competitive advantage around speed-to-formulation rather than manufacturing scale alone. The category is witnessing accelerated substitution of traditional sucrose with novel polyols and rare sugars.
Fat-mimetic emulsifier systems derived from modified starches and protein micelle structures are hybridizing with controlled aeration protocols. Quick-service restaurant chains and institutional buyers are piloting these formulations in frozen dessert lines. The technology is compressing the taste-calorie trade-off window that previously constrained product positioning.
EFSA's expanded novel food assessments and the EU's front-of-pack Nutri-Score mandates are tightening permissible formulation architectures. Manufacturers face compressed development timelines to secure safety opinions before competitor product launches. Refrigerated yogurt segments face the steepest compliance burden given live-culture health claim substantiation requirements.
Subscription-based replenishment models are displacing impulse freezer-aisle purchases among health-conscious households. Direct-to-consumer channels capture recurring revenue through curated low-calorie dessert assortments. United States metropolitan markets exhibit the strongest channel shift velocity as cold-chain logistics density enables reliable home delivery.
Low-Fat Low-Calorie Desserts Market Segmentation
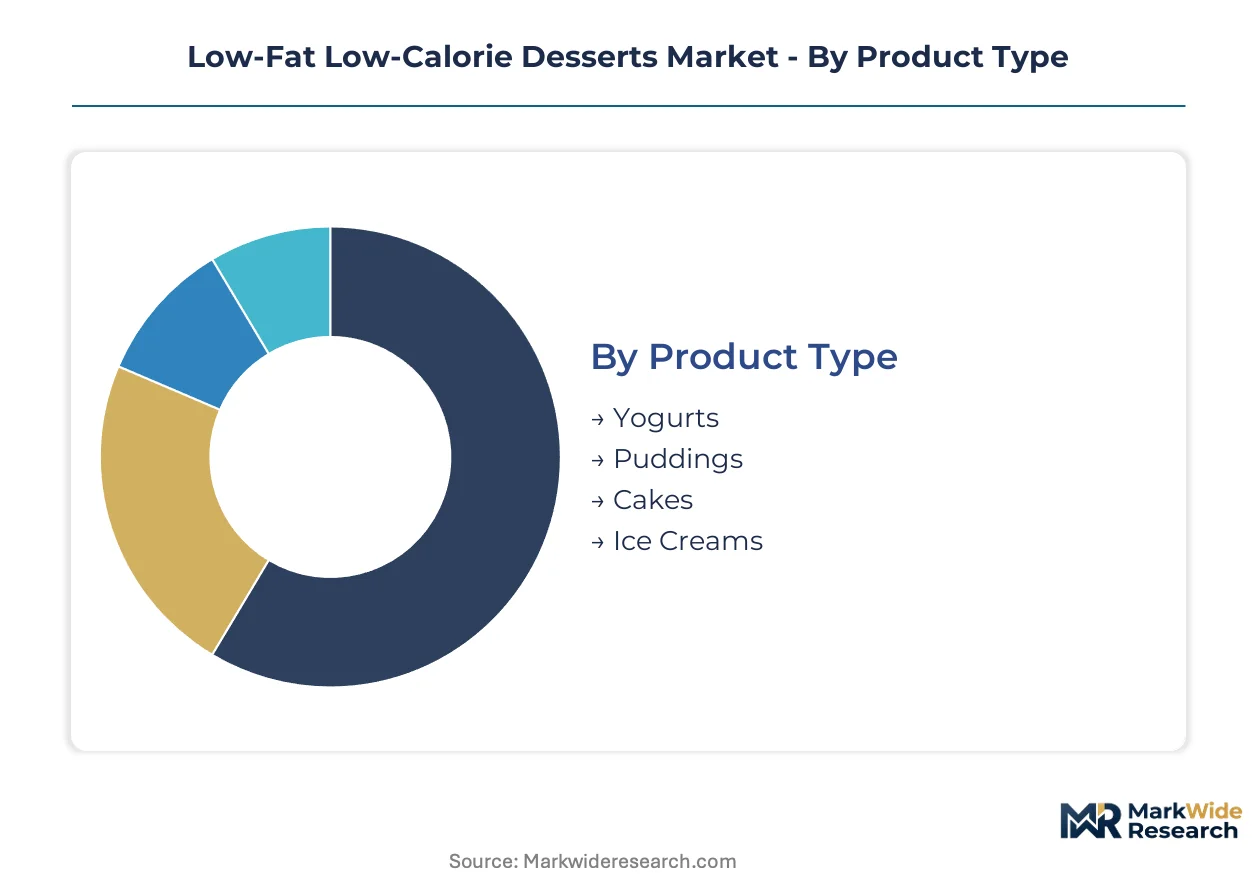
Segmentation in low-fat low-calorie desserts determines formulation priorities, cold-chain investment, and channel-specific packaging formats. Manufacturers align R&D spend with the technical requirements of each product type and delivery mode to capture recurring purchase behavior.
Product Type:
After-sales service intensity varies sharply across frozen versus refrigerated formats, with ice cream requiring sustained freezer-network maintenance and yogurt demanding live-culture freshness guarantees.
- Yogurts:Fermented dairy bases with live cultures deliver tart flavor profiles that mask reduced sugar content. Demand concentrates in United States metropolitan markets where direct-to-consumer subscription channels accelerate weekly replenishment cycles.
- Ice Creams:Overrun technology and fat-mimetic emulsifiers achieve creamy mouthfeel without caloric density. Quick-service restaurant chains in the United States pilot these formulations as standard menu components, creating captive institutional volume.
- Puddings:Starch-thickened or protein-gelled desserts serve retail shelf-stable placement with lower cold-chain burden.
- Cakes:Aerated sponge formulations with soluble fiber bulking agents target celebratory occasions within calorie-controlled diets.
Yogurts hold the largest share; momentum sits with ice creams.
Ingredient Type:
Cost tier stratification separates premium-positioned natural formulations from commodity-scale artificial alternatives, with dairy alternatives commanding mid-tier pricing as enzymatic processing improves.
- Natural Sweeteners:Stevia, monk fruit, and allulose command premium shelf positioning due to clean-label appeal. European Union retailers favor these formulations under EFSA novel food assessments and Nutri-Score disclosure mandates.
- Dairy Alternatives:Oat and coconut bases resolve previous crystallization defects through enzymatic hydrolysis. United States vegan-adjacent positioning drives fastest expansion as oat protein isolates achieve neutral flavor.
- Artificial Sweeteners:Sucralose and aspartame formulations serve price-sensitive retail segments with established regulatory approval.
- Fruit Bases:Puree concentrates and fiber-enhanced fruit preparations deliver bulk with inherent sweetness reduction.
Natural sweeteners dominate premium placement; dairy alternatives are expanding most quickly.
Delivery Mode:
Volume concentration shifts toward recurring subscription models as refrigerated logistics density enables reliable home delivery outside traditional retail placement.
- Subscription:Curated assortments of fresh yogurt-based desserts capture recurring revenue through automated replenishment. United States metropolitan markets exhibit strongest channel shift velocity as cold-chain infrastructure matures.
- Food Service:Institutional cafeterias and quick-service restaurants designate reduced-fat desserts as standard menu components, creating high-volume pipelines with specification-driven procurement.
- Retail:Supermarket freezer and dairy aisle placement remains volume anchor for impulse and planned purchases.
- Online:Third-party delivery platforms aggregate single-serve frozen desserts with expedited last-mile cooling.
Food service holds the largest share; subscription is gaining share fastest.
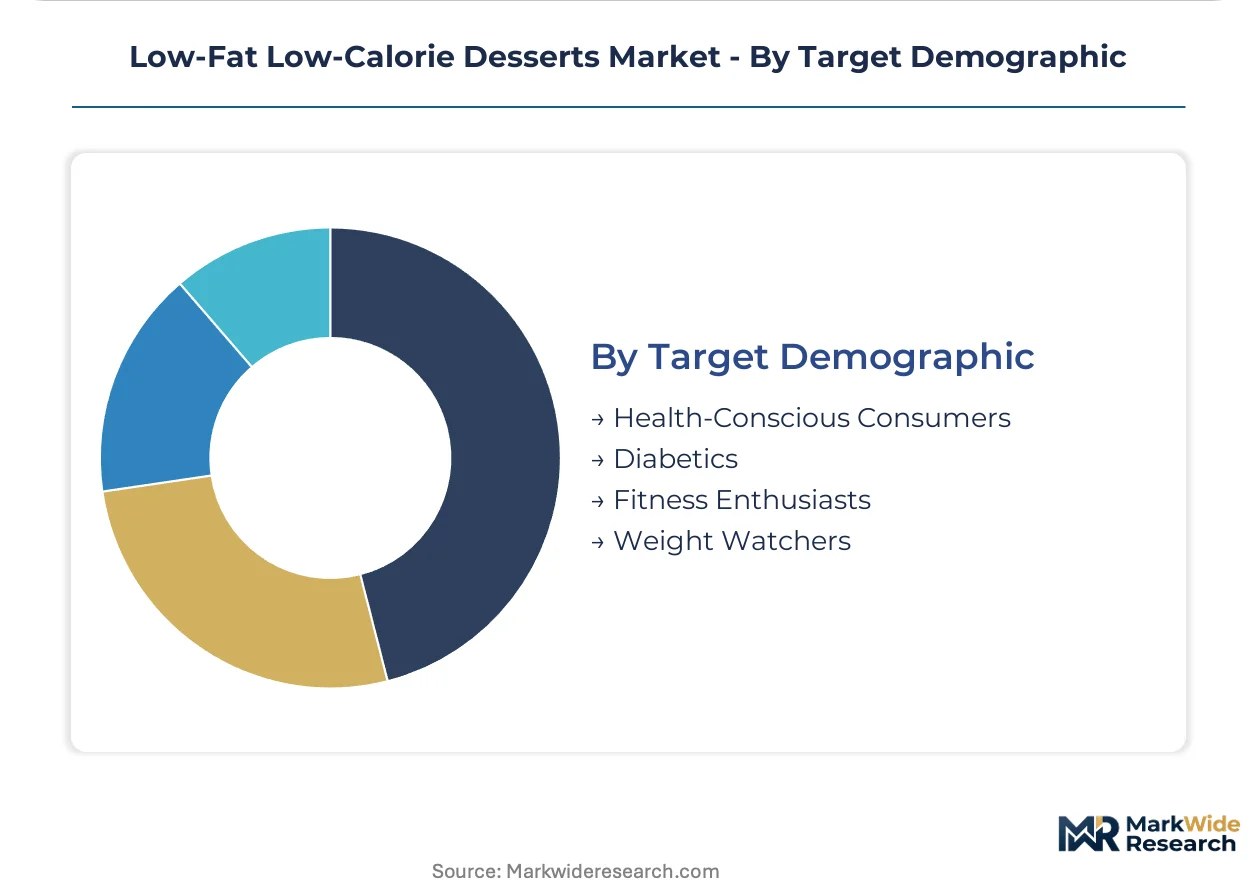
Target Demographic:
Customer type determines messaging architecture, with health-conscious consumers responding to clean-label claims and diabetics requiring glycemic index substantiation.
- Health-Conscious Consumers:Broad demographic seeking indulgence within self-imposed dietary constraints drives mass-market formulation. FDA Nutrition Facts modernization and added-sugar line-item disclosure push this segment toward verified low-calorie positioning.
- Weight Watchers:Calorie-counting behavior aligns with portion-controlled single-serve packaging and front-of-pack disclosure.
- Diabetics:Glycemic management requirements demand sugar alcohol and rare sugar formulations with clinical substantiation.
- Fitness Enthusiasts:High-protein dessert positioning targets post-workout recovery occasions with macronutrient transparency.
Health-conscious consumers hold the largest share; fitness enthusiasts show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where subscription channels command premium positioning, while European markets face margin compression from EFSA novel sweetener approval delays and Nutri-Score disclosure mandates.
United States
Direct-to-consumer subscription channels capture recurring revenue through curated yogurt-based assortments delivered via maturing cold-chain infrastructure in metropolitan markets. FDA Nutrition Facts modernization and added-sugar line-item disclosure push manufacturers toward cleaner label architectures. Quick-service restaurant chains in the Southeast and California designate reduced-fat desserts as standard menu components, creating captive institutional volume pipelines.
Germany
Live-culture yogurt segments face steep compliance burdens under EFSA health claim substantiation requirements and EU Green Deal procurement standards for public sector cafeterias. Northern European dairy cooperatives cluster specialized milk protein and yogurt culture supply chains, exposing margins to agricultural commodity swings. Berlin and Hamburg anchor retail innovation in sustainability-certified ingredient sourcing.
France
EFSA novel food assessments and front-of-pack Nutri-Score mandates tighten permissible formulation architectures for frozen dessert lines. Natural sweetener formulations command premium shelf positioning in Parisian retail channels. The Île-de-France region concentrates R&D activity for enzymatic hydrolysis of oat bases resolving crystallization defects in dairy alternatives.
United Kingdom
Health-conscious consumers in Greater London respond to clean-label claims driving mass-market formulation shifts. Post-Brexit regulatory divergence from EU sweetener approvals creates formulation lock-in complexity for multi-territory portfolios. Manchester and Birmingham clusters specialize in aeration technology improving mouthfeel in high-overrun ice cream applications.
India
FSSAI labeling standards impose parallel compliance requirements that exporters must navigate for market access. Dairy alternative expansion accelerates as urban consumers adopt vegan-adjacent positioning in Mumbai and Delhi-NCR metropolitan markets. Quick-service restaurant penetration in Bangalore and Hyderabad creates emerging institutional volume for reduced-fat dessert categories.
Low-Fat Low-Calorie Desserts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying emulsifier systems and novel sweetener inputs. The vendor base stratifies across global freezer-network operators, refrigerated dairy infrastructure holders, and in-house R&D pipeline owners. Three archetypes dominate: asset-light brands outsourcing production while retaining formulation control, vertically integrated dairy conglomerates leveraging captive supply chains, and sweetener technology licensors monetizing patent estates. Competitive moves concentrate on co-manufacturing partnerships and direct-to-consumer channel capture.
Among global packaged goods conglomerates, Danone, Unilever, and Nestlé occupy positions across the competitive spectrum. Danone exemplifies the dairy-integrated archetype with refrigerated infrastructure spanning European retail channels. Unilever represents freezer-network scale sustaining ice cream distribution in emerging markets. Nestlé anchors the in-house R&D tier with proprietary sweetener pipelines reducing caloric density. These three entities illustrate how formulation control, manufacturing scale, and distribution reach combine into distinct competitive positions.
| Leading Market Players |
|---|
| Danone |
| Mondelez International |
| Pinnacle Foods Group |
| Stanmar International |
| Unilever |
| General Mills |
| J&J Snack Foods |
| The Jel Sert Company |
| Nestlé |
| Others |
Supply & Pricing Matrix
Northern European dairy cooperatives in Denmark and the Netherlands concentrate specialized milk protein and yogurt culture production, translating upstream agricultural commodity exposure into downstream margin volatility for finished dessert pricing. FDA Nutrition Facts modernization and EU front-of-pack disclosure mandates compress formulation windows while co-manufacturing partnerships fragment cost structures across asset-light brands.
Pricing Analysis
Configured-to-order pricing for customized clean-label formulations commands 15-25% premiums over standard artificial-sweetener SKUs in United States subscription channels. Three-tier pricing structure across premium natural-sweetener, standard dairy-alternative, and economy artificial-sweetener levels stratifies the category. Cost compression in the economy tier intensifies because of commodity sucralose oversupply and private-label encroachment. Quick-service restaurant procurement teams exhibit highest price sensitivity due to specification-driven volume tenders, while direct-to-consumer subscribers show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Contract-manufacturing concentration sits with dairy-integrated processors in France and Germany alongside specialized frozen-dessert co-packers in the United States Midwest. Raw material dependencies center on stevia leaf extract from China, allulose from corn starch supply chains, and specialized whey protein isolates from Irish and New Zealand processing facilities. Single-source vulnerability in novel sweetener approvals creates formulation lock-in risk as EFSA safety evaluations extend development timelines. Distribution runs through refrigerated logistics networks serving retail dairy aisles, institutional food service channels, and emerging direct-to-consumer cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-fat low-calorie desserts constitute a high-growth disruption as aeration technology and rare-sugar formulations collapse the historical taste-calorie trade-off. FDA added-sugar disclosure mandates and EU Nutri-Score expansion accelerate clean-label substitution cycles.
For Market Incumbents: Harden formulation IP through accelerated novel-sweetener patent filings before EFSA approval windows close to competitors. Deepen backward integration into specialized milk protein supply from Northern European cooperatives to defend margin position against agricultural commodity swings. Co-manufacturing partnership exclusivity clauses in United States refrigerated logistics networks represent a critical defensive lever against subscription-channel entrants.
For New Entrants and Emerging Players: Mid-market food service contracts in India and Southeast Asia represent the most penetrable entry point given underdeveloped reduced-fat dessert penetration and FSSAI compliance complexity deterring multinational incumbents. Direct-to-consumer oat-based frozen dessert subscriptions in United States metropolitan markets offer second-mover advantage through enzymatic hydrolysis positioning. Go-to-market execution should anchor on sustainability-certified ingredient sourcing narratives aligned with EU Green Deal procurement standards.
For Investors and Strategic Acquirers: Long-term, this sits as a formulation-control play because competitive advantage migrates from manufacturing scale toward speed-to-sweetener-approval and sensory-science talent retention. Acquisition targets should screen for in-house rare-sugar R&D pipelines and live-culture health claim substantiation capabilities. The signal to watch is EFSA novel food opinion issuance velocity for emerging polyols, which will determine which formulation portfolios achieve preferred retail placement.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Refrigerated logistics density in United States metropolitan markets enables recurring revenue capture outside traditional retail. |
| Novel Sweetener Pipeline Investment | Proprietary allulose and rare-sugar R&D accelerates FDA GRAS determinations ahead of competitor formulations. |
| Co-Manufacturing Partnership Expansion | Asset-light production outsourcing preserves capital for formulation control while accessing specialized freezer-network scale. |
| Sustainability Certification Program | EU Green Deal procurement standards for public sector cafeterias favor certified low-fat dessert portfolios. |
| Quick-Service Restaurant Specification Capture | Institutional menu component designation creates captive volume pipelines with multi-year contract visibility. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at packaged goods conglomerates, category buyers at United States quick-service restaurant chains, supply planners at dairy cooperatives, and sensory scientists at formulation laboratories, then refined through secondary validation. FDA GRAS determination databases, EFSA novel food assessment registers, Nielsen retail audit data, and SEC 10-K filings from publicly traded food manufacturers anchored quantitative triangulation. Bottom-up volume modeling across subscription, food service, retail, and online channels converged with top-down macro consumption trend analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, ingredient category, delivery mode, and target demographic. CAGRs were derived from iterative convergence of historical consumption elasticity, regulatory approval pipeline velocity, and cold-chain infrastructure deployment curves. Forecast inputs incorporated live-culture health claim substantiation timelines and enzymatic hydrolysis technology adoption rates in dairy alternative processing.
Practitioners should monitor EFSA novel sweetener safety opinion issuance, FDA serving-size rule enforcement actions, and agricultural commodity price volatility for early signals of forecast revision. Assumptions underlying projections reflect current regulatory disclosure trajectories and cold-chain logistics maturation curves. Quarterly review of front-of-pack labeling mandate expansions and co-manufacturing capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Luxury Cigar Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Zhacai Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Thai Cuisine Market