
 Grain-Free Pet Food Market | 2026-2036
Grain-Free Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Grain-Free Pet Food Market Outlook
Cold-press extrusion at lower thermal thresholds is reconfiguring protein retention in grain-free kibble manufacturing. Champion Petfoods leverages this thermal profile to sustain nutrient density across its freeze-dried and baked product lines. Mars Petcare anchors its volume position through veterinary-exclusive grain-free formulations distributed through clinic networks. Blue Buffalo Company differentiates via LifeSource Bits inclusion systems that compete on antioxidant positioning in premium dry food.
Grain-free pet food excludes cereal grains such as wheat, corn, and rice, substituting alternative carbohydrate sources like sweet potatoes, peas, and lentils while maintaining amino acid profiles through elevated animal protein inclusion; formulations typically target digestibility coefficients above 85 percent to support gastrointestinal tolerance in carnivore-optimized diets. Dry food dominates volume throughput due to shelf stability and logistics efficiency, though wet food concentrates margin pools through higher per-unit pricing and veterinary channel placement. Online retail captures the fastest expansion trajectory as subscription models and direct-to-consumer platforms reshape repurchase behavior for specialized ingredient-source formulations.
The FDA Center for Veterinary Medicine enforces nutritional adequacy claims under AAFCO feeding trial or formulation standards, while state agriculture departments conduct label audits and contaminant surveillance that shape market access requirements. European entrants face REACH-aligned feed additive scrutiny and EFSA novel protein assessments that extend registration timelines. Stakeholders must monitor evolving FDA guidance on dilated cardiomyopathy correlations and adapt formulation architectures ahead of potential ingredient disclosure mandates.
Market Dynamics
Cold-press extrusion technology is compressing thermal degradation losses in grain-free kibble production while FDA dilated cardiomyopathy investigations force formulation transparency across amino acid disclosure protocols.
Growth Catalysts
- Veterinary channel endorsement:Clinic-exclusive distribution networks deepen consumer trust in therapeutic grain-free positioning for dogs with food sensitivities.
- AAFCO feeding trial protocols:Nutritional adequacy substantiation through standardized testing expands premium shelf access in US specialty retail.
- Lentil and pea protein concentrates:Alternative carbohydrate sourcing achieves cost parity with legacy grain inputs while maintaining glycemic indices below 35.
Market Restraints
- Animal protein input volatility:Chicken meal and fish meal spot markets swing 15-40% seasonally, compressing gross margins on fixed-price subscription contracts.
- Midwestern US rendering concentration:Four states supply 60% of domestic meat and bone meal, creating geographic vulnerability to climate-driven feedstock disruptions.
- FDA DCM correlation studies:Ongoing investigations into taurine deficiency links delay new product launches pending longitudinal cardiac health data.
Strategic Opportunities
- Insect protein integration:Black soldier fly larvae meal offers complete amino acid profiles with 90% lower land use than poultry farming.
- Direct-to-consumer subscription platforms:Customized portion algorithms based on breed, weight, and activity level capture lifetime value through auto-replenishment.
- European novel protein pathways:EFSA streamlined assessments for cultured meat ingredients accelerate regulatory clearance timelines relative to traditional approval tracks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in alternative carbohydrate rheology and extrusion die design commands 40% wage premiums over conventional pet food R&D.
- Legacy ERP integration:Batch-level traceability requirements for FDA adverse event reporting strain systems built for commodity grain tracking rather than ingredient-level serialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain-Free Pet Food Market |
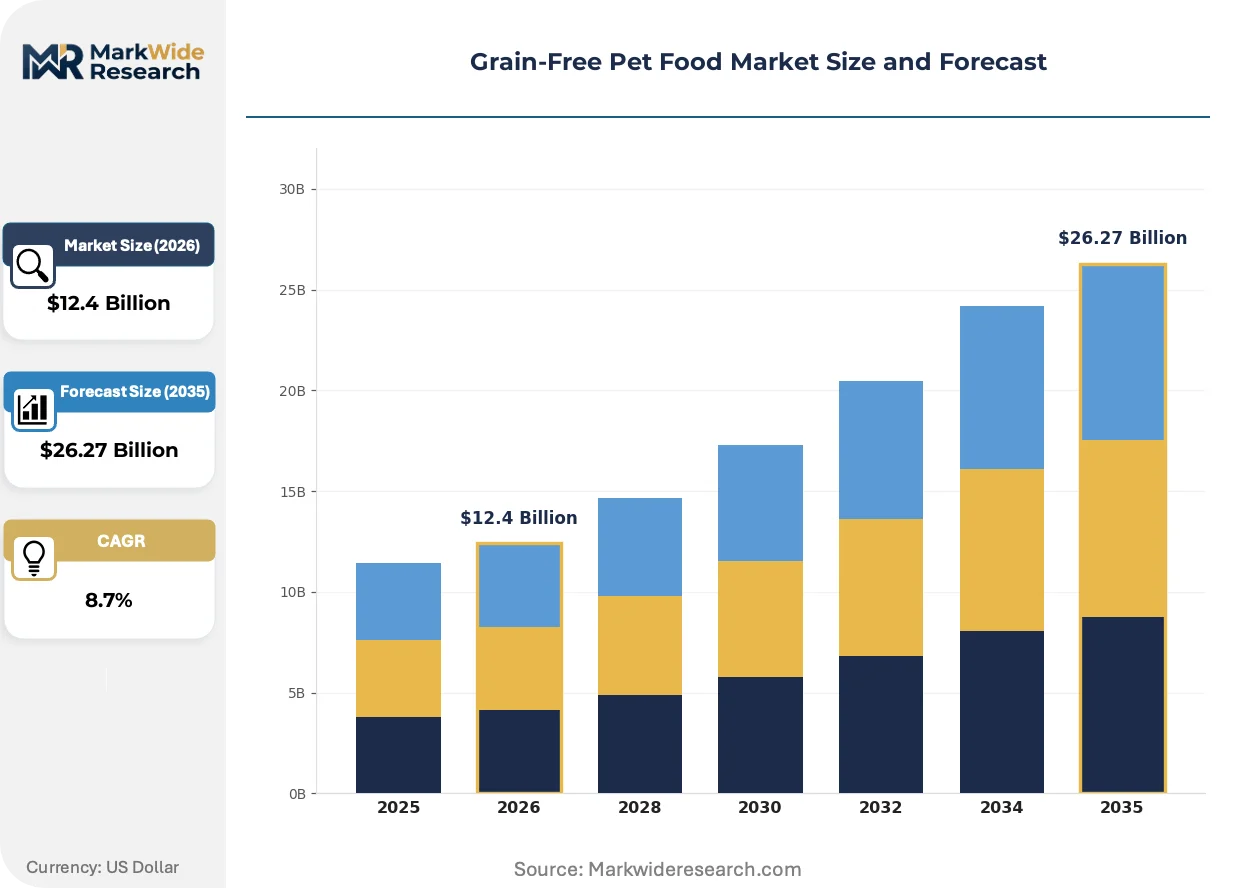
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Animal Protein, Vegetable Protein, Legumes, Fruits Target Animal: Cats, Dogs, Small Animals, Birds Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Veterinarians |
| Companies Covered | Nestle Purina PetCare, Mars Petcare, Blue Buffalo Company, WellPet LLC, The J.M. Smucker Company, Champion Petfoods, Diamond Pet Foods, Canidae Natural Pet Food Company, Farmina Pet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain-Free Pet Food Market Strategic Shifts
Thermal processing architectures and distribution channel structures are undergoing parallel reconfiguration as manufacturers balance nutrient preservation against throughput economics.
High-moisture extrusion is migrating from niche freeze-dried applications toward mainstream kibble production as Champion Petfoods and mid-tier co-packers adopt twin-screw systems operating below 90°C. Premium dog-owning households now accept 15-20% price premiums for cold-processed labels. Protein digestibility coefficients above 90% are compressing the performance gap between traditional baked formats and raw-frozen alternatives.
EFSA novel protein assessments are tightening documentation requirements for alternative carbohydrate sources entering European feed chains. Manufacturers must submit 90-day toxicity studies and allergenicity profiles before market authorization. Wet food formulations containing pea protein isolates face extended review timelines, pushing R&D investment toward established geographies with clearer regulatory pathways.
Subscription auto-replenishment is displacing brick-and-mortar repurchase cycles as Chewy and direct-brand platforms capture 35% of premium grain-free volume. Breed-specific algorithmic feeding recommendations replace generic weight-based portion guidance. Urban households in coastal US metro areas show highest adoption of automated delivery schedules synchronized with veterinary wellness exam intervals.
Grain-Free Pet Food Market Segmentation
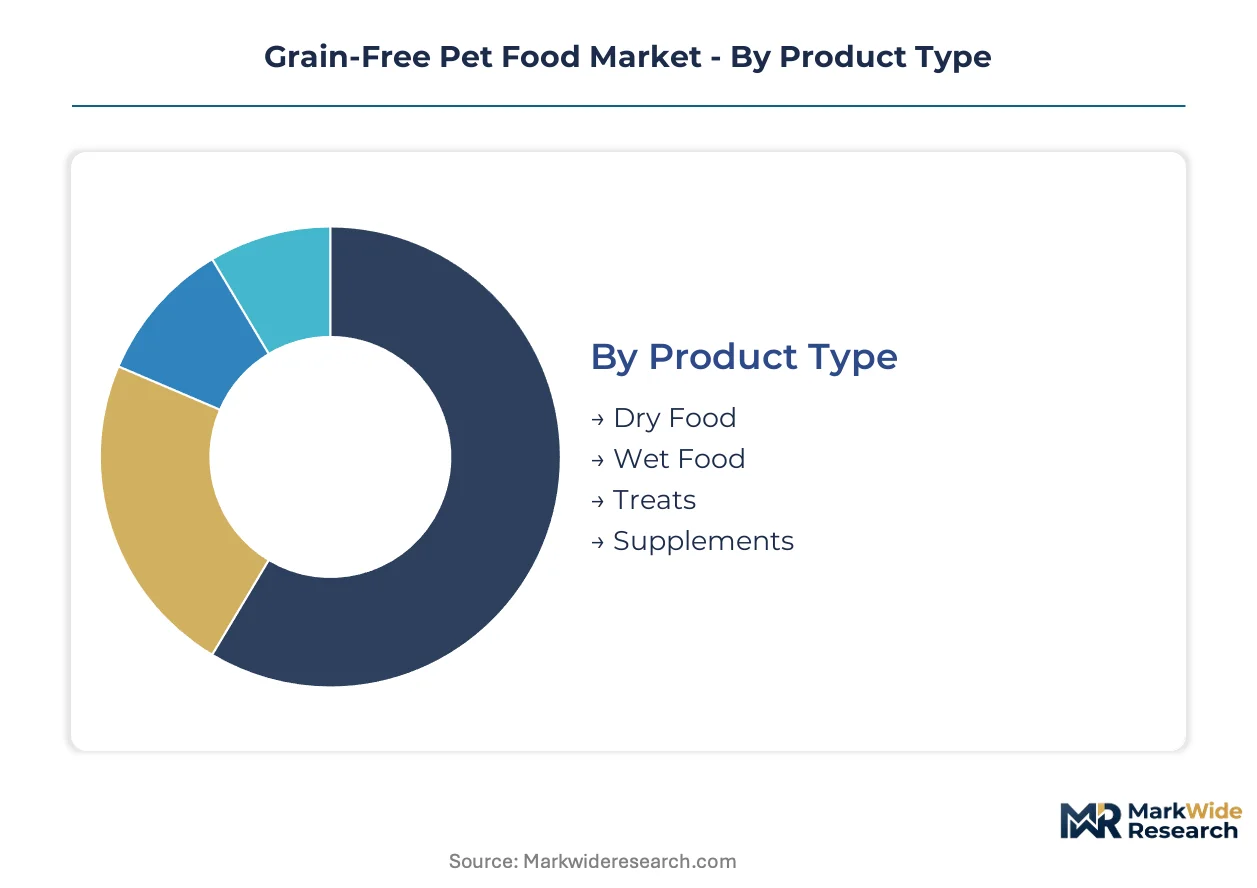
Grain-free pet food manufacturers must navigate divergent production cycles across product formats, with extruded kibble requiring capital-intensive thermal systems while wet food demands sterile canning infrastructure. Ingredient sourcing and channel access further fragment operational priorities, forcing portfolio balancing between margin-rich specialties and volume-driving staples.
Product Type:
Dry food commands the longest production cycles due to extrusion die calibration and extended drying phases, while wet food and treats turn inventory more rapidly through distinct processing architectures.
- Dry Food:Cold-press extrusion at sub-90°C thresholds preserves amino acid integrity in kibble matrices, with Champion Petfoods and Mars Petcare anchoring capacity expansion in US Midwest production clusters. Shelf stability drives 18-month retail distribution windows, though FDA nutritional adequacy protocols extend formulation validation timelines.
- Wet Food:Retort processing in aluminum or steel containers achieves commercial sterility while concentrating protein density above 40% on a dry matter basis. Veterinary channel placement captures margin premiums through clinic-exclusive therapeutic positioning for dogs with diagnosed food sensitivities.
- Treats:Freeze-dried and air-dried formats leverage lower thermal degradation for training and reward applications.
- Supplements:Omega fatty acid and probiotic add-ons target digestive and coat health adjacencies.
Dry food anchors the volume base while wet food gains share at the steepest rate through veterinary channel deepening.
Ingredient Source:
Cost tier stratification separates commodity-scale vegetable inputs from premium-positioned animal proteins, with legume intermediates capturing mid-tier formulation share.
- Animal Protein:Chicken meal, fish meal, and rendered meat and bone meal supply complete amino acid profiles with digestibility coefficients exceeding 85%. Spot market volatility in Midwestern US rendering clusters—where four states concentrate 60% of domestic supply—compresses margin predictability on fixed-price contracts.
- Vegetable Protein:Pea protein isolates and potato protein concentrates substitute for cereal grains while maintaining glycemic indices below 35, though EFSA novel protein assessments extend European registration timelines pending 90-day toxicity documentation.
- Legumes:Lentil and chickpea flours provide binding functionality alongside fermentable fiber content.
- Fruits:Blueberry and cranberry inclusions supply antioxidant positioning through polyphenol content.
Animal protein dominates value concentration while legumes expand most quickly through cost parity achievement with legacy grain inputs.
Target Animal:
Application intensity varies dramatically, with dogs consuming 3-5x daily caloric volume versus cats and small animals driving repurchase frequency differentials.
- Dogs:Carnivore-optimized formulations emphasize elevated animal protein inclusion with taurine supplementation protocols responding to FDA dilated cardiomyopathy investigations. Breed-specific algorithmic feeding recommendations from Chewy and direct-brand platforms now displace generic weight-based portion guidance.
- Cats:Obligate carnivore requirements mandate higher protein minimums and arachidonic acid sourcing from animal tissues, constraining vegetable protein substitution rates.
- Small Animals:Rabbit and guinea pig formulations adapt grain-free positioning to herbivore digestive physiology.
- Birds:Seed-replacement diets target psittacine species with formulated pellet alternatives.
Dogs anchor the volume base while cats command the steepest per-kilogram pricing premiums through ingredient stringency.
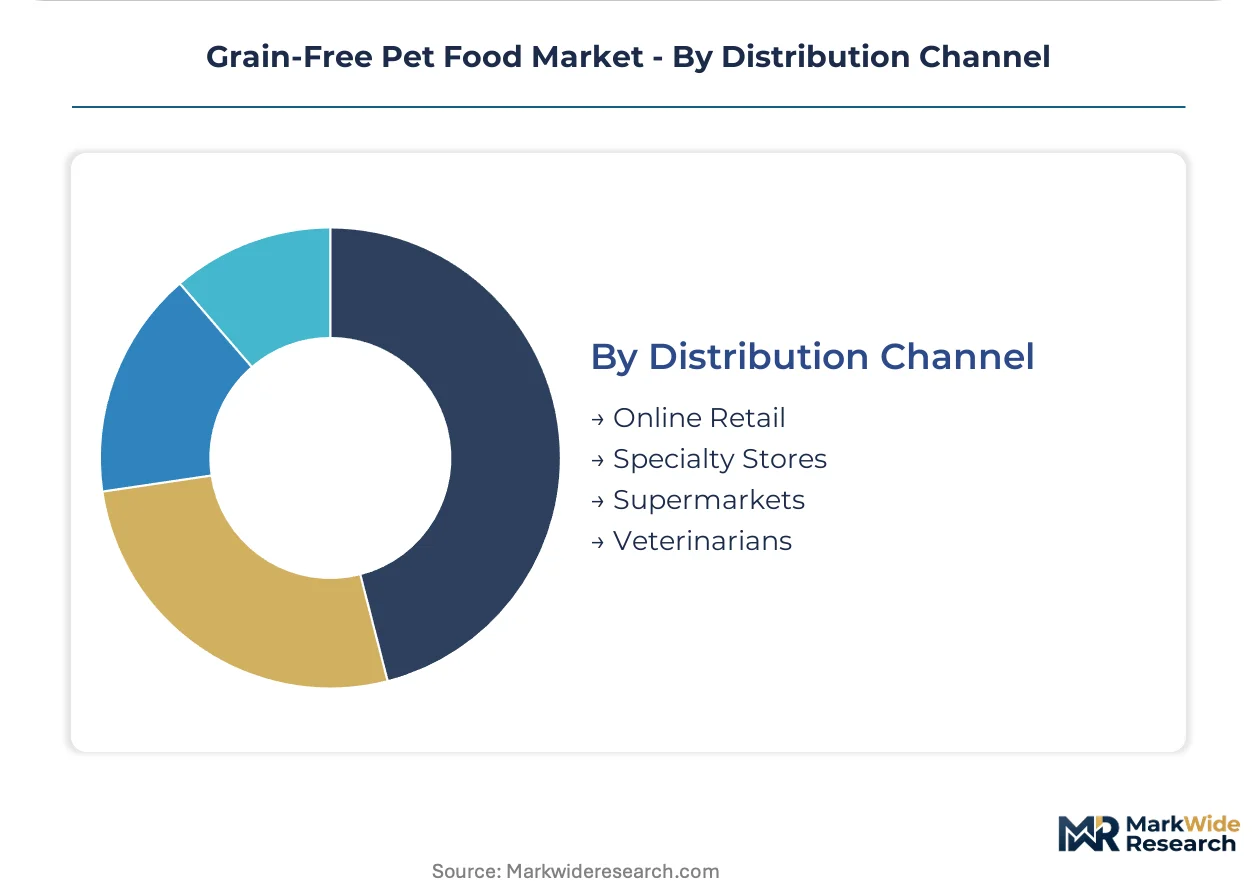
Distribution Channel:
Customer type stratification separates subscription-driven urban households from clinic-dependent therapeutic users, with specialty retail capturing enthusiast engagement.
- Online Retail:Auto-replenishment algorithms synchronized with veterinary wellness exam intervals capture 35% of premium grain-free volume in coastal US metro areas. Direct-to-consumer platforms bypass distributor markups while accumulating lifetime value through breed, weight, and activity-level customization.
- Specialty Stores:Independent pet retailers provide ingredient-source transparency and staff consultation for food-sensitive animals, deepening penetration among premium dog-owning households.
- Supermarkets:Mass-market placement extends reach to price-sensitive converters from conventional grain-inclusive diets.
- Veterinarians:Clinic-exclusive distribution networks validate therapeutic claims through prescription frameworks and cardiac health monitoring protocols.
Online retail anchors the volume base while veterinarians gain share through therapeutic positioning and DCM correlation monitoring requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States grain-free pet food exports flow primarily to Canadian and Mexican markets under USMCA provisions, with specialty formulations commanding premium positioning in cross-border veterinary channels.
United States
Specialty retail chains and veterinary clinic networks drive premium adoption in coastal metro corridors. FDA Center for Veterinary Medicine enforces AAFCO nutritional adequacy protocols while investigating dilated cardiomyopathy correlations. Midwestern rendering clusters in Kansas, Missouri, Nebraska, and Iowa concentrate 60 percent of domestic meat and bone meal supply.
Canada
Urban pet-owning households in Toronto and Vancouver accelerate subscription-based grain-free purchasing through direct-to-consumer platforms. Health Canada and the Canadian Food Inspection Agency coordinate feed safety audits with provincial agriculture departments. Alberta and Saskatchewan rendering facilities supply protein inputs to Ontario-based co-manufacturing operations.
Germany
Discerning pet owners in Munich and Hamburg prioritize cold-processed formulations with transparent ingredient sourcing. EFSA novel protein assessments and REACH-aligned feed additive scrutiny extend registration timelines for alternative carbohydrate entrants. Bavarian pet food production clusters near Nuremberg specialize in high-moisture extrusion systems.
United Kingdom
London and Southeast England concentrate demand for therapeutic grain-free positioning through veterinary referral practices. The Food Standards Agency and Defra enforce feed hygiene regulations while adapting to post-Brexit import protocols. Midlands manufacturing corridors around Leicester and Nottingham host co-packing facilities serving European export markets.
Australia
Sydney and Melbourne metropolitan areas show highest penetration of breed-specific algorithmic feeding recommendations via online platforms. The Department of Agriculture, Water and the Environment administers biosecurity controls on imported protein meals while state-level consumer protection agencies monitor label claims. Victorian rendering and pet food production clusters near Geelong supply domestic and Asia-Pacific export demand.
Grain-Free Pet Food Market Competitive Environment
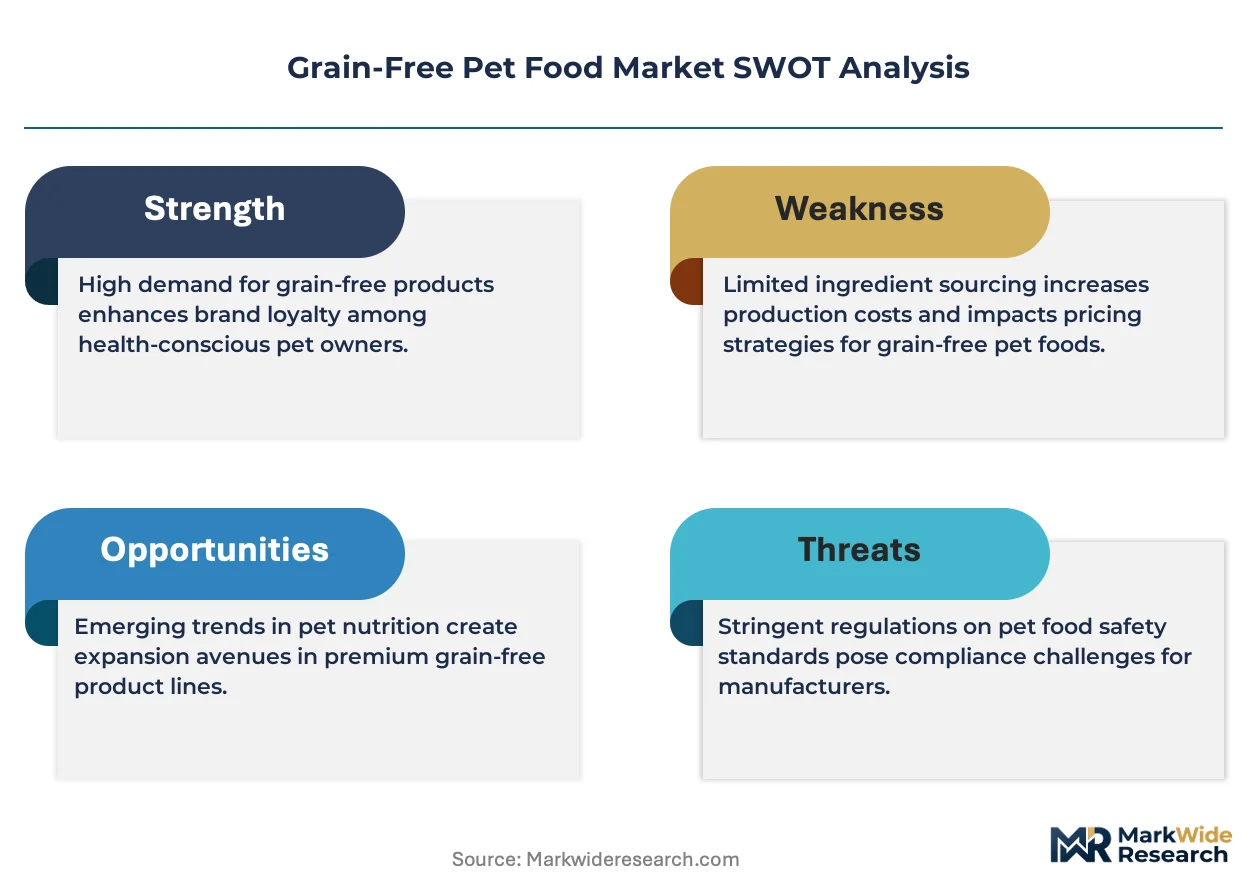
On the supply side, the industry is consolidating around three strategic tiers: multinational conglomerates with veterinary channel dominance, mid-tier specialists with ingredient-source transparency positioning, and emerging challengers with direct-to-consumer subscription architectures. These archetypes compete through divergent capital deployment strategies. Dominant competitive moves include cold-press extrusion technology licensing and backward integration into alternative protein rendering.
Within the multinational tier, Mars Petcare and Nestle Purina PetCare exemplify scale-driven veterinary channel anchoring. Champion Petfoods occupies a position within the premium specialist archetype, representing thermal-process innovation positioning. Blue Buffalo Company sits within the ingredient-transparency tier, exemplifying antioxidant-inclusion differentiation strategies.
| Leading Market Players |
|---|
| Nestle Purina PetCare |
| Mars Petcare |
| Blue Buffalo Company |
| WellPet LLC |
| The J.M. Smucker Company |
| Champion Petfoods |
| Diamond Pet Foods |
| Canidae Natural Pet Food Company |
| Farmina Pet Foods |
| Others |
Value Chain & Pricing Dynamics
Midwestern rendering facility utilization rates near 85 percent are tightening animal protein feedstock availability while simultaneously compressing margin buffers across fixed-price subscription contracts. This capacity squeeze forces manufacturers toward alternative carbohydrate sourcing and cold-press extrusion investments that sustain pricing power in premium tiers.
Pricing Analysis
Cold-press extrusion technology commands 15-20 percent premiums over conventional thermal processing, while legacy baked formats face margin compression from raw-frozen alternatives. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-exclusive therapeutic positioning from mass-market supermarket placement. Pricing pressure stems from animal protein input volatility in Midwestern spot markets. Supermarket converters from grain-inclusive diets exhibit highest price sensitivity, while veterinary channel buyers accept premium positioning for diagnostic monitoring integration.
Supply Chain Analysis
Upstream feedstock concentration in Kansas, Missouri, Nebraska, and Iowa renders 60 percent of domestic meat and bone meal supply vulnerable to climate-driven disruptions. Chicken meal, fish meal, and rendered proteins feed from these clusters into extrusion facilities across the US Midwest. Single-source vulnerability in rendering infrastructure creates geographic risk exposure. Distribution runs through veterinary clinic networks, specialty retail chains, and direct-to-consumer subscription platforms in coastal metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription auto-replenishment services are expanding faster than hardware manufacturing, with breed-specific algorithmic feeding recommendations capturing lifetime value through veterinary wellness exam synchronization.
For Market Incumbents: Pre-empt insect protein integration by securing black soldier fly larvae supply agreements before EFSA streamlined assessments mature. Champion Petfoods and Mars Petcare should accelerate backward integration into alternative protein rendering to defend against emerging challengers with direct-to-consumer architectures. Cold-press extrusion technology licensing offers defensive moat construction. For New Entrants and Emerging Players: Pursue European novel protein pathways where EFSA assessments for cultured meat ingredients accelerate regulatory clearance relative to traditional tracks. Urban coastal US metro areas show underpenetrated algorithmic feeding customization. Direct-to-consumer platforms bypassing distributor markups offer viable go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with thermal-process innovation capabilities and established AAFCO feeding trial protocols. Long-term viability hinges on formulation transparency ahead of potential FDA ingredient disclosure mandates. The signal to monitor is FDA guidance evolution on dilated cardiomyopathy correlations.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Licensing | Champion Petfoods leverages sub-90°C thermal profiles to sustain amino acid integrity in premium kibble matrices. |
| Insect Protein Supply Agreement | Black soldier fly larvae meal offers complete amino acid profiles with 90 percent lower land use than poultry farming. |
| Veterinary Channel Expansion | Clinic-exclusive distribution networks validate therapeutic claims through prescription frameworks and cardiac health monitoring. |
| Direct-to-Consumer Platform Launch | Chewy and brand-direct auto-replenishment capture 35 percent of premium grain-free volume in coastal US metro areas. |
| EFSA Novel Protein Registration | Streamlined assessments for cultured meat ingredients accelerate European regulatory clearance timelines. |
Study Parameters
Cross-validation between formulation chemist interviews and AAFCO feeding trial documentation anchors the qualitative findings in this study. Primary discussions with veterinary nutritionists, extrusion equipment engineers, specialty retail category buyers, and direct-to-consumer platform operators combined with FDA Center for Veterinary Medicine guidance documents, state agriculture department audit records, EFSA novel protein assessment filings, and SEC 10-K disclosures from publicly traded pet food manufacturers. Bottom-up capacity modeling and top-down expenditure tracking triangulate market sizing.
Calibration against historical capacity utilization rates and subscription platform growth trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient source, target animal species, and distribution channel architecture. CAGRs derived from weighted average of technology adoption curves and regulatory pathway timelines. Forecast inputs incorporated thermal processing equipment installation rates and veterinary channel expansion metrics.
Sensitivities concentrate around FDA DCM correlation study outcomes and EFSA registration timeline extensions. Forecasts reflect documented assumptions regarding alternative carbohydrate cost parity achievement and cold-press extrusion adoption rates. Cross-checking against Nielsen retail audit data and veterinary clinic dispensing records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Soft Tofu Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Tahini Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
North America Hummus Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Global Honey Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Global Ethnic Foods Market