
 Postbiotic Pet Food Market | 2026-2036
Postbiotic Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Postbiotic Pet Food Market Analytics
Ingredient science revenue is rewriting margin allocation between commodity nutrition and functional formulation. ADM leverages its fermentation infrastructure to produce standardized postbiotic metabolites at scale. Kerry Group plc anchors European supply through its Biobake and Sheffa ingredient platforms. Mars Petcare Inc. competes via Royal Canin's veterinary therapeutic positioning, extending clinic-channel credibility into retail.
Postbiotic pet food incorporates heat-inactivated microbial cells or their metabolites, typically delivered at defined colony-forming-equivalent thresholds to confer immunomodulatory or gastrointestinal benefits without live-culture viability constraints. Dry food formulations dominate volume due to extended shelf stability and lower per-unit logistics burden, though supplements represent the fastest-expanding margin pool as pet owners dose-add to existing diets. Wet food applications are maturing in Europe, where palatability-driven acceptance among feline consumers sustains premium positioning.
EFSA's feed additive evaluation process, the FDA's GRAS notification pathway for animal food ingredients, and AAFCO's model bill framework collectively determine market access velocity and label claim permissibility. Regulatory divergence between jurisdictions forces dual-track substantiation strategies, elevating R&D spend for multi-region suppliers. Stakeholders must monitor pending EFSA opinions on novel postbiotic strain designations and corresponding state-level adoption by US feed control officials.
Market Dynamics
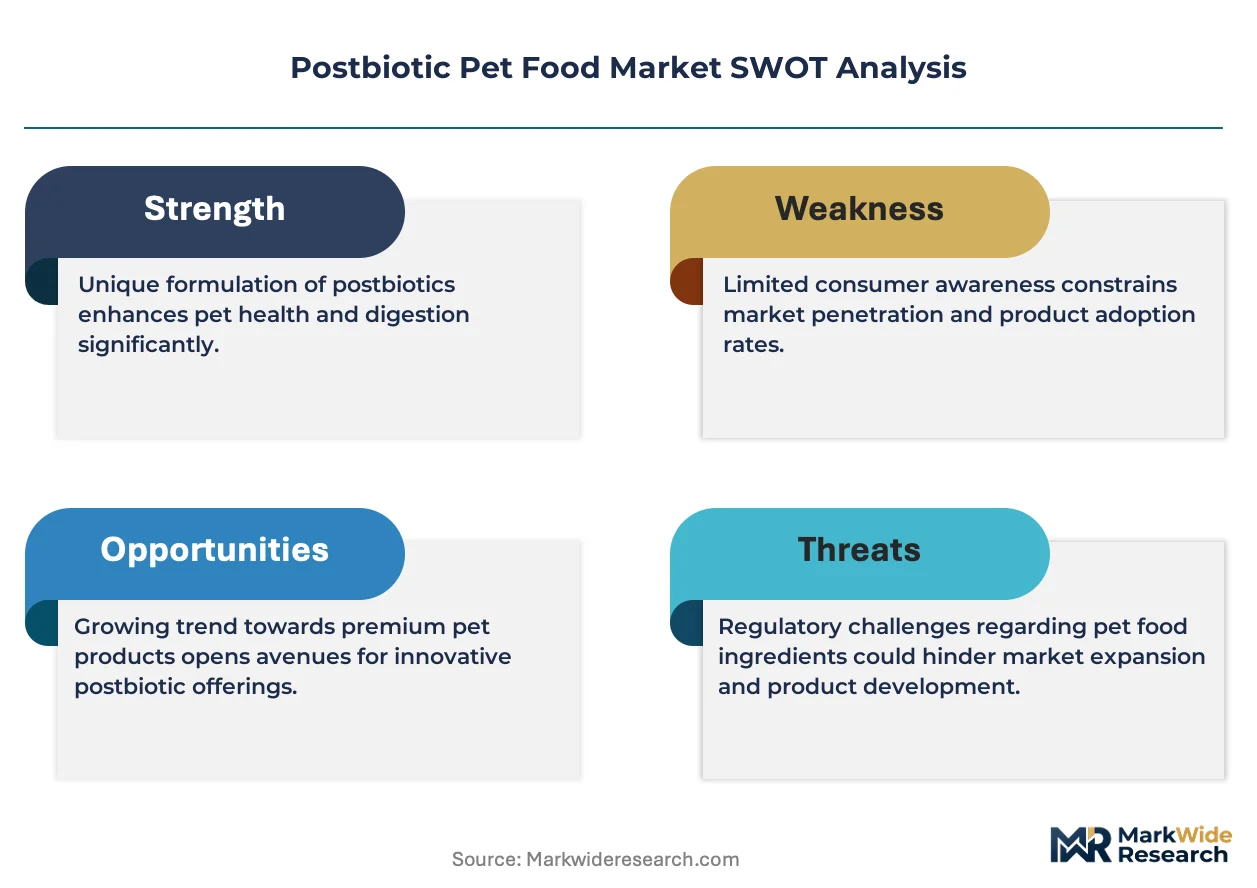
EFSA's novel feed additive authorization framework is compressing go-to-market timelines for postbiotic suppliers while simultaneously elevating substantiation costs, creating a bifurcation between scaled fermentation operators and commodity ingredient traders.
Growth Catalysts
- Veterinary channel endorsement:Clinic-dispensed therapeutic diets normalize postbiotic inclusion for at-risk populations, creating pull-through into retail premium tiers.
- Fermentation infrastructure maturation:Contract manufacturing capacity for heat-inactivated metabolite production expands in the Netherlands and Denmark, reducing batch-to-batch variability.
- Regulatory clarity under EFSA:Streamlined QPS (Qualified Presumption of Safety) pathways for postbiotic strain designations reduce multi-jurisdiction approval uncertainty.
Market Restraints
- Input cost volatility:Specialized growth media for microbial fermentation face price pressure from pharmaceutical sector demand competing for amino acid and carbohydrate feedstocks.
- Supply concentration risk:European Union member states dominate active metabolite production, exposing buyers to single-region logistics disruptions and currency exposure.
- Technical limitation:Heat-inactivation protocols that preserve bioactive metabolite integrity remain strain-specific, preventing universal process standardization across suppliers.
Strategic Opportunities
- Feline wet food penetration:Palatability-driven acceptance among cat owners in France and Germany sustains premium positioning for liquid postbiotic inclusions.
- Supplement channel innovation:Direct-to-consumer dosing formats bypass retail slotting fees while capturing recurring revenue from existing dry-food households.
- Regulatory tailwind from FDA GRAS:Self-affirmed GRAS notifications for animal food ingredients create faster US market access than feed additive petitions.
Industry Challenges
- Metabolomics expertise gap:Analytical chemists capable of quantifying bioactive postbiotic fractions command premium compensation, constraining R&D expansion at mid-tier suppliers.
- Dual-track substantiation burden:Divergent EFSA and FDA evidentiary requirements force parallel clinical study designs, duplicating trial costs for multi-region launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postbiotic Pet Food Market |
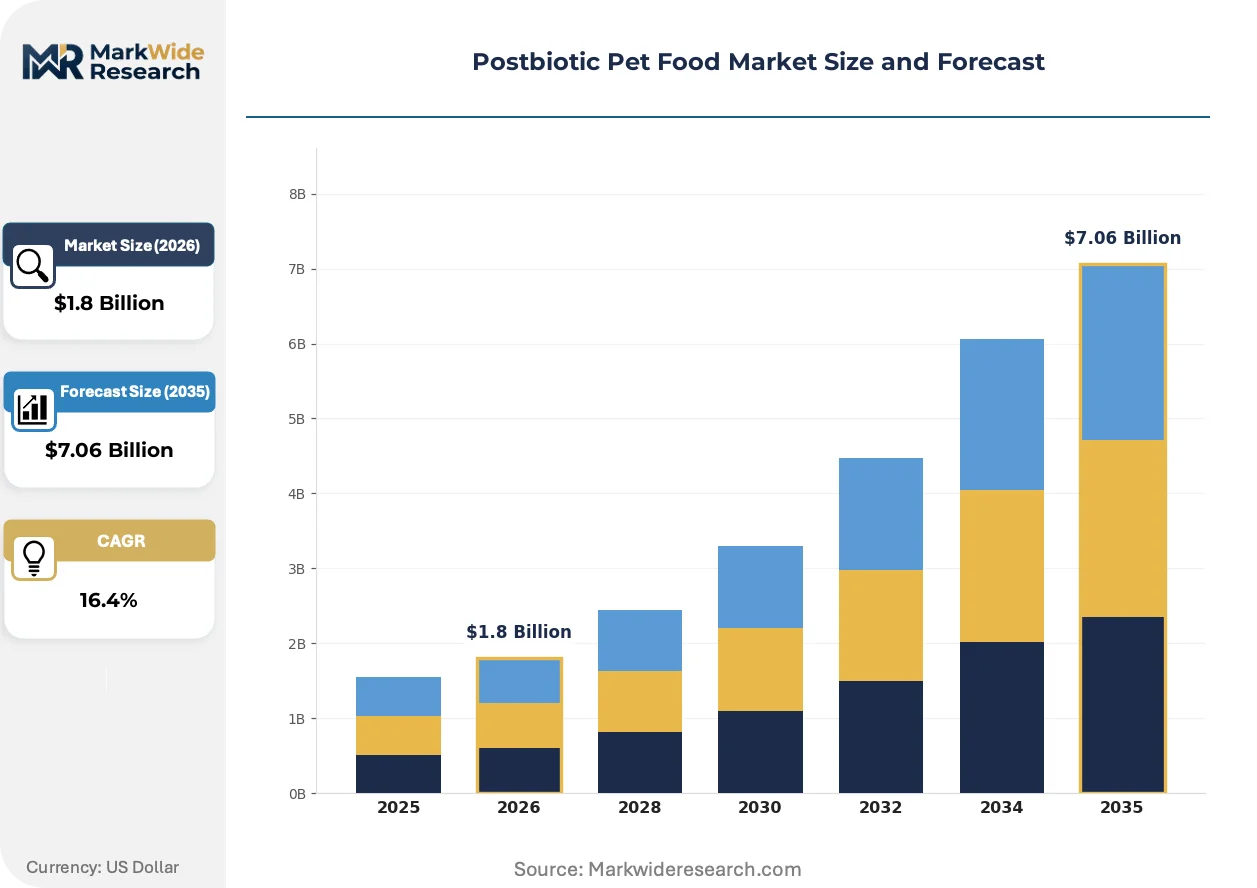
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Dogs, Cats, Small Animals, Birds Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Ingredient Type: Organic, Grain-Free, High-Protein, Others |
| Companies Covered | ADM, dsm-firmenich, Mars Petcare Inc., Kerry Group plc, Cargill, Incorporated, Nestlé Purina PetCare Company, Alltech, Kemin Industries, Inc., Royal Canin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postbiotic Pet Food Market Evolving Landscape
Digital traceability infrastructure and precision fermentation advances are compressing quality assurance cycles while enabling personalized dosing protocols that match metabolite profiles to individual animal microbiome signatures.
Metabolomic fingerprinting technology is digitizing quality control workflows across postbiotic manufacturing. Suppliers deploy high-resolution mass spectrometry to verify metabolite consistency between fermentation batches. Large-scale contract manufacturers adopt these platforms first, forcing smaller competitors into third-party testing dependencies that erode margin.
EFSA's pending opinions on novel postbiotic strain designations are reshaping ingredient claim permissibility across the European Union. The regulator's tightened evidence standards for immunomodulatory assertions compel suppliers to invest in mechanistic studies beyond traditional efficacy trials. Wet food applications face the steepest compliance burden due to complex matrix interactions affecting metabolite stability.
Subscription-based supplement purchasing is displacing single-transaction retail buying among premium pet owners in the United States. Direct-to-consumer platforms capture recurring revenue by offering microbiome testing kits that recommend personalized postbiotic formulations. Veterinary clinics respond by white-labeling their own subscription services to retain client relationships.
Postbiotic Pet Food Market Segmentation
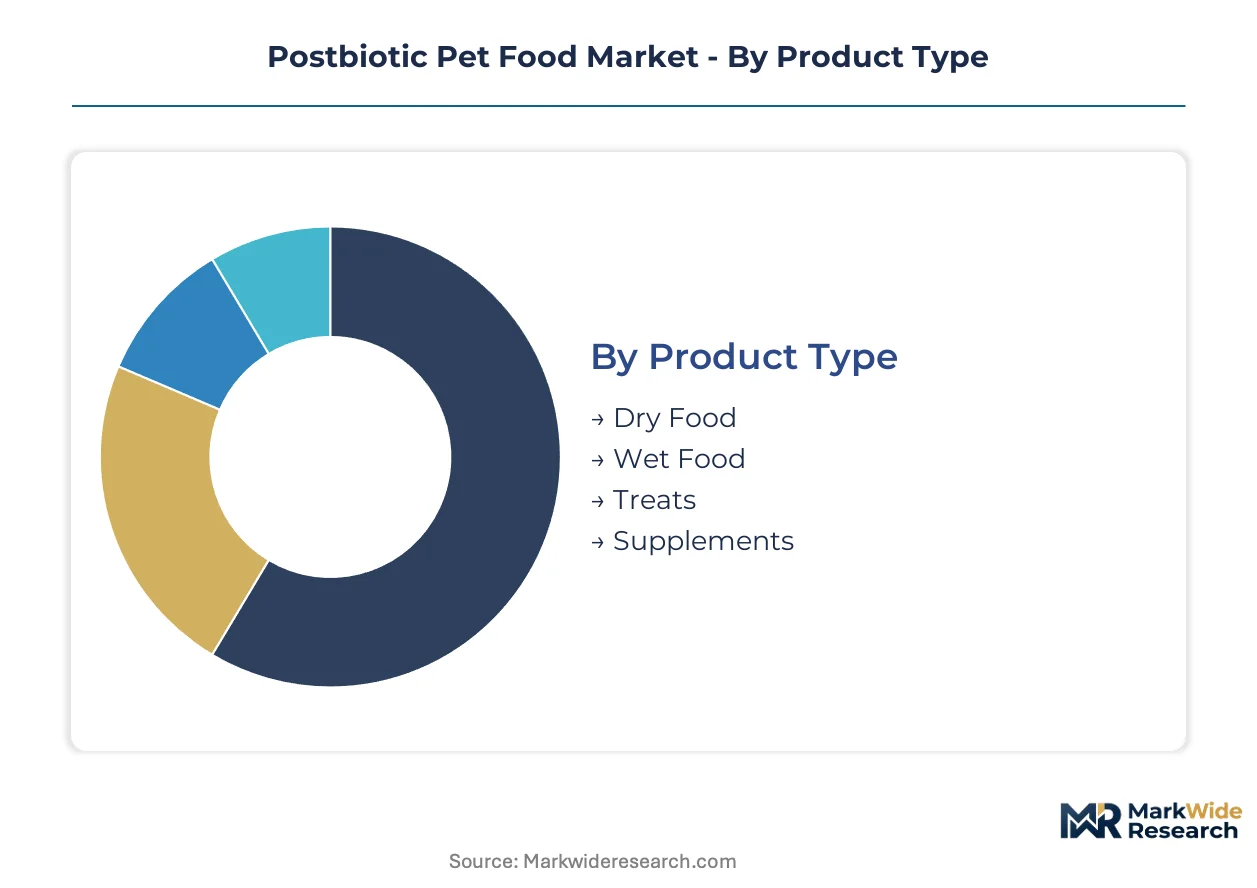
Postbiotic pet food segmentation reveals how delivery format, species targeting, and retail channel each impose distinct technical and commercial constraints on suppliers. Manufacturers must align fermentation output specifications with the stability requirements of each product category while navigating divergent purchasing behaviors across pet owner demographics.
Product Type:
Heat-inactivated metabolite delivery spans a use-case spectrum from shelf-stable daily nutrition to targeted therapeutic dosing.
- Dry Food:Kibble matrices incorporate spray-dried postbiotic powders at defined colony-forming-equivalent thresholds, leveraging extended shelf stability and lower logistics burden to dominate volume in the United States. Mars Petcare's Royal Canin veterinary lines anchor this segment through clinic-channel credibility.
- Supplements:Standalone powders, capsules, and liquid formats enable dose-addition to existing diets, capturing recurring revenue through direct-to-consumer subscriptions. This segment gains share fastest among premium pet owners seeking personalized microbiome interventions.
- Wet Food:Canned and pouch formulations face complex matrix interactions affecting metabolite stability, with palatability-driven acceptance among feline consumers sustaining premium positioning in France and Germany.
- Treats:Functional snacks deliver postbiotic inclusions via palatable delivery vehicles, typically targeting training and reward contexts with shorter consumption windows.
Established volume favors dry food; emerging adoption favors supplements.
End User:
Species-specific digestive physiology dictates metabolite strain selection and dosing protocols across veterinary and retail applications.
- Dogs:Canine gastrointestinal systems accommodate diverse postbiotic strain profiles, with large-breed formulations commanding premium pricing for joint and immune support claims. Veterinary endorsement drives clinic-dispensed therapeutic adoption.
- Cats:Obligate carnivore metabolism requires specialized metabolite formulations, with wet food palatability constraints limiting viable delivery vehicles in the European Union. Feline-specific research substantiation lags canine evidence bases.
- Small Animals:Rabbit, guinea pig, and ferret formulations represent a niche volume pool with concentrated demand among specialty retailers.
- Birds:Avian digestive tract physiology imposes unique strain viability and delivery constraints, restricting commercial development to limited supplier portfolios.
Canine applications concentrate manufacturing investment; feline formats command the steepest per-unit margin premiums.
Distribution Channel:
Channel selection determines margin allocation between retail slotting fees and customer acquisition costs.
- Online Retail:Direct-to-consumer platforms bypass traditional retail intermediaries, enabling subscription-based recurring revenue and microbiome testing integration. Chewy and Amazon dominate this channel in the United States.
- Specialty Stores:Independent pet retailers and veterinary clinics provide educated staff endorsement that normalizes premium postbiotic positioning. This channel captures the highest per-unit margins through consultative selling.
- Supermarkets:Mass-market retail demands price-competitive formulations with simplified label claims, constraining postbiotic inclusion rates to cost thresholds.
- Direct Sales:Manufacturer-owned channels and veterinary white-label programs retain full margin capture while building proprietary customer data assets.
Specialty retail anchors premium positioning; online channels drive volume expansion.
Ingredient Type:
Certification and compositional claims segment the addressable market by pet owner value hierarchy.
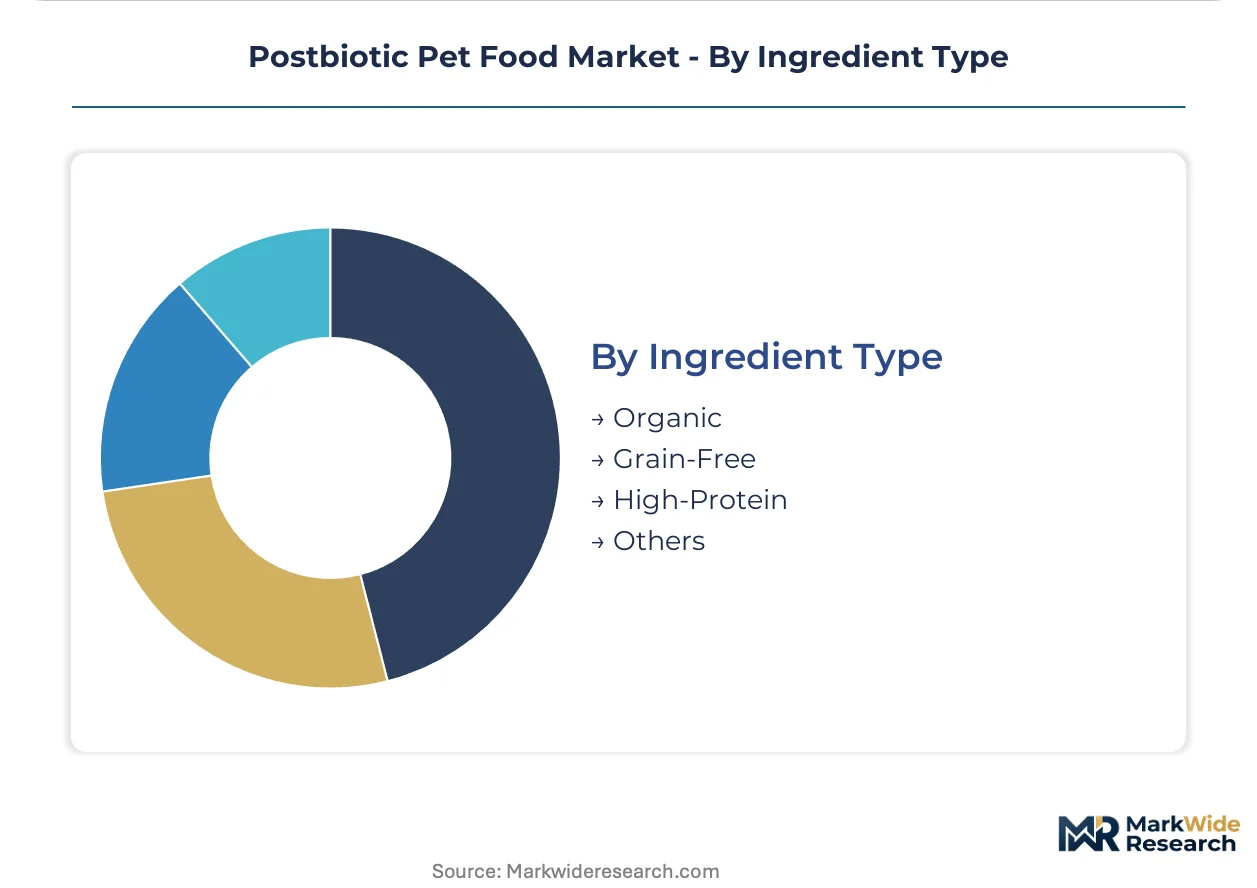
- Organic:USDA Organic and EU Organic certification requirements constrain microbial growth media sourcing, elevating input costs while capturing sustainability-motivated purchasing in Germany and the Netherlands.
- Grain-Free:Formulations excluding cereal carbohydrates align with ancestral diet positioning, though FDA investigations into canine dilated cardiomyopathy associations have tempered growth velocity.
- High-Protein:Elevated meat inclusion rates compete with postbiotic metabolites for formulation space and cost allocation, requiring precise dosing optimization.
- Others:Novel protein, limited ingredient, and veterinary therapeutic designations capture specialized dietary requirement segments.
Grain-free claims dominate shelf presence; organic certification commands the tightest supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat-inactivated metabolite production clusters heavily in the European Union, with contract fermentation capacity expanding fastest in the Netherlands and Denmark. Veterinary endorsement drives premium adoption in the United States, while regulatory divergence between EFSA and FDA pathways shapes multi-region supplier strategies.
United States
Clinic-dispensed therapeutic diets from Mars Petcare's Royal Canin normalize postbiotic inclusion for at-risk canine populations, creating retail pull-through. FDA's GRAS notification pathway offers faster market access than feed additive petitions for animal food ingredients. Greater Boston anchors microbiome testing kit development for direct-to-consumer subscription platforms.
Germany
Palatability-driven wet food acceptance among feline owners sustains premium positioning for liquid postbiotic inclusions. EFSA's QPS pathway streamlines strain designation approvals under the novel feed additive framework. Hamburg hosts specialized growth media suppliers facing pharmaceutical sector competition for amino acid feedstocks.
Netherlands
Contract manufacturing capacity for standardized postbiotic metabolites expands fastest here, reducing batch-to-batch variability for pan-European distribution. EU Green Deal sustainability requirements constrain organic-certified microbial growth media sourcing. Wageningen University clusters fermentations science expertise with industry partnerships.
France
Feline wet food applications command steepest per-unit margin premiums due to complex matrix stability requirements and obligate carnivore formulation constraints. ANSM oversight of veterinary therapeutic claims intersects with EFSA feed additive evaluations. Lyon hosts precision fermentation startups targeting personalized microbiome interventions.
United Kingdom
Post-Brexit regulatory divergence from EFSA frameworks forces dual-track substantiation strategies for suppliers serving both UK and EU markets. Specialty retail channels in London capture highest per-unit margins through consultative staff endorsement. Cambridge clusters metabolomics expertise for bioactive fraction quantification.
Postbiotic Pet Food Market Competitive Landscape
Fermentation-scale operators and formulation specialists split the market between upstream metabolite production and downstream brand positioning. Three archetypes dominate: integrated nutrition conglomerates with captive fermentation assets, ingredient technology platforms licensing standardized metabolites, and veterinary therapeutic brands leveraging clinic-channel credibility. Competitive moves concentrate on fermentation capacity expansion in the Netherlands and Denmark, plus strategic partnerships bridging metabolite supply with direct-to-consumer subscription infrastructure.
Within the integrated nutrition tier, ADM leverages fermentation infrastructure to produce standardized postbiotic metabolites at scale. Kerry Group plc anchors European supply through ingredient platforms. Mars Petcare Inc. competes via veterinary therapeutic positioning, extending clinic-channel credibility into retail premium tiers.
| Leading Market Players |
|---|
| ADM |
| dsm-firmenich |
| Mars Petcare Inc. |
| Kerry Group plc |
| Cargill, Incorporated |
| Nestlé Purina PetCare Company |
| Alltech |
| Kemin Industries, Inc. |
| Royal Canin |
| Others |
Value Network & Pricing Analysis
Single-source dependency on European Union fermentation capacity determines both tiered pricing spreads and supply chain configuration. Buyers face compressed negotiation leverage when specialized growth media suppliers compete with pharmaceutical sector demand for amino acid feedstocks.
Pricing Analysis
EFSA's novel feed additive authorization framework dictates the pricing tier structure across veterinary therapeutic, premium retail, and mass-market economy segments. Three-tier pricing structure across premium, standard, and economy levels separates clinic-dispensed formulations from specialty retail SKUs and supermarket private labels. Price differentiation centers on certification grade and veterinary endorsement density. Cost compression in the mass-market tier is intensifying because supermarket buyers demand simplified label claims with reduced metabolite inclusion rates. Specialty retail channels exhibit the lowest price sensitivity; mass-market retailers demonstrate acute cost consciousness.
Supply Chain Analysis
Extended payment terms from Dutch and Danish contract manufacturers to amino acid feedstock suppliers anchor working capital dynamics across the metabolite production network. Geographic supply concentration clusters in the Netherlands, Denmark, and Germany, with Wageningen University partnerships feeding technical talent pipelines. Raw material dependencies draw from pharmaceutical-grade carbohydrate feedstocks, specialized nitrogen sources, and sterile filtration consumables. Single-source vulnerability persists for heat-inactivation equipment calibrated to strain-specific protocols. Distribution runs through pan-European logistics hubs serving veterinary clinics, specialty retailers, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EFSA's QPS pathway and FDA's GRAS notification create multi-year approval barriers that protect incumbent fermentation-scale operators.
For Market Incumbents: Insulate clinic-channel relationships by white-labeling subscription services before veterinary clinics develop captive postbiotic platforms. Expand fermentation capacity in the Netherlands to capture economies of scale as batch-to-batch variability constraints eliminate smaller competitors. The metabolomics expertise gap threatens R&D expansion velocity; acquire analytical chemistry capabilities or lock in exclusive university partnerships. For New Entrants and Emerging Players: Feline wet food underpenetration in France and Germany offers the most accessible white-space target, as palatability-driven acceptance sustains premium positioning without requiring canine-scale clinical substantiation. Direct-to-consumer supplement formats bypass retail slotting fees while capturing recurring revenue from existing dry-food households. Partner with microbiome testing kit developers to embed postbiotic recommendations within personalized nutrition workflows. For Investors and Strategic Acquirers: EFSA's pending opinions on novel postbiotic strain designations reshape the acquisition landscape by elevating mechanistic study requirements beyond traditional efficacy trials. Five-to-ten-year viability favors integrated operators with captive fermentation assets over pure-play ingredient licensors. Target contract manufacturers with validated heat-inactivation protocols and existing veterinary clinic relationships. Monitor FDA GRAS notification velocity as the inflection indicator for US market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Netherlands-based scale-up reduces batch-to-batch variability for pan-European distribution. |
| Veterinary Channel Partnership | Clinic-dispensed therapeutic diets normalize postbiotic inclusion for at-risk populations. |
| Direct-to-Consumer Launch | Subscription platforms bypass retail slotting fees while capturing recurring revenue streams. |
| Metabolomics Technology Acquisition | Mass spectrometry capabilities verify bioactive fraction consistency between fermentation batches. |
| Regulatory Dual-Track Investment | Parallel EFSA and FDA substantiation strategies accelerate multi-region market access timelines. |
Research Methodology
Cross-validation between primary interviews with fermentation science directors, veterinary nutritionists, specialty retail buyers, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from EFSA feed additive opinions, FDA GRAS notifications, AAFCO model bill frameworks, and customs trade data for specialized growth media inputs. Bottom-up segment sizing triangulates against top-down market consolidation analysis.
Calibration against historical authorization timelines and observed pricing elasticity across veterinary and retail channels stabilizes the analytical framework. Segmentation dimensions span product type, species targeting, distribution channel, and ingredient certification grade. CAGRs derive from fitted growth curves adjusted for regulatory approval velocity and fermentation capacity expansion schedules. Inputs include metabolite production batch records, clinic dispensing data, and subscription platform customer acquisition metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by pharmaceutical contract manufacturers or sudden EFSA opinion reversals would shift outcomes. Macroeconomic volatility in amino acid feedstock markets, regulatory divergence acceleration, or breakthroughs in precision fermentation strain engineering would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Natto Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Cultures Market