
 North America Alcohol Ethoxylates Market | 2026-2036
North America Alcohol Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alcohol Ethoxylates Market Insights
Industrial cleaning buyers is reorganizing procurement priorities toward high-active, low-foam ethoxylate grades for automated warewash and hard-surface applications. Dow leverages its integrated ethylene oxide pipeline along the US Gulf Coast to sustain cost-competitive linear alcohol ethoxylate supply. Stepan Company anchors its position through specialized industrial and institutional formulations. Huntsman International LLC differentiates via controlled molecular architecture for narrow-range ethoxylation.
Alcohol ethoxylates are nonionic surfactants produced by reacting fatty alcohols with ethylene oxide, yielding hydrophilic-lipophilic balance values typically between 10 and 16 for detergent-range applications. These compounds function primarily as wetting agents, emulsifiers, and detergents across aqueous cleaning systems. Linear alcohol ethoxylates dominate volume demand in North America due to superior biodegradability compliance under EPA framework standards. Branched alcohol ethoxylates occupy niche industrial degreasing segments where hard-water tolerance and rapid oil solubilization command price premiums. Liquid formulations lead shipment volumes through concentrated delivery economics and compatibility with automated dosing equipment.
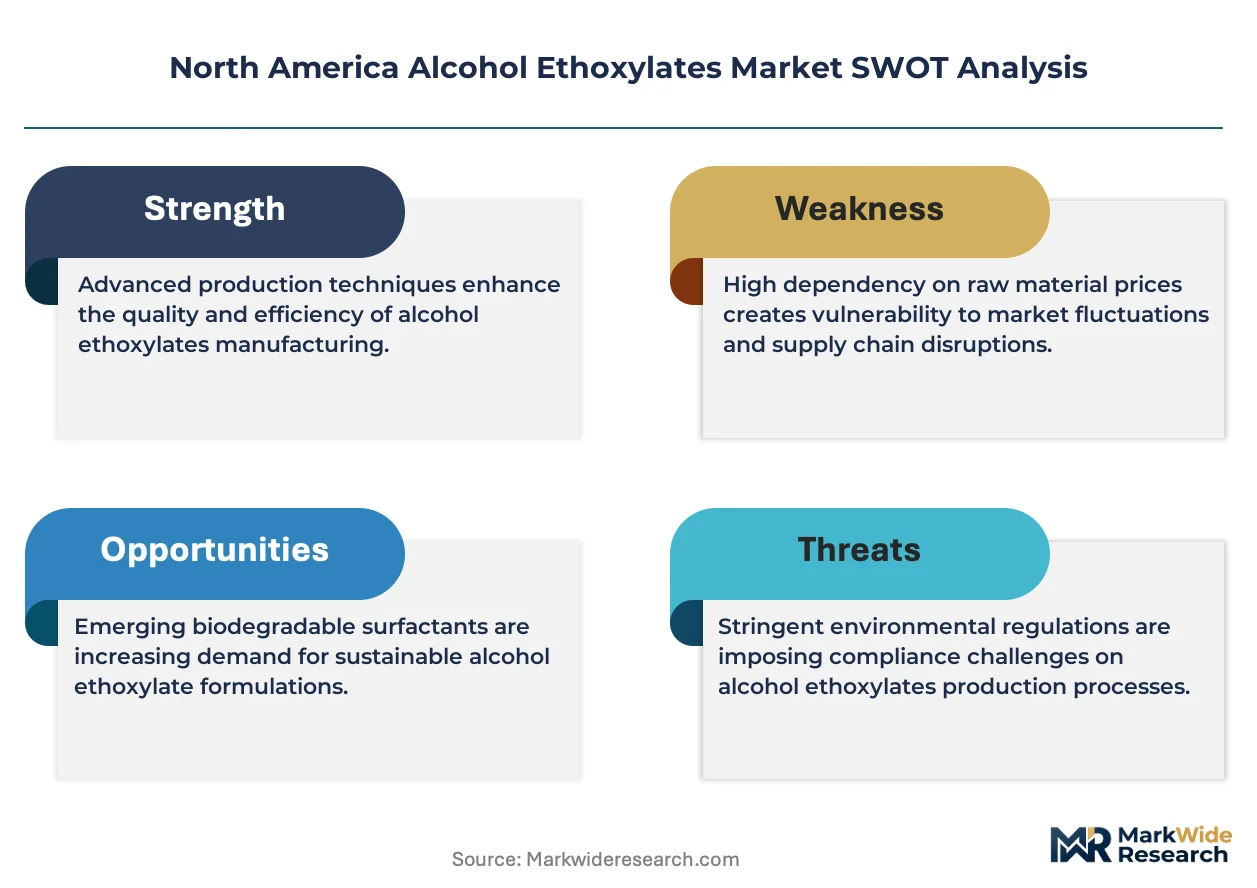
The EPA Safer Choice program and state-level California Safer Consumer Products regulations constrain alkylphenol ethoxylate alternatives and redirect formulators toward alcohol ethoxylate platforms. OSHA Process Safety Management standards govern ethylene oxide handling at production facilities, elevating capital requirements for new entrants. REACH-aligned substance evaluation through Health Canada and PMRA influences cross-border product registration timelines. Stakeholders must monitor bio-based feedstock certification trajectories and ethylene oxide supply reliability as dual determinants of margin stability.
Market Dynamics
Industrial cleaning formulators face mounting pressure from the EPA Safer Choice program to eliminate alkylphenol ethoxylate residues, redirecting procurement toward linear alcohol ethoxylates with certified biodegradability profiles. This regulatory pivot compresses margins for legacy surfactant suppliers while rewarding producers with integrated ethylene oxide access along the Gulf Coast.
Growth Catalysts
- Texas-Louisiana feedstock concentration:Ethylene oxide pipeline infrastructure along the US Gulf Coast anchors production economics for domestic alcohol ethoxylate manufacturing.
- EPA Safer Choice compliance mandates:Federal environmental standards are accelerating formulator migration from alkylphenol ethoxylates to alcohol ethoxylate platforms with verified aquatic toxicity profiles.
- Automated warewash systems:Industrial kitchens and food processing facilities are specifying low-foam, high-active ethoxylate grades compatible with precision dosing equipment.
Market Restraints
- Ethylene oxide supply concentration:Feedstock access clusters along the Texas-Louisiana corridor, exposing buyers to hurricane-related production disruptions and regional price volatility.
- OSHA Process Safety Management compliance:Ethylene oxide handling regulations elevate capital requirements for new production facilities, constraining capacity expansion by independent entrants.
- Branched alcohol ethoxylate substitution:Hard-water industrial degreasing segments retain demand for branched-chain alternatives with superior oil solubilization, limiting pure linear-grade penetration.
Strategic Opportunities
- Mexico manufacturing expansion:Cross-border production facilities can leverage USMCA trade provisions to serve southwestern US industrial cleaning markets with reduced logistics exposure.
- Bio-based feedstock certification:USDA BioPreferred and emerging state-level renewable content mandates create premium positioning for ethoxylates derived from palm kernel or coconut oil alcohols.
- Health Canada-PMRA alignment:REACH-equivalent substance evaluation timelines in Canada are compressing registration cycles for US producers seeking North American market coverage.
Industry Challenges
- Ethoxylate chain length precision:Narrow-range ethoxylation requires specialized reactor control systems and analytical chemistry expertise that concentrate among legacy producers.
- Legacy formulation integration:Hard-surface cleaning compounders face technical friction retrofitting automated dosing infrastructure designed for alkylphenol ethoxylate rheology profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alcohol Ethoxylates Market |
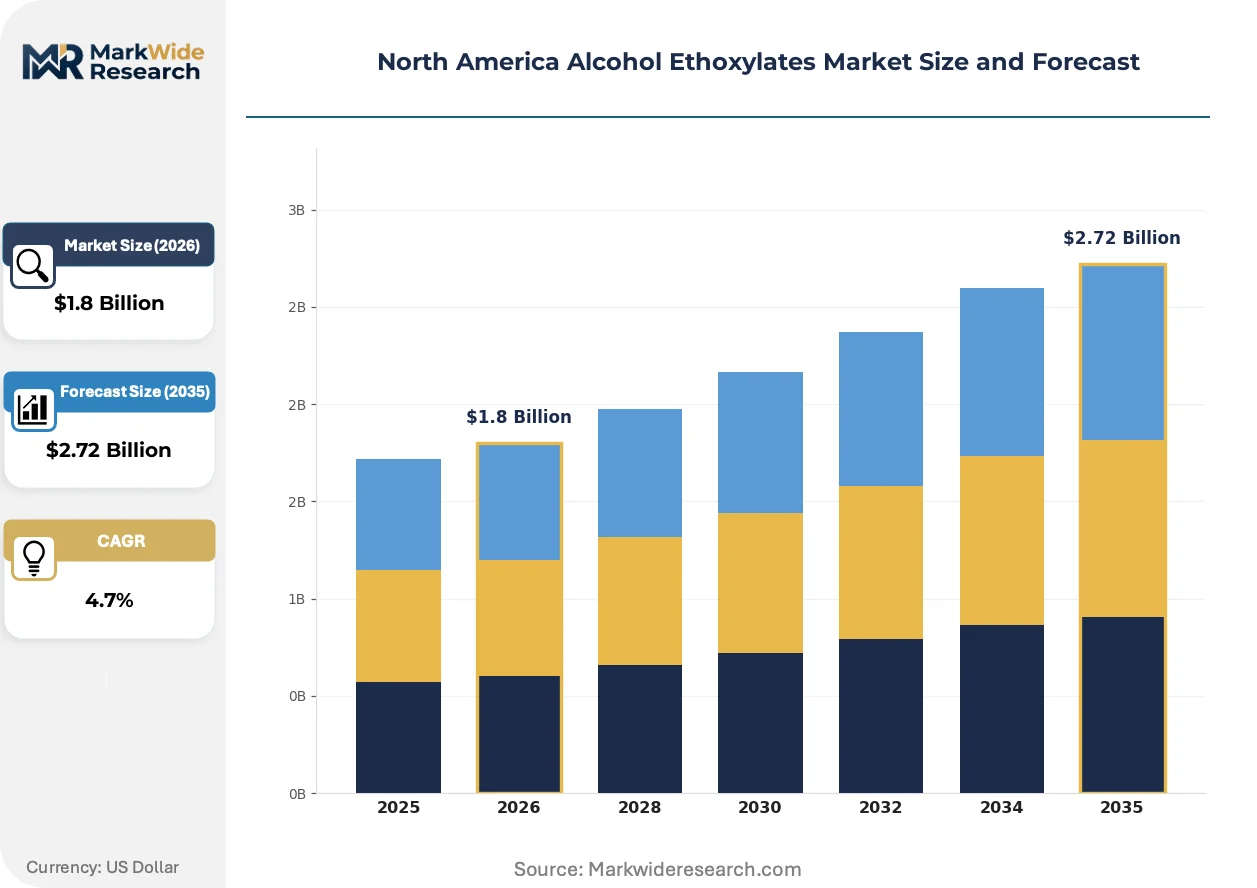
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alcohol Ethoxylates, Branched Alcohol Ethoxylates, Nonionic Surfactants, Amphoteric Surfactants End Use Industry: Personal Care, Household Cleaning, Industrial Cleaning, Agriculture Formulation Type: Liquid, Powder, Gel, Emulsion Packaging Type: Drum, Bag, Bottle, Tank |
| Companies Covered | Dow, Sasol Limited, BASF SE, Evonik Industries, Stepan Company, Huntsman International LLC, Royal Dutch Shell plc, AkzoNobel N.V., Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alcohol Ethoxylates Market Trends and Innovations
Formulation chemistry is fragmenting across multiple performance vectors as end-users demand simultaneous biodegradability compliance, hard-water tolerance, and concentrated active delivery. These pressures are compressing the viable design space for commodity surfactants.
Controlled molecular architecture is fragmenting the traditional broad-range ethoxylation market. Narrow-range alcohol ethoxylates with polydispersity indices below 1.2 deliver superior wetting kinetics and reduced foam stabilization. Industrial laundries and automated warewash operations are specifying these grades for water-heating energy reduction. The technology is fragmenting volume concentration among commodity producers unable to justify specialized reactor investments.
The EPA Safer Choice program is tightening ethoxylate chain length restrictions and aquatic toxicity thresholds for surfactant ingredients. Formulators must now document biodegradation half-lives and metabolite ecotoxicity through standardized OECD test protocols. Household and institutional cleaning products bearing the Safer Choice label command retail shelf placement advantages, pressuring non-compliant suppliers toward reformulation.
Specification-driven procurement is consolidating buyer power among national foodservice and hospitality chains. These operators are unbundling surfactant supply from finished detergent procurement, establishing direct relationships with alcohol ethoxylate producers for captive blending operations. The shift is most visible in Texas and California, where large institutional laundries operate centralized chemical management systems with automated inventory replenishment tied to usage telemetry.
North America Alcohol Ethoxylates Market Segmentation
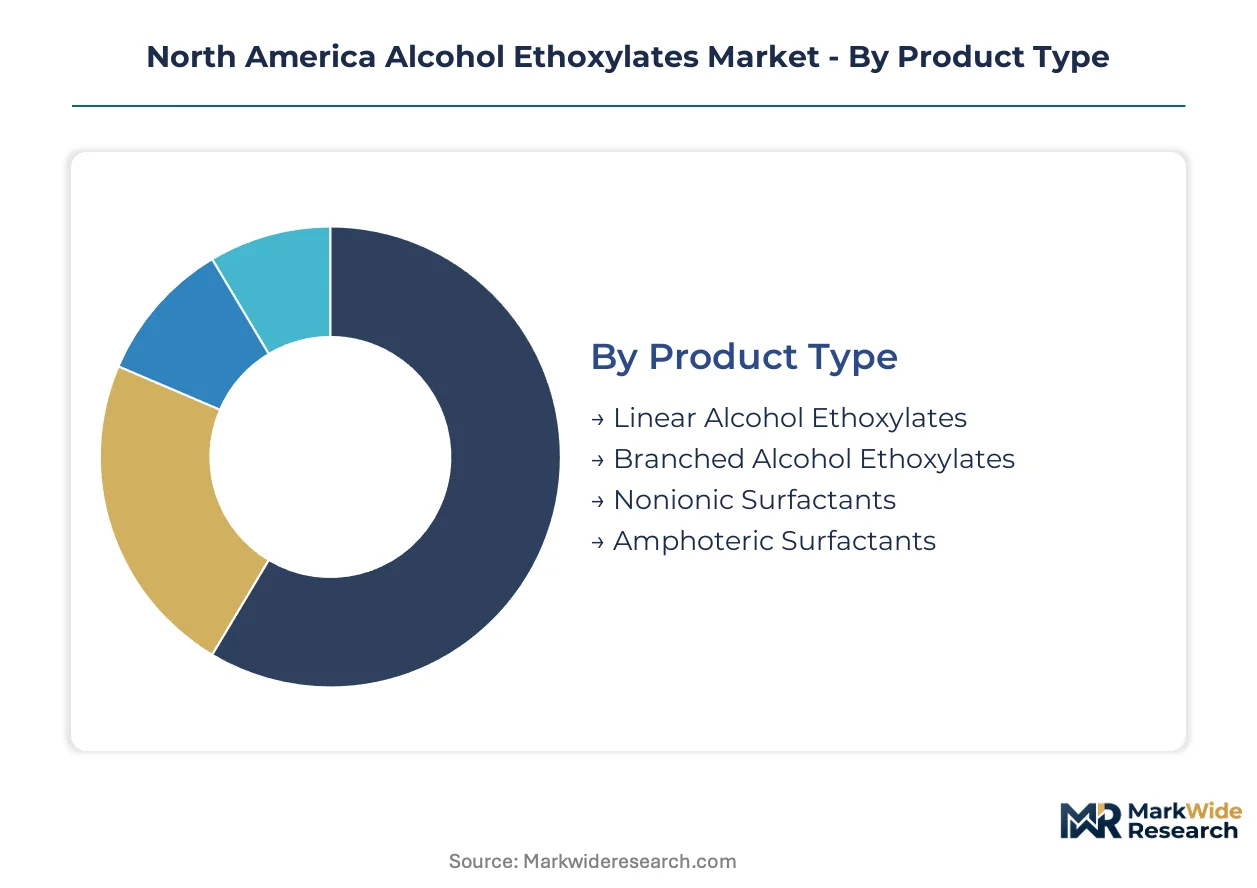
Segmentation in the North America alcohol ethoxylates market reveals how regulatory pressure and feedstock access reshape competitive positioning across product tiers. Each dimension carries distinct substitution risks and margin profiles that determine supplier strategy.
Product Type:
Substitution pressure from bio-based alternatives and regulatory phase-outs hits branched-chain and amphoteric grades hardest, while linear alcohol ethoxylates leverage EPA Safer Choice alignment to defend volume.
- Linear Alcohol Ethoxylates:These surfactants combine fatty alcohols with ethylene oxide to achieve hydrophilic-lipophilic balance values between 10 and 16, delivering superior biodegradability under EPA framework standards. Demand concentrates in Texas and Louisiana petrochemical corridors where integrated ethylene oxide pipelines anchor cost-competitive production against imported alternatives.
- Branched Alcohol Ethoxylates:Synthetic C12-C15 branched alcohols yield hard-water tolerance and rapid oil solubilization for industrial degreasing applications. Niche positioning in metalworking and heavy equipment cleaning segments commands price premiums, though EPA aquatic toxicity scrutiny constrains expansion into institutional formulations.
- Nonionic Surfactants:Broad functional class encompassing alcohol ethoxylates alongside alkoxylated esters and amides, with alcohol-derived variants capturing share from phased-out alkylphenol ethoxylates.
- Amphoteric Surfactants:Betaine and imidazoline derivatives serving personal care foam stabilization, facing substitution from milder nonionic systems in sulfate-free shampoo formulations.
Linear Alcohol Ethoxylates anchors the volume base while Branched Alcohol Ethoxylates gains share at the steepest rate in hard-water industrial niches.
End Use Industry:
Cost tier stratification separates commodity household applications from premium institutional and agricultural segments with divergent specification tolerances.
- Industrial Cleaning:Automated warewash systems and hard-surface formulations specify low-foam, high-active ethoxylate grades compatible with precision dosing equipment. Food processing facilities in California and Texas unbundle surfactant procurement from finished detergents, establishing direct supplier relationships for captive blending.
- Household Cleaning:Laundry detergents and all-purpose cleaners drive volume demand for standard-range ethoxylates with broad HLB compatibility. EPA Safer Choice label requirements are compressing margins for legacy formulators while rewarding producers with verified aquatic toxicity profiles.
- Personal Care:Shampoo and body wash applications favor narrow-range ethoxylation for reduced skin irritation, with sulfate-free trends displacing traditional amphoteric co-surfactants.
- Agriculture:Pesticide emulsifiers and adjuvants require specialized ethoxylate chain lengths for active ingredient compatibility, subject to Health Canada-PMRA and EPA dual registration timelines.
Household Cleaning dominates shipment volumes while Industrial Cleaning expands most quickly through automated system specification.
Formulation Type:
Volume concentration favors liquid delivery systems, though powder and gel formats serve distinct logistics and dissolution requirements.
- Liquid:Concentrated aqueous solutions lead shipment volumes through compatibility with automated dosing equipment and reduced packaging intensity. Industrial laundries and institutional kitchens specify liquid ethoxylates for centralized chemical management systems.
- Powder:Spray-dried granules serve remote agricultural applications and regions with limited bulk liquid handling infrastructure.
- Gel:Thickened formulations for manual dishwashing and specialty cleaning products where controlled dispensing and cling properties command formulation premiums.
- Emulsion:Oil-in-water systems for high-activity delivery in solvent-free degreasers, requiring specialized stabilization chemistry.
Liquid formulations anchor the volume base while Gel gains share at the steepest rate in premium manual-care segments.
Packaging Type:
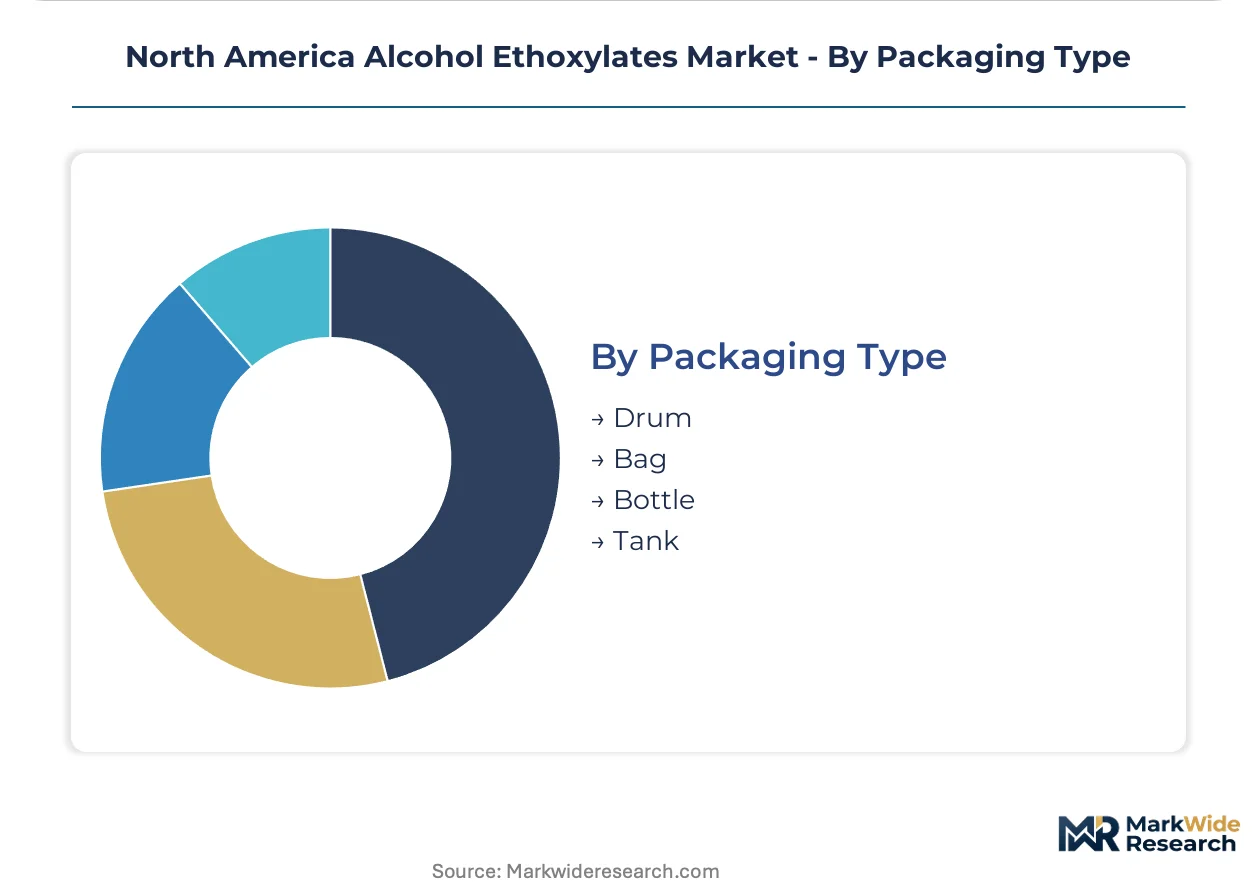
Customer type segmentation separates bulk tank deliveries to integrated formulators from drum and bag shipments to compounders and distributors.
- Drum:Standard 55-gallon steel and polyethylene containers serve mid-volume compounders with batch blending operations across the US Midwest and Southeast.
- Tank:Bulk tanker and tote deliveries to large institutional laundries and foodservice operators with automated inventory replenishment tied to usage telemetry.
- Bag:Flexible intermediate bulk containers and multi-wall sacks for powder formulations in agricultural and remote industrial applications.
- Bottle:Consumer and light commercial retail formats for specialty cleaning products and personal care applications.
Drum shipments anchor the volume base while Tank gains share at the steepest rate among national foodservice chains with centralized procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide pipeline infrastructure clusters along the US Gulf Coast, concentrating production economics for domestic alcohol ethoxylate manufacturing. This feedstock geography shapes regional supply reliability and cost structures across North American markets.
United States
Texas and Louisiana petrochemical corridors anchor integrated ethylene oxide supply for linear alcohol ethoxylate production. EPA Safer Choice program compliance mandates accelerate formulator migration from alkylphenol ethoxylates to certified biodegradable alternatives. California institutional laundries and foodservice operators unbundle surfactant procurement, establishing direct supplier relationships for captive blending operations.
Canada
Health Canada-PMRA REACH-equivalent substance evaluation compresses registration timelines for US producers seeking cross-border market coverage. Ontario and Quebec industrial cleaning formulators face parallel pressure to eliminate legacy surfactant residues under federal environmental standards. The Prairie Provinces serve agricultural adjuvant applications with specialized ethoxylate chain length requirements.
Mexico
Nuevo León and Mexico City Metro industrial zones present USMCA trade leveraged manufacturing expansion opportunities for southwestern US market service. The country's national environmental regulator tightens aquatic toxicity thresholds for institutional cleaning products. Cross-border production facilities reduce logistics exposure to Gulf Coast hurricane-related disruptions.
North America Alcohol Ethoxylates Market Competitive Landscape
Concentration sits with integrated petrochemical majors possessing captive ethylene oxide supply along the US Gulf Coast. Three to four producers command volume leadership through backward integration into feedstock production. The competitive terrain separates into integrated commodity suppliers, specialized narrow-range ethoxylation technologists, and regional formulation-anchored players. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term feedstock agreements and co-location with downstream formulators.
Among the integrated majors, Dow exemplifies the Gulf Coast-anchored archetype through its ethylene oxide pipeline infrastructure. Stepan Company occupies a position within the formulation-anchored tier, while Huntsman International LLC represents the specialized narrow-range ethoxylation segment. These three entities illustrate the strategic segmentation governing competitive positioning in North American alcohol ethoxylate supply.
| Leading Market Players |
|---|
| Dow |
| Sasol Limited |
| BASF SE |
| Evonik Industries |
| Stepan Company |
| Huntsman International LLC |
| Royal Dutch Shell plc |
| AkzoNobel N.V. |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
EPA Safer Choice certification gates both supplier qualification and price differentiation simultaneously, compressing margins for legacy surfactant producers while rewarding narrow-range ethoxylation specialists with verified biodegradability profiles. Industrial cleaning buyers leverage unbundled procurement to extract cost transparency from integrated Gulf Coast producers.
Pricing Analysis
EPA Safer Choice compliance dictates the pricing tier structure across the North America alcohol ethoxylates market. Pricing stratifies across premium narrow-range grades, standard linear formulations, and economy broad-range alternatives, with differentiation anchored in biodegradability certification and ethoxylate chain length precision. Cost compression in standard linear grades is intensifying because of feedstock volatility along the Texas-Louisiana corridor. National foodservice chains demonstrate lowest price sensitivity due to specification-locked automated systems, while regional compounders face acute margin pressure.
Supply Chain Analysis
Texas and Louisiana anchor ethylene oxide production for North American alcohol ethoxylate manufacturing. The supply chain draws from fatty alcohol feedstocks sourced from palm kernel and coconut oil origins, with ethylene oxide as the critical petrochemical input. Hurricane exposure along the Gulf Coast creates single-source vulnerability for domestic production. Distribution runs through bulk tank deliveries to institutional laundries and drum shipments to regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national foodservice and hospitality chains that unbundle surfactant procurement from finished detergents, fragmenting traditional supplier relationships and forcing price transparency.
For Market Incumbents: Consolidate backward integration into ethylene oxide supply through long-term pipeline agreements along the US Gulf Coast. Secure narrow-range ethoxylation reactor capacity to defend against commodity-grade substitution. EPA aquatic toxicity threshold tightening threatens legacy broad-range producers lacking specialized analytical chemistry capabilities. For New Entrants and Emerging Players: Anchor in Mexico manufacturing expansion targeting southwestern US industrial cleaning markets under USMCA trade provisions. The most penetrable white space sits in bio-based feedstock certification for institutional laundries seeking USDA BioPreferred positioning. Pursue toll manufacturing partnerships with established ethylene oxide pipeline operators to bypass OSHA Process Safety Management capital barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional surfactant compounders lacking integrated feedstock access. Long-term viability hinges on five-to-ten-year ethylene oxide supply contract coverage and narrow-range technology acquisition. Monitor Health Canada-PMRA registration timeline compression as inflection indicator for cross-border consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply from Texas-Louisiana pipelines insulates margin from feedstock volatility. |
| Narrow-Range Ethoxylation Capacity | Specialized reactor systems meet EPA Safer Choice chain length specifications for premium institutional buyers. |
| Bio-Based Feedstock Certification | USDA BioPreferred positioning captures state-level renewable content mandates in California and New York. |
| Cross-Border Manufacturing Expansion | USMCA-leveraged Mexico production reduces logistics exposure to Gulf Coast hurricane disruptions. |
| Direct Buyer Relationship Development | Unbundled procurement contracts with national foodservice chains lock in volume through automated system specification. |
Research Methodology
The analysis maps linear alcohol ethoxylates, branched alcohol ethoxylates, and narrow-range specialty grades, each validated through technical directors at industrial cleaning formulators, procurement leads at institutional laundries, plant managers at Gulf Coast ethoxylation facilities, and regulatory affairs specialists navigating EPA Safer Choice protocols. Primary interview findings triangulate against secondary sources including EPA chemical substance databases, ACC surfactant production reports, SEC 10-K filings from integrated petrochemical majors, and Health Canada PMRA registration tracking. Bottom-up volume builds from end-use consumption patterns reconcile with top-down ethylene oxide derivative demand estimates.
Volume and value outputs were validated against external benchmarks including ethylene oxide consumption trends and surfactant trade flow data across the analysis window. The analytical framework models segmentation across product grade tier, end-use industry, formulation type, and regional production hub. CAGRs derive from ethylene oxide feedstock cost trajectories and EPA regulatory compliance cost absorption rates. Forecast inputs include ethoxylate chain length specification shifts and automated warewash system penetration curves.
Underlying assumptions cover ethylene oxide pipeline reliability, EPA Safer Choice program continuity, and USMCA trade provision stability, with deviation risk concentrated in hurricane-related production disruptions and state-level renewable content mandate acceleration. Recalibration cycles align with material shifts in EPA aquatic toxicity thresholds and bio-based feedstock certification adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Squalane Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Global White Oil Market