
 Iso-Octene Market | 2026-2036
Iso-Octene Market Size, Share, and Industry Trends Forecast 2026-2036
Iso-Octene Market Foresight
The EU Green Deal is realigning iso-octene procurement criteria across European fuel additive and polymer supply chains. ExxonMobil leverages its integrated refinery-chemical complexes to sustain cost-competitive polymer-grade output. Shell anchors its position through proprietary hydroprocessing technology that differentiates its high-purity grade streams. LyondellBasell competes on geographic proximity to German automotive formulators, while TotalEnergies navigates evolving bio-based feedstock mandates through strategic R&D partnerships.
Iso-octene is a branched C8 olefin produced primarily via dimerization of isobutylene or fluid catalytic cracking streams, with a boiling point near 101°C and high octane blending value that makes it critical for gasoline pool optimization. Its primary commercial purpose centers on fuel additive formulations, synthetic lubricant base stocks, and polymerization feedstocks where branching density controls product performance. Chemical grade iso-octene dominates volume throughput due to established refinery integration, while polymer grade commands margin premiums from adhesive and synthetic lubricant producers seeking controlled molecular weight distribution. High purity grade represents the fastest-expanding segment as pharmaceutical and cosmetic manufacturers tighten feedstock specification thresholds under REACH and FDA purity protocols.
The EPA fuels and additives program governs U.S. blending allowances and renewable volume obligations that shape iso-octene incorporation rates in domestic gasoline pools. EMA pharmaceutical purity standards and REACH substance restrictions in Europe filter market access for non-compliant producers, compressing supplier lists in high-specification segments. China's GB standards for fuel composition and MIIT industrial chemical regulations are introducing parallel compliance layers for exporters serving Asian polymer markets. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines that determine competitive positioning in grade-specific segments.
Market Dynamics
Refinery-chemical integration economics are compressing merchant iso-octene margins as integrated majors internalize C8 olefin streams for captive fuel additive and polymer applications. This structural concentration is forcing independent producers toward specialty high-purity grades to escape commodity pricing gravity.
Growth Catalysts
- Fuel Pool Reformulation Mandates:The EPA's renewable volume obligations and Tier 3 sulfur standards are expanding high-octane blending component demand across US gasoline refiners. Iso-octene's 101°C boiling point and branching density deliver optimal volatility control for reformulated summer-grade fuels.
- REACH-Driven Purity Escalation:ECHA substance restrictions and pharmaceutical-grade certification requirements are redirecting European adhesive and synthetic lubricant formulators toward polymer-grade iso-octene with documented molecular weight distribution.
- Hydroprocessing Advances:Proprietary catalytic dimerization technologies are enabling refinery operators to upgrade fluid catalytic cracking off-gases directly into polymer-grade streams, bypassing traditional isobutylene feedstock constraints.
Market Restraints
- Isobutylene Feedstock Volatility:Merchant iso-octene producers face margin compression when steam cracker operating rates fluctuate, as isobutylene spot availability tightens during ethylene demand peaks.
- Integrated Supply Concentration:The US Gulf Coast and Rotterdam-Antwerp corridor host over 70% of Western iso-octene conversion capacity, creating geographic vulnerability to regional refinery maintenance cycles and hurricane disruptions.
- Alkylate Substitution Pressure:Refiners with sulfuric acid alkylation units can substitute iso-octane for iso-octene in high-octane gasoline pools, capping premium pricing during octane margin contractions.
Strategic Opportunities
- Bio-Based Feedstock Pathways:The EU Green Deal's renewable fuel mandates and RED III targets are creating qualification pathways for iso-octene produced from bio-isobutylene via fermentation-derived routes.
- Pharmaceutical Excipient Expansion:FDA and EMA purity protocols for topical formulation bases are opening specification windows for high-purity iso-octene in transdermal drug delivery systems.
- Synthetic Lubricant Base Stock Growth:Polyalphaolefin producers in Germany and Belgium are expanding polymer-grade offtake for viscosity index improver applications in electric vehicle thermal management fluids.
Industry Challenges
- REACH Registration Timelines:ECHA's substance evaluation backlog is extending registration-to-market intervals for new high-purity grade entrants, freezing qualification pipelines for 18-24 month cycles.
- Refinery-Chemical Coordination:Iso-octene producers must synchronize production campaigns with downstream fuel additive formulators' just-in-season blending schedules, compressing effective operating windows.
- Analytical Method Harmonization:Divergent GC-MS specification protocols between ASTM D6730 and EN 15553 are forcing dual certification investments for suppliers serving transatlantic polymer markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iso-Octene Market |
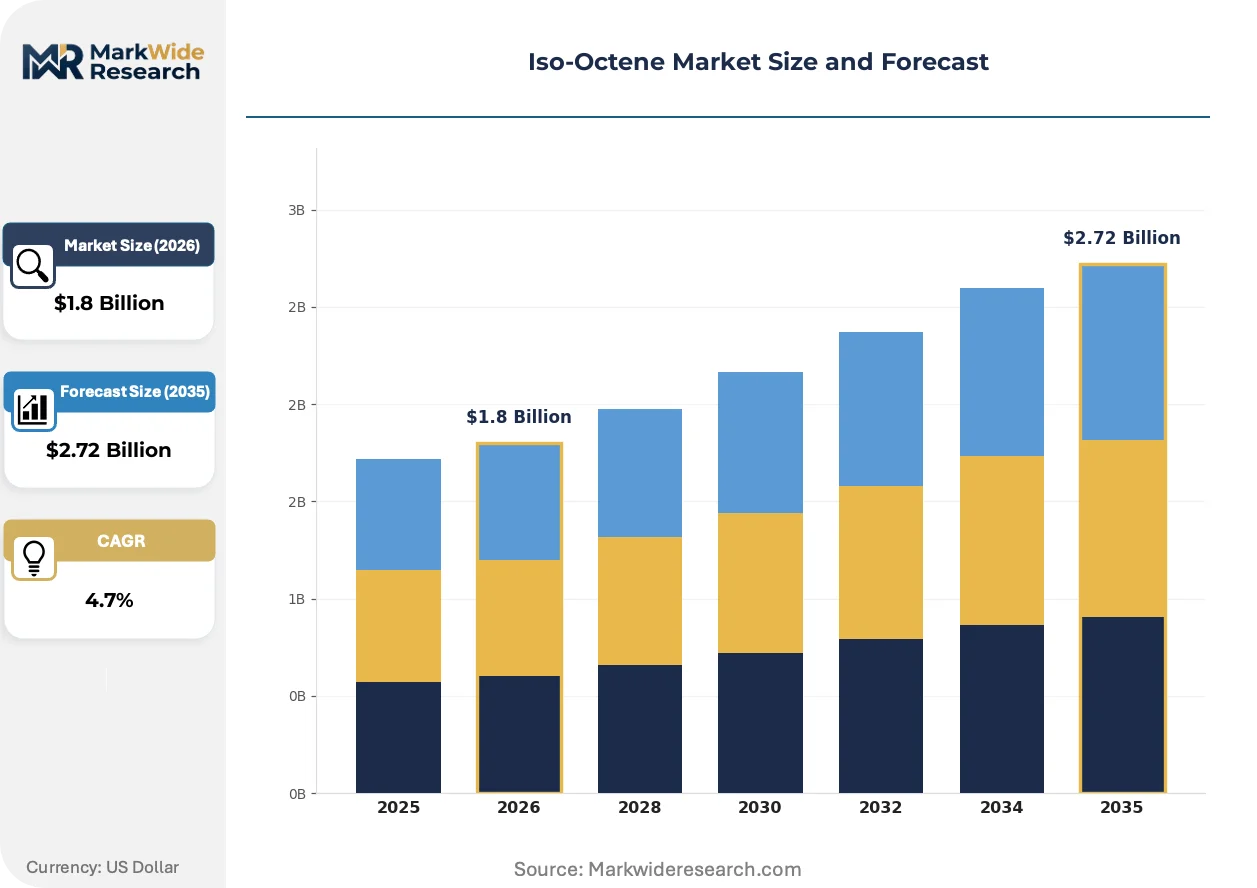
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Grade, Technical Grade, Polymer Grade, High Purity Grade End User: Automotive Industry, Cosmetic Manufacturers, Pharmaceuticals, Adhesive Producers Application: Fuel Additive, Synthetic Lubricants, Polymer Production, Surfactants Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | ExxonMobil, Shell, BP, Gazprom, Borealis, LyondellBasell, Phillips 66, TotalEnergies, Valero Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iso-Octene Market Shifts & Advancements
Process intensification and regulatory precision are converging to redefine competitive advantage in iso-octene supply chains. Technology differentiation now centers on feedstock flexibility and analytical certification depth rather than scale economies alone.
Membrane-assisted reactive distillation is converging with conventional catalytic dimerization to enable direct iso-octene recovery from mixed C4 refinery streams without intermediate isobutylene purification. German chemical engineers at industrial-scale pilot facilities are deploying this hybrid approach to reduce steam consumption by one-third. The technology is converging with established refinery infrastructure to unlock stranded FCC off-gas value that was previously routed to fuel gas.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is redirecting polyurethane formulators toward iso-octene-derived alkoxylates as physical foaming agents with lower global warming potential. ECHA's updated restriction proposals for persistent organic pollutants are accelerating substitution timelines in construction insulation applications. REACH-registered iso-octene oxide derivatives are capturing specification share in rigid foam systems across Benelux and Northern France manufacturing clusters.
Specification-driven spot purchasing is displacing annual volume contracts among European synthetic lubricant blenders seeking molecular weight distribution certificates for each delivery lot. Third-party analytical verification services in Rotterdam are capturing margin from this fragmentation by offering rapid GC-MS batch certification. German automotive formulators are most visibly adopting this procurement model to satisfy OEM audit requirements for adhesive raw material traceability.
Iso-Octene Market Segmentation
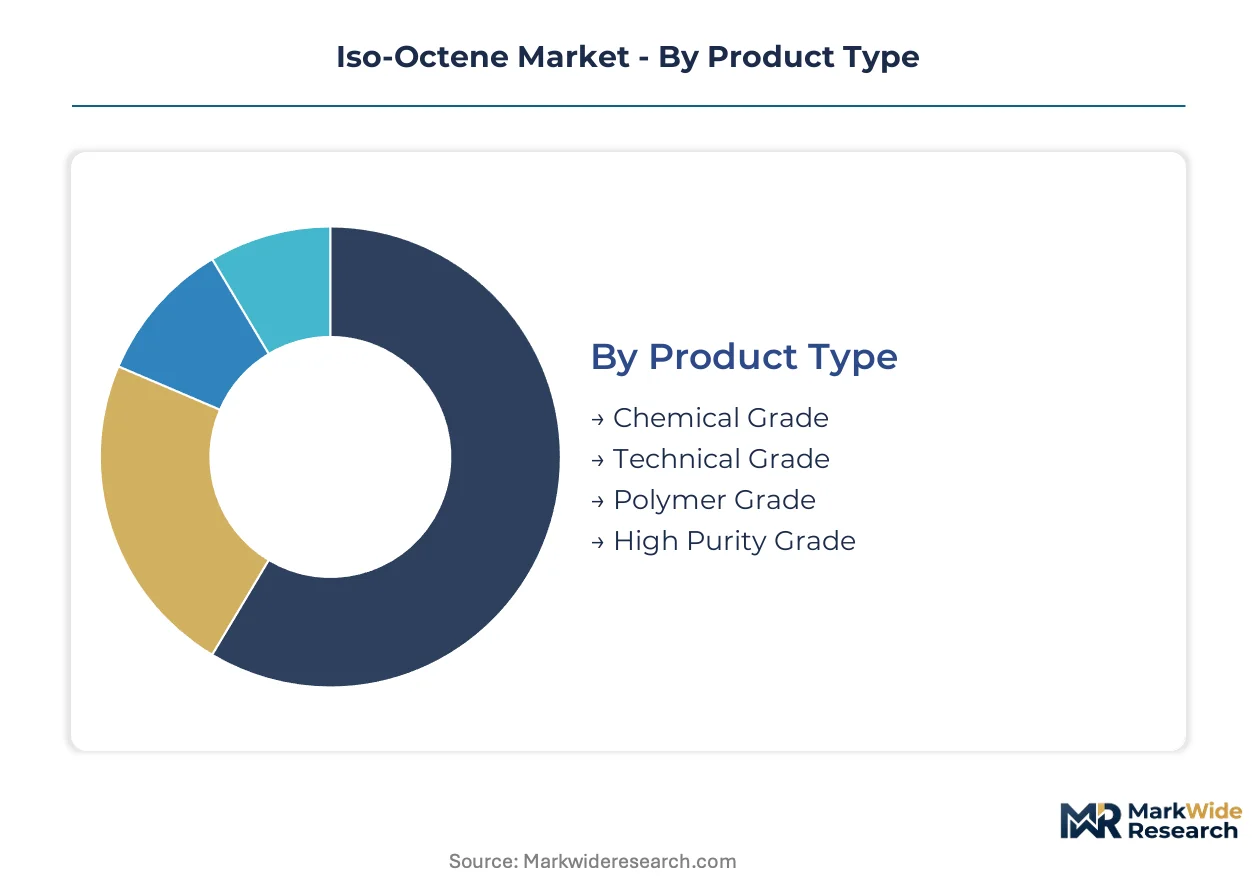
Iso-octene segmentation reflects divergent purity requirements across fuel additive, polymer, and pharmaceutical applications. Grade-specific certification thresholds determine supplier qualification pipelines and margin structures. Each segment category carries distinct procurement patterns tied to downstream formulator compliance obligations.
Product Type:
Integration depth varies sharply: chemical grade operates as standalone refinery output, while polymer and high purity grades embed into multi-step formulation chains with certificate-of-analysis requirements.
- Chemical Grade:Produced via catalytic dimerization of isobutylene or FCC C4 streams with standard 95-98% purity specifications. Refinery-integrated producers in the US Gulf Coast and Rotterdam-Antwerp corridor internalize these volumes for captive fuel additive blending, compressing merchant spot availability during octane margin peaks.
- Polymer Grade:Characterized by controlled molecular weight distribution and branching density for viscosity index improver synthesis. German synthetic lubricant blenders and Belgian polyalphaolefin producers concentrate demand here, driven by OEM audit requirements for adhesive raw material traceability under REACH substance restrictions.
- Technical Grade:Intermediate purity tier serving industrial surfactant and general chemical synthesis applications where analytical certification depth remains limited.
- High Purity Grade:Pharmaceutical and cosmetic-grade material meeting FDA and EMA protocols for topical formulation bases, with documented impurity profiles per batch.
Chemical grade leads volumes today; high purity grade is gaining share fastest.
End User:
Cost tier stratification separates commodity fuel additive buyers from premium pharmaceutical and cosmetic formulators willing to absorb certificate-driven pricing.
- Automotive Industry:Gasoline refiners and fuel additive formulators constitute the volume anchor, purchasing chemical grade iso-octene for octane pool optimization under EPA Tier 3 sulfur standards.
- Pharmaceuticals:Transdermal drug delivery system manufacturers specify high purity grade with GC-MS verification, creating 18-24 month qualification pipelines through ECHA registration backlogs.
- Cosmetic Manufacturers:Topical formulation producers in France and Switzerland source high purity grade for excipient applications under EMA purity protocols.
- Adhesive Producers:German automotive formulators drive polymer grade offtake for synthetic lubricant and adhesive applications requiring molecular weight distribution documentation.
Automotive industry leads volumes today; pharmaceuticals is expanding most quickly.
Application:
Application maturity spans decades-old fuel additive incorporation versus emerging pharmaceutical excipient qualification.
- Fuel Additive:Iso-octene's 101°C boiling point and high octane blending value position it for reformulated summer-grade gasoline production. EPA renewable volume obligations and sulfur standards sustain refiner demand across US gasoline pools.
- Synthetic Lubricants:Polyalphaolefin base stock producers in Germany and Belgium leverage polymer grade for viscosity index improvers in electric vehicle thermal management fluids.
- Polymer Production:Adhesive and sealant manufacturers incorporate iso-octene derivatives for controlled crosslinking density in construction and automotive assembly applications.
- Surfactants:Alkoxylate producers serving polyurethane foam systems substitute iso-octene-derived physical foaming agents under EU F-Gas Regulation hydrofluorocarbon phasedown mandates.
Fuel additive leads volumes today; synthetic lubricants shows steepest expansion trajectory.
Distribution Channel:
Channel selection tracks formulator scale and certification burden: large refiners favor direct supply while specialty buyers fragment across certified distributors.
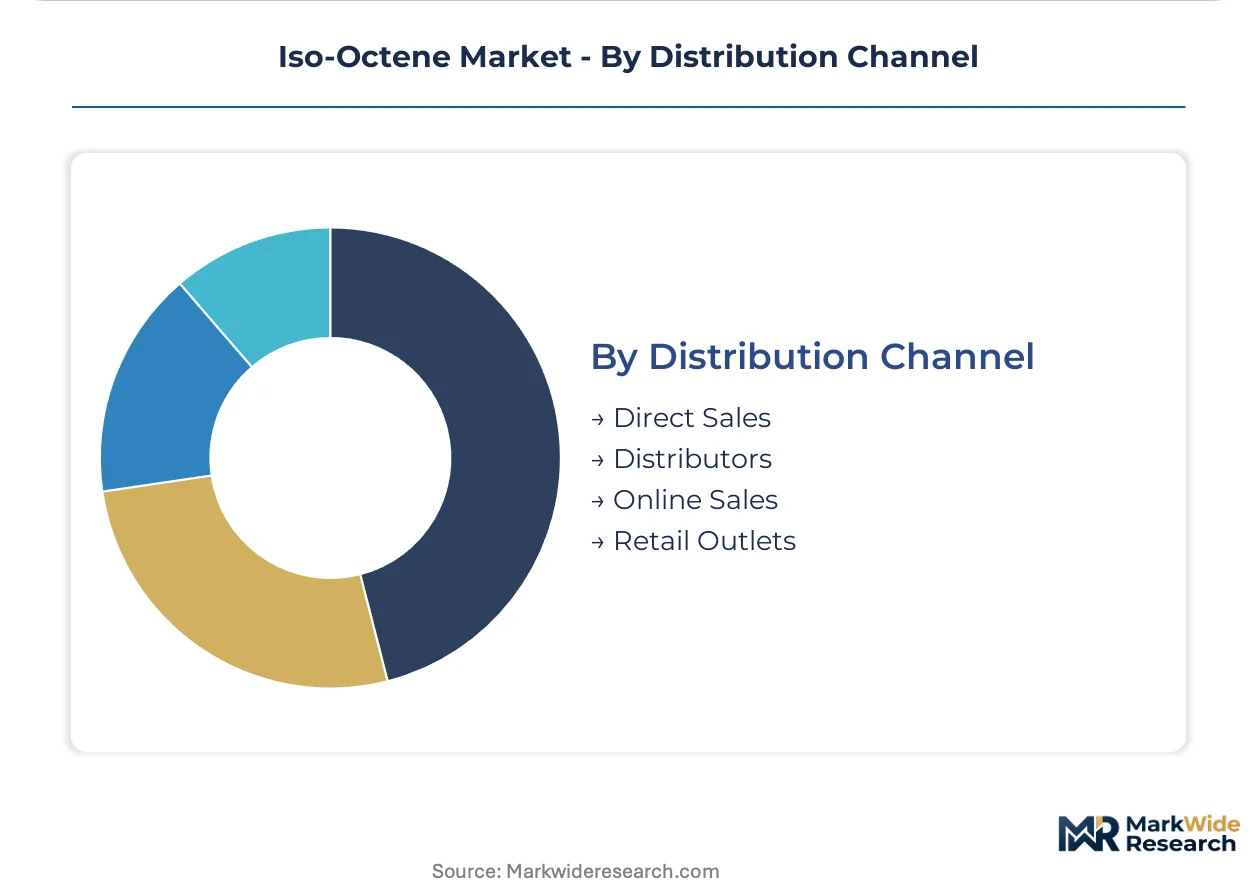
- Direct Sales:Refinery-integrated majors and large fuel additive blenders negotiate annual offtake agreements with specification-driven pricing adjustments.
- Distributors:Rotterdam-based third-party analytical verification services capture margin from fragmented European synthetic lubricant blender procurement.
- Online Sales:Limited to technical grade and small-volume laboratory reagent purchases with standardized certificates of analysis.
- Retail Outlets:Minimal presence given bulk chemical handling requirements and regulatory documentation obligations.
Direct sales leads volumes today; distributors is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial iso-octene production first achieved industrial scale in the United States during the post-war refinery expansion era, with the US Gulf Coast establishing the foundational dimerization infrastructure that subsequent European and Asian producers would later replicate.
United States
EPA Tier 3 sulfur standards and renewable volume obligations sustain refiner demand for high-octane blending components across Midwest and Gulf Coast gasoline pools. The EPA fuels and additives program governs incorporation rates, creating compliance-driven procurement cycles. Houston and Beaumont host concentrated catalytic dimerization capacity serving captive fuel additive integration.
Germany
Polyalphaolefin producers in the Rhine-Ruhr corridor drive polymer-grade offtake for synthetic lubricant base stocks and electric vehicle thermal management fluids. REACH substance restrictions and ECHA registration requirements filter supplier qualification pipelines. Ludwigshafen and Marl chemical clusters anchor European high-purity grade specification development.
Belgium
The Antwerp-Rotterdam port complex handles bulk C4 olefin feedstock flows supporting merchant iso-octene conversion for adhesive and sealant manufacturers. EU F-Gas Regulation hydrofluorocarbon phasedown redirects polyurethane formulators toward iso-octene-derived alkoxylates. Ghent and Feluy production sites concentrate viscosity index improver supply for German automotive formulators.
China
MIIT industrial chemical regulations and GB standards for fuel composition introduce parallel compliance layers for domestic refiners and exporters serving Asian polymer markets. The dual carbon goals framework pressures state-owned refiners toward lower-carbon feedstock pathways. Ningbo and Dalian chemical zones scale fluid catalytic cracking off-gas upgrading for regional adhesive producers.
Netherlands
Rotterdam-based third-party analytical verification services capture margin from fragmented European synthetic lubricant blender procurement patterns. EMA pharmaceutical purity standards and REACH documentation requirements concentrate high-purity grade distribution logistics. The Europoort refining cluster sustains merchant spot availability during regional maintenance cycles.
Iso-Octene Market Competitive Landscape
Premium-margin players sit above commodity-margin players across grade certification depth, with polymer-grade and high-purity specialists commanding sustained pricing power over chemical-grade commodity producers. The competitive terrain stratifies into three archetypes: integrated refinery-chemical majors with captive offtake, merchant producers dependent on spot isobutylene availability, and specialty high-purity grade specialists serving pharmaceutical qualification pipelines. Capacity expansion and strategic R&D partnerships constitute the dominant competitive moves as players navigate bio-based feedstock mandate evolution.
Among integrated energy majors, ExxonMobil and Shell exemplify the refinery-chemical integration archetype, while LyondellBasell occupies a position within the polymer-grade specialization tier. TotalEnergies represents the strategic pivot archetype, navigating renewable feedstock transitions through partnership-based R&D structures. These named entities anchor the competitive landscape without exhausting its full composition.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP |
| Gazprom |
| Borealis |
| LyondellBasell |
| Phillips 66 |
| TotalEnergies |
| Valero Energy |
| Others |
Supply & Pricing Matrix
The EU Green Deal's renewable fuel mandates gate qualified supply access and premium-tier pricing power across European iso-octene procurement. REACH registration depth and ECHA substance evaluation timelines separate certified polymer-grade suppliers from commodity chemical-grade merchants, compressing margin capture into documentation-intensive tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies iso-octene procurement by certification burden and molecular weight distribution precision. Polymer-grade material with REACH-registered COA documentation commands sustained premiums from German adhesive formulators, while chemical-grade spot volumes face compression during octane margin contractions at Gulf Coast refiners. Price differentiation rests on analytical certification depth and captive refinery integration status. Merchant producers without backward control of isobutylene feedstock absorb the sharpest cost pressure when steam cracker operating rates peak. Fuel additive blenders exhibit highest price sensitivity due to volumetric procurement scale, whereas pharmaceutical excipient buyers prioritize batch-verified impurity profiles over unit economics.
Supply Chain Analysis
EMA pharmaceutical purity protocols and REACH substance restrictions gate supply chain participation through 18-24 month qualification pipelines. Geographic concentration centers on the United States, Germany, and Belgium, with the US Gulf Coast and Rotterdam-Antwerp corridor hosting over two-thirds of Western conversion capacity. Raw material flows draw from fluid catalytic cracking off-gases, steam cracker C4 streams, and merchant isobutylene spot markets. Single-source vulnerability intensifies around Rotterdam's third-party analytical verification services, where fragmented synthetic lubricant blender procurement concentrates documentation logistics. Distribution runs through direct annual offtake agreements for refinery-integrated majors and certified distributor networks for specialty high-purity grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iso-octene functions as a stable compounder anchored by EPA Tier 3 sulfur standards and renewable volume obligations that sustain refiner demand through regulatory compliance cycles.
For Market Incumbents: To counter merchant margin compression from integrated refinery-chemical internalization, deepen captive isobutylene supply through FCC off-gas upgrading investments and secure polymer-grade qualification pipelines with German automotive formulators ahead of ECHA registration backlogs. For New Entrants and Emerging Players: E-commerce laboratory reagent channels offer lowest barrier entry for technical-grade iso-octene with standardized COA documentation, targeting underpenetrated cosmetic excipient buyers in France and Switzerland seeking FDA-compliant topical formulation bases without established supplier relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialty high-purity grade specialists because ECHA substance evaluation timelines freeze competitive entry for 18-24 month cycles, creating durable moats around REACH-registered production assets. Watch for inflection signals in bio-isobutylene fermentation pathway cost curves as EU RED III mandates accelerate renewable feedstock qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FCC Off-Gas Upgrading | Shell's proprietary hydroprocessing technology demonstrates refinery-chemical margin capture from stranded C4 stream value. |
| REACH Registration Acceleration | LyondellBasell's German automotive formulator proximity reduces ECHA backlog exposure for polymer-grade qualification. |
| Bio-Based Feedstock Partnership | TotalEnergies' R&D alliances navigate EU Green Deal renewable fuel mandates through fermentation-derived isobutylene pathways. |
| Third-Party Analytical Verification Scale-Up | Rotterdam certification services capture margin from fragmented European synthetic lubricant blender spot purchasing fragmentation. |
| Pharmaceutical Excipient Qualification | High-purity grade producers leverage FDA and EMA topical formulation protocols for transdermal drug delivery system expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, polymer-grade procurement leads at German adhesive formulators, Rotterdam-based distribution channel partners, and ECHA regulatory affairs specialists with secondary validation from customs trade data, SEC refinery segment disclosures, Cefic chemical industry reports, and EPA fuels program regulatory filings. Bottom-up grade-specific volume builds triangulated against top-down refinery capacity assessments across the analysis window.
Segment-weighting approaches distributed value and volume projections across chemical, polymer, and high-purity grade tiers, with further disaggregation by fuel additive, synthetic lubricant, pharmaceutical excipient, and surfactant application endpoints. CAGRs derived from regression against EPA renewable volume obligation trajectories, EU F-Gas Regulation hydrofluorocarbon phasedown timelines, and electric vehicle thermal management fluid adoption curves. Modeling incorporated steam cracker operating rate volatility, REACH registration completion forecasts, and refinery-chemical integration economics throughout the projection horizon.
Feedstock price volatility, ECHA evaluation backlog extensions, and alkylate substitution elasticity at US refiners are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EPA renewable volume obligation stringency or EU RED III bio-based mandate enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Cetyl Esters Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
1-Decene Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
US Esters Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Allyl Caproate Market