
 Glycerol Esters Market | 2026-2036
Glycerol Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Esters Market Outlook
Market Context
Pharmaceutical-grade glycerol ester specifications are redrawing competitive boundaries across the industry. BASF SE leverages its integrated oleochemicals platform to sustain supply security for high-purity monoesters. Croda International Plc anchors its position through lipid-specialization R&D intensity in pharmaceutical and personal care channels. Godrej Industries competes on backward integration into palm oil refining, controlling raw material cost structures across Asian markets.
Technical Definition and Segment Structure
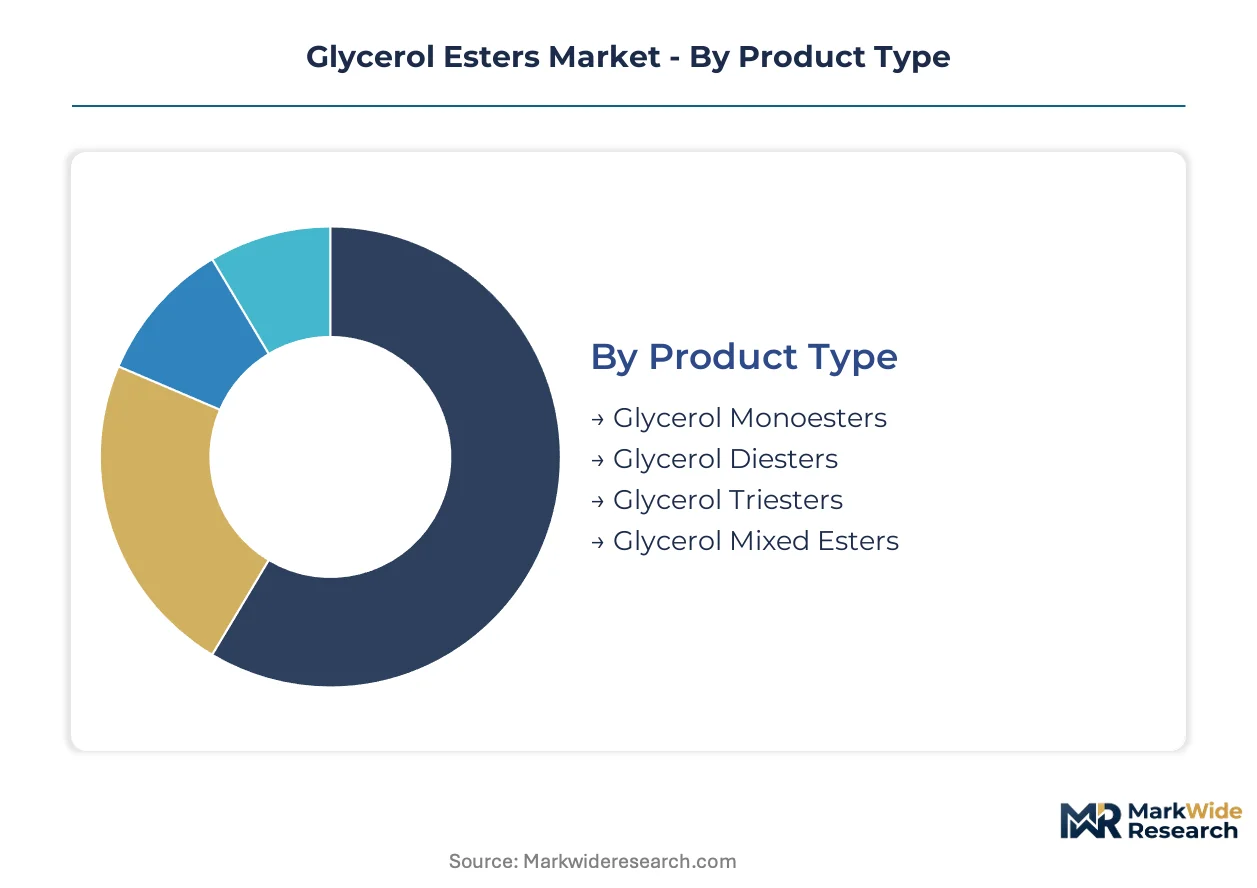
Glycerol esters comprise fatty acid esters of glycerol ranging from mono- through tri-substitution, produced via direct esterification or transesterification of glycerol with vegetable-derived fatty acids at controlled temperatures and pressures to achieve specified hydrophilic-lipophilic balance values. These compounds function primarily as emulsifiers, stabilizers, and lubricants across food, cosmetic, and pharmaceutical formulations. Glycerol monoesters command the dominant share within product type segmentation due to established food-grade emulsifier demand, while glycerol mixed esters represent the fastest-expanding category as manufacturers seek multifunctional additives for simplified labeling. Personal care applications concentrate margin pools through premium cosmetic-grade specifications, whereas industrial applications operate at volume-driven, thinner economics.
Regulatory Framework and Outlook
FDA food additive regulations and EFSA purity standards govern glycerol ester acceptance in food and pharmaceutical channels, with REACH registration requirements in Europe adding compliance layers for import-dependent suppliers. India's FSSAI and BIS standards are tightening contaminant thresholds for domestic nutraceutical applications, forcing reformulation investments among local compounders. Stakeholders must monitor evolving biobased certification schemes and carbon accounting rules that will increasingly determine supplier qualification beyond traditional purity metrics.
Market Dynamics
Clean-label emulsifier specifications from Southeast Asian food processors are compressing supplier margins while simultaneously expanding volume requirements, forcing glycerol ester manufacturers to reconfigure purification investments without passing full cost burdens downstream.
Growth Catalysts
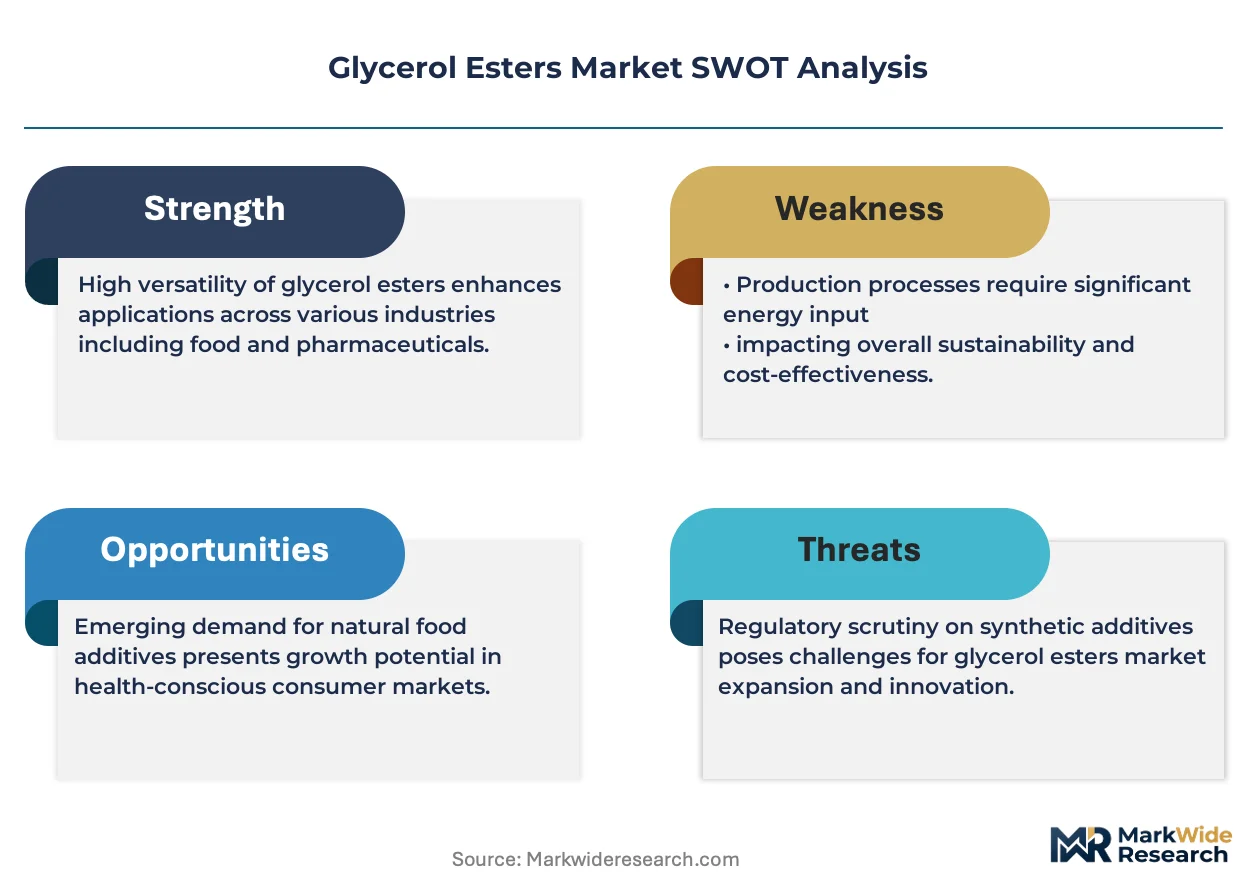
- PLI scheme incentives:India's production-linked incentive framework for specialty chemicals is accelerating domestic oleochemical capacity expansion, drawing regional investment toward captive glycerol ester output.
- Clean-label emulsifier demand:Southeast Asian food processors are scaling glycerol monoester usage to replace synthetic alternatives in bakery and dairy formulations.
- REACH compliance premiums:European purity specifications are creating qualification barriers that favor established high-purity monoester suppliers with existing registration dossiers.
Market Restraints
- Palm oil price volatility:Raw material cost swings in Malaysian and Indonesian feedstock markets transmit directly to glycerol ester producer margins.
- High-purity capacity concentration:Pharmaceutical-grade monoester production remains concentrated among integrated oleochemical platforms with captive fatty acid supply.
- Fatty acid ester competition:Sorbitan esters and propylene glycol esters compete for emulsifier slots in cost-sensitive food applications.
Strategic Opportunities
- Nutraceutical-grade expansion:India's tightening FSSAI contaminant thresholds for domestic nutraceutical applications create first-mover advantage for compliant local compounders.
- Biobased certification schemes:Emerging carbon accounting rules and sustainability certifications will determine supplier qualification beyond traditional purity metrics.
- Multifunctional mixed esters:Simplified labeling demands from European clean-label brands are accelerating glycerol mixed ester adoption across premium food segments.
Industry Challenges
- Pharmaceutical-grade validation timelines:CDSCO and FDA drug master file submissions for excipient-grade glycerol esters extend commercialization cycles by 18-24 months.
- Legacy equipment retrofit costs:Continuous esterification reactor upgrades to achieve specified hydrophilic-lipophilic balance precision demand capital commitments mid-tier producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Esters Market |
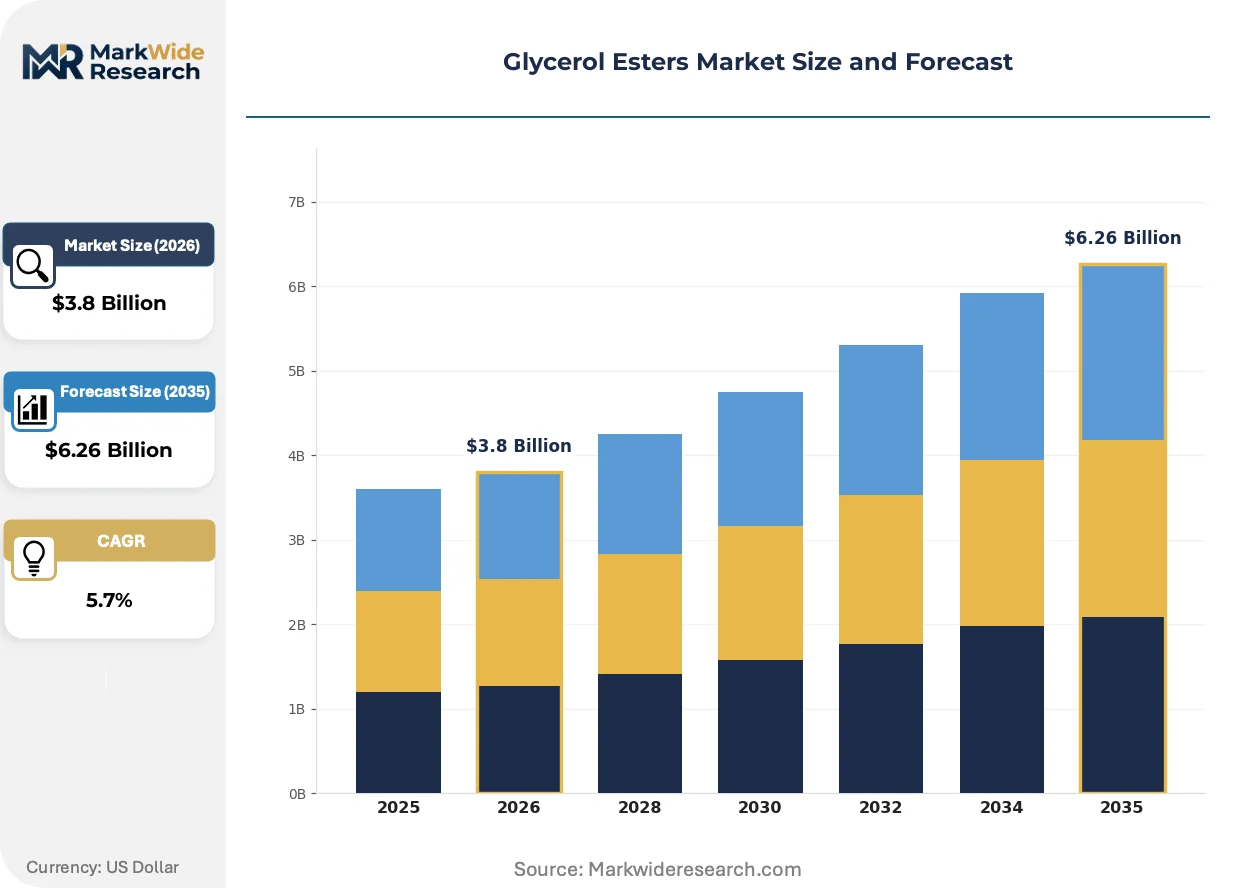
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerol Monoesters, Glycerol Diesters, Glycerol Triesters, Glycerol Mixed Esters Application: Food & Beverage, Personal Care, Pharmaceuticals, Industrial End Use Industry: Cosmetics, Food Processing, Nutraceuticals, Textile Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | Stepan Company, Godrej Industries, BASF SE, Cargill, Wilmar International, Croda International Plc, Evonik Industries AG, Lonza Group AG, Oleon NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Esters Market Strategic Shifts
Enzymatic esterification processes are fragmenting traditional chemical routes, while regulatory carbon accounting and biobased verification schemes are layering new compliance dimensions atop existing purity standards.
Enzymatic glycerol ester production using immobilized lipase catalysts is fragmenting the competitive landscape between chemical and biocatalytic process licensors. Specialty chemical manufacturers in the Netherlands and Germany are piloting continuous enzymatic systems to achieve selective monoester ratios without thermal degradation. This technology is fragmenting capital allocation patterns, as enzyme immobilization equipment and biocatalyst supply contracts displace conventional pressure vessel investments.
EFSA purity standard revisions for food-contact glycerol esters are tightening 3-MCPD and glycidyl ester limits ahead of full REACH reauthorization cycles. European compounders must validate supply chains back to crude glycerol origin to demonstrate contaminant control. Personal care applications face the steepest compliance ramps, as cosmetic-grade specifications now exceed former food-grade thresholds.
Direct procurement relationships between Southeast Asian food processors and Malaysian oleochemical refiners are compressing traditional distributor layers. Bulk emulsifier buyers in Indonesia and Thailand now negotiate annual tonnage contracts with refinery-attached esterification units, bypassing regional traders. This channel consolidation is most visible in mono- and diglyceride categories where specification standardization permits arm's-length contracting.
Glycerol Esters Market Segmentation
Glycerol ester specifications fragment sharply across end-use channels, with pharmaceutical and cosmetic grades commanding substantial premiums over industrial volumes. Segmentation discipline separates margin-rich specialty positions from commodity emulsifier plays.
Product Type:
Margin pools concentrate in high-purity monoester fractions where pharmaceutical and food-grade specifications create qualification barriers.
- Glycerol Monoesters:Single fatty acid substitution on glycerol backbone delivers precise hydrophilic-lipophilic balance values for emulsifier functionality. Food processors in Indonesia and Thailand are scaling annual tonnage contracts with Malaysian refinery-attached esterification units for bakery and dairy applications. REACH registration dossiers and EFSA purity standards favor established suppliers with existing contaminant control validation.
- Glycerol Mixed Esters:Variable substitution patterns combine mono-, di-, and tri-ester fractions in tunable ratios for multifunctional additive performance. European clean-label brands are accelerating adoption across premium food segments seeking simplified ingredient declarations. Enzymatic production using immobilized lipase catalysts enables selective monoester ratios without thermal degradation.
- Glycerol Diesters:Dual fatty acid substitution provides intermediate lipophilicity for cosmetic base formulations and lubricant applications.
- Glycerol Triesters:Fully substituted triglyceride analogs serve industrial lubricant and textile processing markets at volume-driven economics.
Glycerol monoesters hold installed capacity. Glycerol mixed esters are rotating up the share rankings.
Application:
Application tiering reflects regulatory burden intensity, with pharmaceutical and personal care channels absorbing compliance costs that food and industrial segments reject.
- Personal Care:Cosmetic-grade specifications now exceed former food-grade thresholds for 3-MCPD and glycidyl ester limits under EFSA revisions. Lipid-specialization R&D intensity anchors competitive positioning in premium skincare and haircare formulations. Specialty chemical manufacturers in the Netherlands and Germany are piloting continuous enzymatic systems for selective ester production.
- Food & Beverage:Clean-label emulsifier specifications from Southeast Asian processors are compressing supplier margins while expanding volume requirements for bakery, dairy, and confectionery applications. Direct procurement relationships between Indonesian and Thai buyers and Malaysian refiners are bypassing traditional distributor layers.
- Pharmaceuticals:Excipient-grade glycerol esters require CDSCO and FDA drug master file submissions extending commercialization cycles.
- Industrial:Lubricant and processing aid applications operate at thinner margins with specification standardization permitting arm's-length contracting.
Personal care commands the steepest compliance ramps. Food and beverage is expanding most quickly in absolute volume terms.
End Use Industry:
Customer concentration patterns separate fragmented cosmetic compounders from consolidated food processing multinationals.
- Food Processing:Southeast Asian bakery and dairy manufacturers are replacing synthetic emulsifiers with glycerol monoesters for clean-label positioning. Annual tonnage contracts with refinery-attached esterification units are consolidating procurement channels.
- Cosmetics:Premium skincare and haircare brands in Europe are tightening cosmetic-grade specifications beyond former food-grade thresholds. EFSA purity standard revisions for food-contact applications are transmitting upward into personal care requirements.
- Nutraceuticals:India's FSSAI and BIS standards are tightening contaminant thresholds for domestic applications, forcing reformulation investments among local compounders.
- Textile:Industrial processing aid demand concentrates in Asian manufacturing clusters with thinner margin structures.
Food processing anchors volume demand. Nutraceuticals is climbing the fastest in specification intensity.
Form:
Physical form selection tracks downstream handling infrastructure and formulation integration requirements.
- Liquid:Pumpable concentrates dominate bulk food emulsifier and industrial lubricant applications with lower handling costs.
- Powder:Free-flowing particulates serve dry mix formulations in bakery premixes and cosmetic powder compacts.
- Granular:Controlled particle size distribution enables precise dosing in automated food processing lines.
- Emulsion:Pre-dispersed aqueous systems simplify incorporation for cosmetic and pharmaceutical formulators lacking high-shear equipment.
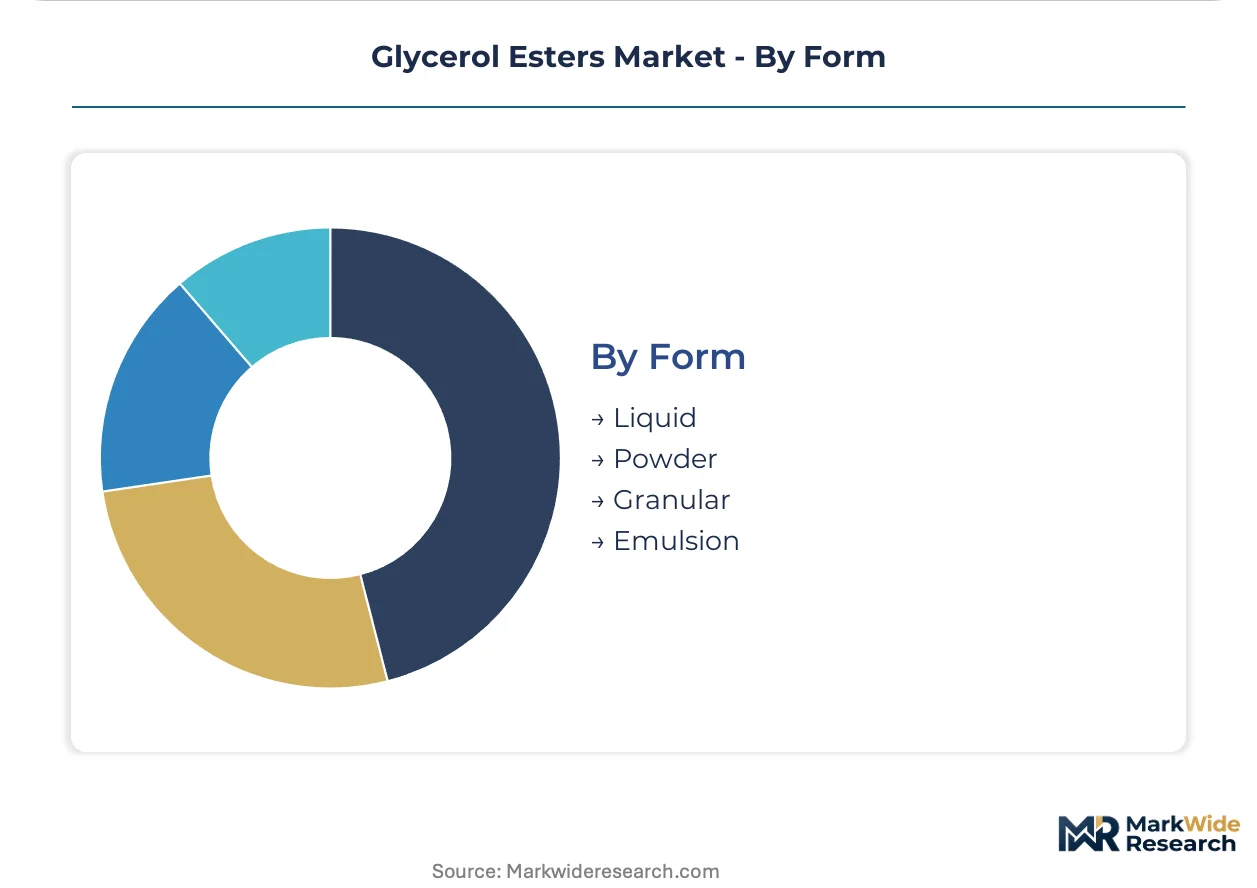
Liquid maintains processing efficiency advantages. Powder is gaining share fastest in dry mix convenience formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oleochemical refineries in Malaysia and Indonesia supply the bulk of fatty acid feedstock, while pharmaceutical-grade purification capacity clusters in Western Europe and parts of India. Demand fragmentation follows clean-label food processing expansion in Southeast Asia and nutraceutical formulation growth in South Asia.
United States
Food processors in the Midwest and California are reformulating bakery and dairy lines to replace synthetic emulsifiers with glycerol monoesters for clean-label positioning. FDA food additive standards and evolving GRAS notification pathways are tightening documentation requirements for imported ester lots. Chicago and Minneapolis house regional distribution hubs serving reformulation laboratories and contract manufacturers.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia are piloting continuous enzymatic esterification systems using immobilized lipase catalysts. REACH registration dossiers and EFSA purity standard revisions for 3-MCPD limits are consolidating supplier qualification around established high-purity monoester producers. The Cologne-Düsseldorf corridor anchors lipid-specialization R&D intensity for pharmaceutical and personal care channels.
India
Domestic oleochemical capacity expansion in Gujarat and Maharashtra is drawing regional investment toward captive glycerol ester output under PLI scheme incentives for specialty chemicals. FSSAI and BIS standards are tightening contaminant thresholds for nutraceutical applications, forcing reformulation investments among Mumbai and Ahmedabad compounders. CDSCO drug master file submissions for excipient-grade specifications extend commercialization cycles by 18-24 months.
Indonesia
Bakery and dairy manufacturers in Java are scaling annual tonnage contracts directly with Malaysian refinery-attached esterification units, bypassing traditional distributor layers. The country's national food safety regulator is aligning domestic additive standards with ASEAN harmonization frameworks for cross-border trade. Surabaya and Jakarta industrial zones concentrate procurement consolidation for mono- and diglyceride categories.
Netherlands
Personal care formulators in Rotterdam and Amsterdam are tightening cosmetic-grade specifications beyond former food-grade thresholds under EFSA purity transmission effects. Biobased certification schemes and emerging carbon accounting rules are layering new compliance dimensions atop existing REACH registration requirements. The Port of Rotterdam cluster serves as a distribution nexus for European pharmaceutical and cosmetic compounders.
Glycerol Esters Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with enzymatic process specialists competing against integrated oleochemical platforms with captive fatty acid supply. The market structure separates pharmaceutical-grade monoester producers with validated contaminant control from food-grade volume suppliers operating at thinner margins. Three archetypes dominate: backward-integrated palm oil refiners controlling raw material structures, lipid-specialization R&D houses serving premium personal care channels, and regional compounders leveraging PLI incentives for domestic capacity. Dominant competitive moves include direct procurement relationship formation with Southeast Asian food processors and continuous reactor upgrades to achieve specified hydrophilic-lipophilic balance precision.
Within the integrated oleochemical tier, BASF SE and Godrej Industries occupy positions shaped by upstream control over feedstock supply chains. BASF SE exemplifies the Western European high-purity monoester supplier archetype with established REACH registration dossiers. Godrej Industries represents the Asian backward-integrated model with captive palm oil refining capacity. Croda International Plc sits within the lipid-specialization R&D intensity segment, anchoring competitive positioning in pharmaceutical and personal care channels through technical service depth rather than scale economics.
| Leading Market Players |
|---|
| Stepan Company |
| Godrej Industries |
| BASF SE |
| Cargill |
| Wilmar International |
| Croda International Plc |
| Evonik Industries AG |
| Lonza Group AG |
| Oleon NV |
| Others |
Value Chain & Pricing Dynamics
Enzymatic esterification replacing thermal processes in European pilot plants is redrawing supply geography toward biocatalyst hubs while compressing pharmaceutical-grade pricing premiums as immobilized lipase systems achieve selective monoester ratios without degradation.
Pricing Analysis
REACH registration dossiers dictate the pricing tier structure across European pharmaceutical and personal care channels. Pricing stratifies across excipient-grade, food-grade, and industrial-grade tiers with certification level and volume scale as primary differentiation drivers. Cost compression in food-grade monoesters is intensifying because Southeast Asian processors negotiate direct annual tonnage contracts with Malaysian refiners. Industrial lubricant buyers exhibit highest price sensitivity while cosmetic compounders absorb premium pricing for EFSA-compliant specifications.
Supply Chain Analysis
Malacca Strait transit underwrites feedstock security for Asian oleochemical platforms serving glycerol ester production. Supply concentrates in Malaysia, Indonesia, and India with palm oil fatty acids, crude glycerol, and immobilized enzyme biocatalysts as critical inputs. Single-source vulnerability runs through Malaysian refinery-attached esterification units that bypass traditional distributor layers. Distribution runs through direct procurement relationships between Indonesian and Thai food processors and upstream refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label interoperability between food processors and cosmetic formulators is creating platform economics where shared glycerol ester specifications enable supplier qualification across previously siloed channels.
For Market Incumbents: Fortify contaminant control validation to defend against enzymatic process specialists achieving REACH-compliant purity without thermal infrastructure. Backward integration into palm oil refining secures raw material cost structures against Malaysian and Indonesian feedstock volatility. Prioritize continuous reactor upgrades to maintain hydrophilic-lipophilic balance precision specifications. For New Entrants and Emerging Players: Anchor in India's nutraceutical-grade expansion under tightening FSSAI thresholds where domestic compounders face 18-24 month CDSCO validation timelines. Target Gujarat and Maharashtra for PLI-supported captive capacity with first-mover advantage in compliant local production. Pursue technical service partnerships with Mumbai and Ahmedabad formulators lacking excipient-grade supply security. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European lipid-specialization houses holding EFSA-validated dossiers but lacking enzymatic transition capital. Five-to-ten year viability favors platforms with dual chemical-biocatalytic process flexibility and established clean-label brand relationships. Monitor immobilized lipase catalyst cost curves as inflection signal for process economics tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Refining | Godrej Industries exemplifies upstream control securing feedstock cost structures across Asian markets. |
| Continuous Enzymatic Esterification Deployment | Specialty chemical manufacturers in North Rhine-Westphalia pilot immobilized lipase systems for selective monoester production. |
| REACH Registration Dossier Investment | BASF SE leverages existing high-purity validation to consolidate European pharmaceutical-grade supply positions. |
| Direct Procurement Relationship Formation | Indonesian and Thai food processors bypass distributor layers through annual tonnage contracts with Malaysian refiners. |
| Biobased Certification Program Alignment | Rotterdam personal care formulators layer carbon accounting compliance atop existing EFSA purity standards. |
Study Parameters
A spread of perspectives from oleochemical plant managers, food processor procurement leads, cosmetic formulator R&D directors, and distribution channel partners converged on the working assumptions. Primary interviews combined with customs/trade data, SEC 10-K filings, FSSAI regulatory notices, and EFSA scientific opinions provided secondary validation. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Segmentation dimensions modeled include product type tier, end-use industry, purity grade specification, and regional production hub across the analysis window. CAGRs derived from installed capacity expansion trajectories, PLI scheme incentive uptake rates, and clean-label reformulation penetration curves. Forecast inputs incorporated enzymatic process adoption timelines and REACH reauthorization cycle impacts.
Material uncertainties — palm oil price volatility, CDSCO validation delays, and EFSA 3-MCPD limit revisions — sit outside the modeled envelope. Forecasts reflect assumptions about PLI scheme continuity and ASEAN harmonization progress. Practitioners should keep alternative scenarios live as biocatalyst cost curves and carbon accounting rule finalizations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Oleophilic Materials Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Global White Oil Market
Oleochemicals
Alpha Olefin Sulfonates Market