
 Enzymatically Interesterified Oils Market | 2026-2036
Enzymatically Interesterified Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymatically Interesterified Oils Market Foresight
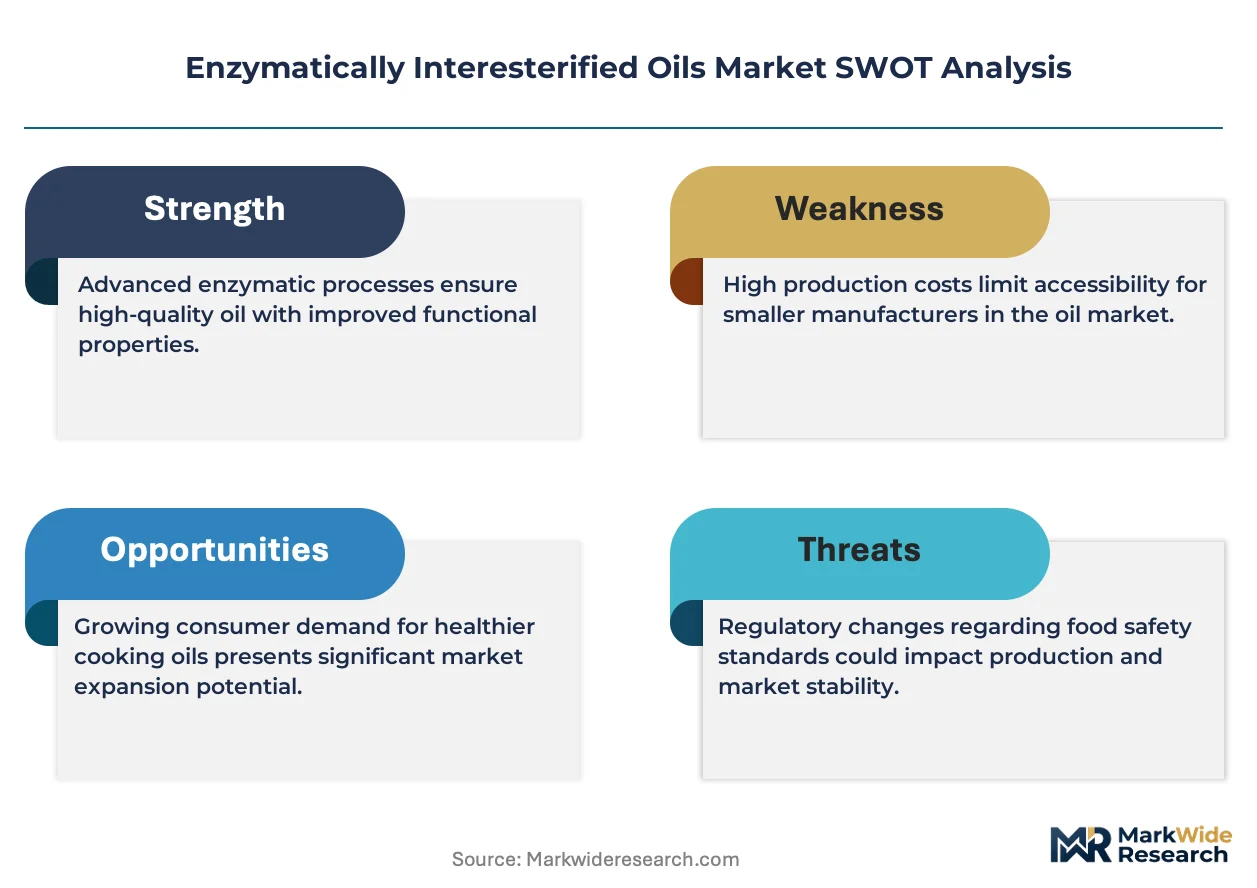
A capital-intensity divergence between integrated plantation-refiners and standalone enzyme technology suppliers is bifurcating competitive returns in the enzymatically interesterified oils sector. Wilmar International Limited leverages backward integration into Indonesian palm estates to sustain cost-advantaged feedstock security. Cargill, Incorporated anchors North American soybean oil interesterification through controlled crush capacity and food-grade certification depth. AAK KAMANI Pvt. Ltd. specializes in premium specialty fats for confectionery applications, differentiating through tailored slip-point engineering and clean-label positioning.
Enzymatically interesterified oils are triglyceride matrices restructured through lipase-catalyzed acyl exchange, typically operating at 60-80°C with 1,3-specific or non-specific enzymes to achieve targeted solid fat content profiles without chemical interesterification's sodium methoxide residues. The process yields plastic fats with precise melting behaviors for margarine, shortening, and cocoa butter equivalents. Vegetable oils dominate current throughput volumes given palm and soybean oil abundance, while specialty fats command concentrated margin pools in chocolate confectionery and infant formula applications where precise polymorphic stability is mandatory. The food industry application segment leads absolute consumption, though cosmetics companies are expanding interesterified oil procurement for emollient formulations requiring oxidative stability and skin-feel customization.
FDA food additive regulations and GRAS self-affirmation pathways shape US market access requirements for novel enzymatic processes, while EFSA evaluates lipase-derived lipid modifications under the EU Novel Food Regulation for non-traditional restructuring methods. BIS standards in India and FSSAI food safety protocols further segment export qualification burdens for multinational refiners. Stakeholders must monitor evolving enzyme supplier consolidation and regional oleochemical feedstock cost spreads to determine capacity placement and partnership structures.
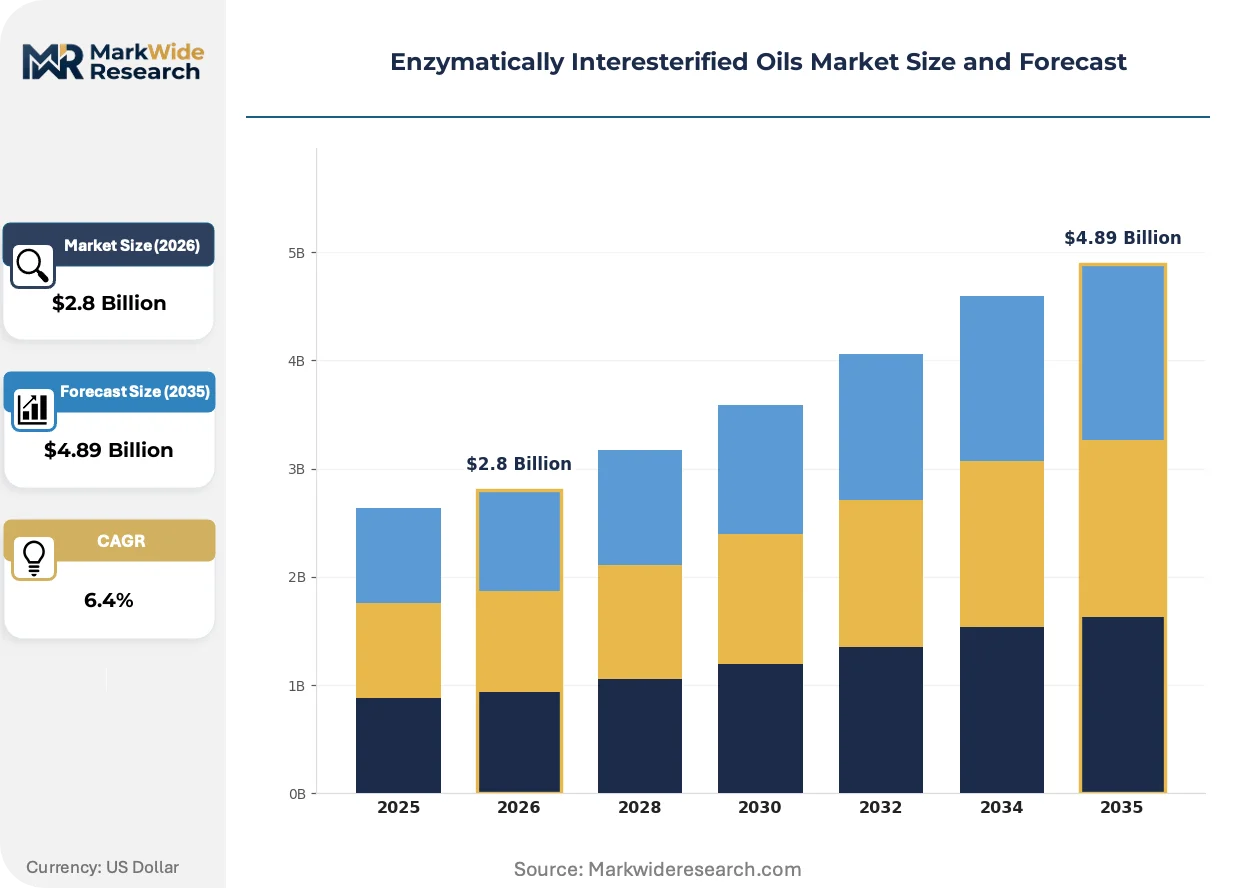
Market Dynamics
The enzymatically interesterified oils sector pivots on tightening regulatory thresholds for chemical residues in food-grade lipids, compelling processors to abandon sodium methoxide-based interesterification in favor of lipase-catalyzed restructuring across margarine and confectionery applications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon cooling agents in European lipid processing facilities accelerates enzyme-based process adoption to eliminate temperature-intensive chemical stages.
- Bakery sector procurement:Industrial bakeries in Germany and France are specifying enzymatically interesterified palm oil variants for laminated dough applications requiring precise plasticity ranges.
- Indonesian refining clusters:Integrated plantation-to-refinery complexes in Sumatra and Kalimantan are expanding dedicated enzymatic capacity to capture premium export certification tiers.
Market Restraints
- Lipase enzyme cost volatility:Fermentation-derived 1,3-specific lipases from Aspergillus niger and Rhizomucor miehei strains command 3-5x the per-kilogram cost of chemical catalysts, compressing processor margins at sub-scale volumes.
- Feedstock concentration risk:Malaysian and Indonesian palm oil supplies dominate input matrices, exposing refiners to El Niño-induced harvest volatility and export duty fluctuations.
- Processing rate limitations:Enzymatic interesterification operates at 60-80°C with 4-12 hour residence times versus 30-minute chemical cycles, constraining throughput at existing reactor infrastructure.
Strategic Opportunities
- Indian oleochemical expansion:BIS standards alignment and FSSAI food safety protocol maturation are enabling enzymatically interesterified oil qualification for domestic infant formula and chocolate compound manufacturers.
- Cosmetics emollient applications:Skincare formulators are sourcing interesterified jojoba and shea derivatives for oxidative stability in premium lotion and balm products.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams and national biorefinery tax credits in the Netherlands and Denmark subsidize enzymatic process retrofits.
Industry Challenges
- Enzyme immobilization engineering:Refiners face persistent catalyst deactivation in fixed-bed reactor configurations, requiring specialized protein engineering partnerships to extend lipase reusability cycles.
- GRAS self-affirmation complexity:Novel lipase strains and non-traditional acyl donors trigger extended FDA review timelines, delaying US market entry for innovative restructuring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzymatically Interesterified Oils Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Synthetic Oils, Specialty Fats Application: Food Industry, Cosmetics, Pharmaceuticals, Biodiesel Delivery Mode: Bulk, Drums, Totes, Retail Packs End User: Food Manufacturers, Cosmetics Companies, Oil Refiners, Research Institutions |
| Companies Covered | Wilmar International Limited, Fuji Oil Co., Ltd., Cargill, Incorporated, Intercontinental Specialty Fats SDN. BHD., AAK KAMANI Pvt. Ltd., Archer Daniels Midland Company, IOI Corporation Berhad, Adams Group, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymatically Interesterified Oils Market Shifts & Advancements
Continuous processing architectures and immobilized enzyme bed designs are restructuring capital deployment patterns among mid-scale refiners, compressing batch-cycle economics while enabling real-time solid fat content modulation.
Immobilized lipase reactor systems employing cross-linked enzyme aggregates (CLEAs) and magnetic nanoparticle supports are supplanting stirred-tank batch configurations in European and Southeast Asian refineries. Chocolate manufacturers in Belgium and Switzerland are adopting these continuous-flow platforms to achieve polymorphic stability in cocoa butter equivalents without tempering variability. The technology is supplanting traditional chemical interesterification for premium confectionery applications where sodium methoxide residue thresholds approach detection limits.
EFSA evaluation protocols under the EU Novel Food Regulation are tightening documentation requirements for enzymatically modified lipid structures not present in the conventional food supply. Processors must now submit comprehensive toxicological dossiers and 90-day feeding studies for new acyl positional distributions. Infant formula manufacturers in Ireland and the Netherlands are front-loading regulatory investment to secure early-mover advantage in specialized fat ingredient qualification.
Brand owners are consolidating supplier relationships around refiners offering integrated certification packages spanning RSPO Mass Balance, ISO 22000, and custom clean-label attestations. Bakery and confectionery procurement teams in France and Germany are reducing qualified vendor lists from 8-12 to 3-4 strategic partners capable of delivering documented enzyme provenance and carbon footprint accounting. This concentration is most visible in the German industrial margarine sector, where Rewe and Aldi Süd private-label specifications now mandate single-source traceability from plantation to interesterification reactor.
Enzymatically Interesterified Oils Market Segmentation
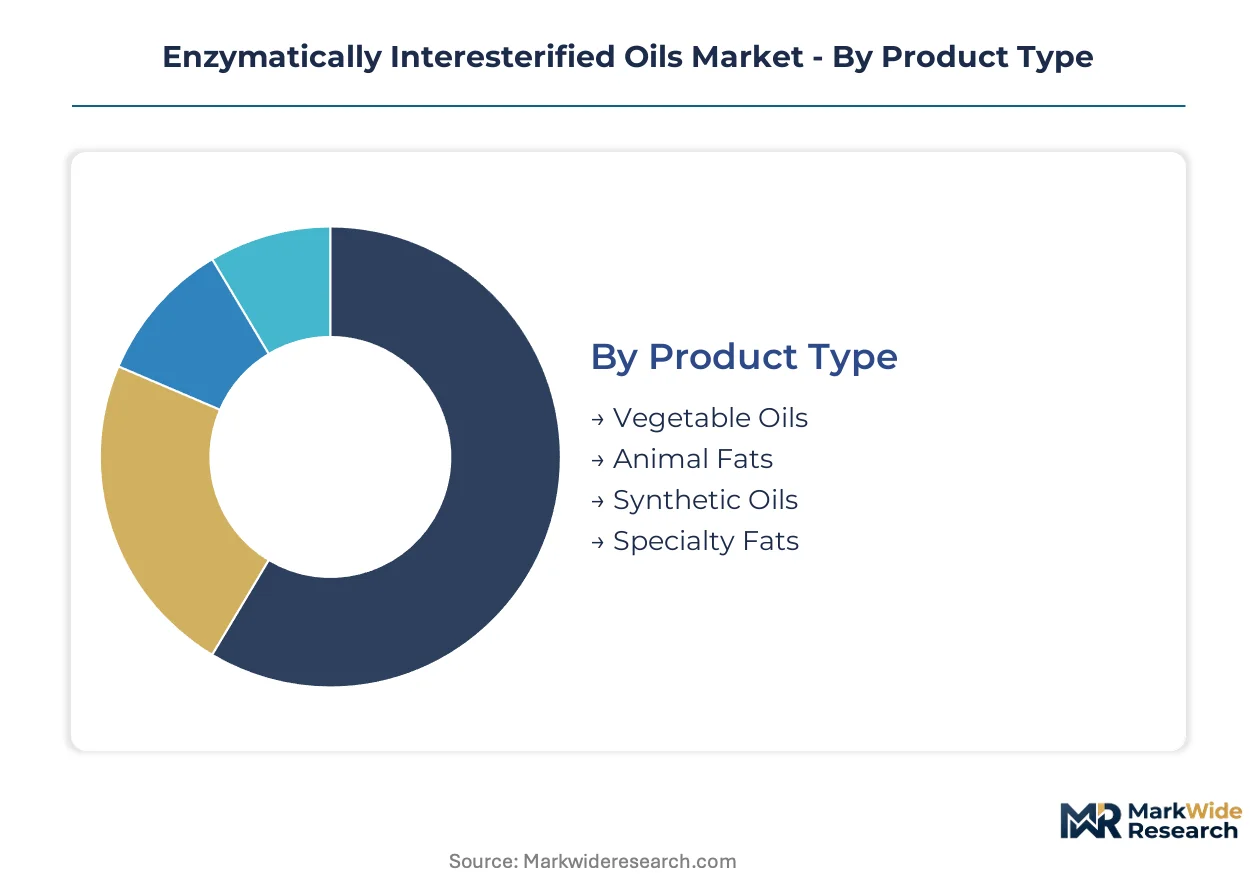
Channel configuration determines how enzymatically interesterified oils reach end-use formulations, with bulk tanker shipments dominating industrial procurement while retail packs capture artisan bakery and small cosmetics formulator demand. Segmentation by product chemistry, application function, and delivery format reveals distinct margin architectures across the value chain.
Product Type:
Bulk liquid logistics and specialized handling infrastructure channel different oil matrices through dedicated supply routes, with plantation-integrated refiners controlling vegetable oil flows while specialty fat distributors manage high-value confectionery ingredients.
- Vegetable Oils:Palm and soybean oil feedstocks processed through 1,3-specific lipase restructuring achieve targeted solid fat content profiles for margarine and shortening applications. Industrial bakeries in Germany and France specify these variants for laminated dough plasticity, though El Niño harvest volatility in Indonesian and Malaysian supply clusters creates feedstock cost pressure.
- Specialty Fats:Cocoa butter equivalents and infant formula lipid fractions engineered through precise acyl exchange deliver polymorphic stability for chocolate confectionery and nutritional oil blends. Belgian and Swiss chocolate manufacturers are consolidating procurement around refiners offering RSPO Mass Balance certification and documented enzyme provenance.
- Animal Fats:Tallow and lard matrices restructured for baking and frying applications in traditional European and Latin American markets.
- Synthetic Oils:Laboratory-derived triglyceride structures for specialized industrial lubricant and technical applications requiring extreme oxidative stability.
By volume, Vegetable Oils leads. By growth pace, Specialty Fats is climbing the fastest.
Application:
Formulation requirements dictate certification depth and technical specification intensity, with food-grade applications demanding GRAS documentation and infant formula segments requiring toxicological dossiers under EFSA Novel Food protocols.
- Food Industry:Margarine, shortening, and confectionery fat applications dominate throughput, with enzymatic restructuring eliminating sodium methoxide residues that chemical interesterification leaves behind. EU F-Gas Regulation compliance is accelerating enzyme-based adoption across French and German industrial bakery procurement specifications.
- Cosmetics:Skincare formulators source interesterified jojoba and shea derivatives for emollient formulations requiring oxidative stability and customized skin-feel profiles. Premium lotion and balm manufacturers in the Netherlands and Denmark are expanding procurement as Horizon Europe bioeconomy incentives subsidize enzymatic process adoption.
- Pharmaceuticals:Excipient-grade lipids for drug delivery systems and parenteral emulsions requiring ultra-low peroxide values and documented batch consistency.
- Biodiesel:Technical-grade interesterified feedstocks for cold-flow property enhancement in renewable diesel blending.
Food Industry commands absolute volume share. Cosmetics represents the steepest expansion trajectory.
Delivery Mode:
Packaging economics align with customer scale and handling infrastructure, with integrated food manufacturers operating dedicated tank farms while mid-scale cosmetics companies rely on intermediate bulk containers.
- Bulk:Tanker and railcar shipments of 20,000+ liter volumes serve plantation-integrated refiners and multinational food manufacturers with captive storage capacity. Wilmar International and Cargill route these flows through dedicated terminal networks in Rotterdam and Singapore.
- Totes:Intermediate bulk containers of 1,000 liter capacity bridge mid-scale cosmetics and specialty food manufacturers lacking bulk infrastructure but requiring volume pricing.
- Drums:Standard 200-liter steel and polyethylene containers for small-batch pharmaceutical and research applications with stringent contamination controls.
- Retail Packs:5-25 liter canisters and pails for artisan bakeries, independent cosmetics formulators, and institutional foodservice operations.
Bulk shipments dominate tonnage. Totes are gaining share fastest among mid-scale processors.
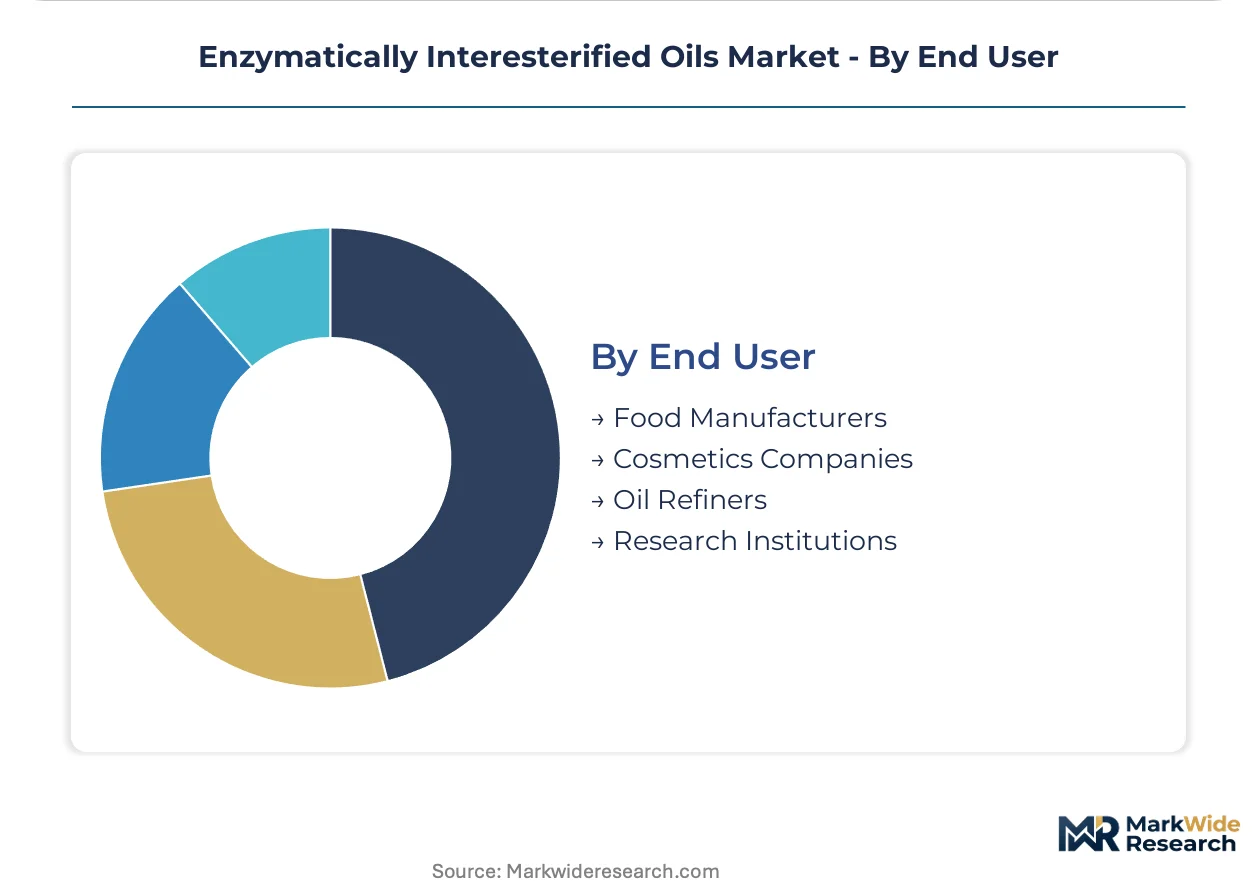
End User:
Procurement sophistication varies dramatically across customer categories, with oil refiners possessing in-house enzymatic capacity while research institutions source small volumes for process development.
- Food Manufacturers:Industrial bakeries, confectionery producers, and margarine blenders specify enzymatically interesterified oils for clean-label positioning and precise functional performance. German retailers Rewe and Aldi Süd now mandate single-source traceability from plantation to reactor for private-label specifications.
- Oil Refiners:Plantation-integrated processors and standalone specialty fat producers operate immobilized lipase reactor systems, with Indonesian refining clusters in Sumatra and Kalimantan expanding dedicated enzymatic capacity for premium export certification tiers.
- Cosmetics Companies:Skincare and personal care formulators requiring documented carbon footprint accounting and RSPO certification for sustainability-marketed product lines.
- Research Institutions:Universities and government laboratories developing novel lipase strains and continuous-flow reactor architectures under EU Green Deal and Horizon Europe funding streams.
Food Manufacturers absorb the largest volume. Cosmetics Companies are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Indonesian refining clusters while European processors absorb enzyme cost premiums. Malaysian plantation-integrated facilities capture feedstock arbitrage through captive palm oil supply. German and Dutch refiners face compressed margins from REACH compliance and F-Gas Regulation retrofit costs.
Indonesia
Sumatra and Kalimantan refining clusters are expanding dedicated enzymatic capacity for premium export certification tiers. The Ministry of Industry's downstream palm oil incentives subsidize lipase reactor installations at integrated plantation facilities. Medan-based processors are capturing EU-bound specialty fat contracts through RSPO Mass Balance documentation.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia specify enzymatically interesterified palm oil variants for laminated dough plasticity. The EU F-Gas Regulation accelerates enzyme-based adoption by eliminating temperature-intensive chemical processing stages. Hamburg terminal operators are consolidating bulk shipments from Southeast Asian refiners for redistribution across Continental Europe.
United States
Midwest soybean crush facilities anchor North American interesterification throughput through controlled supply chain integration. FDA GRAS self-affirmation pathways shape market access requirements for novel enzymatic processes. Chicago-area food manufacturers are retrofitting margarine lines to eliminate sodium methoxide residues from chemical interesterification.
India
Domestic infant formula and chocolate compound manufacturers are qualifying enzymatically interesterified oils under maturing FSSAI protocols. BIS standards alignment enables import substitution for specialty fat ingredients previously sourced from European refiners. Gujarat-based oleochemical processors are expanding enzymatic capacity to serve domestic bakery and confectionery demand.
Netherlands
Horizon Europe bioeconomy incentives subsidize enzymatic process retrofits at Rotterdam-area refineries. Dutch skincare formulators source interesterified emollients for premium cosmetic lines requiring documented carbon footprint accounting. The Port of Rotterdam handles bulk transshipment from Indonesian and Malaysian suppliers for redistribution to German and French food manufacturers.
Enzymatically Interesterified Oils Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Plantation-integrated refiners command feedstock economics through backward integration into palm estates. Specialty fat engineers differentiate through precise slip-point engineering and clean-label positioning. Enzyme technology suppliers and toll processors occupy distinct margin pools based on scale and certification depth. Consolidation pressures are reshaping partnership structures around integrated certification packages.
Within the plantation-integrated tier, Wilmar International Limited and IOI Corporation Berhad exemplify cost-advantaged feedstock security through captive Indonesian and Malaysian palm oil supply. Fuji Oil Co., Ltd. occupies a position among Japanese-led specialty fat engineers focused on confectionery applications. Cargill, Incorporated anchors North American positioning through controlled soybean crush capacity and food-grade certification infrastructure. These three represent the dominant archetypes: plantation-integrated refiners, Asian specialty fat engineers, and North American agricultural processors.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Fuji Oil Co., Ltd. |
| Cargill, Incorporated |
| Intercontinental Specialty Fats SDN. BHD. |
| AAK KAMANI Pvt. Ltd. |
| Archer Daniels Midland Company |
| IOI Corporation Berhad |
| Adams Group |
| Bunge Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Indonesian plantation-integrated refiners and European food manufacturers lock in feedstock access and price visibility across multi-year horizons, insulating processors from El Niño-induced harvest volatility while embedding RSPO certification premiums into negotiated baselines.
Pricing Analysis
Configured-to-order pricing for specialty fats with tailored slip-point engineering commands substantial premiums over standard vegetable oil grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with RSPO Mass Balance and documented enzyme provenance separating tiers. Cost compression in standard palm oil variants is intensifying because lipase enzyme cost volatility compresses margins at sub-scale volumes. Industrial bakeries in Germany exhibit highest price sensitivity, while Belgian chocolate manufacturers show lowest sensitivity due to polymorphic stability requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate among European refiners buffering against Malaysian and Indonesian palm oil supply disruptions, while just-in-time inventory governs cosmetics formulators sourcing interesterified emollients. Feedstock draws from Indonesian Sumatra clusters, Malaysian Peninsular estates, and Midwest US soybean crush facilities. Raw material dependencies center on fermentation-derived lipases from Aspergillus niger and Rhizomucor miehei strains, immobilized enzyme supports, and food-grade handling infrastructure. Single-source vulnerability concentrates in Southeast Asian palm oil supply. Distribution runs through Rotterdam and Singapore bulk terminals for redistribution to downstream formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lipase engineering expertise and immobilized reactor design capabilities remain scarce relative to demand, constraining capacity expansion timelines and creating acquisition premiums for technology-holding entities.
For Market Incumbents: Consolidate backward integration into captive palm estates to defend feedstock cost position against emerging plantation-integrated competitors in Kalimantan. Lock in long-term lipase supply agreements with fermentation specialists to secure enzyme access ahead of supplier consolidation. Prioritize certification investment in EFSA Novel Food dossiers to preempt regulatory barriers for infant formula applications. For New Entrants and Emerging Players: Toll processing services for mid-scale cosmetics companies lacking enzymatic infrastructure represent the most penetrable white-space target. Geographic entry through Gujarat-based oleochemical corridors offers FSSAI-aligned qualification pathways for domestic Indian confectionery demand. Go-to-market leverage rests on offering carbon-footprint-accounted interesterified emollients under Horizon Europe subsidy eligibility. For Investors and Strategic Acquirers: Capital is best deployed toward immobilized enzyme technology suppliers with proven CLEA reactor deployments and protein engineering partnerships. Long-term viability favors entities bridging fermentation scale-up with food-grade certification depth. Watch for FDA GRAS self-affirmation completion timelines as inflection indicators for US market entry readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Wilmar International leverages Indonesian estate control to secure cost-advantaged feedstock security against volatile spot markets. |
| Immobilized Lipase Reactor Deployment | European refiners adopting CLEA-based continuous-flow platforms achieve real-time solid fat content modulation for premium confectionery. |
| EFSA Novel Food Dossier Investment | Irish and Dutch infant formula manufacturers front-load regulatory spending to capture specialized fat ingredient qualification. |
| RSPO Mass Balance Certification | German retailers Rewe and Aldi Süd mandate single-source traceability from plantation to reactor for private-label margarine specifications. |
| Horizon Europe Bioeconomy Retrofit | Dutch and Danish refiners subsidize enzymatic process adoption through national biorefinery tax credits and EU Green Deal funding streams. |
Research Methodology
A spread of perspectives from plantation operations managers, lipase technology suppliers, European bakery procurement leads, and infant formula R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation through customs trade data, FAO oilseed statistics, SEC filings from listed agricultural processors, and EFSA Novel Food evaluation registers. Bottom-up volume triangulation from individual refinery capacity announcements was cross-checked against top-down demand aggregation from end-use sector consumption patterns.
Segmentation dimensions modeled include product chemistry matrices, application function categories, delivery format logistics, and end-user procurement sophistication tiers across the analysis window. CAGRs were derived from trend extrapolation of enzyme adoption rates, regulatory phase-in timelines, and feedstock cost trajectory assumptions. Industry-specific forecast inputs incorporated El Niño cycle impact modeling on Southeast Asian harvest yields and EU F-Gas Regulation compliance cost curves for processing facility retrofits.
Underlying assumptions cover sustained lipase cost premiums over chemical catalysts, with deviation risk concentrated in fermentation technology breakthroughs or regulatory acceleration of chemical residue thresholds. Forecasts reflect these documented assumptions and risk weightings. Revision becomes warranted when enzyme immobilization engineering achieves cost parity with sodium methoxide processes or when palm oil export duty regimes in Indonesia and Malaysia shift substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
US Esters Market
Oleochemicals
Global White Oil Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Rice Bran Wax Market