
 Partially Hydrogenated Oil Market | 2026-2036
Partially Hydrogenated Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Partially Hydrogenated Oil Market Analytics
The WHO REPLACE initiative is expanding reformulation mandates across packaged food sectors, pressuring hydrogenated oil suppliers to diversify product portfolios. Cargill leverages its integrated oilseed processing network to sustain North American supply continuity for food manufacturers navigating label compliance. IOI Corporation Berhad anchors Southeast Asian feedstock access through Malaysian palm oil estates, while Bunge competes in South American soybean oil hydrogenation with crushing assets near Buenos Aires.
Partially hydrogenated oil denotes vegetable oils treated with hydrogen gas under catalytic conditions to raise melting point and oxidative stability, typically achieving iodine values below 100 for semi-solid applications in industrial baking and frying. Liquid oils retain lower saturation levels for cooking applications where pourability matters, whereas solid fats and margarine segments command premium positioning in food processing channels demanding specific texture and shelf-life performance. Spreads applications face structural pressure from clean-label trends, diverting margin pools toward bakery and food manufacturing segments where functional properties resist easy substitution.
The FDA trans fat removal compliance framework and EFSA dietary reference values on industrial trans fatty acids shape permissible product claims and import standards across major Western markets. Malaysia's MEE environmental guidelines and Indonesia's BIS-equivalent national standards govern hydrogenation plant emissions and product safety certifications for regional export eligibility. Stakeholders must monitor evolving national trans fat limits and feedstock sustainability certification requirements as determinants of long-term market access and capital allocation priorities.
Market Dynamics
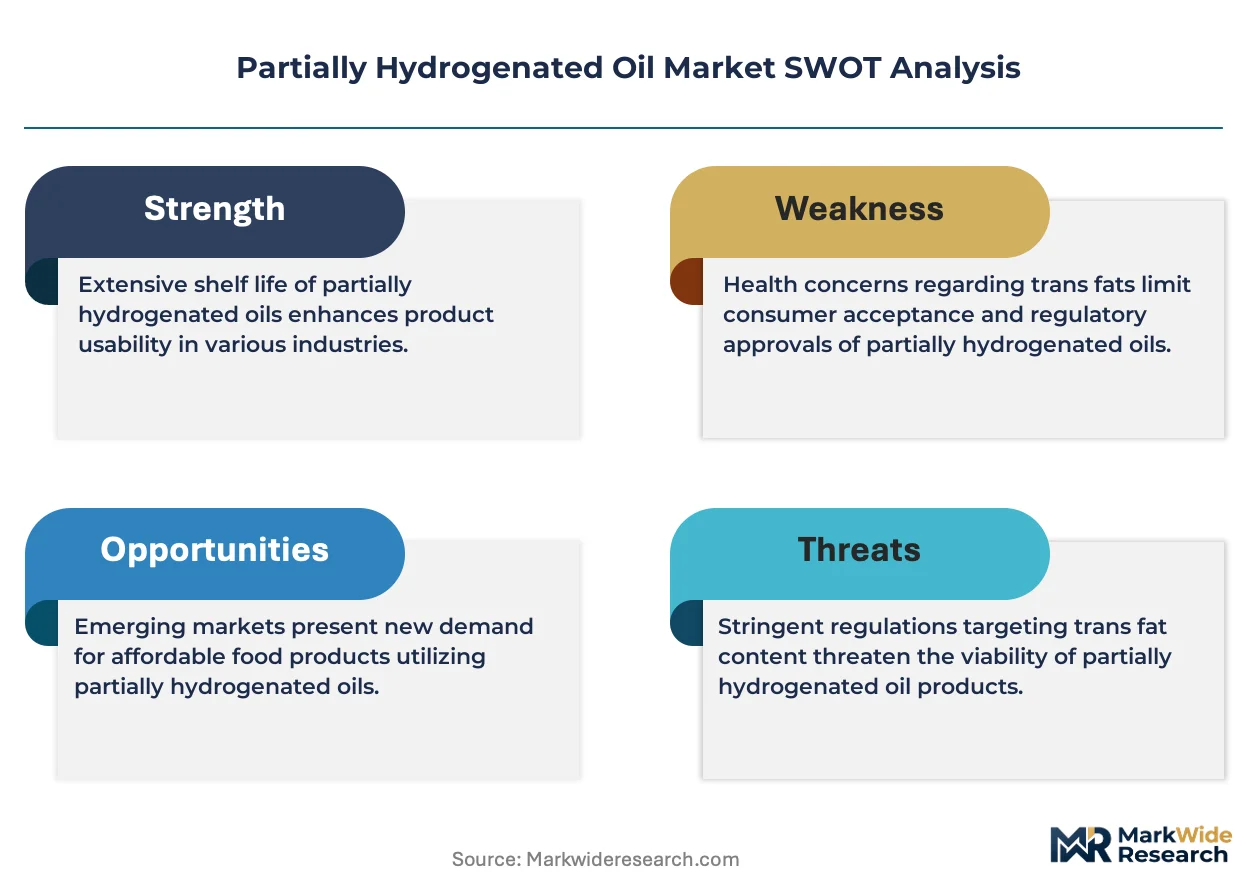
Reformulation pressure from trans fat labeling mandates is compressing demand for traditional partially hydrogenated oils while redirecting capital toward enzymatic interesterification and palm oil fractionation alternatives. This structural force is fragmenting supplier portfolios and reconfiguring procurement relationships across industrial baking channels.
Growth Catalysts
- Indonesian industrial bakery expansion:Domestic snack food manufacturers are scaling production lines for extended shelf-life crackers and biscuits, creating pull for semi-solid fat grades with specific melting profiles.
- WHO REPLACE implementation:National trans fat elimination frameworks across Southeast Asian markets are accelerating technical consultation demand for reformulation support services.
- Palm oil fractionation advancement:Dry fractionation technology improvements are enabling cost-competitive alternatives to partial hydrogenation for specific texture applications in margarine production.
Market Restraints
- Feedstock cost volatility:Crude palm oil price swings in Malaysian futures markets directly compress margin structures for hydrogenation operators without backward integration into plantation assets.
- Regulatory friction from FDA compliance:US food manufacturers face reformulation timelines that strand existing partially hydrogenated oil inventories and accelerate write-downs.
- Substitution threat from high-oleic oils:Trait-enhanced sunflower and canola varieties are displacing hydrogenated oils in frying applications where oxidative stability previously required saturation.
Strategic Opportunities
- Underpenetrated Philippines market:Domestic baking industry consolidation is creating demand for technical fat solutions among emerging pan-Asian snack brands establishing regional production hubs.
- Enzymatic interesterification convergence:Lipase biocatalysis combined with palm mid-fraction blending is opening formulation space for zero-trans claims in premium margarine segments.
- EU deforestation regulation tailwind:EUDR traceability requirements are advantaging Malaysian suppliers with certified sustainable palm oil chain-of-custody documentation.
Industry Challenges
- Reformulation talent scarcity:Food technologists with specialized expertise in fat crystallization behavior and texture engineering command premium compensation and extended recruitment timelines.
- Hydrogenation asset stranded risk:Catalytic hydrogenation reactor systems face accelerated depreciation as trans fat limits tighten across multiple regulatory jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Partially Hydrogenated Oil Market |
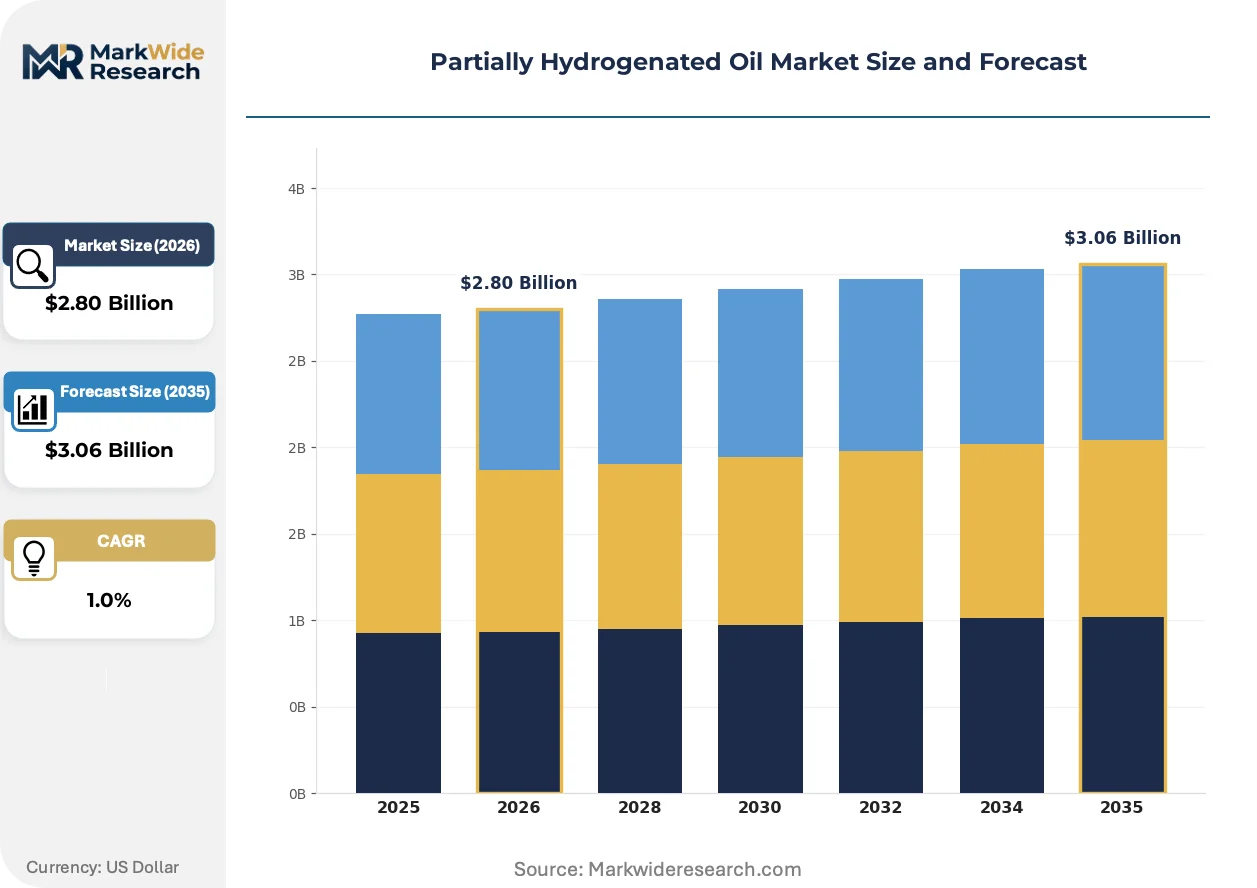
| Market Size in 2026 | $2.80 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Oils, Semi-Solid Fats, Solid Fats, Margarine Application: Baking, Cooking, Food Processing, Spreads End User: Food Manufacturers, Restaurants, Retailers, Bakeries Packaging Type: Buckets, Cans, Pouches, Tubs |
| Companies Covered | AAK, Oleon NV, Cargill, Sime Darby Hudson, IOI Corporation Berhad, Bunge, Wilmar International Ltd, Mewah Group, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Partially Hydrogenated Oil Market Evolving Landscape
Interesterification technology is displacing partial hydrogenation as the dominant pathway for structuring vegetable oils in food manufacturing. Three convergent developments are compressing the traditional hydrogenation value chain and redirecting R&D investment toward enzymatic and chemical restructuring alternatives.
Enzymatic interesterification using immobilized lipase biocatalysts is unifying the functional properties of palm oil fractions with the process efficiency previously associated with chemical interesterification. Industrial margarine producers in Malaysia and Indonesia are adopting this technology at commercial scale to achieve zero-trans fat claims without sacrificing product texture. The structural consequence is unifying premium and standard product tiers under single production platforms, compressing equipment differentiation across supplier offerings.
EFSA dietary reference values on industrial trans fatty acids are tightening permissible thresholds for packaged food claims across European markets. Food manufacturers exporting to EU member states are reformulating recipes to eliminate partially hydrogenated oils entirely rather than managing borderline compliance. Bakery and confectionery segments with complex texture requirements are most affected, responding through accelerated supplier qualification programs for alternative fat structuring technologies.
Buyer concentration among Southeast Asian industrial bakeries is shortening supplier qualification cycles and compressing switching costs for alternative fat technologies. Pan-Asian snack food conglomerates are consolidating procurement decisions at regional headquarters in Singapore and Jakarta, displacing fragmented local distributor relationships. This pattern is most visible in Indonesia, where domestic bakery chains are centralizing technical fat sourcing through direct mill relationships rather than trading house intermediaries.
Partially Hydrogenated Oil Market Segmentation
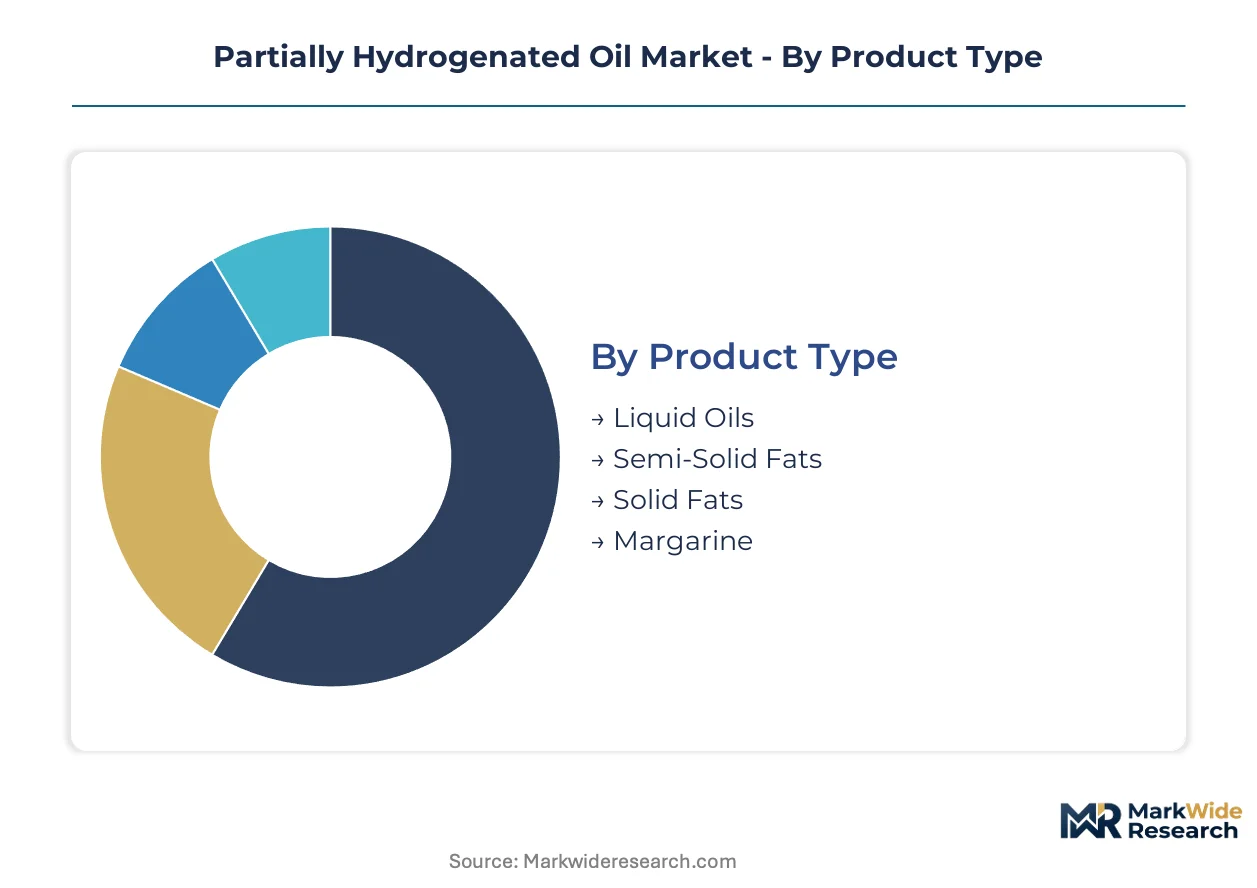
Product form and application requirements dictate capital deployment across hydrogenation infrastructure, reactor sizing, and downstream formulation capabilities. Segmentation reveals where margin pools concentrate and which customer channels resist substitution pressure from alternative fat technologies.
Product Type:
Semi-solid and solid fat grades demand the heaviest upfront investment in catalytic hydrogenation reactors, fractionation towers, and crystallization control systems.
- Liquid Oils:Lower saturation levels preserve pourability for cooking applications where oxidative stability is achieved through light hydrogenation or natural antioxidant content. Food service distributors in Indonesia favor these grades for high-volume frying operations where cost efficiency outweighs texture requirements.
- Semi-Solid Fats:Engineered to specific melting profiles through controlled hydrogenation achieving iodine values between 60 and 90, these grades dominate industrial cracker and biscuit manufacturing in Malaysia where extended shelf-life specifications are non-negotiable.
- Solid Fats:Fully saturated fractions serve confectionery coating and shortening applications requiring sharp melting behavior and structural integrity at ambient temperatures.
- Margarine:Water-in-fat emulsions blend hydrogenated hardstock with liquid oils to achieve spreadable or baking-stable textures; reformulation toward zero-trans claims is compressing traditional hydrogenated base usage.
Semi-solid fats absorb the bulk of installed capacity; margarine is expanding most quickly as manufacturers retrofit lines for enzymatic interesterification alternatives.
Application:
Volume concentration varies sharply by processing intensity and reformulation flexibility across end-use channels.
- Baking:Laminated dough, cake shortening, and biscuit fat applications require precise plasticity ranges that hydrogenation historically delivered cost-effectively. Industrial bakeries in the Philippines are consolidating procurement around technical fat suppliers capable of custom melting curve specifications.
- Cooking:Frying oil stability demands have shifted toward high-oleic sunflower and palm olein alternatives, displacing light hydrogenation for this application. Restaurant chains with standardized frying protocols now specify non-hydrogenated oils to simplify compliance with trans fat labeling mandates.
- Food Processing:Extruded snack, cereal, and prepared food manufacturers use hydrogenated fats for moisture barrier and texture functions where clean-label pressure is less acute than in retail-facing categories.
- Spreads:Consumer-facing margarine and spread products face acute reformulation pressure from WHO REPLACE initiative compliance and retailer clean-label requirements, redirecting R&D spend toward enzymatic restructuring.
Baking commands the deepest supplier relationships and longest qualification cycles; food processing is climbing the fastest as pan-Asian snack conglomerates scale regional production.
End User:
Procurement sophistication and technical service requirements segment the customer base into distinct service tiers.
- Food Manufacturers:Multinational and regional packaged food producers operate direct mill relationships, demanding formulation support, audit documentation, and supply security guarantees that favor suppliers with integrated plantation and processing assets.
- Restaurants:Chain and independent food service operators prioritize cost stability and frying performance over technical customization, purchasing through distributor intermediaries with limited supplier loyalty.
- Retailers:Private-label and branded product sourcing decisions increasingly exclude partially hydrogenated oils entirely, compressing available volume for this channel.
- Bakeries:Artisan and industrial bakeries span a wide technical sophistication range, from commodity shortening buyers to specialists requiring tailored fat crystallization behavior for laminated dough applications.
Food manufacturers lock in the majority of long-term supply contracts; bakeries are gaining share fastest as domestic snack production scales across Southeast Asia.
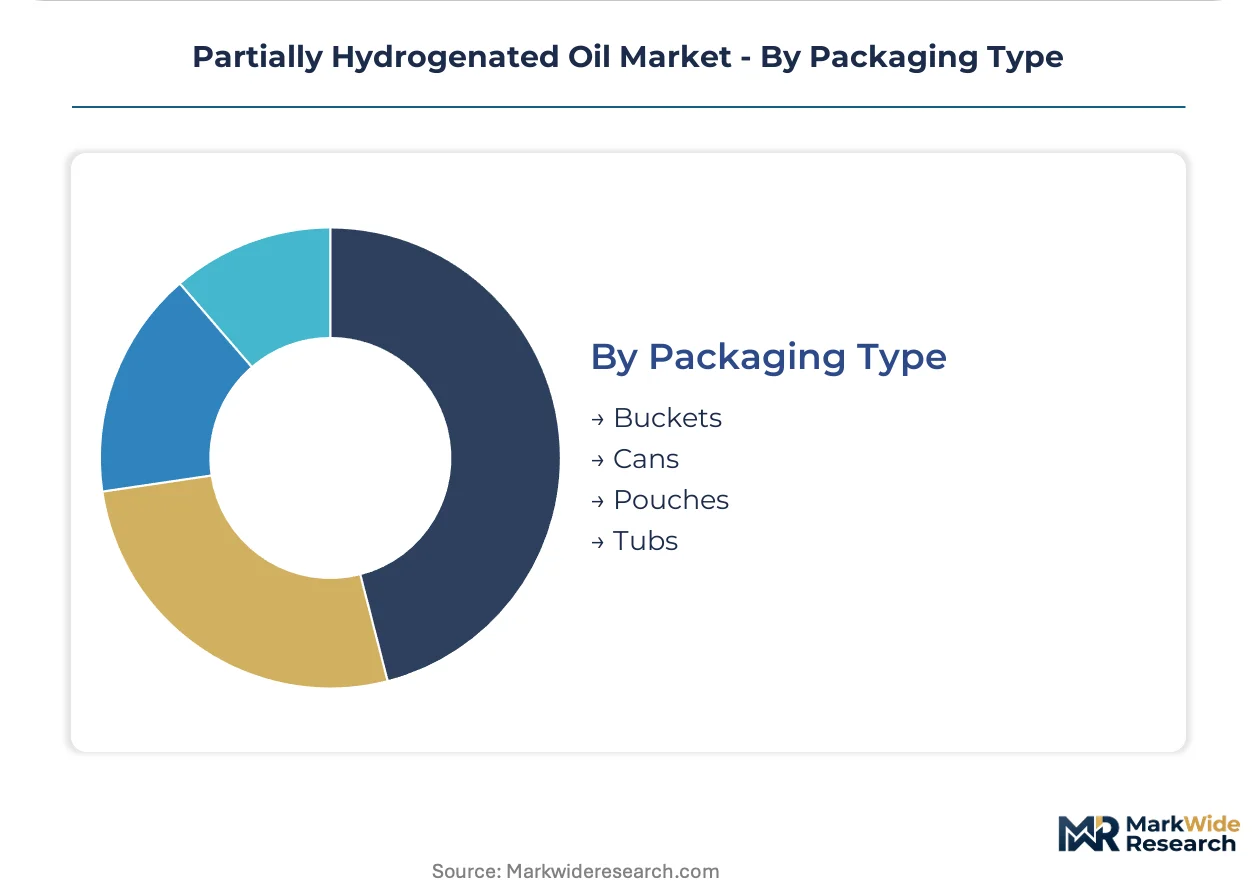
Packaging Type:
Packaging format selection tracks customer scale, handling requirements, and shelf-life needs across the value chain.
- Buckets:Intermediate bulk containers serve industrial food manufacturers with high-throughput production lines and dedicated fat handling systems; standardization around 20-liter formats reduces logistics complexity for Malaysian mill direct shipments.
- Cans:Metal packaging preserves product integrity through extended distribution chains in tropical climates where oxidation sensitivity demands barrier protection; traditional format for retail shortening in Indonesian traditional trade channels.
- Pouches:Flexible packaging reduces material cost and shipping weight for liquid oil grades, gaining preference among cost-optimized food service distributors.
- Tubs:Consumer-facing spreads and retail shortening formats where shelf presentation and resealability influence purchasing decisions; declining relevance as hydrogenated oil content disappears from retail formulations.
Buckets dominate volume throughput; pouches are expanding most quickly as liquid oil alternatives capture frying application share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port Klang anchors the world's densest concentration of hydrogenation capacity, with Malaysian palm oil estates feeding catalytic reactor clusters along the Strait of Malacca corridor.
Indonesia
Domestic snack manufacturers in Bekasi and Tangerang industrial zones are scaling cracker and biscuit production lines. The BIS-equivalent national standards govern hydrogenation plant emissions and product safety certifications. Surabaya's emerging food processing corridor is attracting technical fat suppliers establishing direct mill relationships with pan-Asian bakery chains.
Malaysia
Industrial bakeries in Selangor and Johor are consolidating procurement around semi-solid fat grades with specific melting profiles. MEE environmental guidelines regulate hydrogenation reactor emissions and wastewater discharge standards. Port Klang-Pasir Gudang logistics clusters support integrated plantation-to-processing supply chains with certified sustainable palm oil chain-of-custody documentation.
United States
Food manufacturers in Chicago and Minneapolis-St. Paul metro areas navigate stranded inventory risks from FDA trans fat removal compliance timelines. FDA labeling rules mandate disclosure of partially hydrogenated oil content above threshold limits. New Jersey's industrial corridor hosts reformulation service providers consulting on enzymatic interesterification alternatives for bakery applications.
Philippines
Emerging pan-Asian snack brands are establishing regional production hubs in Cavite and Laguna provinces. The country's food safety regulator enforces trans fat limits aligned with WHO REPLACE initiative frameworks. Manila-based bakery chains are centralizing technical fat sourcing decisions, displacing fragmented traditional distributor relationships.
Partially Hydrogenated Oil Market Competitive Landscape
The competitive structure tilts toward integrated plantation-to-processing conglomerates with captive palm oil feedstock access. Malaysian and Indonesian operators with backward integration into estate assets command margin resilience against crude palm oil futures volatility. Three archetypes dominate: integrated agribusiness conglomerates with plantation assets, regional specialty oil processors with fractionation expertise, and multinational traders with crushing infrastructure. Capacity consolidation and enzymatic technology licensing are the dominant competitive moves reshaping supplier positioning.
Within the integrated conglomerate tier, IOI Corporation Berhad and Wilmar International Ltd exemplify the plantation-backed model with Malaysian and Indonesian estate networks supporting hydrogenation capacity. Cargill occupies a position representing the multinational trader archetype with North American oilseed processing infrastructure. These three anchors illustrate how feedstock integration and geographic diversification separate sustainable margin structures from commodity-exposed operators.
| Leading Market Players |
|---|
| AAK |
| Oleon NV |
| Cargill |
| Sime Darby Hudson |
| IOI Corporation Berhad |
| Bunge |
| Wilmar International Ltd |
| Mewah Group |
| ADM |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between RSPO-certified sustainable palm oil and conventional feedstock splits both procurement premiums and supplier qualification pathways across Southeast Asian hydrogenation corridors. Industrial bakeries in Indonesia and Malaysia pay 8-12% uplifts for mass-balance certified hardstock, while commodity-exposed processors absorb margin compression from Kuala Lumpur futures volatility without estate-backed supply security.
Pricing Analysis
Value-based pricing anchors on oxidative stability performance and melting curve precision for industrial baking applications. Three-tier pricing structure across premium, standard, and economy levels reflects iodine value ranges, with semi-solid fats commanding premiums over liquid grades. Pricing pressure stems from enzymatic interesterification alternatives achieving cost parity in margarine segments. Food manufacturers with direct mill relationships show lowest price sensitivity; independent bakeries and food service distributors exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from pan-Asian snack conglomerates mandate qualified backup suppliers across Malaysian and Indonesian mill networks. Feedstock draws from Malaysian estates, Indonesian smallholder cooperatives, and Argentinian soybean crushing operations. Single-source vulnerability concentrates in Port Klang-Pasir Gudang logistics clusters where 60% of regional hydrogenation capacity sits within 50 kilometers. Distribution runs through integrated plantation-processor direct shipments for large manufacturers, with trading house intermediaries serving fragmented bakery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The partially hydrogenated oil market occupies a technology-transition phase as enzymatic interesterification displaces catalytic hydrogenation for zero-trans fat claims. Lipase biocatalysis now achieves commercial scale in Malaysian margarine production, rendering legacy reactor assets economically obsolete.
For Market Incumbents: Deploy enzymatic technology licensing to capture reformulation service revenue from bakery customers facing WHO REPLACE compliance deadlines. Retrofit existing hydrogenation lines for palm oil fractionation to preserve asset utilization. Backward integration into certified sustainable palm oil estates defends margin position against crude palm oil futures volatility.
For New Entrants and Emerging Players: Begin with enzymatic interesterification capacity in the Philippines, where domestic bakery consolidation creates demand for technical fat solutions without entrenched supplier relationships. Target direct mill relationships with Cavite and Laguna-based pan-Asian snack brands. Offer formulation partnership models rather than commodity supply contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated plantation-processor conglomerates given EUDR traceability tailwinds advantaging certified sustainable palm oil chain-of-custody documentation. Five-to-ten year viability hinges on feedstock security rather than hydrogenation technology. Watch for Indonesian BIS-equivalent national standards tightening as the inflection signal for accelerated asset write-downs.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Licensing | Lipase biocatalysis technology transfer enables zero-trans claims without reactor retrofit costs. |
| RSPO Certification Investment | Mass-balance chain-of-custody documentation secures EU market access under EUDR requirements. |
| Direct Mill Relationship Development | Bypassing trading house intermediaries captures margin from consolidating Indonesian bakery procurement. |
| Fractionation Capacity Expansion | Dry fractionation towers diversify revenue streams as hydrogenation demand compresses. |
| Reformulation Service Partnership | Technical consultation contracts lock in long-term supply relationships during transition periods. |
Research Methodology
Document review covered Malaysian Palm Oil Board production statistics, Indonesian Ministry of Trade export filings, and FDA trans fat labeling guidance documents, complemented by interviews with hydrogenation plant managers, procurement leads at industrial bakeries, palm oil estate operations directors, and enzymatic technology licensors. Secondary sources included customs/trade data, MEE environmental compliance records, and RSPO certification databases. Bottom-up capacity assessments and top-down demand modeling were triangulated against trade flow analysis.
Historical production volumes were cross-referenced against expert panel input from Southeast Asian oil processing executives to establish baseline trajectories. The analytical framework modeled product type, application channel, end-user sophistication tier, and packaging format across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance timelines and substitution technology diffusion rates. Feedstock cost assumptions rested on Malaysian Derivatives Exchange futures curves and plantation yield projections.
Regulatory enforcement timing, palm oil price volatility spikes, and enzymatic technology cost curves are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on substitution rates and compliance deadlines. A model refresh is warranted upon material change in WHO REPLACE implementation schedules or EUDR traceability enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Paraffin Wax Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market