
 Sodium Stearoyl Lactylate Market | 2026-2036
Sodium Stearoyl Lactylate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Stearoyl Lactylate Market Analytics
Direct procurement channels between emulsifier producers and large-scale food manufacturers is narrowing as consolidation upstream tightens supply relationships. Cargill Inc. leverages its integrated oilseed processing network to secure captive stearic acid feedstock for SSL production. Kerry Ingredients competes through bakery application laboratories that co-develop clean-label formulations with end users. Tate & Lyle Plc. anchors its position in European confectionery channels where emulsifier functionality requirements are most stringent.
Sodium stearoyl lactylate is an anionic food emulsifier produced by esterification of stearic acid with lactic acid, yielding a compound with an acid value typically below 70 mg KOH/g and a saponification value between 200-220; it functions primarily as a dough strengthener, crumb softener, and emulsion stabilizer across baked goods and dairy analogs. The food additive segment dominates current volume as commercial bakeries replace diacetyl tartaric acid esters of mono-diglycerides in premium bread lines, while the cosmetic ingredient category registers the fastest trajectory as formulators seek non-ionic alternatives for skin-conditioning applications. Pharmaceutical excipient demand sustains steadier margins due to USP-NF certification requirements that limit supplier pools.
The FDA governs SSL safety through GRAS notifications and food additive petitions, while the EPA regulates plant effluent from esterification facilities under Clean Water Act permits. REACH registration in Europe obliges importers to submit full toxicological dossiers, raising compliance costs for Asian suppliers seeking continental access. Stakeholders must monitor evolving EFSA opinions on refined food emulsifiers and their potential gastrointestinal effects, as regulatory reclassification would force rapid formulation pivots across all end-use categories.
Market Dynamics
The FDA's GRAS reaffirmation process for emulsifiers is compressing supplier qualification timelines and concentrating procurement relationships among vertically integrated oilseed processors with captive stearic acid supply.
Growth Catalysts
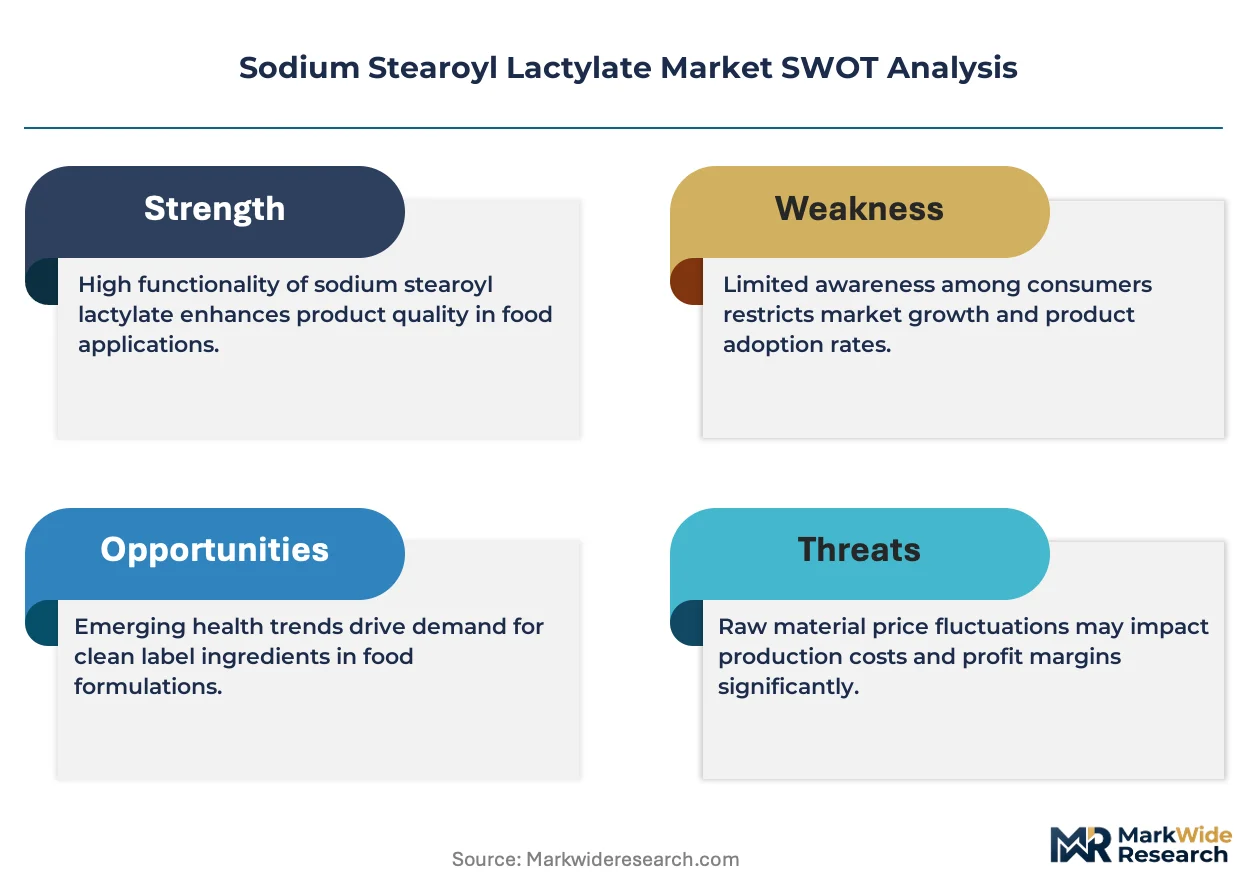
- Clean-label bakery formulations:Artisanal and industrial bakeries in the United States are replacing diacetyl tartaric acid esters of mono-diglycerides with SSL in premium bread lines.
- REACH registration compliance:European importers submitting full toxicological dossiers are raising barriers that favor established SSL producers with regulatory infrastructure.
- Cosmetic ingredient pivot:Formulators seeking non-ionic alternatives for skin-conditioning applications are accelerating SSL adoption in personal care R&D pipelines.
Market Restraints
- Stearic acid feedstock volatility:Palm oil and tallow price swings directly compress SSL production margins for non-integrated manufacturers.
- Asian supplier concentration:Esterification capacity clusters in China create geographic supply risk amplified by MEE effluent enforcement under dual carbon goals.
- EFSA opinion uncertainty:Pending refined food emulsifier gastrointestinal effect assessments threaten regulatory reclassification across all end-use categories.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF compliance requirements limit supplier pools and sustain premium pricing for qualified SSL producers.
- Direct procurement channel consolidation:Large-scale food manufacturers are narrowing supplier bases, creating captive relationships for integrated emulsifier producers.
- Dairy analog emulsion stabilization:Plant-based milk and cheese formulations represent underpenetrated application territory for SSL functionality.
Industry Challenges
- Esterification plant effluent compliance:EPA Clean Water Act permit adherence requires continuous capital deployment for wastewater treatment upgrades.
- Application laboratory co-development:Bakery formulation partnerships demand specialized technical service teams that strain mid-cap SSL producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Stearoyl Lactylate Market |
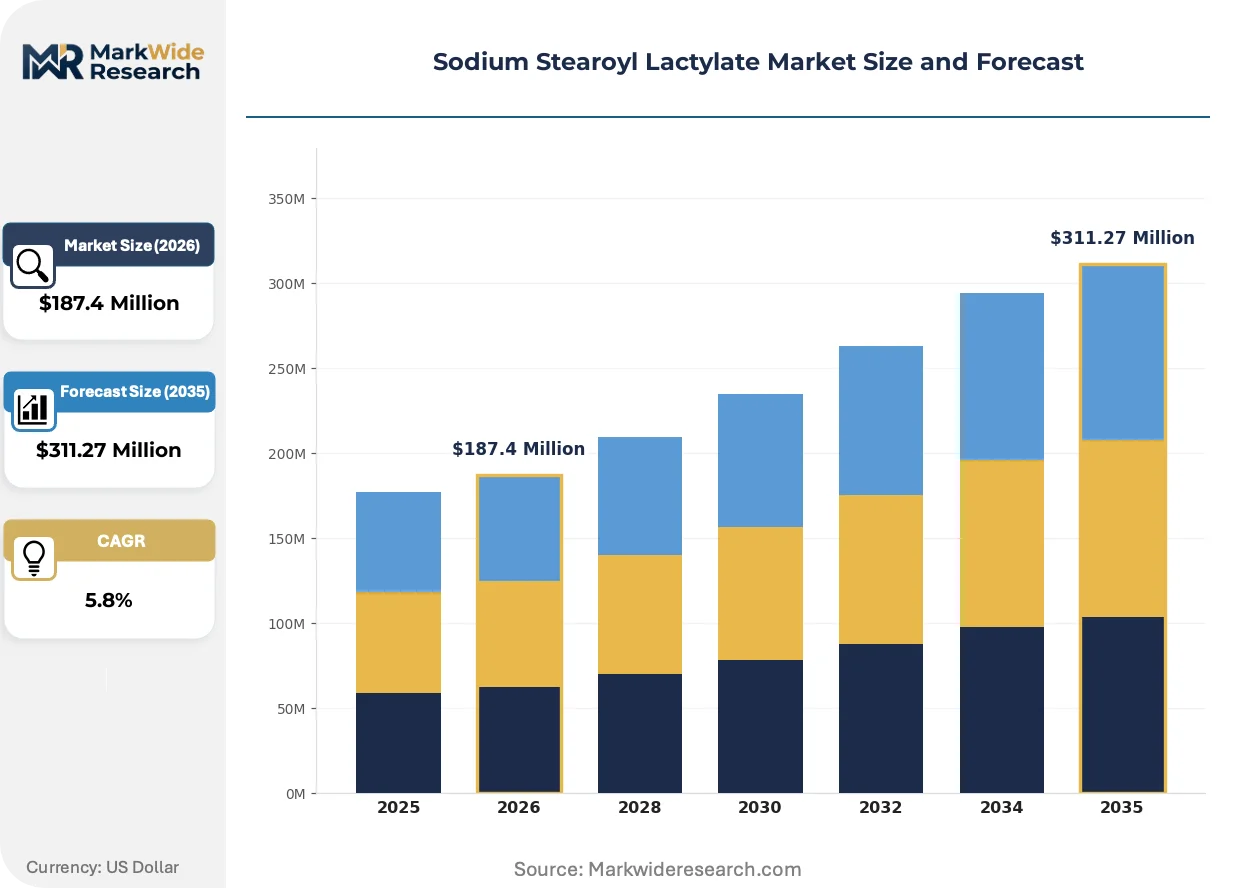
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Cosmetic Ingredient, Pharmaceutical Excipient, Nutraceutical Application: Baking, Confectionery, Personal Care, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Health Brands Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Kowa Europe GmbH, Niacet, Cargill Inc., DuPont, Ivanhoe Industries, Merck KGaA, Zhejiang Synose Tech Co., Kerry Ingredients, Tate & Lyle Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Stearoyl Lactylate Market Evolving Landscape
Process analytical technology is reshaping how SSL manufacturers monitor acid value and saponification parameters in real time, compressing batch release cycles and tightening specification bands.
Inline near-infrared spectroscopy is digitizing quality control workflows for acid value verification below 70 mg KOH/g and saponification value maintenance between 200-220. Commercial bakeries with automated dosing systems are adopting these specifications fastest. This digitization is compressing the specification gap between pharmaceutical-grade and food-grade SSL production.
EFSA opinions on refined food emulsifiers are forcing formulation contingency planning across European confectionery channels. Manufacturers are building dual-source SSL relationships and accelerating clean-label alternative testing. The confectionery segment is responding by diversifying emulsifier portfolios ahead of potential reclassification.
Buyer concentration among industrial bakery groups is consolidating procurement decisions into fewer technical sourcing teams. Direct channel relationships are displacing distributor intermediaries for volume SSL contracts. This concentration is most visible in North American artisanal bakery cooperatives scaling into regional supply networks.
Sodium Stearoyl Lactylate Market Segmentation
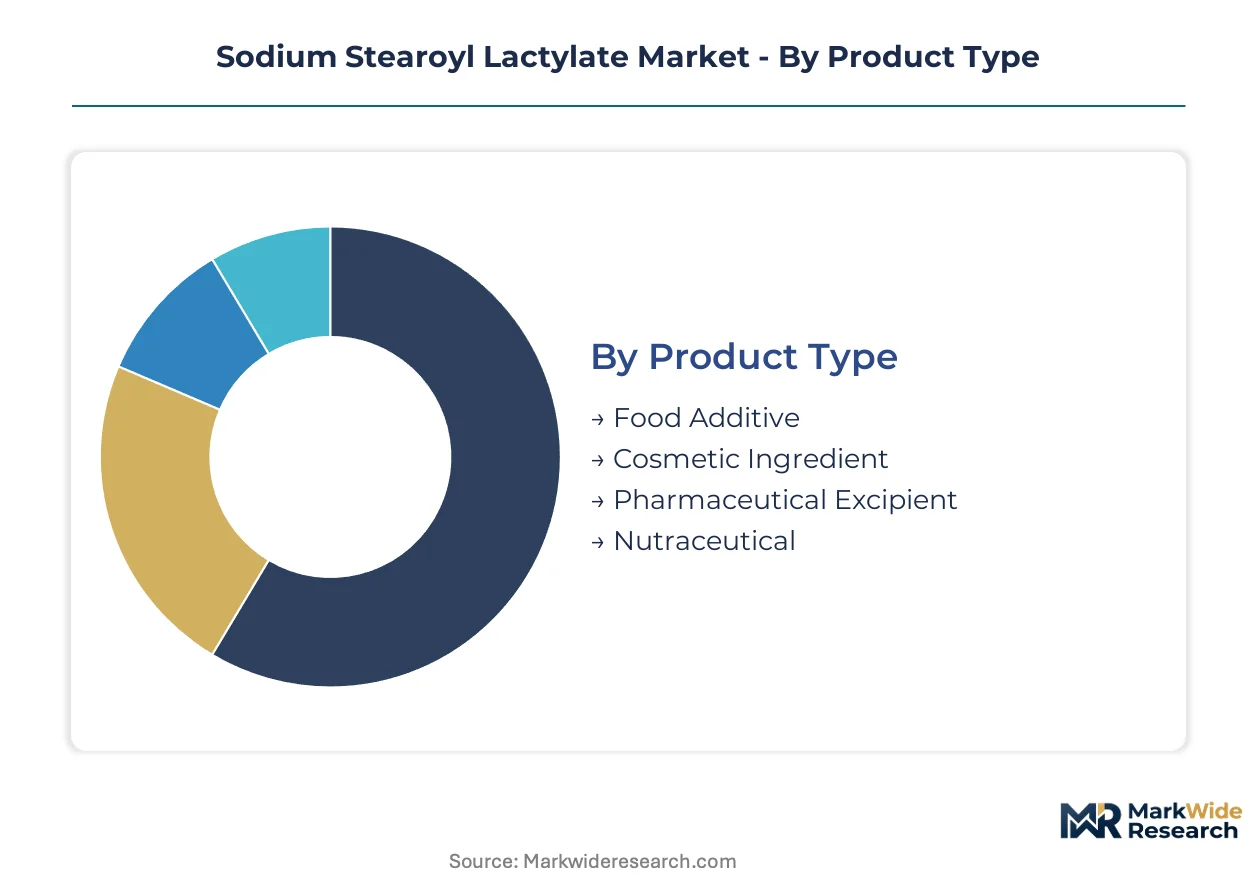
SSL demand fragments across functionally distinct use-cases where specification bands, certification requirements, and formulation compatibility create non-substitutable segment boundaries. Each category reflects divergent buyer priorities: food manufacturers optimize dough rheology, cosmetic formulators prioritize skin-feel, and pharmaceutical buyers demand USP-NF compliance.
Product Type:
The use-case spectrum spans edible emulsification through dermal conditioning to tablet binding, with each tier imposing distinct purity and documentation requirements.
- Food Additive:Acid value below 70 mg KOH/g and saponification between 200-220 define bakery-grade SSL specifications. Industrial bakeries in the United States concentrate procurement here, replacing DATEM in premium bread lines as clean-label pressures intensify.
- Cosmetic Ingredient:Non-ionic functionality for skin-conditioning applications drives personal care R&D pipelines. Formulators seeking alternatives to traditional emollients are accelerating SSL adoption in moisturizers and color cosmetics.
- Pharmaceutical Excipient:USP-NF certification limits supplier pools and sustains premium pricing for qualified producers.
- Nutraceutical:Encapsulation and dispersion applications in dietary supplement manufacturing.
Established volume favors Food Additive; emerging adoption favors Cosmetic Ingredient.
Application:
Cost tier stratification separates commodity-scale bakery operations from premium confectionery and specialized personal care formulations.
- Baking:Dough strengthening and crumb softening dominate commercial bakery demand. North American artisanal cooperatives scaling into regional supply networks pull volumes upward through direct procurement channels.
- Confectionery:European channels impose the most stringent emulsifier functionality requirements, with manufacturers building dual-source SSL relationships ahead of potential EFSA reclassification.
- Personal Care:Skin-conditioning and emulsion stabilization in creams and lotions.
- Dietary Supplements:Bioavailability enhancement and ingredient dispersion in nutraceutical formulations.
Volume concentration sits with Baking; margin expansion sits with Confectionery.
End User:
Customer type determines procurement modality, with large-scale food manufacturers narrowing supplier bases while cosmetic and pharmaceutical buyers prioritize technical service depth.
- Food Manufacturers:Consolidated procurement teams at industrial bakery groups displace distributor intermediaries. Direct channel relationships concentrate SSL contracts among vertically integrated oilseed processors with captive stearic acid supply.
- Cosmetic Companies:Specialized application laboratories co-develop formulations with SSL producers, straining mid-cap manufacturers lacking technical service infrastructure.
- Pharmaceutical Firms:USP-NF compliance requirements restrict qualified supplier pools.
- Health Brands:Nutraceutical and dietary supplement manufacturers with flexible specification tolerances.
Procurement scale favors Food Manufacturers; technical service intensity favors Cosmetic Companies.
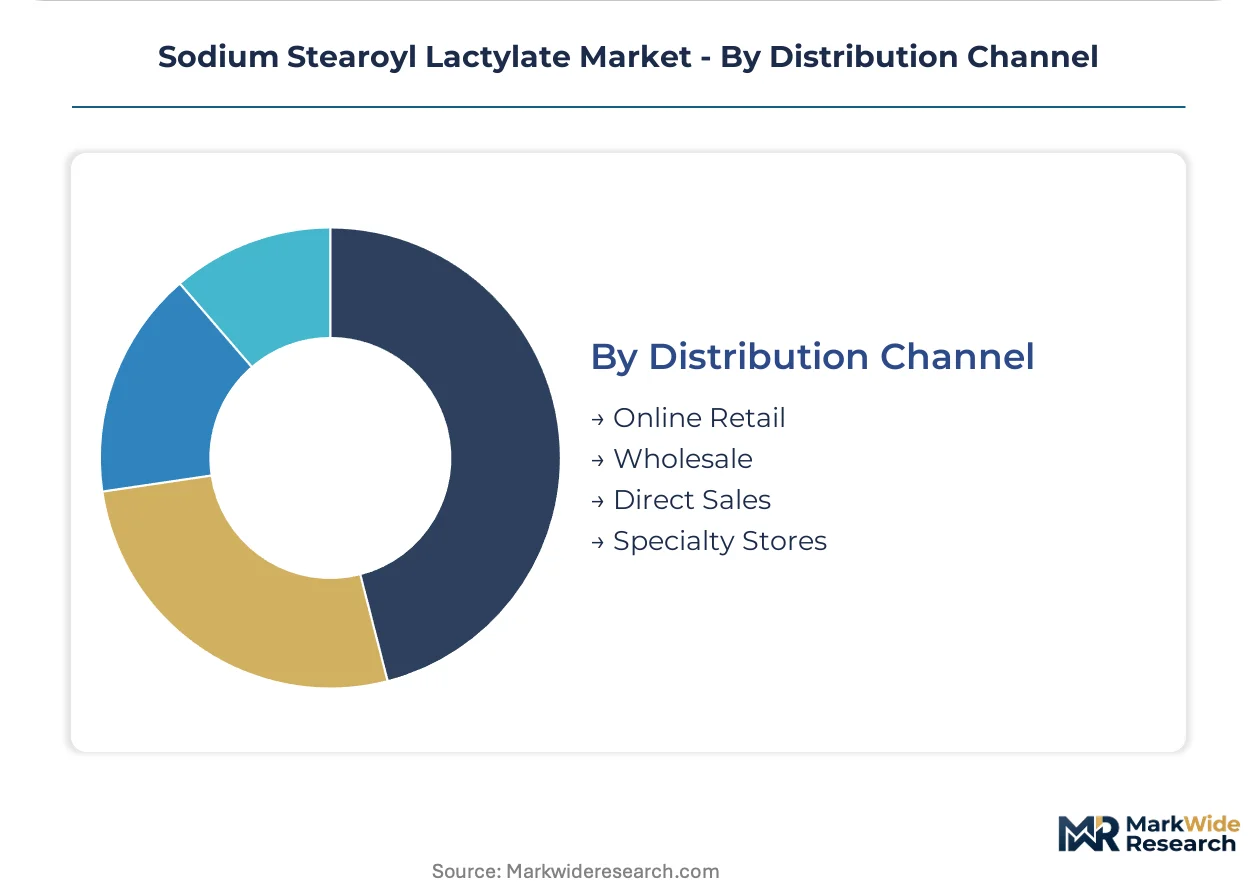
Distribution Channel:
Supply concentration geography shapes channel viability, with Asian esterification capacity clusters favoring wholesale consolidation while North American clean-label demand enables direct sales penetration.
- Direct Sales:Volume SSL contracts increasingly bypass distributor intermediaries as buyer concentration consolidates technical sourcing decisions. Integrated producers with captive feedstock leverage direct channels to defend margin position.
- Wholesale:Geographic supply risk from Chinese esterification capacity clusters amplifies wholesale intermediary importance for risk diversification.
- Online Retail:Small-batch cosmetic and nutraceutical buyers access SSL through digital procurement platforms.
- Specialty Stores:Artisanal bakery supply outlets serving regional cooperative networks.
Contract scale favors Direct Sales; risk diversification favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure underwrites Europe's emulsifier import capacity, while the Mississippi River barge network anchors North American stearic acid feedstock distribution. These logistics arteries determine where SSL production clusters concentrate and which regulatory jurisdictions shape supplier qualification timelines.
United States
Artisanal bakery cooperatives scaling into regional supply networks pull SSL volumes upward through direct procurement channels. The FDA's GRAS reaffirmation process for emulsifiers compresses supplier qualification timelines, favoring established domestic producers. Chicago and Minneapolis-St. Paul industrial corridors host concentrated commercial bakery operations replacing DATEM with SSL in premium bread lines.
Germany
REACH registration obligations oblige importers to submit full toxicological dossiers, raising compliance costs for Asian suppliers seeking continental access. The ECHA enforcement framework tightens documentation requirements for esterification-derived emulsifiers. The Cologne-Düsseldorf chemical corridor anchors European SSL distribution, with formulation laboratories co-developing clean-label alternatives ahead of potential EFSA reclassification.
China
Esterification capacity clusters in coastal provinces face intensifying MEE effluent enforcement under dual carbon goals, amplifying geographic supply risk. The SAMR food additive registration process governs domestic SSL production for both local consumption and export. Yangtze River Delta chemical parks concentrate backward-integrated manufacturers with captive stearic acid supply from regional oilseed processing.
India
Industrial bakeries in Maharashtra and Gujarat are accelerating SSL adoption as diacetyl tartaric acid ester replacements in packaged bread manufacturing. The FSSAI's evolving emulsifier standards create compliance windows for qualified suppliers entering the market. Mumbai-Pune industrial corridors host expanding commercial bakery operations seeking plant-based dough conditioners for clean-label product lines.
Japan
Confectionery manufacturers in the Kanto region impose stringent emulsifier functionality requirements that sustain premium pricing for specification-grade SSL. The PMDA's pharmaceutical excipient standards limit qualified supplier pools for tablet-binding applications. Osaka-Kobe industrial zones concentrate personal care formulators seeking non-ionic alternatives for skin-conditioning applications in moisturizers and color cosmetics.
Sodium Stearoyl Lactylate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying specification-grade emulsifiers to formulation houses. The vendor base organizes around three strategic archetypes: oilseed processors with captive stearic acid supply, integrated food ingredient conglomerates with application laboratories, and regional esterification specialists serving pharmaceutical certification niches. Consolidation upstream tightens supply relationships, while mid-cap producers face strain from technical service demands. Dominant competitive moves include backward integration into oilseed crushing and geographic expansion through distributor acquisition.
Among European-based chemical suppliers, Kowa Europe GmbH and Merck KGaA occupy positions within the pharmaceutical excipient certification tier, where USP-NF compliance requirements sustain premium pricing. Kerry Ingredients exemplifies the integrated food ingredient archetype, competing through bakery application laboratories that co-develop clean-label formulations with end users. Cargill Inc. anchors the oilseed processor category, leveraging its upstream network to secure captive feedstock for SSL production. These three represent distinct competitive vectors: certification-driven, application-driven, and supply-chain-driven.
| Leading Market Players |
|---|
| Kowa Europe GmbH |
| Niacet |
| Cargill Inc. |
| DuPont |
| Ivanhoe Industries |
| Merck KGaA |
| Zhejiang Synose Tech Co. |
| Kerry Ingredients |
| Tate & Lyle Plc. |
| Others |
Value Network & Pricing Analysis
Stearic acid feedstock volatility from palm oil and tallow price swings compresses SSL production margins for non-integrated manufacturers while simultaneously widening spreads between captive-supply tier and merchant-market tier. This commodity input dependency forces pricing stratification across premium pharmaceutical-grade, standard food-grade, and economy industrial-grade tiers while concentrating procurement power among vertically integrated oilseed processors.
Pricing Analysis
Volume-discount tiering structures dominate SSL contract negotiations, with industrial bakery groups commanding 15-25% spreads below artisanal cooperative spot purchases. Price differentiation hinges on USP-NF certification grade and captive stearic acid integration, with pharmaceutical buyers absorbing premiums 40-60% above food-grade baselines. Cost compression in economy-tier industrial applications is intensifying because Asian merchant producers undercut on specification tolerances. Food manufacturers with consolidated procurement teams exhibit lowest price sensitivity; small-batch cosmetic formulators face highest per-kilogram exposure.
Supply Chain Analysis
Tariff exposure between China and North American end-users dominates supply chain risk calculations for merchant-grade SSL procurement. Esterification capacity clusters in China's Yangtze River Delta, Malaysia's palm oil processing corridors, and the US Midwest oilseed belt anchor global supply. Raw material dependencies draw from crude palm oil, rendered tallow, and synthetic stearic acid feedstocks. Single-source vulnerability from MEE effluent enforcement under China's dual carbon goals threatens coastal plant operating rates. Distribution runs through Rotterdam's liquid bulk terminals for European confectionery channels and Mississippi River barge networks for North American bakery supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation fragmentation across artisanal bakery cooperatives, plant-based dairy analog developers, and pharmaceutical excipient specialists creates multiple entry niches for differentiated SSL positioning. Demand-side bifurcation between specification-grade and commodity-grade requirements rewards targeted capability investments over scale chasing.
For Market Incumbents: Harden regulatory infrastructure against EFSA reclassification risk by accelerating dual-source certification across USP-NF and food-grade production lines. Deepen captive stearic acid supply through backward integration into regional oilseed crushing or long-term offtake agreements with Malaysian and Indonesian palm processors. Threat substitution from DATEM resurgence and emerging enzymatic dough conditioners demands preemptive application laboratory expansion in Minneapolis-St. Paul and Cologne-Düsseldorf corridors.
For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical excipient certification where USP-NF compliance limits supplier pools and sustains premium pricing. Target nutraceutical encapsulation applications with flexible specification tolerances that bypass entrenched food manufacturer procurement relationships. Go-to-market leverage rests on digital quality control workflows using inline near-infrared spectroscopy that compress batch release cycles versus incumbent manual testing protocols.
For Investors and Strategic Acquirers: Regional esterification specialists with existing SAMR registration and REACH dossier infrastructure represent the most defensible acquisition archetype for Asia-Europe corridor access. Long-term viability across the analysis window hinges on regulatory compliance moats widening faster than formulation substitution advances. Watch EFSA opinion publication timelines as the critical inflection signal for portfolio reweighting between food-additive and pharmaceutical-excipient exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive stearic acid supply secures margin defense against palm oil volatility. |
| Application Laboratory Expansion | Kerry Ingredients' bakery co-development partnerships lock in clean-label formulation switches from DATEM. |
| USP-NF Certification Investment | Merck KGaA's pharmaceutical excipient tier sustains 40-60% pricing premiums over food-grade SSL. |
| Dual-Source Supplier Relationships | European confectionery manufacturers hedge EFSA reclassification risk through diversified emulsifier portfolios. |
| Process Analytical Technology Deployment | Inline near-infrared spectroscopy compresses specification verification cycles for automated bakery dosing systems. |
Research Methodology
The analysis maps food additive, cosmetic ingredient, pharmaceutical excipient, and nutraceutical sub-sectors, each validated through procurement directors at industrial bakery groups, technical R&D leads at cosmetic formulators, and regulatory affairs managers at pharmaceutical firms. Primary intelligence combined plant manager interviews at Yangtze River Delta esterification facilities with secondary triangulation against FDA GRAS notifications, EFSA scientific opinions, SAMR food additive registries, and customs trade data for stearic acid derivatives. Bottom-up capacity assessments and top-down demand modeling converged on segment-level volume estimates.
Assumption sets held fixed regulatory classification trajectories for emulsifiers while varying palm oil price scenarios and EFSA opinion outcomes across sensitivity bands. The projection framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs derived from installed capacity utilization trends, substitution elasticity estimates for DATEM displacement, and pharmaceutical excipient demand growth curves. Industry-specific inputs incorporated MEE enforcement intensity projections for Chinese coastal plants and artisanal bakery cooperative scaling rates in North American regional networks.
Sensitivities concentrate around EFSA gastrointestinal effect reclassification, dual carbon goal acceleration in Chinese chemical parks, and palm oil sustainability certification disruptions. Forecasts embed these documented assumptions with explicit scenario boundaries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Esters Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Synthetic Wax Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Paraffin Wax Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Oleophilic Materials Market