
 Ethoxylates Market | 2026-2036
Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Ethoxylates Market Analysis
Buyer concentration across the ethoxylates value chain is broadening as regional detergent and agrochemical formulators multiply their sourcing relationships beyond traditional Western suppliers. BASF SE leverages its integrated ethylene oxide feedstock position to sustain cost leadership across European and Asian supply corridors. Shell plc anchors its ethoxylate portfolio on large-scale Gulf Coast manufacturing assets with direct pipeline access to ethylene raw materials. Huntsman International LLC differentiates through specialty alkoxylate capabilities that command premium positioning in personal care and pharmaceutical applications.
Ethoxylates are nonionic surfactants produced by the catalytic addition of ethylene oxide to hydrophobic substrates such as fatty alcohols, fatty acids, or alkylphenols, yielding amphiphilic molecules with tunable hydrophilic-lipophilic balance values typically ranging from 8 to 18. These compounds function primarily as wetting agents, emulsifiers, and detergency boosters across aqueous formulations in consumer and industrial products. The surfactants category dominates volume consumption given its ubiquity in laundry detergents and hard surface cleaners, while specialty-grade ethoxylates capture disproportionate margin pools due to stringent purity requirements in personal care and food-grade applications. Liquid formulations lead shipment volumes owing to easier handling and blending compatibility, though powder and granule forms retain structural importance in concentrated detergent tablets and agrochemical wettable powders.
EPA oversight under the Toxic Substances Control Act governs ethylene oxide emissions and residual limits in U.S.-manufactured ethoxylates, compelling producers to invest in closed-loop reactor designs and advanced stripping technologies. REACH registration requirements and the EU Green Deal's chemical sustainability targets are restricting certain alkylphenol ethoxylate chemistries while accelerating bio-based fatty alcohol feedstock qualification across European supply chains. India's BIS standards and CDSCO pharmaceutical excipient regulations create parallel compliance pathways for exporters targeting its domestic formulators. Stakeholders must monitor feedstock cost volatility between petrochemical and oleochemical routes while positioning for specialty-grade certification requirements that increasingly determine market access in regulated end-use segments.
Market Dynamics
Feedstock bifurcation between petrochemical and oleochemical routes is fragmenting cost structures across ethoxylate supply chains, forcing producers to hedge between integrated ethylene oxide positions and bio-based fatty alcohol sourcing.
Growth Catalysts
- Mild surfactant demand in personal care:Formulators are reformulating rinse-off products to replace sulfates with ethoxylated fatty alcohols that reduce skin irritation while maintaining foam stability.
- REACH-driven substitution:ECHA restrictions on alkylphenol ethoxylates are redirecting volume toward fatty alcohol ethoxylates in European industrial cleaning applications.
- Agrochemical cluster expansion in India:Gujarat and Maharashtra manufacturing hubs are scaling wettable powder and emulsifiable concentrate production, pulling in specialty ethoxylate imports.
Market Restraints
- Ethylene oxide price volatility:Gulf Coast feedstock costs swing with cracker operating rates and ethane-naphtha spread dynamics, compressing margin predictability for non-integrated producers.
- Alkylphenol ethoxylate phase-out timelines:ECHA sunset dates for nonylphenol ethoxylates are stranding formulation investments in textile processing and metalworking fluids.
- Bio-based fatty alcohol supply concentration:Southeast Asian oleochemical capacity dominates qualified feedstock for EU Green Deal-compliant ethoxylates, creating single-source risk.
Strategic Opportunities
- Pharmaceutical excipient certification:CDSCO and USP-grade qualification pathways for polysorbate and cetomacrogol ethoxylates open margin-rich supply contracts to Indian and North American drug formulators.
- Low-EO surfactant architectures:Narrow-range ethoxylation catalysts enable 1-2 mole adduct production for high-performance cleaners with reduced aquatic toxicity profiles.
- Carbon accounting integration:ISCC PLUS and REDcert mass-balance certification is expanding into European home care procurement specifications, favoring bio-attributed ethoxylate suppliers.
Industry Challenges
- Alkoxylation reactor engineering talent:Closed-loop ethylene oxide handling and narrow-distribution catalyst operation require specialized process safety expertise that competes with broader chemical manufacturing.
- Multi-jurisdiction registration timelines:Parallel REACH, EPA TSCA, and BIS compliance pathways for new ethoxylate grades extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethoxylates Market |
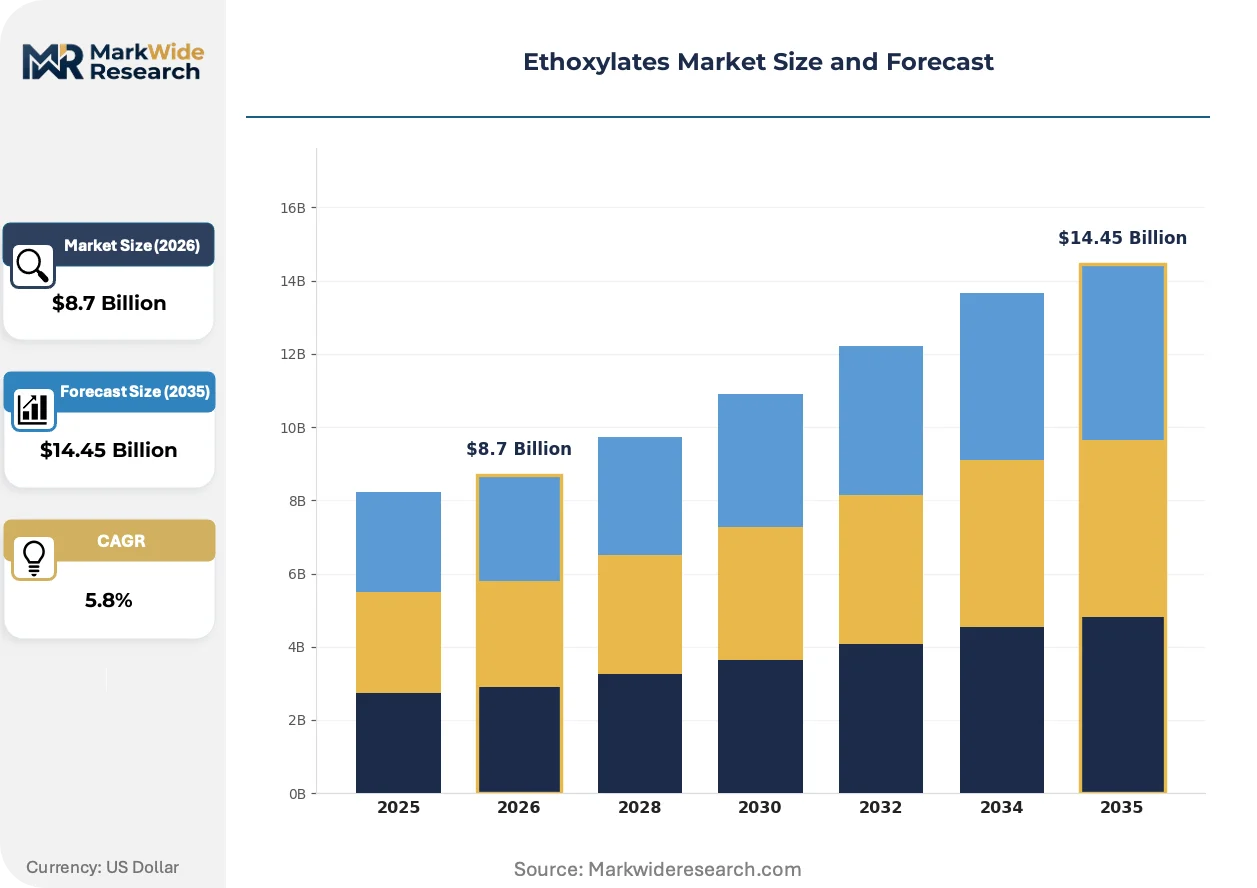
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Emulsifiers, Dispersants, Solubilizers End Use Industry: Personal Care, Agrochemicals, Household Cleaning, Oil & Gas Form: Liquid, Powder, Granules, Paste Grade: Standard, Specialty, Industrial, Food Grade |
| Companies Covered | BASF SE, Shell plc, Clariant, Huntsman International LLC, Dow, Sasol Ltd, Nouryon, Stepan Company, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethoxylates Market Emerging Trajectories
Process intensification and feedstock traceability are converging to redefine competitive advantage, with reactor efficiency gains and carbon accounting transparency becoming inseparable from market access.
Narrow-range ethoxylation catalysts based on alkaline earth metal chemistry are expanding into premium detergent and personal care segments. Procter & Gamble and Unilever formulation labs are validating 1-2 mole adducts for hard surface cleaners at accelerated timelines. This technology is expanding into applications previously reserved for conventional broad-range ethoxylates, compressing the performance gap between commodity and specialty grades.
EPA residual ethylene oxide limits under TSCA Section 5 are compelling reactor redesigns with advanced stripping columns and nitrogen sparging systems. Closed-loop manufacturing investments now exceed open-plant configurations for new U.S. capacity. Personal care and food-grade ethoxylate producers face the steepest compliance burden, with some redirecting volume toward industrial applications with less stringent residual specifications.
Mass-balance certification is altering procurement evaluation criteria for European home care and cosmetics formulators. Buyers now require ISCC PLUS or REDcert documentation alongside traditional quality metrics, displacing spot-market purchasing for strategic supply agreements. This shift is most visible in German and French detergent manufacturing, where sustainability-linked contract terms now govern 60-70 percent of ethoxylate volume planning.
Ethoxylates Market Segmentation
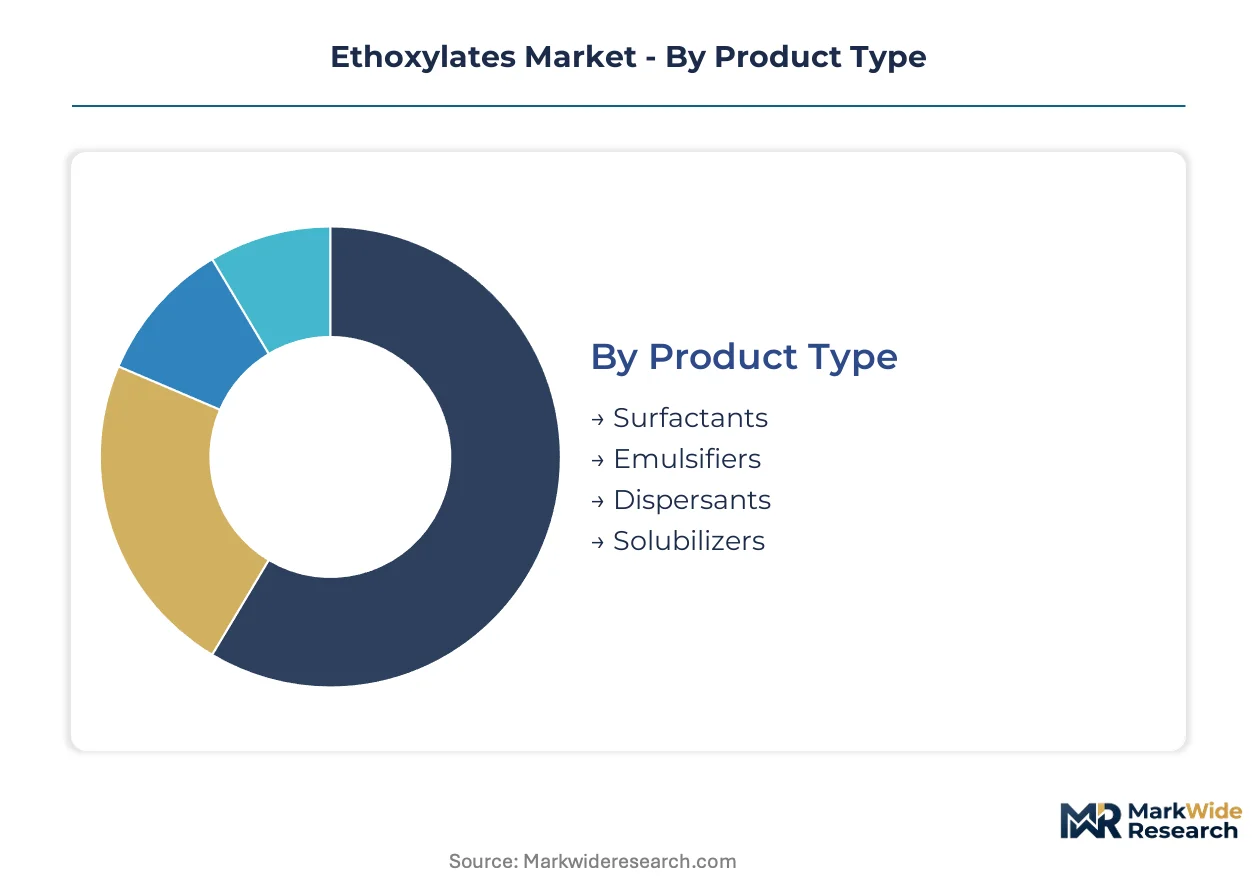
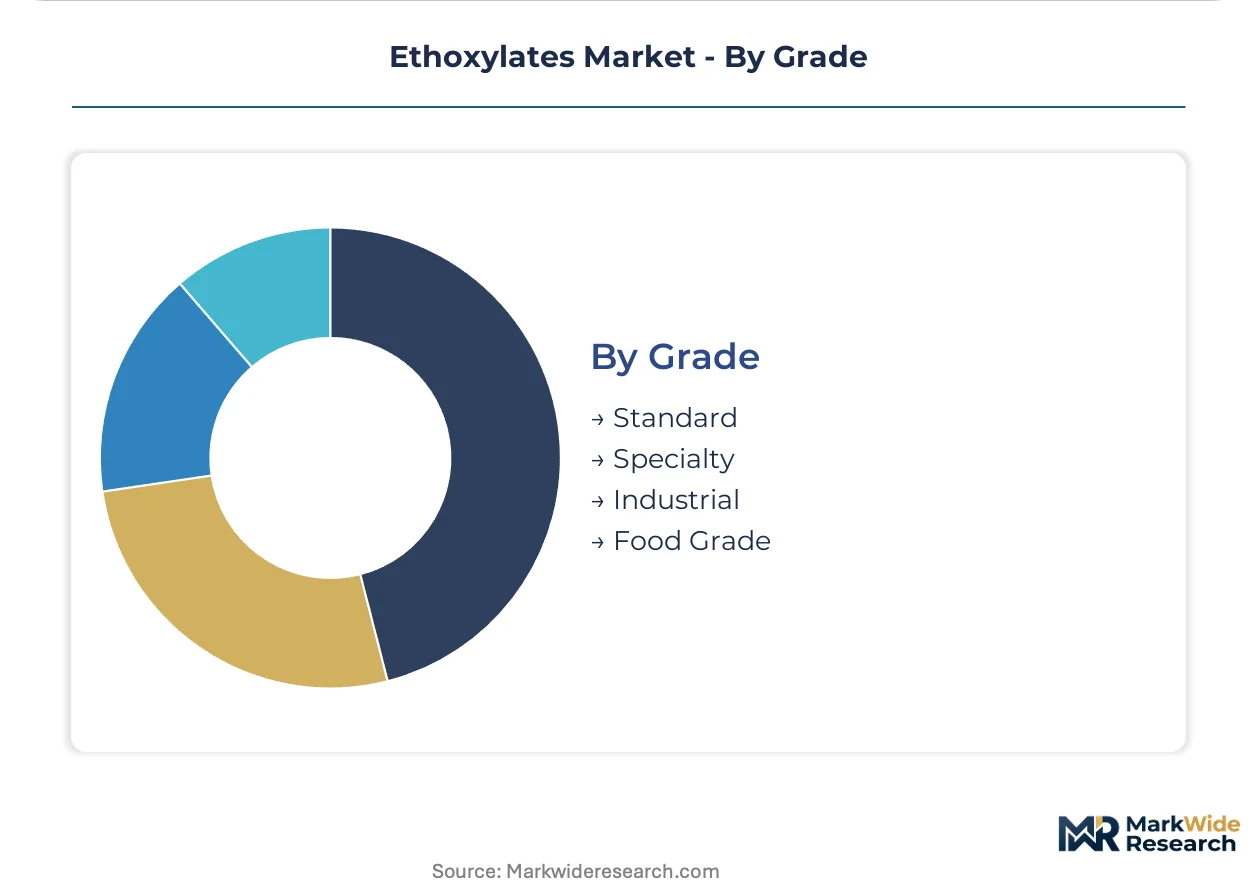
Ethoxylate suppliers configure certification pathways around end-use toxicity thresholds. EPA TSCA residual limits, REACH registration tiers, and FDA food-contact approvals fragment production workflows across grade categories. Formulators select segments based on stripping technology access and feedstock traceability rather than commodity pricing alone.
Product Type:
EPA residual ethylene oxide limits under TSCA Section 5 and REACH Article 57 SVHC listings determine which product types require closed-loop reactor investment versus open-plant configurations.
- Surfactants:Fatty alcohol ethoxylates with 7-12 mole EO adducts dominate laundry and hard surface detergent formulations. Demand concentrates in Indian and Chinese detergent manufacturing clusters where Gujarat and Shandong province formulators scale mild surfactant production for sulfate-free personal care lines.
- Emulsifiers:Polysorbate and sorbitan ester ethoxylates carry USP and Ph.Eur. excipient certification burdens for pharmaceutical applications. North American and European drug formulators drive specification tightening for endotoxin and peroxide impurity limits in parenteral-grade material.
- Dispersants:Alkylphenol ethoxylate replacements for pigment and agrochemical wettable powders face ECHA sunset date pressures.
- Solubilizers:Low-EO adducts for fragrance and essential oil systems require narrow-range catalyst technology.
Leading the category by volume: Surfactants. Growing fastest: Emulsifiers.
End Use Industry:
Customer procurement power varies sharply across end uses, with pharmaceutical and food-grade buyers demanding mass-balance certification while industrial purchasers prioritize feedstock cost hedging.
- Personal Care:Sulfate-free shampoo and body wash reformulations pull fatty alcohol ethoxylates with 2-4 mole EO adducts. Formulators in Germany and France now require ISCC PLUS documentation for 60-70 percent of contracted volume.
- Agrochemicals:Wettable powder and emulsifiable concentrate production in Gujarat and Maharashtra drives specialty ethoxylate consumption for pesticide dispersion stability.
- Household Cleaning:Concentrated detergent tablets favor powder ethoxylate grades with controlled particle size distribution.
- Oil & Gas:Demulsifier applications for crude oil dehydration tolerate higher residual ethylene oxide specifications than consumer-facing segments.
Household Cleaning commands the largest volume share. Personal Care exhibits the steepest expansion trajectory.
Form:
Handling infrastructure and blending compatibility determine form selection, with liquid receiving preference for continuous process integration and solid forms serving batch-oriented agrochemical compounding.
- Liquid:Dominates shipment volumes due to pumpable handling and direct tank-to-reactor blending in detergent and personal care plants. Gulf Coast and Rotterdam storage terminals anchor liquid distribution networks.
- Powder:Spray-dried grades with 80-200 micron particle size serve agrochemical wettable powder manufacturers in India and Brazil.
- Granules:Agglomerated forms for concentrated detergent tablets require low-dust processing to meet OSHA respirable silica guidelines.
- Paste:High-active-content semisolids target small-batch cosmetic formulators with limited heating infrastructure.
Liquid leads by volume. Powder gains share fastest.
Grade:
Margin stratification across grades reflects purification step intensity, with pharmaceutical and food grades requiring multi-stage stripping and carbon treatment that industrial grades bypass.
- Standard:Broad-distribution ethoxylates for industrial cleaning and textile processing face pricing pressure from Asian integrated producers.
- Specialty:Narrow-range ethoxylates with polydispersity indices below 1.1 command premium positioning in personal care and pharmaceutical applications.
- Industrial:Metalworking fluid and textile auxiliary grades tolerate higher residual ethylene oxide under OSHA PEL guidelines versus consumer-facing specifications.
- Food Grade:FDA 21 CFR 173.340 and EC 1333/2008 compliance for direct food contact requires dedicated production campaigns with segregated equipment.
Standard grade dominates volume. Specialty grade climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China concentrate ethoxylate demand through detergent and agrochemical manufacturing clusters, while Germany and the United States anchor specialty-grade production for regulated personal care and pharmaceutical segments.
United States
Gulf Coast petrochemical infrastructure supplies integrated ethylene oxide feedstock to domestic alkoxylation capacity. EPA TSCA Section 5 residual limits compel closed-loop reactor investments at Texas and Louisiana manufacturing sites. Houston-area storage terminals anchor liquid ethoxylate distribution networks serving Midwest detergent formulators.
Germany
REACH registration tiers and EU Green Deal chemical sustainability targets restrict alkylphenol ethoxylate chemistries while accelerating bio-based fatty alcohol qualification. ECHA sunset dates for nonylphenol ethoxylates redirect industrial cleaning volumes toward fatty alcohol alternatives. North Rhine-Westphalia chemical parks host narrow-range ethoxylation catalyst development for premium personal care grades.
India
Gujarat and Maharashtra agrochemical manufacturing hubs scale wettable powder and emulsifiable concentrate production, pulling specialty ethoxylate imports for pesticide dispersion stability. BIS standards and CDSCO pharmaceutical excipient regulations create parallel compliance pathways for domestic and export-oriented formulators. Ankleshwar and MIDC industrial corridors concentrate surfactant consumption for sulfate-free personal care lines.
China
Shandong province detergent manufacturers expand mild surfactant production for sulfate-free personal care reformulations targeting Southeast Asian export markets. NMPA and GB standards govern food-grade and pharmaceutical excipient specifications for domestic and international buyers. Yangtze River Delta chemical clusters integrate oleochemical fatty alcohol sourcing with ethoxylation capacity for European mass-balance certified supply chains.
Brazil
São Paulo state agrochemical formulators drive dispersant demand for soybean and corn crop protection applications. ANVISA pharmaceutical regulations align with USP and Ph.Eur. standards for polysorbate excipient imports. Campinas and Cubatão industrial districts concentrate ethoxylate consumption for Latin American detergent and personal care manufacturing.
Ethoxylates Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and narrow-range specialty positioning. The vendor base stratifies across integrated petrochemical majors, diversified chemical conglomerates, and focused alkoxylation specialists. Three archetypes dominate: Gulf Coast and Rotterdam-integrated ethylene oxide producers; European oleochemical-ethoxylate hybrid suppliers; and Asian detergent-grade volume manufacturers. Competitive moves center on backward integration into ethylene oxide or fatty alcohol feedstock, and mass-balance certification for European home care procurement.
Among European-integrated chemical majors, BASF SE and Shell plc exemplify feedstock-anchored competitive positioning, while Huntsman International LLC occupies the specialty alkoxylate tier. BASF SE leverages its Ludwigshafen ethylene oxide integration across European and Asian supply corridors. Shell plc anchors its portfolio on Gulf Coast manufacturing assets with pipeline ethylene access. Huntsman International LLC represents the premium-tier archetype through differentiated capabilities in personal care and pharmaceutical applications.
| Leading Market Players |
|---|
| BASF SE |
| Shell plc |
| Clariant |
| Huntsman International LLC |
| Dow |
| Sasol Ltd |
| Nouryon |
| Stepan Company |
| Solvay |
| Others |
Supply Flow & Price Mechanics
ISCC PLUS and REDcert mass-balance certification requirements from German and French home care formulators are forcing ethoxylate suppliers to segregate bio-attributed feedstock streams, elevating cost structures for compliant producers while compressing margins for non-certified spot-market sellers.
Pricing Analysis
Volume concentrates in standard-grade fatty alcohol ethoxylates for Indian and Chinese detergent manufacturing, while margin pools accrue to specialty narrow-range grades for pharmaceutical and personal care applications. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified emulsifiers from industrial metalworking fluid grades and unqualified commodity surfactants. Cost compression in standard grades is intensifying because Asian integrated producers leverage captive ethylene oxide positions. Industrial purchasers in oil and gas demulsifier applications exhibit lowest price sensitivity, while Indian agrochemical formulators drive hardest bargain on wettable powder dispersants.
Supply Chain Analysis
Reverse-logistics flows for ethoxylate handling center on nitrogen-sparging equipment returns and spent catalyst reclamation from narrow-range ethoxylation operations. Production gravity centers on the United States Gulf Coast, Germany's North Rhine-Westphalia chemical parks, and India's Gujarat industrial corridor. Feedstock supply rests on ethylene oxide from integrated crackers, fatty alcohols from Southeast Asian oleochemical plants, and alkaline earth metal catalysts from specialized chemical suppliers. Single-source vulnerability concentrates in qualified bio-based fatty alcohol streams for EU Green Deal compliance. Distribution runs through Houston and Rotterdam liquid storage terminals with direct pipeline connections to downstream detergent and personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 57 SVHC listings and ECHA sunset dates for alkylphenol ethoxylates construct a cost-of-compliance moat that rewards early movers in fatty alcohol alternative registration while stranding laggards with stranded formulation investments.
For Market Incumbents: Anticipate margin compression from Indian and Chinese integrated producers by deepening backward integration into ethylene oxide or securing long-term offtake agreements with Southeast Asian fatty alcohol suppliers. Prioritize narrow-range catalyst R&D partnerships in North Rhine-Westphalia to defend premium positioning against specialty-grade entrants. For New Entrants and Emerging Players: Begin with pharmaceutical excipient certification pathways for polysorbate and cetomacrogol grades targeting CDSCO-registered Indian drug formulators. The most penetrable white-space sits in USP-grade emulsifiers for parenteral applications, where incumbent capacity constraints create qualification backlogs. For Investors and Strategic Acquirers: The window for entry favors bio-attributed ethoxylate specialists with ISCC PLUS certification and established relationships with German home care procurement teams. Watch for ECHA acceleration of additional alkylphenol ethoxylate restrictions as the inflection signal for specialty-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Gulf Coast producers with pipeline ethylene access secure feedstock cost predictability against cracker rate volatility. |
| Narrow-Range Catalyst Deployment | Alkaline earth metal chemistry investments unlock premium positioning in P&G and Unilever formulation pipelines. |
| ISCC PLUS Certification Program | German and French detergent manufacturers now require mass-balance documentation for majority of contracted volume. |
| Pharmaceutical Excipient Qualification | CDSCO and USP-grade pathways open margin-rich supply contracts to Indian and North American drug formulators. |
| Closed-Loop Reactor Engineering | EPA TSCA Section 5 compliance investments exceed open-plant configurations for new U.S. capacity additions. |
Methodological Framework
Independent corroboration across alkoxylation plant managers, procurement leads at downstream detergent and agrochemical OEMs, and distribution channel partners underwrites the qualitative findings. Primary fieldwork with technical R&D directors at personal care formulators supplemented customs and trade data from Indian DGFT and Chinese customs authorities, ACC and Cefic industry reports, and SEC 10-K filings from integrated chemical majors. Bottom-up capacity modeling triangulates against top-down consumption estimates from end-use industry associations.
Rate-of-change decomposition across the projection horizon segments volume by grade tier, end-use industry, and regional production hub. CAGRs derive from ethylene oxide feedstock cost trajectories, REACH registration timeline assumptions, and Indian agrochemical cluster expansion rates. Modeled inputs include narrow-range catalyst adoption curves in premium personal care and pharmaceutical-grade stripping technology deployment.
Underlying measurement precision varies by segment; standard-grade industrial ethoxylates carry tighter precision than emerging specialty pharmaceutical grades with limited commercial history. Forecasts reflect documented assumptions on ECHA regulatory timelines and Indian manufacturing cluster growth rates. Practitioners should monitor EPA residual ethylene oxide limit enforcement intensity and Southeast Asian oleochemical capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Oleophilic Materials Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Ozokerite Wax Market