

Aircraft Winglet Retrofit Kits for Narrow-Body Fleets Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Winglet Retrofit Kits for Narrow-Body Fleets Market Insights
EPA aircraft emissions standards are repositioning retrofit economics for narrow-body operators. Aviation Partners Boeing leverages its exclusive licensing agreements with the airframe OEM to sustain aftermarket dominance across the 737 platform. Airbus anchors European retrofit demand through its Sharklet upgrade program for A320ceo operators. GKN Aerospace competes via advanced carbon fiber manufacturing scale, supplying composite winglet structures to multiple retrofit kit providers.
Aircraft winglet retrofit kits for narrow-body fleets are aerodynamic appendage systems, typically fabricated from carbon fiber reinforced polymer with aluminum alloy root fittings, that reduce induced drag by disrupting wingtip vortices to improve fuel efficiency. Their primary commercial purpose is extending operational range and lowering per-flight fuel burn without requiring full airframe replacement. Blended winglets occupy the largest installed base among legacy retrofit programs, while split scimitar variants represent the fastest-growing product category as operators pursue incremental drag reduction beyond first-generation designs. Composite materials dominate technology selection due to strength-to-weight advantages, though titanium hardware commands premium positioning in high-cycle fleet applications where fatigue resistance determines maintenance intervals.
FAA airworthiness directives and EASA certification requirements shape retrofit kit approval pathways, with both agencies mandating flutter and structural integrity testing for supplemental type certificate issuance. EPA greenhouse gas regulations for commercial aviation indirectly drive retrofit demand by tightening fleet-average emissions benchmarks that operators must meet without retiring younger narrow-body assets. Stakeholders must monitor evolving ICAO carbon offset standards and assess whether emerging spiroid winglet geometries can achieve sufficient certification traction to challenge established blended and split-scimitar architectures.
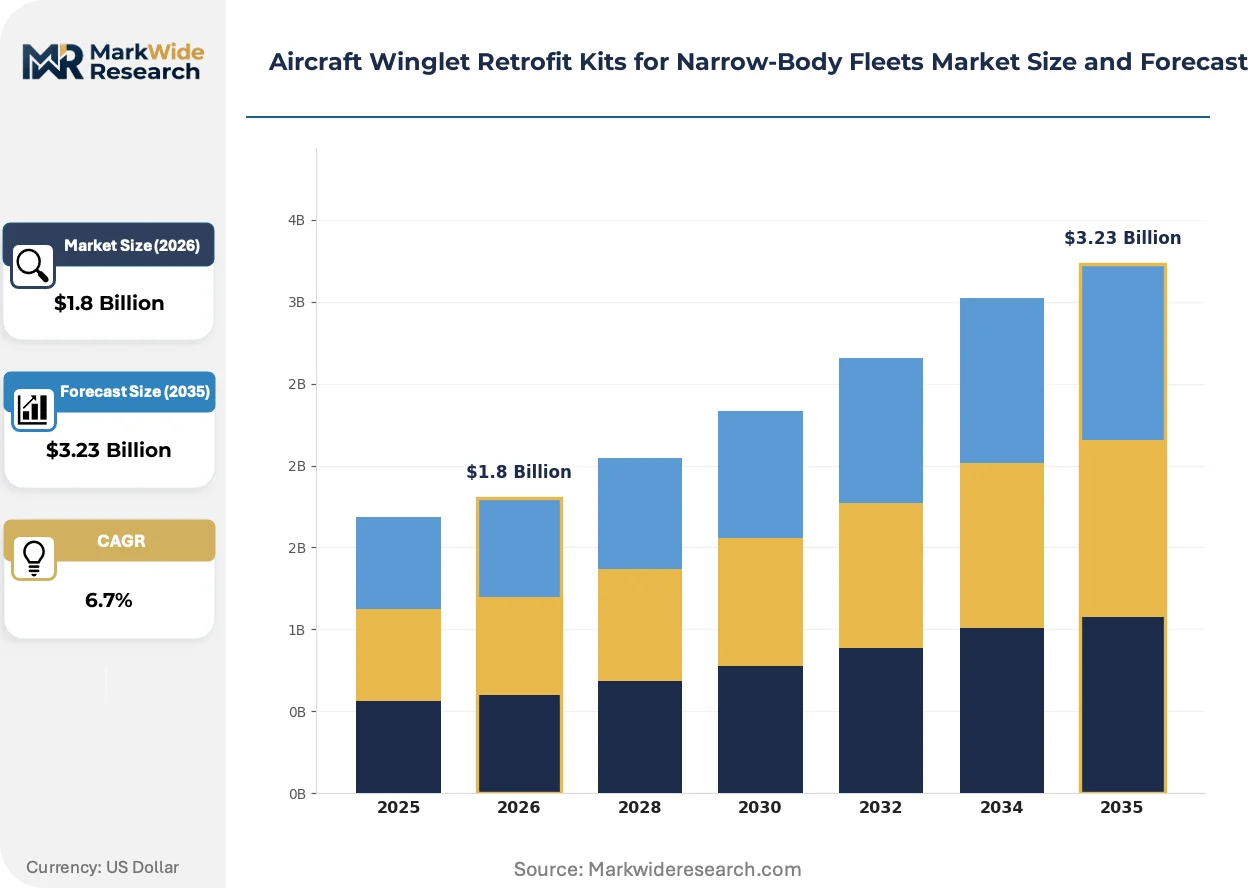
Market Dynamics
Retrofit economics hinge on the divergence between rising jet fuel costs and the fixed capital cost of winglet installation, with EPA emissions standards compressing payback period calculations for narrow-body operators.
Growth Catalysts
- EPA Aircraft Emissions Standards:Fleet-average greenhouse gas benchmarks force operators to upgrade existing assets rather than retire younger narrow-body aircraft.
- Carbon Fiber Reinforced Polymer:Strength-to-weight advantages of composite winglet structures enable drag reduction without structural reinforcement penalties.
- United States Narrow-Body Density:The world's largest installed base of eligible Boeing 737 and Airbus A320 family aircraft concentrates retrofit demand.
Market Restraints
- Titanium Hardware Cost Volatility:Premium fatigue-resistant fasteners for high-cycle fleets expose operators to aerospace metal price swings.
- Supplemental Type Certificate Complexity:FAA and EASA flutter testing requirements extend approval timelines and engineering validation costs.
- First-Generation Blended Winglet Saturation:Legacy retrofit penetration on early-adopter 737NG fleets limits incremental upgrade volume.
Strategic Opportunities
- Split Scimitar Geometry:Second-generation designs offering incremental drag reduction beyond blended architectures command upgrade premiums from fuel-cost-sensitive operators.
- India Narrow-Body Expansion:Low-cost carrier fleet growth creates retrofit-ready installed base as EPA-equivalent emissions pressure builds.
- Performance-Based Navigation Integration:Winglets extending optimal cruise altitude compatibility unlock route efficiency gains for precision flight path operators.
Industry Challenges
- Composite Repair Technician Scarcity:Carbon fiber damage assessment and field repair capabilities lag fleet retrofit deployment rates.
- Airframe-Specific Engineering Validation:Each variant requires distinct structural load analysis, fragmenting kit development resources across OEM platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Winglet Retrofit Kits for Narrow-Body Fleets Market Trends and Innovations
Retrofit technology trajectories center on aerodynamic efficiency gains beyond first-generation designs, with regulatory pressure and operator cost discipline accelerating upgrade cycles.
Spiroid winglet geometries are absorbing developmental attention from advanced aerodynamics teams seeking vortex disruption beyond planar surface limitations. European research consortia and NASA Langley test programs are validating computational fluid dynamics models for non-planar tip devices. This geometry is absorbing certification pathway complexity as EASA and FAA establish precedent for non-traditional wingtip architectures outside existing supplemental type certificate frameworks.
ICAO Carbon Offset and Reduction Scheme for International Aviation tightens fleet emissions accountability across member states, indirectly mandating retrofit investment for compliance-capable narrow-body operators. The scheme's baseline-setting methodology rewards early efficiency upgrades with offset credit eligibility. Asian low-cost carriers with trans-Pacific route authorities face the steepest compliance cost trajectories and are prioritizing split-scimitar retrofits over blended alternatives.
Airline technical procurement departments are consolidating winglet upgrade decisions with engine performance improvement package timing, bundling aerodynamic and propulsion efficiency investments into single maintenance window events. This synchronization compresses fleet downtime but concentrates supplier negotiation leverage. North American legacy carriers with integrated maintenance operations are most advanced in this coordination, pressuring kit providers for volume pricing tied to multi-airframe commitments.
Aircraft Winglet Retrofit Kits for Narrow-Body Fleets Market Segmentation
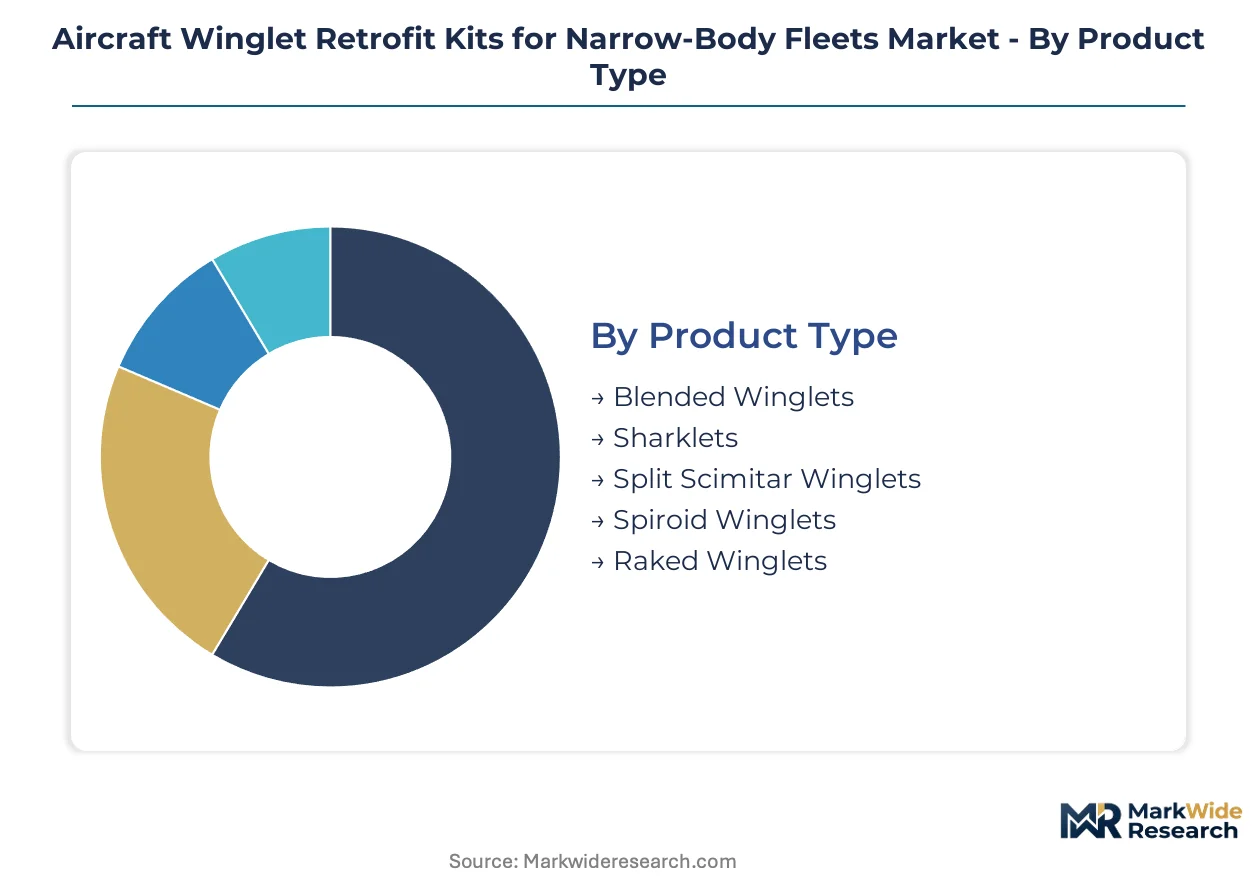
Winglet retrofit kit selection hinges on airframe compatibility, regulatory certification pathways, and payback period calculations that vary sharply across operator types. Segmentation reveals where technology premiums concentrate versus where commodity procurement dominates.
Product Type:
Blended winglets anchor installed base volume while split scimitar variants command upgrade premiums for fuel-cost-sensitive operators.
- Blended Winglets:Curved transition surfaces extending wingtip chord with minimal structural modification requirements. Boeing 737NG operators in the United States concentrate replacement demand as first-generation installations age beyond fatigue inspection thresholds.
- Sharklets:Airbus-proprietary upturned wingtip devices with distinctive triangular planform. A320ceo family retrofits across European low-cost carriers accelerate as EASA emissions benchmarks tighten fleet-average obligations.
- Split Scimitar Winglets:Dual-surface geometry adding lower ventral strake for incremental vortex disruption. Climbing the fastest among upgrade categories as operators extract additional drag reduction from previously retrofitted airframes.
- Spiroid Winglets:Closed-loop ring structures disrupting tip vortices through non-planar aerodynamics. NASA Langley and European research consortia drive developmental validation pending supplemental type certificate precedent.
- Raked Winglets:Swept-back tip extensions optimized for high-Mach cruise efficiency. Boeing 787 and 777-300ER heritage designs see limited narrow-body application due to span constraints at gate positions.
Today's leader: Blended Winglets. Tomorrow's challenger: Split Scimitar Winglets.
Technology:
Material selection trades manufacturing cost against structural weight and inspection interval extension.
- Composite Materials:Glass and carbon fiber laminates dominating external skin fabrication. GKN Aerospace manufacturing scale in the United Kingdom supplies multiple kit providers with certified prepreg structures.
- Aluminum Alloy:Root fittings and attachment lugs requiring high bearing strength. Legacy 737 retrofit programs specify 7075-T6 forgings where galvanic compatibility with carbon fiber drives isolation design.
- Carbon Fiber Reinforced Polymer:Unidirectional and woven prepregs achieving specific strength multiples above metallics. Split scimitar upper and lower surface integration demands automated fiber placement for geometric complexity.
- Honeycomb Core:Nomex and aluminum cellular structures stabilizing thin composite skins against buckling. Repair technician scarcity constrains field damage assessment capabilities for cored structures.
- Titanium:Premium fasteners and fittings for high-cycle fleets exceeding 50,000 flight hours. Price volatility in aerospace-grade Ti-6Al-4V exposes operators to supply chain margin compression.
CFRP commands technology leadership. Titanium hardware faces cost headwinds.
Application:
Retrofit justification centers on fuel burn reduction with secondary benefits shaping operator preference ordering.
- Fuel Efficiency Improvement:Primary commercial driver quantified through flight operational quality assurance data. EPA fleet-average standards reposition retrofit economics for narrow-body operators.
- Noise Reduction:Wingtip vortex attenuation lowering approach noise footprint. ICAO Chapter 14 compliance pathways in Europe and North America create secondary retrofit incentives.
- Flight Stability Enhancement:Reduced induced drag improving high-altitude handling margins. Performance-based navigation integration unlocks route efficiency for precision flight path operators.
- Drag Reduction:Direct aerodynamic benefit measured through cruise fuel flow monitoring. Split scimitar geometries extract incremental gains beyond blended baseline performance.
- Extended Flight Range:Payload-range curve expansion enabling new city pairs without tech stops. United States transcontinental operators prioritize range extension for winter wind contingency reserves.
Fuel efficiency anchors current procurement. Range extension emerges as competitive differentiator.
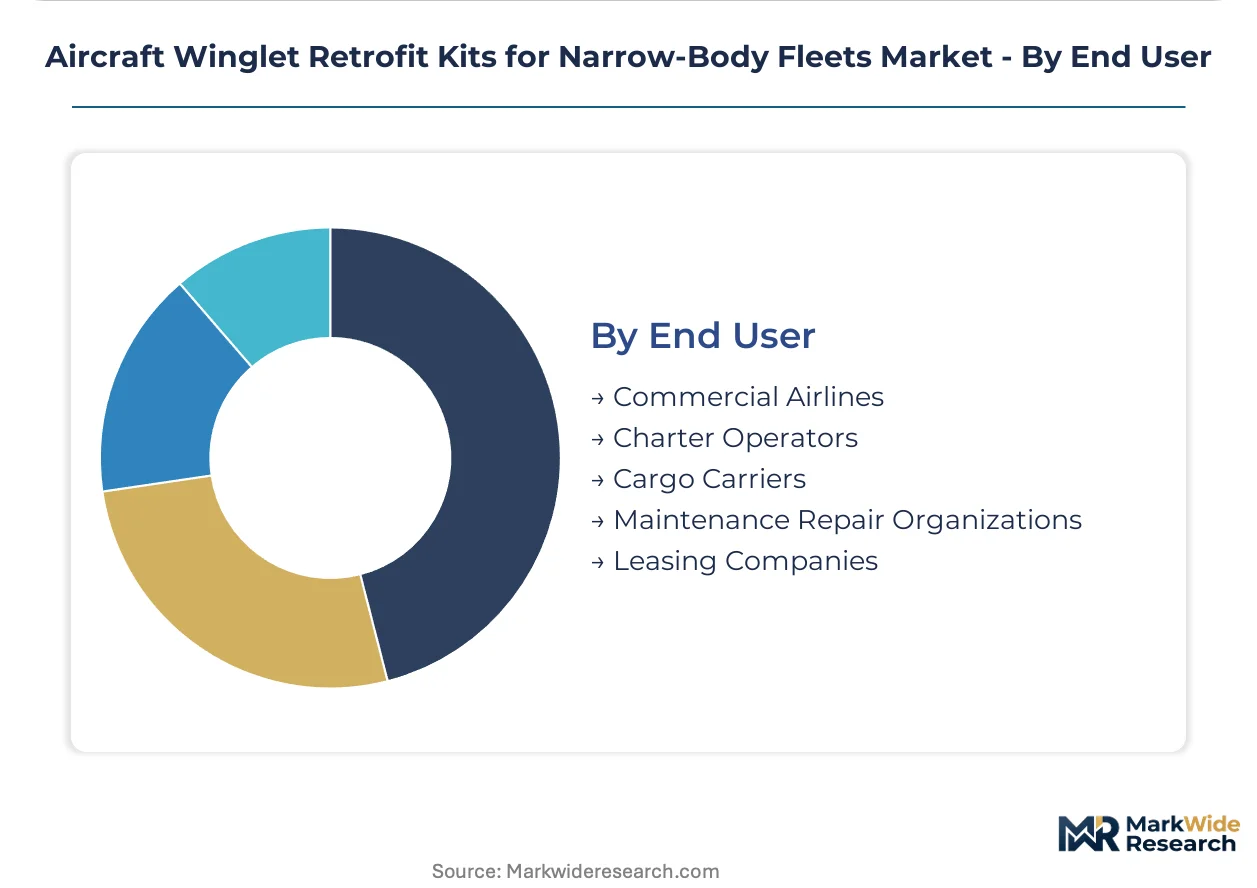
End User:
Customer concentration varies by fleet ownership structure and maintenance integration depth.
- Commercial Airlines:Scheduled passenger operators with integrated engineering departments. North American legacy carriers bundle winglet upgrades with engine performance improvement package timing.
- Charter Operators:Ad-hoc capacity providers with seasonal demand fluctuation. Fragmented fleet composition complicates volume pricing negotiations with kit providers.
- Cargo Carriers:Dedicated freighter operators maximizing payload-range economics. Express parcel networks in the United States prioritize fuel burn reduction for overnight hub-and-spoke operations.
- Maintenance Repair Organizations:Third-party providers executing retrofit on behalf of fleet owners. STC holding authority and composite repair certification determine competitive positioning.
- Leasing Companies:Asset owners mandating retrofits prior to lease placement. Residual value enhancement justifies capital expenditure on mid-life narrow-body returns.
Commercial airlines dominate volume. Leasing companies drive standardization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial aviation winglet retrofit industry traces its commercial scale to Boeing's 737NG program validation in the United States during the early 2000s, establishing the technical and regulatory template that subsequent programs in Europe and Asia would adapt.
United States
American Airlines, Delta Air Lines, and Southwest Airlines operate the densest concentration of eligible 737 and A320 family aircraft worldwide. FAA emissions standards and fuel efficiency mandates compress retrofit payback calculations for domestic carriers. Seattle-area engineering clusters and Wichita maintenance hubs anchor kit installation capacity and composite repair technician training programs.
China
China Eastern, China Southern, and Hainan Airlines are expanding narrow-body fleets under EPA-equivalent emissions pressure from the country's dual carbon goals. The Civil Aviation Administration of China aligns certification requirements with ICAO standards for supplemental type certificate reciprocity. Shanghai Pudong and Guangzhou Baiyun maintenance bases are scaling composite winglet repair capabilities for domestic retrofit demand.
Germany
Lufthansa Group and Eurowings drive Sharklet retrofit penetration across A320ceo family aircraft. EASA emissions benchmarks and EU Green Deal aviation provisions tighten fleet-average obligations for German operators. Hamburg and Munich maintenance clusters specialize in Airbus-proprietary upgrade programs and carbon fiber damage assessment protocols.
India
IndiGo, SpiceJet, and Akasa Air are building retrofit-ready installed bases as low-cost carrier expansion accelerates. The Directorate General of Civil Aviation is harmonizing supplemental type certificate pathways with FAA and EASA precedents. Delhi-NCR and Mumbai maintenance hubs are developing composite repair technician pipelines to match projected fleet upgrade timelines.
United Kingdom
British Airways and easyJet prioritize fuel burn reduction for transatlantic and short-haul European route economics. UK Civil Aviation Authority certification alignment with EASA post-Brexit maintains retrofit kit approval reciprocity. London Gatwick and Manchester maintenance bases concentrate split-scimitar upgrade execution for mixed Boeing and Airbus fleets.
Aircraft Winglet Retrofit Kits for Narrow-Body Fleets Market Competitive Landscape
The competitive structure tilts toward airframe OEM-affiliated specialists with exclusive licensing agreements. Aviation Partners Boeing holds aftermarket dominance through Boeing platform exclusivity, while Airbus anchors European demand via proprietary Sharklet programs. Independent composite manufacturers compete on manufacturing scale and multi-platform supply relationships. Strategic moves concentrate on technology licensing extensions and certification pathway acceleration for second-generation geometries.
Within the OEM-licensed tier, Aviation Partners Boeing and Airbus exemplify airframe-aligned aftermarket control. GKN Aerospace occupies a position among independent composite structure suppliers, manufacturing carbon fiber winglet components for multiple retrofit kit providers. These three anchors represent the dominant competitive archetypes: exclusive platform licensors, proprietary airframe integrators, and scale-driven material specialists.
| Leading Market Players |
|---|
| Aviation Partners Boeing |
| Aviation Partners |
| Airbus |
| Boeing |
| GKN Aerospace |
| FACC AG |
| Safran |
| Korean Aerospace Industries |
| Tamarack Aerospace Group |
| Others |
Pricing and Supply Chain Analysis
EPA aircraft emissions standards gate qualified supply access and premium-tier pricing power for winglet retrofit providers serving narrow-body operators. Certification-holding incumbents command pricing premiums through exclusive supplemental type certificate authority, while uncertified manufacturers face exclusion from fleet upgrade procurement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and fleet scale. Premium tiers attach to titanium-fastened split-scimitar kits for high-cycle operators, while economy tiers cover aluminum-root blended winglet replacements for aging first-generation installations. Cost compression in standard-tier composite structures intensifies as GKN Aerospace and FACC AG expand automated fiber placement capacity. Low-cost carriers in India and Southeast Asia exhibit highest price sensitivity, whereas North American legacy carriers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight costs for oversized carbon fiber prepreg shipments from United Kingdom and German manufacturing hubs to Wichita and Seattle installation centers absorb margin across kit providers. Raw material sourcing draws from Toray Industries carbon fiber in Japan, Hexcel prepreg in the United States, and aerospace-grade titanium from VSMPO-AVISMA in Russia—creating tariff exposure from ongoing trade restrictions. Distribution runs through airframe OEM-authorized channels with Aviation Partners Boeing and Airbus controlling certified kit release to maintenance repair organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with ICAO Carbon Offset and Reduction Scheme for International Aviation baseline-setting methodology mandating retrofit investment for compliance-capable narrow-body operators.
For Market Incumbents: Lock in exclusive licensing extensions with Boeing and Airbus before supplemental type certificate frameworks expand to spiroid geometries. Deepen captive supply of carbon fiber prepreg through backward integration into automated fiber placement to offset titanium price volatility. Defend against emerging composite repair specialists by certifying proprietary damage assessment protocols. For New Entrants and Emerging Players: Launch via maintenance repair organization partnerships targeting India's low-cost carrier expansion where DGCA certification harmonization creates pathway entry. Focus white-space capture on split-scimitar upgrade programs for previously retrofitted 737NG fleets seeking incremental drag reduction. Emphasize field repair technician training bundles to differentiate from OEM-licensed competitors. For Investors and Strategic Acquirers: Roll-up economics work for independent composite structure suppliers because airframe-specific engineering validation fragments kit development resources across OEM platforms. Long-term viability hinges on certification pathway acceleration for second-generation geometries. Watch EASA and FAA supplemental type certificate precedent for non-planar spiroid architectures as inflection signal for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Supplemental Type Certificate Expansion | EASA and FAA flutter testing precedents for spiroid geometries unlock non-planar aerodynamics market entry. |
| Composite Manufacturing Scale-Up | GKN Aerospace automated fiber placement investment reduces unit costs for split-scimitar surface integration. |
| Maintenance Repair Organization Certification | STC holding authority and composite repair credentials determine competitive positioning in third-party retrofit execution. |
| Performance-Based Navigation Integration | Winglets extending optimal cruise altitude compatibility unlock route efficiency gains for precision flight path operators. |
| Technician Training Pipeline Development | Delhi-NCR and Mumbai maintenance hubs build composite repair capacity to match India's projected fleet upgrade timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured fleet planning directors at American Airlines, Delta Air Lines, and Southwest Airlines; procurement leads at IndiGo and SpiceJet; engineering validation specialists at Aviation Partners Boeing; and composite repair technicians at Wichita and Seattle maintenance hubs. Secondary validation drew from FAA supplemental type certificate filings, EASA certification databases, EPA aircraft emissions standard rulemakings, and ICAO CORSIA baseline methodology documentation. Bottom-up fleet inventory analysis triangulated against top-down retrofit spend estimates from airline capital expenditure disclosures.
Historical reference periods anchored demand modeling to 737NG program validation in the early 2000s and subsequent A320ceo Sharklet retrofit adoption curves. Segmentation dimensions spanned product type, material technology, application benefit, and end-user ownership structure. CAGRs derived from regression analysis of fleet age distributions, fuel price scenarios, and regulatory compliance cost trajectories. Forecast inputs incorporated narrow-body delivery backlogs, engine performance improvement package timing synchronization, and emerging market low-cost carrier expansion rates.
Several conditions sit outside the modeled scope, including breakthrough certification of spiroid winglet geometries, sustained aerospace titanium supply disruptions, and accelerated narrow-body retirement programs that would retire eligible airframes before retrofit payback. Forecasts reflect documented assumptions about regulatory enforcement continuity and fuel price banding. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.