
 Asia-Pacific Medical Simulation Market | 2026-2036
Asia-Pacific Medical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Simulation Market Outlook
Software-defined subscription layers for scenario libraries and haptic feedback calibration is hardening into the core revenue mechanism for simulator vendors. CAE Inc. leverages its installed base of aviation simulation infrastructure to cross-sell medical training platforms across Australian defense and civilian hospital networks. Kyoto Kagaku Co. Ltd anchors its position through anatomical model specialization that sustains premium pricing in Japanese medical school procurement cycles. Mentice AB competes in endovascular simulation through proprietary physics engines that dominate interventional cardiology training protocols across South Korean teaching hospitals.
Asia-Pacific medical simulation encompasses electro-mechanical patient replicas, computational physiology engines, and immersive visualization systems designed to replicate clinical scenarios without live patient risk. These systems integrate pneumatic actuators, biomaterial tissue analogs, and real-time physiological modeling software to enable repeatable procedural training for credentialing and competency assessment. Mannequins and virtual reality simulators capture divergent margin structures, with high-fidelity patient mannequins commanding replacement part streams while VR simulators scale through software licensing without per-unit manufacturing constraints. Task trainers occupy a mature procurement channel where price sensitivity from community medical colleges compresses margins, whereas mixed reality platforms represent the fastest-expanding segment as hardware costs decline and surgical societies endorse immersive credentialing pathways.
TGA Australia's medical device framework, Japan's PMDA quality management standards, and South Korea's MFDS clinical training equipment classifications collectively elevate compliance costs for market entry while validating simulation efficacy claims. These regulators mandate traceable competency documentation, which embeds simulation systems into mandatory continuing education pathways rather than discretionary capital expenditure. Stakeholders must monitor evolving reimbursement linkages between simulation-based training hours and clinical licensure renewal requirements across divergent national health systems.
Market Dynamics
Subscription-based scenario licensing is compressing capital expenditure cycles for nursing schools and metropolitan hospital networks across Southeast Asia and Japan. This shift embeds vendors into recurring revenue streams while reducing upfront procurement friction for institutional buyers.
Growth Catalysts
- Accreditation mandates:Nursing schools across Thailand, Vietnam, and the Philippines face compulsory simulation hour requirements from national nursing councils. Procurement volumes for mid-fidelity mannequins are accelerating to meet these standards.
- Endovascular procedural expansion:Interventional cardiology training protocols in South Korean teaching hospitals now require physics-engine simulators for credentialing. Mentice AB's installed base generates replacement software license demand.
- TGA certification tightening:Australia's Therapeutic Goods Administration mandates traceable competency documentation for medical device operator recertification. This embeds simulation into mandatory continuing education rather than discretionary spending.
Market Restraints
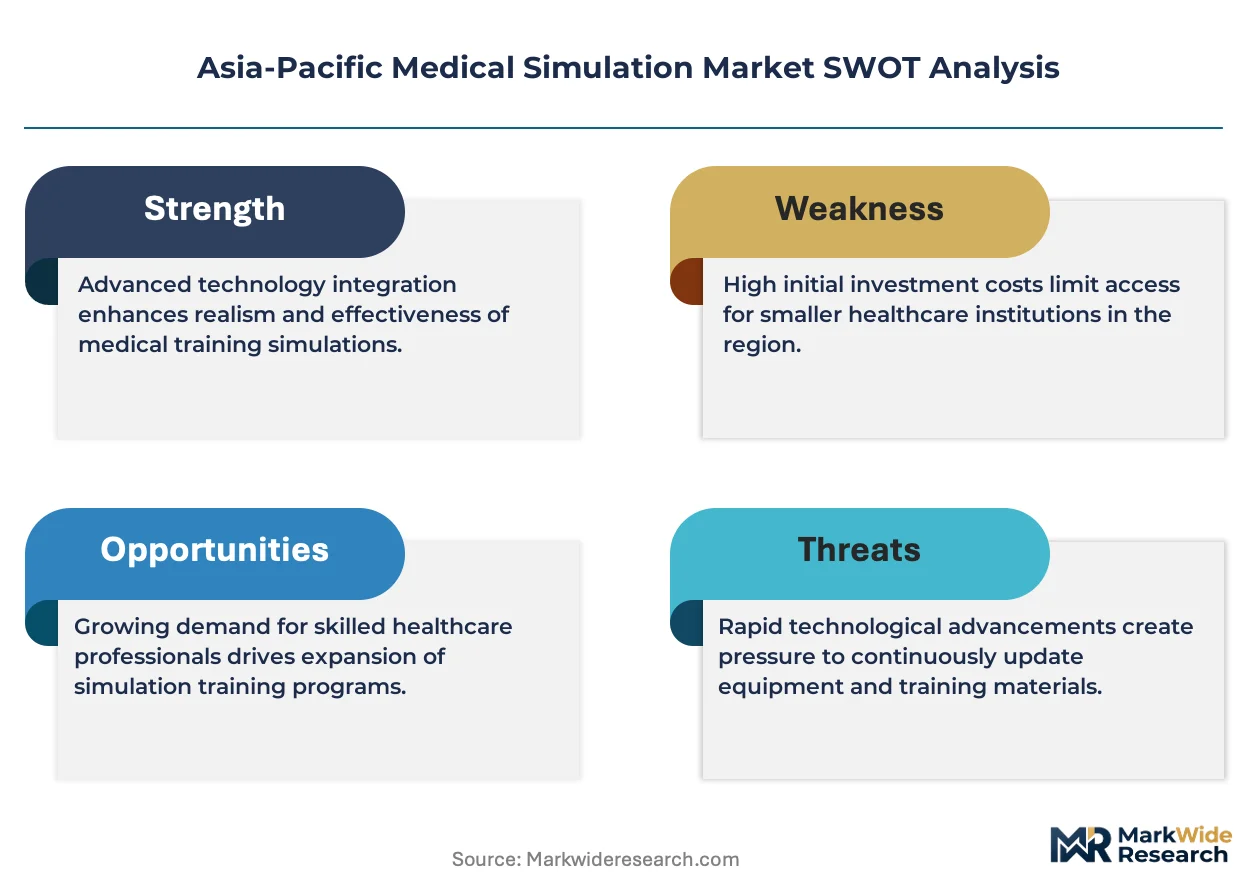
- Biomaterial input volatility:Silicone and polyurethane prices fluctuate with petrochemical feedstock costs. Japanese anatomical model manufacturers absorb margin compression when resin contracts reprice quarterly.
- Supply concentration in haptic actuators:Precision force-feedback components for surgical simulators concentrate among German and Japanese precision motor suppliers. Lead times extend to 14-16 weeks during capacity constraints.
- Technical limitation in physiological fidelity:Real-time cardiovascular modeling software struggles to replicate arrhythmia complexity at sub-50 millisecond latency. Cardiology training programs in Seoul and Tokyo downgrade scenario realism expectations.
Strategic Opportunities
- Indonesia's underpenetrated medical college network:State-funded universities in Surabaya and Medan lack simulation infrastructure. Government health workforce expansion programs create procurement windows for entry-level task trainers.
- Convergence of mixed reality and haptic gloves:Hand tracking and force feedback integration enables laparoscopic training without physical mannequin hardware. Australian surgical societies are piloting immersive credentialing pathways.
- MFDS equipment classification streamlining:South Korea's Ministry of Food and Drug Safety is consolidating clinical training device approval categories. Reduced regulatory friction accelerates market entry for VR-based platforms.
Industry Challenges
- Biomedical engineering talent scarcity:Simulation system integrators in Singapore and Sydney compete for software engineers with dual competencies in physiology modeling and real-time graphics rendering. Salaries inflate 18-22% annually.
- Legacy hospital IT integration friction:Metropolitan networks in Osaka and Melbourne operate on decade-old learning management systems. API compatibility gaps delay simulation data export for competency tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Simulation Market |
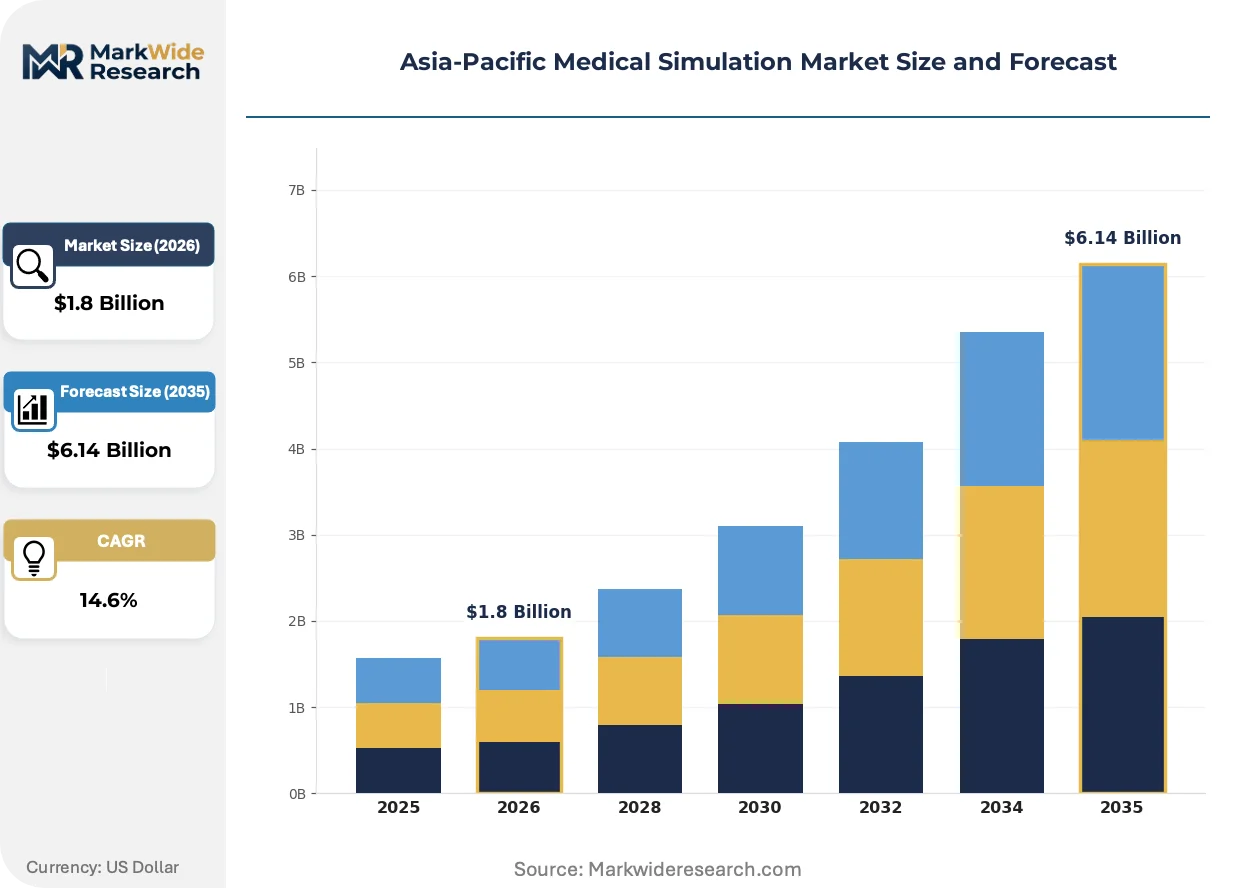
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Simulators, Task Trainers, Hybrid Simulators, Mannequins End User: Hospitals, Medical Schools, Training Centers, Defense Application: Clinical Skills Training, Surgical Training, Emergency Response, Team Training Technology: Software-based Solutions, Hardware Components, Mixed Reality, Interactive Platforms |
| Companies Covered | CAE Inc., Laerdal Medical, Kyoto Kagaku Co. Ltd, Limbs & Things Ltd, 3D Systems, ENF KOREA Co., Mentice AB, Simulab Corporation, Surgical Science Sweden AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Simulation Market Strategic Shifts
Mixed reality hardware cost declines are unlocking immersive surgical training at price points accessible to community medical colleges. Vendors are repositioning from capital equipment sellers to subscription platform operators.
Haptic glove systems with integrated force feedback are absorbing the tactile training functions previously requiring full mannequin setups. Australian defense medical units and civilian teaching hospitals are adopting these platforms for field surgical refresher programs. The technology is absorbing mid-tier procurement budgets that previously flowed to electro-mechanical patient simulators.
PMDA quality management standards in Japan now mandate simulation-based competency documentation for high-risk device recertification. Manufacturers must validate training efficacy claims through clinical outcome studies. Cardiology and interventional radiology departments in Tokyo and Kyoto are restructuring continuing education budgets to comply.
Hospital procurement committees across Southeast Asia are unbundling after-sales service contracts from initial hardware purchases. Malaysian and Indonesian buyers now negotiate software maintenance and scenario library updates as separate line items. This disintermediation compresses vendor margin capture while accelerating competitive switching between simulation platform providers.
Asia-Pacific Medical Simulation Market Segmentation
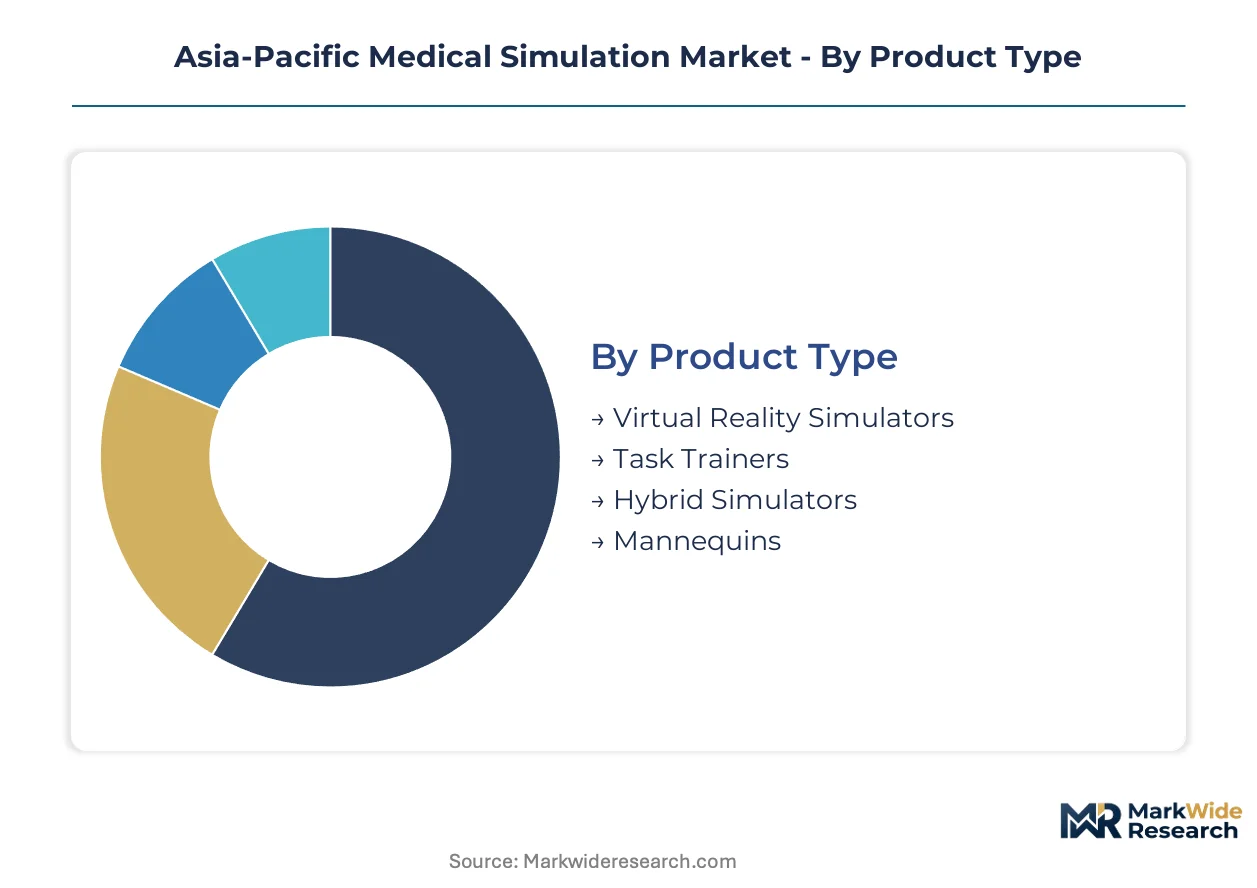
Capital allocation patterns across Asia-Pacific medical simulation diverge sharply by product complexity and regulatory certification burden. Procurement committees in Japanese metropolitan hospitals and Australian teaching networks weight lifecycle service costs against upfront hardware expenditure differently across segment tiers.
Product Type:
Electro-mechanical patient replicas demand the heaviest capital deployment, with pneumatic actuator arrays and biomaterial tissue analogs driving per-unit costs into six figures.
- Mannequins:High-fidelity patient simulators integrate pneumatic cardiovascular systems and programmable pharmacological response modules. Japanese medical schools in Tokyo and Osaka prioritize these for anesthesia and critical care credentialing where PMDA documentation requirements mandate traceable competency records.
- Virtual Reality Simulators:Computational physiology engines render immersive procedural environments without physical hardware constraints. South Korean interventional cardiology programs in Seoul teaching hospitals specify physics-engine platforms for endovascular training where MFDS equipment classifications now recognize software-based credentialing pathways.
- Task Trainers:Anatomical models for discrete procedural skills occupy mature procurement channels across Southeast Asian community colleges.
- Hybrid Simulators:Mixed reality overlays on physical mannequin cores blend haptic feedback with immersive visualization.
Most installed capacity flows through Mannequins. Expansion is steepest in Virtual Reality Simulators.
End User:
Procurement authority concentrates in institutions with mandatory continuing education budgets tied to licensure renewal.
- Hospitals:Metropolitan networks in Japan and Australia operate centralized simulation centers serving multiple clinical departments. TGA Australia's tightened medical device training requirements embed these systems into mandatory recertification workflows rather than discretionary capital cycles.
- Medical Schools:Accreditation mandates from Thailand's Nursing and Midwifery Council and Vietnam's Ministry of Health compel simulation hour minimums. Procurement volumes for mid-fidelity mannequins accelerate across Bangkok and Ho Chi Minh City campuses.
- Training Centers:Independent facilities serve practicing clinicians seeking procedural refreshment outside institutional frameworks.
- Defense:Australian defense medical units deploy portable haptic systems for field surgical refresher programs.
Revenue concentration sits with Hospitals. Medical Schools are climbing the fastest as accreditation deadlines approach.
Application:
Risk stratification in target procedures determines fidelity requirements and corresponding price tiers.
- Surgical Training:Laparoscopic and endovascular procedures demand sub-50 millisecond latency in haptic feedback systems. Australian surgical societies pilot immersive credentialing pathways using mixed reality platforms that bypass physical mannequin hardware entirely.
- Emergency Response:Trauma and mass casualty scenarios require team coordination protocols across multi-station simulation labs. Philippine emergency medicine residency programs in Manila expand procurement for disaster preparedness training.
- Clinical Skills Training:Venipuncture and airway management fundamentals utilize task trainers with compressed margin structures.
- Team Training:Communication and crisis resource management scenarios deploy across nursing and physician cohorts.
Installed base skews toward Clinical Skills Training. Surgical Training gains share fastest as procedural complexity escalates.
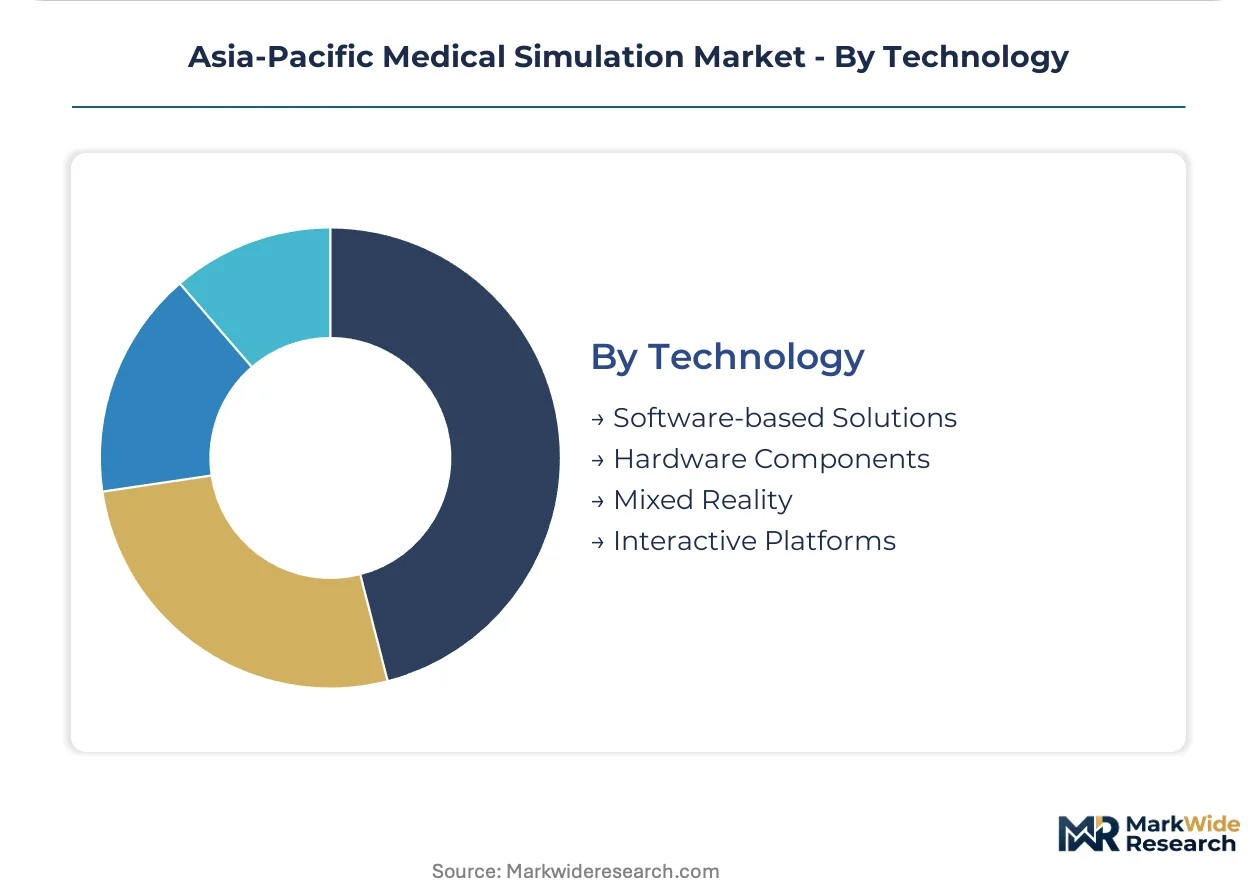
Technology:
Software licensing models are displacing capital-heavy hardware procurement across budget-constrained institutions.
- Software-based Solutions:Scenario libraries and physiological modeling engines generate recurring subscription revenue. Malaysian and Indonesian buyers now unbundle software maintenance from initial hardware purchases, negotiating scenario updates as separate line items.
- Mixed Reality:Head-mounted displays with hand tracking and force feedback integration enable laparoscopic training without physical mannequin infrastructure. Hardware cost declines unlock community medical college access previously blocked by capital constraints.
- Hardware Components:Precision force-feedback actuators and pneumatic systems concentrate supply among German and Japanese precision motor suppliers.
- Interactive Platforms:Web-based competency tracking interfaces bridge simulation sessions with learning management systems.
Deployment volume runs through Hardware Components. Mixed Reality shows the steepest expansion trajectory as price points compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for anatomical models while Indonesia remains chronically underpenetrated in simulation infrastructure. This divergence shapes vendor resource allocation across the region.
Japan
PMDA quality management standards mandate simulation-based competency documentation for high-risk device recertification. Tokyo and Kyoto medical schools prioritize high-fidelity patient simulators for anesthesia credentialing where traceable records are compulsory. Japanese metropolitan hospital networks concentrate procurement in centralized simulation centers serving multiple clinical departments.
Australia
TGA tightened medical device training requirements embed simulation systems into mandatory continuing education workflows. Australian defense medical units deploy portable haptic systems for field surgical refresher programs alongside civilian teaching hospitals. Melbourne and Sydney operate learning management systems that increasingly bridge simulation data with competency tracking.
South Korea
MFDS equipment classification streamlining accelerates market entry for VR-based training platforms. Seoul teaching hospitals specify physics-engine simulators for interventional cardiology credentialing protocols. The Busan-Ulsan corridor generates replacement software license demand from installed endovascular simulation capacity.
Thailand
Nursing and Midwifery Council accreditation mandates compel simulation hour minimums across Bangkok campuses. Government health workforce expansion programs create procurement windows for mid-fidelity mannequins. Thai medical schools accelerate capital deployment to meet 2026 accreditation deadlines.
Indonesia
State-funded universities in Surabaya and Medan lack basic simulation infrastructure despite rising enrollment. National health workforce expansion programs channel funding toward entry-level task trainers. Procurement committees negotiate unbundled software maintenance contracts separately from hardware purchases.
Asia-Pacific Medical Simulation Market Competitive Environment
Top-tier vendors anchor premium-priced anatomical specialization and proprietary physics engines, while mid-tier competitors compete on scenario library breadth and subscription pricing. The vendor base stratifies across three functional tiers: aviation-crossover infrastructure operators, anatomical model specialists, and software-native immersive platform builders. Dominant competitive moves include strategic partnerships with defense medical units and portfolio diversification into subscription-based scenario licensing.
Within the anatomical specialization tier, Kyoto Kagaku Co. Ltd exemplifies premium positioning through Japanese medical school procurement cycles. CAE Inc. represents aviation-crossover infrastructure leverage across Australian defense and civilian networks. Mentice AB occupies a position in physics-engine simulation for interventional cardiology protocols.
| Leading Market Players |
|---|
| CAE Inc. |
| Laerdal Medical |
| Kyoto Kagaku Co. Ltd |
| Limbs & Things Ltd |
| 3D Systems |
| ENF KOREA Co. |
| Mentice AB |
| Simulab Corporation |
| Surgical Science Sweden AB |
| Others |
Value Chain & Pricing Dynamics
Family-owned anatomical model specialists in Japan anchor premium pricing through PMDA-certified production lines while absorbing silicone resin volatility through quarterly contract repricing. Their ownership structure enables long-term supplier relationships with German precision motor manufacturers that transient private-equity-backed competitors cannot replicate, entrenching cost advantages across electro-mechanical patient simulator procurement cycles.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for software-based VR training platforms as MFDS streamlining accelerates competitive entry. Three-tier pricing structure across premium physics-engine systems, standard scenario libraries, and economy task trainers separates academic medical centers from community colleges from nursing institutes. Pricing pressure stems from Malaysian and Indonesian procurement committees unbundling after-sales service contracts into separately negotiated line items. Community medical colleges in Southeast Asia exhibit acute price sensitivity, while Japanese metropolitan hospital networks prioritize lifecycle service reliability over upfront capital expenditure.
Supply Chain Analysis
Freight cost escalation from German and Japanese precision motor suppliers extends lead times for haptic actuator arrays during capacity constraints. Component sourcing concentrates in Germany, Japan, and Taiwan for force-feedback systems, silicone biomaterial feedstocks, and mixed reality display panels. Raw material dependencies span petrochemical-derived polyurethane resins, rare-earth magnet assemblies, and optical-grade polymers. Single-source vulnerability concentrates in pneumatic cardiovascular system manufacturing. Distribution runs through hospital procurement committees, GPO contracts, and direct institutional sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific medical simulation market compounds steadily as regulatory mandates across Japan, Australia, and South Korea embed training systems into mandatory continuing education rather than discretionary capital cycles.
For Market Incumbents: Hedge against software-native platform disruption by deepening captive supply relationships with German precision motor suppliers and accelerating scenario library subscription transitions. Mixed reality hardware cost declines threaten electro-mechanical mannequin margins. Certification investment in PMDA and TGA documentation workflows preserves pricing power in high-fidelity segments. For New Entrants and Emerging Players: Launch via unbundled software maintenance contracts targeting Indonesian state-funded universities in Surabaya and Medan where simulation infrastructure remains chronically underdeveloped. Entry-level task trainers for nursing accreditation compliance represent the most penetrable segment. Direct institutional sales bypassing legacy distributor networks accelerates initial footprint. For Investors and Strategic Acquirers: Valuations sit cheapest among software-native immersive platform builders with physics-engine specialization and established hospital system relationships. Five-to-ten-year viability hinges on recurring revenue transition completion. Watch for MFDS and PMDA reimbursement linkages between simulation hours and clinical licensure renewal as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Scenario Library Subscription Transition | Recurring revenue embedding reduces capital expenditure friction for Thai nursing schools facing accreditation deadlines. |
| PMDA Certification Investment | Traceable competency documentation mandates in Tokyo and Kyoto validate premium pricing for anesthesia training systems. |
| Haptic Glove Platform Development | Force feedback integration enables Australian defense medical units to bypass physical mannequin hardware entirely. |
| Indonesian Distribution Partnership | State-funded university procurement windows in Surabaya channel entry-level task trainer volumes. |
| Mixed Reality Hardware Cost Reduction | Price point compression unlocks community medical college access previously blocked by capital constraints. |
Study Parameters
Coverage spans Japan, Australia, South Korea, Thailand, and Indonesia, with primary inputs from each market cluster obtained through interviews with hospital procurement committee members, biomedical engineering directors, nursing school accreditation officers, and simulation center operations managers. Secondary validation draws from PMDA quality management filings, TGA medical device training requirements, MFDS equipment classification updates, hospital procurement databases, and GPO contract repositories. Bottom-up installed base modeling triangulates against top-down healthcare education expenditure forecasts.
Granularity-level modeling operates at the intersection of product type, end-user institution, application procedure, and technology deployment mode across the projection horizon. Segmentation dimensions include fidelity tier, regulatory certification burden, and software-hardware revenue mix. CAGRs derive from logistic diffusion curves fitted to accreditation mandate implementation timelines and hardware cost decline trajectories. Physics-engine simulator adoption rates in Seoul teaching hospitals and mixed reality pilot program expansions in Australian surgical societies inform scenario weighting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biomaterial input volatility and haptic actuator supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Learning Analytics Market
Others
Space Cables Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Japan Smart Home Market
Others
Disposable Non Woven Sponge Market
Others
Folding Screen Mobile Phone Market
Others
Lightweight Compact Wheel Loader Market
Others
Video-As-A-Service (Vaas) Market
Others
Mobile Computer Cart Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Animal Feed Alternative Protein Market
Others
Asia-Pacific Military 4D Printing Market
Others
ASEAN Agricultural Logistics Market
Others
North America Wiring Duct Market
Others
North America Halal Food and Beverage Market
Others
GCC Cigarette Market