
 North America Adult Diaper Market | 2026-2036
North America Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adult Diaper Market Intelligence
EPA sustainable materials management priorities is expanding demand for biodegradable adult diaper formulations across North American procurement channels. Kimberly-Clark Corporation leverages its integrated pulp supply chain to sustain cost leadership in premium overnight segments. Essity AB anchors its position through specialized distribution partnerships with hospital systems. First Quality Enterprises Inc competes aggressively in the private-label institutional channel.
North America Adult Diaper refers to absorbent hygiene garments engineered with superabsorbent polymer cores, nonwoven topsheets, and breathable backsheet films designed for moderate-to-heavy urinary or fecal incontinence management in non-infant populations. Manufacturing employs hot-melt adhesive bonding and elastic leg-gather integration to achieve fluid retention capacities exceeding one liter while maintaining skin-contact dryness. Pull-up product types command the fastest volume trajectory as consumer preference shifts toward dignity-preserving designs resembling standard underwear. Overnight segments concentrate margin pools due to higher superabsorbent polymer loading and premium pricing tolerance among caregivers. Disposable form factors dominate hospital and long-term care procurement through infection-control protocols that prioritize single-use disposal.
FDA device classification for adult absorbent products shapes quality thresholds through biocompatibility testing requirements for skin-contact materials. EPA guidelines on sustainable materials management and state-level extended producer responsibility frameworks in California and New York are redirecting R&D investment toward compostable core alternatives. Health Canada and the Canadian Standards Association maintain parallel absorbent hygiene standards that facilitate cross-border manufacturing scale. Stakeholders must monitor evolving biodegradable performance certification standards and institutional procurement mandates that will determine which material platforms secure shelf space and contract eligibility.
Market Dynamics
EPA sustainable materials management priorities are redirecting capital toward compostable absorbent core R&D, forcing manufacturers to requalify supply chains while Florida and Georgia retiree migration sustains volume concentration in the U.S. Southeast.
Growth Catalysts
- State-level extended producer responsibility:California and New York frameworks mandate biodegradable content minimums, accelerating institutional procurement of certified compostable products by long-term care facilities.
- Pull-up product engineering:Dignity-preserving designs resembling standard underwear are displacing tape-tab configurations in home care settings, expanding addressable user populations beyond bedbound patients.
- Retiree migration corridors:Interstate relocation of aging populations to Florida and Georgia sustains concentrated demand clusters that justify dedicated distribution infrastructure and localized manufacturing footprints.
Market Restraints
- Superabsorbent polymer supply concentration:Petrochemical-derived SAP feedstock pricing tracks crude oil volatility, compressing margin stability for manufacturers lacking backward integration into acrylic acid production.
- Compostable performance gaps:Biodegradable alternatives currently achieve 15-20% lower fluid retention capacity versus conventional polymer cores, limiting clinical acceptance in heavy incontinence segments.
- FDA biocompatibility testing timelines:Skin-contact material qualification protocols extend new product introduction cycles by 18-24 months, delaying revenue realization for reformulated sustainable lines.
Strategic Opportunities
- Underpenetrated Canadian home care:Provincial reimbursement gaps have suppressed retail channel development relative to U.S. benchmarks, creating first-mover advantage for private-label entrants with direct-to-consumer logistics.
- Hospital sustainability mandates:Health system decarbonization commitments are elevating compostable products to preferred vendor status in group purchasing organization negotiations.
- Overnight segment premiumization:Higher SAP loading requirements and caregiver willingness to pay for sleep protection create margin expansion potential distinct from commoditized day-use categories.
Industry Challenges
- Hot-melt adhesive requalification:Transitioning to bio-based bonding agents requires recalibration of elastic leg-gather integration equipment, disrupting continuous production lines.
- Cross-border standard misalignment:Health Canada and FDA diverge on skin-sensitization testing protocols, forcing dual-track validation that duplicates R&D expenditure for North American manufacturers.
- Composting infrastructure gaps:Municipal facilities capable of processing certified biodegradable diapers remain concentrated in Pacific Coast and Northeast corridors, limiting geographic rollout of sustainable product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adult Diaper Market |
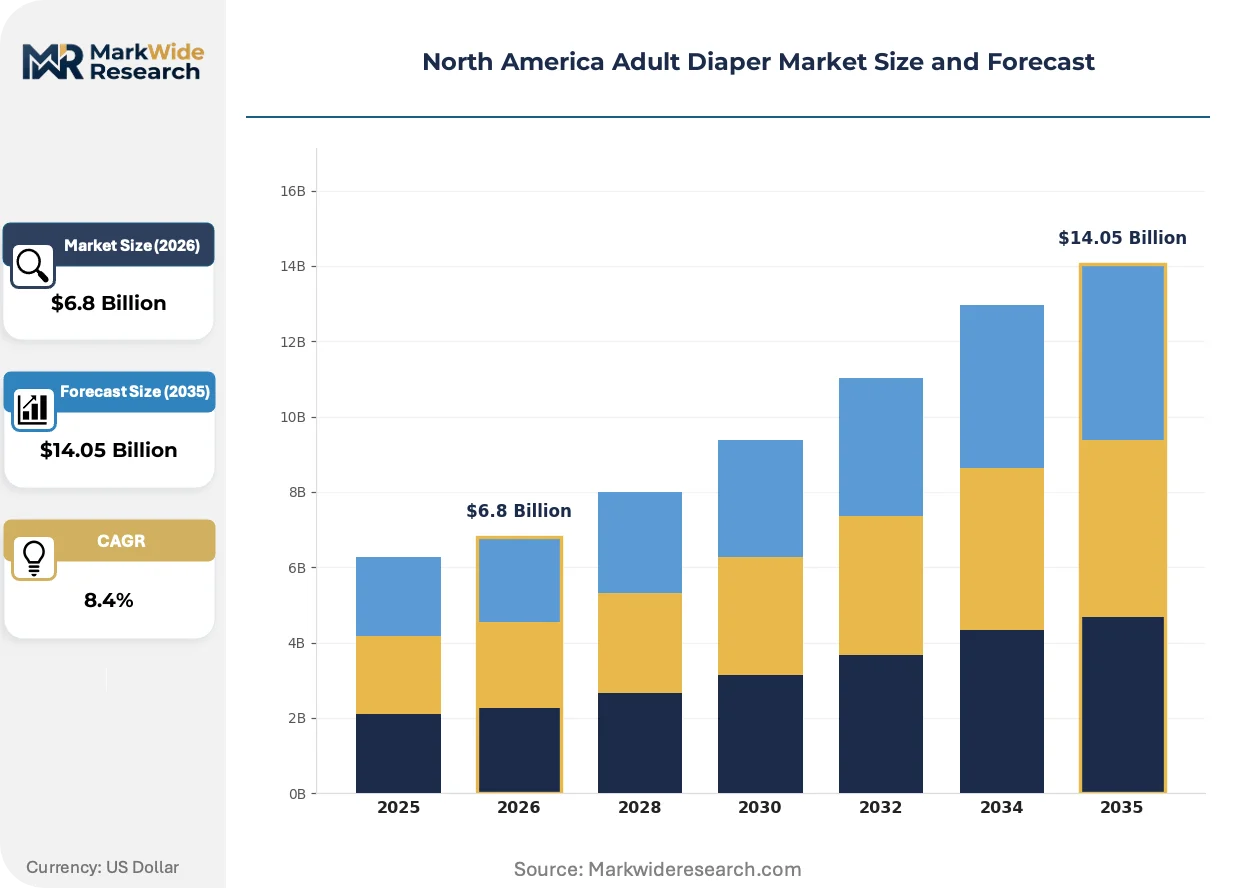
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Premium, Overnight, Pull-up End User: Institutions, Caregivers, Hospitals, Individuals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales Form: Disposable, Reusable, Biodegradable, Cloth |
| Companies Covered | Kimberly-Clark Corporation, Essity AB, Ontex BV, First Quality Enterprises Inc, Drylock Technologies NV, Nippon Paper Industries Co Ltd, Health Care Products Inc, Principal Business Enterprises Inc, Domtar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adult Diaper Market Strategic Shifts & Innovations
Material science advances and procurement policy evolution are converging to redefine product specifications and channel economics across the North American absorbent hygiene landscape.
Cellulose-based fluff pulp alternatives derived from agricultural residues are integrating into core laminates as manufacturers seek to reduce petrochemical dependency without sacrificing wicking performance. Long-term care procurement directors in Texas and Arizona are piloting these formulations for day-use applications where fluid load requirements are moderate. The technology is integrating sustainability credentials into institutional contract bidding processes, reshaping vendor scorecard weightings toward environmental metrics.
EPA guidelines on sustainable materials management are mandating lifecycle assessment disclosures for products entering federal supply schedules, compelling manufacturers to document cradle-to-grave environmental impacts. Industrial consequence includes accelerated investment in third-party compostable certification and supply chain traceability systems. Hospital systems in the U.S. Midwest are responding by inserting sustainability clauses into request-for-proposal documents, effectively screening out suppliers lacking biodegradable SKUs.
Caregiver purchasing behavior is fragmenting across channel types as dignity concerns drive pull-up preference among community-dwelling seniors while institutional protocols maintain tape-tab dominance for bedbound populations. Retail pharmacies and medical supply distributors are repositioning shelf space to accommodate dual-format merchandising. This bifurcation is most pronounced in Florida retirement communities where independent living facilities operate on hybrid procurement models blending institutional volume discounts with individual resident choice allowances.
North America Adult Diaper Market Segmentation
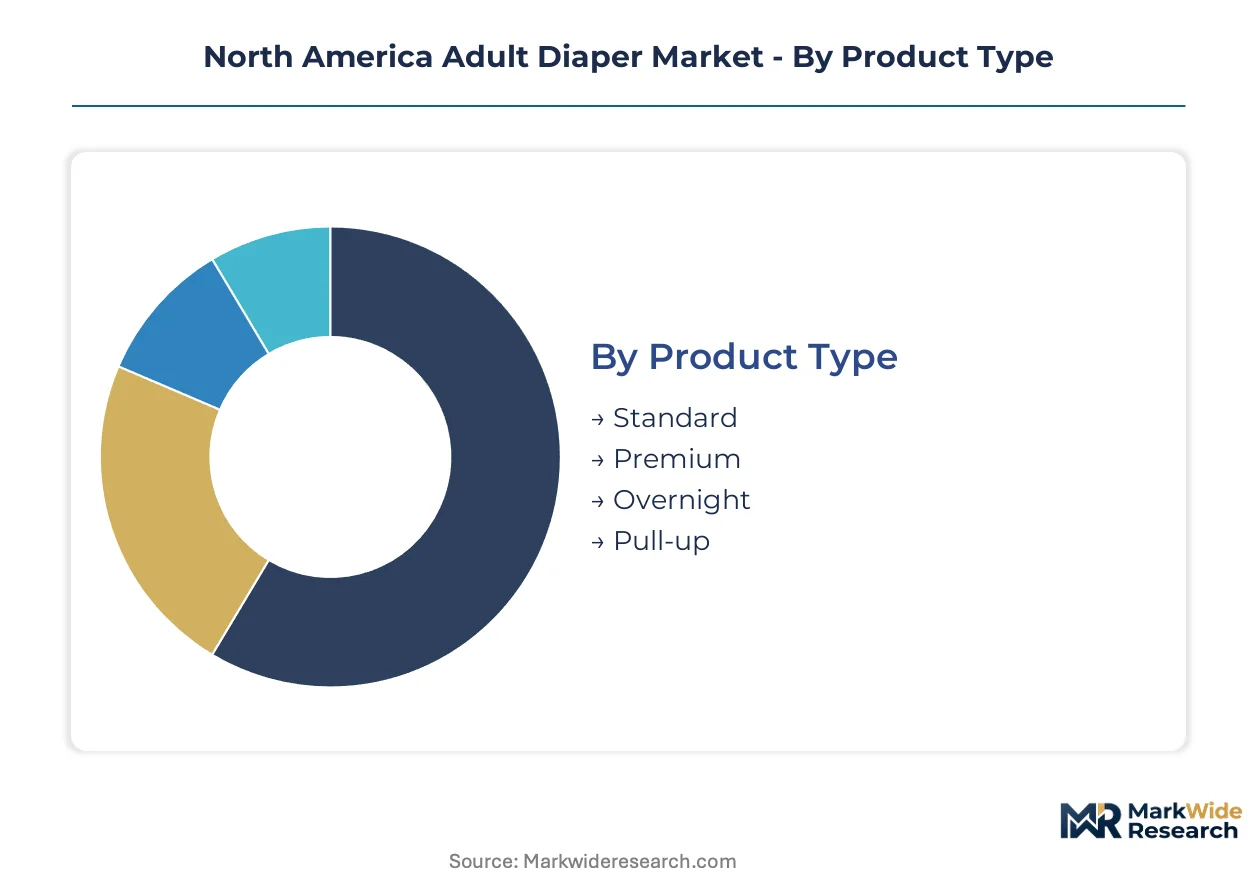
Segmentation in the North America adult diaper market reflects divergent buyer priorities across clinical protocols, dignity preferences, and sustainability mandates. Procurement directors, family caregivers, and individual consumers each weight performance, cost, and environmental credentials differently, fragmenting demand into distinct product specifications and channel pathways.
Product Type:
Cost tier separates buyers seeking basic protection from those prioritizing extended wear performance or lifestyle integration.
- Standard:Moderate absorbency cores with standard SAP loading target budget-conscious institutional procurement in long-term care facilities. Demand concentrates in Texas and Arizona day-use applications where fluid loads remain moderate and cost-per-change drives purchasing decisions.
- Premium:Enhanced breathable backsheet films and aloe-infused topsheets command price tolerance among family caregivers seeking skin health outcomes for homebound seniors. Florida retirement communities sustain concentrated demand clusters for this tier.
- Overnight:Maximum SAP density configurations deliver extended protection during sleep cycles.
- Pull-up:Elastic waistband construction mimics standard underwear aesthetics to preserve user dignity.
Standard leads volumes today; Pull-up is gaining share fastest.
End User:
Application environment dictates infection-control protocols, bulk procurement scale, and individual choice latitude.
- Institutions:Long-term care facilities operate on volume contracts with standardized tape-tab specifications and disposal mandates. Procurement in Florida and Georgia retirement corridors sustains dedicated distribution infrastructure serving multi-facility operators.
- Caregivers:Family members purchasing for homebound relatives prioritize odor control and ease of application over unit cost. Retail pharmacy channels in U.S. Southeast suburban markets capture this segment through consultative counter service.
- Hospitals:Acute care settings require FDA-compliant biocompatibility documentation and single-use disposal protocols.
- Individuals:Self-purchasing seniors in independent living arrangements exercise brand preference and sustainability criteria.
Institutions dominate contract value; Caregivers are expanding most quickly.
Distribution Channel:
Volume scale and customer service intensity differentiate pathways from bulk institutional delivery to discreet home shipment.
- Online Retail:Subscription models and discreet packaging address dignity concerns among self-purchasing community-dwelling seniors. Direct-to-consumer logistics are penetrating underdeveloped Canadian provincial markets where retail infrastructure lags U.S. benchmarks.
- Supermarkets:Mass merchandisers compete on private-label price positioning for standard-tier day-use products. Shelf space allocation in Florida and Georgia retail chains reflects retiree demographic density.
- Pharmacies:Licensed medical supply counters provide product consultation and insurance documentation support.
- Direct Sales:Manufacturer representatives serve hospital systems and long-term care chains with contract negotiation and clinical education.
Supermarkets lead volumes today; Online Retail is climbing the fastest.
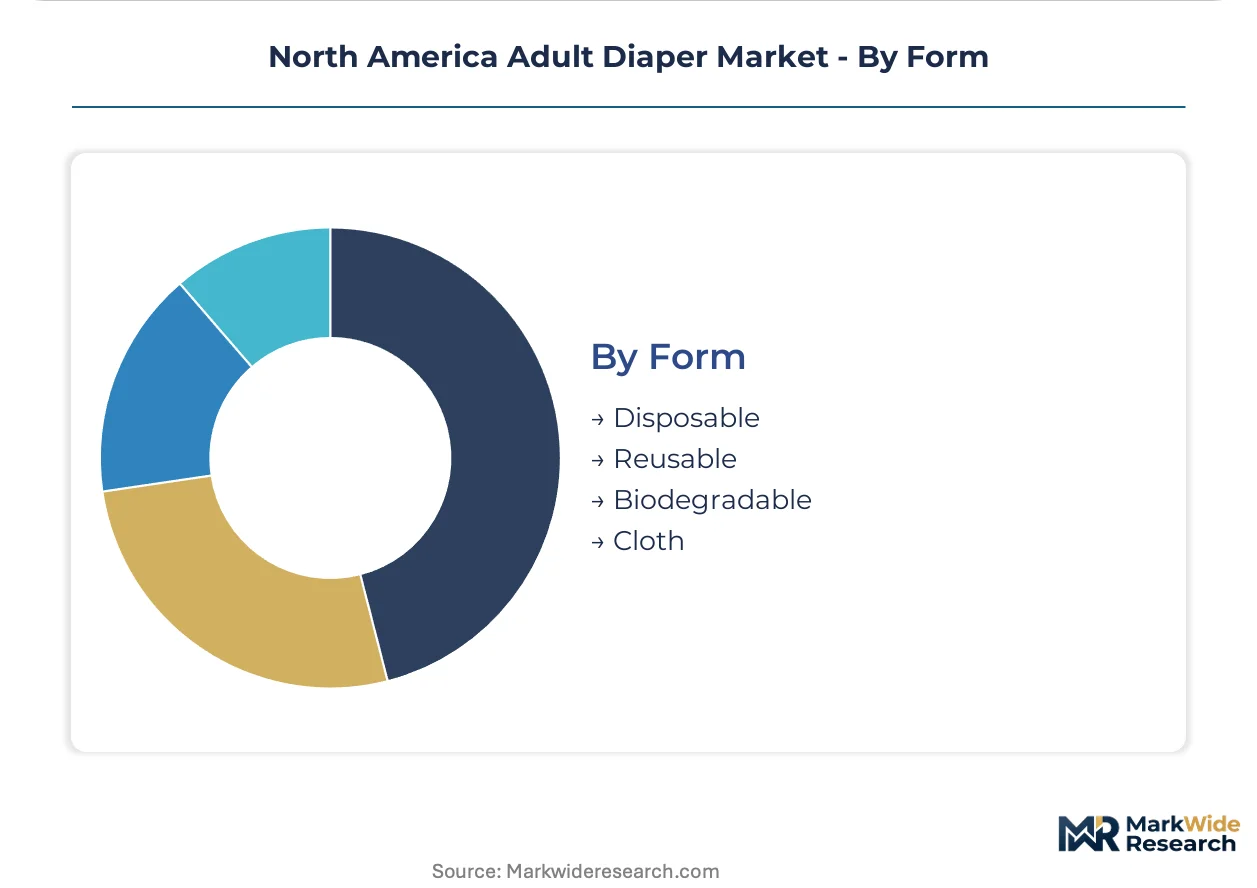
Form:
Material end-of-life pathway and reuse potential separate regulatory-compliant disposable formats from emerging sustainable alternatives.
- Disposable:Petrochemical-derived SAP cores with polypropylene backsheet films dominate hospital and long-term care procurement through infection-control protocols. EPA sustainable materials management priorities are beginning to challenge this hegemony in federal supply schedules.
- Biodegradable:Compostable absorbent cores from agricultural residue feedstocks achieve certification for municipal processing facilities. California and New York extended producer responsibility frameworks are accelerating institutional pilot programs despite 15-20% fluid retention performance gaps versus conventional polymers.
- Reusable:Washable cloth constructions with snap or hook-and-loop closures serve environmentally motivated home care settings.
- Cloth:Traditional woven cotton designs persist in niche home-laundering applications with minimal SAP integration.
Disposable leads volumes today; Biodegradable is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aging care workforce concentrations in the U.S. Southeast and Canadian urban corridors anchor regional demand patterns. Retiree migration streams and institutional procurement networks concentrate volume leadership in specific sub-regional clusters.
United States
Florida and Georgia retirement corridors sustain the densest demand clusters through interstate elderly migration. EPA sustainable materials management priorities redirect federal procurement toward biodegradable formulations in California and New York pilot programs. Texas and Arizona long-term care facilities drive day-use volume through cost-conscious institutional contracting.
Canada
Provincial reimbursement gaps suppress retail channel development relative to U.S. benchmarks, creating whitespace for direct-to-consumer logistics entrants. Health Canada and Canadian Standards Association standards facilitate cross-border manufacturing scale with U.S. producers. Ontario and Quebec urban centers concentrate aging populations where home care infrastructure lags institutional capacity.
Mexico
Border state maquiladora operations supply absorbent hygiene components to U.S. assembly plants through integrated North American production networks. Mexican federal health programs expand institutional procurement eligibility for adult incontinence products in public hospital systems. Guadalajara and Monterrey industrial corridors host converting operations serving both domestic and export demand.
North America Adult Diaper Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered market positions. Integrated pulp and polymer suppliers sustain cost leadership in high-volume institutional channels through captive raw material access. Strategic archetypes separate into three camps: multinational hygiene conglomerates with backward integration, regional specialists with clinical distribution partnerships, and private-label converters with flexible manufacturing footprints. Dominant competitive moves include compostable core R&D investment and dedicated distribution infrastructure deployment in retiree migration corridors.
Among U.S.-based hygiene conglomerates, Kimberly-Clark Corporation and First Quality Enterprises Inc occupy positions at opposite ends of the integration spectrum. Essity AB anchors the European-origin multinational tier through specialized hospital system relationships. These three exemplify how geographic origin and corporate structure shape competitive positioning without predetermining segment focus or technology adoption timelines.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Essity AB |
| Ontex BV |
| First Quality Enterprises Inc |
| Drylock Technologies NV |
| Nippon Paper Industries Co Ltd |
| Health Care Products Inc |
| Principal Business Enterprises Inc |
| Domtar Corporation |
| Others |
Cost & Logistics Intelligence
Compostable absorbent core R&D requalification is simultaneously elevating capital intensity for sustainable lines and fragmenting supplier power away from petrochemical-integrated incumbents. California and New York extended producer responsibility mandates force dual-track material sourcing, bifurcating procurement economics between conventional SAP and agricultural-residue alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by absorbency performance and skin-contact certification grade. Price differentiation hinges on FDA biocompatibility tier and volume scale in institutional contracting, with overnight configurations commanding widest spreads due to superabsorbent polymer loading variance. Cost compression in standard-tier day-use products is intensifying because Florida and Georgia long-term care facilities consolidate purchasing through multi-facility operators. Family caregivers in retail pharmacy channels show least price sensitivity, prioritizing odor control and ease of application over unit economics.
Supply Chain Analysis
Regional distribution centers in Atlanta, Dallas, and Toronto anchor hub-and-spoke patterns serving retiree migration corridors and Canadian provincial markets. Manufacturing concentration in the United States, Canada, and Mexico draws from integrated North American production networks with maquiladora component supply. Raw material dependencies rest on petrochemical-derived superabsorbent polymer, fluff pulp from southeastern U.S. mills, and elastic nonwovens. Single-source vulnerability in acrylic acid feedstock creates margin instability for manufacturers lacking captive supply. Distribution runs through direct sales teams for hospital systems, medical supply distributors for institutional chains, and subscription logistics for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable certification cost differentials between California's stringent frameworks and Texas's lighter mandates create geographic-arbitrage opportunities for dual-sourcing strategies. Regulatory divergence across state lines rewards flexible manufacturing footprints.
For Market Incumbents: Anticipate compostable core performance gaps narrowing through agricultural-residue fiber engineering, threatening conventional SAP cost advantages. Defensive moves require backward integration into fluff pulp supply and dedicated distribution infrastructure deployment in Florida retirement corridors. Channel control through hospital system GPO relationships provides insulation against private-label encroachment. For New Entrants and Emerging Players: The mid-tier price-point gap between premium overnight configurations and economy day-use products offers entry space for hybrid sustainability-performance positioning. Underpenetrated Canadian provincial home care markets present the most penetrable geography, with direct-to-consumer subscription logistics bypassing reimbursement-constrained retail infrastructure. Go-to-market execution should target consultative pharmacy counter relationships in U.S. Southeast suburban clusters. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with clinical distribution partnerships but limited backward integration. Long-term viability over the next decade hinges on compostable certification portfolios securing institutional contract eligibility. Acquisition targets should demonstrate Health Canada-FDA dual-track validation capabilities. The signal to watch is municipal composting infrastructure buildout velocity in Midwest and Southeast corridors, which determines addressable market expansion for biodegradable SKUs.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Core R&D Investment | EPA sustainable materials management priorities elevate certified products to preferred vendor status in federal supply schedules. |
| Backward Integration into Fluff Pulp | Captive pulp supply insulates margin stability against petrochemical-SAP price volatility in standard-tier segments. |
| Direct-to-Consumer Subscription Launch | Discreet packaging and auto-replenishment address dignity concerns among self-purchasing community-dwelling seniors. |
| Hospital System GPO Partnership | Clinical education and contract negotiation secure volume commitments through infection-control protocol alignment. |
| Florida Distribution Infrastructure Deployment | Retiree migration corridors justify dedicated warehousing and localized manufacturing footprints for volume concentration. |
Research Approach
Bottom-up long-term care and home-use modeling reconciled against top-down absorbent hygiene manufacturing tracking forms the analytical core. Primary interviews with procurement directors at multi-facility operators, GPO contracts managers, retail pharmacy category buyers, and biomedical engineers at hospital systems combine with secondary validation from FDA 510(k) filings, EPA sustainable materials management disclosures, Health Canada device licenses, and Nielsen retail audit data. Triangulation across stakeholder perspectives and documentary sources ensures segment-level precision.
Historical trendline analysis of institutional contract volumes and retail channel sell-through patterns establishes baseline trajectory assumptions. The projection framework models demand across product type, end-user environment, distribution channel, and material form dimensions. CAGRs derive from regression analysis of demographic migration patterns, reimbursement policy evolution, and compostable certification adoption curves. Industry-specific inputs include Florida Department of Elder Affairs utilization data and Canadian provincial home care expenditure reports.
Caveats apply where superabsorbent polymer feedstock price shocks, municipal composting infrastructure delays, or FDA biocompatibility timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions around retiree migration velocity and state-level extended producer responsibility implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market