
 Baby Gate Market | 2026-2036
Baby Gate Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Gate Market Analysis
Asset-light leasing models for juvenile safety equipment is narrowing the capital barrier for new entrants in the baby gate space. Summer Infant leverages its brand strength across mass retail channels to sustain shelf presence. Evenflo anchors its competitive stance through vertical integration into domestic distribution networks. Regalo differentiates by specializing in value-tier hardware-mounted systems for multi-child households.
A baby gate is a physical barrier device, typically constructed from wood, metal, or plastic, engineered to restrict infant and toddler access to hazardous areas such as stairwells, kitchens, and doorways; its primary commercial purpose is to reduce household injury incidence among children aged six months to three years. Hardware-mounted gates dominate margin pools due to their permanent installation and higher perceived safety, while pressure-mounted variants lead volume in rental and temporary-use scenarios. The material dimension shows metal frames capturing preference among safety-conscious buyers, whereas plastic and fabric segments compete on portability and price accessibility.
The United States Consumer Product Safety Commission sets mandatory structural and latching standards that all domestic sellers must satisfy, while ASTM International publishes voluntary juvenile product specifications that major retailers require for shelf placement. The European Union's CE marking and General Product Safety Directive govern market access for imported gates across member states. Stakeholders must monitor evolving third-party testing requirements and certification timelines as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
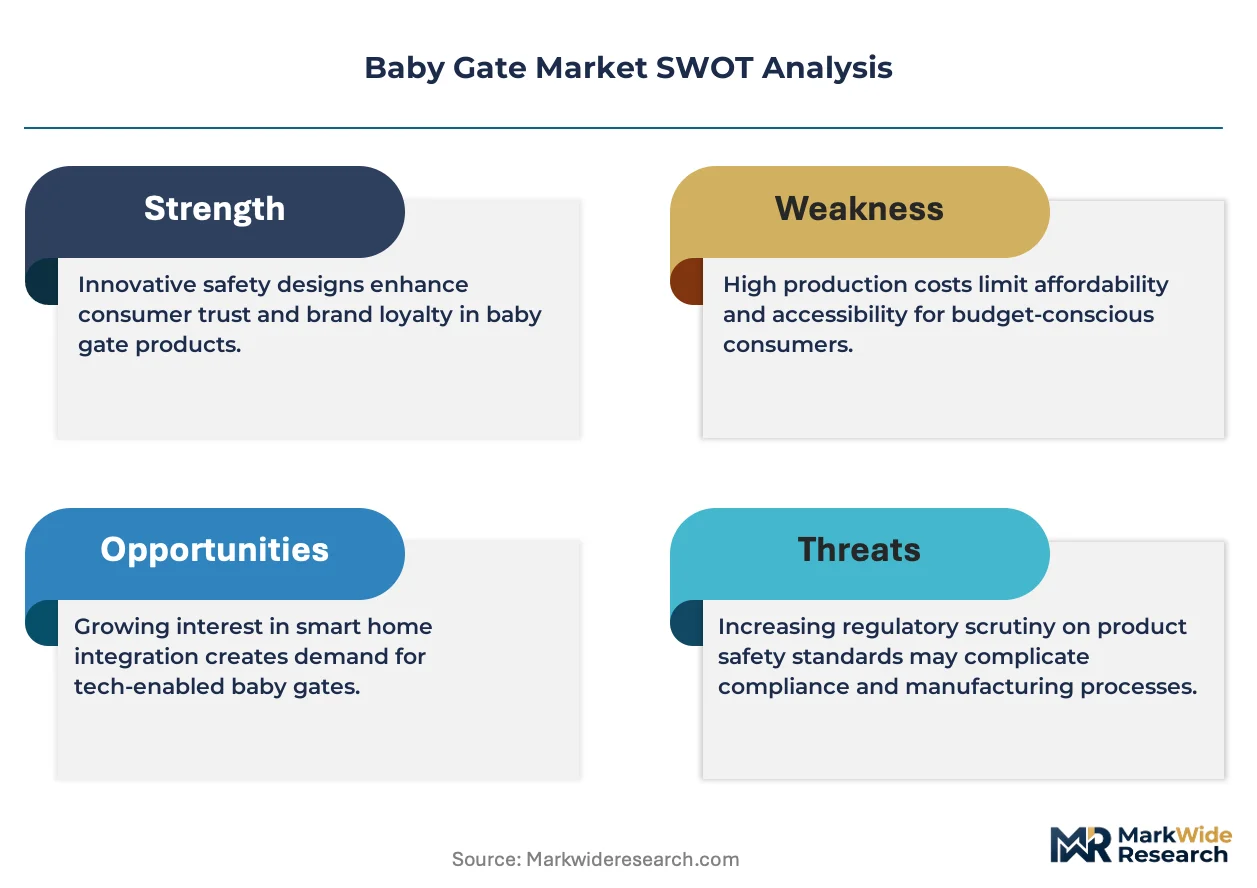
The baby gate market is experiencing structural compression as ASTM juvenile product safety standards tighten latching and structural requirements, forcing manufacturers to redesign hardware-mounted systems while pressure-mounted alternatives face margin erosion from rental substitution.
Growth Catalysts
- Hardware-mounted safety preference:Multi-child households in the United States are prioritizing permanent installation systems that exceed CPSC minimum thresholds, creating durable demand for metal-framed configurations.
- ASTM F1004 compliance mandates:Major retailers now require voluntary juvenile product specifications for shelf placement, elevating certified suppliers and marginalizing uncertified imports.
- Asset-light leasing proliferation:Equipment rental platforms serving temporary-use scenarios are expanding gate accessibility for visiting grandparents and short-term childcare arrangements.
Market Restraints
- Steel and aluminum input volatility:Metal frame manufacturers face margin pressure from commodity price swings that pressure-mounted plastic competitors largely avoid.
- Chinese manufacturing concentration:Domestic United States sellers depend on concentrated Asian supply bases for component fabrication, exposing inventory timelines to transpacific logistics friction.
- Product lifespan extension:Durable hardware-mounted installations reduce replacement frequency compared to consumable childcare categories, compressing addressable volume.
Strategic Opportunities
- Smart home integration convergence:Sensor-enabled gates combining physical barriers with IoT connectivity are capturing interest from tech-forward millennial parents in California and Texas metropolitan corridors.
- Secondary market channel development:Certified pre-owned gate marketplaces addressing sustainability-conscious buyers are emerging as a viable parallel revenue stream.
- EU CE marking pathway expansion:United States manufacturers with existing ASTM certification infrastructure can leverage testing overlap to access German and French retail channels with modest incremental compliance investment.
Industry Challenges
- Third-party testing backlog congestion:CPSC-recognized laboratory capacity constraints are extending certification timelines for new product introductions.
- Cross-jurisdictional standard divergence:United States ASTM specifications, EU General Product Safety Directive requirements, and emerging state-level chemical disclosure mandates create fragmented compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Gate Market |
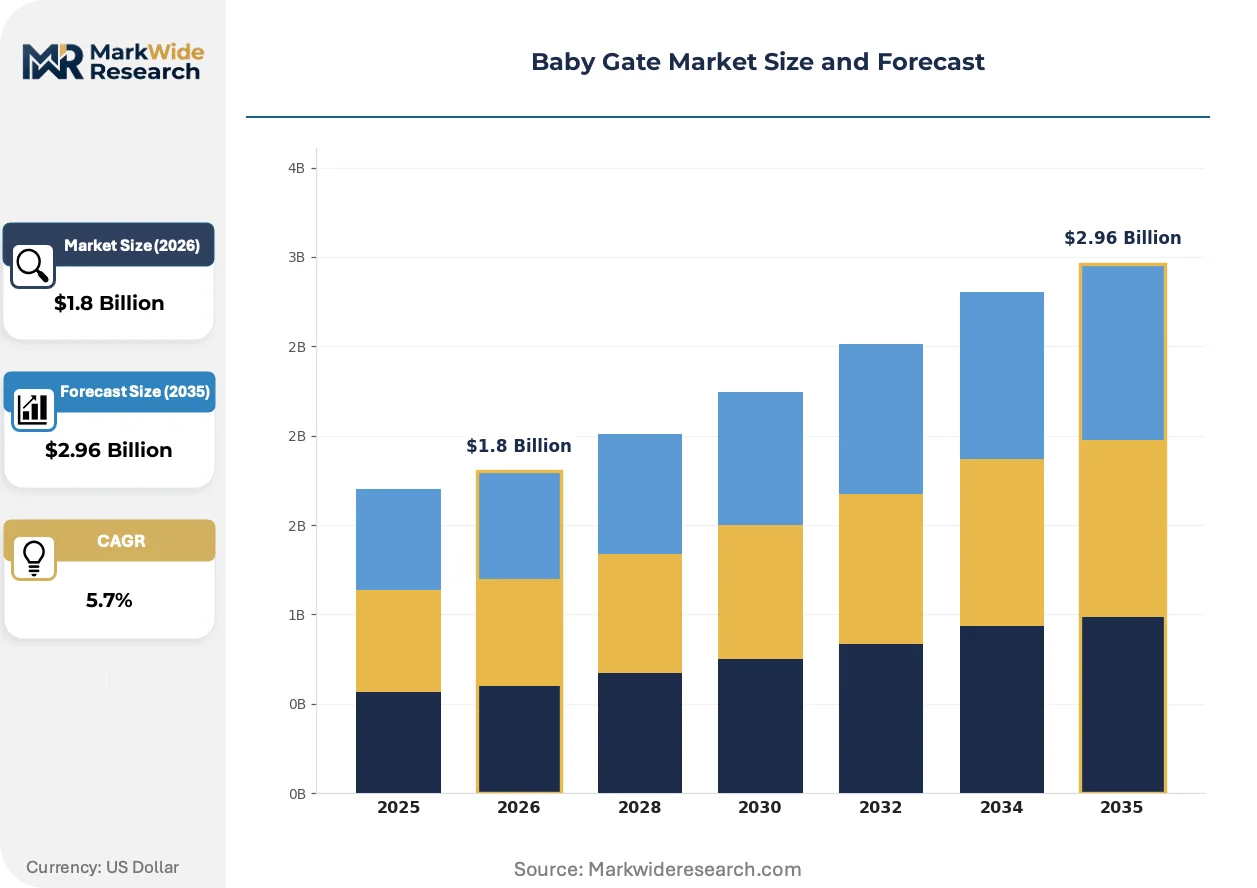
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Mounted, Hardware-Mounted, Sliding, Folding Material: Wood, Metal, Plastic, Fabric End User: Households, Daycares, Clinics, Hotels Installation Type: Permanent, Temporary, Removable, Adjustable |
| Companies Covered | Summer Infant, Evenflo, Babelio, Cumbor, Safety 1st, Regalo, Cardinal Gates, KidCo, North States, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Gate Market Emerging Trajectories
Product development trajectories in the baby gate space center on material substitution, regulatory anticipation, and channel restructuring that together redefine how safety equipment reaches end-users.
Metal alloy construction is migrating from traditional steel tubing toward aluminum-magnesium blends that reduce unit weight without sacrificing structural integrity under ASTM F1004 load testing. Safety-conscious buyers in higher-income brackets are absorbing modest price premiums for these configurations. The shift is compressing demand for legacy steel frames while elevating supplier technical capabilities.
REACH substance restrictions in the European Union are forcing reformulation of plastic components and surface coatings across exported product lines. Manufacturers serving dual United States-EU markets are consolidating SKUs around compliant material sets. The United States market is experiencing downstream effects as domestic sellers preemptively adopt EU-grade chemical standards to simplify supply chain management.
Subscription-based equipment rotation is displacing outright purchase for pressure-mounted categories among urban renters and dual-income households. Retail partnerships with logistics platforms are enabling turnkey installation and retrieval services. This pattern concentrates in dense metropolitan areas where space constraints and mobility frequency reduce appetite for permanent hardware modifications.
Baby Gate Market Segmentation
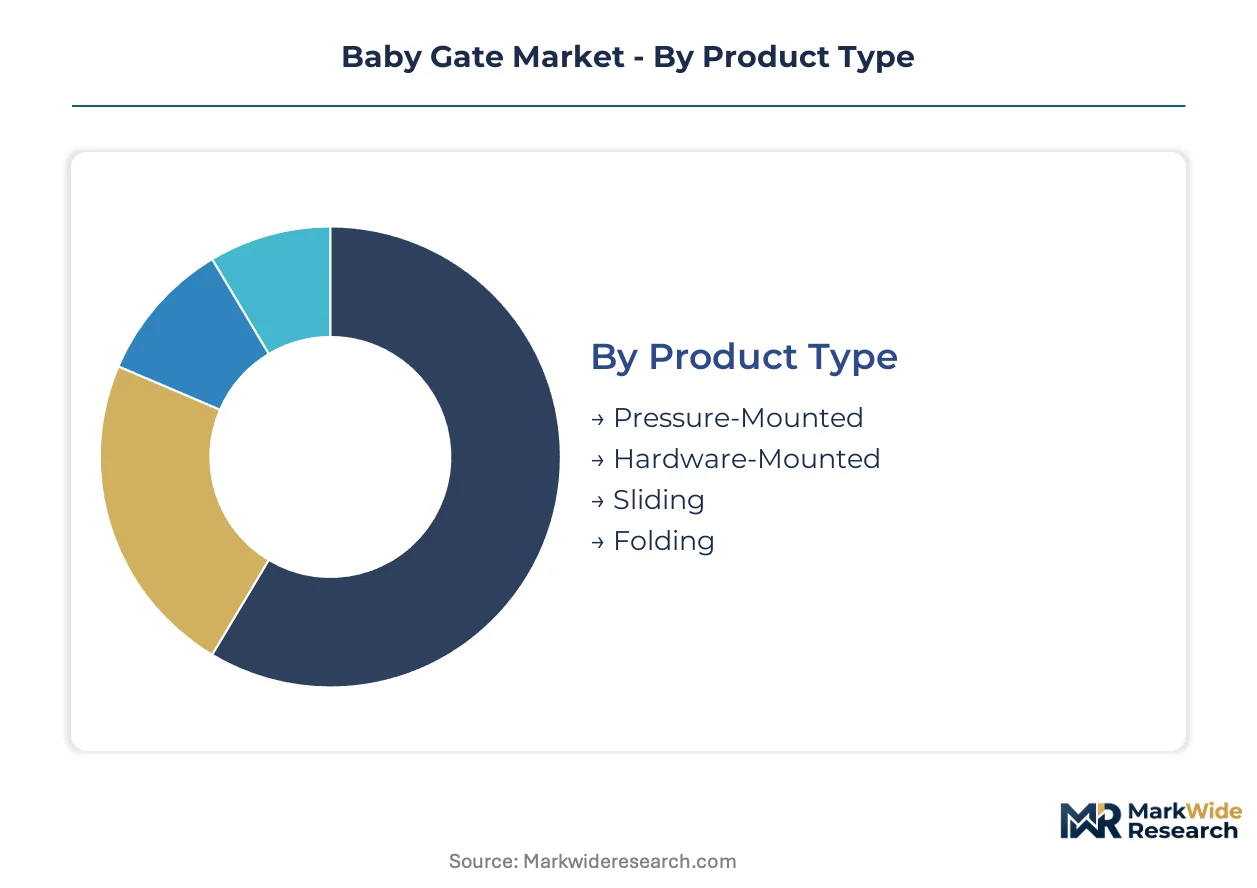
Segmentation in the baby gate market reveals distinct service and replacement cycles across product configurations. Material choices and installation permanence directly shape warranty exposure and customer lifetime value for manufacturers.
Product Type:
After-sales-service intensity varies sharply across mounting mechanisms, with hardware-mounted systems demanding professional installation support while pressure-mounted alternatives rely on self-service troubleshooting.
- Pressure-Mounted:Spring-tension mechanisms wedge between doorframes without tools, enabling rapid deployment. Demand concentrates among urban renters in dense metropolitan areas where lease restrictions prohibit wall modifications, driven by mobility frequency and temporary childcare arrangements.
- Hardware-Mounted:Screw-fixed brackets anchor into structural framing for permanent stairway protection. Multi-child households in suburban United States markets prioritize these configurations for top-of-stair applications where CPSC thresholds mandate structural redundancy.
- Sliding:Retractable mesh barriers roll into discrete housings for space-constrained environments.
- Folding:Accordion-style panels collapse for storage and transport, serving grandparents and traveling caregivers.
Hardware-Mounted holds the largest share; momentum sits with Pressure-Mounted as rental substitution accelerates.
Material:
Cost tier stratification separates premium metal configurations from mass-market alternatives, with raw material volatility compressing margins unevenly across the spectrum.
- Metal:Steel and aluminum-magnesium alloys deliver ASTM F1004 load-bearing performance for high-traffic installations. Safety-conscious buyers in higher-income brackets absorb price premiums for these configurations, particularly for hardware-mounted stairway applications.
- Wood:Aesthetic integration with residential interiors drives preference among design-focused homeowners. Solid hardwood frames command premium positioning in specialty retail channels serving renovation-driven households.
- Plastic:Injection-molded polypropylene dominates pressure-mounted volume through cost accessibility and color variety.
- Fabric:Lightweight mesh and woven textiles enable portable and retractable form factors for travel scenarios.
Metal captures the premium tier; plastic commands the volume base with steepest expansion trajectory in rental channels.
End User:
Application context determines compliance burden and purchase authority, with institutional buyers imposing certification requirements that exceed residential standards.
- Households:Individual consumers drive baseline demand through retail and direct channels, with purchasing decisions influenced by pediatrician recommendations and parenting community endorsements.
- Daycares:Licensed childcare facilities face state-mandated safety inspections that require documented ASTM compliance and maintenance logs.
- Clinics:Pediatric and family practice waiting areas deploy gates for liability mitigation during patient flow.
- Hotels:Hospitality procurement teams specify commercial-grade durability for guest room and common area installations.
Households dominate absolute volume; Daycares present the most demanding specification environment.
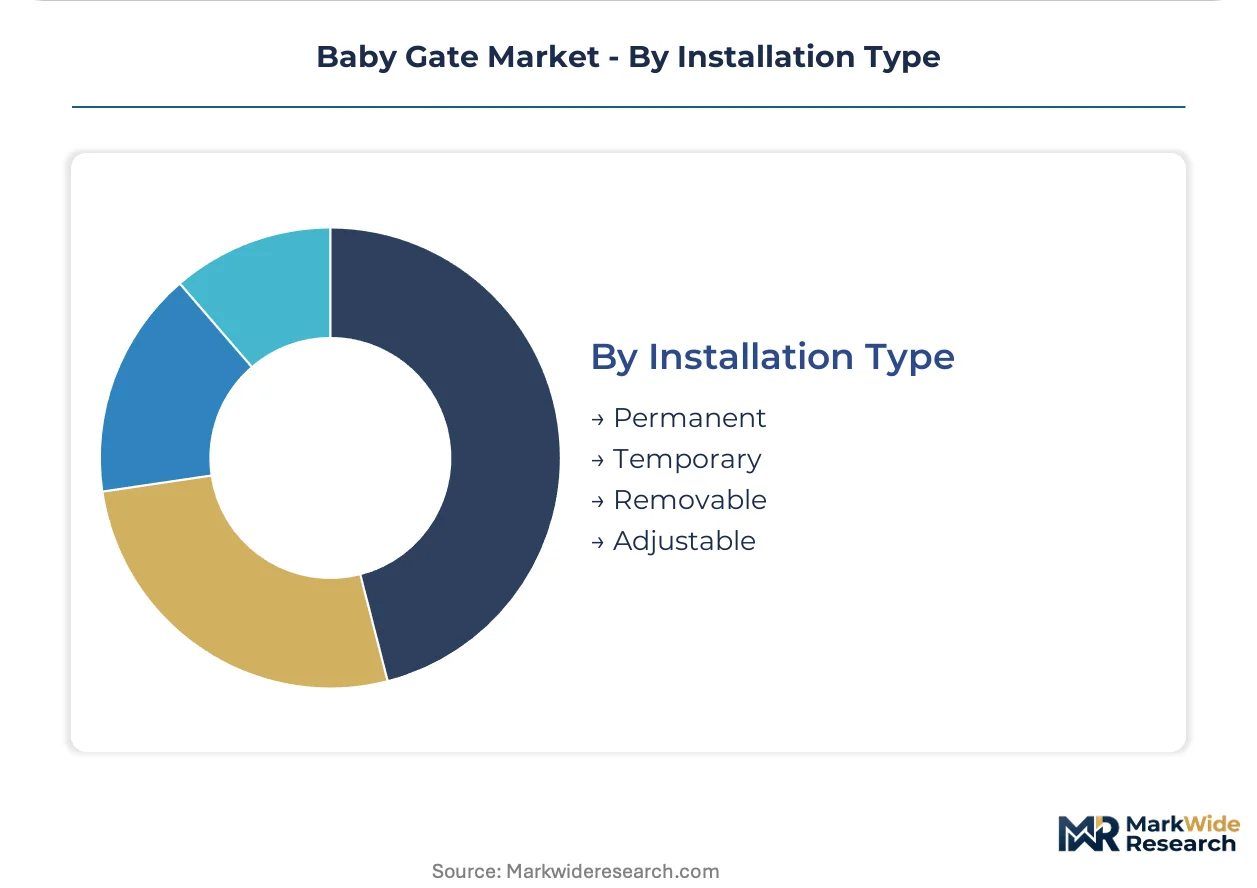
Installation Type:
Customer type alignment maps directly onto mobility patterns, with permanent installations correlating to homeownership tenure and removable systems tracking rental market fluidity.
- Permanent:Fixed hardware mounting into wall studs or structural members delivers maximum stability for stairway applications. Long-tenure homeowners in suburban United States markets prioritize these configurations for multi-year child-rearing periods.
- Temporary:Pressure-based or freestanding systems deploy without surface modification. Visiting grandparents and short-term childcare providers in transient metropolitan areas favor these for intermittent use scenarios.
- Removable:Quick-release mechanisms allow seasonal or situational repositioning without full reinstallation.
- Adjustable:Width-extending frames accommodate non-standard openings in older residential construction.
Permanent installations anchor revenue stability; Temporary configurations are gaining share fastest through equipment-as-a-service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-child households and safety-conscious millennial parents drive concentrated demand across mature markets, with regulatory stringency and rental housing patterns shaping geographic adoption curves.
United States
Suburban homeowners with permanent installation needs favor hardware-mounted metal systems for stairway safety. The Consumer Product Safety Commission enforces mandatory structural and latching standards that all domestic sellers must satisfy. California and Texas metropolitan corridors show strongest momentum for sensor-enabled smart home integration.
Germany
Design-focused consumers prioritize aesthetic wood frames that integrate with residential interiors. REACH substance restrictions from ECHA force reformulation of plastic components and surface coatings across exported product lines. The Bavaria and North Rhine-Westphalia industrial clusters host testing laboratories serving dual EU-US certification needs.
United Kingdom
Urban renters in London and Southeast England drive pressure-mounted volume through equipment-as-a-service models. Trading Standards enforces the General Product Safety Directive alongside voluntary BSI kite-mark specifications. Midlands distribution hubs consolidate inventory for cross-channel fulfillment.
Canada
Visiting grandparent households favor temporary configurations for intermittent childcare arrangements. Health Canada administers the Canada Consumer Product Safety Act with requirements mirroring CPSC thresholds. Ontario and Quebec retail channels show concentration of ASTM-certified imports.
Australia
Traveling caregivers generate portable and fabric segment demand for seasonal repositioning. The ACCC administers mandatory safety standards under the Consumer Goods (Baby Gates) Safety Standard 2014. New South Wales and Victoria metropolitan areas concentrate subscription-based equipment rotation services.
Baby Gate Market Vendor Landscape
Channel-controlling players compete with product-specialist players across mass retail, specialty juvenile, and direct-to-consumer vectors. The vendor base shows moderate concentration with tiered positioning around certification depth and installation support capabilities. Three archetypes dominate: mass-market brands with shelf breadth, safety-specialist manufacturers with ASTM infrastructure, and rental-platform intermediaries with logistics integration. Competitive moves center on retail partnership exclusivity and backward integration into testing laboratory relationships.
Among North American mass-market specialists, Summer Infant and Evenflo exemplify channel-control archetypes with established retail presence, while Regalo anchors the value-tier hardware-mounted specialist position. These three occupy distinct competitive lanes without direct product overlap, reflecting market segmentation by price tier and installation permanence rather than technology differentiation.
| Leading Market Players |
|---|
| Summer Infant |
| Evenflo |
| Babelio |
| Cumbor |
| Safety 1st |
| Regalo |
| Cardinal Gates |
| KidCo |
| North States |
| Others |
Supply Flow & Price Mechanics
Zhejiang Province's concentrated injection-molding capacity for polypropylene components feeds directly into North American retail pricing power, as domestic sellers absorb transpacific logistics premiums to maintain shelf placement against ASTM-certified competitors.
Pricing Analysis
Certification level creates the primary spread across the baby gate market, with CPSC-recognized laboratory validation and ASTM F1004 compliance commanding 15-25% premiums over uncertified imports. Three-tier pricing structure separates premium metal hardware-mounted systems from mid-grade wood configurations and economy plastic pressure-mounted units. Pricing pressure stems from rental-platform substitution in urban markets, compressing transactional margins for outright purchase models. Daycare procurement teams show lowest price sensitivity due to liability-driven specification mandates, while visiting grandparent households in metropolitan rental markets exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on aluminum-magnesium alloy formulations limit certain high-strength frame exports from Chinese foundries, forcing North American manufacturers to diversify sourcing. Component fabrication concentrates in China, Vietnam, and Taiwan, with final assembly increasingly shifting to Mexico to mitigate tariff exposure. Steel tubing, polypropylene resin, and latching hardware constitute the critical input trinity. Single-source vulnerability around CPSC-recognized testing laboratory capacity extends certification timelines. Distribution runs through mass retail partnerships, specialty juvenile stores, and direct-to-consumer platforms with logistics-enabled rental intermediaries gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby gate market sits in early-cycle recovery as multi-child household formation rebounds from demographic troughs, with millennial parenting cohorts driving replacement demand for higher-specification hardware-mounted systems.
For Market Incumbents: Build certification infrastructure moats by securing exclusive relationships with CPSC-recognized testing laboratories, extending lead times for competitor product launches. Anchor backward integration into aluminum-magnesium alloy sourcing to buffer commodity volatility threatening metal frame margins. Counter rental-platform substitution by bundling professional installation services with hardware-mounted purchases, creating switching costs that temporary-use models cannot replicate. For New Entrants and Emerging Players: Smart home integration gaps in California and Texas metropolitan corridors represent the most penetrable entry point for sensor-enabled gate systems targeting tech-forward millennial parents. Secondary certified pre-owned marketplaces for sustainability-conscious buyers remain structurally underserved, with no dominant platform controlling authentication and resale logistics. Pursue direct-to-consumer launch with subscription-based equipment rotation to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ASTM-certified manufacturers with existing laboratory relationships and dual EU-US compliance infrastructure, as regulatory divergence intensifies compliance complexity that scale players can amortize. Long-term viability hinges on capturing recurring revenue streams through installation services and subscription models rather than transactional hardware sales. Watch CPSC staffing levels and third-party laboratory capacity expansion as inflection indicators for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Integration Development | Sensor-enabled gates with IoT connectivity capture California and Texas millennial parent demand. |
| Dual Certification Infrastructure Investment | ASTM and CE marking overlap reduces incremental cost for German and French retail channel access. |
| Subscription Equipment Rotation Launch | Rental platforms serving urban renters displace outright purchase in pressure-mounted categories. |
| Secondary Marketplace Authentication Buildout | Certified pre-owned channels address sustainability-conscious buyer segments with parallel revenue. |
| Aluminum-Magnesium Alloy Backward Integration | Upstream control over lightweight frame materials buffers steel and aluminum commodity volatility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CPSC enforcement databases, ASTM technical committee minutes, and retail point-of-sale audit data, with input from product safety engineers at juvenile equipment manufacturers, category buyers at mass retail chains, and regulatory affairs specialists at third-party testing laboratories. Bottom-up demand modeling across mounting mechanism, material, and end-user segments triangulates against top-down macroeconomic indicators including birth rate trajectories and housing tenure patterns.
Forecast inputs incorporate product type substitution dynamics, regulatory compliance timeline evolution, and channel shift patterns between transactional purchase and equipment-as-a-service models. Segmentation dimensions span mounting mechanism, material composition, installation permanence, and end-user context across household, daycare, clinic, and hospitality applications. CAGRs derive from regression analysis of historical shipment data against demographic and construction activity drivers, with cross-validation against import customs records and retail inventory turnover metrics.
Practitioners should monitor CPSC staffing appropriations, third-party laboratory capacity expansion announcements, and state-level chemical disclosure mandate proliferation for early signals of certification bottleneck severity. Forecasts reflect assumptions regarding sustained ASTM F1004 compliance mandates and continued retailer enforcement of voluntary juvenile product specifications. Material shifts in CPSC structural standard revisions or EU REACH substance restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market