
 Biodegradable Sanitary Napkins Market | 2026-2036
Biodegradable Sanitary Napkins Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Sanitary Napkins Market Intelligence
The EU Green Deal is consolidating demand for plastic-free feminine hygiene across European retail channels. Natracare leverages its organic cotton supply chain to dominate pharmacy shelf space in the United Kingdom. Rael sustains its position through Korean-manufactured bamboo fiber technology and direct-to-consumer subscription models. Saathi anchors rural distribution in India through biodegradable banana fiber products and community-based sales networks.
Biodegradable sanitary napkins are absorbent hygiene products constructed from plant-derived substrates such as organic cotton, bamboo fiber, or corn starch-based biopolymers, typically featuring compostable back sheets and adhesives that decompose within industrial composting conditions. Their primary commercial purpose is to provide menstrual protection while eliminating persistent plastic waste from municipal solid waste streams. Organic cotton and bamboo fiber variants command premium positioning due to certified supply chains and dermatological safety profiles, whereas corn starch segments compete on cost parity with conventional products in emerging markets. Online retail channels are capturing the fastest growth trajectory as subscription services bypass traditional retail markups and enable direct consumer education on composting protocols.
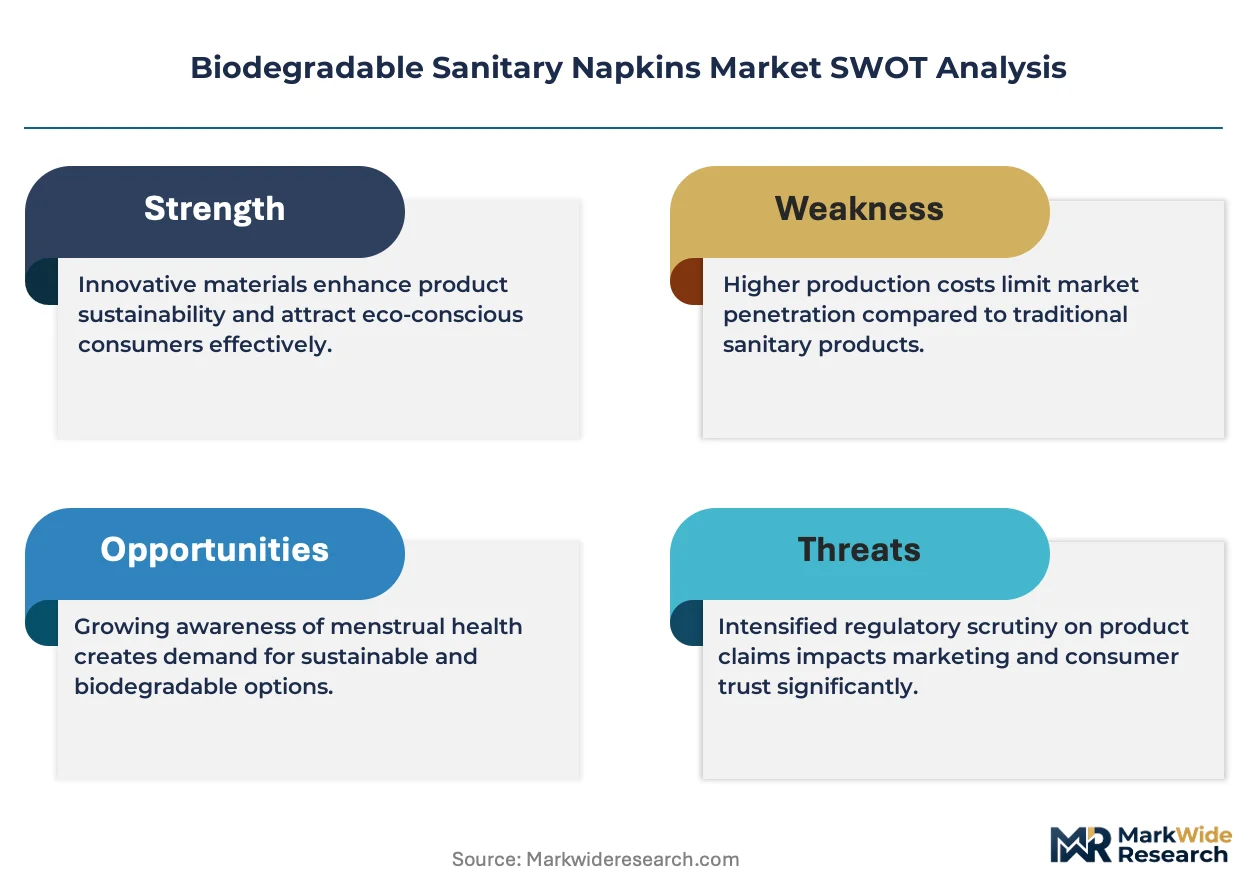
REACH and the EU F-Gas Regulation shape material compliance requirements for European manufacturers, while India's BIS certification mandates biodegradability testing for products claiming environmental benefits. The US FDA regulates absorbent hygiene products as medical devices, requiring substantiated safety claims that influence formulation decisions across export-oriented producers. Stakeholders must monitor evolving composting infrastructure availability and certification harmonization between national standards to validate premium pricing claims and secure retail placement.
Market Dynamics
The EU Green Deal's single-use plastics directive is compressing formulation timelines for absorbent core manufacturers, forcing immediate substitution of petroleum-based back sheets with certified compostable alternatives across European supply chains.
Growth Catalysts
- REACH compliance deadlines:European manufacturers accelerate biopolymer adoption to meet substance authorization requirements for menstrual product constituents.
- Urban millennial demographics:Pharmacy chains in Germany standardize compostable napkin inventory to capture this consumer cohort's preference for plastic-free alternatives.
- Bamboo fiber processing:Korean manufacturing clusters scale cost-competitive absorbent layer production for export markets.
Market Restraints
- Organic cotton supply concentration:Certified fiber availability clusters in Turkey and India, creating input bottlenecks for European converters.
- Industrial composting infrastructure gaps:Municipal facilities in Southern and Eastern Europe lack capacity to process certified products, undermining premium positioning claims.
- Conventional plastic napkin price parity:Mass-market synthetic alternatives retain shelf space through distributor margin structures.
Strategic Opportunities
- Rural Indian distribution networks:Community-based sales models for banana fiber products access underpenetrated demographics outside urban retail channels.
- Direct-to-consumer subscription platforms:Digital channels bypass traditional pharmacy markups while enabling composting protocol education.
- EU F-Gas Regulation alignment:Manufacturers reformulate adhesive systems to capture regulatory preference for fluorine-free absorbent hygiene products.
Industry Challenges
- BIS certification timelines:Indian biodegradability testing protocols delay product launch schedules for export-oriented producers.
- Composting certification harmonization:Divergent national standards between EU member states complicate cross-border retail placement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Sanitary Napkins Market |
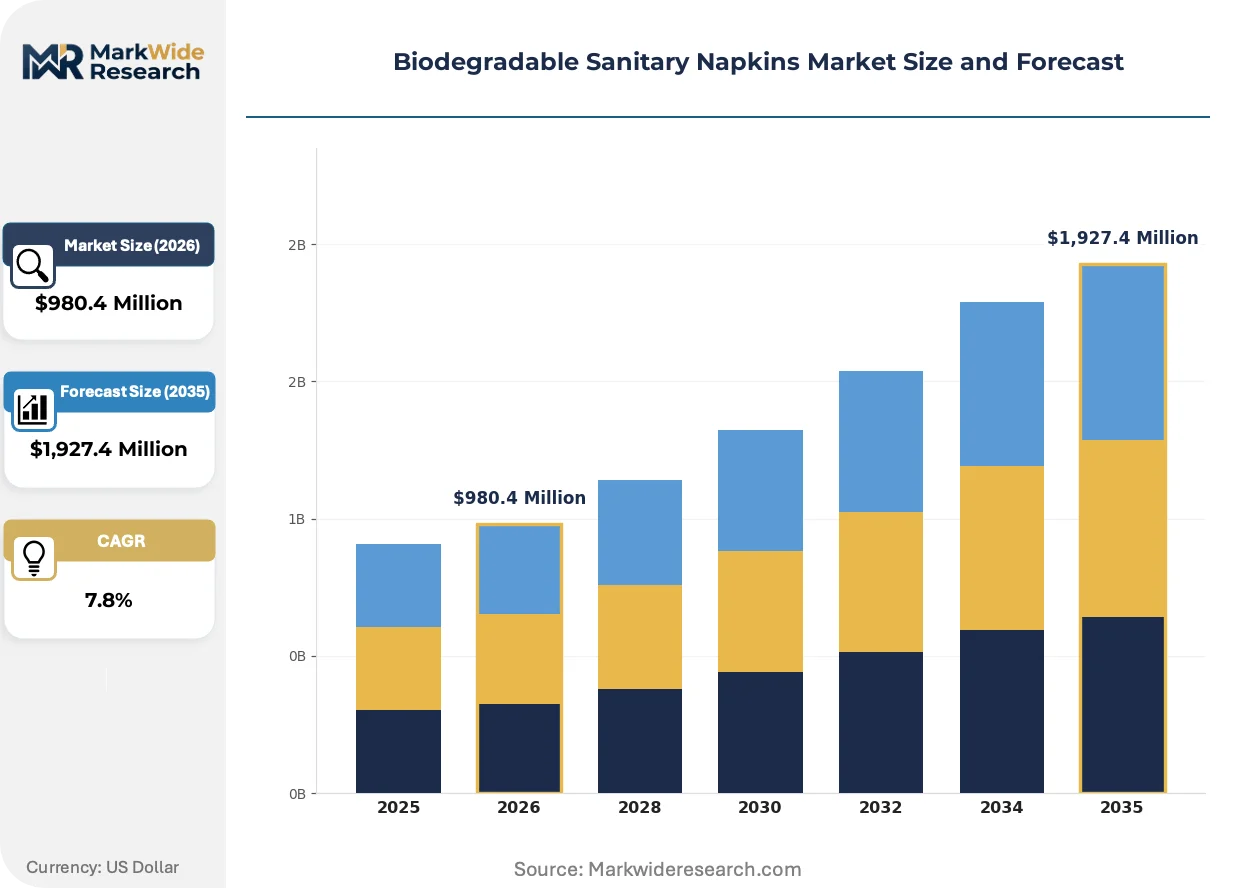
| Market Size in 2026 | $980.4 Million |
| Market Size in 2035 | $1,927.4 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Bamboo Fiber, Recycled Paper, Corn Starch Usage Type: Daily Use, Overnight, Panty Liners, Postpartum End User: Women, Adolescents, Hospitals, Gynecological Clinics Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Organyc, Bamboo Babe, Natracare, Rael, Pee Safe, Carmesi, Niine Sanitary Napkins, Cora, Saathi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Sanitary Napkins Market Strategic Shifts & Innovations
Plant-derived substrate technologies are compressing conventional petroleum-based supply chains, while regulatory frameworks and procurement behaviors simultaneously reshape competitive positioning across absorbent hygiene markets.
Cellulose-based absorbent cores derived from agricultural waste streams are converging with corn starch biopolymer back sheet laminates to create fully compostable napkin architectures. German pharmacy buyers now specify these dual-substrate constructions for private label lines. The technology is converging with established menstrual product manufacturing equipment, reducing capital barriers for incumbent converters.
REACH substance authorization requirements for persistent organic pollutants are forcing reformulation of superabsorbent polymer chemistries across European production facilities. Manufacturers substituting acrylate-based constituents with polysaccharide alternatives face extended safety substantiation timelines. Organic cotton and bamboo fiber segments absorb the highest compliance costs, passing these through to pharmacy retail channels.
Subscription-based replenishment models displace periodic pharmacy purchasing among urban professional demographics in the United Kingdom and Germany. Direct channels capture consumer data on composting facility access, enabling localized product recommendations. Digital education on industrial composting protocols accompanies shipments, addressing the infrastructure awareness gap that constrains repeat purchase rates.
Biodegradable Sanitary Napkins Market Segmentation
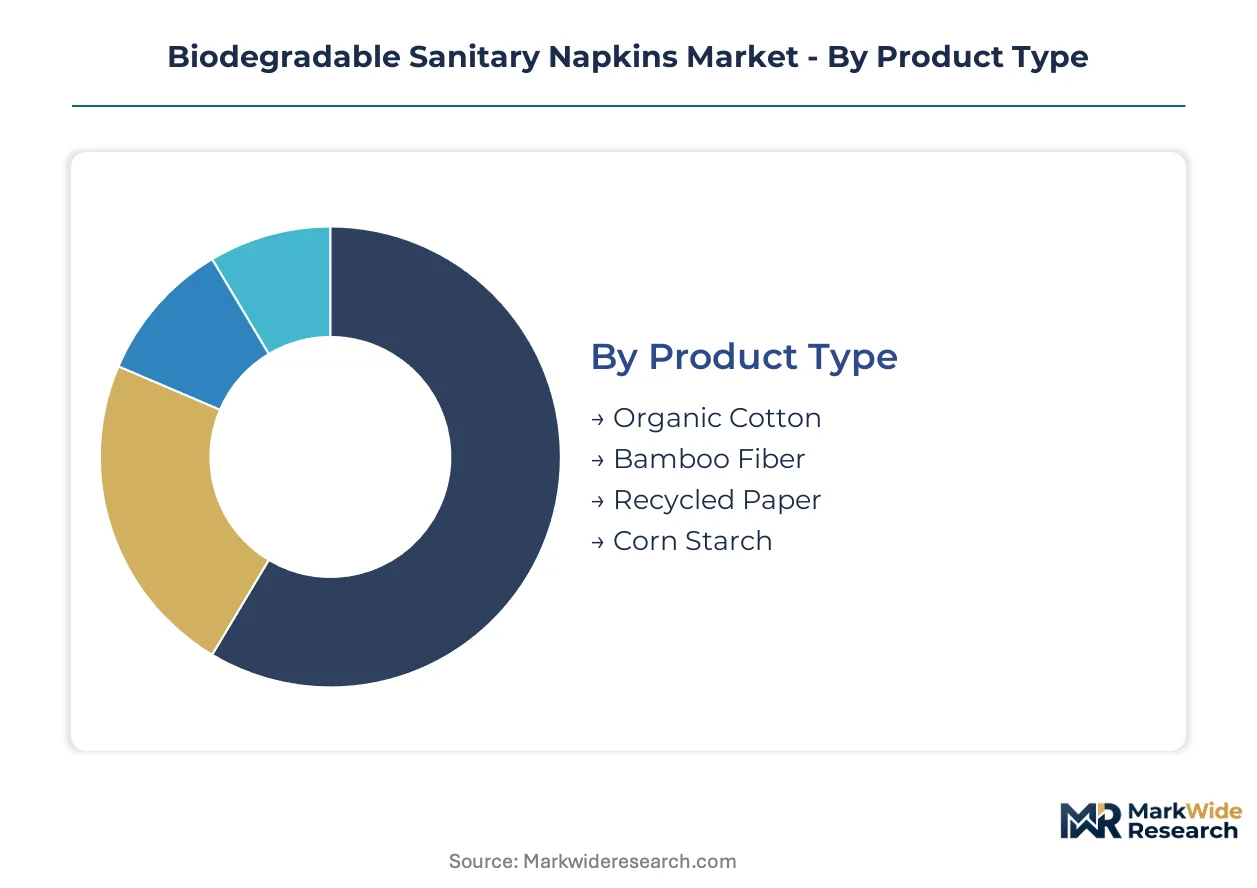
Plant-derived substrate selection and usage occasion specificity drive purchasing decisions across biodegradable sanitary napkin categories. Certification requirements and composting infrastructure availability further differentiate commercial positioning within each segment dimension.
Product Type:
Cost tier separates buyers seeking dermatological certification from those prioritizing price parity with conventional products.
- Organic Cotton:GOTS-certified fiber constructions command premium shelf placement in German and UK pharmacy chains. Demand concentrates among urban millennial demographics willing to absorb price premiums for pesticide-free supply chain transparency.
- Bamboo Fiber:Korean manufacturing clusters scale cost-competitive absorbent layer production through viscose processing technology. German pharmacy buyers now specify bamboo-cotton blends for private label lines seeking mid-tier positioning.
- Recycled Paper:Cellulose-based cores from agricultural waste streams compete on cost parity in emerging markets.
- Corn Starch:Biopolymer back sheet laminates enable full compostability claims where industrial facilities exist.
Organic cotton leads volumes today; bamboo fiber is gaining share fastest.
Usage Type:
Volume scale distinguishes segments, with high-frequency purchase occasions commanding supply chain investment.
- Daily Use:Standard absorbency constructions dominate subscription replenishment models in the United Kingdom. Digital channels capture consumer data on composting facility access to sustain repeat purchase rates.
- Overnight:Extended-wear specifications require thicker absorbent cores that challenge composting timelines. REACH substance authorization requirements force reformulation of superabsorbent polymer chemistries for European production.
- Panty Liners:Thin-profile designs minimize material costs for price-sensitive demographics.
- Postpartum:Hospital procurement specifications demand medical-grade absorbency certification under FDA device regulations.
Daily use leads volumes today; overnight products show steepest expansion trajectory.
End User:
Customer type determines regulatory compliance burden and distribution channel strategy.
- Women:Adult demographic purchases concentrate in pharmacy and subscription channels across Germany and the United Kingdom. EU Green Deal procurement guidelines now favor compostable specifications for institutional buyers.
- Adolescents:School-based distribution programs in India access underpenetrated demographics through community-based sales networks.
- Hospitals:Medical device classification under FDA and CDSCO regulations requires substantiated safety claims.
- Gynecological Clinics:Specialist channel demands dermatological testing documentation for sensitive-skin positioning.
Women lead volumes today; adolescents are climbing the fastest.
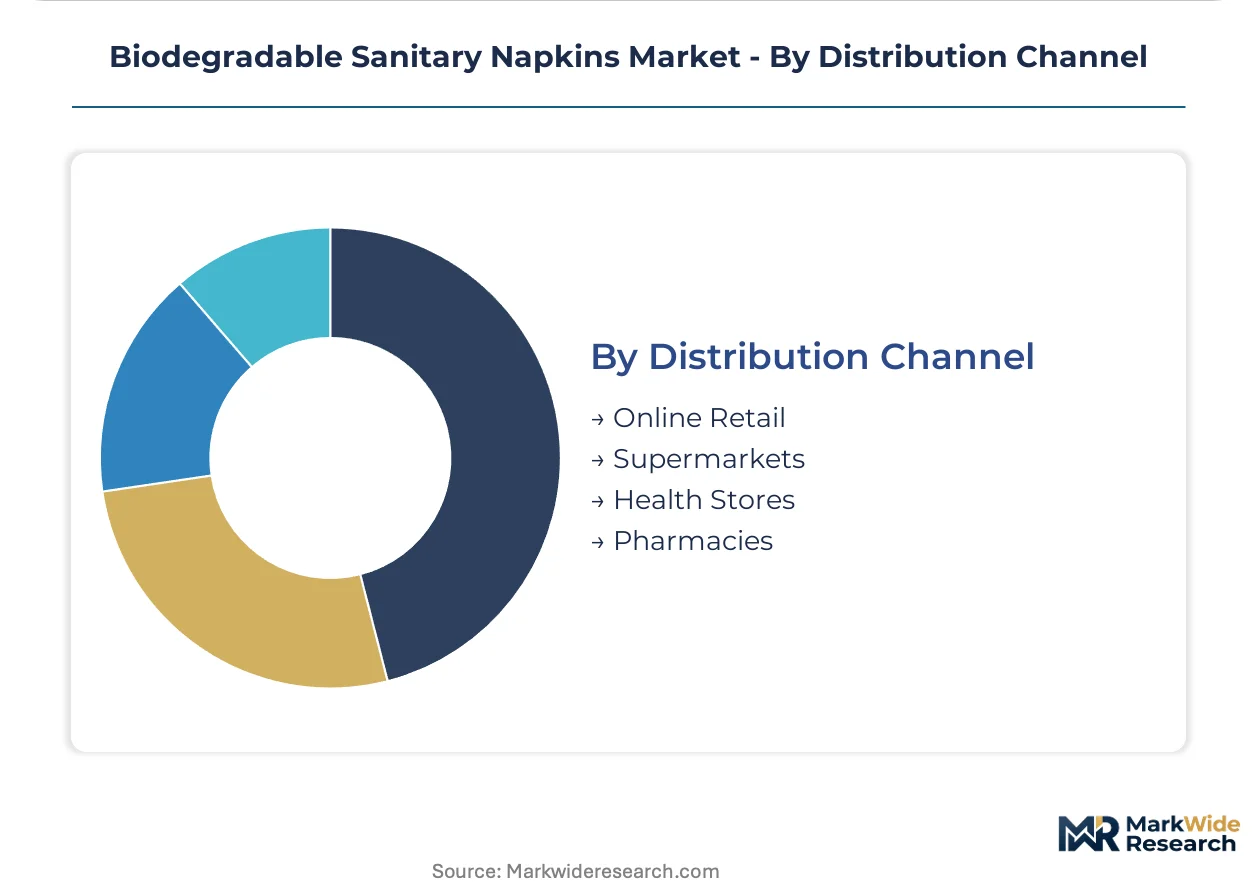
Distribution Channel:
Margin structure and consumer education capability differentiate channel economics.
- Online Retail:Subscription services bypass traditional pharmacy markups while enabling direct composting protocol education. Digital channels capture fastest growth through localized product recommendations based on facility access data.
- Supermarkets:Mass-market placement requires price parity with conventional plastic alternatives.
- Health Stores:Certified organic positioning commands premium pricing in UK and German natural product channels.
- Pharmacies:German pharmacy chains now stock certified compostable napkin lines as standard inventory.
Pharmacies lead volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biodegradable sanitary napkin manufacturing originated in European organic cotton supply chains during the 1980s, with German and UK pharmacy networks establishing the first certified compostable product distribution. Industrial clusters now span three continents as regulatory pressure and consumer preference reshape absorbent hygiene procurement.
Germany
Urban millennial women in Berlin and Hamburg drive pharmacy demand for plastic-free menstrual products. The EU Green Deal's single-use plastics directive compels domestic manufacturers to eliminate petroleum-based back sheets from absorbent cores. Bavarian textile converters now supply certified compostable napkin lines to pharmacy chains as standard inventory.
United Kingdom
Subscription-based replenishment models capture professional demographics in London and Manchester seeking direct-to-consumer convenience. REACH substance authorization requirements force reformulation of superabsorbent polymer chemistries across domestic production facilities. Natracare leverages its organic cotton supply chain to dominate pharmacy shelf space nationwide.
India
School-based distribution programs in Maharashtra and Karnataka access adolescent demographics through community-based sales networks. BIS certification mandates biodegradability testing for products claiming environmental benefits, delaying launch schedules for export-oriented producers. Saathi anchors rural distribution through biodegradable banana fiber products manufactured in Gujarat.
South Korea
Korean manufacturing clusters scale cost-competitive bamboo fiber absorbent layer production for export markets. MFDS regulations align with EU substance safety standards, enabling seamless European market access for domestic converters. Rael sustains its competitive position through viscose processing technology and direct-to-consumer subscription platforms.
United States
FDA medical device classification requires substantiated safety claims that influence formulation decisions across import-dependent supply chains. California and New York Metro consumers demonstrate strongest adoption of plant-based menstrual products through online retail channels. Cora occupies the premium-tier vector through organic cotton positioning and subscription-based customer acquisition.
Biodegradable Sanitary Napkins Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and distribution channel access. The vendor base stratifies between GOTS-certified organic cotton specialists, bamboo fiber technology licensors, and agricultural waste substrate innovators. Three strategic archetypes dominate: pharmacy-centric European heritage brands, Asian manufacturing-integrated exporters, and North American direct-to-consumer platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure certified raw material supply.
Within the European heritage tier, Organyc and Natracare exemplify pharmacy-centric positioning through organic cotton supply chain control. Among Asia-Pacific manufacturing-integrated players, Rael and Saathi occupy positions bridging substrate technology and community-based distribution. At the North American direct-to-consumer end, Cora represents subscription-platform customer acquisition models. These named companies anchor industry-level commentary without specific factual claims about individual strategic actions or financial performance.
| Leading Market Players |
|---|
| Organyc |
| Bamboo Babe |
| Natracare |
| Rael |
| Pee Safe |
| Carmesi |
| Niine Sanitary Napkins |
| Cora |
| Saathi |
| Others |
Cost & Logistics Intelligence
Captive organic cotton supply chains in Turkey and India anchor premium pricing power for GOTS-certified European converters, while outsourced bamboo fiber sourcing from Korean viscose clusters enables mid-tier cost positioning. This integration choice separates pharmacy-centric heritage brands from subscription-platform challengers competing on margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates channel economics, with GOTS certification and dermatological testing documentation commanding pharmacy shelf placement premiums. Cost compression in corn starch biopolymer segments intensifies as Indian manufacturers achieve scale in agricultural waste substrate processing. Urban millennial demographics in Germany and the United Kingdom show lowest price sensitivity, while emerging market adolescents prioritize cost parity with conventional plastic alternatives.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing patterns for European converters, compelling substitution of petroleum-based back sheets with certified compostable alternatives. Raw material flows concentrate in Turkish organic cotton gins, Indian banana fiber cooperatives, and Korean bamboo viscose processing facilities. Single-source vulnerability in GOTS-certified fiber creates bottleneck exposure during harvest cycles. Distribution runs through German pharmacy chains, UK health stores, and direct-to-consumer subscription platforms capturing fastest growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting decisively toward compostable specifications backed by industrial facility access verification.
For Market Incumbents: Acquire certified fiber processing capacity in Turkey or India to secure GOTS supply chain control against emerging biopolymer challengers. Invest in backward integration into banana fiber cooperatives to replicate Saathi's rural Indian distribution model before regional competitors consolidate community-based sales networks. For New Entrants and Emerging Players: Agricultural waste cellulose processing technology offers entry into cost-competitive corn starch back sheet manufacturing for European private label contracts. Target Southern and Eastern European markets where industrial composting infrastructure gaps create white-space for education-heavy direct-to-consumer platforms with localized facility mapping. For Investors and Strategic Acquirers: Consolidation pressure builds where substrate technology overlaps with subscription-platform customer acquisition capabilities. The five-to-ten year viability window favors acquisition targets combining Korean bamboo viscose expertise with EU regulatory compliance infrastructure. Watch composting certification harmonization between EU member states as the inflection signal for cross-border retail placement scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | GOTS and BIS compliance investments unlock pharmacy shelf placement in Germany and India. |
| Direct-to-Consumer Launch | Subscription platforms bypass traditional retail markups while enabling composting protocol education. |
| Backward Integration | Captive organic cotton supply chains in Turkey defend margin position against volatile fiber spot markets. |
| Sustainability Repositioning | EU F-Gas Regulation alignment captures regulatory preference for fluorine-free adhesive systems. |
| Distribution Channel Expansion | Community-based sales networks access underpenetrated rural adolescent demographics in Maharashtra. |
Research Approach
Coverage spans European pharmacy networks, Indian rural distribution channels, and Korean manufacturing clusters, with primary inputs from each. The research combines interviews with brand managers at heritage organic cotton producers, procurement leads at German pharmacy chains, and supply planners at bamboo viscose converters, validated against secondary sources including EU ECHA substance authorization databases, BIS certification registries, and MFDS regulatory filings. Bottom-up volume builds triangulate against top-down category spend estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing trajectory across substrate type, usage occasion, and distribution channel dimensions. The analytical framework models organic cotton, bamboo fiber, corn starch, and recycled paper segments alongside daily use, overnight, and panty liner applications. CAGRs derive from regression analysis against composting infrastructure penetration curves and regulatory compliance timeline acceleration. Forecast inputs include REACH substance authorization backlog projections and Indian school-based distribution program expansion rates.
The model holds under continued EU Green Deal enforcement and stable organic cotton harvest yields; deviation in BIS certification timeline delays or industrial composting facility deployment shortfalls would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Japan Adult Diaper Market