
 BRICS Disposable Hygiene Products Market | 2026-2036
BRICS Disposable Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
BRICS Disposable Hygiene Products Market Outlook
China's dual carbon goals is expanding the addressable market for biodegradable material-based hygiene products across the BRICS bloc. Procter & Gamble leverages its manufacturing scale to serve mass-market segments in Brazil and India. Kimberly-Clark Corporation anchors its position through specialized adult incontinence distribution networks in South Africa and Russia. Essity AB differentiates via R&D intensity in sustainable absorbent core technologies tailored to regional raw material availability.
BRICS disposable hygiene products encompass single-use absorbent articles manufactured from layered non-woven fabrics, superabsorbent polymers, and elastic components designed for bodily fluid management in infant, feminine, and adult care applications. Production employs hot-melt adhesive bonding and thermal calendering to achieve breathability thresholds between 800 and 2,500 g/m²/24h. Diapers capture the largest volume share due to birth-rate demographics and aging populations across Brazil, Russia, India, China, and South Africa. Biodegradable materials represent the fastest-expanding material category as regulatory pressure and urban waste-management constraints intensify in Chinese and Indian metropolitan areas. Online retailers are displacing traditional supermarket dominance in product access, particularly for adult incontinence purchases where consumer privacy preferences reshape channel selection.
China's SAMR enforces GB standards for disposable hygiene product safety, while India's BIS mandates textile and non-woven quality certifications under amended consumer protection rules. Brazil's ANVISA regulates absorbent product registration as medical-grade devices when marketed through healthcare facilities. These frameworks elevate compliance costs for new entrants but simultaneously validate premium-tier domestic manufacturers. Stakeholders must monitor evolving extended producer responsibility mandates in Indian states and Chinese provinces that will reshape material specifications and reverse-logistics obligations.
Market Dynamics
India's PLI scheme for textiles and non-woven materials is accelerating domestic manufacturing capacity across the five-nation bloc, while China's dual carbon goals expand the addressable market for biodegradable material-based hygiene products. Healthcare facility demand strengthens as modern retail penetration deepens in China's tier-two and tier-three cities.
Growth Catalysts
- Extended producer responsibility mandates:Indian states and Chinese provinces are reshaping material specifications and reverse-logistics obligations for absorbent product manufacturers. Compliance investments validate premium-tier domestic producers.
- Superabsorbent polymer innovation:R&D intensity in sustainable absorbent core technologies is accelerating as regional raw material availability dictates formulation choices across Brazil and South Africa.
- Tier-two and tier-three city expansion:Modern retail penetration in China's secondary urban centers concentrates demand visibility for infant and adult care segments.
Market Restraints
- GB standards enforcement:China's SAMR safety requirements elevate compliance costs for new entrants seeking market access.
- Superabsorbent polymer supply concentration:Petrochemical feedstock volatility affects input cost structures for non-woven fabric production.
- Medical-grade device registration:Brazil's ANVISA absorbent product classification creates friction for healthcare channel entry.
Strategic Opportunities
- Adult incontinence privacy channels:Online retailers displace traditional supermarket dominance where consumer confidentiality preferences reshape product access in South Africa and Russia.
- Biodegradable material conversion:Regulatory pressure and urban waste-management constraints in Chinese and Indian metropolitan areas create white space for compostable absorbent core technologies.
- Healthcare facility procurement:Demand from hospitals and long-term care facilities strengthens across the bloc as aging demographics expand the patient base.
Industry Challenges
- Thermal calendering breathability thresholds:Achieving 800 to 2,500 g/m²/24h specifications requires precise process control that scarce technical talent struggles to maintain.
- Hot-melt adhesive bonding certification:BIS textile and non-woven quality certifications under India's amended consumer protection rules extend product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRICS Disposable Hygiene Products Market |
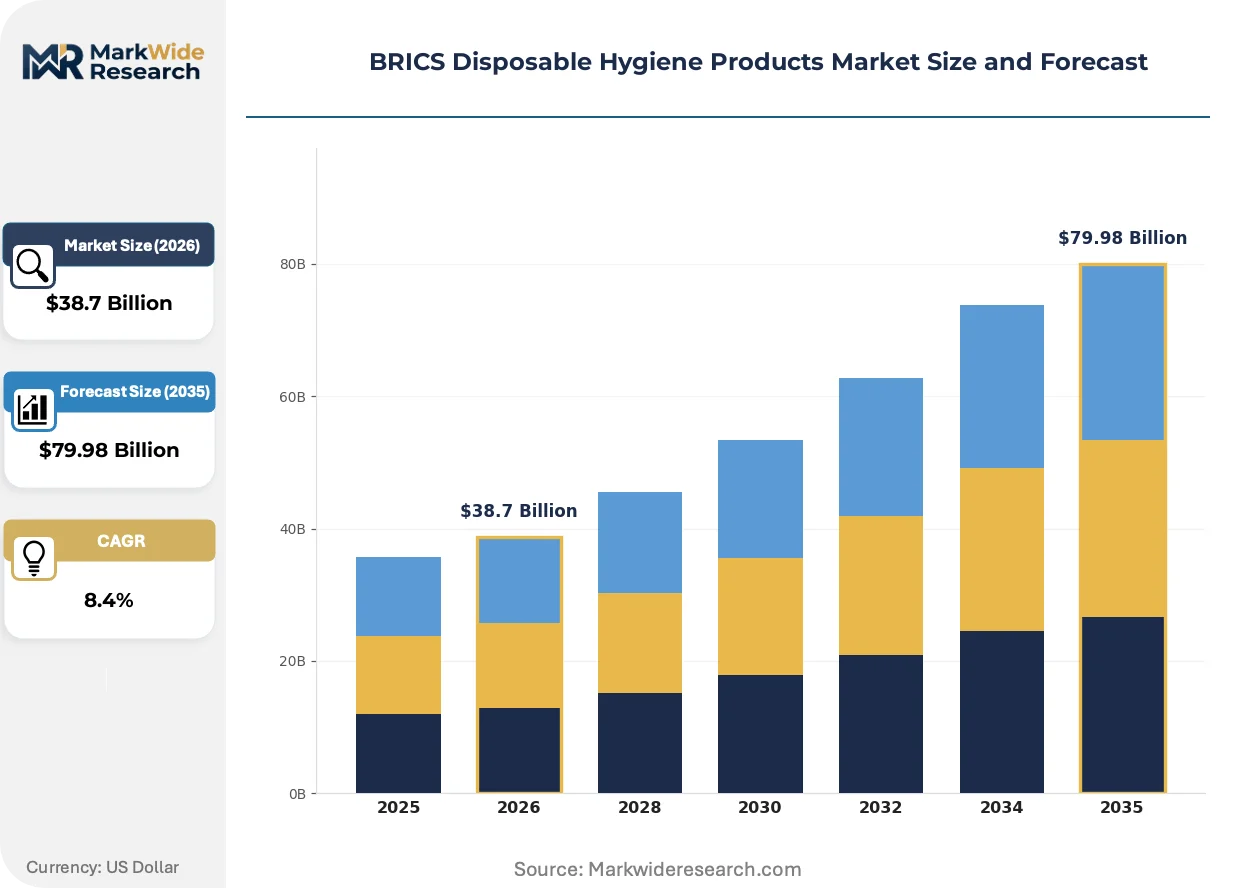
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Sanitary Napkins, Incontinence Products, Wipes End User: Infants, Adults, Women, Healthcare Facilities Material: Plastic, Cotton, Biodegradable Materials, Non-Woven Fabric Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Convenience Stores |
| Companies Covered | Hengan International Group, Ontex Group, Procter & Gamble, Kao Corporation, Johnson & Johnson, Kimberly-Clark Corporation, Essity AB, Vinda International Holdings, Unicharm Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRICS Disposable Hygiene Products Market Strategic Shifts
Material science breakthroughs and channel restructuring are actively reshaping competitive positioning across the BRICS disposable hygiene landscape. Regulatory pressure on waste management intersects with evolving consumer privacy preferences to redirect investment flows.
Plant-based superabsorbent polymers derived from agricultural cellulose waste streams are converging with conventional petroleum-based SAP in hybrid core formulations. Tier-one Chinese manufacturers adopt these materials at pilot scale for premium diaper lines. This convergence is compressing the cost premium between biodegradable and standard absorbent products.
China's dual carbon goals mandate industrial decarbonization timelines that absorbent product manufacturers must incorporate into facility upgrade plans. MEE provincial enforcement actions are accelerating compliance investments. Infant care segments in coastal manufacturing zones respond by sourcing renewable electricity for thermal calendering operations.
Privacy-driven channel migration for adult incontinence purchases redirects volume from hypermarkets toward direct-to-consumer platforms. E-commerce fulfillment networks in Russia and Brazil capture this displacement through subscription-based replenishment models. Urban professional caregivers in São Paulo and Moscow drive this behavioral shift most visibly.
BRICS Disposable Hygiene Products Market Segmentation
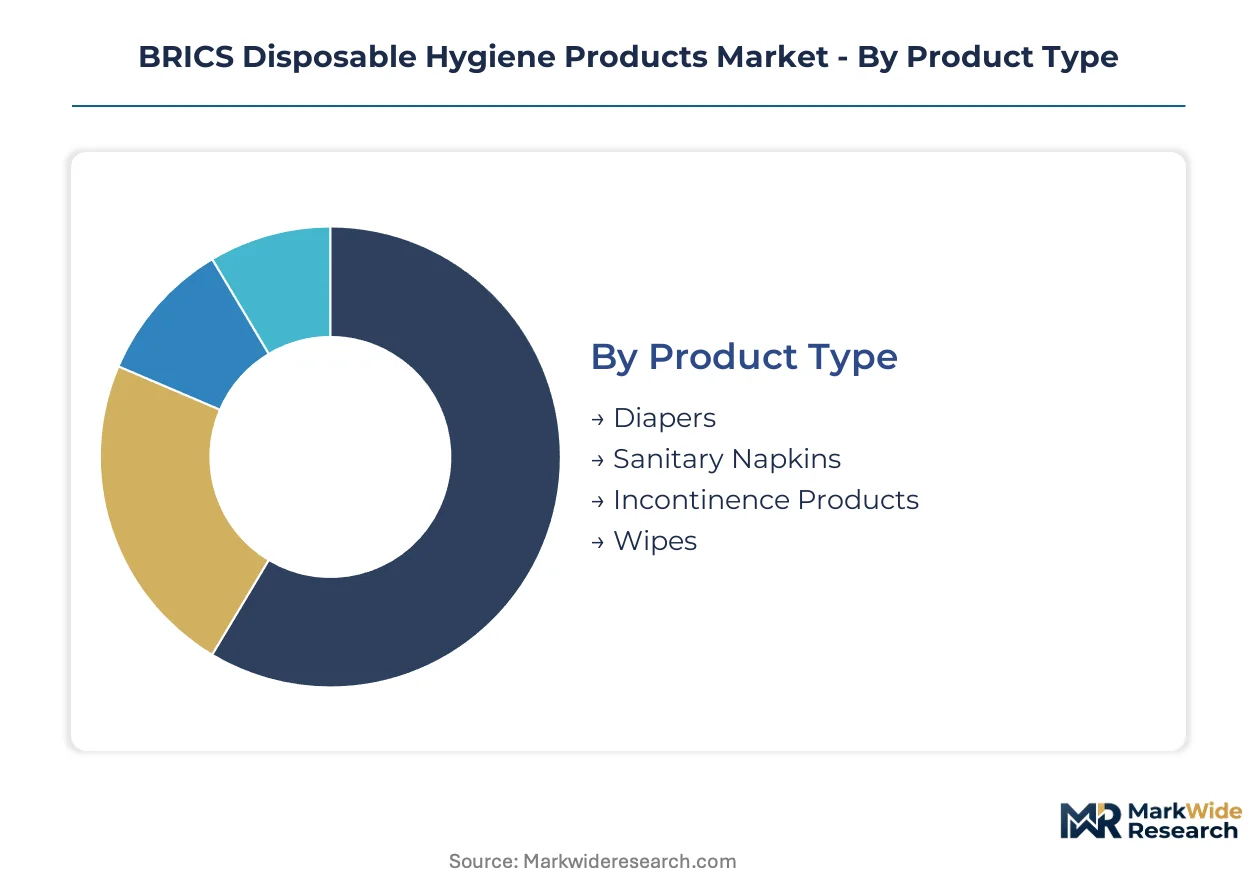
Segmentation in the BRICS disposable hygiene market reveals divergent profit pools across product architectures and channel economics. Manufacturers must calibrate R&D investment and distribution partnerships against which segments operate as standalone consumer purchases versus embedded institutional procurement systems.
Product Type:
Integration depth varies sharply: diapers and sanitary napkins function as standalone retail SKUs with direct consumer decision-making, while incontinence products and institutional wipes embed within healthcare procurement frameworks.
- Diapers:Layered non-woven fabric assemblies with superabsorbent polymer cores achieving 800-2,500 g/m²/24h breathability specifications. Demand concentrates in China's tier-two and tier-three cities where modern retail penetration deepens and birth-rate demographics sustain volume.
- Sanitary Napkins:Absorbent core products utilizing thermal calendering and hot-melt adhesive bonding for fluid management. India's PLI scheme for textiles accelerates domestic manufacturing capacity as BIS certification requirements elevate compliance thresholds for new entrants.
- Incontinence Products:Specialized adult care articles distributed through healthcare facility networks in South Africa and Russia.
- Wipes:Single-use cleansing substrates manufactured from non-woven fabrics for infant and adult hygiene applications.
Diapers lead volumes today; biodegradable material conversion is gaining share fastest across the product portfolio.
End User:
Cost tier stratification separates premium consumer segments from economy institutional procurement, with privacy preferences and reimbursement policies driving divergent channel selection.
- Infants:Birth-rate demographics across Brazil, Russia, India, China, and South Africa anchor volume demand for diaper and wipe products. Coastal Chinese manufacturing zones source renewable electricity for thermal calendering operations to meet dual carbon goals compliance timelines.
- Adults:Aging populations expand the patient base for incontinence management. Online retailers displace supermarket dominance in Russia and Brazil where consumer confidentiality preferences reshape product access toward subscription-based replenishment models.
- Women:Sanitary napkin demand concentrates in urban centers with modern retail infrastructure and direct-to-consumer platform penetration.
- Healthcare Facilities:Hospitals and long-term care facilities strengthen procurement across the bloc as ANVISA medical-grade device registration creates friction for Brazilian market entry.
Infant care leads volumes today; adult incontinence is climbing the fastest as aging demographics reshape end-user composition.
Material:
Supply concentration in petrochemical feedstocks creates margin pressure, while regional raw material availability dictates sustainable formulation choices across manufacturing zones.
- Plastic:Petroleum-derived substrates dominate cost-sensitive segments. Petrochemical feedstock volatility affects input cost structures for non-woven fabric production.
- Cotton:Natural fiber alternatives for premium consumer segments seeking skin-contact comfort.
- Biodegradable Materials:Plant-based superabsorbent polymers derived from agricultural cellulose waste streams. Tier-one Chinese manufacturers adopt these at pilot scale as MEE provincial enforcement actions accelerate compliance investments under dual carbon mandates.
- Non-Woven Fabric:Base substrate for all absorbent article categories, with India's PLI scheme accelerating domestic textile and non-woven capacity expansion.
Plastic-based materials lead volumes today; biodegradable alternatives are expanding most quickly as waste-management constraints intensify.
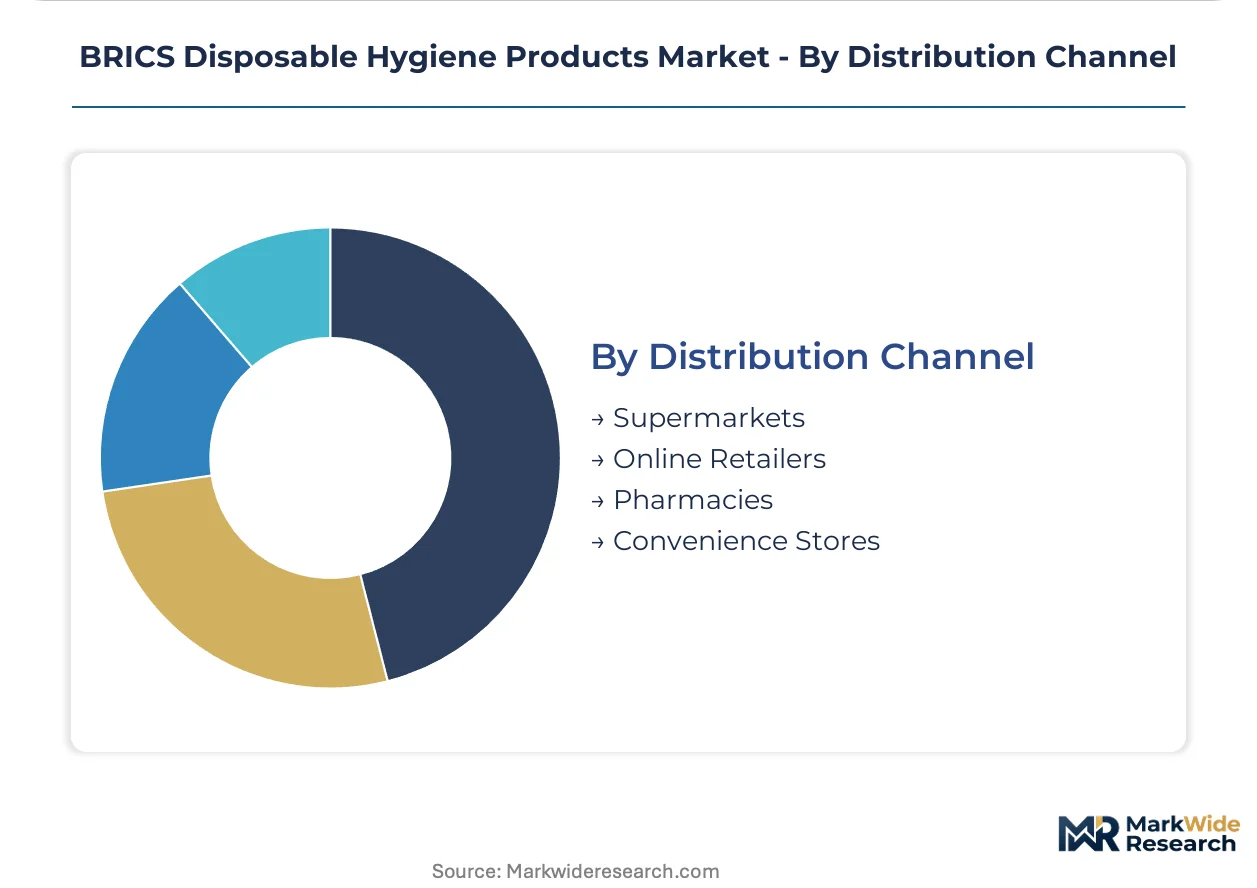
Distribution Channel:
Channel maturity separates established supermarket networks from rapidly scaling e-commerce fulfillment infrastructure, with privacy-sensitive segments driving structural displacement.
- Supermarkets:Traditional mass-market access for infant and feminine care products. Hypermarket dominance erodes in adult incontinence categories where consumer confidentiality preferences redirect volume.
- Online Retailers:Direct-to-consumer platforms capture privacy-driven channel migration. E-commerce fulfillment networks in São Paulo and Moscow drive subscription-based replenishment models for professional caregivers.
- Pharmacies:Healthcare-adjacent distribution for medical-grade incontinence products regulated under Brazil's ANVISA framework.
- Convenience Stores:Emergency purchase access for urban consumers in dense metropolitan zones across Indian and Chinese cities.
Supermarkets lead volumes today; online retailers are gaining share fastest as digital infrastructure penetrates secondary urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disposable hygiene manufacturing first achieved industrial scale in the United States and Western Europe during the 1960s, with technology transfer to BRICS markets accelerating through the 1990s as demographic transitions created sustained demand for infant and adult care products.
China
Tier-two and tier-three cities concentrate demand growth as modern retail penetration deepens beyond coastal manufacturing zones. SAMR enforces GB standards for product safety while MEE provincial actions accelerate dual carbon compliance timelines. Yangtze River Delta manufacturers pilot plant-based superabsorbent polymers for premium diaper lines.
India
Birth-rate demographics and urban sanitation awareness anchor volume expansion for infant and feminine care segments. BIS mandates textile and non-woven quality certifications under amended consumer protection rules. Maharashtra and Gujarat absorb PLI scheme investments for domestic non-woven fabric capacity expansion.
Brazil
São Paulo professional caregivers drive subscription-based replenishment models for adult incontinence products. ANVISA regulates absorbent product registration as medical-grade devices when marketed through healthcare facilities. Southeastern manufacturing clusters serve mass-market segments through established retail networks.
Russia
E-commerce fulfillment networks capture privacy-driven channel migration for adult care purchases. Consumer confidentiality preferences redirect volume from hypermarkets toward direct-to-consumer platforms. Moscow anchors distribution infrastructure for specialized incontinence product access.
South Africa
Healthcare facility procurement strengthens as aging demographics expand the patient base for long-term care. Specialized adult incontinence distribution networks anchor market access. Gauteng province concentrates manufacturing and distribution capabilities for regional supply.
BRICS Disposable Hygiene Products Market Competitive Environment
Premium-margin players sit above commodity-margin players across material innovation and channel control dimensions. The vendor base organizes into three tiers: multinational consumer goods conglomerates with manufacturing scale, regional specialists with distribution depth, and domestic manufacturers capturing PLI-supported capacity expansion. Strategic moves concentrate on sustainable material conversion and privacy-channel fulfillment infrastructure.
Among Asia-Pacific headquartered conglomerates, Hengan International Group and Vinda International Holdings occupy positions within the regional specialist tier. Procter & Gamble and Kimberly-Clark Corporation exemplify scale-driven multinational archetypes. Essity AB represents the sustainability-focused innovation segment with R&D intensity in absorbent core technologies.
| Leading Market Players |
|---|
| Hengan International Group |
| Ontex Group |
| Procter & Gamble |
| Kao Corporation |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Essity AB |
| Vinda International Holdings |
| Unicharm Corporation |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility cascades through superabsorbent polymer procurement into tiered pricing structures across BRICS absorbent product markets. Input cost pressure from petroleum-derived substrates compresses margins for non-woven fabric converters while validating premium positioning for plant-based alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates biodegradable-certified products from conventional petroleum-based lines from institutional bulk contracts. Price differentiation hinges on GB standards compliance tier and renewable electricity sourcing for thermal calendering operations. Cost compression in economy tiers is intensifying because India's PLI scheme accelerates domestic non-woven capacity expansion. Healthcare facilities demonstrate lowest price sensitivity due to reimbursement frameworks, while tier-three Chinese consumers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from multinational buyers mandate qualification of both Chinese and Indian superabsorbent polymer suppliers alongside Southeast Asian non-woven fabric converters. Raw material flows draw from Saudi petrochemical feedstocks, Yangtze River Delta SAP manufacturing, and Maharashtra textile processing clusters. Single-source vulnerability concentrates in petroleum-derived substrate supply. Distribution runs through supermarket networks for infant care, direct-to-consumer platforms for adult incontinence, and healthcare procurement systems for institutional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRICS disposable hygiene market compounds steadily as aging demographics across all five nations expand the addressable patient base for adult incontinence management.
For Market Incumbents: Cement dominance in biodegradable material conversion by piloting agricultural cellulose waste stream sourcing in Yangtze River Delta facilities. Lock in healthcare facility procurement relationships before ANVISA medical-grade registration requirements tighten. Prioritize backward integration into renewable electricity supply for thermal calendering to defend margin position against PLI-subsidized Indian entrants. For New Entrants and Emerging Players: Compostable absorbent core technology offers entry into white-space segments where MEE provincial enforcement actions accelerate compliance timelines. Target tier-two Chinese cities where modern retail penetration deepens but multinational distribution remains thin. Lead with direct-to-consumer subscription models for adult incontinence in São Paulo and Moscow where privacy preferences reshape channel access. For Investors and Strategic Acquirers: Consolidation pressure builds where PLI scheme beneficiaries in Maharashtra and Gujarat achieve scale but lack brand equity. The five-to-ten year viability window favors acquisition of domestic manufacturers with BIS certification infrastructure and established hospital procurement relationships. Watch for MEE enforcement action intensity as the inflection signal for biodegradable material conversion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Conversion | MEE provincial enforcement under China's dual carbon goals mandates industrial facility upgrades. |
| Healthcare Facility Partnership | ANVISA medical-grade device registration creates defensible procurement relationships in Brazil. |
| Direct-to-Consumer Platform Launch | Subscription models capture privacy-driven channel migration in São Paulo and Moscow. |
| Backward Integration into Non-Woven Fabric | India's PLI scheme subsidizes domestic textile capacity expansion in Maharashtra and Gujarat. |
| Renewable Electricity Sourcing | Coastal Chinese manufacturers source clean power for thermal calendering compliance timelines. |
Study Parameters
Coverage spans Brazil, Russia, India, China, and South Africa, with primary inputs from each market through structured interviews with brand managers, category buyers at modern retail chains, supply planners at non-woven fabric converters, and procurement officers at hospital systems. Secondary validation draws from SAMR GB standards filings, BIS certification records, ANVISA device registrations, customs trade data for superabsorbent polymer flows, and Nielsen retail audit information. Bottom-up volume modeling triangulates against top-down demographic demand projections.
Granularity-level modeling disaggregates volume and value across product type, end user, material composition, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against birth-rate trajectories, aging population curves, and retail infrastructure penetration indices. Industry-specific inputs include PLI scheme disbursement schedules, MEE enforcement action timelines, and ANVISA registration approval velocity.
The model holds under stable regulatory enforcement intensity; deviation in petrochemical feedstock price spikes or accelerated EPR mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Panty Liner Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Global Feminine Protection Market