
 Reusable/Washable Hygiene Products Market | 2026-2036
Reusable/Washable Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable/Washable Hygiene Products Market Analytics
EU REACH chemical restrictions and the F-Gas Regulation are consolidating compliance costs around material transparency and fluorinated-compound bans. Saalt leverages direct-to-consumer subscription models to sustain repeat purchase rates across North American markets. GladRags Corporation anchors its competitive position through domestic manufacturing scale in Portland, Oregon. Modibodi differentiates via proprietary moisture-wicking fabric technology that extends product lifecycle claims.
Reusable/washable hygiene products comprise absorbent textile goods engineered for repeated laundering, typically constructed from layered organic cotton, bamboo viscose, or polyester-microfiber blends with waterproof polyurethane laminate barriers. These items serve commercial and personal applications by replacing single-use disposables in menstrual care, incontinence management, and infant hygiene. Menstrual cups and period underwear dominate value generation within product-type segmentation, while cloth pads retain mature volume positions in price-sensitive demographics. Cotton and bamboo materials command premium positioning due to biodegradability credentials, whereas polyester-microfiber blends compete on durability and lower unit economics. Online retail channels lead distribution growth, though specialty stores retain margin advantages through fitting services and education.
FDA oversight of menstrual cups as Class II medical devices in the United States shapes product-registration pathways and clinical-testing requirements for market entrants. ECHA substance restrictions under REACH govern dye chemistry and antimicrobial treatments across European supply chains, while BIS textile standards in India set baseline absorbency and dimensional-stability benchmarks for imported goods. Stakeholders must monitor evolving extended-producer-responsibility frameworks in OECD markets, as these programs increasingly assign end-of-life collection costs to brand owners rather than municipal waste systems.
Market Dynamics
The EU Green Deal's waste-reduction mandates are restructuring disposable-product economics across menstrual care, incontinence management, and infant hygiene segments. This regulatory pressure is compressing margins for single-use incumbents while elevating washable alternatives through extended-producer-responsibility cost reallocation.
Growth Catalysts
- REACH chemical transparency:ECHA substance restrictions on dyes and antimicrobial treatments are accelerating material innovation toward certified organic inputs. Suppliers reformulating under F-Gas fluorinated-compound bans gain preferential positioning with sustainability-scoring retailers.
- Composting infrastructure maturity:German municipal systems accepting biodegradable textiles at end-of-life reduce total cost-of-ownership calculations for bamboo and cotton product users. This infrastructure density supports premium pricing for biodegradable-credential goods.
- Moisture-wicking fabric engineering:Proprietary textile layering that extends laundering cycles above 100 washes is compressing replacement frequency. Performance claims validated under BIS absorbency standards unlock institutional procurement channels.
Market Restraints
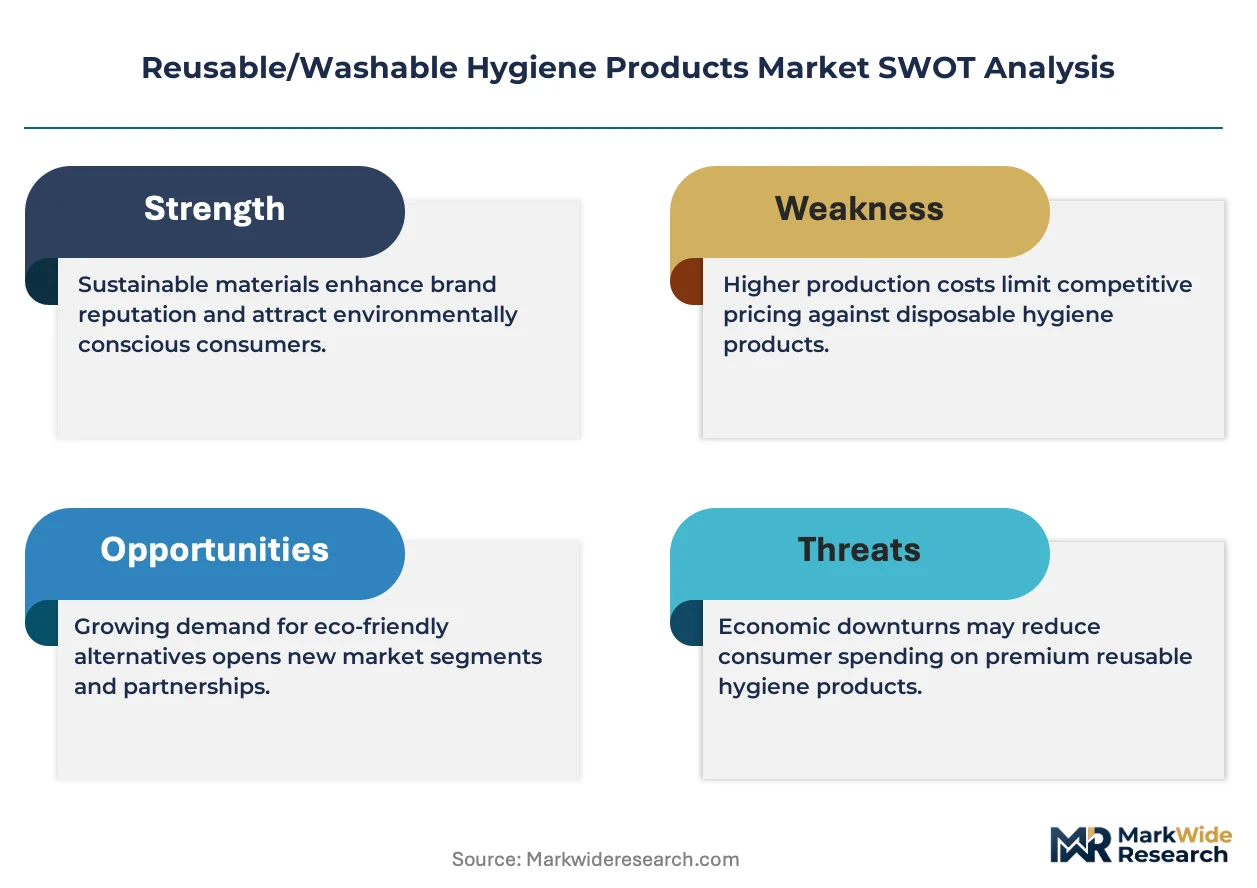
- Organic cotton input volatility:Weather-dependent fiber harvests in India and Turkey create margin pressure for manufacturers without backward integration into agricultural supply.
- FDA Class II device pathways:Menstrual cup market entrants face 12-18 month clinical testing timelines and quality-system documentation requirements that favor incumbent registrants.
- Disposable incumbent scale:Procter & Gamble and Kimberly-Clark manufacturing concentration in the US Southeast generates 40% lower unit costs through petrochemical supply proximity.
Strategic Opportunities
- Indian price-sensitive demographics:BIS textile standards compliance enables import substitution for cloth pads in tier-2 and tier-3 cities where unit economics dominate purchase decisions.
- Subscription direct-to-consumer models:Automated replenishment for period underwear reduces customer acquisition costs through predictable lifetime value calculations.
- EU extended-producer-responsibility expansion:France and Italy are piloting end-of-life collection cost assignment to brand owners, creating competitive advantage for washable product lines with minimal disposal infrastructure requirements.
Industry Challenges
- Textile engineering talent scarcity:Polyurethane laminate bonding and multi-layer moisture management require specialized polymer chemistry expertise concentrated in German and Swiss technical universities.
- Cross-border certification fragmentation:FDA medical device registration, CE marking under MDR, and BIS textile standards create compliance timeline stacking for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable/Washable Hygiene Products Market |
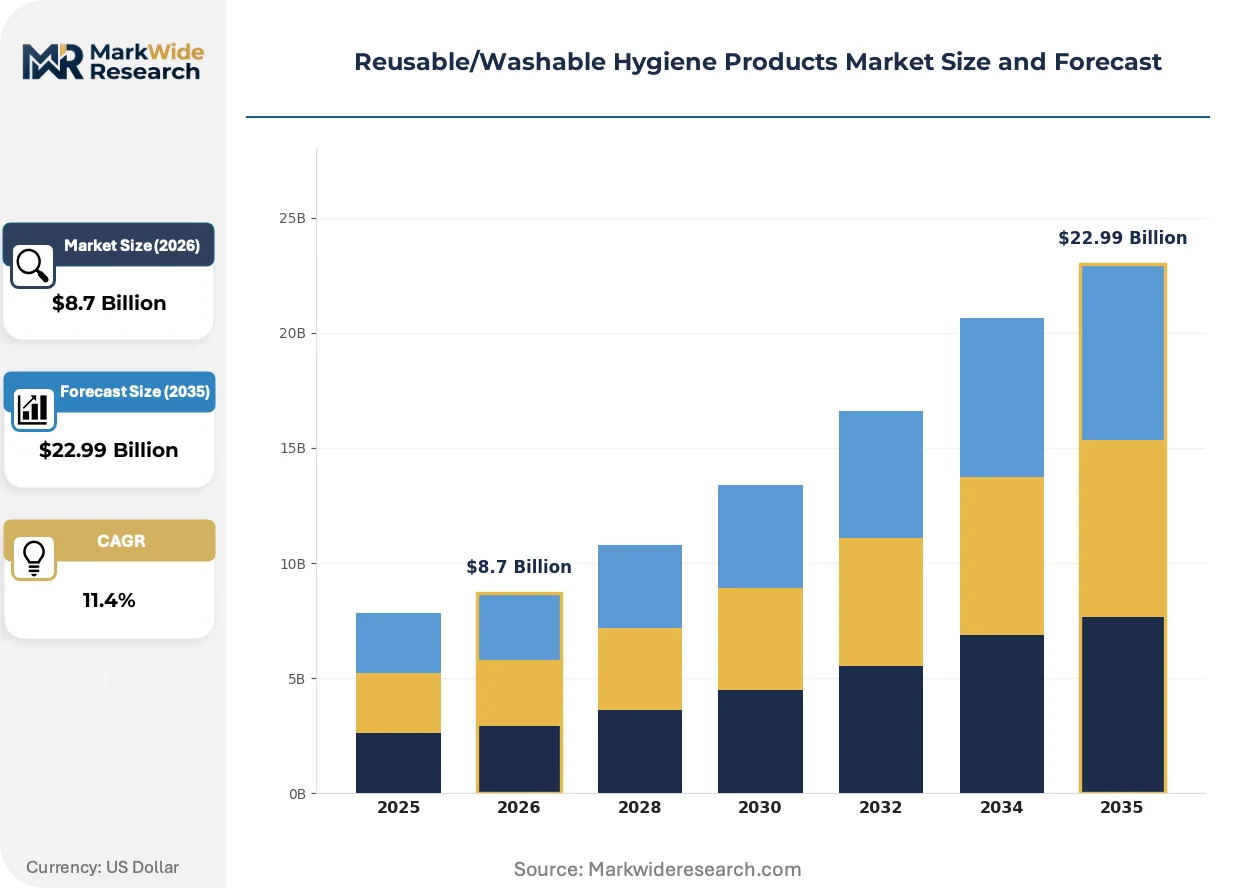
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Menstrual Cups, Cloth Pads, Reusable Wipes, Underwear End User: Individuals, Households, Hospitals, Institutions Material: Cotton, Bamboo, Microfiber, Polyester Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Saalt, Lunapads, Thinx, Bambody, GladRags Corporation, Modibodi, Essity AB, Eco Femme, Knix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable/Washable Hygiene Products Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape product architecture across absorbent textile categories. This convergence is elevating performance-validated biodegradable alternatives while compressing synthetic-microfiber market share.
Biodegradable bamboo viscose engineered with closed-loop solvent recovery is absorbing capital allocation from polyester-microfiber blends. Premium menstrual care buyers in Germany and the Netherlands are adopting these textiles at twice the rate of conventional alternatives. The technology is absorbing volume from petroleum-derived inputs as composting infrastructure validates end-of-life claims.
ECHA dye chemistry restrictions under REACH Annex XVII are forcing reformulation of antimicrobial treatments across European supply chains. Industrial consequence includes 15-20% cost increases for conventional finishing processes. Period underwear manufacturers serving EU markets are responding by shifting to bio-based silver-ion alternatives certified under OEKO-TEX Standard 100.
Retail sustainability scoring systems are compressing wholesale purchasing cycles for unverified product claims. Specialty stores in Berlin and Amsterdam are replacing inventory turnover metrics with lifecycle-assessment documentation requirements. This behavioral shift is most visible in German-speaking markets where municipal procurement guidelines now mandate third-party biodegradability certification for institutional menstrual product contracts.
Reusable/Washable Hygiene Products Market Segmentation
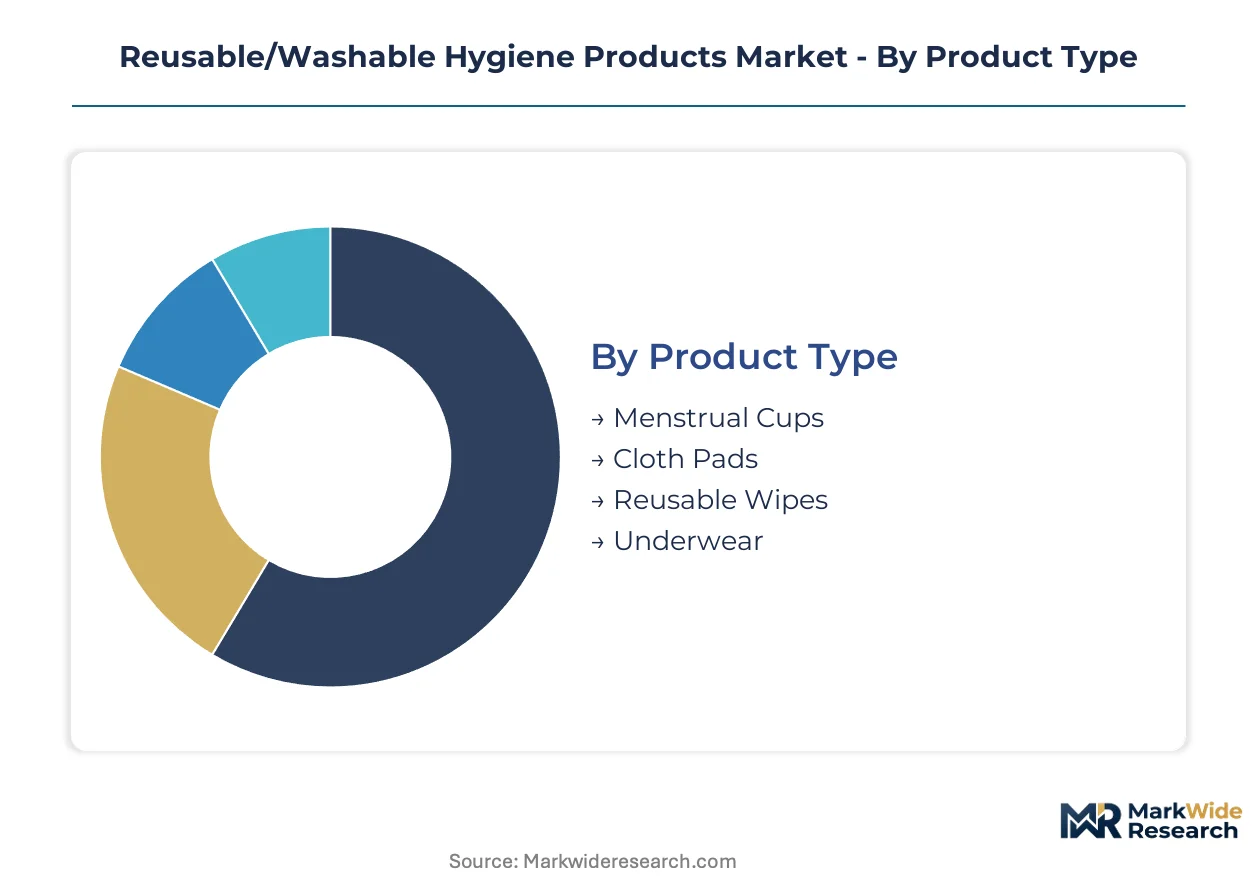
Segmentation in reusable hygiene products reveals how purchase decisions split between performance validation, disposal economics, and channel accessibility. Material certifications and laundering durability increasingly override brand loyalty in repeat purchase behavior.
Product Type:
Buyers prioritize lifecycle cost calculations against single-use alternatives when selecting product formats.
- Menstrual Cups:Medical-grade silicone or thermoplastic elastomer construction delivers 5-10 year replacement cycles. FDA Class II device registration in the United States creates compliance moats that concentrate supply among established registrants. Demand clusters in Germany and the Netherlands where municipal composting infrastructure validates end-of-life claims for biodegradable alternatives.
- Cloth Pads:Layered organic cotton or bamboo viscose with polyurethane laminate barriers enable 100+ wash cycles. Volume concentrates in Indian tier-2 and tier-3 cities where BIS textile standard compliance enables import substitution at price-sensitive unit economics.
- Reusable Wipes:Bamboo terry or cotton flannel constructions target infant hygiene and cosmetic removal applications.
- Underwear:Proprietary moisture-wicking textile layering extends functional lifespan beyond conventional absorbent products.
Volume sits with cloth pads; growth tilts toward period underwear.
End User:
Procurement authority separates institutional buyers seeking standardization from individual purchasers prioritizing fit customization.
- Individuals:Direct-to-consumer subscription models capture predictable replenishment schedules through automated fulfillment.
- Households:Multi-user inventory management drives bulk purchasing toward cloth pad assortments with standardized sizing.
- Hospitals:BIS absorbency validation and ISO 13485 quality system documentation unlock clinical procurement channels in India.
- Institutions:EU Green Deal extended-producer-responsibility pilots in France and Italy assign end-of-life collection costs to brand owners, favoring washable lines with minimal disposal infrastructure requirements.
Revenue concentrates with individual purchasers; institutional procurement is climbing fastest.
Material:
End-of-life pathway availability determines material selection more than upfront unit cost in environmentally-scored retail environments.
- Cotton:Certified organic fiber harvests in India and Turkey command premium positioning through biodegradability credentials validated under municipal composting acceptance.
- Bamboo:Closed-loop solvent recovery viscose processing absorbs capital allocation from petroleum-derived alternatives as REACH Annex XVII dye restrictions accelerate bio-based input adoption.
- Microfiber:Polyester-microfiber blends compete on durability and lower unit economics against biodegradable alternatives.
- Polyester:Petroleum-derived fiber maintains cost advantage in price-sensitive demographics lacking composting infrastructure access.
Shipments favor cotton; bamboo is gaining share fastest.
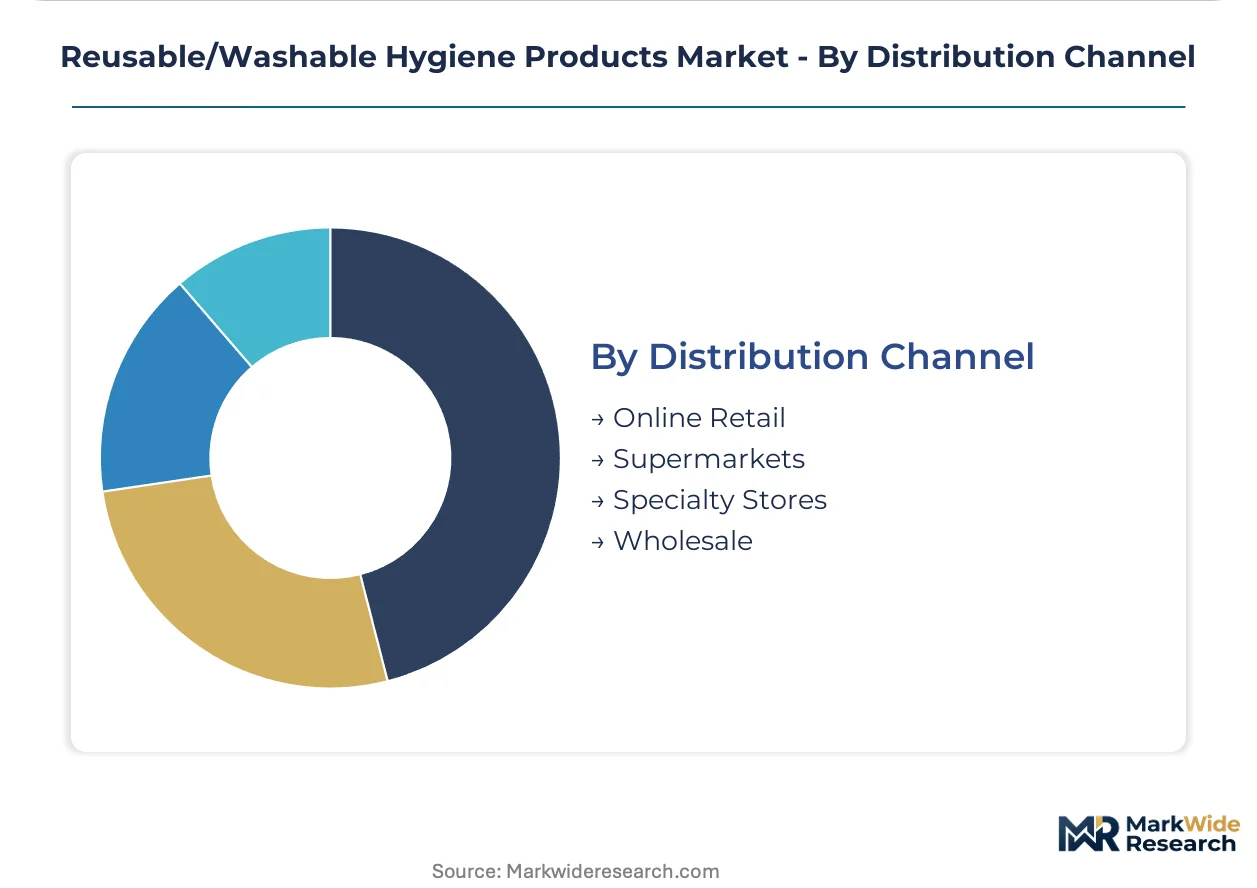
Distribution Channel:
Margin structure and customer acquisition cost economics channel manufacturer investment toward direct relationships.
- Online Retail:Subscription automation reduces customer acquisition costs through predictable lifetime value calculations and eliminates wholesale margin sharing.
- Supermarkets:Sustainability scoring systems in German retail chains compress purchasing cycles for unverified product claims.
- Specialty Stores:Fitting services and education retain margin advantages through consultative selling in Berlin and Amsterdam clusters.
- Wholesale:Institutional procurement consolidation favors suppliers with BIS textile standard documentation and REACH compliance certification.
Transaction volume flows through online retail; specialty stores command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households concentrate demand for washable hygiene products, driven by municipal composting infrastructure and retailer sustainability scoring systems that validate biodegradable alternatives.
Germany
Berlin and Hamburg clusters drive period underwear adoption through municipal procurement guidelines mandating third-party biodegradability certification. The EU Green Deal's extended-producer-responsibility pilots assign end-of-life collection costs to brand owners, favoring washable lines. Bavaria's technical universities supply specialized polymer chemistry expertise for polyurethane laminate bonding.
United States
Portland and Pacific Northwest manufacturing anchors domestic production scale for cloth pad suppliers. FDA Class II device registration creates compliance moats concentrating menstrual cup supply among established registrants. EPA waste-reduction initiatives in California and New York reshape disposable-product economics through landfill diversion mandates.
India
Tier-2 and tier-3 cities in Maharashtra and Gujarat absorb volume for price-sensitive cloth pad demographics. BIS textile standards compliance enables import substitution at unit economics that undercut imported alternatives. Karnataka's technical institutes feed engineering talent into moisture-wicking fabric development centers.
Netherlands
Amsterdam specialty stores replace inventory turnover metrics with lifecycle-assessment documentation requirements. ECHA REACH Annex XVII dye restrictions accelerate bio-based silver-ion antimicrobial adoption. Rotterdam's logistics infrastructure supports distribution hub consolidation for EU-wide washable product fulfillment.
France
Paris institutional procurement channels unlock through ISO 13485 quality system documentation for clinical-grade absorbent textiles. ANSM national health authority oversight shapes product safety validation pathways. Auvergne-Rhône-Alpes textile engineering clusters supply closed-loop solvent recovery expertise for bamboo viscose processing.
Reusable/Washable Hygiene Products Market Competitive Landscape
United States producers anchor one tier; Australian and Indian specialists hold differentiated positions through material innovation and cost engineering. The vendor base splits between direct-to-consumer subscription operators and wholesale-dependent fabricators serving institutional channels. Three archetypes dominate: domestic manufacturing scale players, proprietary textile technology licensors, and sustainability-credential aggregators. Competitive moves concentrate on backward integration into organic fiber supply and automated replenishment platform development.
Among Portland-based fabricators, GladRags Corporation exemplifies domestic manufacturing scale archetypes. Saalt and Modibodi occupy positions within the direct-to-consumer technology tier, representing subscription automation and proprietary moisture-wicking fabric specialization respectively. These three anchors illustrate how geographic concentration and channel strategy divergence structure competitive positioning.
| Leading Market Players |
|---|
| Saalt |
| Lunapads |
| Thinx |
| Bambody |
| GladRags Corporation |
| Modibodi |
| Essity AB |
| Eco Femme |
| Knix |
| Others |
Value Network & Pricing Analysis
EU Green Deal extended-producer-responsibility mandates gate qualified supply access and premium-tier pricing power by assigning end-of-life collection costs to brand owners. This regulatory architecture compresses margins for disposable incumbents while elevating washable alternatives through validated biodegradability credentials.
Pricing Analysis
Short lead-time premiums for REACH-compliant organic cotton inputs separate certified suppliers from spot-market commodity fiber. Pricing stratifies across premium, standard, and economy tiers based on OEKO-TEX Standard 100 certification level and volume scale. Cost compression in the polyester-microfiber tier is intensifying because petrochemical supply proximity favors disposable incumbent scale. Price-sensitive tier-2 and tier-3 Indian cities absorb economy-tier cloth pad volume, while German municipal procurement channels pay certification premiums.
Supply Chain Analysis
Dual-sourcing requirements for medical-grade silicone menstrual cups mandate FDA-registered and CE-marked supplier qualification. Geographic concentration centers on India for organic cotton fiber, Turkey for bamboo viscose processing, and Germany for polyurethane laminate bonding expertise. Raw material dependencies draw from weather-dependent agricultural harvests, closed-loop solvent recovery systems, and petroleum-derived synthetic inputs. Single-source vulnerability in Indian organic cotton supply creates procurement risk during monsoon disruption cycles. Distribution runs through direct-to-consumer subscription platforms and specialty retail clusters in Berlin and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into certified organic fiber supply determines margin sustainability. Players are pursuing captive agricultural sourcing to secure input cost stability against weather volatility.
For Market Incumbents: To counter disposable incumbent manufacturing scale in the US Southeast, anchor domestic production in Portland and expand REACH-compliant dye chemistry capabilities. Invest in automated replenishment platforms to reduce customer acquisition costs through subscription retention. Certification investment in BIS textile standards unlocks institutional procurement channels in Indian hospitals. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting price-sensitive tier-2 and tier-3 Indian cities with BIS-compliant cloth pad assortments. White-space opportunities concentrate in moisture-wicking fabric technology licensing for period underwear extensions. Municipal composting infrastructure gaps in Southern Europe present geographic expansion targets before extended-producer-responsibility mandates mature. For Investors and Strategic Acquirers: FDA Class II menstrual cup registration completion is the leading indicator that clinical-grade supply consolidation is accelerating. Long-term viability over the next decade hinges on proprietary textile engineering talent concentration in German and Swiss technical universities. Acquisition targets should display backward integration into organic cotton supply or automated subscription platform infrastructure. Watch ECHA REACH Annex XVII dye restriction enforcement timelines as the inflection signal for bio-based antimicrobial treatment adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Fiber Supply | Captive cotton sourcing in India and Turkey insulates margin compression from weather-driven input volatility. |
| Direct-to-Consumer Subscription Launch | Automated replenishment for period underwear reduces acquisition costs through predictable lifetime value capture. |
| REACH-Compliant Dye Chemistry Investment | Bio-based silver-ion antimicrobial certification under OEKO-TEX Standard 100 unlocks EU retail sustainability scoring. |
| BIS Textile Standards Compliance | Absorbency validation enables import substitution in Indian tier-2 and tier-3 institutional procurement channels. |
| Proprietary Moisture-Wicking Fabric Development | Multi-layer textile engineering extending 100+ wash cycles compresses replacement frequency and elevates pricing power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with textile engineering directors, sustainability procurement leads at German retail chains, FDA regulatory affairs specialists, and Indian hospital purchasing committees validated supply-side and demand-side assumptions. Secondary sources included ECHA REACH substance restriction databases, BIS textile standard documentation, FDA 510(k) menstrual cup filings, and EU Green Deal extended-producer-responsibility pilot program disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, material, and distribution channel dimensions.
Data-stream reconciliation aligned shipment volumes from Indian cotton fiber exporters with German municipal composting acceptance rates and US subscription platform transaction patterns. Segmentation modeling spanned product type, material composition, end-user archetype, and geographic regulatory cluster throughout the forecast period. CAGRs derived from regression analysis against EU waste-reduction mandate implementation timelines and BIS standard adoption curves in Indian procurement channels. Industry-specific inputs included REACH Annex XVII enforcement intensity indices and composting infrastructure density metrics.
Organic cotton harvest volatility, ECHA dye chemistry restriction acceleration, and FDA Class II device registration backlog are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding municipal infrastructure buildout schedules and retailer sustainability scoring adoption rates. Deviation in EU extended-producer-responsibility cost allocation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Organic Sanitary Napkin Market